
 Global Automated Parcel Delivery Terminals Market | 2026-2036
Global Automated Parcel Delivery Terminals Market Size, Share, and Industry Trends Forecast 2026-2036
Global Automated Parcel Delivery Terminals Market Intelligence
The last-mile logistics channel for parcel delivery is fragmenting as new infrastructure formats emerge, creating distinct competitive arenas. InPost S.A. leverages its dense, open-network model of outdoor kiosks across Europe. Quadient differentiates with intelligent locker systems targeting residential and corporate mailroom applications. Cainiao Network, an affiliate of Alibaba, rapidly expands its terminal footprint to support its e-commerce ecosystem in Asia.
Automated parcel delivery terminals are secure, self-service structures that enable 24/7 package drop-off and pickup without direct human assistance. These systems integrate technologies like barcode scanning or QR codes for user authentication via a central touchscreen interface. Outdoor kiosks and indoor lockers represent the dominant terminal types due to their deployment flexibility in public spaces and private buildings. Within applications, e-commerce fulfillment and package returns drive the majority of deployments by logistics providers and retail chains.
Data privacy regulations, including the EU's General Data Protection Regulation (GDPR), govern how user information and access credentials are managed. In the United States, the Americans with Disabilities Act (ADA) sets standards for the physical design and accessibility of kiosk interfaces. Postal service regulations in countries like Germany and France also influence terminal placement and carrier access. Stakeholder success depends on navigating urban planning requirements, technology integration, and evolving consumer expectations for convenience.
Market Dynamics
The central structural force shaping the market is the rapid fragmentation of last-mile delivery infrastructure. Driven by the unrelenting volume growth from e-commerce, logistics networks are decentralizing away from traditional door-to-door delivery toward a multi-format system of automated terminals.
Growth Catalysts
- Urban Density and E-commerce:The concentration of online shoppers in high-density urban areas, particularly in European countries like Germany, creates intense demand for efficient, consolidated delivery points to reduce last-mile costs and vehicle traffic.
- Contactless Technology Adoption:Public health considerations and consumer demand for convenience accelerate the integration of contactless technologies. QR code and barcode scanning systems for authentication are becoming standard, minimizing physical interaction and speeding up pickup times.
- Sustainable Urban Logistics Policies:Municipal governments are promoting low-emission zones and freight consolidation strategies. These policies incentivize the deployment of parcel terminals as a way to reduce delivery vehicle mileage and associated carbon emissions in city centers.
Market Restraints
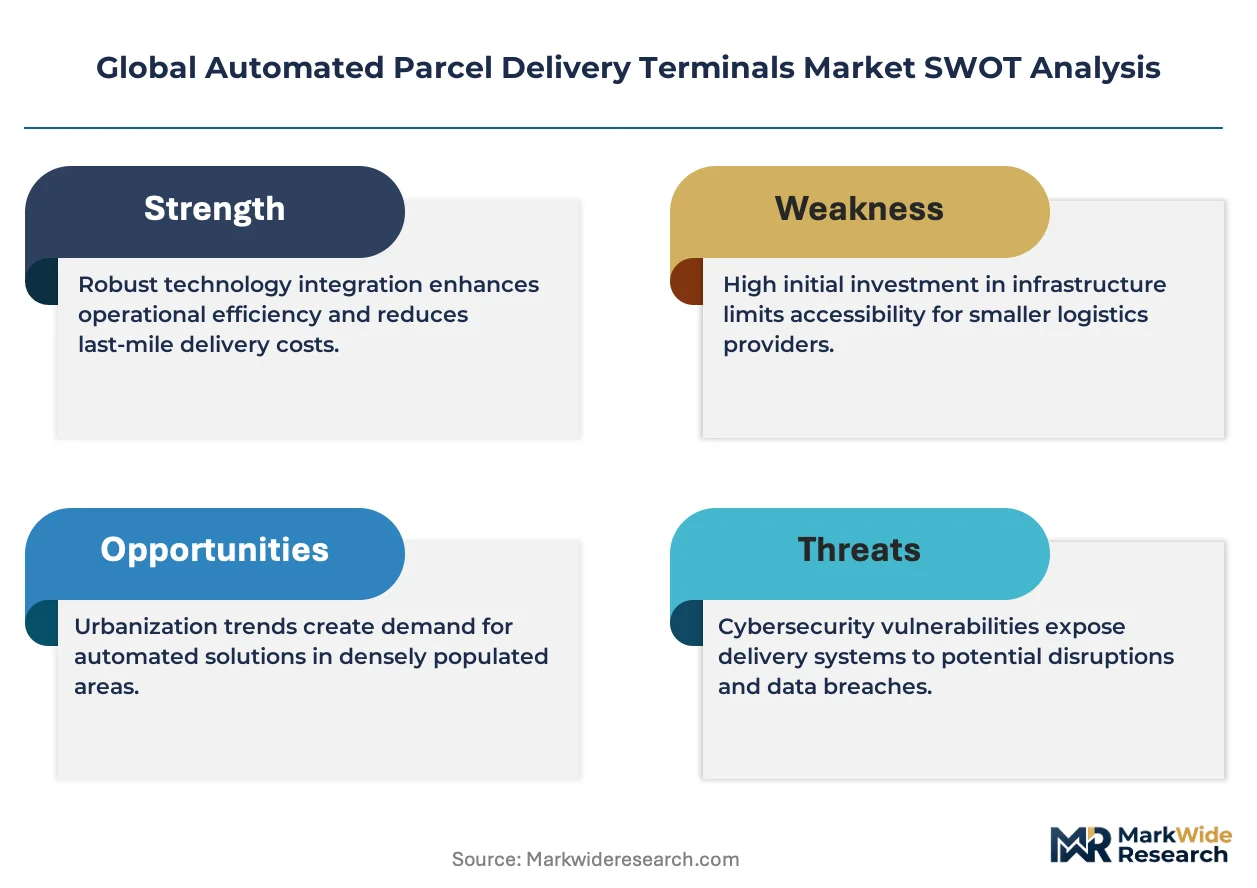
- High Capital Expenditure:The initial investment for acquiring sites, manufacturing hardware, and deploying a network of terminals is substantial. These high upfront costs can be a significant barrier to entry for smaller logistics players or new market entrants.
- Fragmented Regulatory Approvals:Gaining permits for terminal installation involves navigating a complex web of local zoning laws, public right-of-way regulations, and property owner agreements, which vary significantly between municipalities and slow down network expansion.
- Infrastructure Dependency:Terminals require consistent access to reliable electricity and high-speed data connectivity to function. The lack of this essential infrastructure in some public spaces, transit hubs, or older buildings limits viable deployment locations.
Strategic Opportunities
- Suburban and Secondary City Expansion:Significant opportunity exists in expanding terminal networks beyond primary urban cores into dense suburban communities and secondary cities where e-commerce penetration is high but automated pickup options remain limited.
- Service Diversification:Terminals can be upgraded to support new revenue streams, such as temperature-controlled compartments for grocery and meal-kit delivery, or secure lockers for high-value item exchange, transforming them into multi-purpose community hubs.
- Integration with EV Charging Infrastructure:Co-locating automated parcel terminals with electric vehicle charging stations creates a synergistic value proposition for consumers and property owners, leveraging shared electrical infrastructure and high-traffic locations.
Industry Challenges
- Software and Network Interoperability:A major operational hurdle is ensuring seamless software integration between a terminal operator's platform and the disparate tracking and logistics systems of multiple carriers, which is critical for open-network models.
- Compliance with Accessibility Mandates:Designing terminals that meet stringent accessibility standards, such as the Americans with Disabilities Act (ADA), for reach, visibility, and usability by all users presents a complex engineering and user-interface design challenge.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Automated Parcel Delivery Terminals Market |
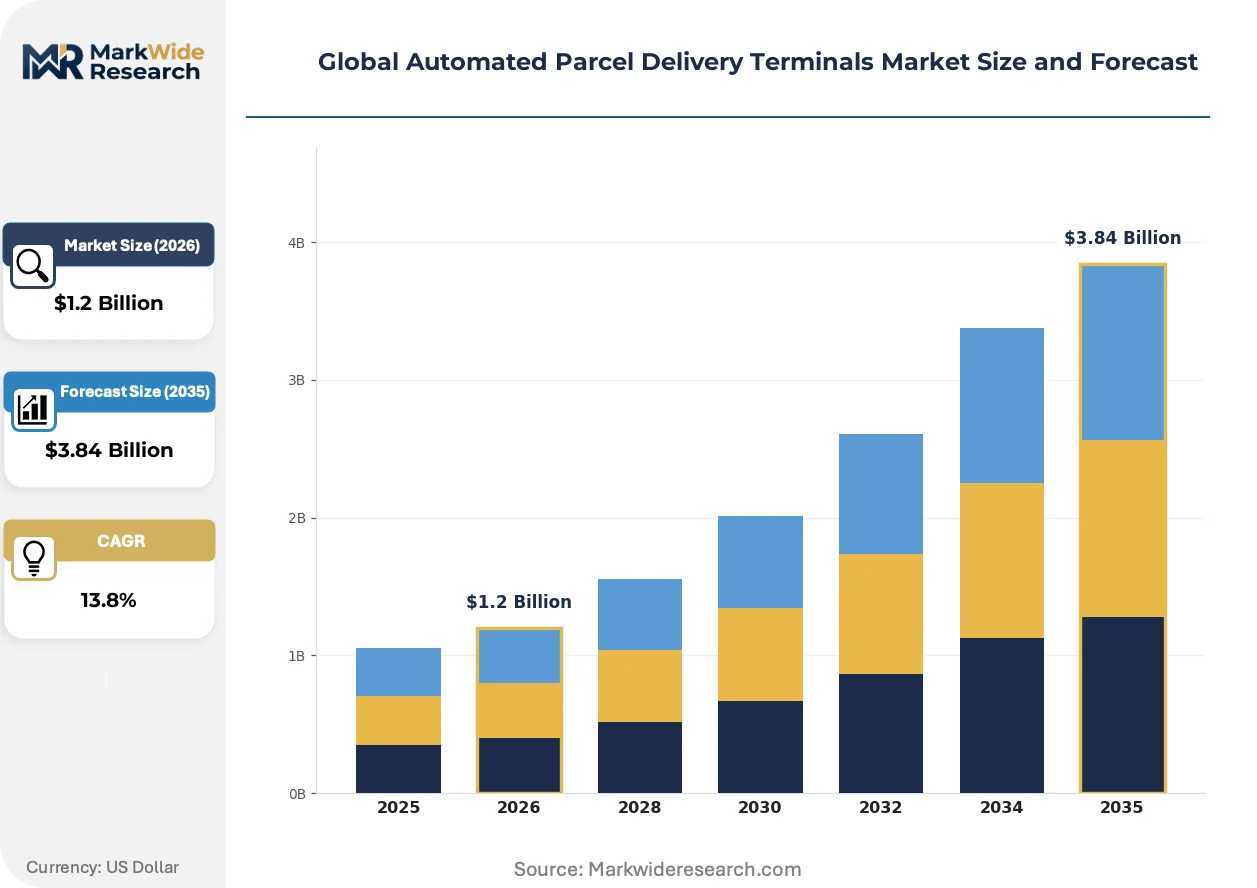
| Market Size in 2026 | $1.2 Billion |
| Market Size in 2035 | $3.84 Billion |
| CAGR (2026 – 2036) | 13.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Terminal Type: Outdoor Kiosks, Indoor Lockers, Mobile Terminals, Interactive Booths, Smart Cabinets Technology: RFID, NFC, Barcode Scanning, Touchscreen Interface, Biometric Authentication Application: E-commerce Fulfillment, Last-Mile Delivery, Corporate Mailrooms, Retail Pickups, Package Returns End User: Logistics Providers, Postal Services, Retail Chains, Facility Management, Courier Companies |
| Companies Covered | InPost S.A., Quadient, Cleveron AS, Amazon, Deutsche Post DHL Group, Cainiao Network, TZ Limited, KEBA Group AG, Luxer One, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Automated Parcel Delivery Terminals Market Strategic Shifts & Innovations
The market's evolution is defined by the shift of terminals from standalone hardware to intelligent, networked nodes integrated into broader digital and urban ecosystems. This transition enhances their functionality beyond simple package holding to active participation in logistics and data networks.
Temperature-controlled compartments represent a key product evolution. These refrigerated or heated locker modules are being adopted by grocery chains and meal-kit services to maintain the integrity of perishable goods during last-mile delivery. This technology is hybridizing the core function of a parcel terminal, transforming it from a simple dry-goods repository into a viable access point for the cold-chain logistics market.
The EU's General Data Protection Regulation (GDPR) is a prominent regulatory influence. This framework mandates strict protocols for handling the personal data collected during the package pickup process, including names, phone numbers, and access codes. The regulation forces terminal operators to invest heavily in data encryption, secure cloud infrastructure, and transparent user consent mechanisms, particularly affecting pan-European network providers.
A clear behavioral shift toward open-network access is disrupting established logistics models. Consumers increasingly prefer carrier-agnostic terminals that can accept packages from any sender, rather than being locked into a single provider's proprietary locker system. This preference for universal access is most visible in dense European markets, compelling logistics companies to join shared networks to retain customer convenience.
Global Automated Parcel Delivery Terminals Market Segmentation
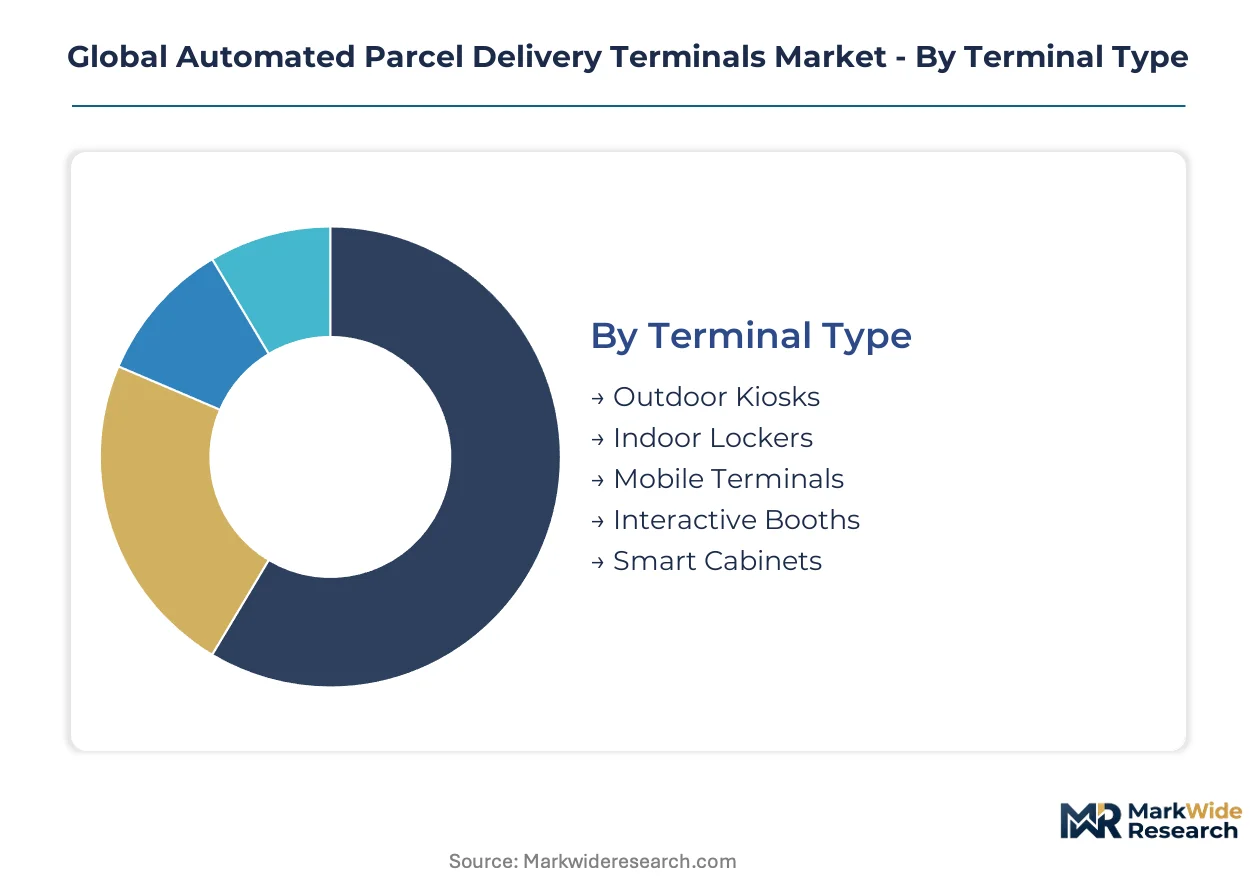
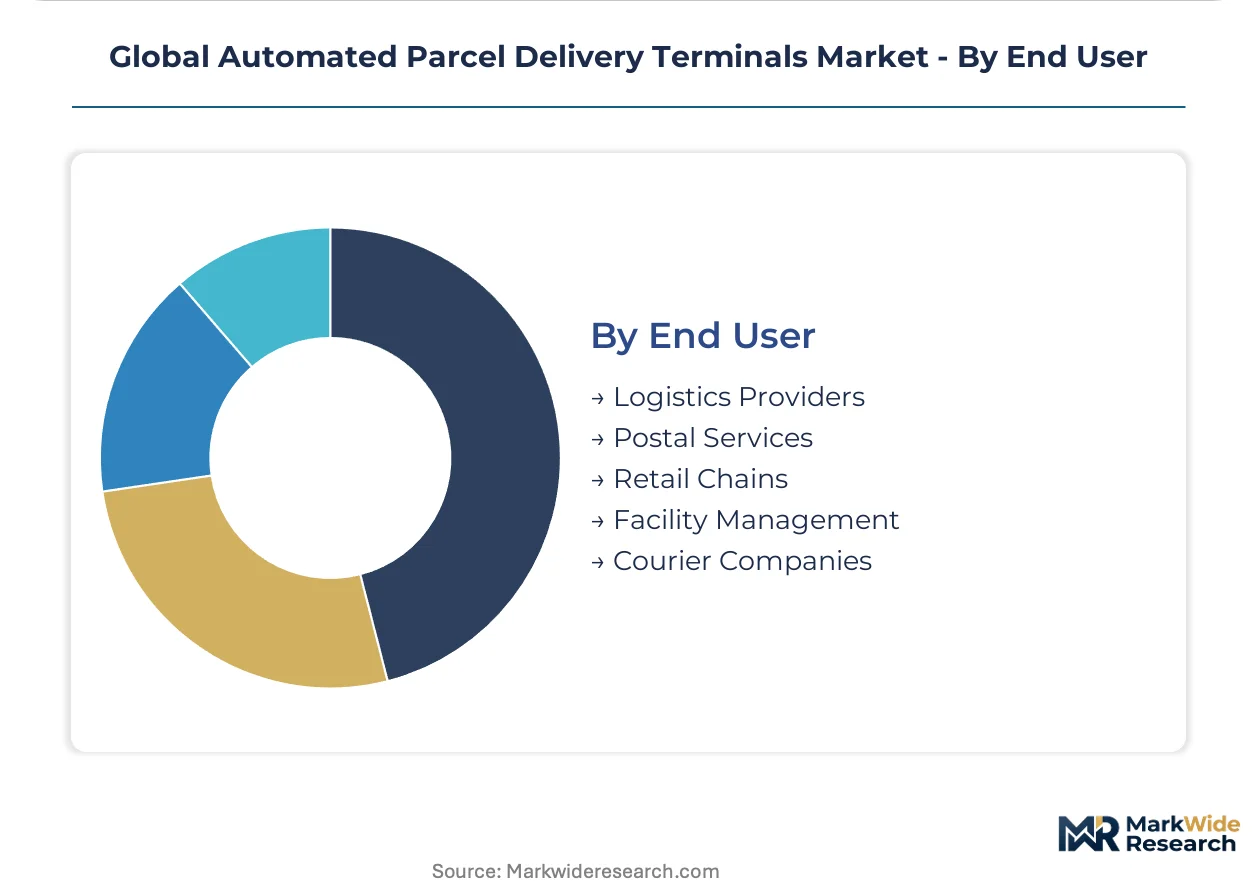
Market segmentation provides a granular understanding of the diverse components shaping the global automated parcel delivery terminals industry. Analyzing these distinct segments reveals the underlying demand drivers, technological preferences, and operational models influencing market expansion.
Terminal Type:
The market for automated parcel delivery terminals spans a maturity spectrum, from established outdoor kiosks to emerging mobile solutions that offer greater deployment flexibility.
- Outdoor Kiosks:These standalone, weatherproof units provide 24/7 package access in public locations. Demand concentrates in high-density urban areas like Germany, where they reduce last-mile delivery costs and vehicle traffic.
- Indoor Lockers:Modular and secure, these systems are typically integrated within private buildings such as residential complexes or corporate offices. Adoption is significant in the United Kingdom for enhancing tenant convenience and managing package flow efficiently.
- Mobile Terminals:Vehicle-mounted or portable units offer flexible deployment options, often used for temporary events or remote locations.
- Interactive Booths:These terminals feature advanced user interfaces and can provide additional services beyond simple parcel exchange.
- Smart Cabinets:IoT-enabled units offer real-time tracking, remote management, and advanced security features for parcels.
Outdoor Kiosks retain volume leadership; Smart Cabinets hold the steepest expansion curve.
Technology:
Technology integration defines the functional utility and user experience across automated parcel terminals, enabling secure access and efficient operations.
- Barcode Scanning:This common authentication method utilizes optical readers to identify packages and users via printed codes. It is a foundational technology for e-commerce fulfillment globally, ensuring fast and accurate package identification.
- Touchscreen Interface:A central command unit provides intuitive navigation and user interaction for package retrieval and drop-off. Public kiosks in urban centers rely on touchscreens, often designed to meet ADA compliance standards in the United States.
- RFID:Radio-frequency identification enables contactless package and user identification, often used for inventory management within the terminal.
- NFC:Near Field Communication facilitates secure, short-range wireless interaction, commonly used for mobile device authentication.
- Biometric Authentication:This advanced security feature employs fingerprint or facial recognition for user verification, enhancing parcel security.
Barcode Scanning remains foundational for terminal operation, while Biometric Authentication promises advanced security features.
Application:
Demand for automated parcel terminals is primarily shaped by specific end-use applications, each addressing distinct logistical challenges and consumer needs.
- E-commerce Fulfillment:This application involves direct consumer pickup of online orders, handling high volumes of packages. Urban populations in China represent a significant demand cluster, supporting the rapid growth of online retail.
- Package Returns:Terminals facilitate reverse logistics by allowing consumers to self-service drop off return items. European markets show strong adoption, simplifying the consumer returns process for various retailers.
- Last-Mile Delivery:Terminals improve efficiency and reduce congestion in the final leg of parcel delivery, especially in dense urban environments.
- Corporate Mailrooms:These systems manage internal package distribution within businesses, ensuring secure and tracked delivery to employees.
- Retail Pickups:Terminals support click-and-collect models, offering customers an alternative to in-store pickup for online purchases.
E-commerce Fulfillment drives the largest deployment volumes, with Package Returns representing a critical value-added service.
End User:
The operational models and strategic priorities of various end users dictate terminal adoption, influencing network design and service offerings.
- Logistics Providers:These entities operate extensive networks, deploying terminals as part of their delivery infrastructure, whether carrier-agnostic or proprietary. InPost in Poland exemplifies this, expanding delivery options and market reach.
- Retail Chains:Retailers integrate terminals for click-and-collect services and customer convenience, often located within or adjacent to stores. Major retailers in the United States utilize terminals to enhance their omnichannel strategies.
- Postal Services:National postal operators deploy terminals to fulfill their public service mandate, providing universal access to parcel services.
- Facility Management:These users deploy terminals within buildings to enhance security and convenience for tenants and residents.
- Courier Companies:Specialized delivery firms utilize terminals for secure handover of high-value or time-sensitive packages.
Logistics Providers are the primary investors in terminal infrastructure, while Retail Chains integrate terminals for enhanced customer experience.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regional pricing power for automated parcel delivery terminals shows asymmetry. Germany commands higher per-unit value due to established infrastructure and high urban density, while China prioritizes volume-driven deployment across its vast e-commerce landscape. This dynamic shapes investment priorities and network expansion strategies across diverse geographies.
Germany
German cities generate demand for efficient consolidated delivery points, driven by urban density and e-commerce growth. Sustainable urban logistics policies incentivize terminal deployment to reduce vehicle mileage and emissions. Berlin and Hamburg actively integrate parcel terminals into public transport hubs for commuter convenience and environmental benefits.
United Kingdom
United Kingdom residential complexes and corporate offices drive indoor locker adoption for tenant convenience and secure package management. Local zoning laws and property owner agreements influence deployment flexibility across urban centers. London and Manchester demonstrate high uptake for efficiently managing package flow in multi-tenant buildings.
China
China's vast e-commerce fulfillment needs propel rapid terminal expansion across urban and suburban areas. GB standards govern terminal safety and performance, ensuring reliable public use for millions of daily transactions. The Yangtze River Delta sees massive terminal footprint growth, supporting Alibaba's logistics ecosystem and consumer access.
United States
United States retailers integrate terminals for click-and-collect services and enhanced omnichannel strategies, improving customer experience. The Americans with Disabilities Act (ADA) sets standards for physical design and accessibility of public kiosks. New York City and Los Angeles see significant adoption in retail and public spaces for last-mile efficiency.
Poland
Poland's logistics providers expand delivery options through extensive terminal networks, particularly for open-network models. GDPR compliance is crucial for managing user data securely across European operations and maintaining consumer trust. Warsaw and Krakow exemplify the success of dense outdoor kiosk networks for widespread consumer convenience.
Global Automated Parcel Delivery Terminals Market Key Industry Players
Platform integrators command the system tier; component specialists sit upstream providing hardware. The market structure is tiered, featuring dedicated hardware manufacturers alongside comprehensive logistics solution providers. These archetypes compete across service offerings and network reach. Geographic expansion into underserved urban and suburban areas, coupled with advanced technology integration, are dominant competitive moves among industry participants.
Specialized logistics providers like InPost S.A. and Quadient exemplify distinct strategies within the market. InPost, a Polish-based company, anchors the open-network model, emphasizing dense outdoor kiosk deployments across Europe. Quadient, a French-based firm, differentiates with intelligent locker systems tailored for residential and corporate mailrooms. Meanwhile, Cainiao Network, affiliated with Alibaba, represents a scale-driven approach, rapidly expanding its terminal footprint to support its vast e-commerce ecosystem in Asia.
| Leading Market Players |
|---|
| InPost S.A. |
| Quadient |
| Cleveron AS |
| Amazon |
| Deutsche Post DHL Group |
| Cainiao Network |
| TZ Limited |
| KEBA Group AG |
| Luxer One |
| Others |
Cost & Logistics Intelligence
European last-mile delivery corridors dictate cost dynamics, influenced by hardware manufacturing concentration in Asia and Europe, which in turn shapes price differentiation for automated parcel terminals.
Pricing Analysis
The customization-premium spread differentiates pricing for automated parcel terminals, with configured-to-order systems commanding higher value than standard units. Pricing models are primarily project-based for large network deployments, complemented by subscription fees for software and maintenance. Customization levels, such as temperature control or biometric authentication, and geographic installation costs drive price differentiation. Pricing pressure stems from large logistics providers demanding volume discounts, while retail chains exhibit greater price sensitivity compared to facility management entities.
Supply Chain Analysis
Contract manufacturing concentration in China and Germany holds significant capacity for automated parcel terminal hardware. The supply chain draws from electronic components like sensors and touchscreens, alongside sheet metal and plastics for robust enclosures. A structural risk involves single-source vulnerability for specialized security hardware. Distribution runs through direct sales channels to major logistics providers and retail chains, complemented by regional channel partners for smaller-scale deployments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The automated parcel delivery terminals market demands a substitution defense strategy, as incumbents navigate the threat of advanced direct-to-home smart locker solutions. This dynamic necessitates strategic adaptation.
For Market Incumbents: Build network density moats by expanding into dense suburban communities and secondary cities. Incumbents must diversify service offerings, incorporating temperature-controlled compartments to address evolving consumer expectations for varied package types. Seamless software interoperability with multiple carriers acts as a critical technology integration lever against fragmented last-mile delivery. This defends against emerging direct-to-home smart locker solutions.
For New Entrants and Emerging Players: Establish a beachhead in niche applications such as temporary event logistics or specialized high-value item exchange. Focus on underserved geographic areas like remote locations or new residential developments lacking existing infrastructure. Facility management for corporate mailrooms in secondary cities represents a penetrable segment. A compelling go-to-market angle involves co-locating terminals with electric vehicle charging infrastructure, leveraging shared utility access and high-traffic locations.
For Investors and Strategic Acquirers: Carve-out targets emerge from large logistics conglomerates or e-commerce giants seeking to divest non-core assets. The market demonstrates strong long-term viability over the next decade, driven by sustained e-commerce growth. Acquisition targets include specialized software platforms enhancing carrier interoperability or hardware manufacturers with unique accessibility features. A critical signal to watch is the adoption rate of new accessibility mandates across major urban centers.
| Strategic Initiative | Industry Significance |
|---|---|
| Geographic Expansion | Broadens market reach into underserved suburban and secondary cities, increasing network utility. |
| Service Diversification | Integrates temperature-controlled compartments, tapping into the growing cold-chain logistics market. |
| Platform Integration | Ensures seamless software interoperability with diverse carrier systems, enhancing open-network models. |
| Accessibility Compliance | Designs terminals meeting ADA standards, expanding user base and ensuring regulatory adherence in the United States. |
| Co-location Partnerships | Leverages shared infrastructure with EV charging stations, creating synergistic value for property owners. |
Research Approach
Two parallel data streams informed the analysis: primary interviews with industry stakeholders and secondary validation from regulatory filings. The primary research engaged logistics executives, e-commerce platform managers, urban planners, and facility managers. Secondary data encompassed postal service reports, e-commerce market analyses, and municipal planning documents. Bottom-up and top-down triangulation ensured robust data synthesis and accuracy.
Forecast inputs considered e-commerce growth rates, urban density projections, and infrastructure development plans across the analysis window. The analytical framework modeled segmentation dimensions including terminal type, technology, application, end user, and regional regulatory frameworks. Compound Annual Growth Rates derived from historical trends and projected market drivers. Key industry-specific inputs included last-mile delivery volume and smart city initiatives.
Sensitivities concentrate around global economic downturns and rapid technology shifts. Forecasts reflect underlying assumptions, though geopolitical instability or unforeseen regulatory changes could revise projections. Quarterly review of e-commerce penetration rates and urban logistics policies is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Robotics and Automation
Grafting Robot Market
Robotics and Automation
Global Medical Robotic Systems Market
Robotics and Automation
India Cloud Robotics Market
Robotics and Automation
Nanorobotics Market
Robotics and Automation
Global Robotics Market
Robotics and Automation
Self-Driving Delivery Robot Market
Robotics and Automation
United States Articulated Robot Market
Robotics and Automation
AGV Software Market
Robotics and Automation
Commercial Service Robotics Market
Robotics and Automation
North America AUV and ROV Market
Robotics and Automation
Nano Robots Market
Robotics and Automation
Asia-Pacific Medical Robots Market
Robotics and Automation
Robotic Process Automation in BFSI Market
Robotics and Automation
Canada Cloud Robotics Market
Robotics and Automation
Firefighting Robots Market
Robotics and Automation
Asia-Pacific Service Robotics Market