
 Electric Power Intelligent Inspection Robot Market | 2026-2036
Electric Power Intelligent Inspection Robot Market Size, Share, and Industry Trends Forecast 2026-2036
Electric Power Intelligent Inspection Robot Market Insights
Aftermarket service revenue is reshaping profit pools across the electric power intelligent inspection robot landscape as hardware margins compress. RedZone Robotics leverages its pipeline robotics heritage to anchor recurring inspection contracts in North American utility networks. General Electric sustains competitive positioning through deep vertical integration into sensor arrays and analytics software. Wuhan Easy-Sight Technology dominates domestic deployment scale across Chinese provincial grid operators.
Electric power intelligent inspection robots are electromechanical platforms integrating locomotion systems, multispectral sensors, and edge-computing modules to traverse energized infrastructure and capture diagnostic data without service interruption. These systems typically operate at voltage ratings from 110 kV to 500 kV, employing infrared thermography and partial discharge detection to identify insulation degradation before failure. Autonomous robots command the largest installed base among product types due to their suitability for repetitive substation rounds, while drones represent the fastest-expanding category for transmission corridor surveys over rough terrain. AI-driven technology segments attract disproportionate R&D investment as utilities demand predictive fault classification rather than raw imagery collection.
China's SAMR enforces GB standards for electromagnetic compatibility and safety in robotic grid equipment, while the country's dual carbon goals from MEE accelerate replacement of manual inspection with electrified automation. In the United States, NERC reliability standards and OSHA electrical safety regulations create compliance-driven procurement cycles for certified inspection platforms. Stakeholders must weigh the capital intensity of full autonomy against regulatory pressure for documented, repeatable inspection protocols as grid modernization budgets tighten.
Market Dynamics
Grid reliability mandates from China's energy administration are accelerating replacement of manual inspection protocols with autonomous electromechanical platforms across provincial transmission networks. This regulatory pressure cascades through procurement cycles as utilities face documented accountability for infrastructure failures.
Growth Catalysts
- Dual carbon goals:China's MEE targets compel grid operators to electrify inspection workflows and eliminate diesel-powered maintenance fleets.
- NERC reliability standards:US utilities deploy certified inspection platforms to satisfy compliance-driven procurement cycles for documented, repeatable protocols.
- Aging 110-500 kV infrastructure:East Asian transmission corridors require non-contact thermal diagnostics that autonomous robots deliver without service interruption.
Market Restraints
- Capital intensity of full autonomy:Edge-computing modules and multispectral sensor arrays require substantial upfront investment that strains municipal utility budgets.
- Supply concentration in precision locomotion:High-torque drive systems for energized environments depend on a narrow base of specialized electromechanical suppliers.
- GB electromagnetic compatibility certification:China's SAMR enforcement creates friction for non-domestic manufacturers seeking grid equipment approval.
Strategic Opportunities
- Rural transmission corridors:Drone-based inspection platforms penetrate rough-terrain segments where wheeled robots face locomotion constraints.
- Outcome-based maintenance contracts:Utilities in Japan's METI jurisdiction experiment with performance-linked service agreements rather than hardware procurement.
- AI-driven predictive fault classification:Convergence of edge computing and infrared thermography enables shift from raw imagery to automated degradation alerts.
Industry Challenges
- Partial discharge detection expertise:Utilities face acute shortages of technicians capable of interpreting insulation degradation signals from robotic sensor arrays.
- Legacy SCADA integration:Substation automation systems built on proprietary protocols resist seamless data ingestion from third-party inspection platforms.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Electric Power Intelligent Inspection Robot Market |
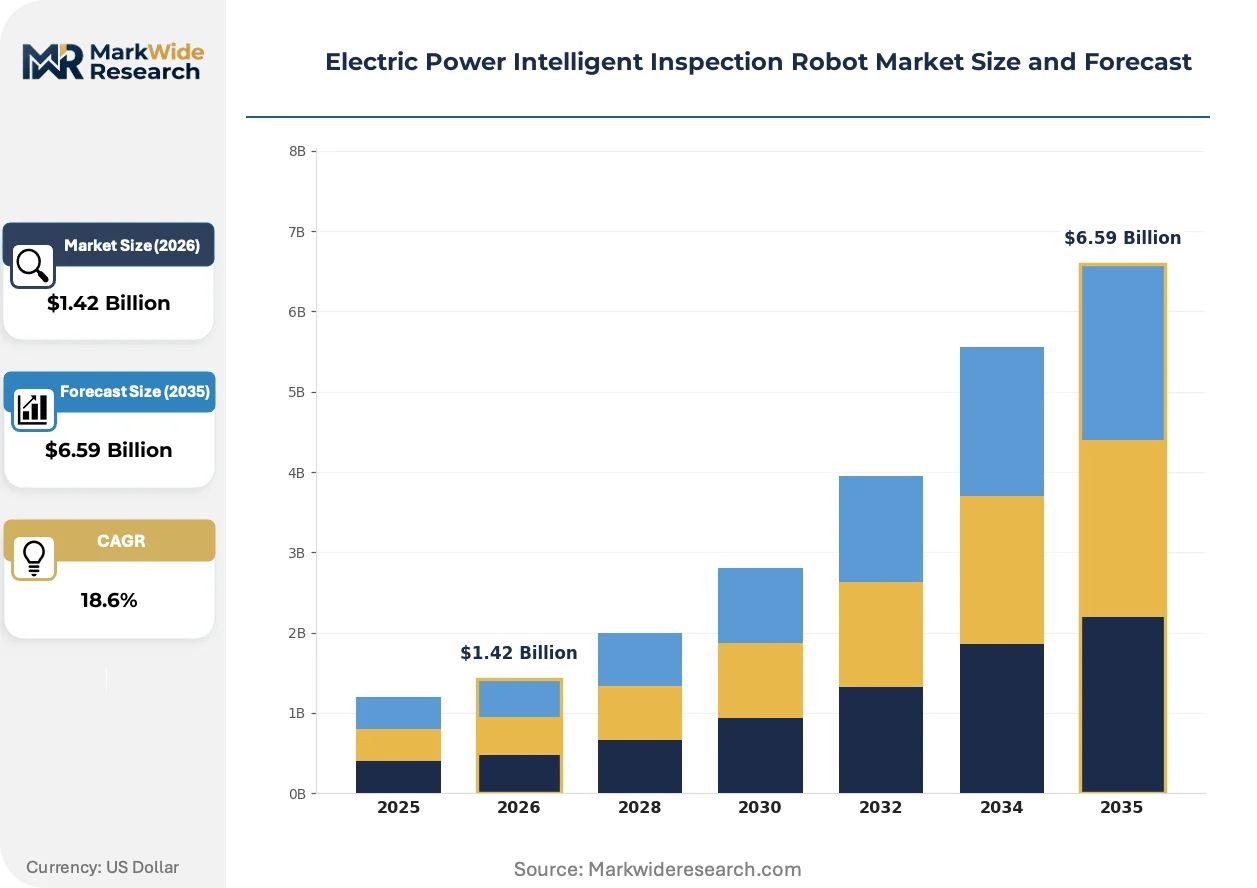
| Market Size in 2026 | $1.42 Billion |
| Market Size in 2035 | $6.59 Billion |
| CAGR (2026 – 2036) | 18.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Autonomous Robots, Drones, Robotic Arms, Fixed Inspection Units End User: Utilities, Energy Providers, Maintenance Contractors, Industrial Facilities Technology: AI-Driven, Image Recognition, Remote Monitoring, Wireless Communication Application: Substation Inspection, Transmission Line Inspection, Routine Maintenance, Emergency Response |
| Companies Covered | RedZone Robotics, Tongren Tuofeng (Beijing) Technology, General Electric, Envirosight, Wuhan Easy-Sight Technology, Xylem, Maxon, IPEK International, Eddyfi Technologies, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Electric Power Intelligent Inspection Robot Market Trends and Innovations
Inspection technology is pivoting from data collection toward autonomous decision-making as edge computing penetrates energized infrastructure environments. This shift compresses response times for fault isolation and redefines competitive advantage around software-defined diagnostics.
Multi-sensor fusion architectures combining infrared thermography, ultraviolet corona detection, and acoustic partial discharge analysis are rendering obsolete single-modality inspection robots that require human interpretation of raw imagery. Japanese utilities under METI guidance have accelerated deployment of these integrated platforms across 275 kV and 500 kV substations. The structural consequence compresses hardware margins while expanding recurring software revenue pools.
China's GB standards for electromagnetic compatibility and robotic grid safety are tightening compliance windows for equipment certification. The SAMR enforcement regime now mandates third-party testing for autonomous platforms operating above 220 kV. Domestic manufacturers with captive certification capabilities capture disproportionate share of provincial grid operator tenders.
Service unbundling is fragmenting traditional hardware-plus-maintenance contracts into discrete software subscriptions, sensor calibration services, and fleet management agreements. European utilities responding to EU Green Deal transparency requirements prefer granular cost visibility over bundled procurement. This behavioral shift is most pronounced in Germany's transmission sector, where TenneT and 50Hertz pilot usage-based inspection pricing.
Electric Power Intelligent Inspection Robot Market Segmentation
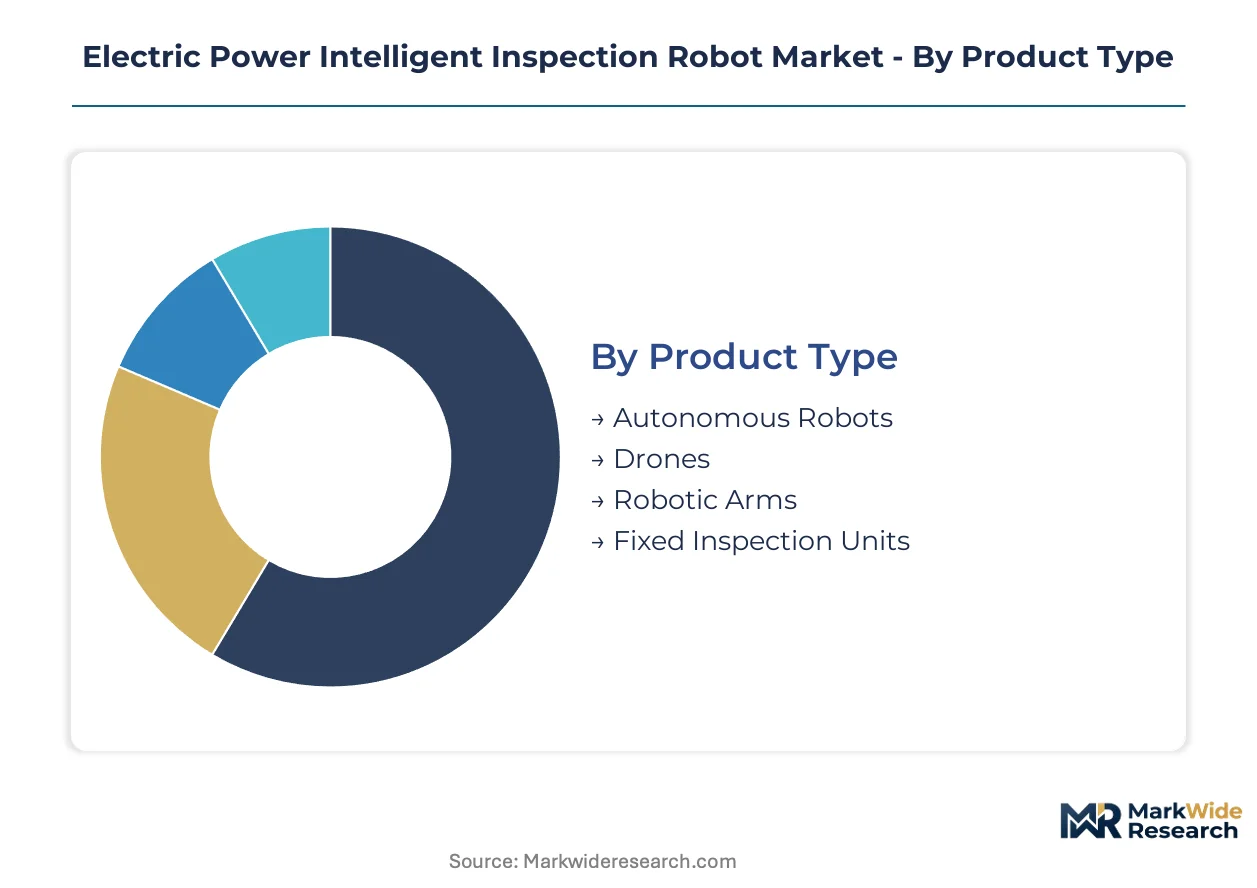
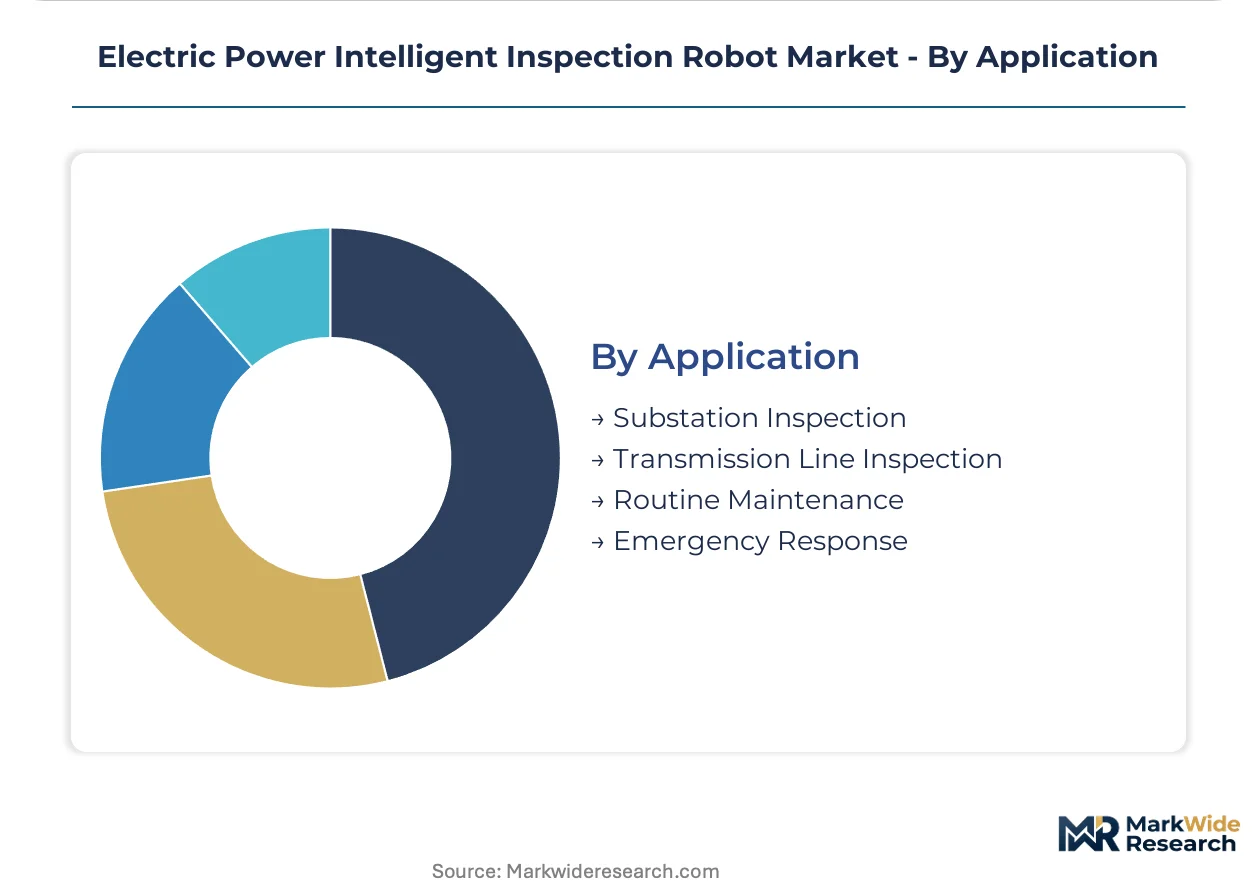
Segmentation in the electric power intelligent inspection robot market reveals how procurement priorities diverge across operational contexts. Voltage ratings, terrain constraints, and regulatory compliance requirements shape purchasing decisions more than unit economics alone.
Product Type:
Mature wheeled platforms coexist with emerging aerial systems as utilities balance reliability against reach.
- Autonomous Robots:Self-propelled electromechanical platforms navigate energized substations on tread or wheel configurations. Chinese provincial grid operators under State Grid Corporation deploy these for repetitive 220 kV and 500 kV substation rounds where electromagnetic interference tolerance is mandatory.
- Drones:Aerial platforms carry multispectral payloads across transmission corridors inaccessible to ground vehicles. Demand concentrates in Japan's mountainous terrain under METI grid reliability directives where helicopter-based inspection costs prove unsustainable.
- Robotic Arms:Articulated manipulators mounted on fixed gantries or mobile bases perform precision close-up inspection of busbars and isolators. German transmission operators TenneT and 50Hertz deploy these for detailed contact-point analysis in compact 380 kV switchyards.
- Fixed Inspection Units:Stationary sensor arrays permanently installed at critical infrastructure points provide continuous monitoring. These units serve South Korean KEPCO substations requiring 24-hour thermal surveillance of transformer banks.
Autonomous robots handle the majority of throughput; drones are expanding most quickly on share.
End User:
Procurement authority concentrates with grid asset owners while service unbundling creates contractor opportunity.
- Utilities:Vertically integrated transmission and distribution operators own the largest installed base of inspection platforms. State Grid Corporation of China maintains autonomous robot fleets exceeding any other single entity globally.
- Energy Providers:Independent power producers and renewable farm operators purchase inspection capacity for generation-side assets. Offshore wind developers in the North Sea contract drone services for turbine-to-substation cable runs.
- Maintenance Contractors:Third-party service providers acquire robotic platforms to fulfill outcome-based contracts. Japanese contractors under METI jurisdiction increasingly lease rather than own inspection equipment.
- Industrial Facilities:Heavy manufacturing and petrochemical complexes operate private electrical infrastructure requiring inspection. German chemical parks along the Rhine deploy fixed inspection units for captive 110 kV substations.
Utilities command the dominant procurement volume; maintenance contractors are gaining share fastest as service models fragment.
Technology:
Software-defined capability is displacing hardware-centric specifications in competitive evaluations.
- AI-Driven:Edge-computing architectures execute predictive fault classification without cloud dependency. These systems attract disproportionate R&D investment from vendors seeking recurring software revenue streams.
- Image Recognition:Computer vision algorithms process visual and thermal imagery for defect identification. Chinese GB standards mandate minimum detection accuracy thresholds for grid equipment certification.
- Remote Monitoring:Telemetry systems transmit sensor data to centralized control centers for human review. US utilities under NERC reliability standards favor documented, repeatable inspection protocols.
- Wireless Communication:Mesh and cellular networks enable real-time data transmission from energized environments. Japan's METI has accelerated spectrum allocation for utility-private 5G networks.
AI-driven platforms capture the steepest expansion trajectory; remote monitoring retains the largest installed base among legacy deployments.
Application:
Operational use cases stratify by voltage exposure risk and frequency of intervention.
- Substation Inspection:Systematic rounds of switchyard equipment including transformers, circuit breakers, and isolators. Autonomous robots dominate this application due to predictable terrain and repetitive route optimization.
- Transmission Line Inspection:Corridor surveys of conductor condition, tower structural integrity, and right-of-way vegetation. Drones represent the primary technology for spans crossing rough terrain or water bodies.
- Routine Maintenance:Scheduled diagnostic activities supporting preventive maintenance programs. German transmission system operators integrate these workflows with asset management software for capital planning.
- Emergency Response:Rapid deployment following storm damage or fault events to assess restoration requirements. Chinese utilities under dual carbon mandates are replacing diesel-powered emergency crews with electrified robotic alternatives.
Substation inspection generates the highest procedure volume; transmission line inspection climbs fastest as aerial platforms proliferate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Price sensitivity concentrates among municipal utilities in North America and Western Europe, where procurement committees scrutinize capital expenditure per kilometer of inspected infrastructure. East Asian grid operators under national reliability mandates demonstrate markedly lower elasticity, prioritizing electromagnetic compatibility certification and documented fault-detection accuracy over unit cost.
China
State Grid Corporation and Southern Power Grid drive fleet expansion across 220 kV and 500 kV substations under MEE dual carbon mandates. SAMR enforces GB electromagnetic compatibility standards that domestic manufacturers navigate more efficiently than foreign entrants. Deployment concentrates in Jiangsu and Zhejiang provinces where aging coastal transmission infrastructure requires continuous thermal monitoring.
United States
Investor-owned utilities face NERC reliability standard compliance cycles that favor certified inspection platforms with documented repeatability. OSHA electrical safety regulations constrain manual live-line work, accelerating robotic substitution in high-voltage environments. Procurement activity clusters in Texas and California where independent system operators manage extensive transmission corridors.
Japan
METI grid reliability directives compel replacement of helicopter-based inspection in mountainous terrain with drone platforms. JIS standards for robotic grid equipment create certification friction for non-domestic suppliers. Deployment focuses on Chubu Electric's 275 kV and 500 kV substations around Nagoya and Tokyo Electric's coastal transmission spine.
Germany
TenneT and 50Hertz pilot outcome-based maintenance contracts under EU Green Deal transparency requirements, unbundling hardware from service procurement. REACH and CE marking govern electromechanical platform certification. Fixed robotic arm installations concentrate in North Rhine-Westphalia's compact 380 kV switchyards along the Rhine industrial corridor.
South Korea
KEPCO maintains 24-hour thermal surveillance mandates for transformer banks that favor permanently installed fixed inspection units. MFDS-equivalent grid equipment standards align with IEC frameworks for electromagnetic compatibility. Deployment centers on Seoul metropolitan substations and the southeastern industrial belt around Busan.
Electric Power Intelligent Inspection Robot Market Competitive Landscape
Capability concentration sits with specialized electromechanical firms possessing captive certification expertise; scale advantage sits with diversified industrial conglomerates leveraging procurement relationships with national grid operators. The vendor base stratifies into three tiers: domestic champions with SAMR certification pipelines, multinational technology integrators with sensor array backward integration, and regional service contractors leasing equipment under outcome-based agreements. Dominant competitive moves include strategic partnerships between locomotion specialists and AI software providers, plus geographic expansion through provincial grid operator tender participation.
Among North American robotics specialists, RedZone Robotics exemplifies the recurring-contract archetype anchored in pipeline inspection heritage. Chinese domestic champions Wuhan Easy-Sight Technology and Tongren Tuofeng (Beijing) Technology occupy positions within the certification-advantaged tier serving State Grid Corporation procurement cycles. General Electric represents the diversified industrial archetype with upstream control over sensor manufacturing and analytics platforms.
| Leading Market Players |
|---|
| RedZone Robotics |
| Tongren Tuofeng (Beijing) Technology |
| General Electric |
| Envirosight |
| Wuhan Easy-Sight Technology |
| Xylem |
| Maxon |
| IPEK International |
| Eddyfi Technologies |
| Others |
Pricing and Supply Chain Analysis
Overcapacity in precision electromechanical drive systems across East Asian manufacturing hubs is compressing component pricing while simultaneously eroding supplier willingness to absorb certification costs for non-standard voltage ratings. This utilization dynamic forces buyers toward bundled procurement models that internalize compliance risk.
Pricing Analysis
Long-term service contracts dominate procurement for autonomous inspection platforms, with Chinese provincial grid operators favoring multi-year fleet management agreements over per-unit transactional purchases. Price differentiation hinges on GB electromagnetic compatibility certification tier and after-sales software subscription depth. Cost compression in mid-tier sensor arrays is intensifying because domestic manufacturers are capturing scale advantages in Jiangsu and Zhejiang production clusters. Municipal utilities in North America exhibit the highest price sensitivity due to capital expenditure committee scrutiny, while East Asian state-owned grid operators prioritize documented fault-detection accuracy over unit economics.
Supply Chain Analysis
Tariff exposure between the United States and China dominates supply chain risk planning for multispectral sensor arrays and edge-computing modules. Manufacturing concentration rests on China, Japan, and Germany for high-torque locomotion systems, precision infrared optics, and electromagnetic shielding components. Raw material dependencies draw from rare-earth magnet supply for drive motors, germanium substrates for thermal cameras, and specialized alloys for energized-environment enclosures. Single-source vulnerability persists in partial discharge detection sensors certified for 500 kV operation. Distribution runs through direct utility procurement channels and specialized industrial automation distributors serving maintenance contractor networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market is approaching a platform-economics inflection where interoperability between robotic inspection systems and utility SCADA architectures will determine competitive survival. The convergence of edge AI and standardized data protocols is reshaping value capture toward software-defined recurring revenue.
For Market Incumbents: Harden defensive positions by securing captive certification pipelines for China's SAMR GB standards above 220 kV, insulating against domestic manufacturer cost advantages. Deepen backward integration into sensor array production to preserve margin structure as hardware commoditization accelerates. Prioritize API development for legacy SCADA integration to lock in switching costs with utility customers facing technician shortages.
For New Entrants and Emerging Players: Establish a beachhead in drone-based transmission corridor inspection for Japan's mountainous terrain under METI reliability directives, where helicopter substitution creates immediate demand. Target maintenance contractor leasing models in Germany's TenneT and 50Hertz networks, where outcome-based contracts favor equipment-as-a-service over capital purchase. Deploy AI-driven predictive fault classification as the primary go-to-market wedge against legacy remote monitoring incumbents.
For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting downward across fixed inspection unit manufacturing as standardized sensor platforms achieve modular scale. Long-term viability favors vendors with software subscription attach rates above hardware replacement cycles. Acquisition targets should display captive electromagnetic compatibility certification capabilities and established provincial grid operator relationships. The signal to watch is SAMR enforcement velocity for non-domestic equipment approval, which will determine competitive access to China's fleet expansion programs.
| Strategic Initiative | Industry Significance |
|---|---|
| AI Software Platform Integration | Edge-computing architectures from vendors like General Electric enable predictive fault classification without cloud dependency. |
| GB Certification Pipeline Investment | Domestic manufacturers with SAMR-captive testing capabilities capture disproportionate share of State Grid Corporation tenders. |
| Outcome-Based Service Contracting | German transmission operators TenneT and 50Hertz pilot usage-based pricing under EU Green Deal transparency requirements. |
| 5G Spectrum Allocation for Private Networks | Japan's METI has accelerated utility-private spectrum deployment for real-time robotic telemetry in energized substations. |
| Multi-Sensor Fusion Architecture Development | Japanese utilities under METI guidance deploy integrated infrared-ultraviolet-acoustic platforms across 275 kV and 500 kV infrastructure. |
Research Methodology
A standing panel of utility planning officers, substation automation engineers, robotics procurement leads, and aftermarket service directors provided ongoing calibration across the study period. Primary interviews combined with secondary validation from FERC filings, EIA grid infrastructure databases, SAMR certification registries, and IEC electromagnetic compatibility standards. Bottom-up unit deployment estimates triangulated against top-down utility capital expenditure disclosures.
Scenario-bracketing framed analytical outputs across the projection horizon, with sensitivity bands for regulatory enforcement velocity and technology substitution rates. Segmentation dimensions modeled include product type, voltage rating tier, technology architecture, and regional regulatory cluster. CAGRs derived from installed base growth curves and replacement cycle analysis, incorporating AI adoption velocity and dual carbon mandate implementation pace as industry-specific inputs.
Stress conditions across SAMR certification timeline compression, rare-earth magnet supply disruption, and utility budget constraint severity were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions regarding grid reliability mandate enforcement and autonomous platform technical maturation. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Robotics and Automation
Robotic Desktop Automation (RDA) Market
Robotics and Automation
Motion Control Software in Robotics Market
Robotics and Automation
Sweden Robotic Lawn Mower Market
Robotics and Automation
Mobile Robotics Market
Robotics and Automation
China Autonomous Mobile Robot Market
Robotics and Automation
Asia-Pacific Medical Robots Market
Robotics and Automation
Asia-Pacific AUV and ROV Market
Robotics and Automation
Asrs and Ruos Market
Robotics and Automation
Healthcare Assistive Robot Market
Robotics and Automation
Professional Service Robots Market
Robotics and Automation
Data Center Robotics Market
Robotics and Automation
Automotive Robotics Market
Robotics and Automation
Deep Sea Robot Market
Robotics and Automation
Europe Warehouse Robotics Market
Robotics and Automation
Smart Exoskeleton Market
Robotics and Automation
Pipe Inspection Robot Market