
 Simultaneous Localization and Mapping (SLAM) Technology Market | 2026-2036
Simultaneous Localization and Mapping (SLAM) Technology Market Size, Share, and Industry Trends Forecast 2026-2036
Simultaneous Localization and Mapping (SLAM) Technology Market Analysis
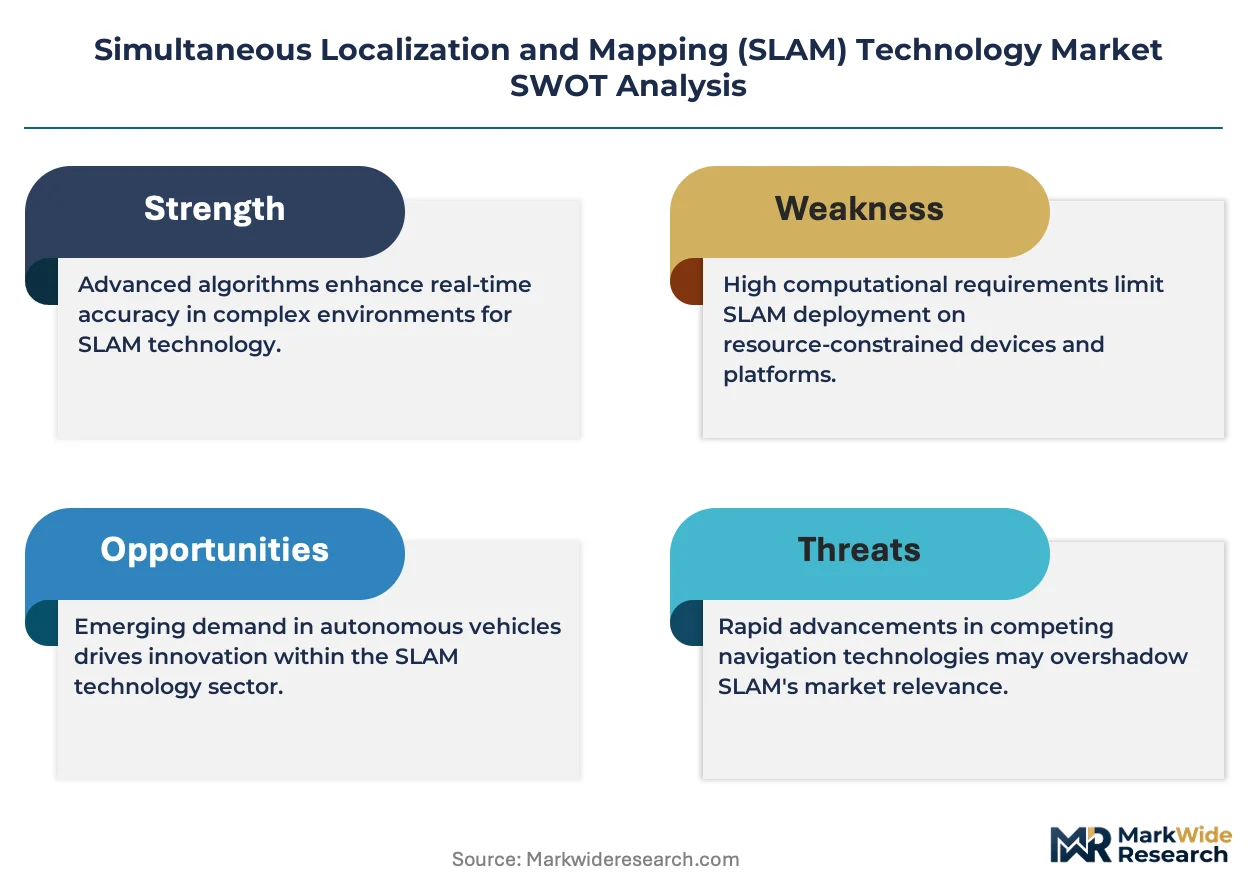
Real-time 3D spatial accuracy at centimeter-grade resolution is reorganizing competitive requirements across the SLAM technology landscape. Google leverages its Street View mapping corpus and TensorFlow inference stacks to sustain algorithmic leadership in large-scale visual SLAM. Apple anchors premium hardware-software integration through its dedicated spatial computing silicon and tight sensor fusion pipelines. NavVis differentiates by controlling end-to-end mobile mapping workstations for industrial digital twin creation.
Simultaneous Localization and Mapping denotes the computational process by which an autonomous agent constructs or updates a map of an unknown environment while simultaneously tracking its own position within that map, typically relying on probabilistic estimation frameworks such as Extended Kalman Filters or graph-based optimization running at 10-30 Hz refresh rates to maintain pose consistency. The technology serves the primary commercial purpose of enabling navigation without GPS dependency in GPS-denied environments including warehouses, mines, and indoor facilities. Visual SLAM and lidar SLAM currently occupy divergent margin structures, with lidar commanding higher hardware attach rates in precision manufacturing while visual approaches penetrate cost-sensitive logistics robotics through camera-minimal designs. Application traction clusters heavily around Automated Guided Vehicles and autonomous drones, where path planning reliability directly determines operational uptime.
The Federal Aviation Administration governs beyond-visual-line-of-sight drone operations in the United States, compelling SLAM-equipped UAV manufacturers to demonstrate redundant navigation failover capabilities before commercial certification. The European Union's Machinery Directive and CE marking framework mandate functional safety validations for autonomous mobile robots operating near human workers, elevating compliance costs for graph-based SLAM deployments in European manufacturing. China's Ministry of Industry and Information Technology issues GB standards for service robot navigation performance, creating a regulated domestic testing pathway for lidar SLAM systems. Stakeholders must monitor how divergent national certification timelines for autonomous navigation reshape geographic deployment sequencing and partnership priorities.
Market Dynamics
Centimeter-grade spatial accuracy requirements are compressing hardware margins while elevating software licensing value in autonomous navigation stacks. The divergence between lidar and visual SLAM cost structures is forcing vendors to choose between precision manufacturing premiums and logistics robotics volume.
Growth Catalysts
- Warehouse automation mandates:Fulfillment operators in Germany and the Netherlands are deploying autonomous mobile robots for material transport, creating sustained demand for robust indoor navigation systems.
- EU AI Act compliance pathways:European commercial space operators must validate autonomous system performance, accelerating certification-ready SLAM software procurement.
- China's smart city infrastructure:Domestic robotics manufacturers and municipal projects are scaling lidar-based mapping deployments at unprecedented rates, concentrating hardware demand.
Market Restraints
- Lidar sensor cost volatility:Solid-state lidar component shortages and foundry capacity constraints in Taiwan are inflating hardware attach rates for precision manufacturing applications.
- Computational latency thresholds:Graph-based optimization running below 10 Hz refresh rates fails to maintain pose consistency in high-speed autonomous drones, limiting deployment scenarios.
- CE marking timeline friction:The European Union's Machinery Directive functional safety validations extend certification cycles for autonomous mobile robots operating near human workers.
Strategic Opportunities
- Underpenetrated mining autonomy:Underground operations in Australia and Canada remain GPS-denied environments where robust SLAM navigation can displace beacon-dependent systems.
- Sensor fusion convergence:Integration of event cameras with traditional frame-based visual SLAM promises order-of-magnitude latency improvements for drone obstacle avoidance.
- India's PLI scheme for robotics:Production-linked incentives for service robot manufacturing are creating a regulated domestic testing pathway for navigation software vendors.
Industry Challenges
- Probabilistic estimation expertise scarcity:Extended Kalman Filter and factor graph optimization specialists command premium compensation, constraining algorithm team scaling.
- FAA certification timeline uncertainty:Beyond-visual-line-of-sight drone operators face unpredictable redundant navigation failover demonstration requirements.
- Legacy warehouse management system integration:Real-time pose data streaming into existing fleet orchestration software requires custom middleware development.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Simultaneous Localization and Mapping (SLAM) Technology Market |
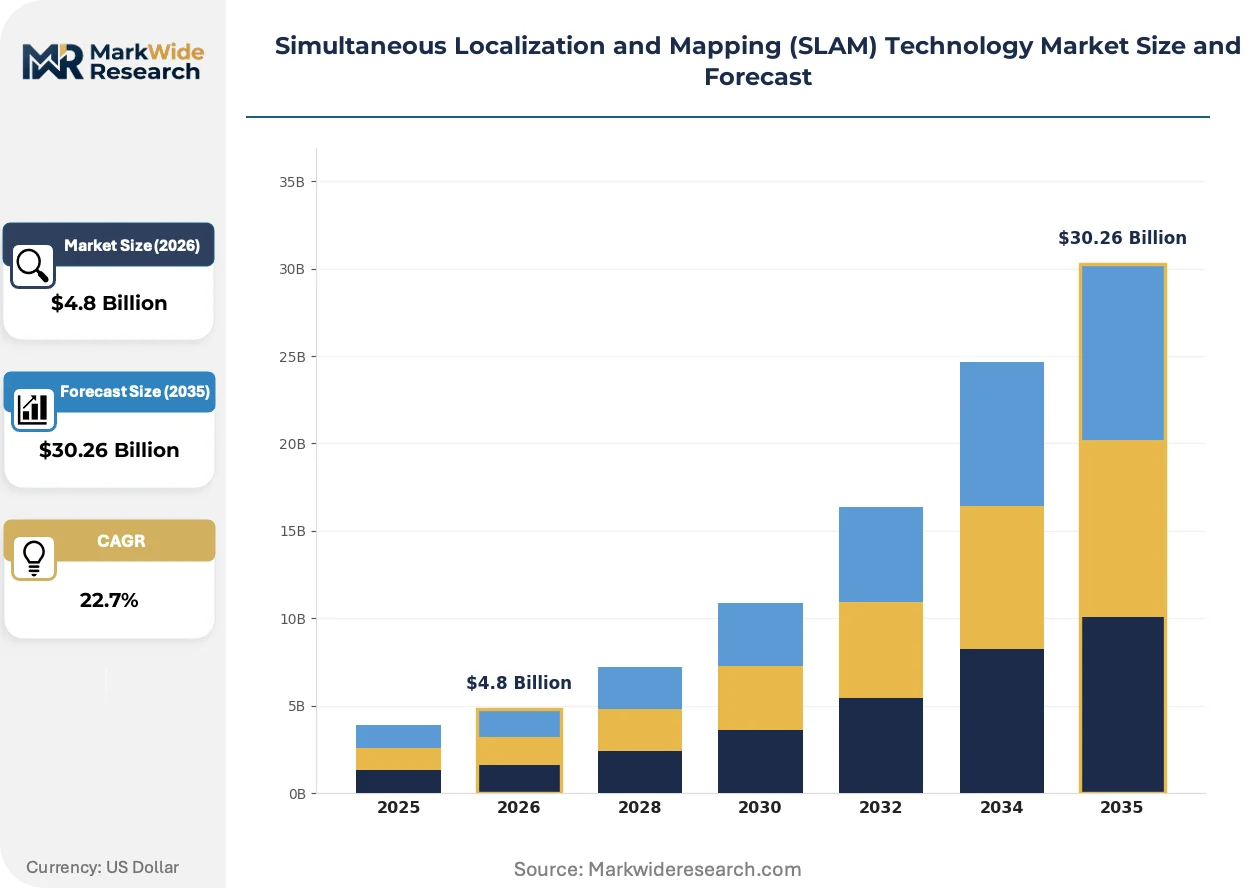
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $30.26 Billion |
| CAGR (2026 – 2036) | 22.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: 2D SLAM, 3D SLAM, Visual SLAM, Lidar SLAM Application: Automated Guided Vehicles, Drones, Robotics, Augmented Reality End User: Manufacturing, Logistics, Healthcare, Agriculture Technology: EKF, Particle Filter, Graph-based, QR Code |
| Companies Covered | Google, Apple, Microsoft, Amazon Robotics, Clearpath Robotics, NavVis, SLAMcore, Niantic, Locus Robotics, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Simultaneous Localization and Mapping (SLAM) Technology Market Emerging Trajectories
Algorithm-hardware co-design is compressing the traditional separation between sensing modalities and computational backends. Vendors are embedding neural inference directly into sensor head firmware to reduce bandwidth constraints and latency.
Event-based vision sensors are supplanting conventional frame cameras in high-dynamic-range industrial environments. Automotive tier-one suppliers are integrating these bio-inspired sensors into next-generation autonomous mobile robots for warehouse logistics. The technology is supplanting expensive lidar configurations in cost-sensitive material transport applications while maintaining navigation reliability.
The EU AI Act's risk-based classification system is imposing documentation burdens on autonomous navigation software deployed in European commercial spaces. High-risk system providers must maintain technical files demonstrating performance validation against harmonized standards. Autonomous mobile robot manufacturers targeting German manufacturing facilities are restructuring quality management systems to satisfy conformity assessment body requirements.
Robot-as-a-service procurement models are displacing capital expenditure approaches in mid-sized logistics operations. Third-party fleet operators in the United States are absorbing hardware obsolescence risk while charging per-pallet-moved fees. The shift is most visible among e-commerce fulfillment providers lacking internal robotics integration capabilities.
Simultaneous Localization and Mapping (SLAM) Technology Market Segmentation
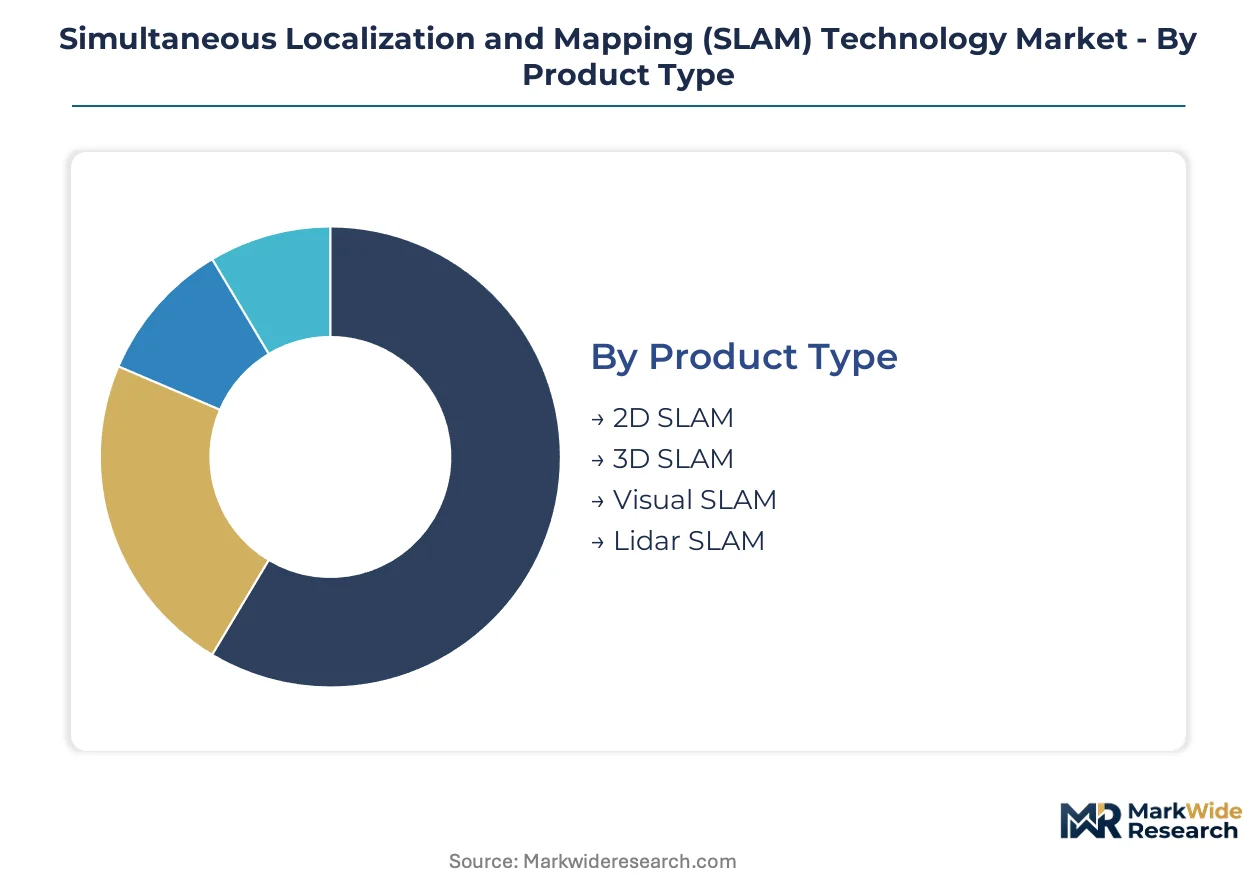
SLAM technology segmentation reveals divergent margin structures across sensing modalities and computational approaches. Hardware-software coupling intensity varies dramatically by application, reshaping vendor specialization strategies.
Product Type:
Margin pools concentrate in lidar SLAM configurations serving precision manufacturing, while visual SLAM penetrates cost-sensitive logistics robotics through camera-minimal designs.
- 3D SLAM:Dense point cloud reconstruction enables sub-centimeter spatial accuracy for digital twin creation and industrial metrology. German automotive manufacturers and Chinese smart city infrastructure projects are scaling deployments where geometric fidelity determines operational value.
- Visual SLAM:Frame-based and event-camera approaches leverage commodity imaging sensors to reduce hardware attach rates. Warehouse automation mandates in the Netherlands and fulfillment operator procurement in the United States are accelerating adoption where cost-per-robot dominates investment decisions.
- 2D SLAM:Occupancy grid mapping for flat-floor environments serves Automated Guided Vehicle navigation in structured warehouse layouts.
- Lidar SLAM:Time-of-flight and solid-state configurations command premium pricing in GPS-denied mining operations across Australia and Canada.
3D SLAM holds installed capacity. Visual SLAM is rotating up the share rankings.
Application:
Volume concentration sits with material transport systems, while steepest expansion trajectory emerges in aerial platforms facing FAA certification timelines.
- Automated Guided Vehicles:Fleet orchestration software integration demands real-time pose streaming at 10-30 Hz refresh rates. Fulfillment operators in Germany and the Netherlands are deploying autonomous mobile robots where CE marking under the EU Machinery Directive mandates functional safety validation.
- Drones:Beyond-visual-line-of-sight operations require redundant navigation failover demonstrations before FAA commercial certification. Agricultural spraying and infrastructure inspection in China are scaling lidar-based mapping under MIIT GB standards.
- Robotics:Service robot navigation performance testing follows regulated domestic pathways in India under PLI scheme incentives.
- Augmented Reality:Spatial computing silicon integration drives premium hardware-software coupling for indoor positioning and occlusion handling.
Automated Guided Vehicles anchor current procurement volumes. Drones are climbing the fastest.
End User:
Customer-type differentiation separates capital-intensive manufacturing from robotics-as-a-service logistics models absorbing hardware obsolescence risk.
- Logistics:Third-party fleet operators in the United States charge per-pallet-moved fees, displacing capital expenditure approaches among e-commerce fulfillment providers lacking internal robotics integration capabilities. Warehouse management system middleware requirements create customization friction.
- Manufacturing:Precision assembly and quality inspection demand centimeter-grade spatial accuracy where solid-state lidar component shortages in Taiwan inflate hardware attach rates.
- Healthcare:Hospital navigation and surgical assistance applications face extended CE marking cycles for autonomous systems operating near human workers.
- Agriculture:Autonomous tractors and crop monitoring platforms in Australia leverage SLAM for GPS-denied orchard environments.
Manufacturing retains premium pricing power. Logistics is gaining share fastest through RaaS proliferation.
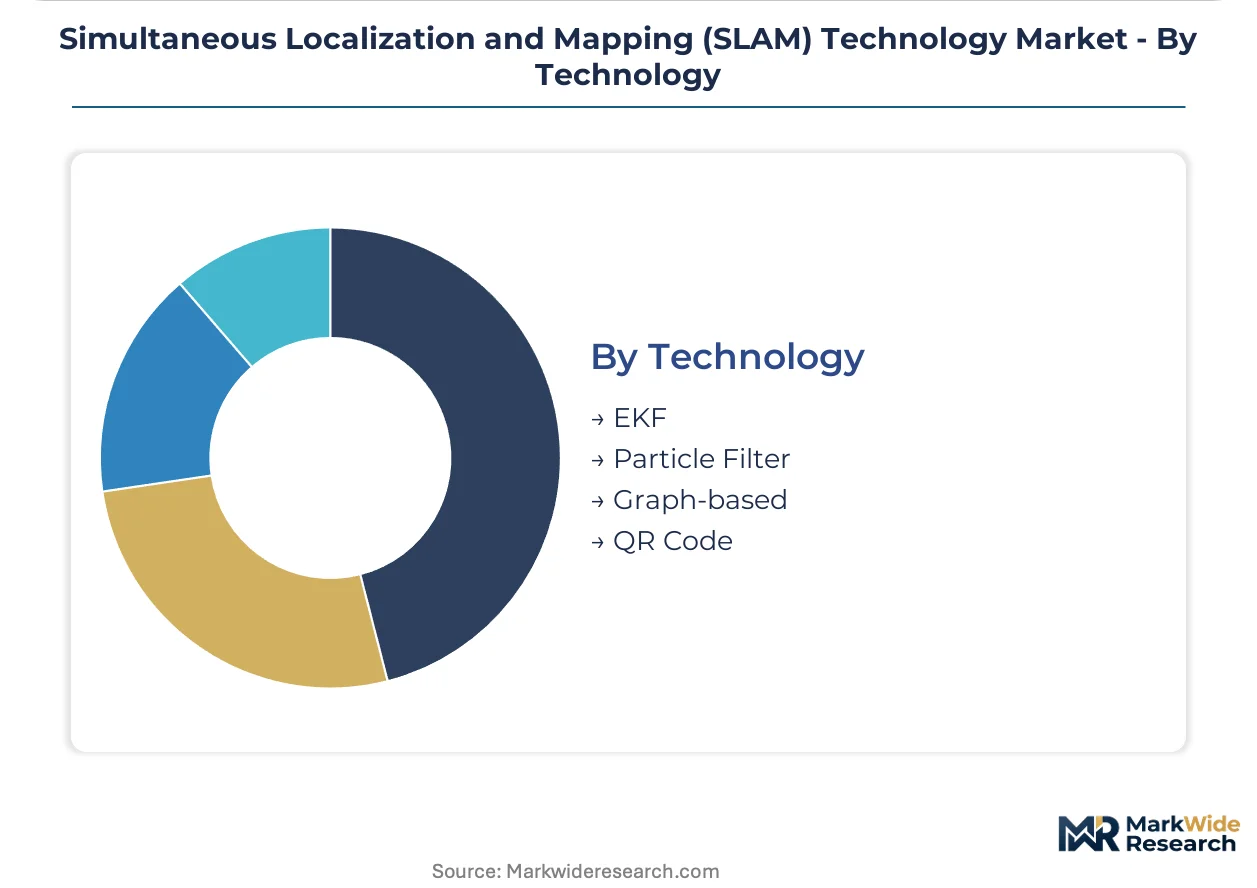
Technology:
Computational backend selection determines latency thresholds and probabilistic estimation expertise requirements, with graph-based optimization commanding specialist compensation premiums.
- Graph-based:Factor graph optimization delivers superior accuracy for large-scale mapping but requires refresh rates above 10 Hz to maintain pose consistency in high-speed drone applications. European commercial space operators under EU AI Act risk-based classification must document technical files for high-risk navigation software.
- EKF:Extended Kalman Filter implementations dominate embedded systems with constrained computational resources. Scarcity of probabilistic estimation specialists constrains algorithm team scaling across vendors.
- Particle Filter:Monte Carlo localization approaches serve robustness-critical applications with non-Gaussian noise models.
- QR Code:Artificial landmark dependency provides deterministic positioning fallback for hybrid SLAM systems in structured industrial corridors.
Graph-based holds algorithmic leadership. EKF maintains embedded volume dominance.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Foundry capacity constraints in Taiwan and certification bottlenecks across multiple jurisdictions are redistributing hardware deployment timelines. Vendors now sequence geographic entry based on regulator readiness rather than demand magnitude alone.
United States
FAA beyond-visual-line-of-sight certification requirements are compressing drone navigation software procurement cycles. The agency's redundant failover demonstrations are extending commercial deployment timelines for SLAM-equipped UAV manufacturers. Agricultural spraying operators in California's Central Valley and infrastructure inspection providers in Texas are absorbing these compliance costs to access early-mover advantages.
China
MIIT GB standards for service robot navigation performance are creating regulated domestic testing pathways that favor local lidar SLAM vendors. Smart city infrastructure projects in Shenzhen and Hangzhou are scaling deployments at rates unmatched elsewhere. Domestic robotics manufacturers in the Yangtze River Delta are capturing municipal procurement contracts through compliance proximity.
Germany
CE marking under the EU Machinery Directive is mandating functional safety validations for autonomous mobile robots operating near human workers. Fulfillment operators in the Netherlands and Germany are deploying warehouse automation at scale, creating concentrated demand for certification-ready navigation stacks. Industrial clusters in Bavaria and North Rhine-Westphalia are restructuring quality management systems to satisfy conformity assessment body requirements.
Australia
Underground mining operations in Western Australia and Queensland remain GPS-denied environments where robust SLAM navigation displaces beacon-dependent positioning systems. The country's national mining safety regulator is evaluating autonomous vehicle navigation performance standards for subterranean deployments. Perth-based mining services firms are piloting lidar-based mapping for autonomous haulage in iron ore operations.
India
PLI scheme production-linked incentives for service robot manufacturing are attracting navigation software vendors to establish regulated domestic testing capabilities. E-commerce fulfillment providers in Maharashtra and Karnataka lack internal robotics integration expertise, creating openings for third-party fleet operators. Mumbai and Bangalore are emerging as pilot markets for robot-as-a-service procurement models.
Simultaneous Localization and Mapping (SLAM) Technology Market Vendor Landscape
Technology leadership and cost leadership are held by different player archetypes across the SLAM technology landscape. The vendor base separates into precision-manufacturing specialists commanding lidar premiums and logistics-focused challengers driving camera-minimal designs. Three archetypes dominate: hyperscale cloud platforms with mapping corpora, dedicated spatial computing hardware-software integrators, and industrial mobile mapping workstation providers. Competitive moves concentrate on algorithm-hardware co-design partnerships and sensor fusion convergence licensing.
Within the hyperscale platform tier, Google and Apple exemplify divergent strategic positions. Google leverages its Street View mapping corpus and TensorFlow inference infrastructure to sustain algorithmic leadership in large-scale visual SLAM deployments. Apple anchors premium hardware-software integration through dedicated spatial computing silicon and tight sensor fusion pipelines. NavVis occupies a distinct position controlling end-to-end mobile mapping workstations for industrial digital twin creation, representing the specialized equipment archetype against platform breadth.
| Leading Market Players |
|---|
| Apple |
| Microsoft |
| Amazon Robotics |
| Clearpath Robotics |
| NavVis |
| SLAMcore |
| Niantic |
| Locus Robotics |
| Others |
Supply Flow & Price Mechanics
Long-term capacity reservation contracts with Taiwanese foundries lock in lidar sensor supply visibility while capping hardware attach rate volatility for precision manufacturing SLAM deployments. These arrangements tether pricing power to semiconductor fabrication slot allocation under MIIT and CE marking compliance timelines.
Pricing Analysis
EU AI Act risk-based classification dictates the pricing tier structure for navigation software deployed in European commercial spaces. Three-tier pricing structure across premium, standard, and economy levels separates CE-marked functional safety stacks from uncertified algorithmic cores. Price differentiation hinges on certification grade under Machinery Directive mandates and after-sales service bundling for fleet orchestration middleware. Cost compression in visual SLAM tiers is intensifying because camera-minimal designs displace lidar in logistics robotics procurement. Third-party fleet operators in the United States exhibit highest price sensitivity, while German automotive manufacturers absorb premium lidar SLAM attach rates for metrology-grade digital twin creation.
Supply Chain Analysis
Taiwan and South Korea anchor wafer fabrication for solid-state lidar components and spatial computing silicon. The SLAM hardware pipeline draws from Japanese precision optics for time-of-flight sensors and Chinese rare earth processing for magnetometer subsystems. Single-source vulnerability concentrates in Taiwanese foundry capacity for automotive-grade lidar ASICs. Distribution runs through direct OEM integration for precision manufacturing and robot-as-a-service fleet operators for logistics volume procurement.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Software licensing and certification-ready navigation stacks represent the fastest-expanding recurring-revenue layer, outpacing hardware attach rates as fulfillment operators outsource fleet integration risk.
For Market Incumbents: Compound algorithm-hardware co-design partnerships to defend against sensor fusion convergence from automotive tier-one suppliers entering warehouse logistics. Secure captive supply of solid-state lidar components through backward integration into Taiwanese foundry capacity reservation. Accelerate EU AI Act technical file documentation to maintain premium pricing in German manufacturing clusters. For New Entrants and Emerging Players: India's PLI scheme certification fast-track offers regulated domestic testing pathways with lower compliance friction than European CE marking cycles. Target underpenetrated underground mining autonomy in Western Australia and Queensland where beacon-dependent positioning systems face displacement. Lead with robot-as-a-service fleet operator partnerships to bypass capital expenditure barriers among e-commerce fulfillment providers lacking internal robotics integration. For Investors and Strategic Acquirers: Specialized industrial mobile mapping workstation providers with end-to-end digital twin creation capabilities represent acquisition targets with defensible margin pools against hyperscale platform commoditization. Long-term viability centers on algorithmic differentiation in GPS-denied environments rather than sensor hardware volume. Watch FAA beyond-visual-line-of-sight certification timeline clarity as inflection indicator for drone navigation software valuations.| Strategic Initiative | Industry Significance |
|---|---|
| Sensor Fusion Convergence Partnership | Event camera integration with visual SLAM reduces latency for drone obstacle avoidance in FAA-regulated airspace. |
| CE Marking Fast-Track Investment | Machinery Directive compliance acceleration unlocks German fulfillment operator procurement concentrated in Bavaria. |
| Lidar Foundry Capacity Reservation | Taiwanese fabrication slot locking insulates against solid-state component shortages in precision manufacturing tiers. |
| Robot-as-a-Service Platform Launch | Per-pallet-moved fee structures absorb hardware obsolescence risk for e-commerce providers in Maharashtra and Karnataka. |
| Mining Autonomy Pilot Deployment | Western Australian iron ore operations validate lidar-based mapping for autonomous haulage under national safety regulator evaluation. |
Methodological Framework
Operator-level perspectives from warehouse fleet managers, autonomous mobile robot procurement leads, SLAM algorithm engineering directors, and conformity assessment body auditors anchored the qualitative base. Primary interview insights combined with secondary validation from FAA certification filings, MIIT GB standard documentation, EU AI Act technical file repositories, and SEC 10-K hyperscaler capex disclosures. Bottom-up unit economics from lidar and camera sensor attach rates triangulated against top-down market sizing from smart city infrastructure procurement databases.
Sensitivity analysis across algorithm-hardware coupling intensity, certification timeline scenarios, and foundry capacity utilization framed the projection horizon. Segmentation dimensions modeled include sensing modality, computational backend architecture, application velocity tier, and regional regulatory cluster. CAGRs derived from weighted scenario outcomes across warehouse automation mandate trajectories and mining autonomy pilot conversion rates. Industry-specific inputs incorporated refresh rate thresholds for pose consistency and probabilistic estimation specialist compensation premiums.
Decision-makers should treat outputs as directional under sustained lidar cost compression and stable FAA certification pathway assumptions; material deviation in Taiwanese foundry capacity or EU AI Act enforcement intensity would warrant model refresh. Recalibration cycles align with material shifts in national autonomous navigation certification timelines and solid-state sensor yield improvements.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Robotics and Automation
Global K-12 Robotic Toolkits Market
Robotics and Automation
Smart Personal Assistance Devices Market
Robotics and Automation
Cognitive Robotic Process Automation Market
Robotics and Automation
Commercial Security Robots Market
Robotics and Automation
Southeast Asia Industrial and Service Robot Market
Robotics and Automation
Robot Charging Station Market
Robotics and Automation
Healthcare Assistive Robot Market
Robotics and Automation
Cleaning Robot Market
Robotics and Automation
Global Robot Kitchen Market
Robotics and Automation
Hotel Robot Market
Robotics and Automation
Robotic Welding Market
Robotics and Automation
Global Robotics Market
Robotics and Automation
Medical Robotics Market
Robotics and Automation
Internet of Robotic Things Market
Robotics and Automation
Pharmaceutical Collaborative Robots Market
Robotics and Automation
Cloud Robotics Market