
 Global Rescue Robot Market | 2026-2036
Global Rescue Robot Market Size, Share, and Industry Trends Forecast 2026-2036
Global Rescue Robot Market Outlook
The gap between military-spec rescue platforms and municipal-grade emergency units is repositioning how vendors allocate engineering resources and pricing power. Boston Dynamics leverages its legged locomotion heritage to dominate terrain-adaptive ground systems for defense clients. Lockheed Martin Corporation anchors long-cycle government contracts through integrated command-and-control architectures. iRobot Corporation competes in the compact, throwable robot segment where portability drives municipal purchasing decisions.
Rescue robots are electromechanical systems engineered for autonomous or teleoperated intervention in hazardous environments, typically incorporating thermal cameras, LiDAR mapping, and manipulator arms rated for debris lifting exceeding 50 kilograms. Their primary purpose is to locate, assess, and extract human subjects from structural collapse, chemical contamination, or submerged conditions without exposing responders to mortal risk. Ground robots lead product type revenue owing to battery density limitations that constrain aerial endurance in disaster zones. Sensor integration represents the fastest-growing technology segment as multi-spectral fusion becomes standard for smoke-penetrating visibility. Artificial Intelligence remains a margin pool where proprietary navigation algorithms command pricing premiums from defense end users.
FAA regulations govern beyond-visual-line-of-sight drone operations for aerial rescue missions in the United States, while the EU AI Act imposes conformity assessments on autonomous decision-making systems deployed in European emergency services. Japan's PMDA collaborates with METI on medical-extraction robot standards that blend device safety with rescue functionality. Stakeholders must monitor whether emerging liability frameworks for autonomous harm decisions will fragment certification requirements across jurisdictions or consolidate toward ISO interoperability benchmarks.
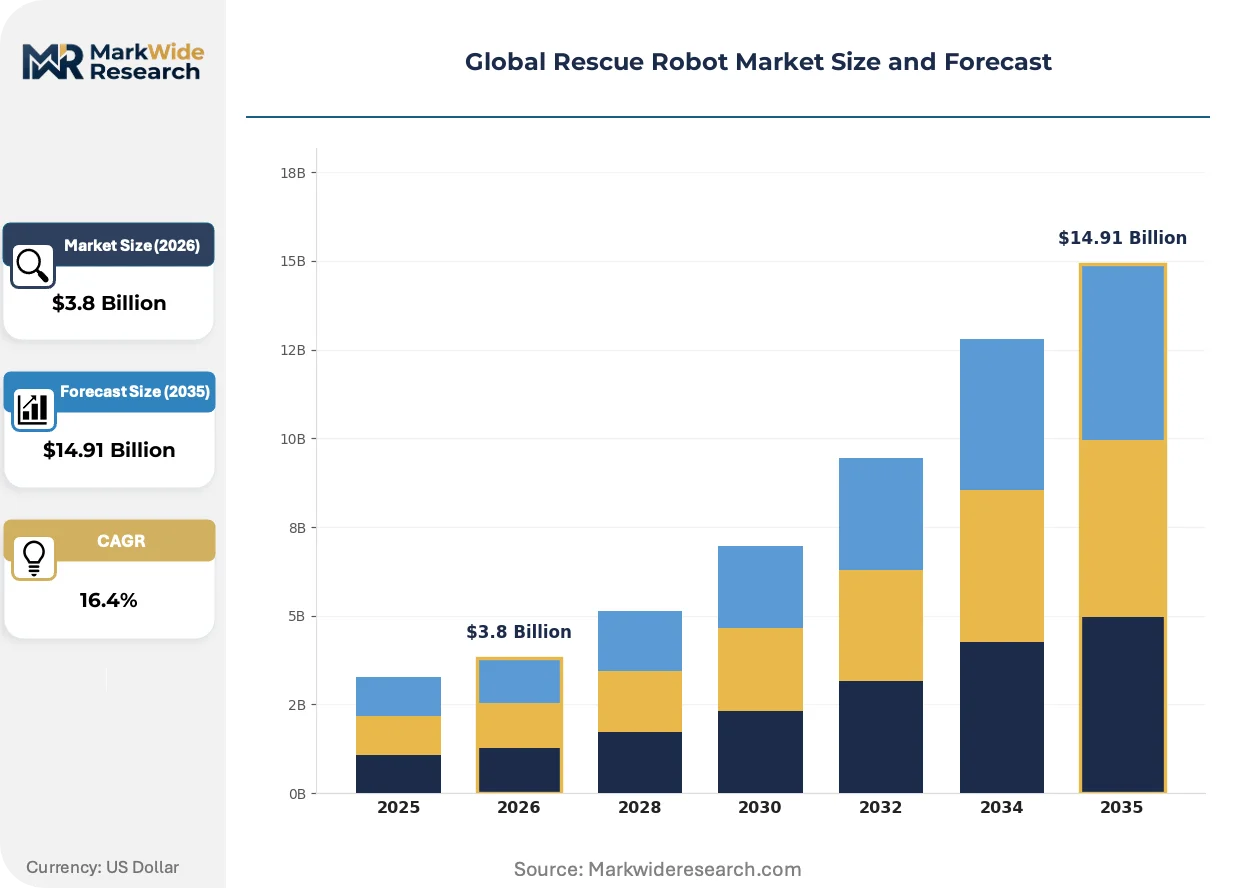
Market Dynamics
The EU AI Act's risk-based classification framework for autonomous systems is compressing certification timelines while fragmenting compliance pathways across NATO procurement channels and Asian disaster-response programs.
Growth Catalysts
- Defense procurement modernization:NATO member states are expanding ground robot fleets for battlefield casualty extraction, with integrated command-and-control architectures becoming mandatory in tender specifications.
- Japan's METI-funded disaster programs:Humanoid rescue platforms receive prioritized funding for earthquake and tsunami response scenarios, creating concentrated demand for legged locomotion systems.
- Multi-spectral sensor fusion:Smoke-penetrating visibility standards are driving thermal-LiDAR integration into municipal emergency units, accelerating replacement cycles for legacy optical-only systems.
Market Restraints
- Battery density limitations:Lithium-ion energy storage constraints cap aerial endurance in disaster zones, forcing reliance on ground platforms for extended missions.
- Specialized actuator supply concentration:High-torque harmonic drives for manipulator arms depend on Japanese and German precision manufacturers, creating single-source vulnerability.
- FAA beyond-visual-line-of-sight friction:Restricted drone operations for aerial rescue missions in the United States delay deployment authorization for swarming search configurations.
Strategic Opportunities
- Submerged extraction robotics:Tsunami-prone coastal municipalities in Japan and Indonesia represent underpenetrated demand for amphibious rescue platforms with pressure-rated sealing.
- EU Green Deal procurement incentives:Carbon-neutral manufacturing certifications are becoming weighted criteria in European emergency services tenders, rewarding localized production investments.
- 5G-enabled teleoperation:Ultra-reliable low-latency communication is converging with haptic feedback systems to enable remote surgical extraction procedures during structural collapse scenarios.
Industry Challenges
- Autonomous harm liability frameworks:Emerging jurisdictional fragmentation around decision-making accountability for extraction robots is delaying insurance product development and municipal adoption.
- ISO interoperability benchmark delays:Slow consolidation of navigation and communication standards between defense and civilian platforms is forcing redundant engineering investments.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Rescue Robot Market |
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $14.91 Billion |
| CAGR (2026 – 2036) | 16.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Ground Robots, Aerial Drones, Underwater Robots, Hybrid Robots End User: Emergency Services, Defense Forces, Municipalities, NGOs Technology: Autonomous Navigation, Remote Control, Artificial Intelligence, Sensor Integration Application: Disaster Relief, Search and Rescue, Surveillance, Hazardous Material Handling |
| Companies Covered | Boston Dynamics, Lockheed Martin Corporation, Teledyne FLIR, Northrop Grumman, Kongsberg Gruppen, QinetiQ Group, iRobot Corporation, Hydronalix, Shark Robotics, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Rescue Robot Market Strategic Shifts
Autonomous decision architectures and hardened communication layers are compressing the gap between laboratory prototypes and field-deployable systems, with regulatory pressure accelerating rather than slowing commercialization timelines.
Transformer-based neural networks for real-time path planning through unstable debris fields is rewriting competitive requirements for terrain-adaptive locomotion. Defense procurement agencies in the United States and United Kingdom are mandating onboard AI inference within eighteen-month acquisition cycles. This capability compression is eliminating vendors dependent on cloud-tethered processing for navigation decisions.
The EU AI Act's conformity assessment procedures for high-risk autonomous systems are reshaping European supplier certification investments. Third-party notified bodies must validate emergency decision algorithms before platform deployment in member state fire services. German and French robotics firms are responding by pre-certifying modular software stacks that port across ground and aerial form factors.
Service-unbundling is disrupting traditional integrated vendor relationships in municipal emergency procurement. Japanese prefectures are separating hardware acquisition from software maintenance and operator training contracts, enabling specialized firms to compete against full-stack incumbents. This purchasing pattern fragmentation is most visible in Tokyo and Osaka metropolitan disaster response departments.
Global Rescue Robot Market Segmentation
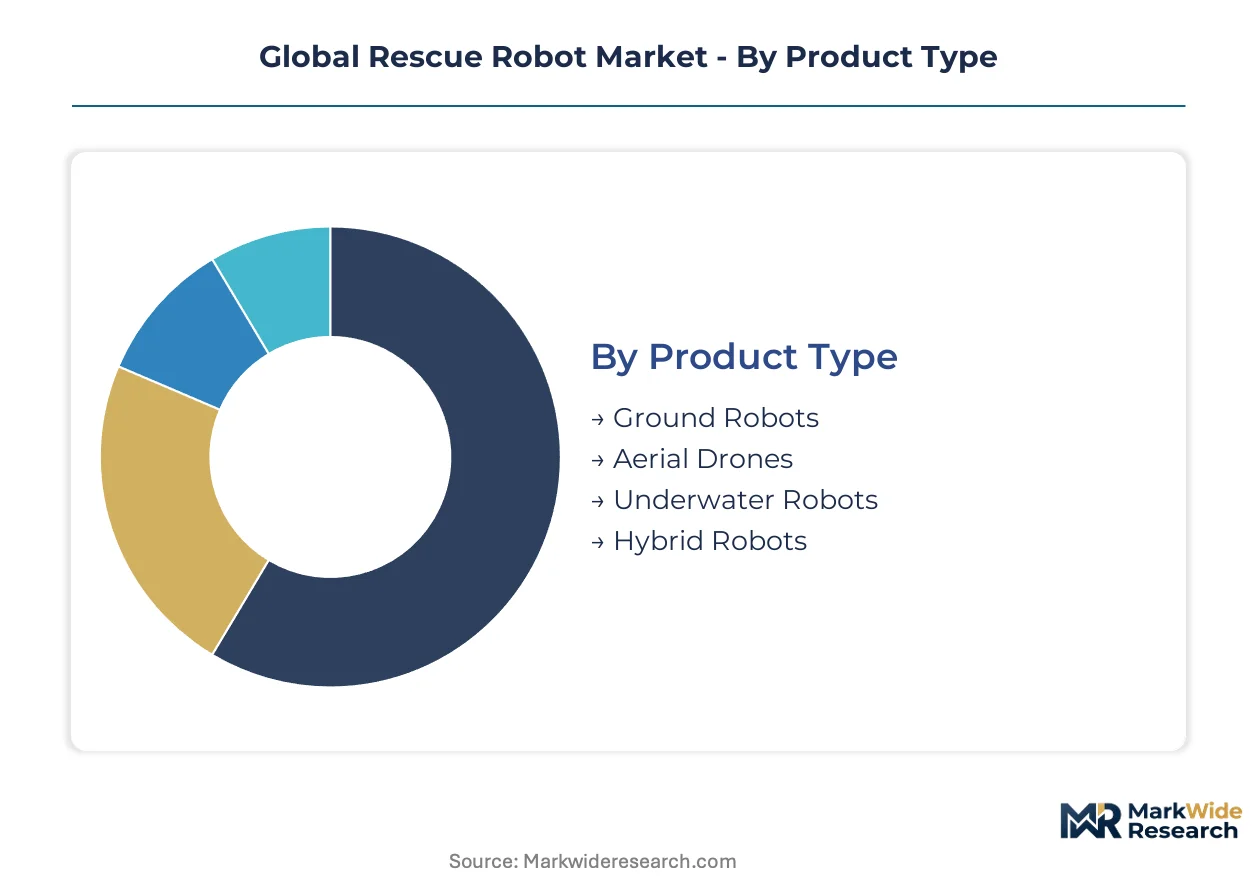
Segmentation in rescue robotics reveals how certification burdens, battery physics, and procurement authority distribute across product architectures and buyer types. Each dimension exposes distinct margin pressures and regulatory gatekeepers that shape vendor strategy.
Product Type:
Ground robots carry lighter certification loads under FAA frameworks, while aerial platforms face stricter beyond-visual-line-of-sight approvals and underwater systems navigate maritime classification societies.
- Ground Robots:Wheeled and legged platforms dominate municipal procurement in Japan and Germany, where METI and KBA respectively validate structural integrity for debris traversal. Battery density constraints actually favor these systems for missions exceeding four hours.
- Aerial Drones:Rotary-wing and fixed-wing configurations require FAA Part 107 waivers or EASA equivalent certificates for autonomous swarm deployment. Thermal-LiDAR fusion payloads are concentrating demand in US wildfire response and Australian bushfire zones.
- Underwater Robots:Remotely operated vehicles with pressure-rated hulls serve tsunami-prone Japanese prefectures and Indonesian coastal municipalities.
- Hybrid Robots:Amphibious platforms combining surface and submerged locomotion address flood scenarios in Bangladesh and Vietnam river delta regions.
Leading the category by volume: Ground Robots. Growing fastest: Hybrid Robots.
End User:
Defense procurement operates on classified acquisition channels with integrated command-and-control mandates, while municipal buyers fragment across separated hardware, software, and training contracts.
- Emergency Services:Fire departments and urban search-and-rescue teams in Tokyo, London, and Los Angeles drive compact throwable robot demand. Portability specifications under 15 kilograms dominate tender requirements.
- Defense Forces:NATO member state battlefield casualty extraction programs mandate hardened communication layers and onboard AI inference without cloud dependency. These specifications are eliminating vendors lacking eighteen-month capability compression cycles.
- Municipalities:City-level disaster response departments in Osaka and Tokyo metropolitan areas are unbundling service contracts, enabling specialized software firms to compete against integrated vendors.
- NGOs:Humanitarian organizations operating in earthquake zones prioritize low-cost teleoperated units with minimal training requirements.
Defense Forces command premium pricing tiers. Emergency Services show steepest expansion trajectory in unit volume.
Technology:
Autonomy levels determine regulatory pathway complexity, with the EU AI Act imposing conformity assessments on decision-making algorithms that remote-controlled systems bypass entirely.
- Autonomous Navigation:Simultaneous localization and mapping with obstacle avoidance requires third-party notified body validation under EU AI Act high-risk system classifications. German robotics firms are pre-certifying modular software stacks that port across form factors.
- Remote Control:Tethered and radio-frequency teleoperation remains the default for hazardous material handling where human-in-the-loop accountability satisfies liability frameworks. 5G-enabled haptic feedback is converging with surgical extraction applications in Japanese structural collapse scenarios.
- Artificial Intelligence:Transformer-based neural networks for real-time path planning through unstable debris are becoming mandatory in US and UK defense procurement cycles.
- Sensor Integration:Multi-spectral fusion combining thermal, LiDAR, and gas detection is displacing legacy optical-only systems in smoke-penetrating visibility applications.
Remote Control retains installed base dominance. Sensor Integration is climbing the fastest as replacement cycles accelerate.
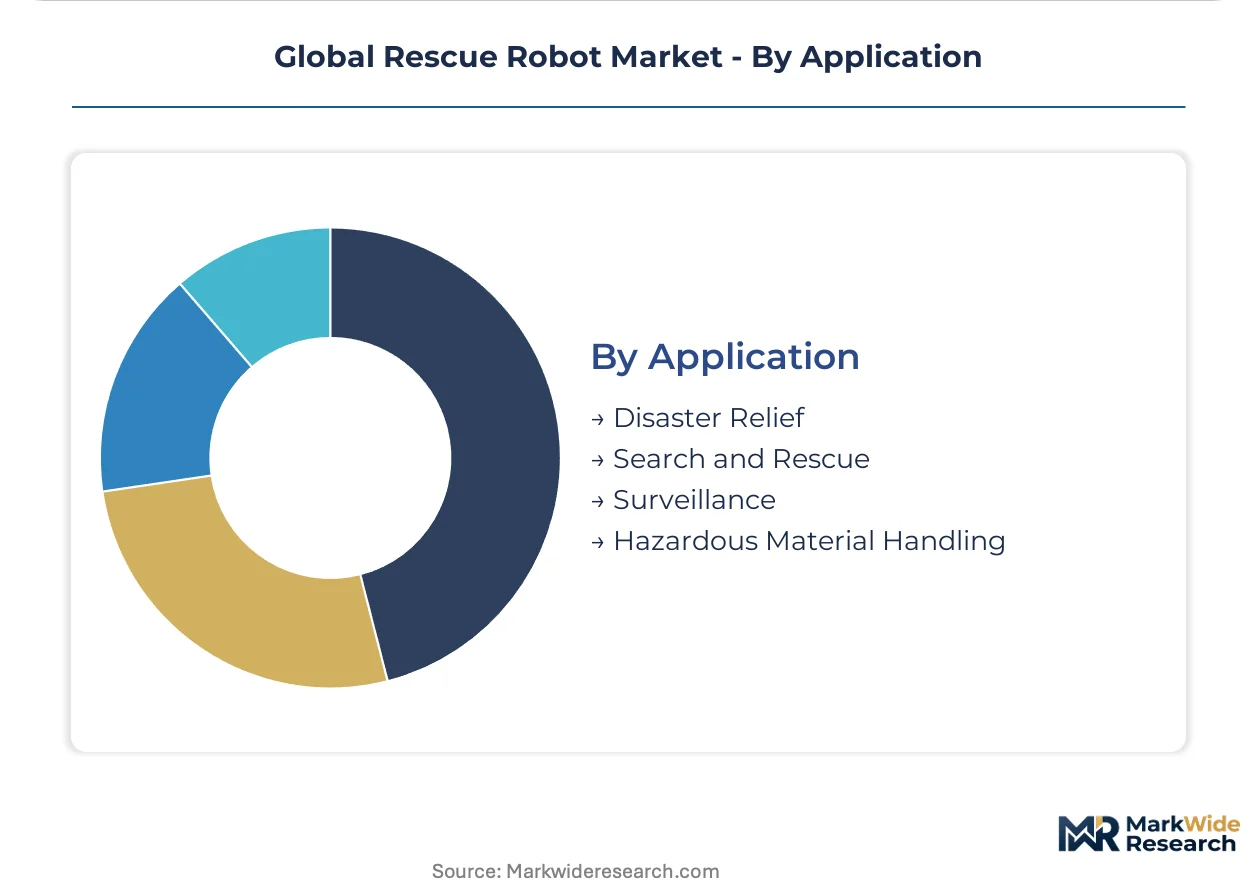
Application:
Mission type dictates payload requirements and environmental sealing standards, with disaster relief demanding amphibious capability and hazardous material handling requiring chemical-resistant actuator housings.
- Disaster Relief:Earthquake, tsunami, and flood response in Japan, Indonesia, and Turkey drives demand for humanoid and legged platforms capable of debris traversal and victim extraction.
- Search and Rescue:Confined space penetration in collapsed structures concentrates demand on compact tracked robots with manipulator arms rated for 50+ kilogram lifting.
- Surveillance:Perimeter monitoring and situational awareness missions favor aerial drones with extended loiter times, constrained by battery chemistry limitations.
- Hazardous Material Handling:Chemical, biological, and radiological containment operations require sealed actuator systems and decontamination protocols validated by EPA and equivalent regulators.
Search and Rescue anchors current revenue. Disaster Relief is gaining share fastest on METI funding concentration.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Tokyo anchors the global rescue robot demand concentration, with METI-funded disaster response programs driving humanoid platform procurement for earthquake and tsunami scenarios across Japanese prefectures.
United States
Defense procurement agencies at the Pentagon and DARPA expand ground robot fleets for battlefield casualty extraction, with FAA Part 107 waivers governing beyond-visual-line-of-sight drone operations for aerial rescue missions. Boston and Pittsburgh technology corridors concentrate legged locomotion development for terrain-adaptive systems.
Germany
KBA validates structural integrity standards for debris-traversal ground robots, while the EU AI Act's conformity assessment procedures reshape supplier certification investments for high-risk autonomous systems. Stuttgart and Munich industrial clusters host precision actuator manufacturers supplying harmonic drives for manipulator arms.
Japan
METI prioritizes funding for humanoid rescue platforms in earthquake-prone prefectures, with PMDA collaborating on medical-extraction robot standards blending device safety with rescue functionality. Osaka and Tokyo metropolitan disaster response departments unbundle service contracts, enabling specialized software firms to compete.
United Kingdom
Defense procurement mandates onboard AI inference without cloud dependency within eighteen-month acquisition cycles, eliminating vendors dependent on tethered processing. London and Bristol technology hubs concentrate transformer-based neural network development for real-time path planning through unstable debris.
Indonesia
Tsunami-prone coastal municipalities generate underpenetrated demand for amphibious rescue platforms with pressure-rated sealing, with Jakarta and Surabaya emergency services piloting hybrid robot deployments for flood response in river delta regions.
Global Rescue Robot Market Competitive Environment
Premium-margin players sit above commodity-margin players across certification complexity and defense contract tenure. The vendor base stratifies between full-stack integrated suppliers and modular component specialists. Three archetypes dominate: defense primes anchoring long-cycle government contracts, legged locomotion heritage firms commanding terrain-adaptive positioning, and compact throwable robot specialists capturing municipal portability requirements. Strategic moves concentrate on pre-certifying modular software stacks for EU AI Act compliance and separating hardware acquisition from maintenance contracts to capture unbundled procurement.
Within the defense prime tier, Lockheed Martin Corporation and Northrop Grumman occupy positions anchored by integrated command-and-control architectures. Boston Dynamics exemplifies the legged locomotion heritage archetype, while iRobot Corporation represents the compact throwable robot specialist segment targeting municipal emergency services procurement.
| Leading Market Players |
|---|
| Boston Dynamics |
| Lockheed Martin Corporation |
| Teledyne FLIR |
| Northrop Grumman |
| Kongsberg Gruppen |
| QinetiQ Group |
| iRobot Corporation |
| Hydronalix |
| Shark Robotics |
| Others |
Value Chain & Pricing Dynamics
Precision robotics engineers concentrated in Stuttgart and Munich anchor European actuator manufacturing, with labor-cost differentials between German technical specialists and Asian assembly operations driving three-tier pricing spreads across defense, municipal, and NGO procurement tiers.
Pricing Analysis
Outcome-based pricing tied to mission-success rates and casualty-extraction throughput anchors premium tiers for NATO battlefield contracts. Pricing stratifies across military-grade certified systems, municipal emergency units with METI validation, and economy-tier teleoperated platforms for humanitarian deployment. Cost compression in compact throwable segments intensifies as iRobot and Shark Robotics compete for sub-15-kilogram portability specifications. Municipal fire departments in Tokyo and Los Angeles exhibit highest price sensitivity; defense procurement agencies show lowest sensitivity due to integrated command-and-control mandates.
Supply Chain Analysis
Dual-sourcing requirements for high-torque harmonic drives mandate Japanese and German supplier qualification, fragmenting procurement leverage across Harmonic Drive Systems and Wittenstein. Actuator housings, lithium-ion battery packs, and multi-spectral sensor arrays draw from South Korean, Chinese, and US component streams. Single-source vulnerability in precision gearing creates structural risk for vendors lacking backward integration into motion-control subsystems. Distribution runs through defense prime integrators for military channels and unbundled software specialists for municipal buyers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Specialized actuator manufacturing capacity constrains platform output, with harmonic drive lead times propping pricing power for vendors with captive precision-motion supply.
For Market Incumbents: To counter modular software specialists unbundling municipal contracts, anchor integrated service relationships through embedded operator training programs and pre-certified EU AI Act software stacks. Deepen upstream control over harmonic drive supply through equity partnerships with Stuttgart precision manufacturers. For New Entrants and Emerging Players: Direct-to-municipality SaaS platforms for 5G-enabled teleoperation offer the most penetrable route. Target Indonesian coastal municipalities for amphibious platform trials, leveraging Jakarta flood-response pilot programs as reference deployments. Lead with outcome-based pricing tied to victim-extraction success rates. For Investors and Strategic Acquirers: Re-rating potential sits with legged locomotion heritage firms given METI humanoid platform funding concentration. Five-to-ten-year viability favors vendors with defense contract tenure exceeding three procurement cycles. Monitor EU AI Act notified body capacity as inflection indicator for certification bottleneck severity.| Strategic Initiative | Industry Significance |
|---|---|
| EU AI Act Pre-Certification | Modular software stack validation accelerates deployment across German and French fire services procurement. |
| Harmonic Drive Supply Partnership | Captive precision gearing access eliminates single-source vulnerability for high-torque manipulator arms. |
| 5G Teleoperation Platform Launch | Ultra-reliable low-latency communication enables remote surgical extraction in Japanese structural collapse scenarios. |
| Amphibious Platform Development | Pressure-rated sealing capability addresses underpenetrated demand from tsunami-prone Indonesian coastal municipalities. |
| Service Contract Unbundling | Separated software maintenance and operator training contracts capture purchasing pattern fragmentation in Tokyo and Osaka. |
Study Parameters
Trade association data, regulatory filings, and customs records anchored secondary inputs, combined with primary interviews across defense procurement officers, municipal fire chiefs, biomedical engineers, robotics platform developers, and precision actuator manufacturers. EASA certification databases, METI program disclosures, FAA Part 107 waiver filings, and NATO tender specifications supplied validation benchmarks. Bottom-up unit deployment tracking and top-down defense budget allocation analysis triangulated market sizing.
Data-stream reconciliation across product type, end user, technology, and application segments modeled volume and value outputs over the projection horizon. Autonomy level, certification tier, and payload capacity variations shaped segment-level CAGRs. Defense procurement cycle timing, battery chemistry advancement curves, and EU AI Act implementation phasing served as industry-specific forecast inputs.
The model holds under stable regulatory enforcement timelines and continued METI funding authorization; deviation in EU AI Act notified body capacity or lithium-ion supply chain disruption would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Robotics and Automation
Robotic Process Automation in BFSI Market
Robotics and Automation
South Korea Cloud Robotics Market
Robotics and Automation
United States Articulated Robot Market
Robotics and Automation
Snake Robots Market
Robotics and Automation
Hospitality Robots Market
Robotics and Automation
Service Robotics Market
Robotics and Automation
Automated Facade Contact Cleaning Robot Market
Robotics and Automation
Europe AUV Market
Robotics and Automation
Latin America Autonomous Mobile Robot Market
Robotics and Automation
Humanoid Robot Market
Robotics and Automation
Automated Guided Vehicle (AGV) Market
Robotics and Automation
Middle East and Africa Medical Robots Market
Robotics and Automation
Global Delivery Robots Market
Robotics and Automation
China Cloud Robotics Market
Robotics and Automation
Hotel Robot Market
Robotics and Automation
Gimbal Stabilizers Market