
 Commercial Robotics Market | 2026-2036
Commercial Robotics Market Size, Share, and Industry Trends Forecast 2026-2036
Commercial Robotics Market Analysis
China is fragmenting commercial robotics manufacturing capacity across Shenzhen, Shanghai, and Beijing industrial zones. Kuka AG anchors European automotive assembly line deployments with heavy-payload articulated systems. Yaskawa Electric Corporation specializes in motion control architectures for precision manufacturing. Boston Dynamics differentiates through legged locomotion platforms serving inspection and logistics end users.
Commercial robotics encompasses programmable electromechanical systems designed to execute commercial tasks with minimum human intervention, typically incorporating servo motors, programmable logic controllers, and payload capacities ranging from kilograms to multiple tons. These systems automate material handling, assembly, inspection, and service operations across industrial and commercial facilities. Industrial robots command the largest installed base, though collaborative robots are capturing margin pools in small-batch manufacturing where fenceless human-robot interaction reduces floor space requirements. Service robots in healthcare and retail are expanding fastest, driven by computer vision and natural language processing integrations.
FDA device regulations govern surgical and diagnostic robotics in the United States, while the EU Machinery Directive and CE marking framework mandate functional safety assessments for European deployments. OSHA workplace standards intersect with ANSI/RIA robot safety specifications to shape installation protocols and liability frameworks. Stakeholders must monitor evolving AI liability legislation and harmonization gaps between regional certification regimes.
Market Dynamics
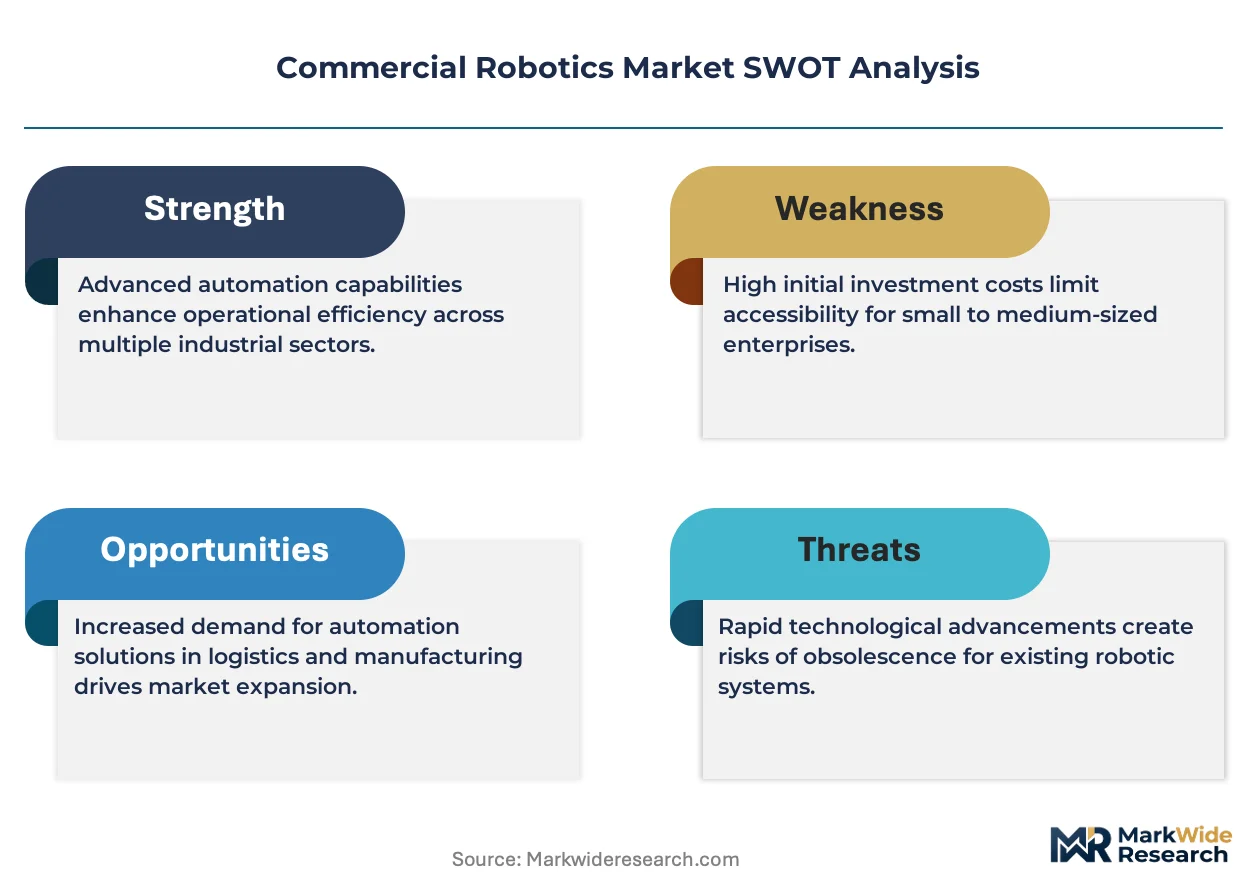
The EU AI Act's risk-based classification system is forcing robotics OEMs to redesign control architectures and documentation workflows before CE marking eligibility. This regulatory compression is accelerating consolidation among smaller integrators lacking compliance infrastructure.
Growth Catalysts
- EU Machinery Directive harmonization:The 2023 update mandates functional safety validation for collaborative robot installations, creating certified upgrade cycles across German and Italian automotive plants.
- Computer vision convergence:3D depth sensing and edge AI processors enable fenceless human-robot collaboration in electronics assembly, reducing floor space requirements by eliminating protective enclosures.
- Shenzhen manufacturing cluster:Vertical integration of servo motor, reducer, and controller production concentrates component sourcing for Asia-Pacific system integrators.
Market Restraints
- Rare earth magnet dependency:Neodymium supply from Chinese processing facilities exposes motor manufacturers to export quota volatility and price spikes.
- CE marking timeline friction:EU Notified Body backlogs extend safety certification cycles to 14-18 months, delaying product launches for mid-tier OEMs.
- Legacy PLC protocol fragmentation:Proprietary fieldbus standards from Rockwell, Siemens, and Mitsubishi create integration lock-in that slows multi-vendor fleet deployments.
Strategic Opportunities
- India PLI scheme for robotics:Production-linked incentives targeting 25% value addition attract component manufacturing to Pune and Chennai industrial corridors.
- Autonomous mobile robot leasing:Warehouse operators in the Netherlands and Belgium shift from capital purchase to per-pick pricing models, reducing barrier-to-entry for 3PLs.
- 5G private network integration:Ultra-reliable low-latency communication enables real-time fleet coordination in Japanese automotive plants, replacing wired infrastructure.
Industry Challenges
- Systems integration talent scarcity:Shortage of ROS-Industrial programmers and safety-certified engineers constrains deployment velocity for mid-size manufacturers.
- Retrofit capex burden:Legacy conveyor systems in US food processing facilities require structural reinforcement to support AMR navigation, inflating project budgets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Commercial Robotics Market |
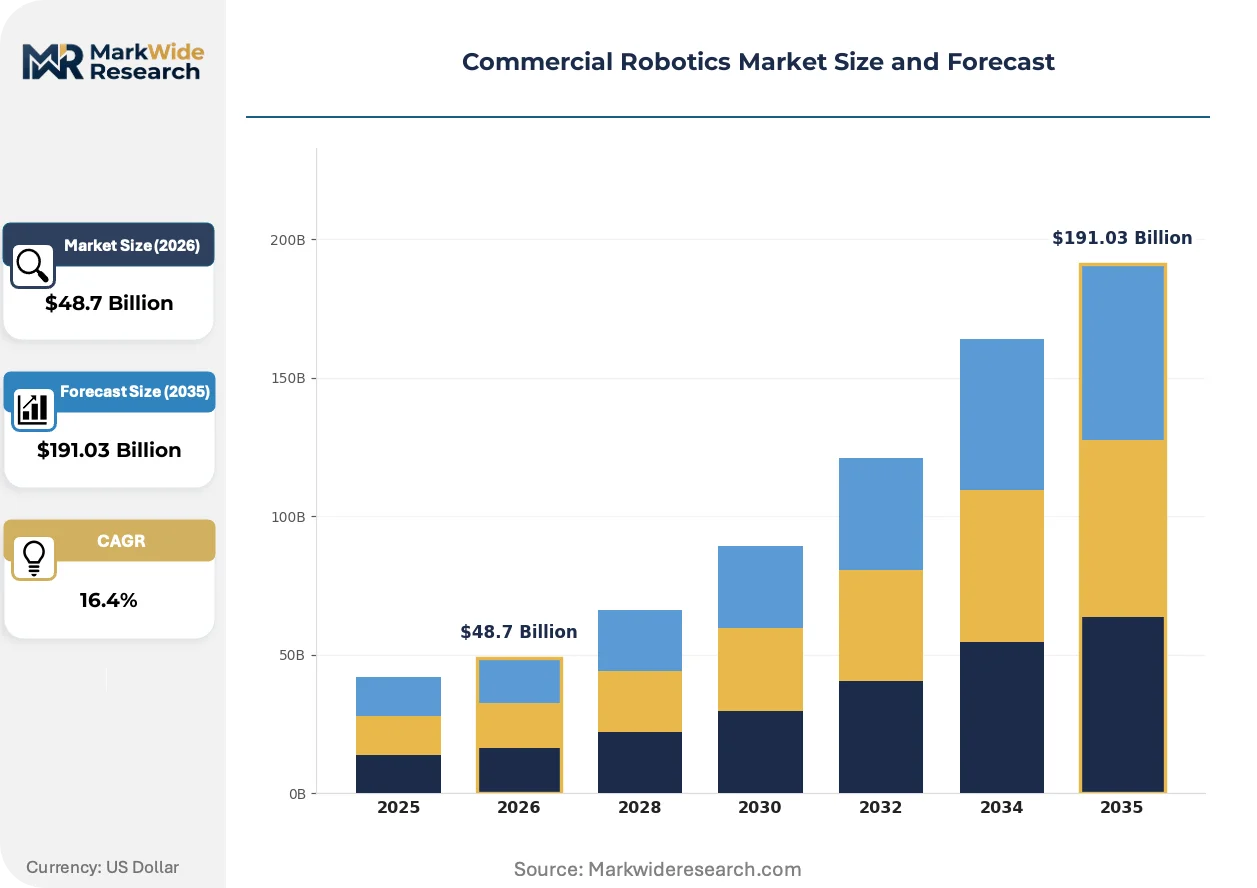
| Market Size in 2026 | $48.7 Billion |
| Market Size in 2035 | $191.03 Billion |
| CAGR (2026 – 2036) | 16.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Industrial Robots, Agricultural Robots, Service Robots, Collaborative Robots Technology: AI, Machine Learning, Sensors, IoT End User: Manufacturing, Healthcare, Retail, Construction Deployment: On-Premise, Cloud-Based, Hybrid, Mobile |
| Companies Covered | Google LLC (Alphabet, Inc.), Omron Corporation, Boston Dynamics (Hyundai Motor Company), Northrop Grumman Corporation, iRobot Corporation (Amazon.com, Inc.), Kuka AG (Midea Investment Holding Co., Ltd.), Yaskawa Electric Corporation, Honda Motor Co. Ltd., Accuray Incorporated, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Commercial Robotics Market Emerging Trajectories
Edge AI inference and digital twin simulation are compressing robot commissioning timelines while enabling predictive maintenance contracts. These capabilities are redefining competitive differentiation away from hardware specifications toward software-defined performance guarantees.
LiDAR-based navigation is migrating from high-bay warehousing to dynamic retail environments. Grocery chains in France and South Korea deploy these systems for overnight shelf scanning and inventory reconciliation. The shift from fixed infrastructure to infrastructure-free deployment is compressing installation costs and enabling rapid site reconfiguration.
The EU AI Act's high-risk system classification imposes conformity assessment requirements on surgical and logistics robots with autonomous decision-making capabilities. German medical device manufacturers are restructuring quality management systems to accommodate notified body audits of training data governance. This regulatory segmentation is creating a two-tier market between certified autonomous systems and remotely supervised alternatives.
Third-party robot-as-a-service platforms are displacing direct OEM sales relationships in North American warehousing. Operators in Ohio and Texas procurement departments now evaluate fleet management software and uptime guarantees ahead of hardware specifications. This purchasing pattern shift is visible most acutely in e-commerce fulfillment centers facing seasonal volume spikes.
Commercial Robotics Market Segmentation
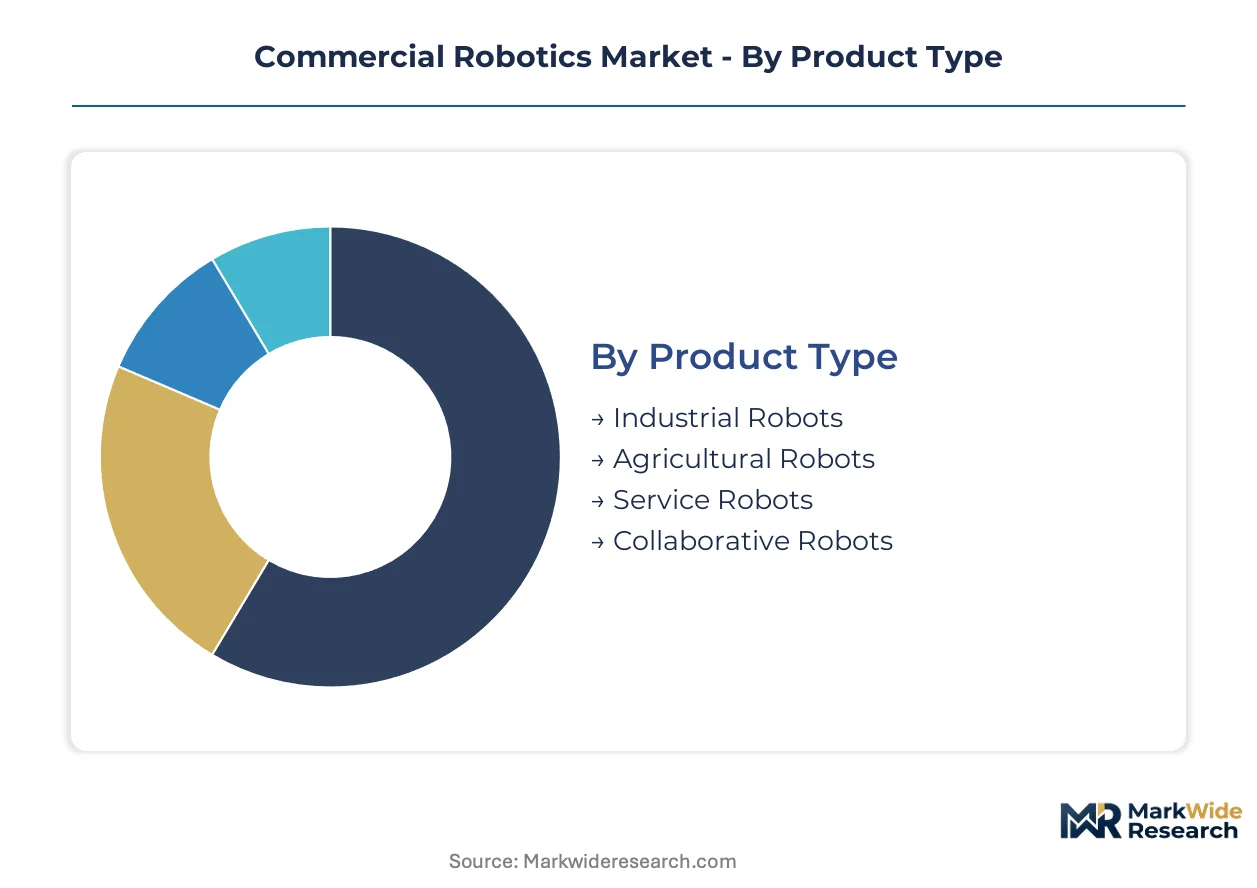
Commercial robotics procurement cycles vary dramatically by segment, with warehouse AMRs refreshing every 3-4 years while heavy industrial installations persist for 15-20 years. Understanding these replacement rhythms shapes inventory planning, service contract structures, and R&D prioritization for component suppliers.
Product Type:
Replacement cycles compress from decades to quarters across this spectrum, creating fundamentally different margin profiles and customer relationship models for each segment type.
- Industrial Robots:Heavy-payload articulated systems with six or more degrees of freedom dominate automotive welding and press tending. German and Japanese automotive plants sustain demand through EU Machinery Directive compliance upgrades and workforce shortage mitigation.
- Collaborative Robots:Force-limited articulated arms enable fenceless human-robot interaction in electronics assembly and small-batch manufacturing. Demand concentrates in Shenzhen and Shanghai facilities where 3C manufacturers deploy cobots for precision screwdriving and quality inspection.
- Service Robots:Autonomous systems for hospitality, cleaning, and security applications leverage SLAM navigation and voice interaction. South Korean retail chains and French healthcare facilities drive procurement for inventory scanning and patient logistics.
- Agricultural Robots:GPS-guided tractors, harvesting platforms, and crop monitoring drones automate field operations. California Central Valley and Dutch greenhouse clusters adopt precision spraying and autonomous picking for labor-intensive specialty crops.
Industrial robots anchor the volume base while collaborative robots gain share at the steepest rate.
Technology:
Cost tiers stratify sharply here, with sensor hardware commanding premium pricing against commoditized computing substrates.
- AI:Deep learning inference engines power visual inspection, grasp planning, and predictive maintenance. Edge deployment in Japanese automotive plants and Texas semiconductor fabs demands real-time processing with minimal cloud dependency.
- Sensors:LiDAR, 3D vision systems, and force-torque transducers constitute the highest-margin component layer. Velodyne and SICK dominate high-bay warehousing and outdoor logistics applications where environmental robustness justifies cost premiums.
- Machine Learning:Training pipelines and model optimization tools enable fleet learning across distributed robot deployments. Cloud-based training in Netherlands logistics hubs and Singapore ports accelerates navigation algorithm refinement.
- IoT:Connectivity protocols and device management platforms link distributed robot fleets to centralized monitoring systems. 5G private networks in German automotive plants replace wired fieldbus infrastructure for mobile robot coordination.
Sensors command the highest margin tier while AI expands most quickly across new installation categories.
End User:
Application intensity varies by sector, with manufacturing exhibiting the deepest robot density per worker versus emerging penetration in service environments.
- Manufacturing:Assembly, welding, painting, and material handling applications sustain the largest installed base. Chinese EV battery plants and German powertrain facilities drive articulated robot demand for high-throughput precision operations.
- Healthcare:Surgical systems, rehabilitation devices, and hospital logistics robots face FDA and EU MDR regulatory pathways. Da Vinci installations in US academic medical centers and diagnostic imaging robots in Japanese hospitals concentrate procurement.
- Retail:Inventory scanning, shelf replenishment, and customer service robots penetrate grocery and big-box formats. French hypermarkets and South Korean convenience chains deploy overnight shelf-scanning systems for inventory reconciliation.
- Construction:Bricklaying, welding, and site inspection robots address skilled labor scarcity in developed markets. Australian mining operations and UAE infrastructure projects pilot autonomous earthmoving and rebar-tying systems.
Manufacturing anchors the volume base while healthcare climbs the fastest on regulatory approval momentum.
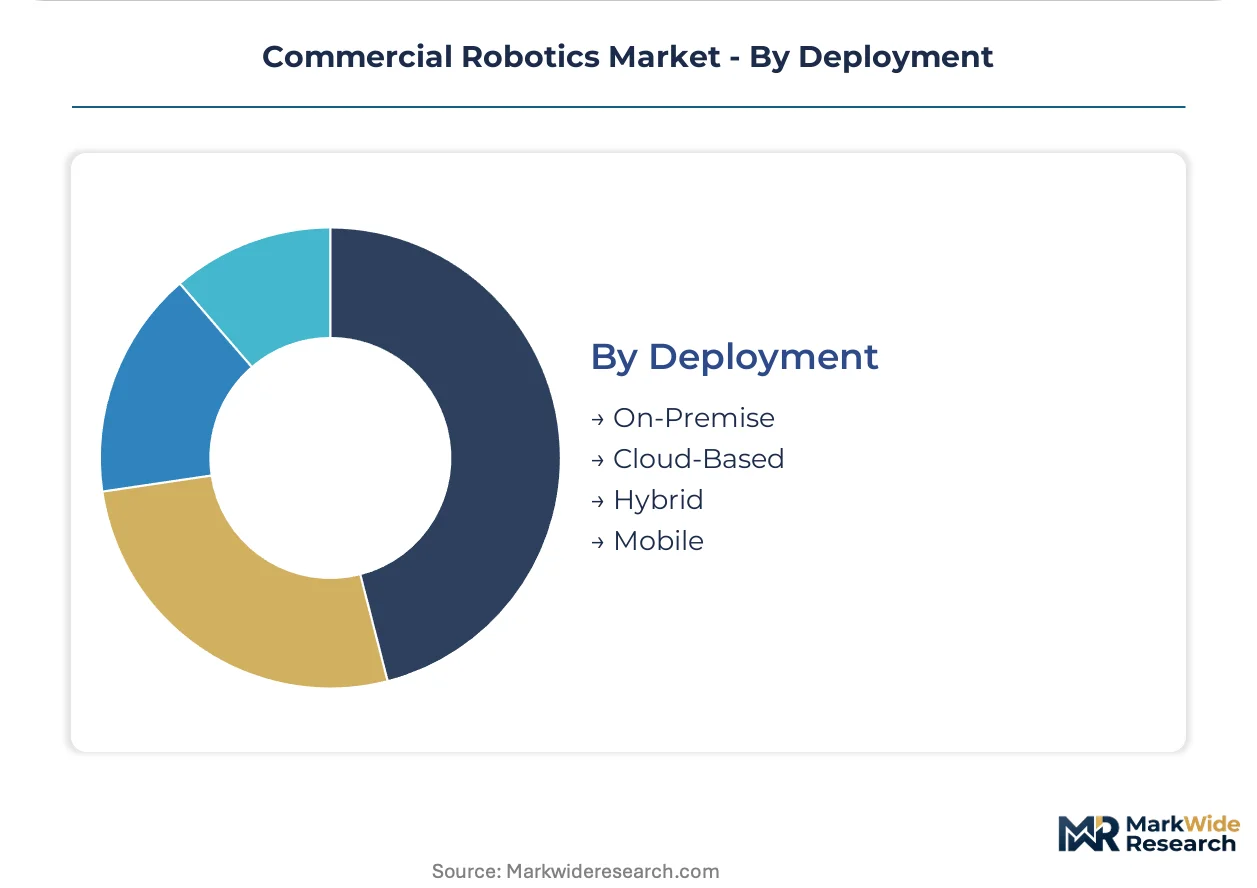
Deployment:
Customer type bifurcates sharply between asset-heavy manufacturers preferring on-premise control and asset-light 3PLs embracing cloud-orchestrated fleets.
- On-Premise:Localized control systems with dedicated computing infrastructure serve security-sensitive and latency-critical applications. Defense contractors and pharmaceutical manufacturers mandate air-gapped robot controllers for IP protection.
- Cloud-Based:Centralized fleet management, over-the-air updates, and predictive analytics platforms enable multi-site coordination. Netherlands and Belgium warehouse operators adopt per-pick pricing models with uptime guarantees from RaaS providers.
- Hybrid:Edge processing for real-time control combined with cloud analytics for optimization and maintenance scheduling. Japanese automotive plants balance deterministic cycle times with cloud-based production analytics.
- Mobile:Untethered autonomous platforms with onboard power and computing for dynamic environment navigation. Ohio and Texas e-commerce fulfillment centers deploy AMR fleets for seasonal volume elasticity.
On-premise deployment anchors the volume base while cloud-based models gain share at the steepest rate among 3PL operators.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China deploys commercial robotics for high-throughput manufacturing automation, while Germany prioritizes precision assembly and the United States emphasizes warehouse logistics and defense applications. This consumption-mix differential shapes distinct regulatory pathways and supplier ecosystems across major markets.
China
Electric vehicle battery plants and 3C electronics manufacturers drive articulated robot demand for precision welding and component placement. MIIT smart manufacturing mandates accelerate factory digitization timelines. Shenzhen, Shanghai, and Beijing industrial zones fragment manufacturing capacity across servo motor, reducer, and controller production.
Germany
Automotive powertrain facilities and machinery OEMs sustain heavy-payload robot installations for press tending and assembly operations. The EU Machinery Directive and EU AI Act impose functional safety validation and conformity assessment requirements. Stuttgart and Munich industrial corridors concentrate system integrator expertise and notified body relationships.
United States
E-commerce fulfillment centers and defense contractors procure autonomous mobile robots and legged platforms for logistics and inspection missions. FDA device regulations govern surgical robotics while OSHA standards intersect with ANSI/RIA specifications for workplace safety. Ohio and Texas warehouse clusters adopt robot-as-a-service models for seasonal volume elasticity.
Japan
Automotive plants and semiconductor fabs deploy collaborative robots and precision motion control systems for deterministic cycle-time operations. METI industrial policy supports smart factory investments and 5G private network infrastructure. Nagoya and Osaka manufacturing belts anchor Yaskawa Electric and precision component supplier ecosystems.
South Korea
Electronics assembly and retail chains drive demand for collaborative arms and inventory-scanning service robots. MFDS medical device regulations and KOSHA workplace standards shape certification requirements. Seoul Capital Area and Busan-Ulsan industrial zones concentrate display panel and shipbuilding automation deployments.
Commercial Robotics Market Vendor Landscape
Capability concentration sits with precision motion control specialists; scale advantage sits with diversified industrial conglomerates. The vendor base separates into three tiers: integrated automation platforms, component-focused specialists, and application-specific system integrators. German and Japanese incumbents anchor the premium tier through decades of automotive relationships. Chinese manufacturers capture mid-market share via vertical integration into servo motors and reducers. Consolidation pressure intensifies as EU AI Act compliance costs favor players with established notified body relationships and quality management infrastructure.
Within the precision motion tier, Yaskawa Electric Corporation and Kuka AG exemplify divergent strategic positions—Yaskawa as a standalone specialist, Kuka as a Chinese-owned platform with European automotive heritage. Boston Dynamics occupies a distinct niche representing legged locomotion capabilities for inspection and logistics end users. Among diversified technology conglomerates, Google LLC anchors AI and perception software development through cloud and edge computing infrastructure rather than hardware manufacturing.
| Leading Market Players |
|---|
| Google LLC (Alphabet, Inc.) |
| Omron Corporation |
| Boston Dynamics (Hyundai Motor Company) |
| Northrop Grumman Corporation |
| iRobot Corporation (Amazon.com, Inc.) |
| Kuka AG (Midea Investment Holding Co., Ltd.) |
| Yaskawa Electric Corporation |
| Honda Motor Co. Ltd. |
| Accuray Incorporated |
| Others |
Supply Flow & Price Mechanics
Shenzhen's servo motor and reducer manufacturing clusters concentrate component capacity for Asia-Pacific system integrators, translating upstream scale into pricing leverage over mid-tier European OEMs facing CE marking delays. This geographic asymmetry creates tiered margin structures where vertically integrated Chinese suppliers undercut Western competitors on hardware while premium software-defined performance guarantees sustain price premiums for German and Japanese incumbents.
Pricing Analysis
Long-term offtake contracts dominate industrial robot procurement from German automotive OEMs, while spot-market spot-buying prevails for warehouse AMR fleets facing seasonal volume spikes. Three-tier pricing structure across premium, standard, and economy levels separates CE-marked collaborative systems from uncertified alternatives and refurbished legacy units. Cost compression in the mid-tier is intensifying because Chinese manufacturers are bundling controllers with servo packages at below-component cost. Third-party logistics operators exhibit the highest price sensitivity, prioritizing per-pick RaaS models over capital purchases, whereas defense contractors accept 40-60% premiums for air-gapped on-premise systems.
Supply Chain Analysis
Foxconn and Luxshare Precision anchor contract manufacturing capacity for robot controllers and edge AI processors, with additional concentration at Pegatron for sensor module assembly. Component sourcing draws from Japan for precision reducers, Germany for safety-certified PLCs, and China for rare-earth magnet processing. Single-source vulnerability in neodymium supply from Chinese processing facilities exposes motor manufacturers to export quota volatility. Distribution runs through authorized system integrator networks in Stuttgart and Nagoya for complex installations, while direct OEM sales persist for standardized AMR fleets in North American warehousing.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The commercial robotics sector is entering a cyclical recovery phase driven by EU Machinery Directive compliance upgrade cycles forcing replacement demand across German and Italian automotive plants. Capital deployment should prioritize software-defined differentiation and regulatory certification infrastructure over pure hardware scale.
For Market Incumbents: Build switching-cost moats through proprietary fleet management platforms that embed predictive maintenance contracts and over-the-air update capabilities. Deepen backward integration into safety-certified controller firmware to reduce dependency on Rockwell and Siemens protocol licensing. Acquire ROS-Industrial programming talent pools in Stuttgart and Munich to constrain deployment velocity for mid-tier competitors lacking systems integration bench strength. For New Entrants and Emerging Players: Mid-market food processing facilities in the US Southeast represent the most penetrable entry point, where OSHA-aligned retrofit requirements have frozen incumbent sales cycles and created procurement backlogs. Target India's Pune and Chennai industrial corridors under PLI scheme coverage, where 25% value addition incentives reduce effective manufacturing cost bases for component suppliers. Lead with AMR-as-a-service pricing models that shift capital risk to balance sheets of 3PL operators facing e-commerce volume volatility. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors edge AI inference specialists with automotive-grade safety certification and established notified body relationships in Germany. Long-term viability over the next decade hinges on software recurring revenue attachment rates rather than hardware shipment volumes. Monitor EU AI Act high-risk system classification expansion as the critical inflection signal; surgical and logistics autonomy thresholds will determine addressable market boundaries for autonomous decision-making capabilities.| Strategic Initiative | Industry Significance |
|---|---|
| CE Marking Pathway Investment | EU Notified Body pre-submission for AI Act high-risk classification compresses 14-18 month timelines for German medical device manufacturers. |
| 5G Private Network Integration | Ultra-reliable low-latency infrastructure in Japanese automotive plants replaces wired fieldbus for real-time AMR fleet coordination. |
| Backward Integration into Servo Motors | In-house production of precision motion components insulates margin structures from Chinese rare-earth export quota volatility. |
| Robot-as-a-Service Platform Launch | Per-pick pricing models with uptime guarantees capture seasonal volume elasticity in Ohio and Texas e-commerce fulfillment centers. |
| ROS-Industrial Talent Acquisition | Safety-certified programmer pools in Stuttgart constrain deployment velocity for competitors lacking systems integration infrastructure. |
Methodological Framework
Demand-side practitioners and supply-side operators were both consulted across primary interview programs with warehouse operations directors, automotive plant engineers, robotics OEM product managers, and EU Notified Body auditors. Secondary validation incorporated EU Machinery Directive implementation guidance, FDA 510(k) surgical robotics filings, METI smart factory investment disclosures, and customs data on servo motor trade flows. Bottom-up installation forecasts triangulated against top-down manufacturing automation spending projections from automotive and 3PL sectors.
Calibration against historical replacement cycles and regulatory compliance deadlines anchored volume and value outputs across the projection horizon. Segmentation dimensions modeled include robot kinematic architecture, payload capacity tier, deployment model, end-use industry intensity, and regional regulatory cluster. CAGRs were derived from elasticity-adjusted adoption curves incorporating labor shortage severity indices and capital expenditure commitment patterns from disclosed automotive and logistics customer pipelines.
Stress conditions across neodymium supply disruption scenarios, EU AI Act enforcement intensity gradients, and 3PL RaaS pricing model penetration rates were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions regarding labor cost trajectories, harmonization timelines between regional certification regimes, and edge AI processor cost curves. Quarterly review of EU Notified Body backlog durations and MIIT smart manufacturing mandate implementation pace is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Robotics and Automation
Mobile Stabilizer Market
Robotics and Automation
Smart Remote Control Market
Robotics and Automation
Europe Agricultural Robot Market
Robotics and Automation
Africa Cloud Robotics Market
Robotics and Automation
APAC Service Robots Market
Robotics and Automation
Global K-12 Robotic Toolkits Market
Robotics and Automation
Surgical Robots Market
Robotics and Automation
Europe Articulated Robot Market
Robotics and Automation
Telepresence Robot Market
Robotics and Automation
Asia-Pacific Robotics Technology Market
Robotics and Automation
Pipe Inspection Robot Market
Robotics and Automation
Robot for Public Service Market
Robotics and Automation
Europe Warehouse Robotics Market
Robotics and Automation
Robotics and Automation Actuators Market
Robotics and Automation
Global All Terrain Robots Market
Robotics and Automation
Cybersecurity in Robotics Market