
 United States Agricultural Robots Market | 2026-2036
United States Agricultural Robots Market Size, Share, and Industry Trends Forecast 2026-2036
United States Agricultural Robots Market Intelligence
Dealer and OEM direct-to-farm channels is rewriting how agricultural robot systems reach American growers. Deere & Company leverages its integrated operations center to anchor high-margin subscription services alongside hardware sales. AGCO Corporation differentiates through its Fendt brand's autonomous tractor line, which sustains premium positioning in the Midwest row-crop segment. CNH Industrial competes via Raven Industries integration, extending precision control systems across Case IH and New Holland dealer networks.
United States agricultural robots comprise mobile and stationary electromechanical systems equipped with GPS guidance, multispectral sensors, and articulated manipulators designed to perform crop-specific tasks with minimal human intervention. These platforms integrate real-time kinematic positioning achieving sub-inch accuracy for seeding and chemical application across variable field conditions. Harvesting robots currently lead product type deployment in specialty fruit operations, while weeding robots represent the fastest-expanding category as herbicide resistance escalates input costs. Sensor-based technology occupies the largest installed base, though AI-powered systems capture expanding margin pools through predictive crop analytics and autonomous decision loops.
The USDA Natural Resources Conservation Service and EPA pesticide application standards shape equipment certification requirements, while FAA Part 107 governs aerial robot deployment for crop monitoring and variable-rate application. OSHA agricultural safety directives influence autonomous platform design specifications, particularly regarding human-robot interaction protocols in shared field environments. Stakeholders must monitor evolving state-level autonomous vehicle classifications, as California, Iowa, and Nebraska regulatory frameworks will determine interstate equipment mobility and liability allocation.
Market Dynamics
Rural labor scarcity across the Corn Belt and Central Valley is compressing grower tolerance for equipment downtime and accelerating capital deployment toward autonomous platforms with predictive maintenance architectures.
Growth Catalysts
- USDA Precision Agriculture Grant Programs:Federal cost-share mechanisms reduce upfront capital barriers for mid-scale operators adopting GPS-guided seeding and chemical application systems.
- Herbicide Resistance Escalation:Weed biotypes resistant to glyphosate and ALS inhibitors are forcing specialty crop growers toward mechanical and laser-based weeding robotics.
- California Water Stress:Groundwater Sustainability Agency enforcement is driving variable-rate irrigation robots that optimize water application across heterogeneous soil zones.
Market Restraints
- LiDAR and Compute Module Costs:Perception hardware and edge AI processors constitute 35-40% of autonomous platform bill-of-materials, constraining price elasticity in the mid-market.
- Dealer Network Concentration:Three OEM-controlled distribution channels dominate Midwest row-crop equipment procurement, limiting independent robotics vendor market access.
- FAA Part 107 Operational Limitations:Beyond-visual-line-of-sight restrictions constrain aerial robot deployment for large-acreage crop monitoring and variable-rate spraying.
Strategic Opportunities
- Texas Panhandle Feedlot Automation:Cattle finishing operations present untapped demand for autonomous feed delivery and health monitoring platforms in concentrated animal feeding corridors.
- AI-Computer Vision Convergence:Real-time fruit detection algorithms paired with robotic grasping architectures enable strawberry and apple harvesting in unstructured canopy environments.
- OSHA Agricultural Safety Directive Alignment:Compliance with human-robot interaction protocols creates certification-driven preference shifts toward platforms with embedded collision avoidance and emergency stop architectures.
Industry Challenges
- Mechatronics Talent Scarcity:Agricultural equipment OEMs compete with automotive and aerospace sectors for embedded systems engineers capable of integrating RTK-GPS with hydraulic actuation.
- Dealer Technician Certification Timelines:Autonomous platform diagnostics require 18-24 month training programs that outpace current vocational pipeline output across Iowa, Nebraska, and Kansas dealer networks.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | United States Agricultural Robots Market |
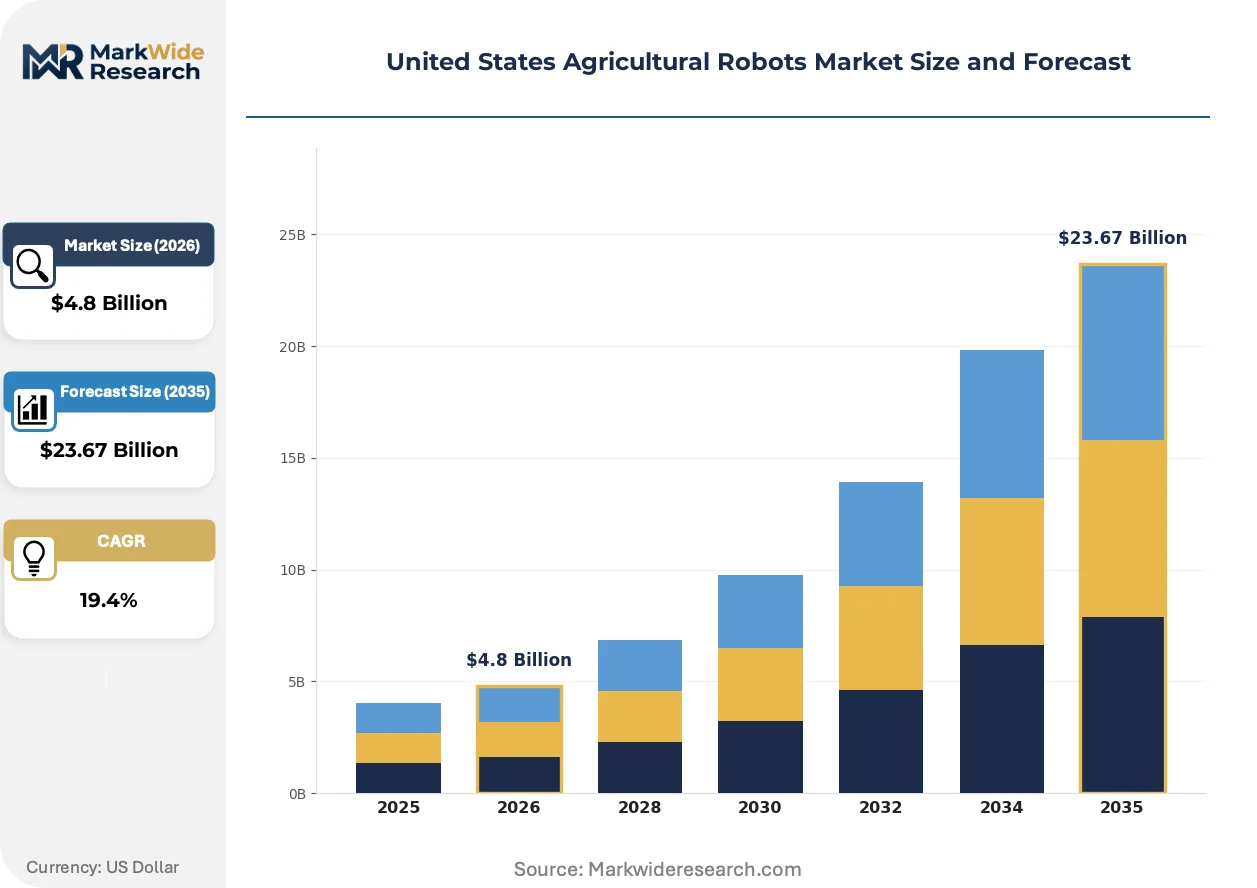
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $23.67 Billion |
| CAGR (2026 – 2036) | 19.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Harvesting Robots, Seeding Robots, Pruning Robots, Weeding Robots Technology: AI-Powered, Autonomous, Sensor-Based, Machine Learning End User: Farmers, Agricultural Cooperatives, Research Institutions, Crop Producers Application: Fruit Picking, Soil Analysis, Pest Control, Crop Monitoring |
| Companies Covered | Deere & Company, AGCO Corporation, CNH Industrial, Autonomous Solutions, Trimble, GEA Group, Harvest Automation, Lely, DroneDeploy, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
United States Agricultural Robots Market Strategic Shifts & Innovations
Digital twin architectures and edge-native AI are collapsing the latency between field data capture and autonomous decision execution, restructuring how American growers interact with capital equipment.
Multispectral sensor fusion is virtualizing crop health assessment by integrating NDVI, thermal, and chlorophyll fluorescence data streams into unified canopy models. Large-scale row-crop operators in Illinois and Indiana are deploying these systems at 10,000+ acre scale during 2024-2025 growing seasons. This virtualization is compressing the agronomic advisory cycle from weekly scout reports to real-time prescription map generation.
EPA pesticide application standards are tightening droplet size spectrum requirements and buffer zone mandates for autonomous aerial and ground platforms. Equipment manufacturers must now certify spray systems through drift reduction technology testing protocols before interstate commerce eligibility. Specialty crop operations in Florida citrus and Washington tree fruit are responding by retrofitting existing fleets with pulse-width modulation nozzles and wind-compensating boom controls.
Subscription-based equipment access is displacing traditional loan-and-own procurement across younger operator cohorts with constrained balance sheet capacity. Deere's Operations Center and AGCO's Fuse platform are unbundling hardware from analytics services, forcing independent dealers to restructure compensation around recurring revenue rather than unit margin. This shift concentrates in the Red River Valley sugar beet and potato production zones where equipment utilization rates support time-based pricing models.
United States Agricultural Robots Market Segmentation
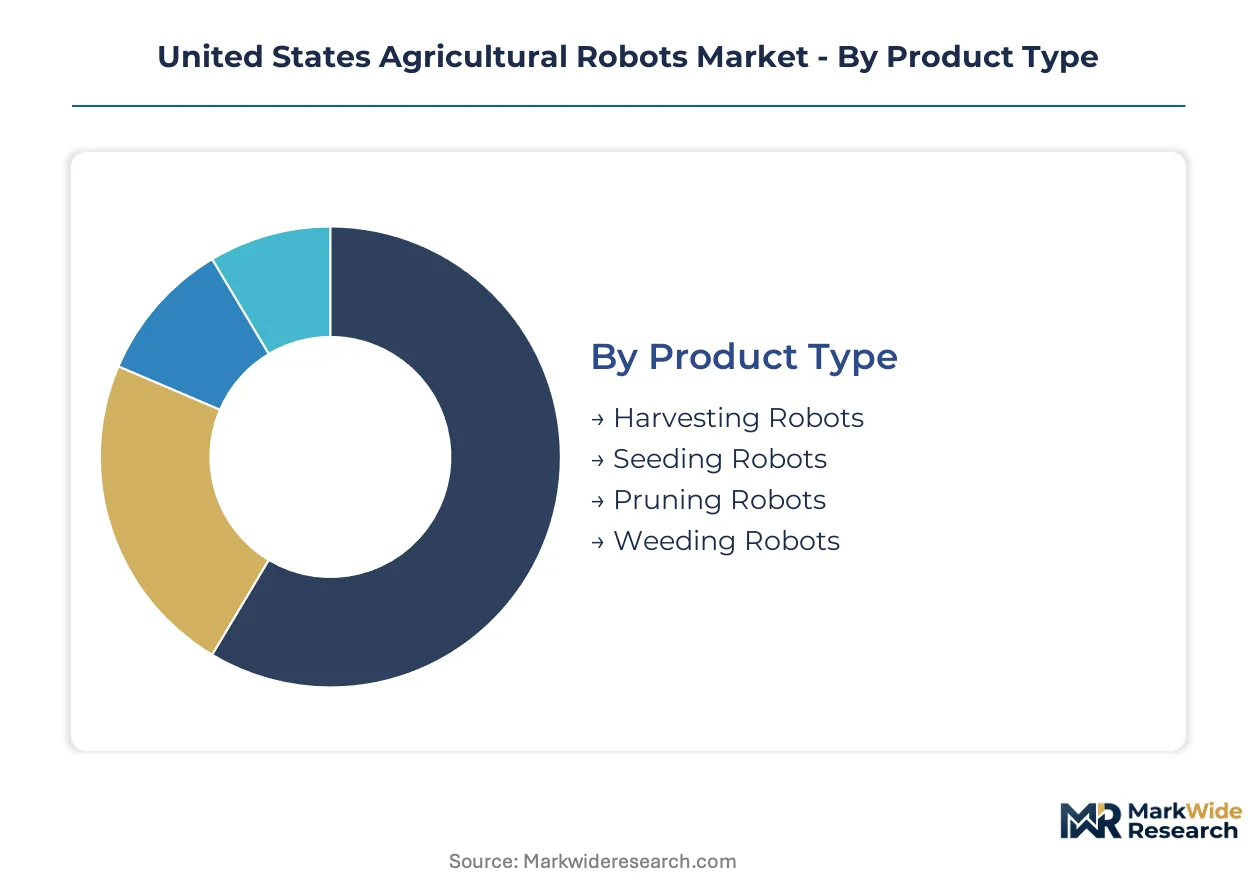
Equipment buyers in the United States Agricultural Robots Market navigate heterogeneous technology stacks and procurement models across crop systems. Segmentation reveals where capital deployment concentrates and which platform architectures command premium positioning.
Product Type:
Mature mechanical systems dominate installed base economics while emerging electromechanical platforms capture expansion capital.
- Harvesting Robots:Articulated manipulators with computer vision-guided grasping execute selective fruit detachment in California strawberry operations and Washington apple orchards. Specialty crop producers facing seasonal labor compression in the Central Valley and Yakima Valley are accelerating procurement of these platforms despite higher capital intensity versus conventional crews.
- Weeding Robots:Laser-based and mechanical intra-row cultivators deploy sub-inch RTK-GPS positioning to eliminate herbicide-resistant weed biotypes without chemical application. Corn Belt row-crop operators confronting glyphosate-resistant Palmer amaranth and waterhemp are redirecting input budgets toward these systems as resistance management mandates intensify.
- Seeding Robots:Autonomous planters with variable-rate seed metering optimize population density across soil conductivity maps.
- Pruning Robots:Vision-guided cutting heads execute dormant and summer pruning in nut orchards and vineyards.
Harvesting robots handle the majority of throughput; weeding robots are the fastest mover on share.
Technology:
Cost tier stratification separates premium autonomous platforms from accessible sensor-augmented equipment.
- Sensor-Based:Multispectral cameras, soil moisture probes, and ultrasonic canopy sensors constitute the largest installed technology base through retrofit attachments and dedicated platforms. Midwest corn and soybean operations deploy these systems at 5,000+ acre scale for NDVI-based nitrogen prescription mapping.
- AI-Powered:Edge-native inference engines running real-time fruit detection and weed classification algorithms capture expanding margin pools through predictive analytics subscriptions. California specialty crop growers are prioritizing these platforms for harvest timing optimization and labor coordination.
- Autonomous:Self-driving tractors and unmanned ground vehicles with collision avoidance and path planning operate without operator presence.
- Machine Learning:Cloud-trained models refined on field-specific datasets improve detection accuracy across growing seasons.
Sensor-based systems anchor volume deployment; AI-powered platforms are climbing the fastest on revenue contribution.
End User:
Customer type determines procurement channel access and financing structure availability.
- Farmers:Owner-operators with 500-5,000 acre holdings constitute the core demand base for mid-market autonomous platforms, leveraging USDA precision agriculture cost-share programs to reduce capital barriers. These operators prioritize equipment with 72-hour dealer service response commitments across Iowa, Illinois, and Indiana.
- Agricultural Cooperatives:Member-owned purchasing consortia aggregate demand across 50-200 farm operations, enabling volume pricing on seeding and chemical application robots. Cooperatives in the Red River Valley and Northern Plains are deploying shared equipment pools with telemetry-based utilization tracking.
- Research Institutions:University extension services and USDA ARS facilities pilot next-generation phenotyping and autonomous systems.
- Crop Producers:Large-scale integrated operations with captive processing infrastructure deploy robotics across vertically controlled supply chains.
Farmers command the dominant procurement volume; agricultural cooperatives are gaining share fastest through pooled capital structures.
Application:
Margin concentration follows the divergence between high-frequency monitoring tasks and capital-intensive selective operations.
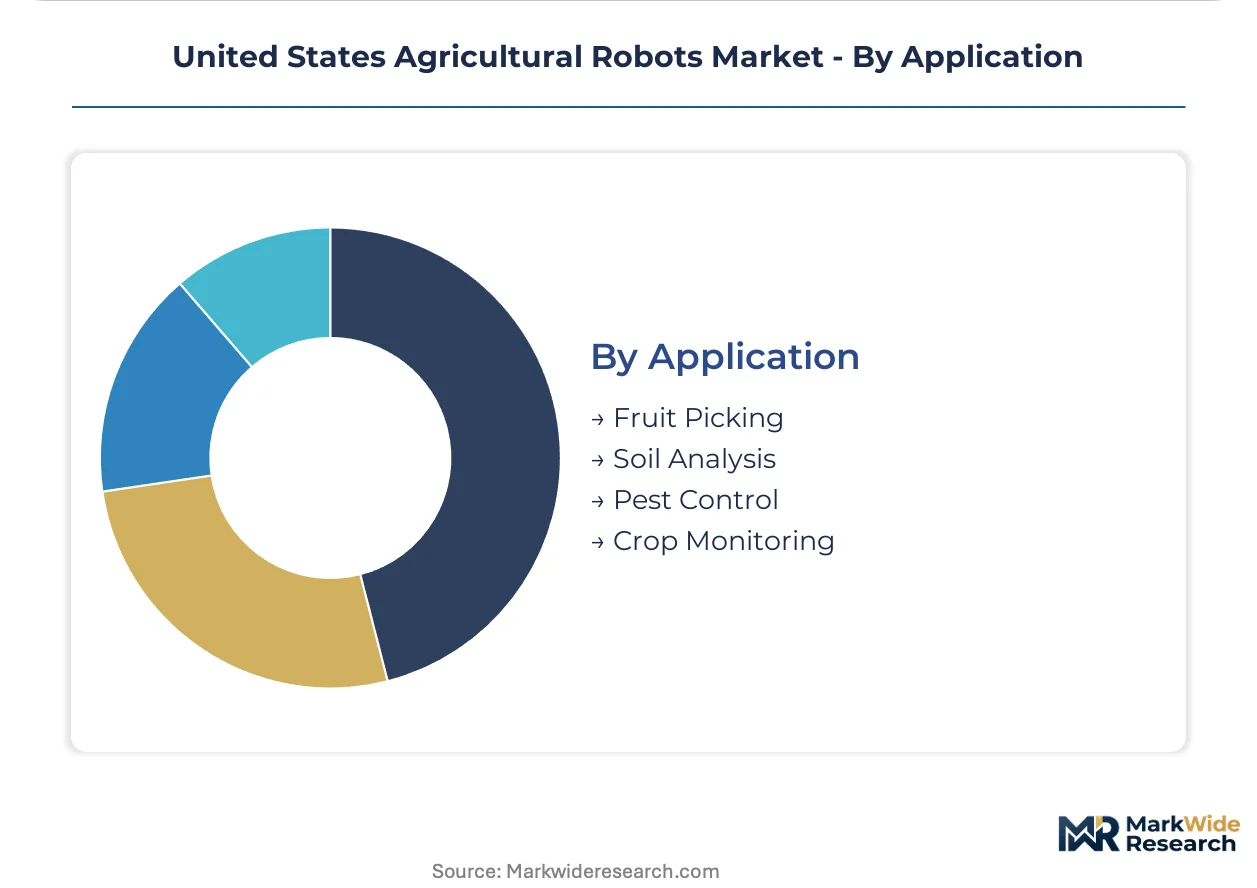
- Fruit Picking:Robotic harvesting of strawberries, apples, and citrus requires soft-touch end-effectors and real-time ripeness classification to minimize bruising and post-harvest decay. Washington tree fruit and Florida citrus operations are deploying these systems where H-2A visa uncertainty disrupts seasonal crew availability.
- Crop Monitoring:Aerial and ground-based multispectral platforms generate prescription maps for variable-rate input application, compressing the agronomic advisory cycle from weekly to real-time. Illinois and Indiana operators are integrating these systems with irrigation scheduling across 10,000+ acre footprints.
- Soil Analysis:Autonomous soil sampling robots with automated core collection and GPS tagging replace manual grid sampling.
- Pest Control:Autonomous sprayers with individual nozzle control and drift reduction technology execute targeted insecticide application.
Crop monitoring carries the largest installed base; fruit picking is expanding most quickly on capital deployment.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
USDA precision agriculture grant programs and EPA pesticide application standards are accelerating capital deployment toward autonomous platforms across distinct agricultural production corridors.
California
Central Valley specialty crop operations confront groundwater sustainability mandates from the California Department of Water Resources. Strawberry and nut orchard operators in Fresno and Kern counties deploy computer vision-guided harvesters to offset H-2A visa uncertainty. The Sacramento-San Joaquin Delta corridor concentrates laser-weeding robot trials targeting herbicide-resistant weed biotypes.
Iowa
Corn Belt row-crop producers leverage USDA Natural Resources Conservation Service cost-share mechanisms for GPS-guided seeding systems. Autonomous tractor deployment concentrates in the Des Moines Lobe and Northwest Iowa Plains where 10,000-acre operations achieve scale economics. Dealer networks in Ames and Waterloo anchor predictive maintenance service commitments for autonomous platforms.
Texas
Panhandle feedlot automation corridors present untapped demand for autonomous cattle health monitoring and feed delivery systems. The Texas Commission on Environmental Quality shapes air quality compliance requirements for concentrated animal feeding operations. Lubbock and Amarillo industrial clusters host pilot deployments of unmanned ground vehicles for pen surface management.
Washington
Yakima Valley tree fruit operations deploy soft-touch robotic end-effectors for apple harvesting amid seasonal labor compression. The Washington State Department of Agriculture enforces pesticide buffer zone mandates that drive precision spray system adoption. Wenatchee and Yakima metropolitan areas concentrate equipment service infrastructure for computer vision-based ripeness classification platforms.
Illinois
Large-scale corn and soybean operators integrate multispectral crop monitoring across 10,000+ acre footprints in the Central Corn Belt Plains. The Illinois Department of Agriculture coordinates with EPA Region 5 on drift reduction technology certification for autonomous aerial application. Champaign-Urbana and Decatur industrial corridors anchor dealer technician training programs for RTK-GPS diagnostic systems.
United States Agricultural Robots Market Key Industry Players
On the supply side, the industry is consolidating around integrated OEM platforms with captive distribution networks and independent robotics specialists with direct-to-farm channels. Equipment manufacturers cluster into three strategic archetypes: legacy agricultural machinery conglomerates with subscription service unbundling, precision agriculture technology vendors with sensor-to-cloud integration, and task-specific robotics startups with narrow application focus. Dominant competitive moves include dealer network exclusivity arrangements and backward integration into edge AI compute modules.
Within the legacy machinery tier, Deere & Company and AGCO Corporation occupy positions defined by integrated operations center architectures and premium brand positioning. CNH Industrial represents the precision control systems archetype through its Raven Industries integration across dealer networks. These three OEMs exemplify how hardware-software bundling creates defensive moats against independent robotics vendors seeking Midwest row-crop market access.
| Leading Market Players |
|---|
| Deere & Company |
| AGCO Corporation |
| CNH Industrial |
| Autonomous Solutions |
| Trimble |
| GEA Group |
| Harvest Automation |
| Lely |
| DroneDeploy |
| Others |
Cost & Logistics Intelligence
Undercapacity in LiDAR sensor fabrication across East Asian contract manufacturers is compressing lead times for perception hardware and forcing Midwest OEMs to accept binding volume commitments that lock in elevated component costs across autonomous platform tiers.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels separates Deere's Operations Center-integrated bundles from AGCO's Fuse-enabled mid-market configurations and independent vendor retrofit kits. Price differentiation rests on RTK-GPS accuracy certification and dealer service response guarantees. Cost compression in the mid-market is intensifying because agricultural cooperatives are aggregating demand across 50-200 member operations. Smallest owner-operators with 500-1,000 acre holdings exhibit highest price sensitivity; integrated 10,000-acre operations show lowest elasticity due to downtime cost exposure.
Supply Chain Analysis
Tariff exposure between China and the United States dominates component sourcing risk for edge AI processors and multispectral camera modules. Geographic supply concentration centers on Taiwan for semiconductor foundry capacity, South Korea for memory components, and domestic Michigan and Ohio facilities for hydraulic actuator assembly. Raw material dependencies draw from rare earth magnets for servo motors, high-purity silicon for sensor substrates, and specialty steel alloys for chassis fabrication. Single-source vulnerability in RTK-GPS receiver chipsets creates procurement fragility. Distribution runs through OEM-captive dealer networks in Iowa, Illinois, and Nebraska with direct-to-farm channels gaining traction among California specialty crop operators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The United States Agricultural Robots Market represents a high-growth disruption as EPA pesticide application standards and FAA Part 107 operational constraints force equipment replacement cycles that favor autonomous platform architectures over conventional machinery.
For Market Incumbents: Harden subscription service architectures against independent robotics vendors by embedding predictive maintenance telemetry into Operations Center and Fuse platforms. Deepen backward integration into edge AI compute modules to reduce exposure to Nvidia and Qualcomm supply constraints. Prioritize 72-hour dealer service response commitments across Corn Belt networks to defend against direct-to-farm channel erosion. For New Entrants and Emerging Players: Establish a beachhead in Texas Panhandle feedlot automation corridors where cattle health monitoring and autonomous feed delivery present white-space demand outside OEM-captive channels. Target California Central Valley specialty crop operations facing H-2A visa uncertainty with computer vision-guided harvesters. Pursue agricultural cooperative purchasing consortia in the Red River Valley as the most penetrable customer archetype with pooled capital structures and shared equipment utilization models. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across AI-powered platform development as edge-native inference engines require sustained R&D commitment beyond mid-market vendor capacity. Long-term viability over the coming decade favors acquisition targets with task-specific robotics expertise in laser-weeding or soft-touch fruit harvesting paired with direct-to-farm channel control. Monitor USDA precision agriculture grant program funding allocations as the signal to watch for demand inflection timing.| Strategic Initiative | Industry Significance |
|---|---|
| Dealer Network Exclusivity Arrangement | OEM-controlled distribution in Iowa and Illinois limits independent vendor market access and pricing power. |
| Backward Integration into Edge AI Modules | In-house perception processor development reduces exposure to Taiwan foundry capacity constraints and tariff risk. |
| Subscription Service Unbundling | Deere's Operations Center and AGCO's Fuse platforms separate hardware from analytics recurring revenue streams. |
| Direct-to-Farm Channel Development | Independent robotics vendors bypass dealer concentration by selling laser-weeding platforms to California strawberry operations. |
| OSHA Safety Protocol Certification Investment | Embedded collision avoidance architectures create compliance-driven preference shifts in shared field environments. |
Research Approach
Findings reconcile primary fieldwork against secondary review of USDA NRCS grant disbursement records, EPA drift reduction technology certification databases, and FAA Part 107 waiver filings. Primary interviews engaged precision agriculture directors at Corn Belt cooperatives, California specialty crop operations managers, and autonomous platform engineering leads at OEM technical centers. Secondary validation drew from SEC 10-K equipment revenue disclosures, dealer network service capacity reports, and university extension precision agriculture adoption surveys. Bottom-up equipment shipment tracking and top-down agricultural machinery expenditure analysis were triangulated to anchor volume estimates.
Forecast inputs incorporate equipment replacement cycle timing, USDA cost-share program funding trajectories, and rural labor availability indices across the projection horizon. Segmentation modeling spans product type, technology tier, end-user archetype, and application with crop system specificity as an additional dimension. CAGRs were derived from fitted growth curves calibrated to historical precision agriculture technology diffusion patterns. Industry-specific inputs include herbicide resistance biotype spread rates and groundwater sustainability agency enforcement timelines.
Sensitivities concentrate around FAA beyond-visual-line-of-sight rulemaking evolution, LiDAR component tariff rate adjustments, and dealer technician certification pipeline expansion. Forecasts reflect documented assumptions regarding autonomous platform reliability maturation and agricultural labor supply constraints. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Robotics and Automation
Hospital Robots Market
Robotics and Automation
Long-Range Drone Package Delivery Market
Robotics and Automation
Global Medical Telepresence Robot Market
Robotics and Automation
Global IT Robotic Automation Market
Robotics and Automation
Smart Curtain Robot Market
Robotics and Automation
Professional Service Robots Market
Robotics and Automation
LAMEA Demolition Robot Market
Robotics and Automation
AGV Software Market
Robotics and Automation
Cordless Router Market
Robotics and Automation
Autonomous Navigation Robots Market
Robotics and Automation
Biaxial Mobile Phone Stabilizer Market
Robotics and Automation
Drone Package Delivery Market
Robotics and Automation
North America AUV and ROV Market
Robotics and Automation
Human-Robot Collaborative Picking Optimization Platforms Market
Robotics and Automation
Robot Controller, Integrator and Software Market
Robotics and Automation
Cybersecurity in Robotics Market