
 Global Indoor Robots Market | 2026-2036
Global Indoor Robots Market Size, Share, and Industry Trends Forecast 2026-2036
Global Indoor Robots Market Outlook
Direct-to-consumer online channels for indoor robots is tilting toward specialized B2B procurement platforms for commercial and healthcare buyers. iRobot Corporation leverages its brand recognition and established retail partnerships to sustain household segment dominance. Ecovacs Robotics competes aggressively on manufacturing scale and price positioning across European and Asian markets. Intuitive Surgical Inc. anchors the healthcare vertical with precision-engineered systems for sterile indoor environments.
Indoor robots comprise autonomous electromechanical systems equipped with lidar, ultrasonic arrays, and simultaneous localization and mapping algorithms, designed to navigate enclosed environments without GPS dependency and execute programmed tasks including cleaning, surveillance, material transport, or human assistance. Vacuum robots occupy the largest installed base among product types due to mature consumer awareness and declining unit costs, while security robots represent the fastest-expanding category as commercial real estate operators seek to reduce overnight staffing expenses. AI-enabled navigation systems command premium positioning within the technology stack, though sensor fusion architectures are displacing single-modality approaches in high-reliability healthcare and delivery applications.
The FDA regulates medical indoor robots as Class II devices requiring 510(k) clearance, while the EU AI Act imposes conformity assessments on autonomous systems interacting with vulnerable populations, directly shaping product development timelines and market access costs. Japan's METI promotes service robot deployment through JIS standards and subsidy programs, creating regulatory pull for eldercare and hospitality applications. Stakeholders must monitor divergence between emerging national AI liability frameworks and existing product safety directives to anticipate certification burdens that will determine competitive viability in regulated indoor environments.
Market Dynamics
Sensor fusion architectures are compressing product development cycles as healthcare and logistics operators demand sub-centimeter navigation precision without GPS dependency. This technical imperative is forcing capital reallocation toward lidar-ultrasonic integration and away from single-modality legacy stacks.
Growth Catalysts
- EU AI Act conformity pathways:The EU AI Act mandates risk-classification assessments for autonomous systems near vulnerable populations, creating certified-product premiums for eldercare deployments in France and Germany.
- Japan METI subsidy programs:METI's service robot deployment incentives accelerate hospital and retail adoption in Tokyo and Osaka metropolitan clusters.
- LiDAR cost curves:Solid-state lidar manufacturing scale is collapsing per-unit sensor costs, enabling mid-tier cleaning robot vendors to spec navigation systems previously confined to premium healthcare units.
Market Restraints
- Semiconductor supply concentration:Advanced motor driver ICs and edge AI processors concentrate among Taiwan and South Korea foundries, exposing production schedules to geopolitical friction.
- FDA 510(k) clearance timelines:Medical indoor robots face average review periods exceeding months for Class II device designation, compressing first-mover windows for patient-monitoring systems.
- Facility retrofit costs:Legacy hospital and warehouse infrastructure requires physical environment modifications for autonomous navigation, inflating total cost of ownership beyond hardware sticker prices.
Strategic Opportunities
- India healthcare infrastructure:Underpenetrated tertiary hospital networks in Maharashtra and Karnataka present first-mover advantages for medication-delivery robot vendors willing to navigate CDSCO medical device rules.
- 5G-private network convergence:Integration of 5G latency with edge computing is enabling real-time multi-robot coordination in dense warehouse environments previously unreachable by Wi-Fi-dependent systems.
- Germany F-Gas Regulation:Phase-down mandates for hydrofluorocarbons in climate-controlled facilities are creating specification windows for temperature-monitoring robots in pharmaceutical cold-chain applications.
Industry Challenges
- SLAM algorithm talent scarcity:Simultaneous localization and mapping expertise concentrates among robotics PhD programs in Zurich, Munich, and Boston, inflating compensation premiums for qualified navigation engineers.
- ISO 13482 certification complexity:Personal care robot safety standards require extensive hazard analysis and documentation, extending product launch timelines for eldercare assistance units.
- Legacy WMS integration:Warehouse management system protocols vary across installed bases, forcing custom API development for each material-handling robot deployment.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Indoor Robots Market |
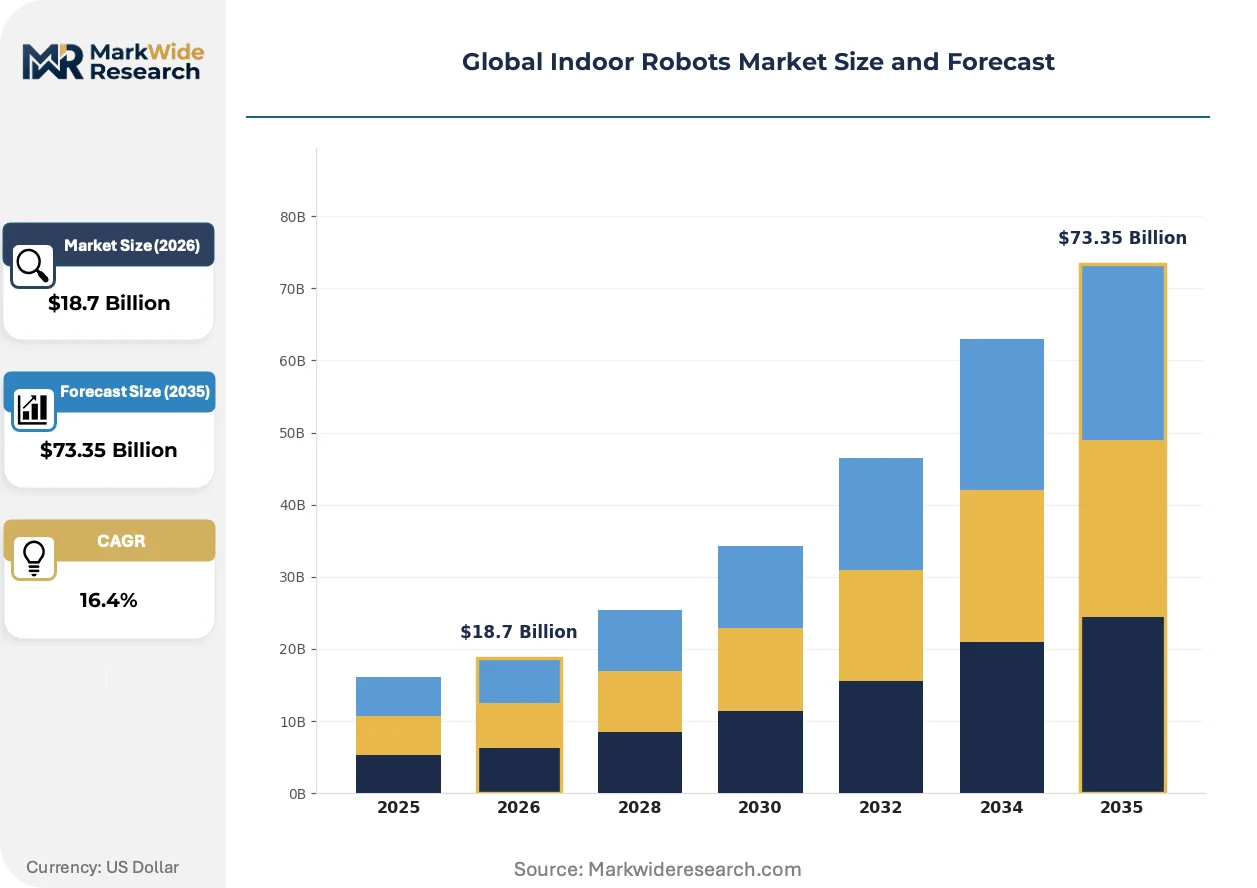
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $73.35 Billion |
| CAGR (2026 – 2036) | 16.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Vacuum Robots, Mopping Robots, Security Robots, Assistant Robots End User: Households, Commercial Spaces, Healthcare Facilities, Educational Institutions Technology: AI, Machine Learning, Navigation Systems, Sensors Application: Cleaning, Surveillance, Delivery, Assistance |
| Companies Covered | iRobot Corporation, Ecovacs Robotics, Intuitive Surgical Inc., Cobalt Robotics, Aethon, Knightscope Inc., DENSO Corporation, Kawasaki Heavy Industries Ltd., Simbe Robotics Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Indoor Robots Market Strategic Shifts
Multi-modal perception stacks are redefining competitive moats as buyers prioritize reliability over raw specification metrics. Technical differentiation now concentrates on sensor fusion robustness and edge-case handling rather than individual component performance.
Neuromorphic computing architectures are rendering obsolete conventional GPU-based inference engines for battery-constrained indoor robots. Eldercare facility operators in Japan and the Netherlands are piloting event-driven vision processors that reduce power consumption by orders of magnitude. This shift is compressing the addressable market for legacy inference hardware and elevating chip vendors with neuromorphic IP.
The EU AI Act's risk-based classification system is mandating conformity assessments for autonomous systems operating in healthcare and eldercare environments. Device manufacturers must now maintain technical documentation and human oversight protocols that extend development timelines. Medical robot segments in France, Germany, and Italy are responding by embedding compliance teams earlier in product design cycles.
Hospital procurement departments are consolidating vendor relationships around full-service fleet management contracts rather than capital equipment purchases. This behavioral pivot displaces traditional distributor networks in favor of direct manufacturer partnerships with dedicated service arms. The transformation is most visible in German and Japanese healthcare systems where operating lease structures now dominate new robot acquisitions.
Global Indoor Robots Market Segmentation
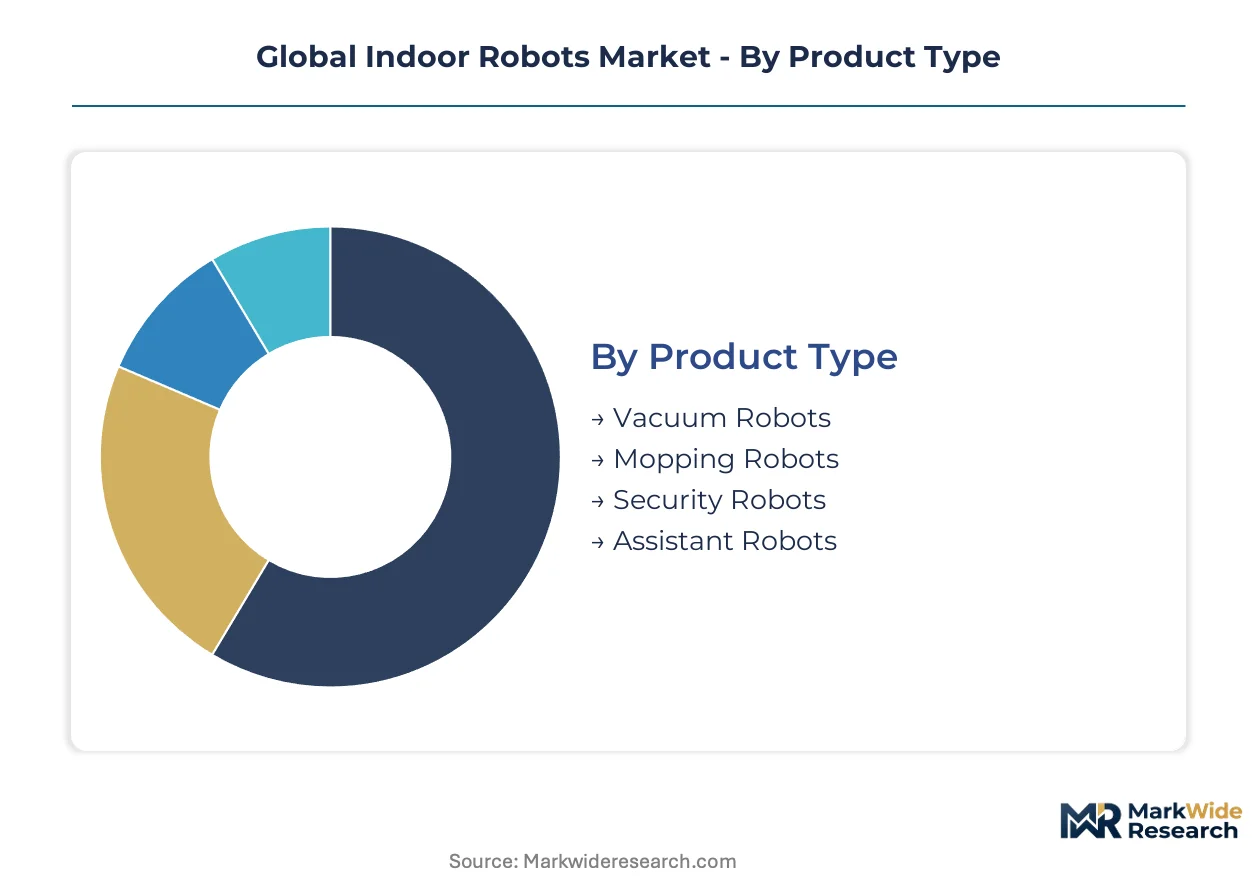
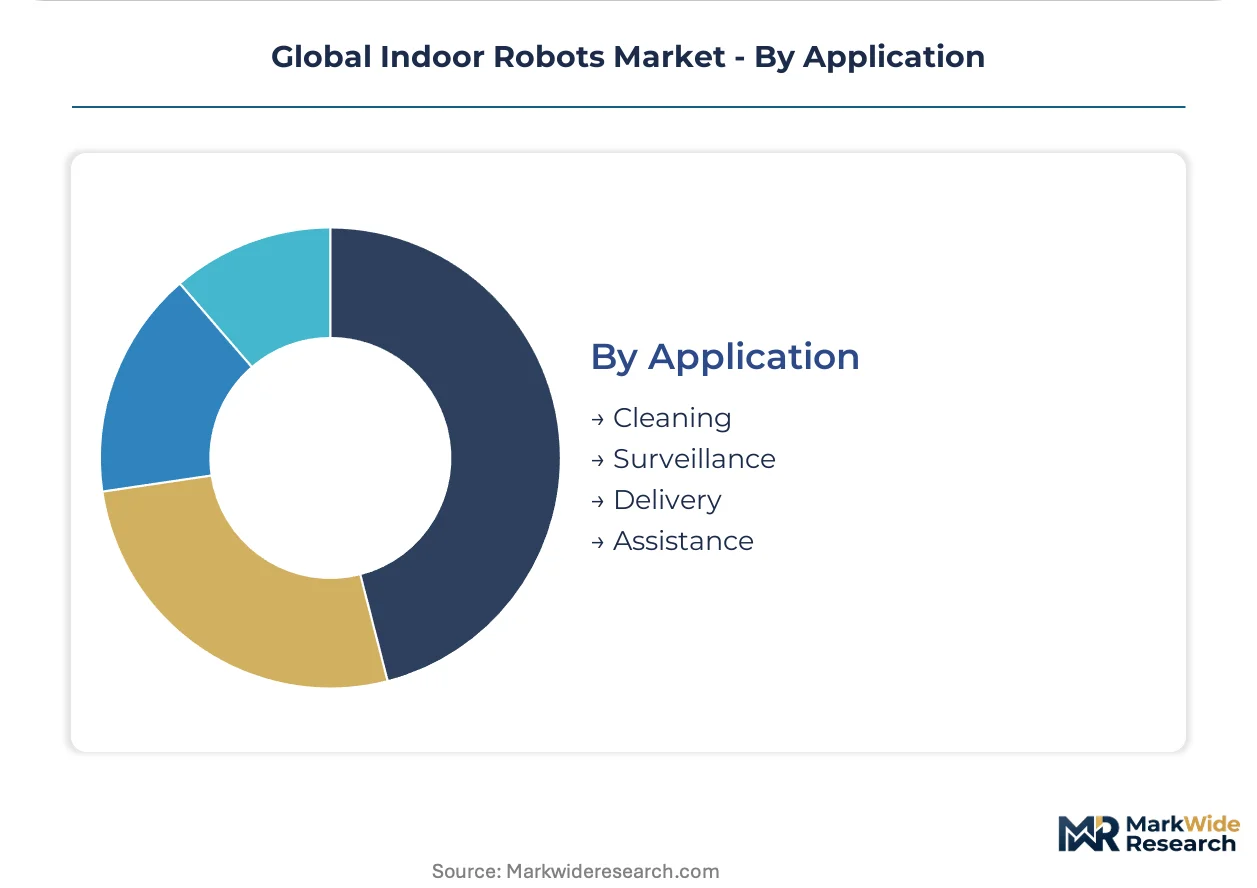
Segmentation in indoor robotics reveals divergent maturity curves across product categories, with consumer-facing applications saturating while healthcare and security verticals command premium positioning through specialized compliance requirements.
Product Type:
Mature household automation contrasts sharply with emerging autonomous systems for commercial security and patient care.
- Vacuum Robots:Autonomous floor-cleaning units equipped with lidar and SLAM algorithms for residential navigation. Demand concentrates in Japanese and German urban households where aging demographics and dual-income constraints compress domestic labor availability.
- Security Robots:Autonomous surveillance platforms integrating thermal imaging, acoustic sensors, and real-time alert systems for commercial real estate. Deployment accelerates in Singapore and Dubai office complexes seeking to eliminate overnight security staffing costs while satisfying insurer risk-assessment protocols.
- Mopping Robots:Hard-surface cleaning systems with water management and surface-detection capabilities. Adoption clusters in South Korean and Spanish residential markets with high hard-flooring penetration.
- Assistant Robots:Human-interactive platforms for patient mobility support and medication reminders in eldercare settings. Pilot programs in Dutch and Swedish assisted-living facilities are validating ISO 13482 safety protocols for physical human-robot contact.
Vacuum robots retain volume leadership; security robots hold the steepest expansion curve.
End User:
Procurement sophistication separates consumer impulse purchases from institutional capital-commitment cycles.
- Households:Individual consumers acquiring single-unit or small-fleet cleaning automation through retail and direct-to-consumer channels. Replacement cycles in US and Australian markets are shortening as subscription-based consumable models lock in brand loyalty.
- Healthcare Facilities:Hospitals and eldercare operators deploying patient-monitoring and medication-delivery systems under FDA 510(k) or EU MDR compliance frameworks. German university hospitals in Munich and Berlin are consolidating vendor relationships around full-service fleet management contracts.
- Commercial Spaces:Retail operators and office landlords integrating cleaning and security robots into facilities management workflows. Deployment in French hypermarket chains is accelerating through EU AI Act conformity pathways that certify autonomous operation near shopping publics.
- Educational Institutions:Universities and research facilities utilizing indoor robots for laboratory logistics and campus security. MIT and ETH Zurich maintain active procurement for multi-robot coordination research platforms.
Households dominate installed base; healthcare facilities generate the highest revenue per unit deployed.
Technology:
Hardware-software integration depth determines competitive differentiation across price tiers.
- Navigation Systems:SLAM-based spatial mapping and path-planning architectures enabling GPS-independent operation. Solid-state lidar cost curves are collapsing per-unit sensor expenses, democratizing sub-centimeter precision for mid-tier cleaning vendors.
- AI:Edge-deployed inference engines for object recognition, anomaly detection, and human intent prediction. EU AI Act risk-classification mandates are forcing architecture redesigns for eldercare applications in France and Italy.
- Sensors:Multi-modal perception stacks combining ultrasonic, infrared, and tactile arrays for environmental awareness. Japanese automotive suppliers are leveraging manufacturing scale to supply healthcare robot manufacturers with automotive-grade reliability components.
- Machine Learning:Training pipelines for edge-case handling and fleet-wide behavioral optimization. Cloud-dependent learning architectures face deployment constraints in German healthcare settings under GDPR data-localization requirements.
Navigation systems anchor current bill-of-materials costs; AI layers are climbing the fastest as compliance documentation requirements expand.
Application:
Task specificity shapes hardware configuration and software stack requirements.
- Cleaning:Floor maintenance automation spanning vacuum, mop, and scrubbing modalities. Mature category with price compression forcing vendor consolidation toward Ecovacs and iRobot manufacturing scale.
- Assistance:Physical support and companionship functions for elderly and mobility-impaired users. METI subsidy programs in Tokyo and Osaka metropolitan clusters are accelerating hospital adoption of patient-monitoring platforms.
- Surveillance:Autonomous patrol and anomaly detection for commercial and institutional security. 5G-private network convergence is enabling real-time multi-robot coordination in dense warehouse environments previously unreachable by Wi-Fi-dependent systems.
- Delivery:Internal logistics for medication, documents, and supplies within controlled facilities. Underpenetrated tertiary hospital networks in Maharashtra and Karnataka present first-mover positioning for vendors navigating CDSCO medical device rules.
Cleaning commands installed base dominance; delivery applications are expanding most quickly as hospital infrastructure modernizes.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
METI subsidy programs in Japan accelerate service robot deployment in eldercare and retail environments. The EU AI Act tightens conformity assessments for autonomous systems near vulnerable populations. FDA 510(k) clearance timelines compress first-mover windows for patient-monitoring systems in the United States.
Japan
Aging demographics and acute labor shortages drive hospital and retail adoption of assistant robots. METI service robot deployment incentives channel capital toward Tokyo and Osaka metropolitan clusters. Kanto region facilities validate ISO 13482 safety protocols for physical human-robot contact in eldercare settings.
Germany
University hospitals in Munich and Berlin consolidate vendor relationships around full-service fleet management contracts. The EU AI Act mandates risk-classification assessments for eldercare deployments, creating certified-product premiums. Bavarian healthcare systems now dominate operating lease structures for new robot acquisitions.
United States
Healthcare facilities expand adoption of assistant robots for patient monitoring and medication delivery. FDA Class II device classification requires average review periods exceeding months, compressing commercialization timelines. MIT and Greater Boston research institutions maintain active procurement for multi-robot coordination platforms.
France
Hypermarket chains accelerate deployment through EU AI Act conformity pathways certifying autonomous operation near shopping publics. ANSM and CNIL oversight shapes data-localization requirements for cloud-dependent learning architectures. Île-de-France hospital procurement departments pivot from capital equipment purchases to consolidated fleet management contracts.
India
Underpenetrated tertiary hospital networks in Maharashtra and Karnataka present first-mover positioning for medication-delivery vendors. CDSCO medical device rules govern product registration and clinical evaluation requirements. Bengaluru and Mumbai metropolitan clusters concentrate pilot programs for internal logistics automation.
Global Indoor Robots Market Competitive Environment
On the supply side, the industry is consolidating around manufacturing scale and specialized healthcare engineering capabilities. Tiered competitive positioning separates household consumer brands from precision medical device fabricators. Three strategic archetypes dominate: retail-anchored consumer electronics vendors, sterile-environment surgical system specialists, and commercial security automation providers. Dominant competitive moves include backward integration into sensor manufacturing and geographic expansion through direct manufacturer partnerships replacing distributor networks.
Within the household automation tier, iRobot Corporation and Ecovacs Robotics exemplify scale-driven manufacturing archetypes competing on brand recognition and price positioning across European and Asian markets. Intuitive Surgical Inc. anchors the healthcare vertical as a precision-engineered systems specialist for sterile indoor environments. These three entities collectively represent the divergence between consumer volume leadership and premium medical device engineering.
| Leading Market Players |
|---|
| iRobot Corporation |
| Ecovacs Robotics |
| Intuitive Surgical Inc. |
| Cobalt Robotics |
| Aethon |
| Knightscope Inc. |
| DENSO Corporation |
| Kawasaki Heavy Industries Ltd. |
| Simbe Robotics Inc. |
| Others |
Value Chain & Pricing Dynamics
Shanghai-to-Rotterdam container freight corridors transmit cost volatility from Asian component hubs into European end-market pricing, amplifying spreads between FDA-certified medical units and uncertified commercial alternatives while compressing margins for mid-tier cleaning robot vendors lacking scale.
Pricing Analysis
Certification level (ISO 13482/FDA 510(k)/CE-MDR tier) creates the primary spread between premium healthcare systems and standard commercial units. Three-tier pricing structure across premium, standard, and economy levels dominates, with EU AI Act conformity documentation adding certification premiums for eldercare deployments. Price erosion runs through the standard tier as solid-state lidar cost compression enables feature migration downward. Healthcare procurement committees show lowest price sensitivity due to operating lease structures, while household consumers in price-elastic Asian markets drive volume through promotional discounting.
Supply Chain Analysis
Export controls on advanced edge AI processors and solid-state lidar components restrict flows from Taiwan and South Korea into Chinese assembly operations, fragmenting procurement strategies. Manufacturing concentrates in China, Japan, and Germany for final assembly, with critical inputs drawing from Taiwanese foundries for motor driver ICs and Japanese automotive suppliers for sensor modules. Single-source vulnerability in advanced neuromorphic vision processors elevates supply risk for battery-constrained eldercare units. Distribution runs through direct manufacturer partnerships replacing legacy distributor networks in German and Japanese healthcare systems.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Global Indoor Robots Market sits in early-cycle expansion as METI subsidy programs and EU AI Act conformity pathways accelerate institutional procurement beyond consumer saturation levels.
For Market Incumbents: Harden certification moats by embedding EU AI Act technical documentation teams into product design cycles before competitor catch-up. Deepen backward integration into solid-state lidar manufacturing to neutralize sensor cost compression threats from emerging Asian vendors. Prioritize fleet management contract structures in German university hospitals to lock out substitution.
For New Entrants and Emerging Players: Mid-market commercial buildings in Southeast Asia represent the most penetrable entry point, with Singapore and Dubai office complexes seeking overnight security staffing elimination. Underpenetrated tertiary hospital networks in Maharashtra and Karnataka offer first-mover positioning for medication-delivery specialists navigating CDSCO rules. Lead with 5G-private network integration capabilities to differentiate from Wi-Fi-dependent incumbents in warehouse coordination.
For Investors and Strategic Acquirers: Carve-out targets emerge from diversified industrial conglomerates with dormant service robotics divisions lacking healthcare certification expertise. Long-term viability hinges on regulatory compliance scalability across EU AI Act and FDA 510(k) jurisdictions. Watch for inflection when Japanese eldercare facilities shift from pilot programs to fleet-scale procurement under revised METI subsidy thresholds.
| Strategic Initiative | Industry Significance |
|---|---|
| EU AI Act Conformity Pathway | Technical documentation investment unlocks certified-product premiums in French and German eldercare markets. |
| Solid-State LiDAR Backward Integration | Captive sensor manufacturing neutralizes cost compression threats and secures sub-centimeter navigation supply. |
| Fleet Management Contract Pivot | Operating lease structures in Bavarian healthcare systems displace capital equipment distributors. |
| 5G-Private Network Partnership | Real-time multi-robot coordination capabilities penetrate dense warehouse environments unreachable by Wi-Fi systems. |
| Neuromorphic Computing Platform Launch | Event-driven vision processors reduce power consumption for battery-constrained Japanese eldercare deployments. |
Study Parameters
Findings reconcile primary fieldwork against secondary review of FDA 510(k) filings, EU MDR conformity assessments, METI subsidy program disclosures, and hospital procurement databases. Interviews with biomedical engineers, GPO contracts managers, eldercare facility operators, and robotics navigation specialists informed demand-side validation. Top-down macroeconomic triangulation against bottom-up vendor shipment estimates anchored volume projections.
Forecast inputs span product type, end-user vertical, technology stack tier, and application specificity across the projection horizon. CAGRs derive from segment-level adoption curve modeling calibrated to regulatory approval timelines and facility retrofit cost amortization. Neuromorphic computing penetration rates and 5G-private network deployment schedules inform technology transition assumptions.
Stress conditions across semiconductor supply availability, EU AI Act enforcement intensity, and Japanese labor shortage acceleration were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions about certification timeline compression and facility infrastructure readiness. Material shifts in export control regimes for edge AI processors would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Robotics and Automation
Underwater Rescue Robot Market
Robotics and Automation
Drone-Based NDT Inspection Systems for Energy and Infrastructure Assets Market
Robotics and Automation
GCC AUV Market
Robotics and Automation
Middle East and Africa Medical Robots Market
Robotics and Automation
Agriculture Robotics Market
Robotics and Automation
South America AUV and ROV Market
Robotics and Automation
Robotics for NDT Market
Robotics and Automation
Hospital Logistics Robots Market
Robotics and Automation
Hospital Robots Market
Robotics and Automation
Social Robots Market
Robotics and Automation
Global AI Based Surgical Robots Market
Robotics and Automation
Lab Robotics Market
Robotics and Automation
Robotic Process Automation in Legal Services Market
Robotics and Automation
Europe AUV and ROV Market
Robotics and Automation
Nanorobotics Market
Robotics and Automation
Snake Robots Market