
 Root Canal Irrigators Market | 2026-2036
Root Canal Irrigators Market Size, Share, and Industry Trends Forecast 2026-2036
Root Canal Irrigators Market Analysis
Equipment leasing and pay-per-procedure financing is rewriting competitive entry barriers for smaller dental practices seeking advanced irrigator systems. Dentsply Sirona leverages its global service network to sustain installed-base loyalty across premium ultrasonic platforms. Ultradent Products anchors its position through concentrated R&D spending on closed-loop irrigation technologies. Vista Dental Products specializes in disposable tip configurations that reduce cross-contamination liability for high-volume clinics.
Root canal irrigators are fluid-delivery devices engineered to generate controlled pressure between 0.3 and 6.0 bar for debriding and disinfecting complex root canal anatomies, with tip diameters typically ranging from 27 to 31 gauge for apical third penetration. Their primary purpose is to eliminate microbial biofilm and smear layer debris that mechanical instrumentation alone cannot remove, thereby improving endodontic treatment outcomes. Ultrasonic irrigators command the dominant margin pool due to acoustic streaming enhancement of irrigant penetration into lateral canals. Automated delivery systems represent the fastest-expanding segment as workflow integration and repeatable pressure profiling reduce operator variability. Syringe irrigators remain a mature, cost-driven category with stable replacement demand across price-sensitive private practices.
FDA 510(k) clearance pathways and ISO 13485 quality management standards govern device commercialization and manufacturing audit requirements in the United States and European export markets. The EU Medical Device Regulation intensifies clinical evidence expectations for reusable irrigator handpieces, extending development timelines and consolidating compliance investment among larger manufacturers. Stakeholders must monitor evolving biofilm efficacy validation protocols and reimbursement shifts toward outcome-based dental contracts as these forces reshape procurement criteria and vendor selection.
Market Dynamics
Automated delivery systems are compressing operator variability while EU MDR compliance timelines are consolidating development resources among manufacturers with sufficient regulatory infrastructure.
Growth Catalysts
- EU MDR clinical evidence mandates:Reusable handpiece requirements are filtering out undercapitalized competitors and concentrating procurement authority among hospital systems with dedicated compliance teams.
- Acoustic streaming enhancement:Ultrasonic activation protocols are expanding irrigant penetration into lateral canal anatomies previously unreachable through passive delivery.
- German endodontic specialist density:Concentrated practitioner networks in Bavaria and North Rhine-Westphalia generate per-capita utilization rates that exceed broader European averages.
Market Restraints
- Stainless steel cannula cost volatility:Input price swings for precision-gauge tubing compress margins on disposable tip configurations.
- Reusable handpiece sterilization liability:Cross-contamination litigation exposure elevates insurance costs for clinics maintaining legacy instrument fleets.
- Syringe irrigator substitution pressure:Manual delivery systems retain cost advantage in price-sensitive private practices with lower procedure volumes.
Strategic Opportunities
- Closed-loop irrigation convergence:Integration of suction-irrigation coupling with real-time pressure feedback is opening workflow efficiency gains in high-volume clinics.
- Pay-per-procedure financing:Equipment leasing structures are lowering capital barriers for independent dental practices seeking automated platform access.
- FDA 510(k) predicate pathway optimization:Streamlined clearance routes for ultrasonic platform iterations are accelerating product refresh cycles relative to European counterparts.
Industry Challenges
- ISO 13485 audit preparation:Quality management certification timelines extend product launch windows for manufacturers without established regulatory affairs functions.
- Legacy system integration complexity:Automated irrigator deployment requires chairside workflow reconfiguration that strains staff training bandwidth.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Root Canal Irrigators Market |
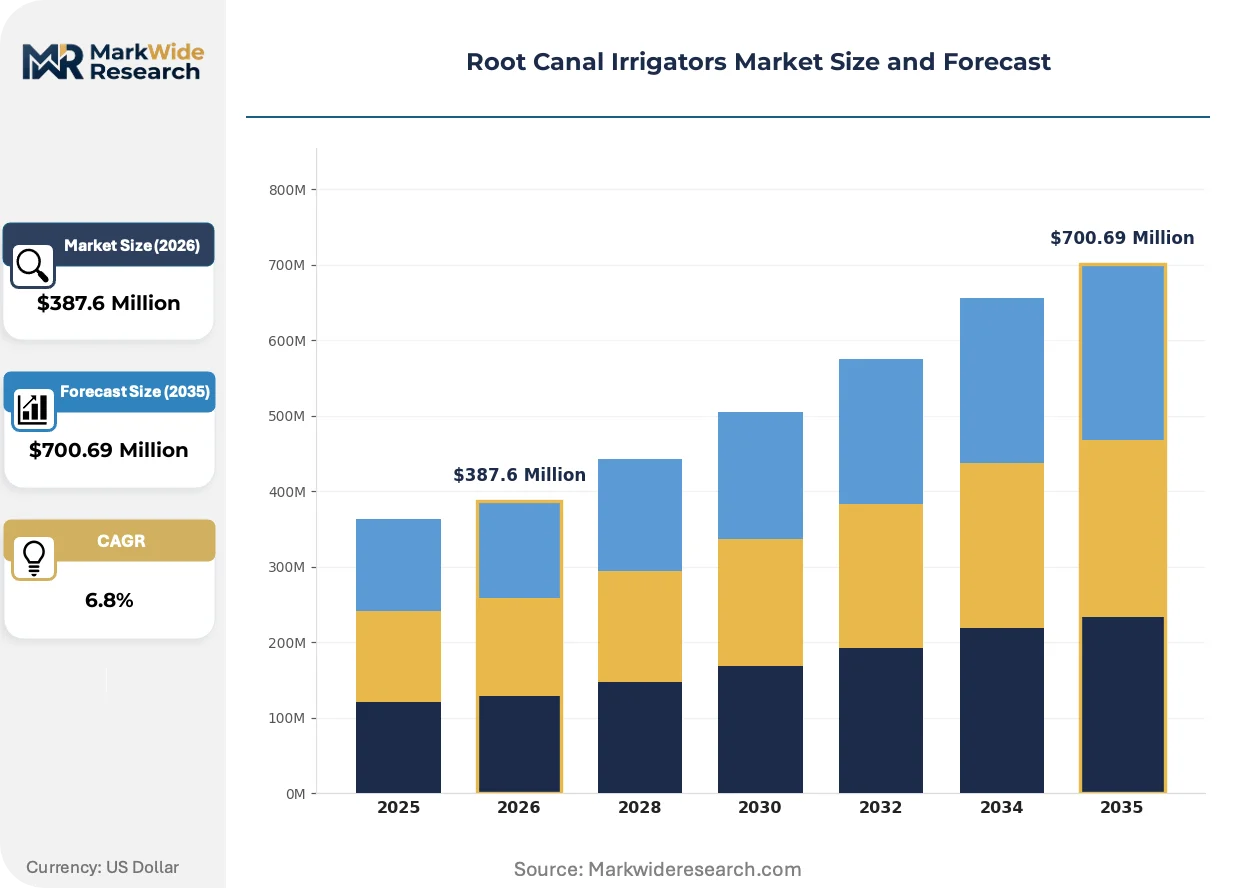
| Market Size in 2026 | $387.6 Million |
| Market Size in 2035 | $700.69 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Apex Locators, Syringe Irrigators, Sonic Irrigators, Ultrasonic Irrigators Delivery Mode: Manual, Automated, Disposable, Reusable End User: Dental Clinics, Hospitals, Research Institutes, Private Practices Application: Root Canal Treatment, Endodontic Procedures, Cleaning, Disinfection |
| Companies Covered | Dentsply Sirona, Ultradent Products, Vista Dental Products, Zipperer, Roydent Dental Products, PD Dental, Pac-Dent International, Medesy, Septodont, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Root Canal Irrigators Market Emerging Trajectories
Pressure profiling automation and closed-loop feedback architectures are displacing manual technique dependency while regulatory evidence requirements reshape competitive entry economics.
Photacoustic-activated irrigant delivery is hybridizing ultrasonic streaming with laser-induced cavitation to penetrate dentinal tubule networks beyond conventional acoustic reach. Academic dental centers in Switzerland and Japan are piloting these platforms for complex retreatment cases. The technology is hybridizing premium system positioning by bundling previously separate energy modalities into single-device configurations that command expanded service contracts.
FDA's medical device classification framework is intensifying predicate device scrutiny for ultrasonic irrigator submissions, extending 510(k) preparation timelines for novel pressure-control algorithms. Manufacturers are responding by accumulating clinical performance data through institutional review board protocols ahead of formal filings. Class II device reclassifications are most affecting automated delivery platforms with integrated suction capabilities.
After-sales service unbundling is fragmenting traditional equipment-purchase bundles into separate maintenance, calibration, and software update subscriptions. Dental service organizations in the United States are driving this shift by centralizing procurement across multi-site networks and negotiating standalone technical support agreements. Independent practices in Texas and Florida are following this model to preserve capital flexibility.
Root Canal Irrigators Market Segmentation
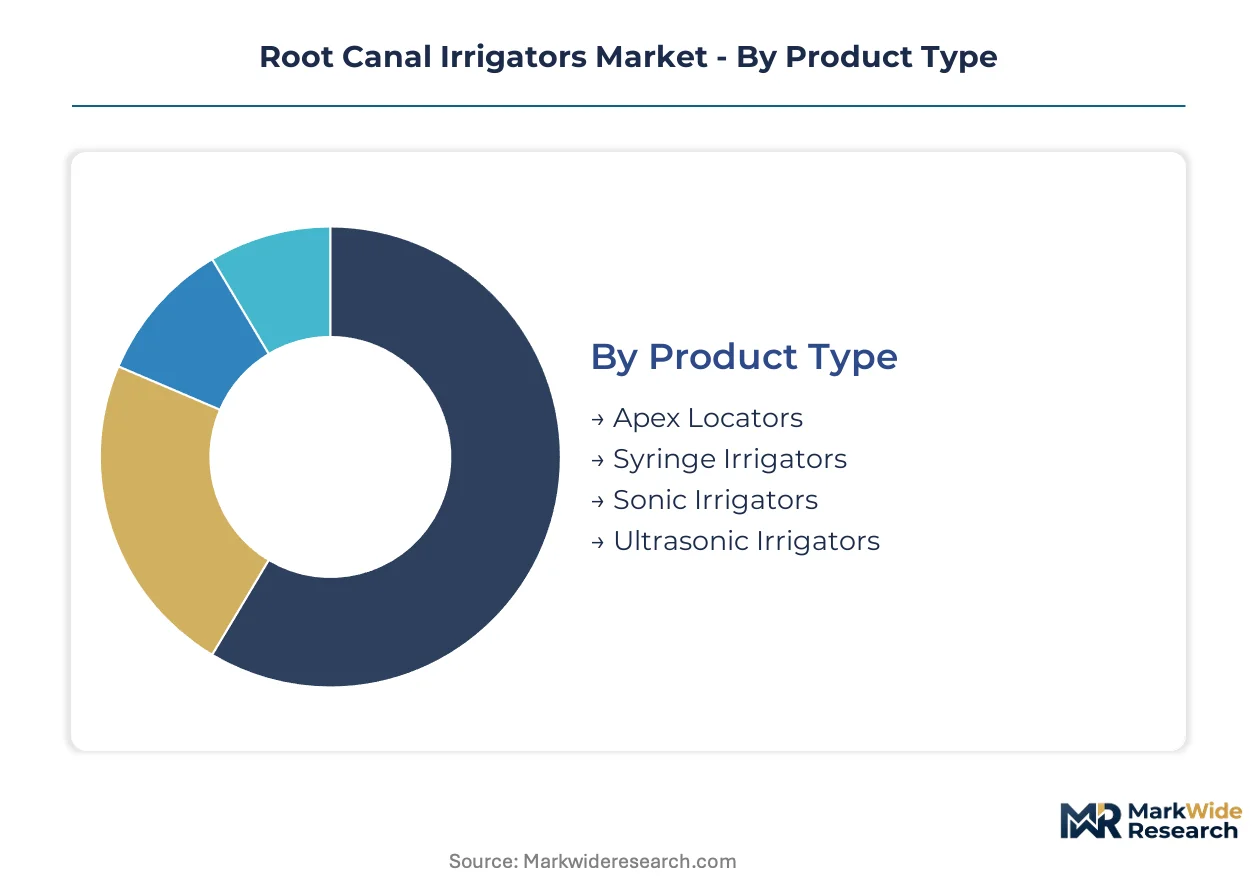
Segmentation in root canal irrigators reveals how clinical workflow requirements, sterilization protocols, and capital investment thresholds partition demand across device configurations. Understanding these splits enables manufacturers to align pressure-control specifications and service models with distinct procurement contexts.
Product Type:
Use-case spectrum spans passive mechanical delivery through active energy-assisted systems, with each tier commanding different margin profiles and replacement cycles.
- Ultrasonic Irrigators:These systems generate acoustic streaming through piezoelectric transducers oscillating at 25-30 kHz, enhancing irrigant penetration into lateral canal branches. Bavarian endodontic specialists in Germany drive concentrated demand for these premium platforms due to complex retreatment caseloads and reimbursement structures favoring outcome documentation.
- Syringe Irrigators:Manual plunger-operated devices utilizing 27-31 gauge stainless steel or polymer cannulas for basic debridement. Private practices in price-sensitive U.S. markets like Texas and Florida sustain replacement demand for these configurations where procedure volumes do not justify automated capital expenditure.
- Sonic Irrigators:Air-driven oscillation at 1,500-6,000 Hz provides intermediate activation energy for clinics seeking enhanced penetration without ultrasonic infrastructure investment.
- Apex Locators:Electronic impedance-based devices for working length determination, often bundled with irrigation systems in integrated endodontic consoles.
The dominant share belongs to Ultrasonic Irrigators, while Syringe Irrigators retain stable penetration in cost-constrained settings.
Delivery Mode:
Capital intensity and cross-contamination liability create sharp differentiation between permanent infrastructure and consumable alternatives.
- Automated:Microprocessor-controlled pressure profiling between 0.3-6.0 bar with programmable delivery cycles. High-volume dental clinics in North Rhine-Westphalia are standardizing on these platforms to reduce operator variability and document irrigant volume for regulatory compliance.
- Disposable:Single-use polymer handpieces and cannula assemblies eliminating sterilization workflow. Hospital systems managing multi-operator environments prioritize these configurations to mitigate cross-contamination litigation exposure.
- Manual:Operator-dependent pressure application through conventional syringe mechanics.
- Reusable:Autoclavable metal handpieces requiring validated sterilization protocols per EU MDR clinical evidence mandates.
Automated systems command the premium tier, with Disposable configurations climbing fastest as liability concerns reshape procurement specifications.
End User:
Procurement authority concentrates differently across organizational structures, from centralized hospital supply chains to independent practice owner-operators.
- Dental Clinics:Multi-chair group practices with dedicated endodontic operators. These facilities in urban German clusters are deploying closed-loop irrigation systems with integrated suction to compress chair time per procedure.
- Hospitals:Academic medical centers and tertiary care facilities with institutional review board infrastructure for clinical evidence generation. Swiss and Japanese academic dental centers are piloting photacoustic-activated platforms within these settings.
- Private Practices:Solo or small-group owner-operators with direct capital allocation authority.
- Research Institutes:University-affiliated centers developing novel irrigant formulations and delivery protocols.
Dental Clinics hold the volume base, though Hospitals are expanding fastest as EU MDR compliance requirements favor centralized procurement functions.
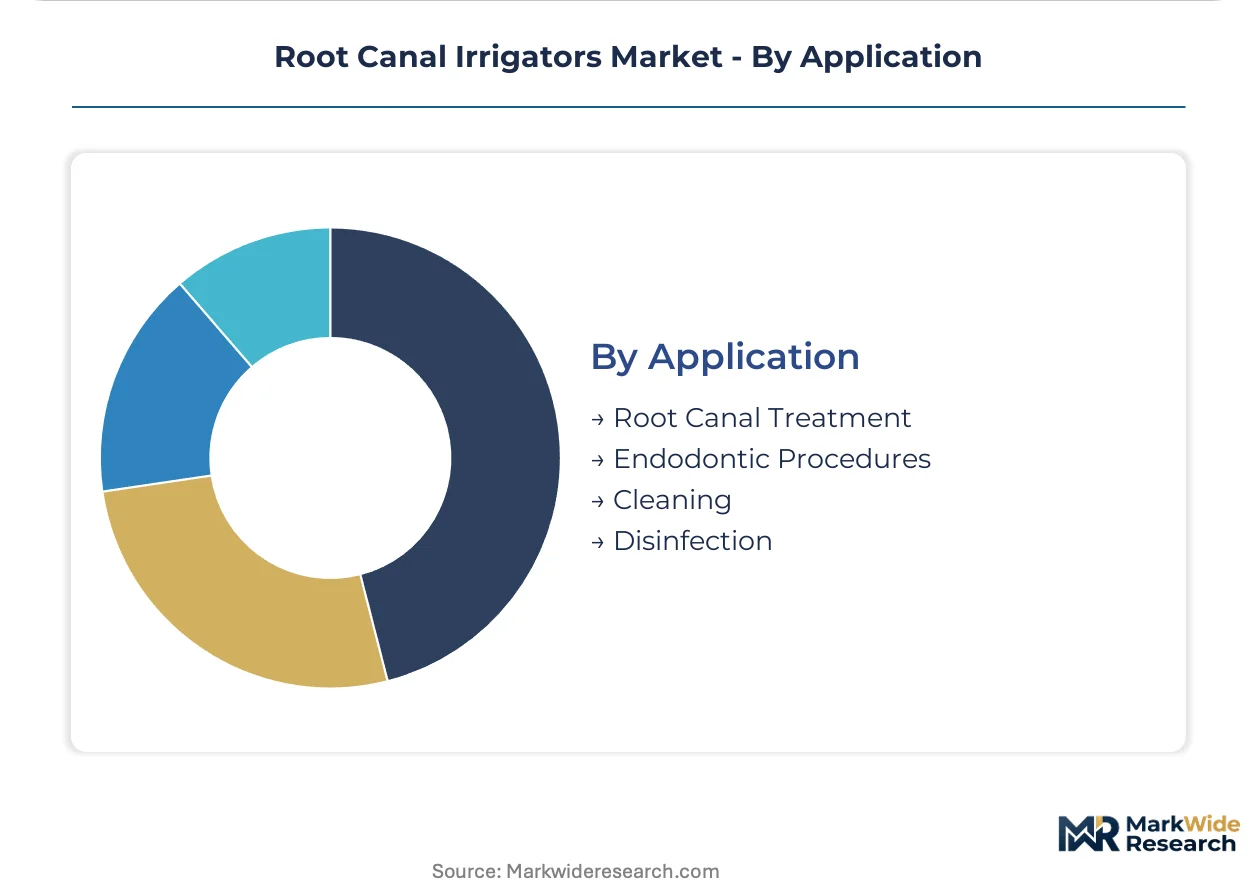
Application:
Clinical indication severity determines pressure-parameter requirements and irrigant selection, from routine debridement through complex retreatment scenarios.
- Root Canal Treatment:Primary debridement and disinfection of vital and necrotic pulpal tissue. German specialist networks concentrate demand for precision pressure control in these foundational procedures.
- Endodontic Procedures:Broader category encompassing retreatment, apical surgery, and regenerative protocols. Academic centers in Switzerland are advancing photacoustic-activated delivery for complex retreatment anatomies previously unreachable through conventional acoustic streaming.
- Cleaning:Mechanical debris removal prior to obturation.
- Disinfection:Antimicrobial irrigant activation for biofilm elimination.
Root Canal Treatment anchors installed base, while Endodontic Procedures are gaining share fastest as retreatment caseloads expand across aging populations.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
EU MDR compliance timelines are filtering market access across jurisdictions, with reimbursement structures and specialist density shaping national adoption curves for automated irrigator platforms.
Germany
Bavarian and North Rhine-Westphalian endodontic specialist networks drive per-capita utilization rates above European averages. The country's statutory health insurance system reimburses outcome-documented procedures, incentivizing precision pressure-control adoption. Stuttgart-based dental equipment distributors report accelerating automated platform deployments among multi-chair group practices.
United States
FDA 510(k) clearance pathways enable faster product refresh cycles for ultrasonic platform iterations compared to European counterparts. Texas and Florida private practices sustain syringe irrigator demand where procedure volumes limit capital expenditure justification. Cleveland Clinic and Mayo Clinic systems are piloting closed-loop irrigation with integrated suction capabilities.
Switzerland
Academic dental centers in Geneva and Zurich are advancing photacoustic-activated delivery protocols for complex retreatment anatomies. Swissmedic maintains stringent clinical evidence requirements for reusable handpiece approvals, consolidating procurement among hospital systems with dedicated regulatory affairs functions. Basel-region manufacturers supply precision piezoelectric transducers to global ultrasonic platform producers.
Japan
PMDA medical device classifications extend review timelines for automated delivery systems with integrated suction, favoring established manufacturers with regulatory infrastructure. Tokyo and Osaka metropolitan dental clinics are standardizing on disposable tip configurations to mitigate cross-contamination liability. METI funding supports academic-industry collaboration on laser-induced cavitation technologies.
India
CDSCO medical device rules are harmonizing with international standards, enabling import substitution for premium ultrasonic platforms. Maharashtra and Karnataka dental college networks generate replacement demand for syringe irrigators across price-sensitive training institutions. Mumbai-based distributors are introducing pay-per-procedure financing to lower capital barriers for independent practitioners.
Root Canal Irrigators Market Vendor Landscape
On the supply side, the industry is consolidating around manufacturers with sufficient regulatory infrastructure to navigate EU MDR clinical evidence mandates and FDA 510(k) predicate pathway requirements. The competitive terrain separates into three archetypes: multinational dental conglomerates with global service networks, mid-cap specialists in closed-loop irrigation technologies, and disposable-focused manufacturers targeting cross-contamination liability mitigation. Dominant competitive moves include strategic partnerships for workflow integration and geographic expansion through distributor consolidation in high-growth Asian markets.
Within the multinational tier, Dentsply Sirona and Ultradent Products occupy positions anchored by established regulatory affairs functions and institutional customer relationships. Vista Dental Products exemplifies the disposable-specialist archetype, with its configuration focus reflecting procurement priorities among hospital systems managing multi-operator environments. These three entities represent the spectrum of strategic positioning from premium platform ecosystems to liability-mitigation consumables.
| Leading Market Players |
|---|
| Dentsply Sirona |
| Ultradent Products |
| Vista Dental Products |
| Zipperer |
| Roydent Dental Products |
| PD Dental |
| Pac-Dent International |
| Medesy |
| Septodont |
| Others |
Supply Flow & Price Mechanics
Precision-gauge stainless steel tubing production concentrates in German and Swiss manufacturing clusters, anchoring margin capture for ultrasonic handpiece producers while disposable polymer tip assemblers in East Asia compete on scale economics. This upstream concentration shapes downstream pricing power, with EU MDR-compliant manufacturers commanding premium positioning against non-certified alternatives.
Pricing Analysis
Certification level creates the primary spread between premium ultrasonic platforms and commodity syringe alternatives. Pricing stratifies across FDA-cleared automated systems, CE-marked reusable handpieces, and economy-grade manual configurations without quality management certification. Cost compression in the syringe tier intensifies because polymer cannula producers in India and China expand capacity. Hospital systems with centralized procurement functions demonstrate lowest price sensitivity, while independent Texas and Florida private practices drive substitution toward manual delivery.
Supply Chain Analysis
Tariff exposure between the United States and China dominates supply chain risk planning for disposable tip manufacturers. Piezoelectric transducer fabrication draws from Japanese and German component specialists, while polymer resin compounding rests on South Korean and Thai petrochemical networks. Single-source vulnerability concentrates in precision-gauge steel tubing from Baden-Württemberg mills. Distribution runs through Stuttgart-based dental equipment distributors serving Bavarian specialist networks, with Mumbai and São Paulo hubs covering emerging market access.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Hardware procurement cycles are lengthening while software update subscriptions and calibration service contracts expand at multiples of device shipment growth. This service-attach dynamic reorients vendor economics toward recurring revenue capture.
For Market Incumbents: Entrench installed-base loyalty by embedding closed-loop irrigation software that locks clinics into proprietary service protocols. Acquire disposable tip manufacturers in India to secure cost-competitive supply for price-sensitive market tiers. Dentsply Sirona's global service network exemplifies this defensive posture against emerging ultrasonic platform competitors.
For New Entrants and Emerging Players: Pursue white-space opportunity in photacoustic-activated delivery systems for complex retreatment cases, where academic validation precedes commercial adoption. Target Swiss and Japanese academic dental centers as reference sites before FDA submission. Lead with pay-per-procedure financing to bypass capital expenditure barriers among independent German practitioners.
For Investors and Strategic Acquirers: Capital is best deployed toward mid-cap specialists with established EU MDR technical documentation and ISO 13485 certification infrastructure. Five-to-ten-year viability hinges on regulatory compliance scalability rather than product innovation velocity alone. Monitor FDA 510(k) clearance velocity for ultrasonic platform iterations as inflection signal for competitive positioning shifts.
| Strategic Initiative | Industry Significance |
|---|---|
| CE Marking Pathway Investment | EU MDR technical documentation accelerates hospital system procurement in Germany and Switzerland. |
| Hospital System Partnership | Cleveland Clinic and Mayo Clinic pilots validate closed-loop irrigation for multi-site standardization. |
| Software Companion Development | Real-time pressure feedback applications differentiate automated platforms from manual alternatives. |
| Reimbursement Strategy Alignment | German statutory health insurance outcome documentation requirements favor precision-control adoption. |
| Disposable Tip Manufacturing Scale-Up | East Asian polymer assembly capacity addresses cross-contamination liability concerns in hospital systems. |
Methodological Framework
A standing panel of endodontic specialists, hospital purchasing committee chairs, biomedical engineers, and GPO contracts managers provided ongoing calibration against operating reality. Primary fieldwork combined structured interviews with secondary validation through FDA 510(k) filings, EU MDR technical documentation databases, hospital procurement records, and German statutory health insurance reimbursement schedules. Bottom-up shipment modeling and top-down expenditure triangulation anchored volume and value estimates.
Scenario bracketing around EU MDR compliance timelines and FDA clearance velocity shaped projection boundaries across the analysis window. Segmentation modeling incorporated product type, delivery mode, end user, and application dimensions alongside regional regulatory cluster differentiation. CAGRs derived from procedure volume growth, replacement cycle compression, and premium system penetration curves. Photacoustic technology adoption rates and pay-per-procedure financing uptake served as industry-specific forecast inputs.
Sensitivities concentrate around EU MDR audit preparation delays, stainless steel input price volatility, and outcome-based dental contract reimbursement shifts. Forecasts reflect documented assumptions regarding specialist density growth and automated platform workflow integration rates. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
India Static Compression Therapy Market
Medical Devices
Global Anti-Snoring Device Market
Medical Devices
US Contact Lenses Market
Medical Devices
Global Neurovascular Thrombectomy Devices Market
Medical Devices
Global Breast Pumps Market
Medical Devices
Complementary Therapy Devices Market
Medical Devices
Global Disability Devices Market
Medical Devices
Mexico Ultrasound Devices Market
Medical Devices
Retinal Implant Market
Medical Devices
Steam Inhaler Devices Market
Medical Devices
Global Live Cell Encapsulation Market
Medical Devices
ECG Patch and Holter Monitor Market
Medical Devices
Hearing Devices 3D Printing Market
Medical Devices
Global Neurovascular Guidewires Market
Medical Devices
Orthodontic Headgear Market
Medical Devices
Reusable Laparoscopic Instrument Market