
 Hearing Devices 3D Printing Market | 2026-2036
Hearing Devices 3D Printing Market Size, Share, and Industry Trends Forecast 2026-2036
Hearing Devices 3D Printing Market Foresight
Aftermarket service revenue is fragmenting across hearing device 3D printing ecosystems as original equipment manufacturers internalize repair, recalibration, and material replenishment workflows. Formlabs leverages its desktop resin platform to dominate audiology clinic deployments in North America. Materialise sustains centralized production hubs that process digital ear impressions for distributed clinic networks. EOS GmbH anchors industrial-grade selective laser sintering capacity for titanium cochlear implant components.
Hearing devices 3D printing encompasses additive fabrication of patient-matched shells, earmolds, and implant housings using biocompatible photopolymers and metal powders with layer resolutions below 50 microns, primarily to eliminate manual molding latency and acoustic leakage in fitted hearing instruments. Stereolithography and digital light processing lead production volume for custom earmolds due to surface finish requirements and build speed, while selective laser sintering captures premium margin pools in titanium cochlear implant chassis where fatigue resistance governs device longevity. Plastic materials occupy the largest consumption share across hearing aid shells, yet biomaterials represent the fastest-growing category as osseointegrative coatings advance implant fixation performance.
FDA 510(k) pathways govern market access for 3D-printed hearing aids and implantable components in the United States, while EMA MDR conformity assessments shape commercialization timelines for European manufacturers. ISO 10993 biocompatibility testing and IEC 62304 software lifecycle standards constrain material selection and digital workflow validation across all regulated jurisdictions. Stakeholders must monitor evolving FDA guidance on point-of-care additive manufacturing as clinic-based production erodes traditional centralized fabrication economics.
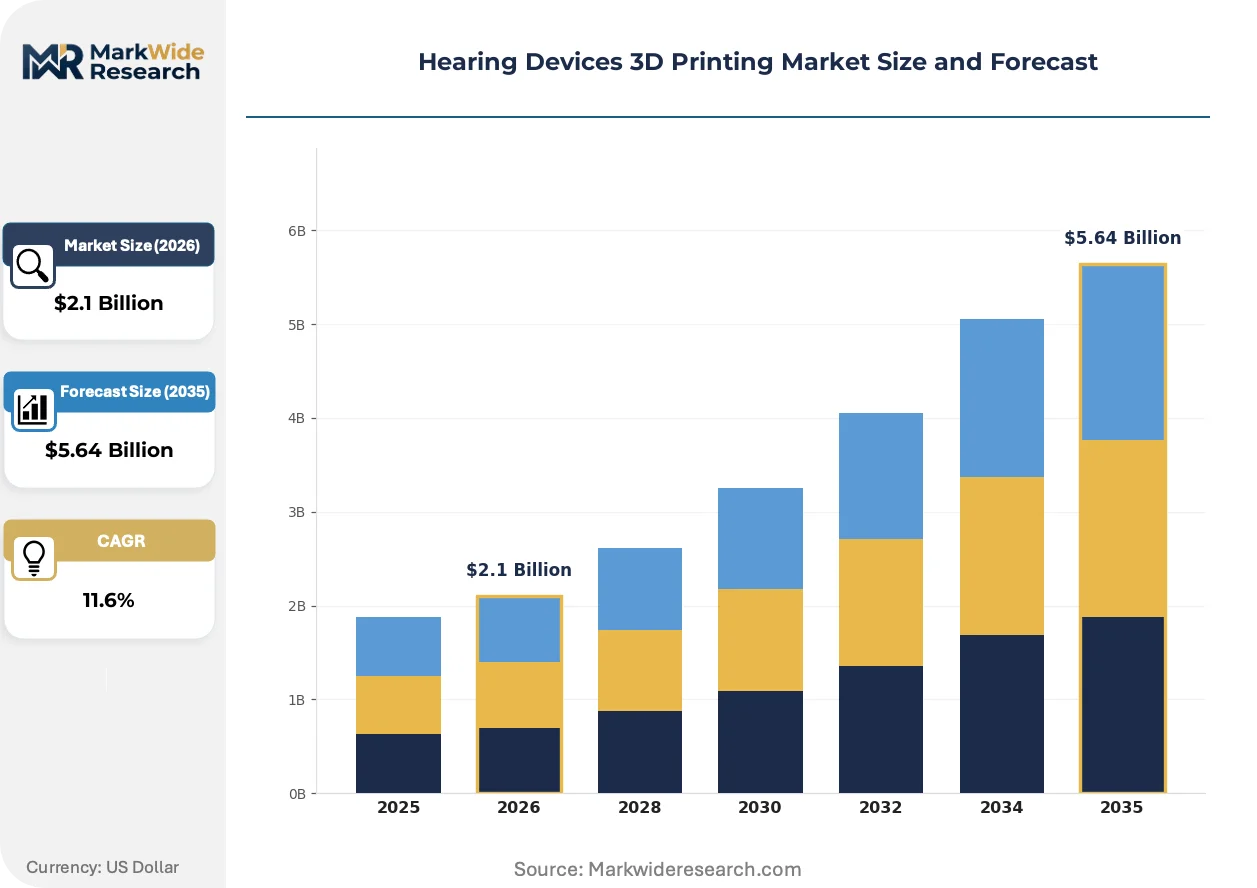
Market Dynamics
Patient-specific shell production is consolidating fabrication workflows into audiology clinics, compressing traditional centralized manufacturing economics while FDA point-of-care additive manufacturing guidance accelerates decentralized deployment.
Growth Catalysts
- ISO 10993 biocompatibility frameworks:Standardized material validation protocols reduce regulatory friction for photopolymer earmold commercialization across multiple jurisdictions.
- Titanium cochlear implant chassis:Selective laser sintering fatigue resistance specifications extend device longevity, capturing premium reimbursement pools in implantable hearing systems.
- Germany:EOS GmbH and Rapid Shape GmbH anchor precision polymer and metal printing infrastructure, concentrating industrial-grade capacity for European audiology supply chains.
Market Restraints
- Biocompatible photopolymer input costs:Medical-grade resin formulations command 3-5x commodity polymer pricing, constraining margin expansion for high-volume earmold producers.
- Selective laser sintering equipment concentration:Industrial metal powder bed systems require capital commitments exceeding $500,000 per unit, limiting clinic-level adoption to institutional purchasers.
- IEC 62304 software lifecycle compliance:Digital workflow validation for patient-matched shell design tools extends development timelines by 12-18 months for new market entrants.
Strategic Opportunities
- Osseointegrative coating convergence:Biomaterial surface engineering advances implant fixation performance, opening premium pricing tiers for bone-anchored hearing systems.
- EMA MDR conformity acceleration:Streamlined technical documentation pathways for patient-matched devices reduce European commercialization timelines relative to legacy manual molding approvals.
- Digital ear impression networks:Distributed scanning infrastructure enables same-day shell production workflows, displacing centralized laboratory shipping logistics.
Industry Challenges
- Additive manufacturing technician certification:Clinic-based production requires cross-trained audiology staff capable of operating resin printers and post-processing equipment.
- Legacy enterprise resource planning integration:Patient-specific manufacturing workflows demand API connectivity between 3D printing management software and established hearing aid dispensing platforms.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Hearing Devices 3D Printing Market |
| Market Size in 2026 | $2.1 Billion |
| Market Size in 2035 | $5.64 Billion |
| CAGR (2026 – 2036) | 11.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Hearing Aids, Ear Molds, Cochlear Implants, Assistive Listening Devices Technology: Stereolithography, Fused Deposition Modeling, Selective Laser Sintering, Digital Light Processing End User: Hospitals, Audiology Clinics, Home Care Providers, Rehabilitation Centers Material Type: Plastic, Biomaterials, Metals, Composites |
| Companies Covered | Formlabs, Desktop Metal, Sonova Holding AG, EOS GmbH, Rapid Shape GmbH, 3D Systems, Materialise, B9Creations LLC, Asiga, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Hearing Devices 3D Printing Market Shifts & Advancements
Distributed production architectures are displacing centralized laboratory models, while regulatory frameworks evolve to accommodate point-of-care manufacturing without compromising patient safety validation.
Digital light processing technology is digitizing custom earmold fabrication by enabling 50-micron layer resolution at production speeds exceeding stereolithography systems. Audiology clinics across North America and Western Europe are deploying desktop resin platforms for same-day shell delivery. This capability is digitizing patient throughput economics by eliminating multi-day shipping cycles and reducing remanufacture rates from impression distortion.
FDA guidance on point-of-care additive manufacturing is clarifying quality system requirements for clinic-based hearing device production. The framework distinguishes between distributed manufacturing networks and captive production facilities, imposing differentiated validation protocols. Hearing aid manufacturers with established centralized operations face strategic decisions regarding facility licensing versus third-party clinic certification programs.
After-sales service unbundling is fragmenting revenue streams across hearing device ecosystems. Original equipment manufacturers are internalizing repair, recalibration, and material replenishment workflows that previously supported independent service providers. This concentration is most visible in Germany and the United States, where vertically integrated audiology chains capture recurring revenue from 3D-printed component replacement programs.
Hearing Devices 3D Printing Market Segmentation
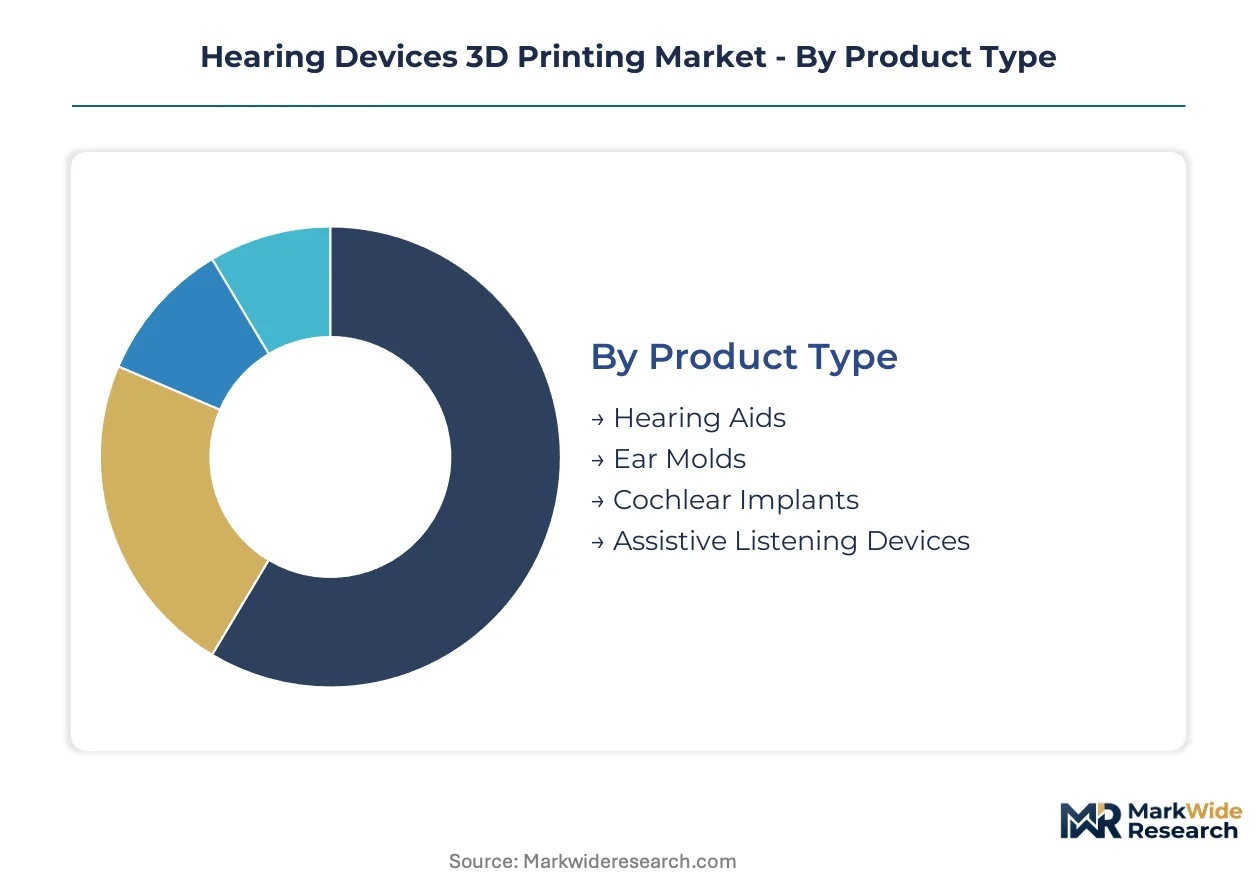
Hearing devices 3D printing segmentation reveals divergent production economics across patient-matched shells, implantable hardware, and assistive peripherals. Material compatibility with biocompatibility standards and layer resolution requirements drive technology selection more than unit cost alone.
Product Type:
Mature hearing aid shells dominate current fabrication volume while emerging implant categories reshape margin structures.
- Hearing Aids:Patient-specific shell geometries achieve sub-50-micron tolerances through photopolymer vat polymerization, eliminating acoustic leakage paths common to manual molding. Demand concentrates in German and US audiology chains pursuing same-day fitting workflows to compress patient acquisition costs.
- Cochlear Implants:Titanium chassis fabrication via selective laser sintering delivers fatigue resistance specifications exceeding cast or machined alternatives, extending device longevity under cyclic loading. Japanese and Korean otologic surgery centers drive specification tightening for osseointegrative surface finishes.
- Ear Molds:Soft silicone and acrylic variants serve musician monitors and swim protection applications with shorter regulatory pathways than therapeutic devices.
- Assistive Listening Devices:Personal amplification hardware for theater and lecture environments utilizes standardized geometries with lower customization depth than prescription hearing instruments.
Hearing Aids retains volume leadership; Cochlear Implants holds the steepest expansion curve.
Technology:
Cost tier stratification separates clinic-deployable desktop systems from capital-intensive industrial metal platforms.
- Digital Light Processing:Mask-based photopolymer curing achieves production speeds exceeding point-source stereolithography while maintaining equivalent surface finish quality for earmold applications. North American audiology clinics favor this technology for same-day shell delivery economics.
- Selective Laser Sintering:Powder bed fusion of titanium and cobalt-chrome alloys produces cochlear implant housings with isotropic mechanical properties and complex internal channel geometries impossible through subtractive methods. German industrial printing infrastructure anchors European supply security for these components.
- Stereolithography:Laser-drawn photopolymer systems retain installed base advantages in centralized laboratory environments with established validation protocols.
- Fused Deposition Modeling:Thermoplastic extrusion serves prototyping and educational applications where biocompatibility certification is not required.
Selective Laser Sintering commands premium pricing tiers; Digital Light Processing is gaining share fastest among clinic-level deployments.
End User:
Customer type fragmentation reflects divergent procurement authority and patient throughput models across care settings.
- Audiology Clinics:Independent and chain-affiliated dispensing practices are internalizing shell production through desktop resin platforms, displacing centralized laboratory relationships. German and US markets lead this transition with established technician certification pathways.
- Hospitals:Academic medical centers and otologic surgery departments coordinate implantable device production with sterile processing requirements and surgical scheduling logistics.
- Rehabilitation Centers:Post-surgical fitting and adjustment services require rapid remanufacture capabilities for device replacement and modification.
- Home Care Providers:Remote patient monitoring and mail-order impression services create distributed production nodes without clinical infrastructure investment.
Audiology Clinics anchor decentralized production adoption; Hospitals maintain concentrated demand for implant-grade metal fabrication.
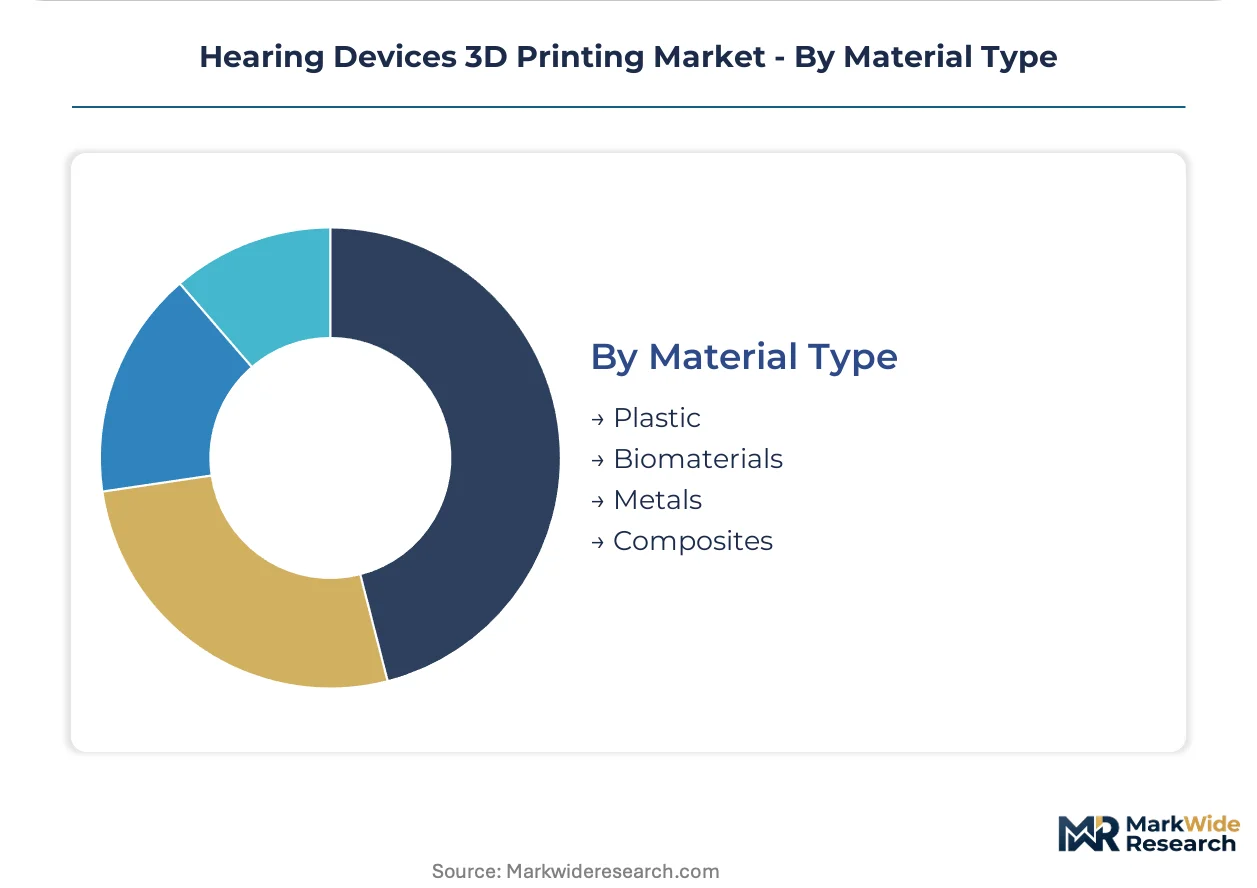
Material Type:
Application requirements dictate material selection across acoustic performance, biocompatibility, and mechanical load-bearing specifications.
- Biomaterials:Osseointegrative coatings and resorbable scaffolds for bone-anchored hearing systems represent the most rapidly advancing material category, with surface engineering protocols migrating from dental implant science. Japanese research institutes and German chemical suppliers co-develop these formulations.
- Metals:Titanium Grade 23 and cobalt-chrome alloys satisfy fatigue and corrosion resistance requirements for permanent implantation, processed exclusively through powder bed fusion given density and surface quality demands.
- Plastic:Medical-grade photopolymers and thermoplastics occupy the largest consumption share for non-implantable shells and earmolds.
- Composites:Ceramic-filled polymers and fiber-reinforced matrices serve niche applications requiring acoustic damping combined with structural rigidity.
Plastic maintains current volume dominance; Biomaterials is climbing the fastest as implant fixation performance becomes a competitive differentiator.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Price sensitivity varies sharply across geographies, with European audiology chains absorbing premium resin costs while Asian clinics prioritize equipment depreciation economics. Germany and the United States demonstrate the lowest demand elasticity for patient-matched shells. Emerging markets in Asia-Pacific exhibit higher substitution risk toward centralized laboratory services.
United States
FDA 510(k) clearance pathways for point-of-care additive manufacturing are accelerating clinic-level deployments across independent audiology practices. The agency's draft guidance on distributed manufacturing networks distinguishes captive production from third-party certification, reshaping compliance investments. Boston and Minneapolis medical device clusters host validation laboratories supporting decentralized shell production workflows.
Germany
EMA MDR conformity assessments for patient-matched devices are streamlining technical documentation relative to legacy manual molding approvals. EOS GmbH and Rapid Shape GmbH anchor industrial-grade selective laser sintering capacity in Krailling and Heimsheim, supplying titanium cochlear implant components across European otologic surgery centers. Bavaria's precision polymer printing infrastructure concentrates supply security for audiology applications.
Japan
PMDA marketing authorization timelines for 3D-printed implantable hearing systems are tightening fatigue resistance specifications for titanium chassis. Tokyo and Osaka academic medical centers drive osseointegrative surface finish requirements, migrating dental implant engineering protocols to bone-anchored hearing devices. METI subsidizes biocompatibility testing infrastructure for domestic material suppliers.
China
NMPA medical device registration pathways for customized hearing aid shells are expanding domestic photopolymer resin validation requirements. Yangtze River Delta manufacturing hubs in Shanghai and Suzhou are integrating digital ear impression scanning with same-day shell production for private audiology chains. Provincial health commissions are piloting clinic-based additive manufacturing licensing frameworks.
South Korea
MFDS regulatory science programs for patient-matched otologic devices are accelerating software lifecycle validation for shell design tools. Seoul Capital Area otologic surgery centers specify selective laser sintering density requirements for cochlear implant housings that exceed international standards. Daegu-Gyeongbuk medical device clusters are developing post-processing automation for titanium powder bed fusion components.
Hearing Devices 3D Printing Market Competitive Landscape
Capability concentration sits with industrial metal powder bed specialists; scale advantage sits with desktop resin platform deployers. The vendor base stratifies across three tiers: capital-intensive selective laser sintering infrastructure owners, clinic-deployable photopolymer system providers, and centralized digital manufacturing service operators. Strategic moves center on technician certification program expansion and API integration with hearing aid dispensing software platforms.
Among German precision printing specialists, EOS GmbH and Rapid Shape GmbH exemplify the industrial-grade infrastructure tier, anchoring European supply security for titanium cochlear implant components and photopolymer earmold applications. Formlabs represents the clinic-deployable platform vector, with its desktop resin systems dominating North American audiology practice deployments.
| Leading Market Players |
|---|
| Formlabs |
| Desktop Metal |
| Sonova Holding AG |
| EOS GmbH |
| Rapid Shape GmbH |
| 3D Systems |
| Materialise |
| B9Creations LLC |
| Asiga |
| Others |
Supply & Pricing Matrix
Krailling and Heimsheim anchor European titanium powder bed capacity, concentrating supply security for cochlear implant chassis while enabling premium pricing tiers for fatigue-resistant components. German precision polymer infrastructure simultaneously supports photopolymer earmold production, creating divergent cost structures across implant-grade metal and clinic-deployable resin workflows.
Pricing Analysis
After-sales service contracts and material replenishment programs drive lifetime value capture, with original equipment manufacturers internalizing repair and recalibration workflows previously served by independent providers. Pricing stratifies across premium titanium implant chassis, standard photopolymer earmolds, and economy-tier assistive listening devices, with certification grade and volume scale as primary differentiation levers. Cost compression in high-volume earmold production is intensifying as biocompatible resin formulations command significant premiums over commodity polymers. Independent audiology clinics exhibit highest price sensitivity, while hospital otologic surgery departments demonstrate lowest elasticity for implant-grade components.
Supply Chain Analysis
Biocompatible photopolymer resin formulations and titanium Grade 23 powder feedstock concentration in Germany, the United States, and Japan creates upstream dependencies for precision audiology manufacturing. Medical-grade resin supply draws from specialty chemical suppliers in Bavaria and Massachusetts, while titanium powder production rests on plasma atomization capacity concentrated in Pennsylvania and Osaka. Single-source vulnerability in certified resin formulations poses structural risk for clinic-level producers dependent on ISO 10993-validated material lots. Distribution runs through vertically integrated audiology chains and hospital procurement systems, with digital ear impression networks enabling direct clinic-to-patient fulfillment.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Cross-trained technician pools capable of operating resin printers while managing digital workflow validation represent the critical capability gap constraining decentralized production expansion. Firms that secure certified workforce pipelines and API-integrated software ecosystems will capture disproportionate share of clinic-level deployment economics.
For Market Incumbents: Build regulatory certification moats by accelerating FDA 510(k) pathway expertise and EMA MDR technical documentation capabilities ahead of point-of-care manufacturing guidance finalization. Internalize biomaterial surface engineering competencies for osseointegrative coatings to defend against implant-grade competitors from dental implant science migration. Expand technician certification programs in North American and Western European audiology chains to preempt channel displacement by desktop resin platform deployers.
For New Entrants and Emerging Players: Build out digital ear impression network infrastructure in Asia-Pacific markets where centralized laboratory services retain cost advantages over clinic-level equipment depreciation. Target rehabilitation centers and home care providers as the most penetrable end-user segment, exploiting rapid remanufacture requirements and remote patient monitoring workflows. Pursue white-label resin formulation partnerships with established German chemical suppliers to bypass biocompatibility validation timelines.
For Investors and Strategic Acquirers: Mid-cycle technology positioning favors clinic-deployable photopolymer platform specialists with established API integrations over capital-intensive selective laser sintering infrastructure owners facing equipment concentration limits. Long-term viability across the projection horizon hinges on software lifecycle validation capabilities and point-of-care regulatory pathway navigation. Acquisition focus should center on digital workflow management platforms with hearing aid dispensing software connectivity. Monitor FDA draft guidance finalization on distributed manufacturing networks as the key inflection signal for decentralized production economics.
| Strategic Initiative | Industry Significance |
|---|---|
| Technician Certification Program Expansion | Cross-trained audiology staff enable clinic-based production workflows, displacing centralized laboratory relationships. |
| API Integration with Dispensing Platforms | Patient-specific manufacturing workflows demand connectivity between 3D printing management software and established hearing aid systems. |
| Biomaterial Surface Engineering Investment | Osseointegrative coating capabilities capture premium pricing tiers for bone-anchored hearing systems. |
| Point-of-Care Regulatory Pathway Navigation | FDA guidance on distributed manufacturing networks reshapes compliance investments for decentralized deployment. |
| Digital Ear Impression Network Buildout | Distributed scanning infrastructure enables same-day shell production, eliminating multi-day shipping cycles. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of FDA 510(k) filings, EMA MDR submission databases, and ISO 10993 biocompatibility test reports. Primary interviews engaged biomedical engineers at academic medical centers, procurement managers at audiology clinic chains, and regulatory affairs leads at hearing device manufacturers. Secondary validation incorporated customs trade data for titanium powder and photopolymer resin shipments, SEC filings from listed medical device companies, and hospital procurement database extracts. Bottom-up demand modeling triangulated against top-down market sizing across technology, material, and end-user segmentation dimensions.
Forecast inputs include patient throughput economics at audiology clinics, reimbursement rate trajectories for implantable hearing systems, and equipment depreciation schedules for desktop resin platforms. The analytical framework models product type, technology, end user, and material type segments across the analysis window. CAGRs derive from installed base projections for selective laser sintering and digital light processing systems, layered with material consumption intensity assumptions per device category. Industry-specific inputs encompass FDA point-of-care manufacturing guidance implementation timelines and EMA MDR conformity assessment acceleration patterns.
Practitioners should monitor FDA guidance finalization, biomaterial coating patent filings, and audiology chain consolidation announcements for early signals of forecast revision. Cross-checking against CMS Medicare reimbursement data and private payer coverage policy updates is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Airotar Handpiece Market
Medical Devices
North America Medical Device Regulatory Affairs Outsourcing Market
Medical Devices
Enteral Feeding Devices Market
Medical Devices
Injection Practice Pad Market
Medical Devices
Pressure Ulcer Detection Devices Market
Medical Devices
Spain Diabetes Devices Market
Medical Devices
Europe Nurse Call Systems Market
Medical Devices
US Surgical Microscopes Market
Medical Devices
Global Portable Ultrasound Equipment Market
Medical Devices
Sleep Apnea Devices Market
Medical Devices
Cryoablation System Market
Medical Devices
Removable Partial Dentures Market
Medical Devices
US Medical Display Monitors Market
Medical Devices
Hearing Aid with Lithium-Ion Battery Market
Medical Devices
Functional Electrical Stimulation Market
Medical Devices
Medical Bionic Implants and Exoskeletons Market