
 Global Disability Devices Market | 2026-2036
Global Disability Devices Market Size, Share, and Industry Trends Forecast 2026-2036
Global Disability Devices Market Foresight
Remote monitoring subscriptions for powered wheelchairs and hearing aid companion apps is realigning vendor revenue models toward recurring service streams. Ottobock leverages its clinical engineering heritage to sustain premium positioning in microprocessor-controlled prosthetics. Cochlear Limited anchors its competitive edge through direct-to-implant surgeon training networks. Sunrise Medical differentiates via configurable seating systems that span pediatric through bariatric applications.
Disability devices encompass electromechanical and sensory augmentation equipment engineered to restore or substitute impaired motor, auditory, or visual function, typically incorporating biocompatible materials, rechargeable power systems, and programmable control firmware with ISO 13485 quality certification. Hearing aids and prosthetics command concentrated margin pools due to custom fitting protocols and specialist channel requirements. Mobility scooters occupy a mature volume tier where electronic control modules are displacing manual throttle mechanisms. Bluetooth-enabled and sensor-based technologies are gaining fastest across home care and elderly care facility deployments.
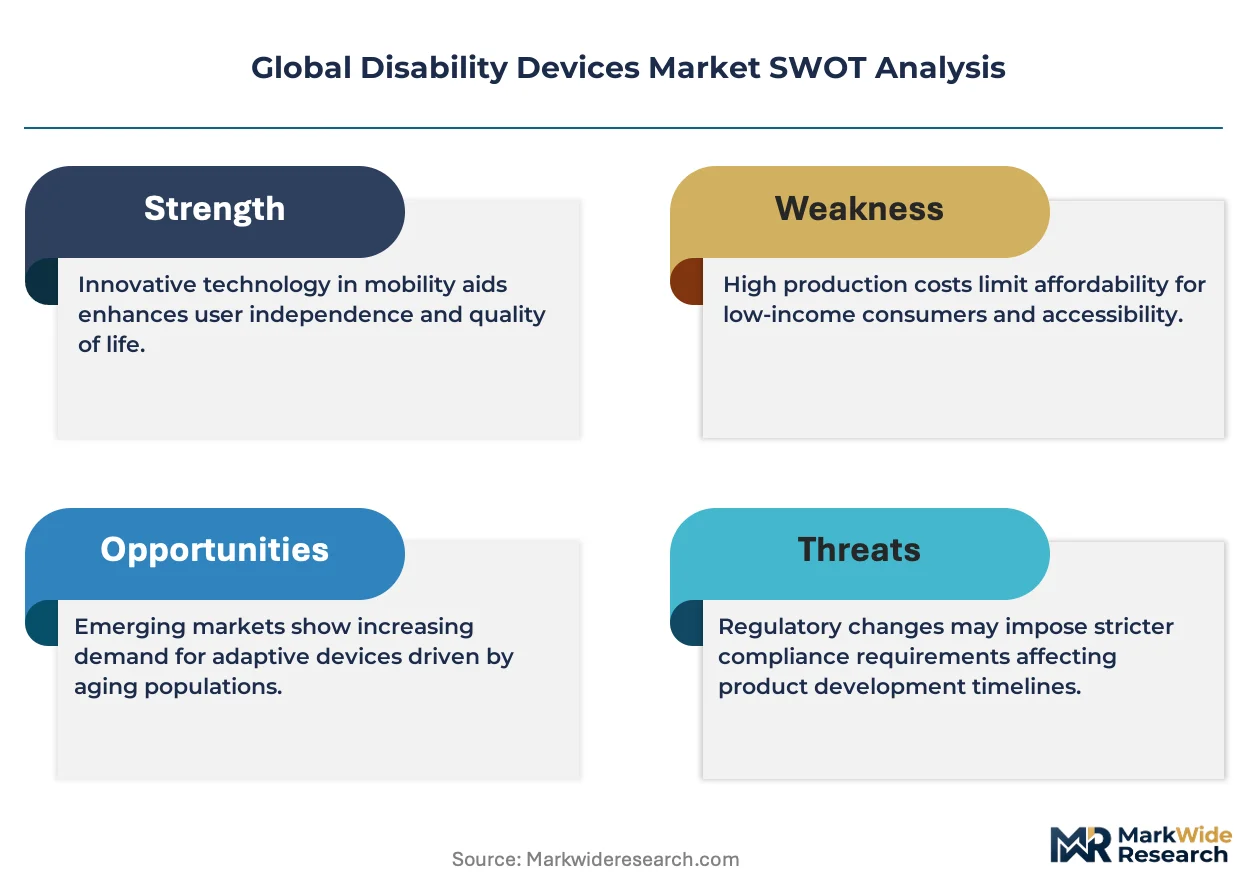
The FDA's 510(k) premarket notification and the EU Medical Device Regulation (MDR) impose clinical evidence and post-market surveillance obligations that filter lower-capability suppliers from transatlantic access. Japan's PMDA and Australia's TGA maintain aligned but distinct essential principles for active implantable devices, adding compliance layers for hearing and neural prosthesis manufacturers. Stakeholders must monitor how WHO assistive technology priority lists and national reimbursement catalog revisions reshape procurement eligibility across publicly funded channels.
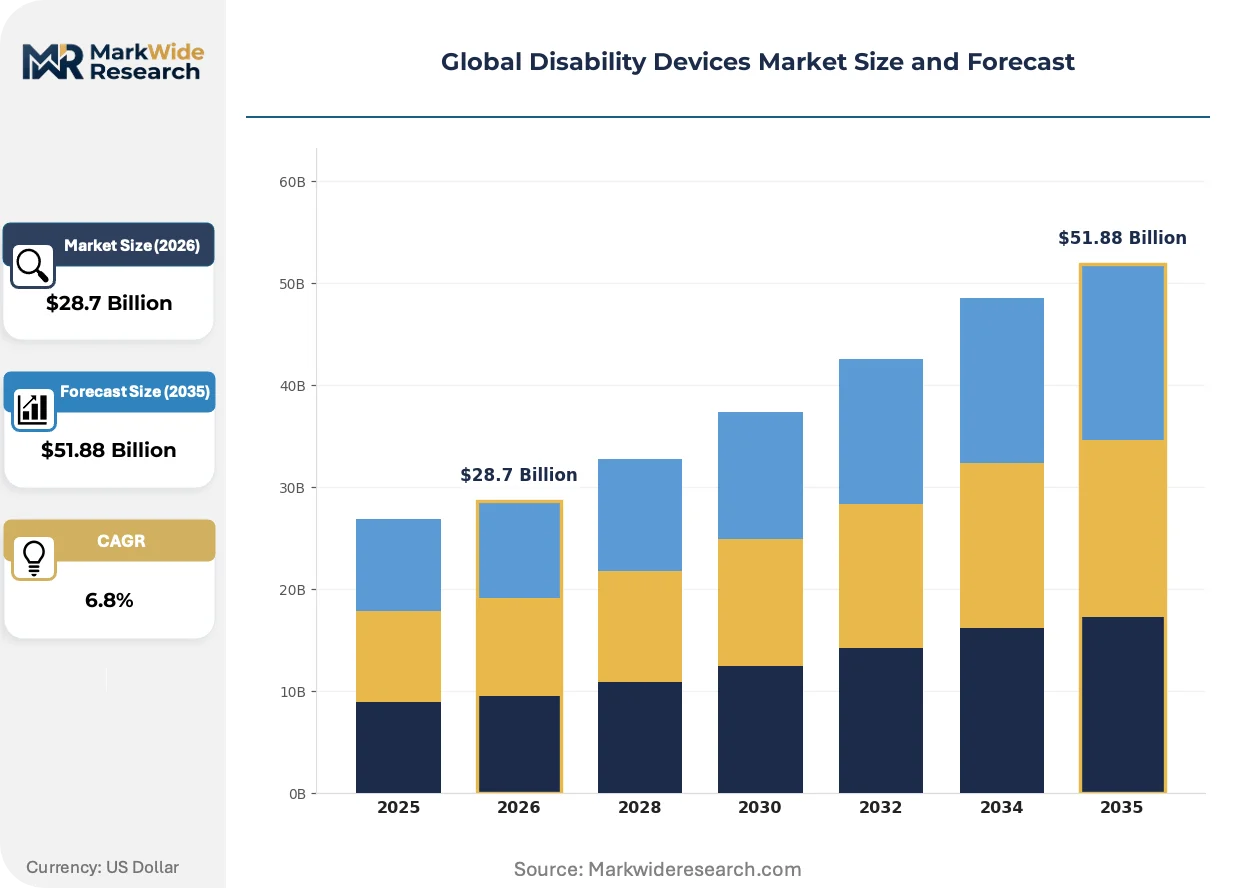
Market Dynamics
Sensor-based mobility equipment is absorbing capital flows as home care agencies retrofit fleets for remote patient monitoring, compressing replacement cycles and forcing firmware-over-air competency into vendor core capabilities.
Growth Catalysts
- FDA 510(k) pathway maturation:Streamlined premarket notification for moderate-risk devices accelerates electromechanical prosthetics entry, particularly for microprocessor-controlled knee systems targeting rehabilitation centers.
- Bluetooth Low Energy integration:Hearing aid companion apps now capture real-time usage analytics, creating stickier patient-clinician relationships and reducing return-for-credit rates in audiology practices.
- Germany's rehabilitation infrastructure density:Deep clinical partnerships between device manufacturers and statutory health insurance funds sustain premium positioning for configurable seating systems across pediatric through bariatric applications.
Market Restraints
- Lithium-ion cell supply concentration:Rechargeable power systems for powered wheelchairs face input cost volatility from Southeast Asian cathode material processing bottlenecks.
- EU MDR clinical evidence requirements:Post-market surveillance obligations filter lower-capability suppliers from transatlantic access, raising compliance burn rates for active implantable device portfolios.
- Manual throttle mechanism displacement friction:Electronic control module retrofits in mature mobility scooter fleets encounter technician certification gaps in rural home care networks.
Strategic Opportunities
- Japan's super-aging prefectures:PMDA-aligned essential principles for sensor-based fall detection create procurement eligibility for ISO 13485-certified mobility aids in publicly funded elderly care facilities.
- Neural prosthesis-audiology convergence:Direct-to-implant surgeon training networks expand addressable market beyond conventional hearing aid candidacy into cochlear osseointegration protocols.
- WHO assistive technology priority lists:National reimbursement catalog revisions in emerging markets reshape procurement eligibility for basic mobility devices through Gavi-aligned purchasing consortia.
Industry Challenges
- ISO 13485 quality certification talent scarcity:Biocompatibility testing and programmable control firmware validation functions face recruitment gaps as medical device software complexity outpaces regulatory affairs training pipelines.
- Legacy analog hearing aid inventory obsolescence:Distributor networks struggle with channel reconfiguration friction as Bluetooth-enabled models capture margin from programmable digital predecessors.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Disability Devices Market |
| Market Size in 2026 | $28.7 Billion |
| Market Size in 2035 | $51.88 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Wheelchairs, Hearing Aids, Visual Aids, Prosthetics, Mobility Scooters Application: Mobility Assistance, Hearing Impairment, Visual Impairment, Speech Therapy, Daily Living Support End User: Rehabilitation Centers, Elderly Care Facilities, Home Care, Special Schools, Occupational Therapists Technology: Bluetooth Enabled, Voice Activated, Sensor Based, Electronic Control, Manual Operation |
| Companies Covered | Invacare Corporation, Sunrise Medical, Ottobock, Cochlear Limited, Sonova Holding AG, Medtronic plc, GF Health Products, Pride Mobility Products Corp., Permobil, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Disability Devices Market Shifts & Advancements
Electromechanical control architectures are converging with consumer electronics supply chains, compressing development timelines while introducing cybersecurity and interoperability requirements foreign to traditional prosthetics engineering cultures.
Machine learning inference at the edge is absorbing into microprocessor-controlled prosthetic knees, enabling terrain-adaptive damping without cloud latency. Veterans Affairs procurement channels in the United States are piloting these systems for above-knee amputee gait normalization. The technology is absorbing rehabilitation center expectations for real-time performance telemetry into standard product specifications.
EU Medical Device Regulation post-market clinical follow-up requirements are extending surveillance obligations to legacy implantable hearing devices already in situ. Manufacturers must now maintain clinical evidence generation infrastructure across product lifecycles exceeding fifteen years. Cochlear implant portfolios face the steepest compliance cost escalation due to their active implantable classification and direct neural interface risk profiles.
Home care agencies are consolidating vendor relationships around sensor-based equipment providers offering predictive maintenance subscriptions. Traditional durable medical equipment distributors lose share to direct-manufacturer service contracts bundling hardware, connectivity, and remote monitoring. This concentration is most visible in Germany's statutory long-term care insurance-funded sector, where procurement centralization at the Land level favors scaled platform vendors.
Global Disability Devices Market Segmentation
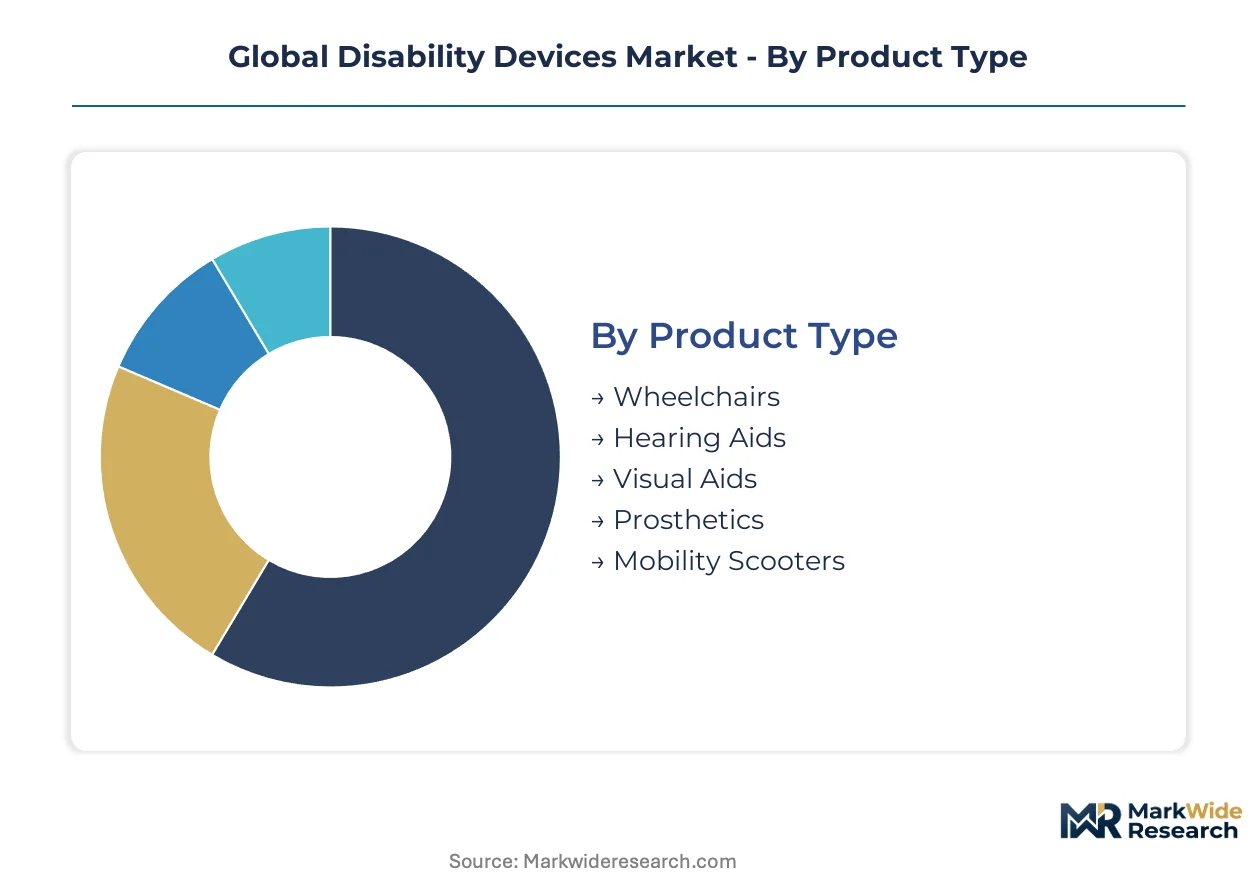
Segmentation in disability devices reveals distinct margin architectures. Product categories separate premium custom-fitted prosthetics from volume-driven mobility hardware, while technology tiers isolate firmware-dependent systems from mechanical legacy equipment.
Product Type:
Standalone mobility systems dominate procurement volumes, whereas embedded microprocessor architectures concentrate in rehabilitation workflows requiring programmable gait modulation.
- Wheelchairs:Powered variants incorporate lithium-ion rechargeable systems and programmable joystick firmware with ISO 13485 validation. Demand clusters in German statutory long-term care insurance channels where remote monitoring subscriptions are displacing outright purchase models.
- Hearing Aids:Behind-the-ear and in-canal configurations integrate Bluetooth Low Energy for companion app telemetry. Audiologist practices in Japan's super-aging prefectures are absorbing these as standard fittings under PMDA-aligned reimbursement protocols.
- Visual Aids:Electronic magnifiers and screen readers serve low-vision populations through occupational therapist channels.
- Prosthetics:Microprocessor-controlled knee and ankle systems command premium positioning via specialist prosthetist networks.
- Mobility Scooters:Electronic throttle modules are displacing manual mechanisms in elderly care facility fleets.
Volume placements concentrate in Wheelchairs; the faster expansion belongs to Hearing Aids.
Application:
Cost tier stratification separates acute rehabilitation reimbursement codes from chronic maintenance categories, with mobility assistance absorbing the largest public procurement budgets.
- Mobility Assistance:Sensor-based fall detection and terrain-adaptive damping absorb Veterans Affairs pilot budgets in the United States.
- Hearing Impairment:Cochlear osseointegration protocols are expanding addressable market beyond conventional aid candidacy through direct-to-surgeon training networks.
- Visual Impairment:Wearable camera systems and haptic navigation aids serve degenerative retinal conditions.
- Speech Therapy:Augmentative communication devices support post-stroke recovery in rehabilitation centers.
- Daily Living Support:Adaptive utensils and environmental control units enable independent home care.
Public reimbursement concentrates in Mobility Assistance; climbing the fastest is Hearing Impairment.
End User:
Customer type determines channel configuration, with institutional buyers demanding predictive maintenance subscriptions while individual purchasers prioritize configurability.
- Rehabilitation Centers:German clinical partnerships with device manufacturers sustain premium positioning for configurable seating spanning pediatric through bariatric applications.
- Elderly Care Facilities:Japan's prefecture-level procurement centralization favors scaled platform vendors offering sensor-based equipment with firmware-over-air capability.
- Home Care:Remote patient monitoring retrofits are compressing replacement cycles for powered wheelchair fleets.
- Special Schools:Pediatric seating systems require growth-adjustable frame architectures.
- Occupational Therapists:Daily living aids move through distributor networks facing channel reconfiguration friction from Bluetooth-enabled inventory.
Procurement volume concentrates in Rehabilitation Centers; gaining share fastest is Elderly Care Facilities.
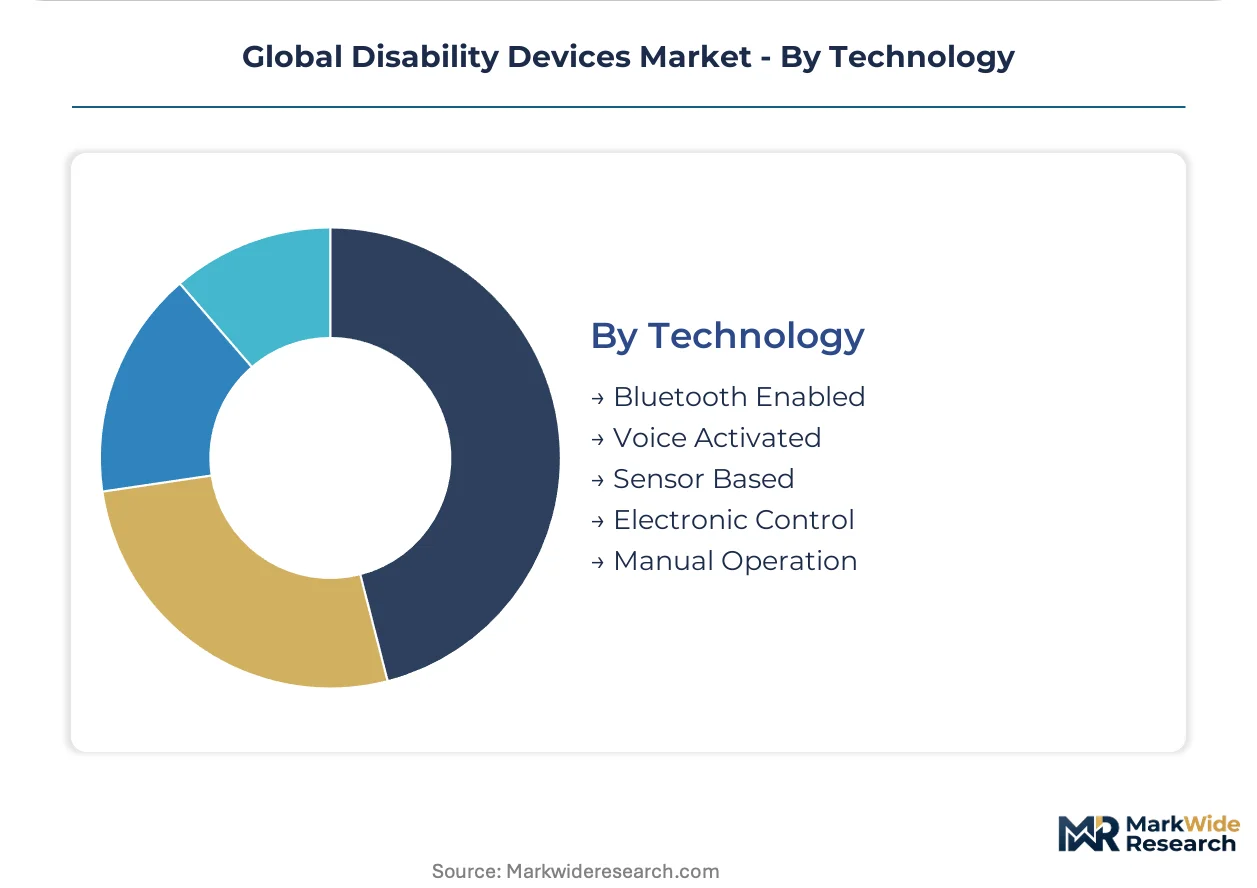
Technology:
Maturity curves separate established electronic control modules from emerging edge-inference architectures, with connectivity features commanding subscription revenue attachments.
- Bluetooth Enabled:Hearing aid companion apps capture real-time usage analytics, reducing return-for-credit rates in audiology practices.
- Voice Activated:Environmental control systems serve tetraplegic users through speech recognition firmware.
- Sensor Based:Predictive maintenance subscriptions are consolidating vendor relationships among home care agencies retrofitting fleets.
- Electronic Control:Microprocessor-driven prosthetic knees enable terrain-adaptive damping without cloud latency.
- Manual Operation:Legacy throttle mechanisms face technician certification gaps in rural networks.
Installed base concentrates in Electronic Control; steepest expansion trajectory belongs to Sensor Based.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Manufacturing clusters concentrate in Germany and the United States, while consumption spreads across aging populations in Japan and rehabilitation infrastructure in Australia. Supply chains bridge these geographies through ISO 13485-certified component networks.
United States
Veterans Affairs procurement channels pilot terrain-adaptive prosthetic knees for above-knee amputee gait normalization. FDA 510(k) premarket notifications streamline moderate-risk electromechanical device entry. Boston and Minneapolis rehabilitation centers absorb real-time performance telemetry into standard specifications.
Germany
Statutory long-term care insurance funds centralize procurement at the Land level, favoring scaled platform vendors. EU Medical Device Regulation post-market surveillance obligations filter lower-capability suppliers from transatlantic access. Ottobock maintains clinical engineering partnerships with rehabilitation centers across North Rhine-Westphalia and Bavaria.
Japan
PMDA-aligned essential principles for sensor-based fall detection create procurement eligibility in super-aging prefectures. Prefecture-level procurement centralization favors vendors offering firmware-over-air capability. Tokyo and Osaka elderly care facilities retrofit fleets with predictive maintenance subscriptions.
Australia
TGA essential principles for active implantable devices add compliance layers for hearing and neural prosthesis manufacturers. National Disability Insurance Scheme revisions reshape procurement eligibility for basic mobility devices. Sydney and Melbourne rehabilitation networks consolidate vendor relationships around direct-manufacturer service contracts.
China
NMPA medical device registration requirements intensify clinical evidence demands for imported active implantable portfolios. Dual carbon goals accelerate lithium-ion cell localization for powered wheelchair rechargeable systems. Shanghai and Shenzhen component suppliers face cathode material processing bottlenecks.
Global Disability Devices Market Competitive Landscape
Capital-heavy producers compete with asset-light designers across electromechanical and sensory augmentation equipment. The vendor base separates into three tiers: integrated rehabilitation platform operators, specialized prosthetic component fabricators, and regional mobility hardware distributors. Strategic moves concentrate on firmware-over-air competency acquisition and predictive maintenance subscription bundling.
Within the integrated rehabilitation tier, Ottobock and Sunrise Medical exemplify platform vendors leveraging clinical partnerships for premium positioning. Cochlear Limited anchors the sensory implant specialist archetype through surgeon training network investments. These three occupy positions where ISO 13485 certification depth and regulatory affairs infrastructure create defensible moats against lower-capability entrants.
| Leading Market Players |
|---|
| Invacare Corporation |
| Sunrise Medical |
| Ottobock |
| Cochlear Limited |
| Sonova Holding AG |
| Medtronic plc |
| GF Health Products |
| Pride Mobility Products Corp. |
| Permobil |
| Others |
Supply & Pricing Matrix
Lithium carbonate price volatility cascades through cathode material processing into powered wheelchair rechargeable systems, stratifying final equipment pricing across premium firmware-integrated tiers and economy manual-operation alternatives. German statutory insurance reimbursement bands compress margin absorption capacity for mid-tier electronic control modules, while Southeast Asian cell supply bottlenecks force selective component substitution in volume mobility scooter segments.
Pricing Analysis
Margin tightening in mid-tier electronic control modules reflects ISO 13485 certification cost escalation and firmware validation talent scarcity. Three-tier pricing structure across premium, standard, and economy levels separates microprocessor-controlled prosthetics with terrain-adaptive damping from configurable seating systems and basic manual wheelchairs. Cost-down pressure on standard-tier mobility hardware accelerates because home care agencies consolidate procurement around predictive maintenance subscription bundling. Pediatric rehabilitation centers exhibit lowest price sensitivity due to growth-adjustable frame customization requirements; rural elderly care facilities face highest sensitivity as electronic throttle retrofits strain technician certification budgets.
Supply Chain Analysis
Biocompatibility testing technician shortages in Germany and the United States constrain ISO 13485-certified component throughput for programmable control firmware validation. Manufacturing gravity centers on Germany for microprocessor-controlled prosthetics, China for lithium-ion cell assembly, and Japan for sensor-based fall detection modules. Raw material dependencies span Southeast Asian cathode material processing, German precision-machined titanium alloys, and Taiwanese semiconductor foundry capacity. Single-source vulnerability concentrates in lithium-ion cell supply chains exposed to cathode material processing bottlenecks. Distribution runs through statutory health insurance-funded procurement channels in Germany, Veterans Affairs centralized purchasing in the United States, and prefecture-level elderly care facility contracts in Japan.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
ISO 13485 certification talent scarcity props pricing power for incumbent firmware-integrated device manufacturers, constraining supply expansion faster than demand absorption in terrain-adaptive prosthetic knee segments. Capacity bottlenecks in biocompatibility testing laboratories and regulatory affairs training pipelines sustain margin premiums for qualified suppliers across the analysis window.
For Market Incumbents: Deepen clinical engineering partnerships with German rehabilitation centers to lock in statutory insurance reimbursement eligibility for configurable seating systems. Acquire firmware-over-air competency through specialist talent recruitment in programmable control validation, defending against direct-manufacturer service contract displacement of traditional durable medical equipment distributors. Prioritize backward integration into lithium-ion cell supply relationships to mitigate Southeast Asian cathode material processing volatility. For New Entrants and Emerging Players: The pricing gap between premium microprocessor-controlled prosthetics and economy manual wheelchairs opens white-space targeting for sensor-based mobility retrofit kits in Japan's super-aging prefectures. Prefecture-level procurement centralization favors scaled platform vendors offering predictive maintenance subscriptions, creating entry leverage for firmware-over-air capable equipment providers. Audiologist practice channel partnerships for Bluetooth-enabled hearing aid companion apps represent the most penetrable go-to-market angle, capturing real-time usage analytics stickiness before incumbent digital inventory transitions complete. For Investors and Strategic Acquirers: Distressed-cycle entries favor mid-cap sensor-based equipment specialists with ISO 13485 certification depth and existing elderly care facility service contracts in Germany and Japan. Long-term viability hinges on regulatory affairs infrastructure scalability across EU MDR post-market surveillance obligations and FDA 510(k) pathway maturation. Monitor WHO assistive technology priority list revisions and national reimbursement catalog updates in emerging markets as inflection signals for procurement eligibility expansion into Gavi-aligned purchasing consortia.| Strategic Initiative | Industry Significance |
|---|---|
| Firmware-Over-Air Capability Development | Enables predictive maintenance subscriptions that consolidate home care agency vendor relationships in Germany. |
| ISO 13485 Certification Expansion | Filters lower-capability suppliers from EU MDR transatlantic access, defending incumbent positioning. |
| Direct-to-Implant Surgeon Training Networks | Expands cochlear implant addressable market beyond conventional hearing aid candidacy into osseointegration protocols. |
| Lithium-Ion Cell Supply Integration | Mitigates Southeast Asian cathode material processing bottlenecks affecting powered wheelchair input costs. |
| Bluetooth Low Energy Platform Integration | Captures real-time usage analytics that reduce return-for-credit rates in Japanese audiologist practices. |
Research Methodology
Multi-period observation of FDA 510(k) clearance timelines, EU MDR post-market surveillance compliance rates, and statutory insurance reimbursement catalog revisions anchored the trend analysis, supplemented by interviews with prosthetists, rehabilitation center clinical engineers, hospital purchasing committee managers, biomedical equipment technicians, and GPO contracts administrators. Secondary validation drew from FDA premarket notification databases, EU MDR vigilance reports, German statutory health insurance procurement records, Japan PMDA medical device registration filings, and hospital procurement database aggregators. Bottom-up equipment shipment tracking and top-down reimbursement expenditure analysis were triangulated against manufacturer capacity disclosures.
Input-output matrices modeled unit demand across product type, application, end user, and technology segmentation dimensions, with regional regulatory cluster overlays for FDA, EU MDR, PMDA, and TGA compliance pathways. CAGRs were derived from installed base replacement cycle compression rates and subscription revenue attachment trajectories. Forecast inputs incorporated lithium-ion cell supply concentration indices, ISO 13485 certification pipeline throughput estimates, and firmware-over-air adoption curves in elderly care facility procurement.
Underlying measurement precision varies by segment; sensor-based mobility equipment and Bluetooth-enabled hearing aids carry tighter precision than manual operation legacy categories due to discrete subscription revenue reporting. Forecasts reflect assumptions about reimbursement catalog stability, cathode material processing capacity expansion, and regulatory affairs talent pipeline recovery. Material deviation in WHO assistive technology priority list adoption timelines, EU MDR clinical evidence requirement enforcement intensity, or lithium carbonate price index trajectory warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Aortic Cannula Systems Market
Medical Devices
Vaginal Specula Market
Medical Devices
TMJ Implants Market
Medical Devices
Carotid Artery Stents Market
Medical Devices
Interventional Spine Devices Market
Medical Devices
Airway Clearance Systems Market
Medical Devices
Heel Incision Devices Market
Medical Devices
Baby Warmer Devices Market
Medical Devices
Global Pupillometer Market
Medical Devices
Powered Wheelchair Market
Medical Devices
Neonatal & Preterm Infant Enteral Feeding Devices Market
Medical Devices
Slit Lamps Market
Medical Devices
Below-The-Knee Implants Market
Medical Devices
Vaginal Applicators Market
Medical Devices
Germany Ophthalmic Devices Market
Medical Devices
Spinal Machined Bone Allograft Market