
 India Static Compression Therapy Market | 2026-2036
India Static Compression Therapy Market Size, Share, and Industry Trends Forecast 2026-2036
India Static Compression Therapy Market Foresight
Multi-source procurement of elastic yarns and knitted fabrics is restructuring supply arrangements across the India Static Compression Therapy Market. Cardinal Health leverages its hospital distribution network to sustain bulk contract visibility in metro corridors. Sigvaris AG anchors premium-grade stocking imports through direct specialist channel control. Medi GmbH & Co differentiates via calibrated pressure-class portfolios that occupy the therapeutic-grade tier.
Static compression therapy employs precisely graduated external pressure garments, typically delivering 15–20 mmHg to 30–40 mmHg at the ankle with progressive reduction toward the thigh, to enhance venous return and reduce edema. These devices serve primary clinical purposes in managing chronic venous insufficiency, post-thrombotic syndrome, and secondary lymphedema across inpatient and ambulatory settings. Compression stockings command the largest revenue pool due to repeat prescription cycles and retail pharmacy penetration, while compression bandages capture acute-care margin concentration through hospital burn and wound protocols. The home care user segment is expanding fastest as post-surgical patients transition earlier from institutional rehabilitation.
CDSCO's Medical Device Rules mandate registration and quality certification for all compression garments marketed in India, creating compliance barriers for unnotified imported stock. BIS textile standards for elastic woven and knitted medical fabrics further shape domestic manufacturing specifications and raw material sourcing. India's PLI scheme for medical textiles incentivizes local production of specialized compression yarns and finished garments. Stakeholders must monitor evolving pressure-class labeling requirements and state-level tender specifications as public hospital procurement digitizes.
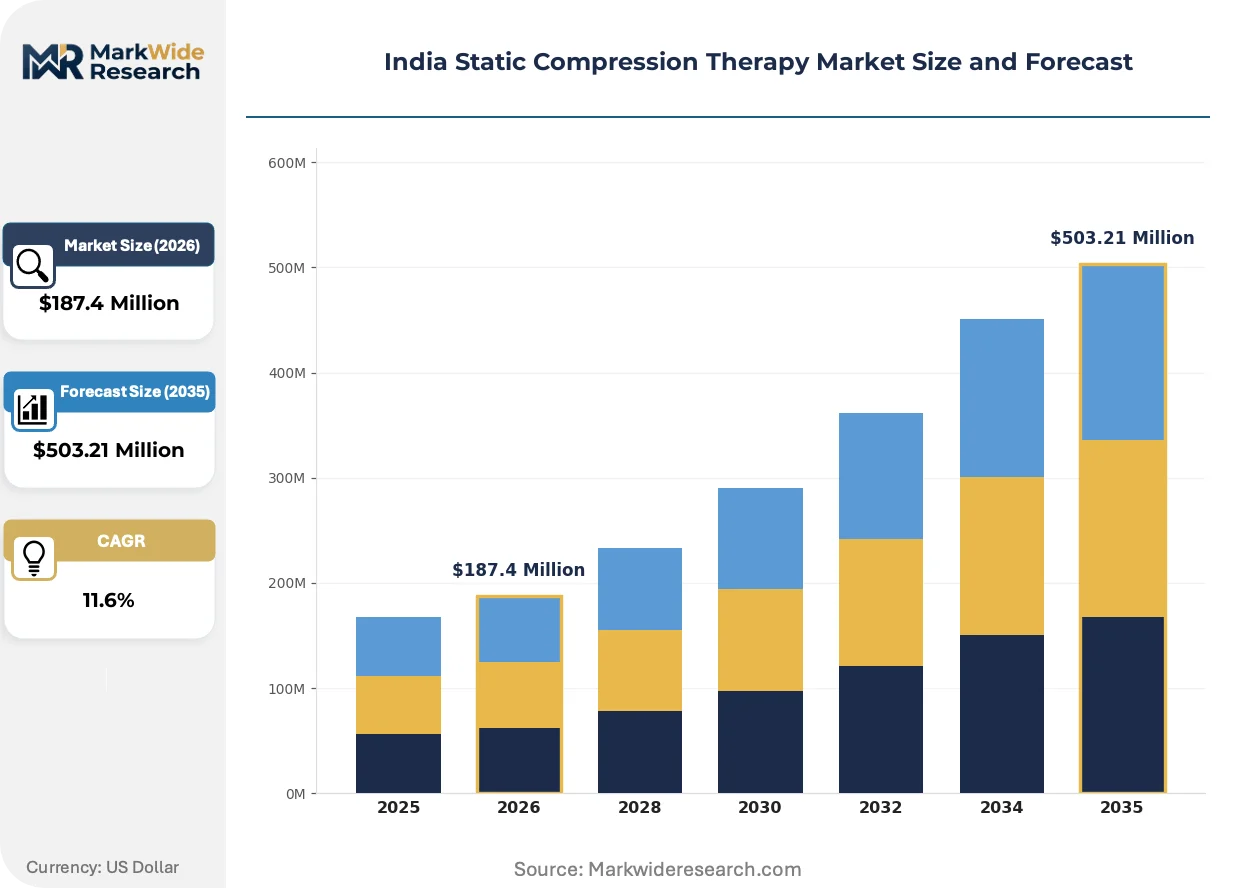
Market Dynamics
CDSCO's tightened Medical Device Rules are compressing market entry timelines while Maharashtra's tertiary hospitals scale post-surgical recovery departments, creating simultaneous supply-side filtering and demand-side expansion.
Growth Catalysts
- PLI Scheme for Medical Textiles:Domestic yarn and fabric producers gain cost competitiveness against imported elastic materials, incentivizing captive manufacturing of compression-grade knits.
- Tamil Nadu Vascular Surgery Clusters:Concentrated specialist infrastructure in Chennai generates institutional procurement pull for calibrated pressure-class garments.
- Home Care Transition Protocols:Earlier discharge from institutional rehabilitation is extending prescription cycles for ambulatory compression stockings.
Market Restraints
- Petrochemical Input Volatility:Spandex and elastane yarn prices fluctuate with crude derivatives, compressing margin predictability for domestic knitters.
- Import Dependency for Precision Looms:Circular knitting machinery for medical-grade compression concentrates with German and Italian suppliers, creating equipment lead-time risk.
- CDSCO Registration Friction:Unnotified foreign manufacturers face extended quality certification timelines, limiting product variety in the premium therapeutic tier.
Strategic Opportunities
- Karnataka Tier-II City Penetration:Mysore and Mangalore vascular centers remain underprovisioned relative to Bangalore, offering whitespace for distribution network extension.
- BIS Standard Harmonization:Alignment of textile pressure-class labeling with CDSCO device rules would streamline multi-regulator compliance for integrated manufacturers.
- Digital Tender Platforms:State-level e-procurement systems for public hospitals are opening direct supplier access previously gated by distributor networks.
Industry Challenges
- Pressure Calibration Technician Scarcity:Qualified personnel for garment pressure testing and quality assurance remain concentrated in Mumbai and Delhi, constraining regional manufacturing scale-up.
- Multi-Regulator Certification Lag:Simultaneous BIS textile and CDSCO device approvals extend product launch timelines by 8-14 months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | India Static Compression Therapy Market |
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $503.21 Million |
| CAGR (2026 – 2036) | 11.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Compression Stockings, Compression Bandages, Compression Wraps, Compression Garments Application: Chronic Venous Insufficiency, Lymphedema, Post-Surgical Recovery, Varicose Veins User Type: Healthcare Providers, Patients, Home Care, Physiotherapists Distribution Channel: Online Retail, Pharmacies, Medical Supply Stores, Hospitals |
| Companies Covered | 3M, BSN Medical, Sigvaris AG, Cardinal Health, Medi GmbH & Co, ArjoHuntleigh Healthcare India, Bio Compression Systems Inc, Zimmer Biomet India, Vissco Healthcare, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
India Static Compression Therapy Market Shifts & Advancements
Material science advances and procurement digitization are restructuring how compression garments move from yarn to patient, with regulatory data requirements now embedded at the design stage rather than post-production.
Smart textile integration with embedded pressure sensors is expanding into post-surgical monitoring applications. Bangalore-based tertiary hospitals are piloting connected garments for remote edema tracking. This capability is compressing the boundary between passive compression and active patient monitoring, creating new reimbursement negotiation leverage for equipped providers.
CDSCO's 2024 guidance on software-as-medical-device classification is capturing pressure-sensor data transmission modules under stricter quality management system requirements. Domestic manufacturers must now embed cybersecurity documentation in registration dossiers. Karnataka's medical device parks are responding by building shared testing infrastructure for connected garment validation.
Specialist channel consolidation is compressing distributor tiers in metropolitan corridors. Mumbai and Delhi vascular clinics are negotiating direct contracts with calibrated-portfolio suppliers, bypassing traditional pharmaceutical distributors. This disintermediation is most visible in the 30-40 mmHg therapeutic grade, where prescription volume justifies dedicated logistics investment.
India Static Compression Therapy Market Segmentation
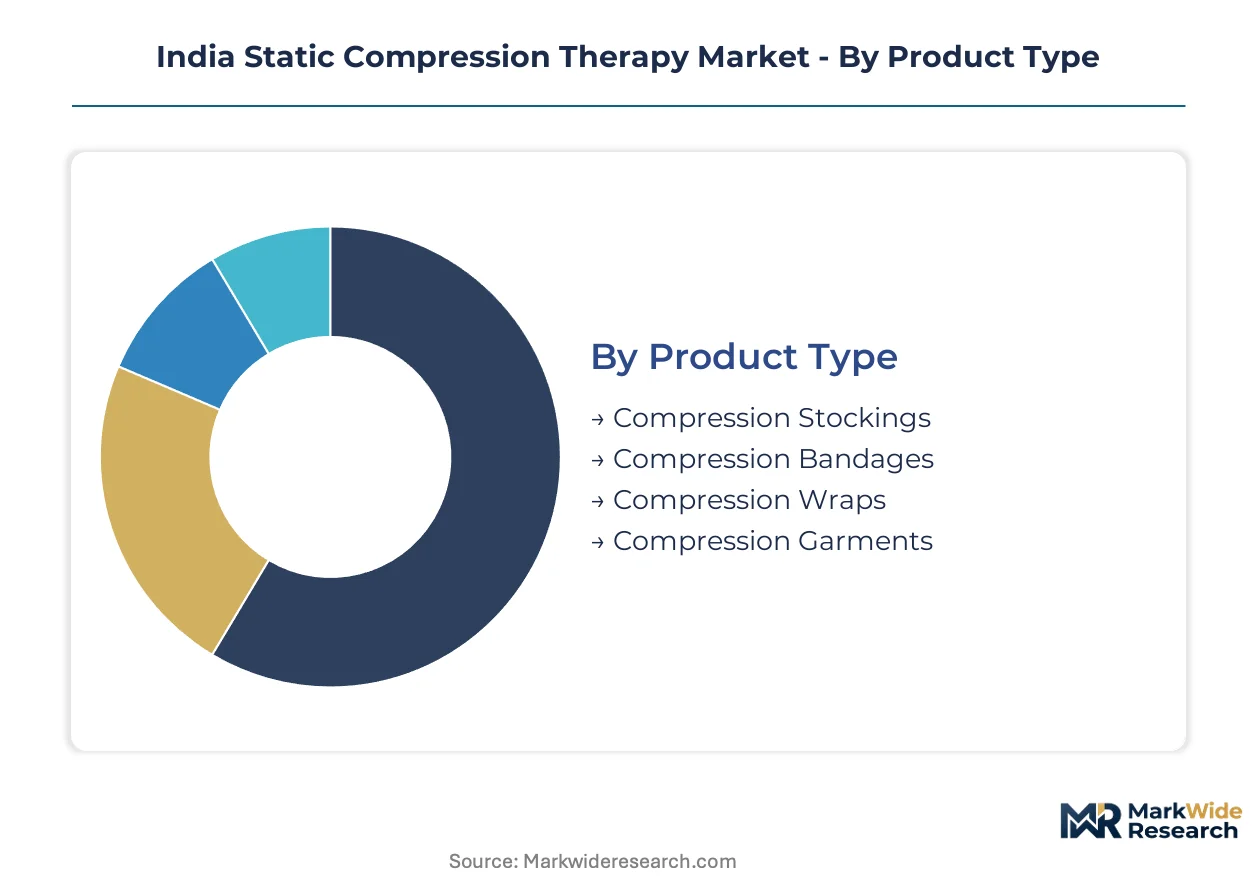
Compression therapy demand fragments across distinct pressure-class requirements, procurement workflows, and patient mobility profiles. Understanding these divides reveals where calibrated-portfolio suppliers can capture repeat prescription cycles versus one-time acute-care sales.
Product Type:
Supply-side capacity clusters around circular knitting infrastructure in Maharashtra and Tamil Nadu, with pressure-calibration capabilities determining tier access.
- Compression Stockings:Graduated elastic garments delivering 15–20 mmHg to 30–40 mmHg pressure gradients through circular-knit construction. Maharashtra's vascular surgery centers in Mumbai and Pune drive institutional procurement of therapeutic-grade stockings for chronic venous insufficiency management.
- Compression Bandages:Multi-layer elastic or short-stretch wraps applied in acute care for edema control and wound healing. Karnataka's tertiary hospital burn units concentrate demand for high-compression bandaging protocols, though trained application technician scarcity constrains expansion.
- Compression Wraps:Adjustable hook-and-loop systems for patients with dexterity limitations or fluctuating limb volume.
- Compression Garments:Custom-fitted upper-body and full-limb pieces for lymphedema and post-surgical applications.
Compression stockings absorb the bulk of installed capacity; compression bandages are expanding most quickly through hospital wound care protocol adoption.
Application:
Clinical indication determines pressure-class specification, reimbursement pathway, and prescriber specialty concentration across India's state-level health systems.
- Chronic Venous Insufficiency:Progressive venous valve failure requiring lifelong compression maintenance. Tamil Nadu's Chennai-based vascular clusters generate concentrated demand for 20–30 mmHg prescription stockings, with CDSCO registration requirements filtering supplier participation.
- Lymphedema:Secondary lymphatic fluid accumulation post-cancer surgery or radiation. Home care transition protocols in Delhi NCR are extending custom garment prescription cycles for ambulatory lymphedema patients.
- Post-Surgical Recovery:Acute edema prevention following orthopedic, vascular, or oncologic procedures.
- Varicose Veins:Cosmetic and symptomatic management of superficial venous dilation.
Chronic venous insufficiency captures the largest prescriber attention share; post-surgical recovery is climbing the fastest as early discharge protocols proliferate.
User Type:
Procurement authority and volume scale diverge sharply between institutional buyers and individual patients navigating retail channels.
- Healthcare Providers:Tertiary hospital vascular departments and wound care clinics with centralized purchasing authority. Karnataka's medical college hospitals are consolidating compression garment procurement through digital tender platforms.
- Patients:Direct-pay retail purchasers seeking over-the-counter 15–20 mmHg stockings for occupational or travel-related venous stress.
- Home Care:Post-discharge patients requiring ongoing compression through visiting nurse services or family-managed protocols.
- Physiotherapists:Rehabilitation specialists prescribing compression as adjunctive therapy for mobility restoration.
Healthcare providers dominate volume procurement; home care is gaining share fastest as institutional rehabilitation lengths contract.
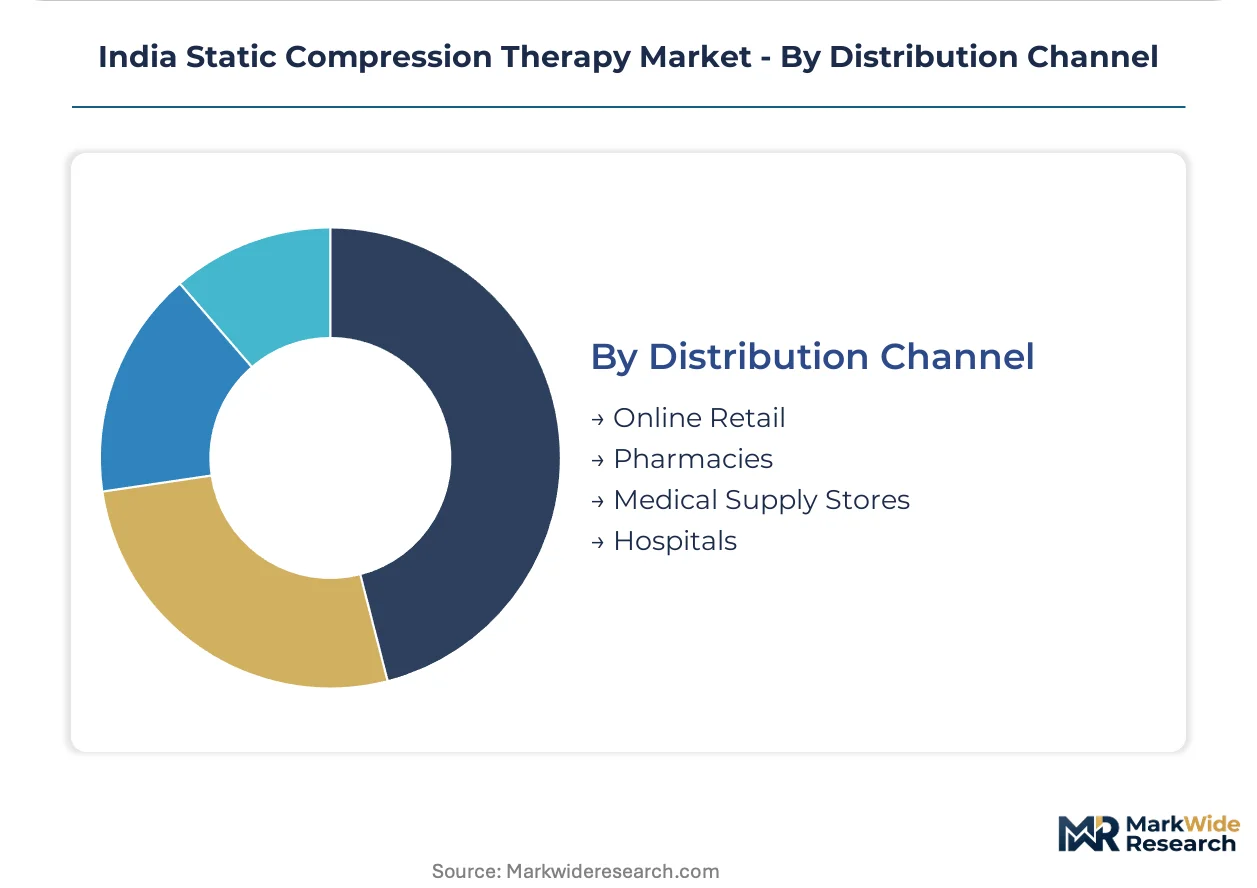
Distribution Channel:
Channel structure determines margin capture, with direct hospital contracts yielding lowest per-unit pricing but highest volume security.
- Hospitals:Institutional procurement through state-level tenders and direct supplier negotiations. Maharashtra's e-procurement platform is disintermediating traditional pharmaceutical distributors for 30–40 mmHg therapeutic grades.
- Pharmacies:Retail prescription fulfillment and over-the-counter stocking for 15–20 mmHg preventive grades.
- Medical Supply Stores:Specialized durable medical equipment retailers with fitting services for custom garments.
- Online Retail:Direct-to-patient platforms expanding in Tier-II cities with limited specialist retail presence.
Hospitals channel the greatest procurement volume; online retail is expanding most quickly in Mysore, Mangalore, and other underserved vascular corridors.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Spandex and elastane yarn production clusters in Maharashtra and Tamil Nadu anchor the India Static Compression Therapy Market's supply base. These coastal states concentrate circular knitting infrastructure and vascular surgery demand within a 200-kilometer radius. CDSCO's Medical Device Rules and BIS textile standards create dual-regulator compliance corridors that favor integrated manufacturers in these zones.
Maharashtra
Mumbai and Pune tertiary hospitals drive institutional procurement of 30–40 mmHg therapeutic-grade compression stockings for chronic venous insufficiency management. The state's e-procurement platform for public hospitals is disintermediating traditional pharmaceutical distributors for high-pressure garment tenders. CDSCO registration requirements filter supplier participation, concentrating contract awards among notified domestic and imported brands with established quality management systems.
Tamil Nadu
Chennai's vascular surgery clusters generate concentrated demand for calibrated pressure-class garments, with specialist infrastructure density unmatched elsewhere in India. The state's medical device parks are building shared testing infrastructure for connected garment validation under CDSCO's 2024 software-as-medical-device guidance. Coimbatore's textile engineering base supplies precision circular knitting machinery maintenance, reducing equipment downtime for local manufacturers.
Karnataka
Bangalore's tertiary hospitals pilot smart textile integration with embedded pressure sensors for remote edema tracking in post-surgical patients. BIS textile standards for elastic woven and knitted medical fabrics shape domestic manufacturing specifications among Bangalore-based producers. Mysore and Mangalore vascular centers remain underprovisioned relative to the capital, offering whitespace for distribution network extension and tier-II city penetration.
Delhi-NCR
Home care transition protocols in Delhi NCR extend custom garment prescription cycles for ambulatory lymphedema patients discharged from institutional rehabilitation. The region concentrates qualified personnel for garment pressure testing and quality assurance, constraining regional manufacturing scale-up elsewhere. India's PLI scheme for medical textiles incentivizes local production of specialized compression yarns among Noida and Faridabad textile processors.
Gujarat
Surat's synthetic fiber production base supplies elastane and spandex feedstock to Maharashtra and Tamil Nadu knitting operations, creating upstream dependency. The state's chemical processing infrastructure supports medical-grade fabric finishing with antimicrobial and moisture-wicking properties. CDSCO's tightened import quality benchmarks are redirecting some procurement toward Gujarat-based domestic manufacturers with integrated yarn-to-garment capabilities.
India Static Compression Therapy Market Competitive Landscape
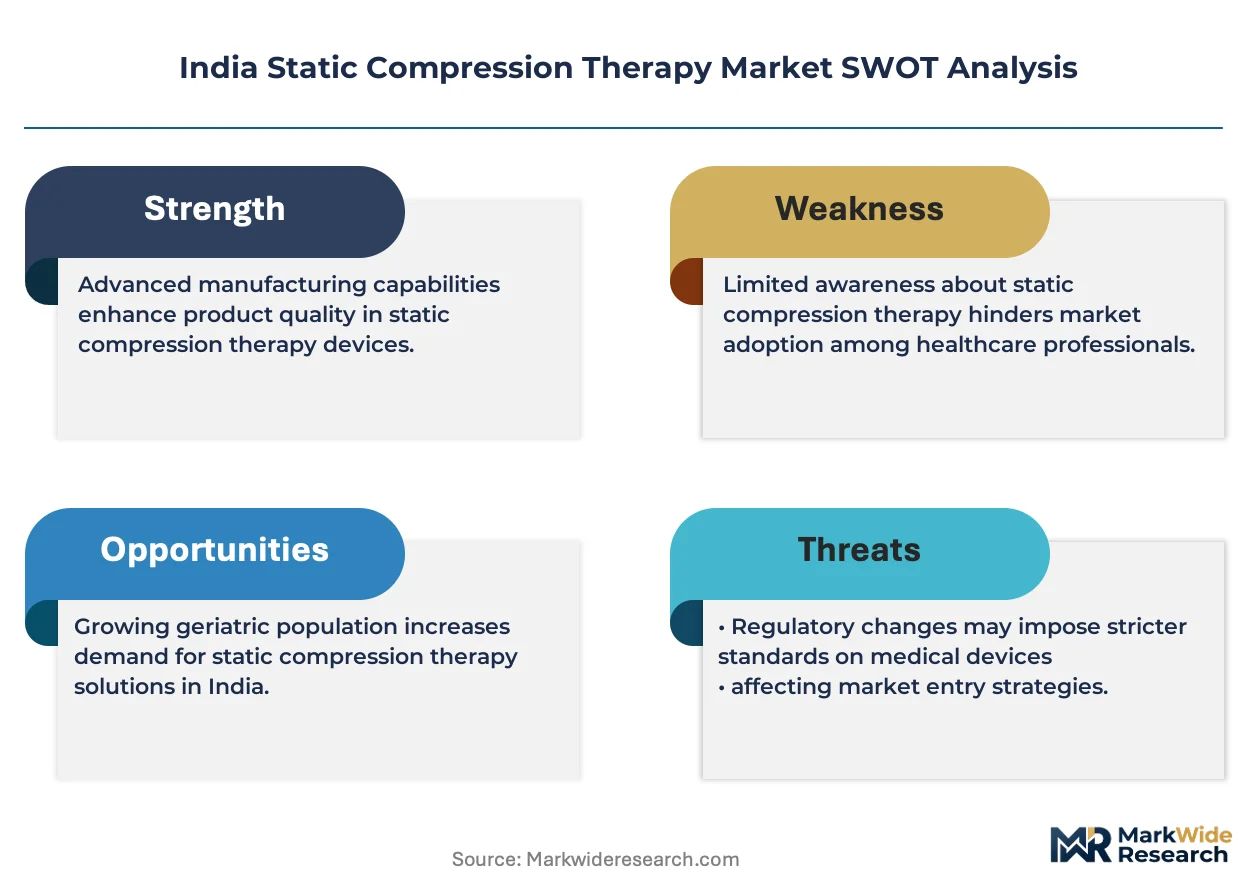
Portfolio diversification dominates the current landscape as suppliers calibrate pressure-class offerings to capture distinct reimbursement and procurement channels. The market structures around three tiers: premium therapeutic-grade importers with direct specialist channel control, mid-tier domestic manufacturers leveraging PLI scheme incentives, and economy-grade local knitters serving retail pharmacy preventive segments. Strategic archetypes include calibrated-portfolio specialists, hospital distribution network operators, and integrated textile-to-device manufacturers. M&A activity and capacity expansion in medical-grade circular knitting represent the dominant competitive moves, with state-level tender digitization accelerating direct supplier access.
Within the premium therapeutic tier, Sigvaris AG and Medi GmbH & Co exemplify European-origin specialists with established CDSCO registration dossiers and direct vascular clinic relationships. Cardinal Health occupies a position among hospital distribution network operators, leveraging institutional procurement scale in metro corridors. These three anchors represent contrasting geographic origins—Swiss, German, and American—and distinct structural forms: Aktiengesellschaft, GmbH & Co, and Inc. The competitive dynamic between direct specialist channel control and bulk hospital contract visibility shapes margin capture, with BIS-CDSCO dual compliance capabilities determining tier access rather than price alone.
| Leading Market Players |
|---|
| 3M |
| BSN Medical |
| Sigvaris AG |
| Cardinal Health |
| Medi GmbH & Co |
| ArjoHuntleigh Healthcare India |
| Bio Compression Systems Inc |
| Zimmer Biomet India |
| Vissco Healthcare |
| Others |
Supply & Pricing Matrix
Crude-linked elastane price indices cascade through Maharashtra's circular knitting clusters into three-tier pricing structures across premium, standard, and economy levels. Spandex yarn cost volatility compresses margin buffers for domestic manufacturers while CDSCO registration requirements sustain premium tier pricing power among notified importers.
Pricing Analysis
Warranty and calibration service bundling separates Sigvaris AG's direct specialist channel contracts from unbundled retail pharmacy stockings. Pricing stratifies across premium, standard, and economy tiers based on CDSCO notification status and BIS textile certification grade. Cost compression in the mid-tier is intensifying because PLI scheme beneficiaries are expanding calibrated-portfolio capacity. Individual patients seeking over-the-counter 15–20 mmHg stockings exhibit highest price sensitivity; tertiary hospital procurement committees negotiating 30–40 mmHg therapeutic grades prioritize pressure calibration accuracy over unit cost.
Supply Chain Analysis
Single-source vulnerability sits with German and Italian precision circular knitting machinery suppliers, constraining domestic capacity expansion timelines. Raw material sourcing draws from Gujarat's Surat synthetic fiber base for elastane feedstock, Maharashtra's textile chemical processors for antimicrobial finishing, and Tamil Nadu's Coimbatore engineering hub for equipment maintenance. Tariff exposure concentrates on imported therapeutic-grade yarns from European notified bodies. Distribution runs through disintermediating state e-procurement platforms for hospital contracts alongside traditional pharmaceutical distributor networks for retail pharmacy penetration.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Smart textile integration with embedded pressure sensors is displacing passive compression garments in Bangalore's tertiary hospital pilots, compressing the technology-transition window for legacy manufacturers.
For Market Incumbents: Deploy backward integration into captive elastane yarn production to buffer margin compression from petrochemical input volatility. Cardinal Health should expand direct hospital contract visibility through Karnataka's digital tender platforms before distributor networks consolidate. Medi GmbH & Co must accelerate CDSCO software-as-medical-device registration for connected garment data transmission modules to defend against emerging domestic competitors.
For New Entrants and Emerging Players: BIS standard harmonization with CDSCO device rules in India opens a window for integrated textile-to-device manufacturers to capture tier-II city whitespace in Mysore and Mangalore vascular corridors. Target home care transition protocols with adjustable compression wraps for patients with dexterity limitations. Pursue direct-to-clinic distribution bypassing pharmaceutical intermediaries in Maharashtra's e-procurement corridors.
For Investors and Strategic Acquirers: Distressed-cycle entries favor mid-tier domestic knitters with partial PLI scheme qualification in Tamil Nadu medical device parks. Five-to-ten year viability hinges on pressure calibration technician training infrastructure scaling beyond Mumbai and Delhi concentration. Watch Karnataka's shared testing infrastructure buildout for connected garment validation as inflection signal for smart textile reimbursement pathway maturation.
| Strategic Initiative | Industry Significance |
|---|---|
| CDSCO Software-as-Medical-Device Registration | Cybersecurity documentation requirements for pressure-sensor data modules favor early registrants in Karnataka's medical device parks. |
| PLI Scheme Capacity Expansion | Domestic elastane yarn production incentives compress import dependency for Maharashtra circular knitting operations. |
| Direct Hospital System Partnership | Maharashtra's e-procurement disintermediation rewards suppliers with dedicated logistics investment in 30–40 mmHg therapeutic grades. |
| Pressure Calibration Technician Training | Qualified personnel scarcity in regional manufacturing constrains scale-up; training infrastructure builds defensive moat. |
| Smart Textile Reimbursement Strategy | Remote edema tracking capabilities in Bangalore pilots create negotiation leverage for equipped providers with payers. |
Research Methodology
Hospital procurement databases, CDSCO registration filings, and BIS textile standard documentation formed the secondary backbone for this analysis. Primary interviews with vascular surgeons, biomedical engineers, hospital purchasing committee members, and GPO contracts managers validated demand-side assumptions. Customs records for elastane and spandex yarn imports triangulated supply-side concentration against bottom-up manufacturer capacity surveys.
Historical trendline analysis of pressure-class prescription volumes and circular knitting capacity utilization established baseline growth trajectories across the projection horizon. The analytical framework modeled segmentation dimensions including product type, clinical application, user type, and distribution channel alongside regional regulatory cluster differentiation. CAGRs were derived from installed capacity expansion timelines, PLI scheme incentive uptake rates, and state-level tender digitization penetration curves.
Caveats apply where CDSCO registration timeline extensions or petrochemical price spikes could materially shift the outlook for domestic manufacturer competitiveness. Forecasts reflect documented assumptions regarding BIS-CDSCO harmonization progress and smart textile reimbursement pathway maturation. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Spain Aesthetic Devices Market
Medical Devices
North America Portable Medical and Healthcare Devices Market
Medical Devices
Europe Mobility Aids Market
Medical Devices
Thrombectomy System Market
Medical Devices
United States Small Bone and Joint Devices Market
Medical Devices
North America Cardiac Rhythm Management Devices Market
Medical Devices
Global Surgical Drills Market
Medical Devices
Global Bone Tumor Ablation Devices Market
Medical Devices
Urodynamic Catheter Market
Medical Devices
Global Capillary Blood Collection Devices Market
Medical Devices
Oxygen Concentrators Market
Medical Devices
Intrapartum Monitors Market
Medical Devices
Skin Rejuvenation Devices Market
Medical Devices
China Respiratory Devices Market
Medical Devices
Europe Manual Resuscitators Market
Medical Devices
Germany Spinal Surgery Devices Market