
 Global Neurovascular Thrombectomy Devices Market | 2026-2036
Global Neurovascular Thrombectomy Devices Market Size, Share, and Industry Trends Forecast 2026-2036
Global Neurovascular Thrombectomy Devices Market Foresight
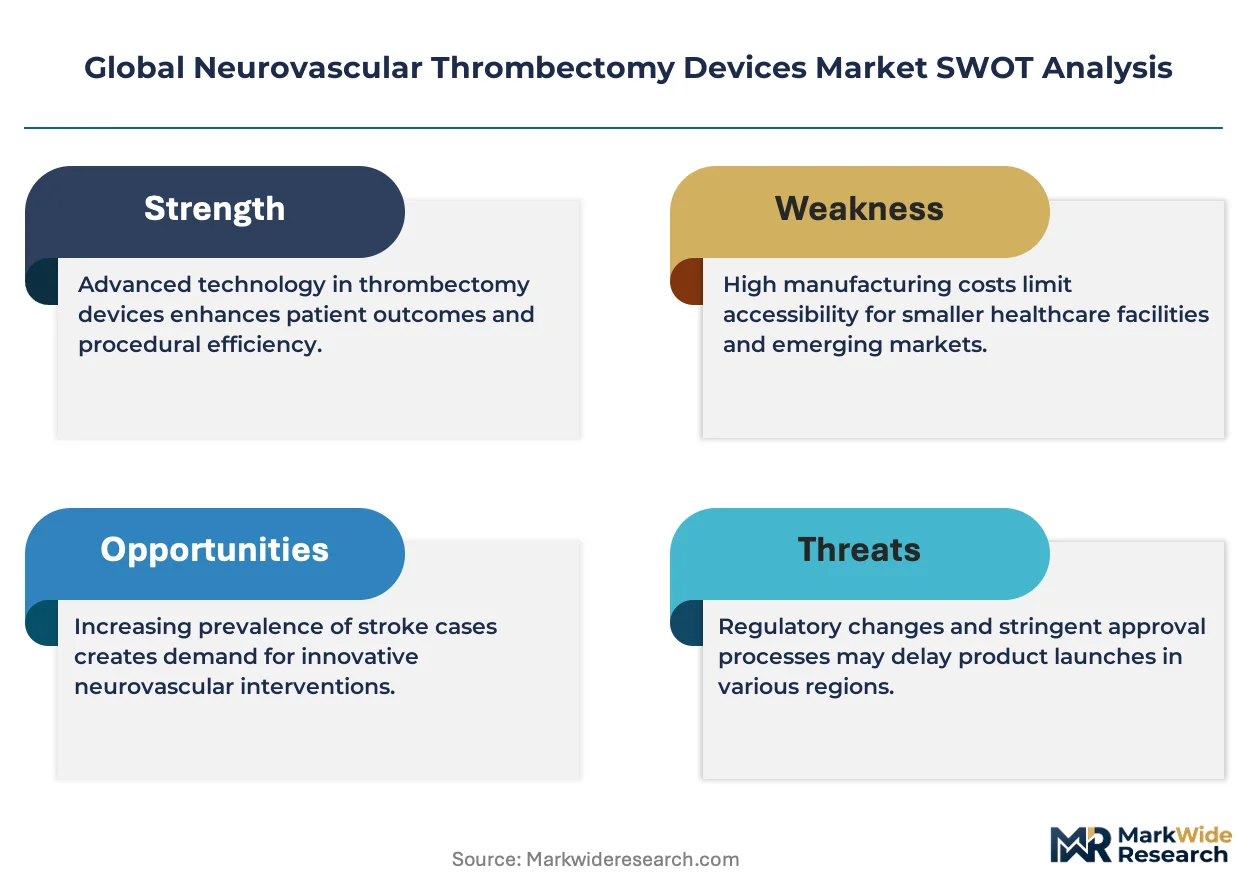
A widening capital-intensity gap between integrated manufacturers and component assemblers is rotating competitive advantage toward firms with captive nitinol supply chains. Medtronic leverages its vertically integrated catheter production to sustain margin resilience across stent retriever portfolios. Stryker anchors North American market presence through dense specialist hospital contracting networks. Penumbra differentiates via proprietary aspiration technology that occupies the fastest-expanding procedural segment.
Global neurovascular thrombectomy devices encompass minimally invasive instruments designed to extract or dissolve intracranial blood clots, typically constructed from nitinol alloys with distal tip diameters ranging from 0.017 to 0.035 inches and deployed through microcatheters under fluoroscopic guidance. These devices restore cerebral perfusion in acute ischemic stroke, reducing permanent neurological deficit when deployed within the therapeutic window. Stent retrievers command the largest revenue pool due to established clinical validation and broad physician familiarity, while aspiration catheters represent the fastest-growing product category as direct aspiration first pass techniques gain protocol adoption. Mechanical thrombectomy technology dominates procedural volume, though pharmacomechanical approaches are gaining traction in complex distal vessel occlusions where standalone mechanical retrieval faces anatomical constraints.
FDA premarket approval pathways and EU MDR conformity assessments shape neurovascular device commercialization timelines, with both regulators demanding extensive clinical safety datasets for permanent implantable thrombectomy platforms. Japan's PMDA imposes additional domestic trial requirements that extend market entry lag for foreign manufacturers. China's NMPA has accelerated innovative device review channels, altering Asia-Pacific competitive dynamics. Stakeholders must monitor evolving real-world evidence requirements and prioritize health technology assessment alignment across reimbursement authorities.
Market Dynamics
Specialty hospitals are consolidating neurointerventional service lines around direct aspiration first pass techniques, compressing demand for conventional stent retrievers and rewarding manufacturers with integrated aspiration catheter portfolios.
Growth Catalysts
- EU MDR clinical evidence mandates:The EU Medical Device Regulation's tightened requirements for Class III implantable devices are accelerating hospital preference toward established thrombectomy platforms with robust safety datasets.
- Comprehensive stroke center networks:Maturing referral systems in the United States, Germany, and Japan are standardizing mechanical thrombectomy protocols and expanding eligible patient pools.
- Nitinol alloy supply security:Captive production of shape-memory alloys is rotating procurement advantage toward vertically integrated device manufacturers with in-house metallurgical capabilities.
Market Restraints
- Input cost volatility:Nitinol pricing fluctuation and rare earth supply concentration in China are compressing margins for component assemblers without backward-integrated supply chains.
- Regulatory friction:Japan's PMDA domestic trial requirements extend market entry timelines for foreign manufacturers, creating structural lag versus local competitors.
- Technical limitation:Distal vessel anatomical constraints in M2 and M3 segments limit standalone mechanical retrieval efficacy, constraining addressable procedural volume.
Strategic Opportunities
- Underpenetrated geography:China's NMPA accelerated innovative device review channels are altering Asia-Pacific competitive dynamics for early entrants with localized clinical programs.
- Technology convergence:Pharmacomechanical approaches combining aspiration with intra-arterial thrombolytics are opening white space in complex distal occlusions.
- Distribution innovation:Direct-to-hospital consignment models for aspiration catheters are displacing traditional distributor networks in high-volume stroke centers.
Industry Challenges
- Skill gap in neurointerventional nursing:Acute shortage of trained scrub technicians capable of supporting direct aspiration procedures is constraining service line expansion.
- Certification timeline compression:FDA premarket approval pathway requirements for permanent implantable platforms demand extensive clinical datasets, stretching R&D-to-revenue cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Neurovascular Thrombectomy Devices Market |
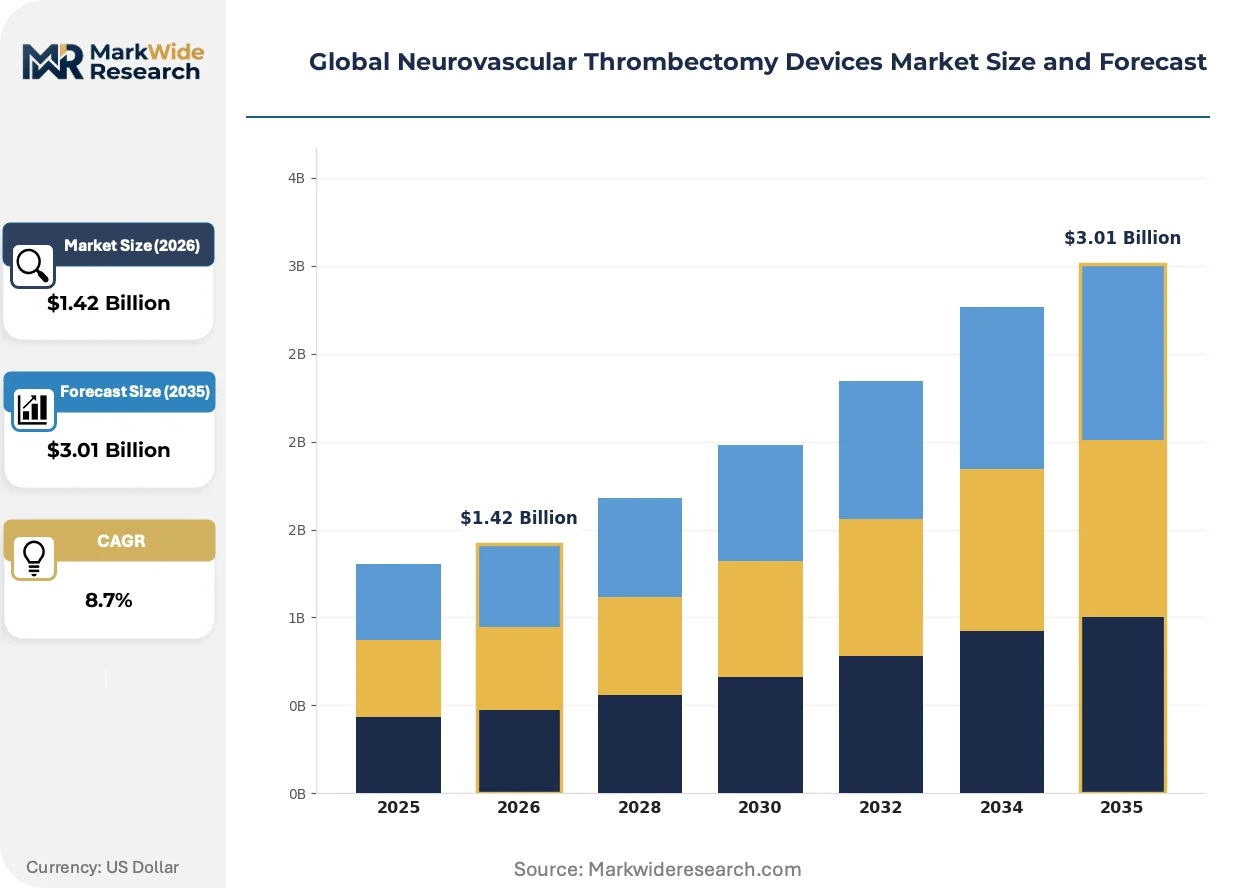
| Market Size in 2026 | $1.42 Billion |
| Market Size in 2035 | $3.01 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Stent Retrievers, Aspiration Catheters, Separator Devices, Balloon Guide Catheters Technology: Mechanical Thrombectomy, Pharmacomechanical, Suction Assisted, Laser Assisted Application: Ischemic Stroke, Cerebral Aneurysm, Intracranial Hemorrhage, Arteriovenous Malformation End User: Specialty Hospitals, Neurology Clinics, Research Institutes, Emergency Care Centers |
| Companies Covered | Medtronic, Stryker, Penumbra, Acandis GmbH, Johnson & Johnson, Terumo Corporation, Abbott Laboratories, Vesalio, Phenox GmbH, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Neurovascular Thrombectomy Devices Market Shifts & Advancements
Device miniaturization and real-world evidence requirements are reshaping competitive positioning across thrombectomy portfolios, while procurement patterns in mature stroke center networks favor integrated supply arrangements.
Distal access aspiration technology is miniaturizing catheter outer diameters below 0.050 inches while maintaining aspiration lumen integrity. Comprehensive stroke centers in the United States and Germany are adopting these platforms for M2 segment interventions at accelerating pace. This miniaturization is compressing the addressable gap between standalone aspiration and stent retriever adjunctive use, consolidating procedure economics toward single-device strategies.
The EU Medical Device Regulation's post-market surveillance requirements are mandating systematic collection of real-world performance data for Class III implantable thrombectomy devices. Manufacturers must now maintain active implant registries and periodic safety update reports, elevating compliance infrastructure costs. Stent retriever portfolios face the steepest documentation burden given their permanent implant classification and established procedural volume base.
Hospital procurement committees are consolidating vendor relationships around single-source contracts covering aspiration catheters, microcatheters, and access equipment. This bundling behavior is displacing multi-vendor purchasing patterns previously common in academic medical centers. The shift is most visible in United States comprehensive stroke centers, where annual contract values now hinge on total procedural cost guarantees rather than device-level pricing.
Global Neurovascular Thrombectomy Devices Market Segmentation
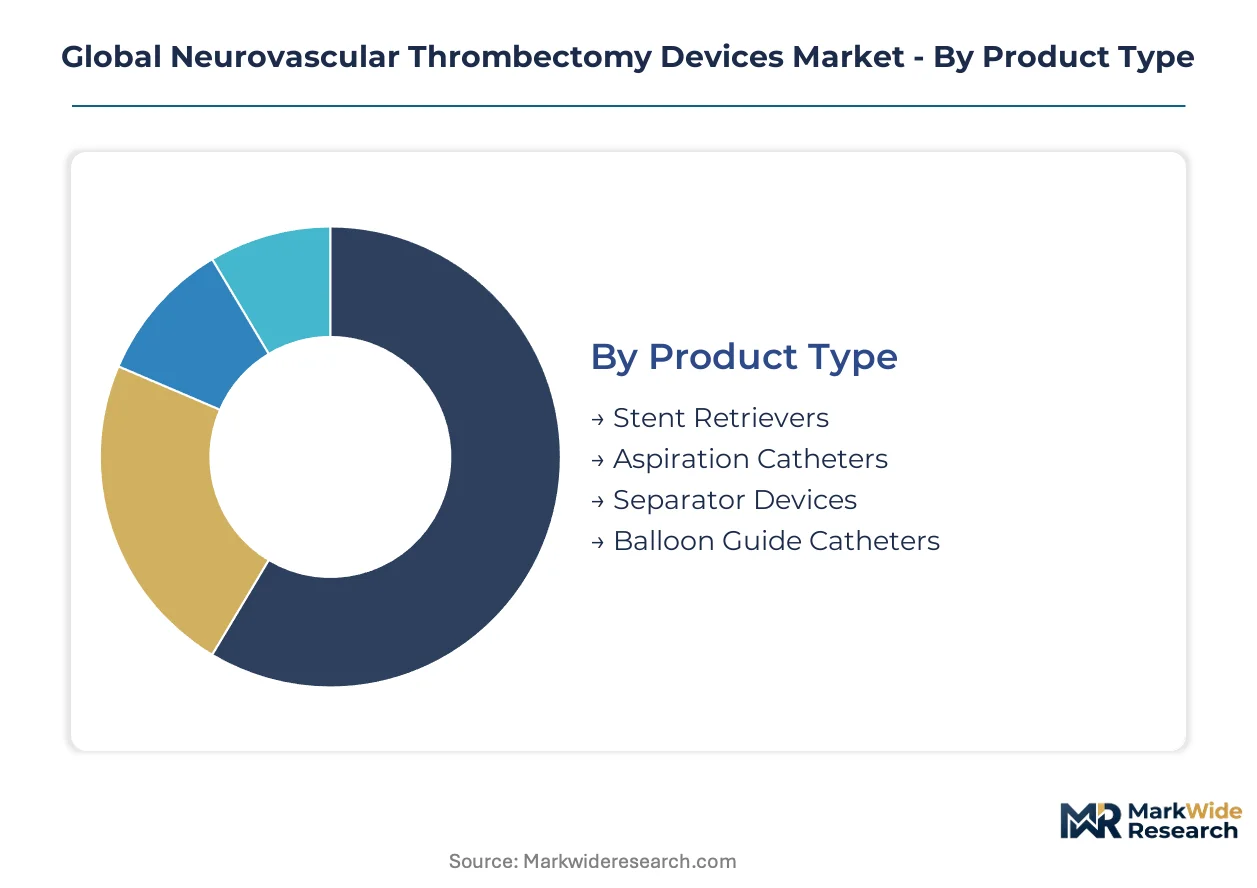
Segmentation in neurovascular thrombectomy devices reveals how substitution pressures between mechanical and pharmacomechanical approaches are redistributing procurement budgets across hospital service lines. Understanding these dynamics helps manufacturers prioritize R&D allocation and anticipate which device categories face imminent displacement.
Product Type:
Substitution pressure runs strongest against stent retrievers as aspiration-first protocols displace established mechanical retrieval workflows in comprehensive stroke centers.
- Stent Retrievers:These nitinol-mesh devices deploy across cerebral vessel occlusions then collapse to ensnare thrombus during retrieval. Demand concentrates in Germany and Japan where physician training programs favor established mechanical techniques and reimbursement pathways reward proven efficacy data. Regulatory familiarity with FDA PMA pathways sustains incumbent positioning despite procedural shift risks.
- Aspiration Catheters:Large-bore suction systems extract thrombus through direct aspiration without permanent implantation. United States comprehensive stroke centers are consolidating procurement around these platforms as first-line therapy, driven by reduced procedural steps and lower per-case device costs. Miniaturization below 0.050-inch outer diameters is expanding addressable anatomy into M2 segments.
- Separator Devices:Adjunctive tools fragment resistant thrombus to facilitate extraction.
- Balloon Guide Catheters:Flow-arrestment devices that stabilize proximal circulation during retrieval procedures.
Stent retrievers anchor the volume base while aspiration catheters gain share at the steepest rate.
Technology:
Cost tier stratification separates capital-intensive laser platforms from disposable mechanical systems, with mid-range pharmacomechanical hybrids capturing investment interest for complex distal cases.
- Mechanical Thrombectomy:Physical clot retrieval through stent-based or aspiration-based instrumentation dominates procedural economics. United States and German stroke centers standardize protocols around these approaches, with device selection increasingly dictated by hospital consignment contract terms rather than individual physician preference.
- Pharmacomechanical:Combined intra-arterial thrombolytic delivery with mechanical extraction addresses distal M2 and M3 occlusions where standalone aspiration fails. Japan's PMDA has accelerated review pathways for these hybrid platforms, creating regulatory arbitrage opportunities versus EU MDR timelines.
- Suction Assisted:Enhanced aspiration systems with pump-integrated vacuum generation.
- Laser Assisted:Photoacoustic thrombus disruption systems requiring specialized capital equipment.
Mechanical thrombectomy commands installed base dominance while pharmacomechanical approaches expand most quickly in anatomically complex cases.
Application:
Patient volume distribution concentrates overwhelmingly in acute ischemic stroke, though aneurysm intervention devices command premium pricing tiers that sustain margin contribution despite smaller case loads.
- Ischemic Stroke:Acute large-vessel occlusion treatment represents the core addressable market. Comprehensive stroke center networks in the United States, Germany, and Japan drive procedural standardization, with door-to-device time metrics directly influencing hospital certification status and reimbursement rates.
- Cerebral Aneurysm:Flow diversion and coiling adjuncts occupy higher price bands with longer sales cycles. Japanese and German academic medical centers concentrate demand for these platforms, where physician training depth supports complex case selection.
- Intracranial Hemorrhage:Hematoma evacuation and hemorrhage control applications.
- Arteriovenous Malformation:Niche vascular anomaly interventions with specialized device requirements.
Ischemic stroke anchors procedure volume while cerebral aneurysm applications sustain premium pricing tiers.
End User:
Customer type segmentation reveals procurement concentration in hospital systems with neurointerventional fellowship programs, while emergency care centers represent a latent demand channel constrained by technical staffing gaps.
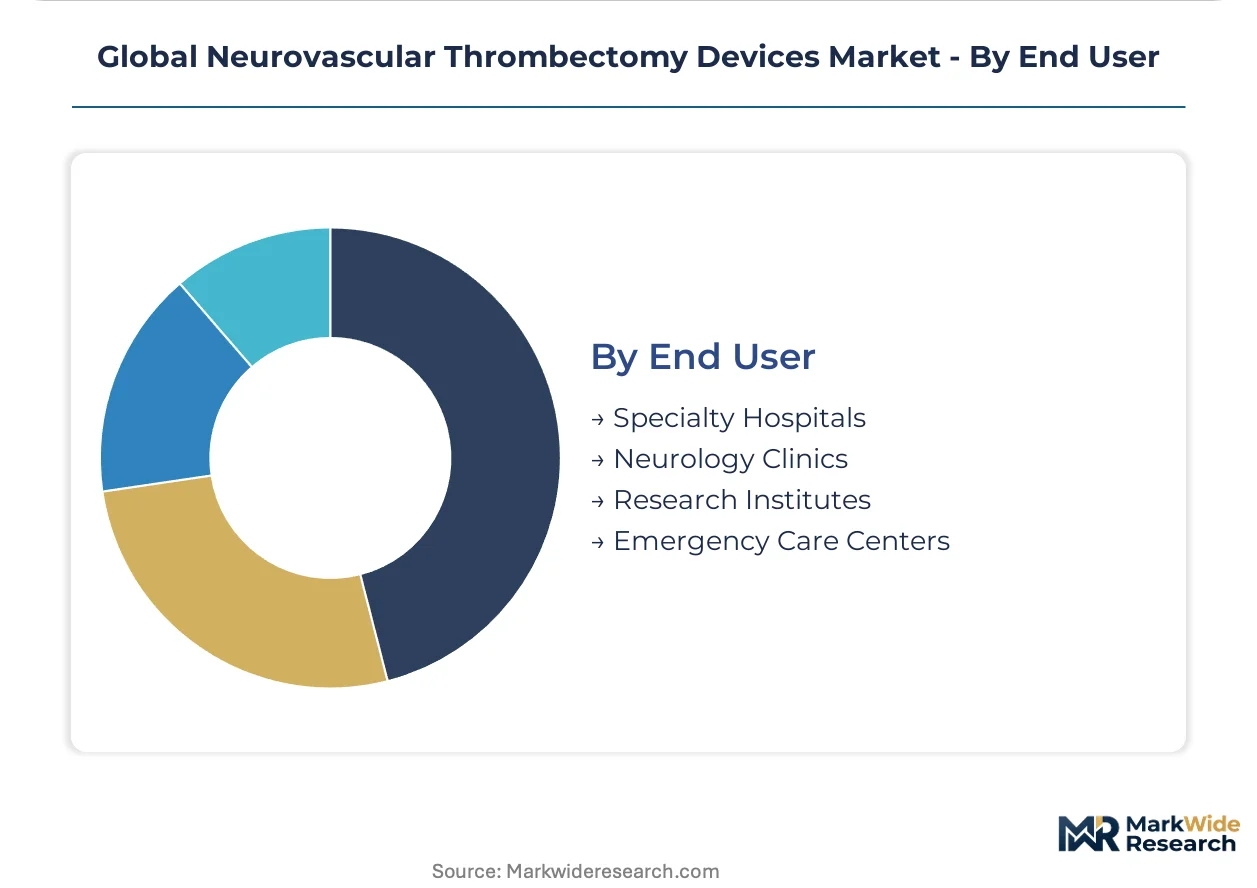
- Specialty Hospitals:Comprehensive stroke centers with 24/7 neurointerventional coverage concentrate device procurement through annual vendor contracts. United States hospital systems are consolidating purchasing across multi-facility networks, displacing individual hospital autonomy in device selection.
- Neurology Clinics:Outpatient diagnostic and post-acute referral sites with limited device utilization.
- Research Institutes:Clinical trial sponsors and technology assessment bodies shaping protocol evolution.
- Emergency Care Centers:Pre-hospital and urgent care sites with thrombolytic administration capability but lacking interventional infrastructure.
Specialty hospitals dominate current revenue concentration while emergency care centers present long-term channel expansion potential contingent on workforce development investments.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Hospital procurement committees in Germany demonstrate the lowest price elasticity, prioritizing device reliability and clinical validation over per-unit costs. United States buyers exhibit moderate sensitivity, balancing door-to-device time metrics against total procedural economics. Japanese purchasers face the highest elasticity constraints due to reimbursement compression and domestic trial cost burdens.
United States
Comprehensive stroke center networks in Texas, Florida, and California drive concentrated demand for aspiration catheter platforms. FDA premarket approval pathways for Class III implantable devices enforce rigorous clinical safety datasets, extending commercialization timelines. The Greater Boston cluster anchors neurointerventional training programs that standardize direct aspiration first pass protocols across affiliated hospital systems.
Germany
Academic medical centers in Bavaria and North Rhine-Westphalia sustain premium demand for stent retriever portfolios with established efficacy data. EU MDR conformity assessments for permanent implantable platforms mandate extensive post-market surveillance infrastructure. The Heidelberg-Mannheim corridor concentrates catheter manufacturing capabilities that supply device assemblers across Western Europe.
Japan
PMDA domestic trial requirements create structural entry lag for foreign manufacturers, protecting local competitors in the Kanto and Kansai regions. METI funding programs accelerate pharmacomechanical hybrid platform development for complex distal vessel interventions. The Tokyo-Osaka axis hosts the densest concentration of neurointerventional fellowship programs in Asia-Pacific.
China
NMPA accelerated innovative device review channels are compressing market entry timelines for aspiration technology entrants with localized clinical programs. Dual carbon goals in the Yangtze River Delta are reshaping nitinol alloy processing facility permitting. The Shanghai-Suzhou corridor attracts foreign joint ventures seeking to bypass traditional regulatory lag through domestic manufacturing partnerships.
United Kingdom
NHS England specialized commissioning frameworks concentrate thrombectomy service authorization in London, Manchester, and Birmingham stroke centers. MHRA alignment with EU MDR post-market surveillance requirements elevates compliance costs for implantable device portfolios. The Oxford-Cambridge arc hosts emerging medtech incubators focused on miniaturized distal access catheter development.
Global Neurovascular Thrombectomy Devices Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes, creating tiered competitive dynamics across the neurovascular thrombectomy devices market. Vertically integrated manufacturers with captive nitinol supply chains command margin resilience against input cost volatility. Component assemblers without backward-integrated metallurgical capabilities face procurement disadvantage and pricing pressure. Strategic moves concentrate on hospital consignment contract consolidation and integrated portfolio bundling covering aspiration catheters, microcatheters, and access equipment.
Among diversified medical technology conglomerates, Medtronic, Stryker, and Johnson & Johnson occupy positions exemplifying scale-driven competitive advantage through dense specialist hospital contracting networks and vertically integrated catheter production infrastructure. These entities represent the integrated manufacturer archetype that procurement committees increasingly favor for single-source annual contracts. Smaller specialized firms including Acandis GmbH and Phenox GmbH sit within a distinct tier focused on regional market penetration and technology-specific clinical validation strategies.
| Leading Market Players |
|---|
| Medtronic |
| Stryker |
| Penumbra |
| Acandis GmbH |
| Johnson & Johnson |
| Terumo Corporation |
| Abbott Laboratories |
| Vesalio |
| Phenox GmbH |
| Others |
Supply & Pricing Matrix
Sixty-to-ninety day nitinol alloy lead times concentrate procurement leverage with vertically integrated manufacturers possessing in-house metallurgical capabilities, compressing margins for component assemblers and rotating pricing power toward firms with captive supply chains.
Pricing Analysis
After-sales service contracts covering catheter reprocessing and technical field support drive lifetime customer value beyond initial device placement. Three-tier pricing structure across premium, standard, and economy levels separates FDA PMA-validated stent retrievers from CE-marked aspiration platforms and unbranded consumables. Cost compression in standard-tier aspiration catheters is intensifying because Chinese nitinol processors are expanding output. Academic medical centers in Germany demonstrate lowest price sensitivity while Japanese district hospitals face reimbursement compression.
Supply Chain Analysis
Shanghai-Suzhou nitinol processing concentration creates single-source vulnerability for Western device assemblers dependent on Chinese shape-memory alloy feedstock. Supply draws from China, Germany, and the United States for nitinol wire and catheter extrusions. Rare earth element dependence and EU MDR documentation requirements compound input risk. Distribution runs through hospital consignment models displacing traditional distributor networks in high-volume stroke centers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation opportunity exists as procedural protocol divergence between aspiration-first and stent-retriever advocates creates distinct equipment preferences across hospital systems.
For Market Incumbents: Shield installed base relationships by accelerating backward integration into nitinol supply and securing multi-year consignment contracts with comprehensive stroke center networks. Substitute technology pressure from miniaturized aspiration platforms demands preemptive portfolio bundling covering access equipment and microcatheters. For New Entrants and Emerging Players: Differentiate on pharmacomechanical hybrid platforms for M2-M3 distal occlusions where standalone mechanical retrieval faces anatomical constraints. China's NMPA accelerated review channels offer the most penetrable regulatory pathway for localized clinical programs. Target direct-to-hospital sales models bypassing established distributor relationships. For Investors and Strategic Acquirers: Carve-out targets emerge from diversified medical technology conglomerates seeking to divest non-core neurovascular assets. Five-to-ten year viability hinges on EU MDR compliance infrastructure and real-world evidence generation capabilities. Watch for inflection signals in China's NMPA approval velocity versus Japan's PMDA domestic trial burden.| Strategic Initiative | Industry Significance |
|---|---|
| EU MDR Conformity Assessment | Post-market surveillance infrastructure elevates compliance costs for implantable stent retriever portfolios. |
| Backward Integration into Nitinol Supply | In-house metallurgical capabilities rotate procurement advantage against Chinese rare earth concentration. |
| Hospital System Partnership | Single-source annual contracts displace multi-vendor purchasing in United States comprehensive stroke centers. |
| Software Companion Development | Real-world evidence platforms automate registry maintenance for Class III implantable safety datasets. |
| Reimbursement Strategy | Door-to-device time metrics directly influence CMS certification status and hospital payment rates. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of FDA PMA filings, EU MDR technical documentation, hospital GPO contracts, and nitinol trade flow data. Interviews with neurointerventionalists, biomedical engineers, hospital purchasing committees, and GPO contracts managers inform demand-side validation. Bottom-up procedural volume estimates triangulate against top-down manufacturer revenue disclosures.
Segmentation dimensions modeled include product type, technology platform, application indication, and end-user facility tier across the analysis window. CAGRs derive from procedure volume growth, device substitution rates, and pricing trajectory assumptions. Forecast inputs incorporate comprehensive stroke center network expansion timelines and regulatory pathway velocity differentials by geography.
Material uncertainties — nitinol price volatility, EU MDR implementation delays, and Japanese reimbursement compression — sit outside the modeled envelope. Practitioners should keep alternative scenarios live as pharmacomechanical protocol adoption and China NMPA review channel evolution reshape competitive dynamics.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Minimally Invasive Laser Therapy Devices Market
Medical Devices
Rib Fracture Repair Systems Market
Medical Devices
PET Injectors Market
Medical Devices
Bone Power Tools Market
Medical Devices
Medication Management System Market
Medical Devices
Cholesterol Monitors Market
Medical Devices
Electric Massage Equipment Market
Medical Devices
Medical Germicidal Lamps Market
Medical Devices
Europe Insulin Pumps Market
Medical Devices
Global Hydrogel Based Drug Delivery System Market
Medical Devices
Global Large Volume Wearable Injectors Market
Medical Devices
Bone Allografts Market
Medical Devices
Drug Delivery Devices Market
Medical Devices
Injection Practice Pad Market
Medical Devices
Hysterectomy Devices Market
Medical Devices
Global Organs-On-Chips Market