
 Agriculture Solar Water Pumps Market | 2026-2036
Agriculture Solar Water Pumps Market Size, Share, and Industry Trends Forecast 2026-2036
Agriculture Solar Water Pumps Market Insights
The EU Green Deal is broadening the addressable market for solar-powered irrigation across member states with stringent carbon-reduction benchmarks for agricultural inputs. Grundfos leverages its Danish engineering heritage to dominate high-efficiency submersible system design. Shakti Pumps anchors the Indian market through deep backward integration into motor and controller manufacturing. LORENTZ sustains technology leadership in DC brushless pump architectures optimized for variable solar irradiance.
Agriculture solar water pumps are photovoltaic-driven fluid displacement systems, typically comprising a solar array, maximum power point tracker, motor controller, and either helical rotor or multistage centrifugal pump head, engineered to lift groundwater or surface water for crop irrigation without grid dependency. Submersible pumps occupy the largest installed base owing to superior lift capacity in deep borewell applications across arid and semi-arid farming zones. Surface pumps represent the fastest-expanding category in small-scale horticulture and aquaculture settings where suction depth remains shallow and capital constraints predominate. Fixed installations command the dominant share of power-rated deployments, though portable configurations gain traction among seasonal vegetable cultivators requiring relocation across fragmented landholdings.
India's Ministry of New and Renewable Energy administers the PM-KUSUM component dedicated to standalone solar pumps, while the Bureau of Indian Energy Standards mandates efficiency benchmarks for solar photovoltaic water pumping systems. REACH compliance in Europe restricts certain elastomer and coating chemistries used in pump housings, redirecting procurement toward certified suppliers. Stakeholders must monitor evolving subsidy disbursement timelines and local content requirements, as these mechanisms determine effective equipment cost and manufacturer eligibility across priority deployment territories.
Market Dynamics
Groundwater depletion mandates across arid agricultural zones are forcing a wholesale shift from diesel and grid-tied irrigation toward photovoltaic-powered pumping infrastructure, with subsidy disbursement velocity determining effective demand timing.
Growth Catalysts
- PM-KUSUM Component C:India's standalone solar pump subsidy program covers up to 60 percent of capital costs for farmers in groundwater-stressed states, accelerating off-grid adoption in Rajasthan and Gujarat.
- Brushless DC motor architectures:Permanent magnet synchronous designs eliminate commutator friction losses, extending operational lifespan in variable irradiance conditions across Sub-Saharan cooperatives.
- EU Green Deal carbon benchmarks:Member state agricultural decarbonization targets are redirecting public procurement toward solar irrigation systems in Spain, Italy, and Greece.
Market Restraints
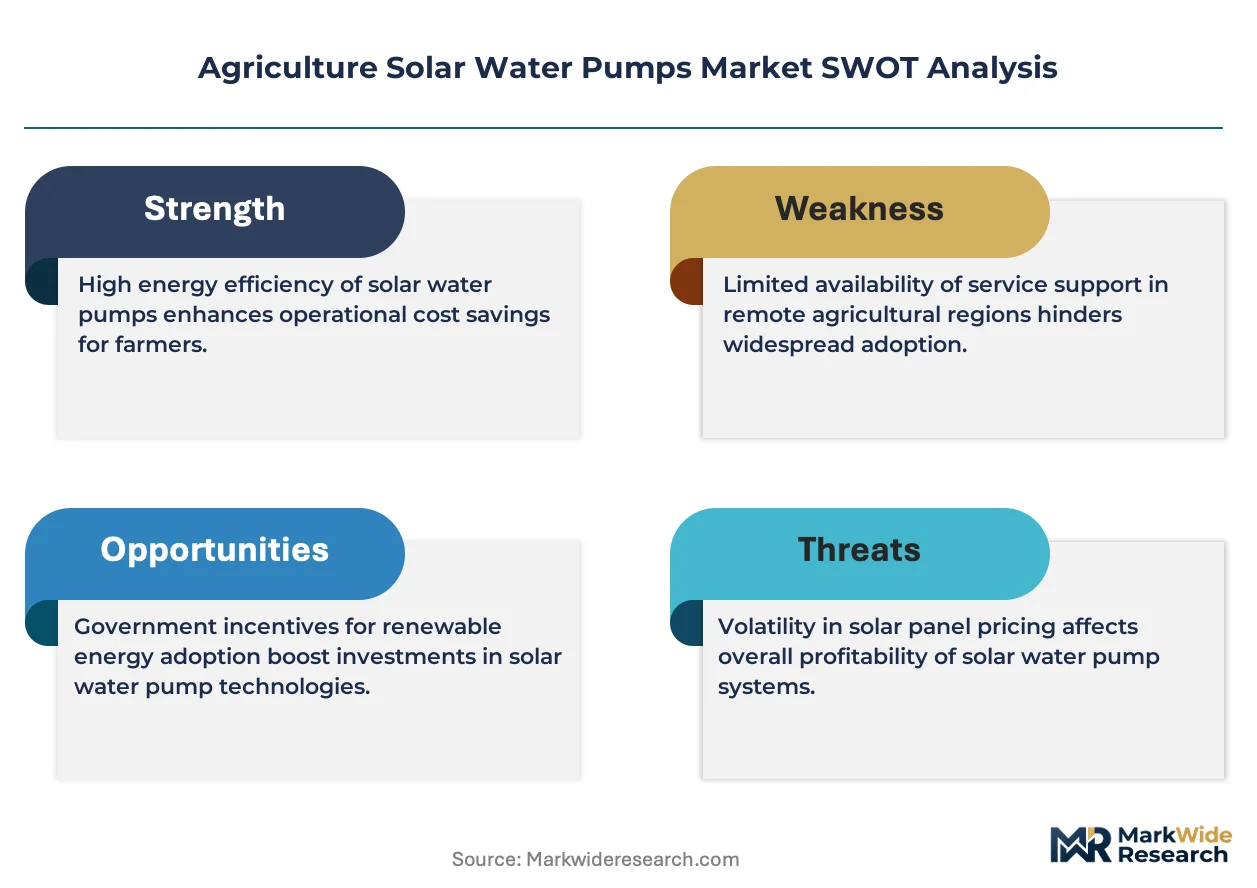
- Polysilicon price volatility:Solar module input costs fluctuate with Chinese manufacturing capacity, compressing system integrator margins and delaying rural deployment timelines.
- Borewell depth technical limits:Submersible pump lift capacity plateaus beyond 200 meters, excluding deep aquifer access in parts of the Sahel and Deccan Plateau.
- REACH compliance redirection:European restrictions on elastomer chemistries in pump housings force manufacturers toward certified suppliers, elongating procurement cycles.
Strategic Opportunities
- Portable surface pump configurations:Seasonal vegetable cultivators across India's fragmented landholdings require relocatable systems, opening a fast-expanding product category.
- Aquaculture integration:Shrimp and freshwater fish farms in Vietnam and Indonesia represent an underpenetrated demand vertical for shallow-lift solar circulation systems.
- Maximum Power Point Tracker convergence with IoT:Real-time irradiance optimization combined with remote monitoring platforms enables predictive maintenance service models.
Industry Challenges
- Skilled technician scarcity:Solar pump installation and controller troubleshooting require hybrid electrical-mechanical competencies absent in traditional agricultural equipment service networks.
- BIS certification timelines:India's Bureau of Indian Standards efficiency testing protocols create six-to-nine-month product approval delays, freezing inventory deployment.
- Legacy diesel pump retrofit complexity:Existing borewell infrastructure often requires casing diameter modifications to accommodate submersible solar pump dimensions.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Agriculture Solar Water Pumps Market |
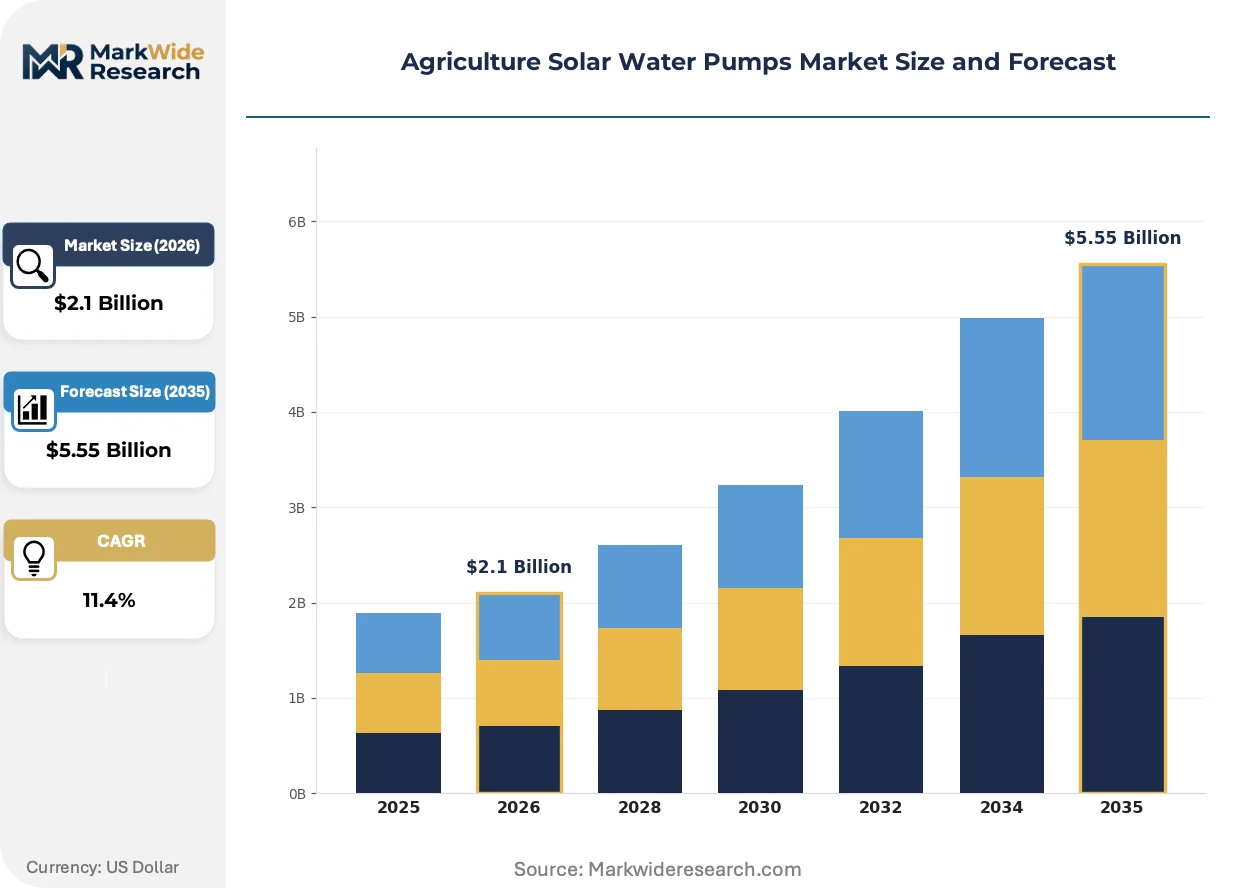
| Market Size in 2026 | $2.1 Billion |
| Market Size in 2035 | $5.55 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Submersible Pumps, Surface Pumps, Centrifugal Pumps, Diaphragm Pumps End Use Industry: Agriculture, Horticulture, Landscaping, Aquaculture Power Rating: 1 HP, 2 HP, 3 HP, 5 HP Installation Type: Fixed Installation, Portable Installation, Semi-Portable Installation, Temporary Installation |
| Companies Covered | Shakti Pumps, Grundfos, Xylem, KSB, Waaree Energies Ltd, Franklin Electric, LORENTZ, Tata Power Solar, Kirloskar Brothers Ltd, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Agriculture Solar Water Pumps Market Trends and Innovations
Photovoltaic irrigation hardware is converging with digital control layers and circular material standards, compressing total cost of ownership while expanding addressable farmer segments beyond early adopters.
Permanent magnet synchronous motors paired with variable frequency drives are rewriting efficiency benchmarks for deep-borewell applications. Smallholder cooperatives in Kenya and Tanzania are deploying these systems at accelerating pace. The technology is rewriting competitive positioning by enabling smaller solar array footprints for equivalent hydraulic output.
REACH restrictions on perfluorinated compounds and heavy-metal coatings are redirecting European procurement toward certified polymer suppliers. Pump manufacturers serving France and Germany now face mandatory material disclosure requirements. Surface pump suppliers serving horticulture segments are responding fastest due to simpler housing geometries.
Farmer purchasing committees in Gujarat and Maharashtra are consolidating procurement through district-level cooperative federations, bypassing traditional equipment dealers. These aggregators negotiate volume discounts and standardized service terms directly with manufacturers. The pattern is most visible in groundwater-stressed districts where PM-KUSUM awareness campaigns have concentrated demand formation.
Agriculture Solar Water Pumps Market Segmentation
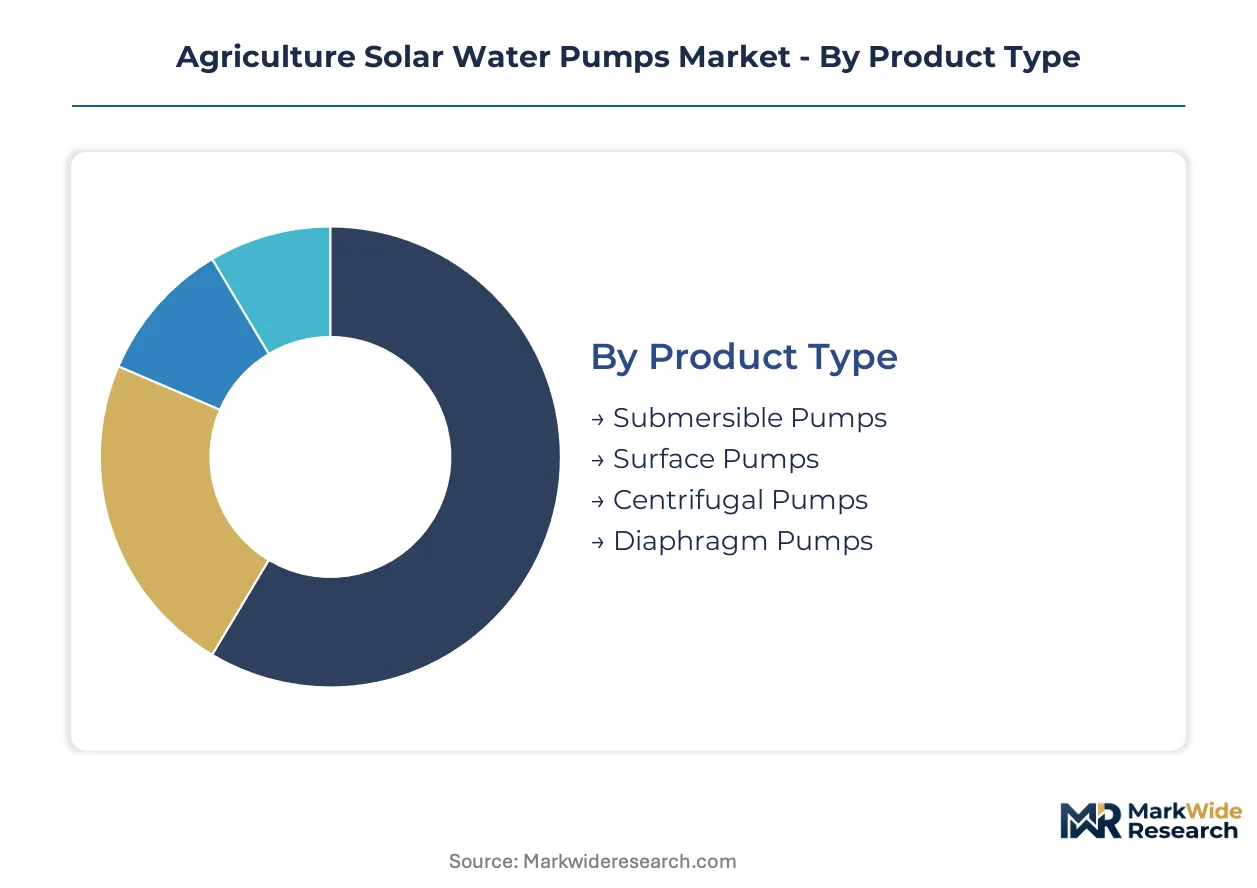
Segmentation in agriculture solar water pumps reveals how hydraulic performance requirements, mobility needs, and farm-scale economics fragment procurement patterns. Equipment selection hinges on borewell depth, crop water intensity, and subsidy eligibility rather than brand preference alone.
Product Type:
Standalone pump heads dominate deep groundwater extraction, while surface configurations serve embedded irrigation networks where suction lift remains minimal.
- Submersible Pumps:Multistage centrifugal or helical rotor designs operate below dynamic water levels exceeding 100 meters. Demand concentrates in Gujarat and Rajasthan where aquifer depletion forces deeper drilling and PM-KUSUM subsidies offset capital intensity.
- Surface Pumps:Self-priming centrifugal units deploy at suction depths below 8 meters for canal-fed horticulture. Smallholder cooperatives across Sub-Saharan Africa favor these for shallow river intakes and mobile deployment across fragmented plots.
- Centrifugal Pumps:Radial flow impellers deliver high discharge rates for flood irrigation of rice and sugarcane.
- Diaphragm Pumps:Positive displacement mechanisms handle high-viscosity water or mild abrasives in drip filtration systems.
Submersible pumps lead volumes today; surface pumps are gaining share fastest.
End Use Industry:
Cost tier stratification separates subsidy-dependent staple crop irrigation from premium horticulture and export-oriented aquaculture.
- Agriculture:Open-field cereal and oilseed cultivation consumes the largest installed base of 3-5 HP submersible systems. India's groundwater-stressed districts drive replacement of diesel pumps through PM-KUSUM Component C disbursements.
- Horticulture:Drip and sprinkler networks demand precise pressure control and variable flow modulation. Polyhouse clusters in Maharashtra and Karnataka specify surface pumps with integrated maximum power point trackers for micronutrient fertigation cycles.
- Landscaping:Golf courses and municipal parks prioritize aesthetic integration and low-noise operation over hydraulic efficiency.
- Aquaculture:Shrimp farms in Vietnam and Indonesia require continuous water exchange at shallow lift heads.
Agriculture anchors revenue today; aquaculture is climbing the fastest.
Power Rating:
Application maturity curves diverge sharply between established 3-5 HP borewell segments and emerging sub-2 HP horticulture configurations.
- 3 HP:Balanced flow-head characteristics suit medium-depth borewells for cotton and groundnut cultivation. Rajasthan's cooperative federations consolidate procurement at this rating for standardized service contracts.
- 5 HP:High-discharge capacity serves flood irrigation and large-diameter borewells in the Indo-Gangetic plain. BIS efficiency testing protocols create approval bottlenecks that freeze inventory deployment for this premium segment.
- 1 HP:Compact arrays suit kitchen gardens and rooftop horticulture with minimal hydraulic demand.
- 2 HP:Mid-range capacity bridges smallholder vegetable plots and marginal groundwater access.
3 HP leads deployment today; 1 HP is expanding most quickly.
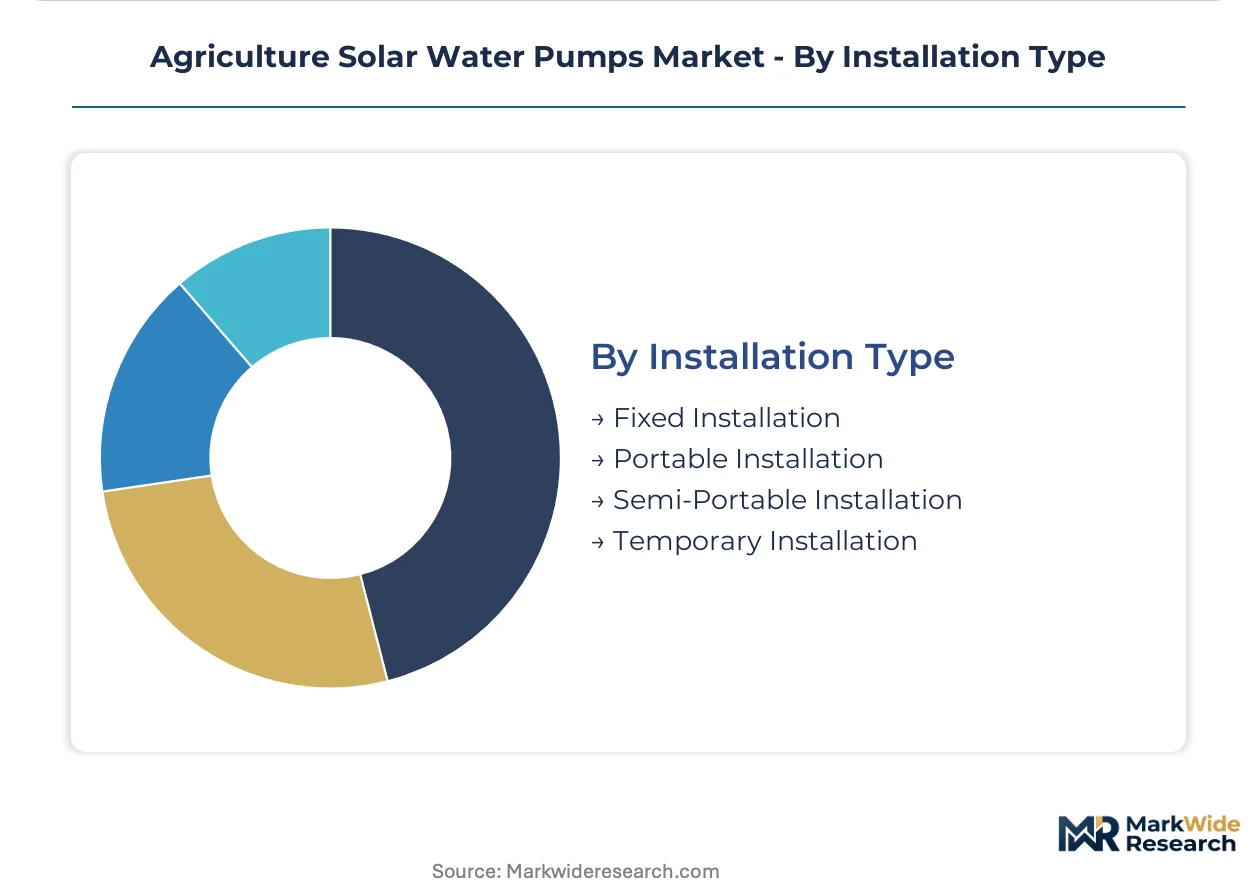
Installation Type:
Customer mobility requirements split procurement between permanent asset investments and seasonal rental markets.
- Fixed Installation:Permanent solar array and pump mounting on reinforced borewell platforms maximizes system longevity. Gujarat's farmer purchasing committees favor these for long-term groundwater access security in regulated extraction zones.
- Portable Installation:Skid-mounted or trolley-based systems relocate across fragmented landholdings for seasonal vegetable rotations. Kenya's smallholder cooperatives deploy these for flexible water access without multiple borewell investments.
- Semi-Portable Installation:Detachable array frames with fixed pump housings split the mobility-cost tradeoff.
- Temporary Installation:Rental-market configurations serve annual cropping cycles without capital ownership.
Fixed installation dominates deployments today; portable systems are gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
India pioneered mass-scale solar pump deployment through the PM-KUSUM scheme, establishing the operational template that Sub-Saharan cooperatives and Southeast Asian aquaculture operators now adapt to local conditions.
India
Gujarat and Rajasthan dominate installed capacity where groundwater depletion intersects with high solar irradiance. The Ministry of New and Renewable Energy administers PM-KUSUM Component C subsidies covering up to 60 percent of capital costs. Farmer purchasing committees in Ahmedabad and Jodhpur districts consolidate procurement through cooperative federations, bypassing traditional equipment dealers.
Kenya
Smallholder irrigation cooperatives in the Rift Valley and Eastern Province drive demand for portable surface pump configurations. The country's national renewable energy regulator channels development finance toward off-grid agricultural electrification. Nairobi-based equipment distributors service fragmented landholdings across Kiambu and Machakos counties where seasonal vegetable rotations require relocatable systems.
Germany
EU Green Deal carbon benchmarks redirect public procurement toward solar irrigation in Bavarian and Baden-Württemberg horticulture clusters. ECHA REACH compliance restricts elastomer chemistries in pump housings, elongating procurement cycles toward certified suppliers. Stuttgart-area engineering firms integrate maximum power point trackers with IoT monitoring platforms for precision viticulture applications.
Vietnam
Shrimp farms in the Mekong Delta represent underpenetrated demand for shallow-lift solar circulation systems. The country's national standards body mandates efficiency testing protocols for photovoltaic water pumping equipment. Can Tho and Soc Trang provinces host expanding aquaculture zones where continuous water exchange requirements outpace grid infrastructure extension.
United States
California's Central Valley almond and pistachio growers deploy submersible systems where SGMA groundwater sustainability regulations restrict diesel pumping. The EPA administers agricultural equipment emissions standards that elevate photovoltaic alternatives. Fresno and Kern counties concentrate deployment through irrigation districts negotiating volume procurement contracts.
Agriculture Solar Water Pumps Market Competitive Landscape
Premium-margin players sit above commodity-margin players across motor efficiency and controller integration capabilities, with Danish and German engineering heritage commanding pricing power in deep-borewell segments. The vendor base stratifies into three tiers: integrated manufacturers controlling motor and controller production, system integrators assembling imported components, and regional fabricators serving price-sensitive smallholder markets. Two strategic archetypes dominate: backward-integrated specialists and technology licensors. Competitive intensity concentrates on BIS certification velocity in India and REACH-compliant material sourcing for European contracts.
Within the integrated manufacturing tier, Shakti Pumps anchors the Indian market through captive motor and controller production, while Grundfos occupies the premium engineering position rooted in Danish submersible system heritage. LORENTZ exemplifies the technology-focused archetype with DC brushless pump architectures. These three companies represent the competitive poles—volume-scale Indian fabrication, European engineering premium, and solar-native specialization—that structure procurement decisions across groundwater-stressed agricultural zones.
| Leading Market Players |
|---|
| Shakti Pumps |
| Grundfos |
| Xylem |
| KSB |
| Waaree Energies Ltd |
| Franklin Electric |
| LORENTZ |
| Tata Power Solar |
| Kirloskar Brothers Ltd |
| Others |
Pricing and Supply Chain Analysis
Certification-grade divergence between BIS-validated systems and uncertified imports splits procurement economics across Indian states while simultaneously reshaping supplier sourcing footprints toward in-house motor production. PM-KUSUM subsidy disbursement velocity amplifies this bifurcation, as eligibility hinges on Bureau of Indian Standards compliance that commodity assemblers cannot access without captive manufacturing investment.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels anchors the market, with differentiation driven by motor efficiency certification and after-sales service bundling. Cost compression in the economy tier is intensifying because polysilicon input volatility squeezes system integrator margins. Smallholder cooperatives in Sub-Saharan Africa exhibit highest price sensitivity, while European horticulture clusters under EU Green Deal mandates show lowest sensitivity to capital outlay.
Supply Chain Analysis
Single-source vulnerability sits with Chinese polysilicon wafer supply that feeds module assembly across India, Vietnam, and Germany. Manufacturing draws from permanent magnet rare earth processing in China, copper winding production in India, and controller semiconductor fabrication in Taiwan. Tariff exposure on solar module imports into India threatens margin structures. Distribution runs through district-level cooperative federations that consolidate farmer demand and bypass traditional dealer networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a regulatory compounder where India's PM-KUSUM scheme creates sustained demand visibility through multi-year subsidy allocation windows.
For Market Incumbents: To counter polysilicon cost volatility and commodity assembler encroachment, deepen backward integration into permanent magnet motor manufacturing and accelerate BIS certification velocity for 5 HP premium segments. Prioritize captive controller production to defend margin position against system integrators sourcing from Shenzhen. For New Entrants and Emerging Players: Launch via aquaculture-focused shallow-lift surface pump configurations in Vietnam's Mekong Delta and Indonesia's shrimp farming corridors. Portable systems for Kenya's seasonal vegetable cooperatives offer the most penetrable white space, with pay-per-use rental models reducing capital barriers for fragmented landholders. For Investors and Strategic Acquirers: Asymmetric upside sits with mid-scale Indian manufacturers possessing captive motor production and active BIS certification pipelines. Five-to-ten-year viability favors those consolidating district-level service networks. Watch PM-KUSUM Component C disbursement acceleration as the definitive demand inflection signal.| Strategic Initiative | Industry Significance |
|---|---|
| BIS Certification Acceleration | Unlocks PM-KUSUM subsidy eligibility and freezes out uncertified competitors in Rajasthan and Gujarat procurement. |
| Permanent Magnet Motor Integration | Reduces solar array footprint requirements and rewrites efficiency benchmarks for deep-borewell applications. |
| District Cooperative Federation Partnerships | Bypasses traditional dealer markups and secures volume procurement contracts through farmer purchasing committees. |
| IoT-Enabled MPPT Platform Development | Enables predictive maintenance service models and recurring revenue streams from remote monitoring subscriptions. |
| REACH-Compliant Material Sourcing | Mandatory for European horticulture contracts and redirects procurement toward certified polymer suppliers. |
Research Methodology
Bottom-up farmer segmentation modeling reconciled against top-down manufacturer shipment tracking forms the analytical core of this study. Primary interviews with solar pump system integrators, cooperative federation procurement officers, Bureau of Indian Standards certification specialists, and MNRE subsidy administrators combined with secondary validation from customs trade records, MNRE disbursement databases, and ECHA REACH compliance registries. Top-down triangulation against module import data and motor production statistics anchors volume estimates.
Historical trendline analysis of subsidy disbursement velocity and installed capacity growth rates informed projection parameters across the analysis window. Segmentation dimensions modeled include product type, power rating, installation mobility, and end-use application intensity. CAGRs derive from regression analysis of capital cost trajectories, efficiency improvement curves, and regulatory milestone timing. Forecast inputs incorporate polysilicon price volatility scenarios and PM-KUSUM budget allocation patterns.
Forecast precision tightens around the base case; tail outcomes carry wider variance under abrupt subsidy suspension or severe polysilicon supply disruption. Projections reflect documented assumptions regarding regulatory continuity and technology cost curves. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Solar Power Systems
Solar Cell (Photovoltaic) Module Market
Solar Power Systems
Solar Panel Market
Solar Power Systems
Residential Solar Panels Market
Solar Power Systems
Australia Solar Market
Solar Power Systems
Photovoltaic Solar Kits Market
Solar Power Systems
Bifacial Solar Market
Solar Power Systems
Solar PV Carport Market
Solar Power Systems
On-Grid Solar Inverter Market
Solar Power Systems
United Kingdom Distributed Solar Power Generation Market
Solar Power Systems
Solar Cell Busbar Market
Solar Power Systems
Czech Republic Solar Energy Market
Solar Power Systems
Qatar Solar Energy Market
Solar Power Systems
Solar Panel Glass Market
Solar Power Systems
Portugal Solar Energy Market
Solar Power Systems
Europe Solar Backsheet Market
Solar Power Systems
Thin-Film Photovoltaic Market