
 India Rooftop Solar Market | 2026-2036
India Rooftop Solar Market Size, Share, and Industry Trends Forecast 2026-2036
India Rooftop Solar Market Outlook
Gujarat's manufacturing corridor is rewriting India's solar module supply geography. Waaree Energies leverages its Gujarat production base to dominate domestic module supply for rooftop projects. Tata Power Solar anchors its integrated EPC and financing model across residential and commercial segments. Adani Solar competes through backward integration into polysilicon and wafer production, cutting import dependence.
Rooftop solar denotes photovoltaic systems installed on building surfaces, typically comprising crystalline silicon modules rated between 300-550 watts, string inverters with 98% peak efficiency, and galvanized aluminum mounting structures engineered for wind loads up to 150 km/h. These systems convert incident solar radiation into grid-compatible alternating current for on-site consumption or export. Grid-tied configurations without battery storage command the largest installed base due to lower capital outlay and simpler operations, while hybrid systems pairing solar with lithium-ion storage are capturing margin pools in premium commercial and industrial applications where backup power commands tariff premiums. The agricultural end-user segment remains structurally underpenetrated despite favorable load profiles, constrained by fragmented land titles and limited access to institutional credit.
The Ministry of New and Renewable Energy's rooftop solar programme mandates net metering standards that determine project economics across states, while the Bureau of Indian Standards enforces module certification protocols that filter import quality. State electricity regulatory commissions in Maharashtra, Karnataka, and Tamil Nadu set divergent wheeling and banking charges that fragment returns. Stakeholders must track state-level renewable purchase obligation enforcement intensity and distribution company financial health as these determine offtake reliability and payment timelines.
Market Dynamics
Net metering regulations across Indian states are fragmenting project economics, with distribution company financial health determining offtake reliability and payment timelines for rooftop solar developers.
Growth Catalysts
- Central Financial Assistance:The Ministry of New and Renewable Energy's rooftop solar subsidy scheme reduces capital outlay for residential consumers, accelerating deployment in tier-2 and tier-3 cities.
- Commercial Real Estate:Developers in Mumbai and Bengaluru are mandating solar-ready building designs, creating built-in demand for grid-tied photovoltaic systems across new construction.
- Polysilicon Localization:Backward integration into wafer and cell production is cutting import dependence, improving module availability for domestic rooftop installers.
Market Restraints
- Aluminum Price Volatility:Galvanized aluminum mounting structures face input cost pressure, compressing margins for engineering-procurement-construction contractors.
- Distribution Company Risk:State electricity regulatory commissions in Maharashtra and Tamil Nadu set divergent wheeling charges, fragmenting returns across state boundaries.
- Grid Integration Limits:Weak rural distribution infrastructure caps export capacity for agricultural feeders, constraining net metering eligibility.
Strategic Opportunities
- Agricultural Electrification:Fragmented land titles and limited institutional credit access have left the agricultural segment structurally underpenetrated despite favorable daytime load profiles.
- Hybrid Storage Convergence:Lithium-ion battery pairing with rooftop systems is capturing premium margin pools in commercial and industrial applications where backup power commands tariff premiums.
- State RPO Enforcement:Intensified renewable purchase obligation tracking by state electricity regulatory commissions is creating compliance-driven demand from obligated entities.
Industry Challenges
- Skilled Installer Scarcity:Certified system design and grid interconnection expertise remains concentrated in Gujarat, Rajasthan, and Maharashtra, limiting deployment velocity elsewhere.
- Bureau of Indian Standards Certification Lag:Module testing protocols and inverter compliance timelines create procurement bottlenecks for projects targeting subsidy eligibility.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | India Rooftop Solar Market |
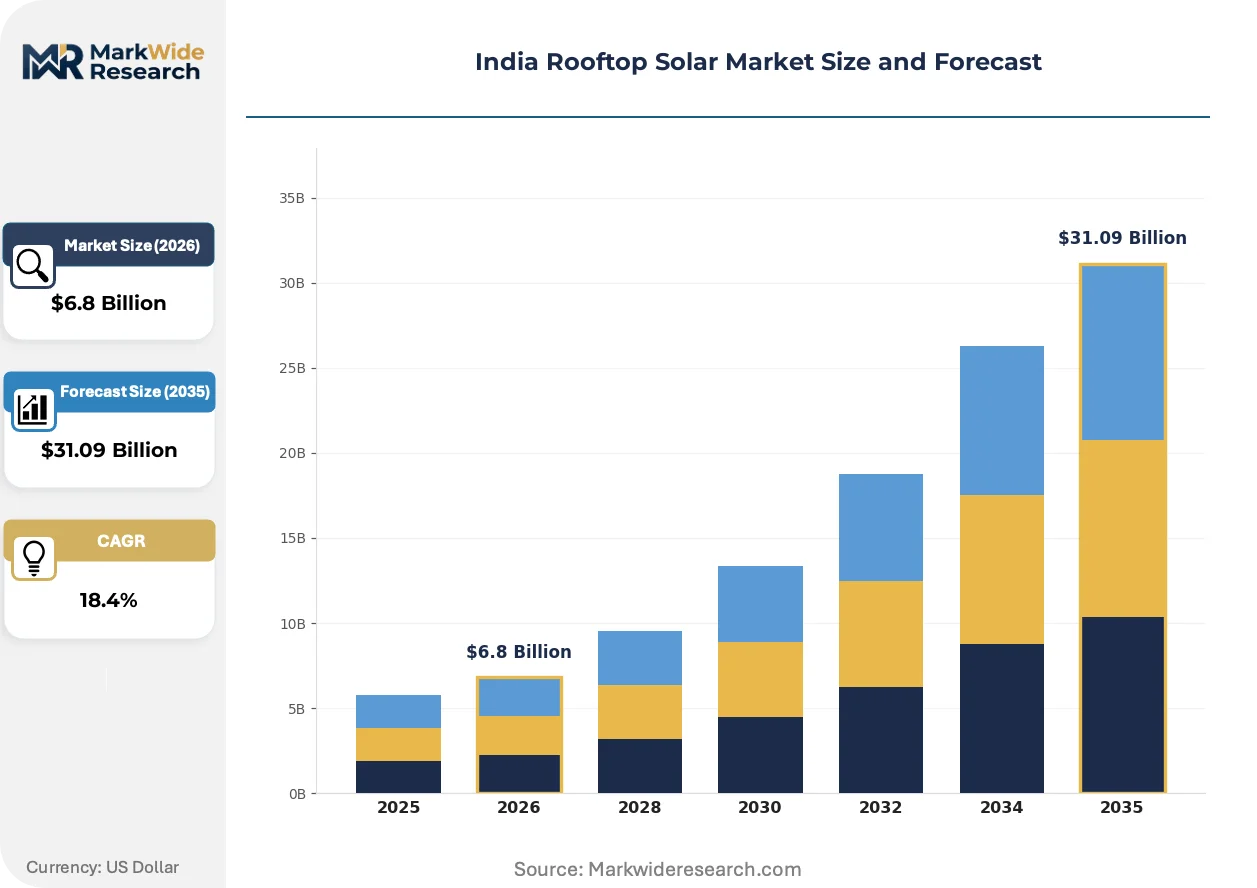
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $31.09 Billion |
| CAGR (2026 – 2036) | 18.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | System Type: Grid-Tied, Off-Grid, Hybrid, Floating End User: Residential, Commercial, Industrial, Agricultural Installation Type: Built-Up Roof, Ground Mount, Carport, Integrated Component: Inverter, Solar Panel, Battery, Mounting Structure |
| Companies Covered | Vikram Solar, Saatvik Green Energy Limited, Tata Power Solar, Azure Power, Sterling & Wilson, Adani Solar, ACME Solar, Jakson Solar, Waaree Energies, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
India Rooftop Solar Market Strategic Shifts
Module-level power electronics and remote monitoring platforms are compressing operational expenditure structures while reshaping competitive differentiation among rooftop solar installers.
Module-level power electronics (MLPE) technology, comprising power optimizers and microinverters, maximizes energy harvest from partially shaded rooftop configurations. Commercial real estate developers in Bengaluru and Mumbai are specifying MLPE-equipped systems for premium projects. This technology is digitizing performance monitoring granularity, enabling predictive maintenance contracts and remote fault detection that reduce truck-roll costs for distributed asset operators.
The Ministry of New and Renewable Energy's revised net metering standards, limiting net metering to systems below specified capacity thresholds, are redirecting commercial and industrial customers toward gross metering arrangements. State electricity regulatory commissions in Karnataka and Tamil Nadu have issued divergent implementation orders, creating regulatory arbitrage opportunities. Large commercial rooftop developers are responding by restructuring power purchase agreements to capture available banking provisions.
Building-integrated photovoltaics (BIPV) procurement is displacing conventional retrofit installations in new commercial construction, with architects specifying solar glass and facade-integrated modules as primary building materials. Premium office developments in Mumbai's Bandra-Kurla Complex and Bengaluru's Electronic City are mandating BIPV compliance in design briefs. This specification shift is most visible in green building certification-driven projects targeting Indian Green Building Council ratings.
India Rooftop Solar Market Segmentation
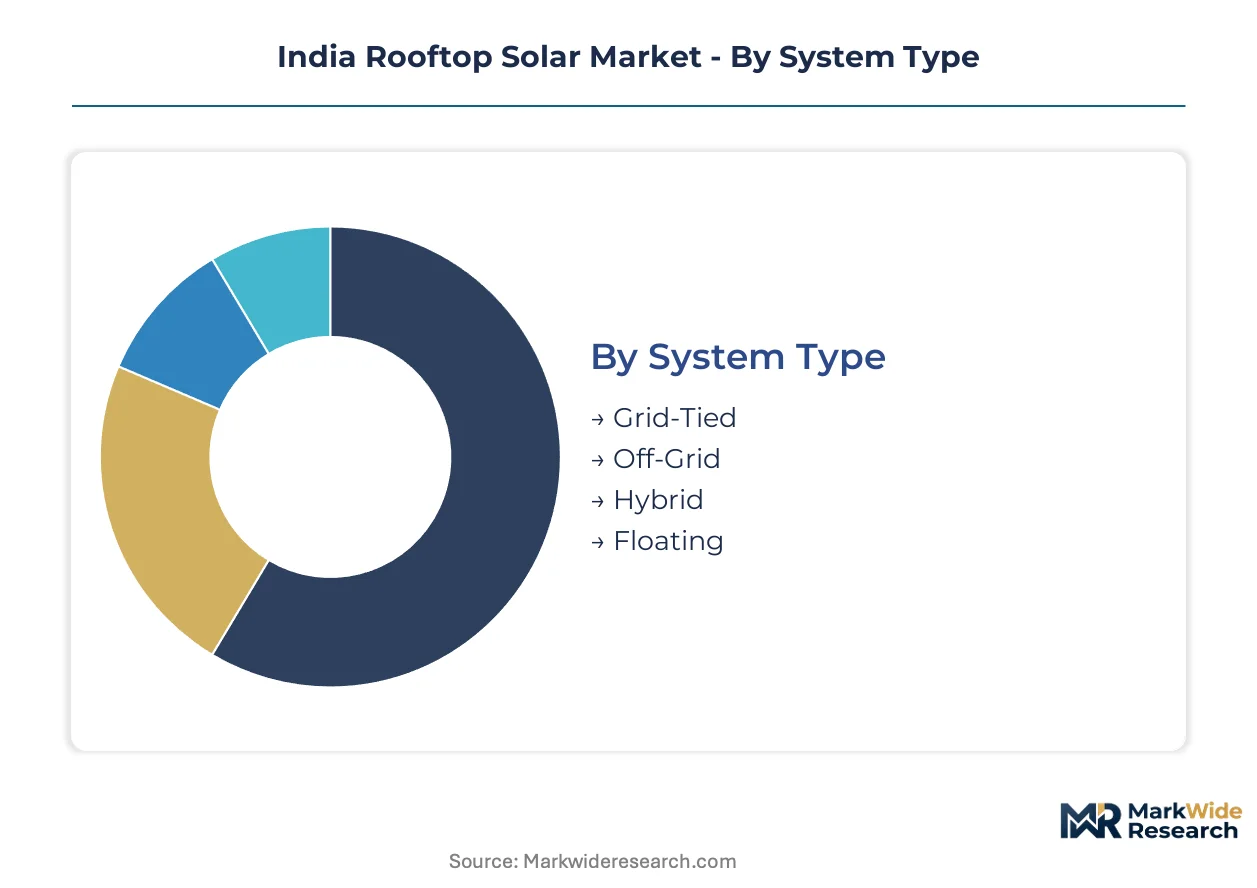
India's rooftop solar market fragments across four structural dimensions that determine capital intensity, regulatory treatment, and customer acquisition economics. System architecture and end-use profiles drive divergent margin pools, while installation method and component sourcing reshape competitive positioning for engineering-procurement-construction contractors.
System Type:
Mature configurations dominate installed base; emerging hybrid architectures are capturing premium commercial applications.
- Grid-Tied:Direct grid-interconnected systems without battery storage utilize string inverters with 98% peak efficiency. Commercial real estate developers in Mumbai and Bengaluru specify these for new construction to minimize capital outlay and simplify operations.
- Hybrid:Solar-plus-lithium-ion configurations pair rooftop photovoltaic arrays with battery storage for backup power. Premium commercial and industrial customers in Gujarat and Maharashtra pay tariff premiums for resilience against distribution company outages.
- Off-Grid:Standalone systems serve rural locations beyond distribution infrastructure reach, constrained by high battery replacement costs and limited institutional financing access.
- Floating:Reservoir-mounted photovoltaic arrays address land scarcity constraints in water-abundant states, though deployment remains nascent outside Kerala and Tamil Nadu pilot projects.
Grid-tied systems retain volume leadership; hybrid configurations hold the steepest expansion curve.
End User:
Customer type determines subsidy eligibility, net metering access, and financing instrument availability.
- Commercial:Office buildings, retail complexes, and hospitality properties deploy 100-kilowatt to megawatt-scale systems under power purchase agreements or direct ownership. Developers in Mumbai's Bandra-Kurla Complex and Bengaluru's Electronic City mandate solar-ready designs.
- Industrial:Manufacturing facilities exploit favorable daytime load profiles to offset grid purchases. Textile processors in Surat and automotive suppliers in Pune anchor demand clusters.
- Residential:Individual households access Ministry of New and Renewable Energy capital subsidies that reduce upfront costs, accelerating deployment in tier-2 and tier-3 cities.
- Agricultural:Fragmented land titles and limited access to institutional credit have left this segment structurally underpenetrated despite favorable irrigation pump load profiles.
Commercial installations retain volume leadership; industrial applications hold the steepest expansion curve.
Installation Type:
Mounting method shapes engineering complexity, wind load requirements, and rooftop structural reinforcement needs.
- Built-Up Roof:Ballasted or mechanically attached systems on concrete or membrane roofs dominate retrofit deployment across existing commercial stock in Maharashtra and Karnataka.
- Ground Mount:Elevated structures on adjacent land serve industrial campuses with surplus plot availability, common in Rajasthan's manufacturing zones.
- Carport:Elevated canopy installations dual-purpose parking coverage with generation, gaining specification in premium commercial developments.
- Integrated:Building-integrated photovoltaics displace conventional retrofit in new construction, with solar glass specified as primary building material in green building certification-driven projects.
Built-up roof installations retain volume leadership; integrated systems hold the steepest expansion curve.
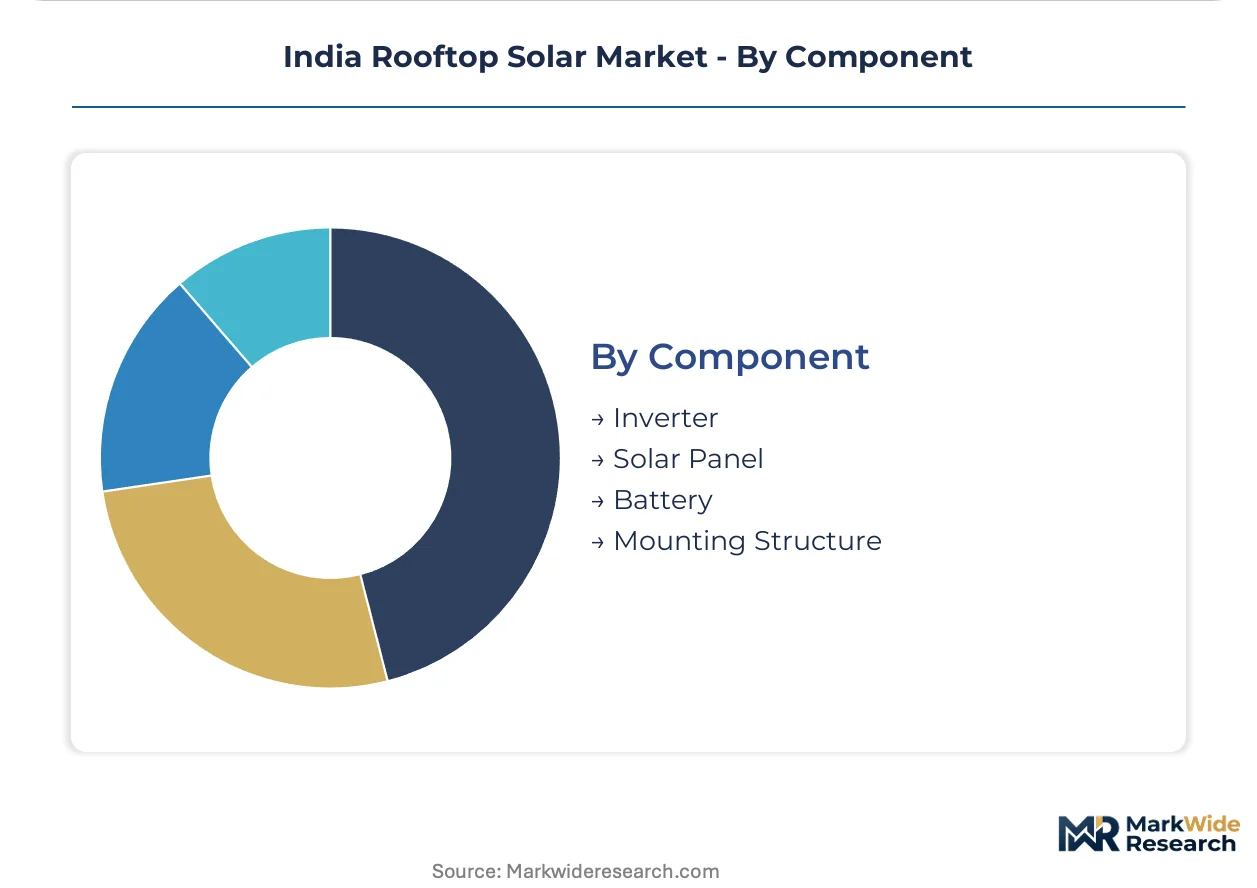
Component:
Supply chain localization and import dependence vary sharply across the bill of materials.
- Solar Panel:Crystalline silicon modules rated 300-550 watts constitute the largest cost line item. Waaree Energies and Tata Power Solar anchor domestic crystalline silicon supply.
- Inverter:String and central inverters with 98% peak efficiency face Bureau of Indian Standards certification timelines that create procurement bottlenecks.
- Battery:Lithium-ion storage pairing with rooftop systems captures premium margin pools where backup power commands tariff premiums.
- Mounting Structure:Galvanized aluminum structures engineered for 150 km/h wind loads face input cost pressure from aluminum price volatility.
Solar panels retain volume leadership; battery components hold the steepest expansion curve.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
CEA regulations anchor deployment patterns across Indian states, with state electricity regulatory commissions determining wheeling charges and banking provisions that reshape project returns. MNRE subsidy allocations flow disproportionately toward states demonstrating distribution infrastructure readiness. Sub-regional concentration tracks manufacturing corridor proximity, grid reliability, and commercial real estate development velocity.
Gujarat
Industrial load centers in Ahmedabad and Vadodara drive commercial rooftop demand from textile processors and chemical manufacturers. Gujarat Urja Vikas Nigam Limited administers net metering regulations that permit 100% banking of surplus generation. Mundra and Hazira industrial corridors concentrate captive solar installations at manufacturing facilities seeking tariff arbitrage against grid purchases.
Maharashtra
Mumbai's Bandra-Kurla Complex and Pune's automotive supplier clusters anchor megawatt-scale commercial deployments. Maharashtra Electricity Regulatory Commission imposes wheeling charges that fragment returns for cross-subsidy category consumers. Thane and Navi Mumbai commercial real estate developers mandate solar-ready specifications in new construction permits.
Karnataka
Bengaluru's Electronic City and Whitefield IT corridors generate concentrated demand from data centers and technology campuses. Karnataka Electricity Regulatory Commission's gross metering orders for systems above 1 MW redirect large commercial consumers toward captive consumption models. Mysuru and Hubballi industrial estates are emerging as secondary deployment clusters for food processing and engineering units.
Rajasthan
Jodhpur and Jaipur industrial zones exploit high irradiation levels exceeding 5.5 kWh/m²/day for maximum capacity utilization factors. Rajasthan Electricity Regulatory Commission's renewable purchase obligation enforcement creates compliance-driven demand from distribution licensees. Bhiwadi and Neemrana manufacturing belts attract solar-plus-storage hybrid configurations for critical process continuity.
Tamil Nadu
Coimbatore textile clusters and Chennai automotive component parks deploy rooftop systems under open access arrangements. Tamil Nadu Generation and Distribution Corporation's banking restrictions limit surplus carryover to monthly settlement cycles. Tiruppur and Salem industrial concentrations are expanding deployment through group captive structures for small and medium enterprises.
India Rooftop Solar Market Competitive Environment
Integrated manufacturers and specialized engineering-procurement-construction contractors split the market along capital intensity and project execution capability lines. The vendor base concentrates in western India, with Gujarat and Maharashtra hosting module fabrication and installation expertise clusters. Three archetypes dominate: backward-integrated polysilicon-to-module producers, distributed EPC specialists with financing partnerships, and captive engineering arms of conglomerate energy divisions. Competitive intensity centers on module supply security and distribution company payment guarantee structures.
Among integrated manufacturers, Tata Power Solar and Adani Solar exemplify capital-intensive archetypes with in-house wafer and cell production. Waaree Energies anchors the specialized fabrication tier with Gujarat-based module supply dominance. These three occupy positions that reflect divergent strategic bets on supply chain depth versus EPC service breadth.
| Leading Market Players |
|---|
| Vikram Solar |
| Saatvik Green Energy Limited |
| Tata Power Solar |
| Azure Power |
| Sterling & Wilson |
| Adani Solar |
| ACME Solar |
| Jakson Solar |
| Waaree Energies |
| Others |
Value Chain & Pricing Dynamics
Polysilicon and wafer production concentration in China feeds directly into module cost structures for Indian rooftop installers, with domestic backward integration by Adani Solar and Waaree Energies capturing margin pools that otherwise leak to import channels. Aluminum price volatility in mounting structures and lithium-ion cell supply tightness are compressing EPC contractor margins while redirecting procurement toward long-term offtake contracts.
Pricing Analysis
Price spreads between Gujarat-based domestic module supply and imported Chinese alternatives range widely across Indian states, with Maharashtra and Karnataka buyers facing higher landed costs due to distribution logistics. Three-tier pricing structure across premium MLPE-equipped systems, standard string inverter configurations, and economy-grade off-grid kits separates commercial real estate developers from residential subsidy-eligible households. Pricing pressure stems from aluminum input cost volatility in galvanized mounting structures. Residential consumers accessing MNRE capital subsidies exhibit highest price sensitivity, while data center operators in Bengaluru prioritize resilience premiums over unit economics.
Supply Chain Analysis
Waaree Energies, Tata Power Solar, and Adani Solar anchor domestic module fabrication capacity, with cell and wafer production drawing from China, Vietnam, and limited captive Indian lines. Crystalline silicon ingots, silver paste for metallization, and lithium iron phosphate cells constitute critical input dependencies. Single-source vulnerability in polysilicon purification creates exposure to trade policy shifts. Distribution runs through EPC contractor networks with direct utility interconnection, bypassing traditional electrical wholesale channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is concentrating among commercial real estate developers in Mumbai and Bengaluru, with consolidated procurement mandates across multi-building portfolios squeezing EPC margins and favoring integrated module-to-installation providers.
For Market Incumbents: Build certification moats around Bureau of Indian Standards module testing and state-level DISCOM payment guarantee structures. Secure captive polysilicon supply through upstream partnerships to offset import tariff exposure. Defend against emerging EPC specialists by locking in commercial developer relationships through solar-ready building design partnerships.
For New Entrants and Emerging Players: Build out agricultural electrification capabilities targeting irrigation pump loads in fragmented land-title regions where institutional credit gaps have stalled incumbent penetration. Prioritize hybrid solar-plus-storage configurations for Bhiwadi and Neemrana manufacturing belts where process continuity commands tariff premiums. Go-to-market through group captive structures aggregating small and medium enterprise demand.
For Investors and Strategic Acquirers: Capital is best deployed toward EPC contractors with demonstrated DISCOM payment collection track records and module supply security through long-term manufacturer offtakes. Viability over the coming decade hinges on state electricity regulatory commission enforcement intensity for renewable purchase obligations. Watch for net metering policy reversals in Maharashtra and Tamil Nadu as inflection signals for commercial segment demand destruction.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Polysilicon | Adani Solar's captive wafer production cuts import dependence and secures module supply for rooftop EPC pipelines. |
| MLPE Technology Specification | Bengaluru commercial developers mandating power optimizers capture premium margins through predictive maintenance contracts. |
| Group Captive Structure Deployment | Tiruppur textile clusters aggregate SME demand to bypass gross metering thresholds and access net metering benefits. |
| Building-Integrated Photovoltaics Mandate | Mumbai's Bandra-Kurla Complex green building certifications drive solar glass specification as primary facade material. |
| DISCOM Payment Guarantee Programs | Gujarat Urja Vikas Nigam Limited's banking provisions reduce offtake risk and accelerate project finance closure. |
Study Parameters
Operator-level perspectives from EPC project managers, DISCOM planning officers, commercial real estate development executives, and MNRE subsidy administration officials anchored the qualitative base. Primary fieldwork combined with secondary validation against CEA capacity addition statistics, state electricity regulatory commission tariff orders, and MNRE rooftop solar programme disbursement records. Bottom-up installation volume estimates triangulated against top-down module shipment data from domestic manufacturers.
Scenario-bracketing around aluminum price volatility bands, DISOM financial health deterioration cases, and net metering policy reversal scenarios shaped the analytical framework across the projection horizon. Segmentation modeling incorporated system architecture, end-user category, installation method, and component sourcing dimensions. CAGRs derived from capacity utilization trends, subsidy allocation trajectories, and commercial real estate construction pipelines.
Stress conditions across polysilicon supply disruptions, state-level banking restriction implementations, and distribution infrastructure upgrade delays were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions regarding MNRE subsidy continuity and state RPO enforcement intensity. Cross-checking against Central Electricity Authority monthly capacity reports is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Solar Power Systems
US Solar Market
Solar Power Systems
Europe Solar Concentrator Market
Solar Power Systems
Residential Solar Panels Market
Solar Power Systems
Asia Pacific Solar Inverter Market
Solar Power Systems
Solar Panel Laminator Market
Solar Power Systems
Solar Module Market
Solar Power Systems
US Solar Power Meters Market
Solar Power Systems
Iran Solar Energy Market
Solar Power Systems
Floating Solar System Market
Solar Power Systems
Utility Scale PV Inverter Market
Solar Power Systems
High-Efficiency Solar Modules Market
Solar Power Systems
Mexico Solar Photovoltaic (PV) Market
Solar Power Systems
Mexico Solar Energy Market
Solar Power Systems
Residential Solar Shading System Market
Solar Power Systems
Qatar Solar Energy Market
Solar Power Systems
France Distributed Solar Power Generation Market