
 North America Solar Photovoltaic (PV) Market | 2026-2036
North America Solar Photovoltaic (PV) Market Size, Share, and Industry Trends Forecast 2026-2036
North America Solar Photovoltaic (PV) Market Analytics
Utility procurement is bifurcating from distributed generation as the dominant demand driver across the North America Solar Photovoltaic (PV) landscape. First Solar leverages its thin-film cadmium telluride platform to anchor utility-scale deployments across the southwestern United States. NextEra Energy sustains vertical integration from project development through grid interconnection, while Enphase Energy specializes in module-level power electronics for commercial and residential rooftops.
North America Solar Photovoltaic (PV) systems convert sunlight into direct-current electricity through semiconductor junctions, with crystalline silicon cells achieving conversion efficiencies above 21% in mass production and thin-film alternatives offering superior temperature coefficients for arid climates. The technology serves utility-scale generation, commercial load offset, and residential self-consumption across integrated and islanded configurations. C-Si Modules dominate installed capacity owing to supply chain scale and bankability, while Heterojunction cell architectures capture expanding share in premium efficiency segments. Ground-Mounted installations concentrate in utility pipelines, whereas Community Solar programs unlock access for renters and multi-tenant buildings across regulated state markets.
The US Federal Energy Regulatory Commission streamlines interconnection queue reform to accelerate utility-scale project completion, while the Environmental Protection Agency enforces domestic content thresholds tied to Inflation Reduction Act credit monetization. State-level renewable portfolio standards in California, New York, and Texas mandate escalating solar procurement obligations that reshape offtake contracting structures. Stakeholders must monitor interconnection cost allocation rulings and domestic content percentage escalations to preserve project finance viability and tax equity returns.
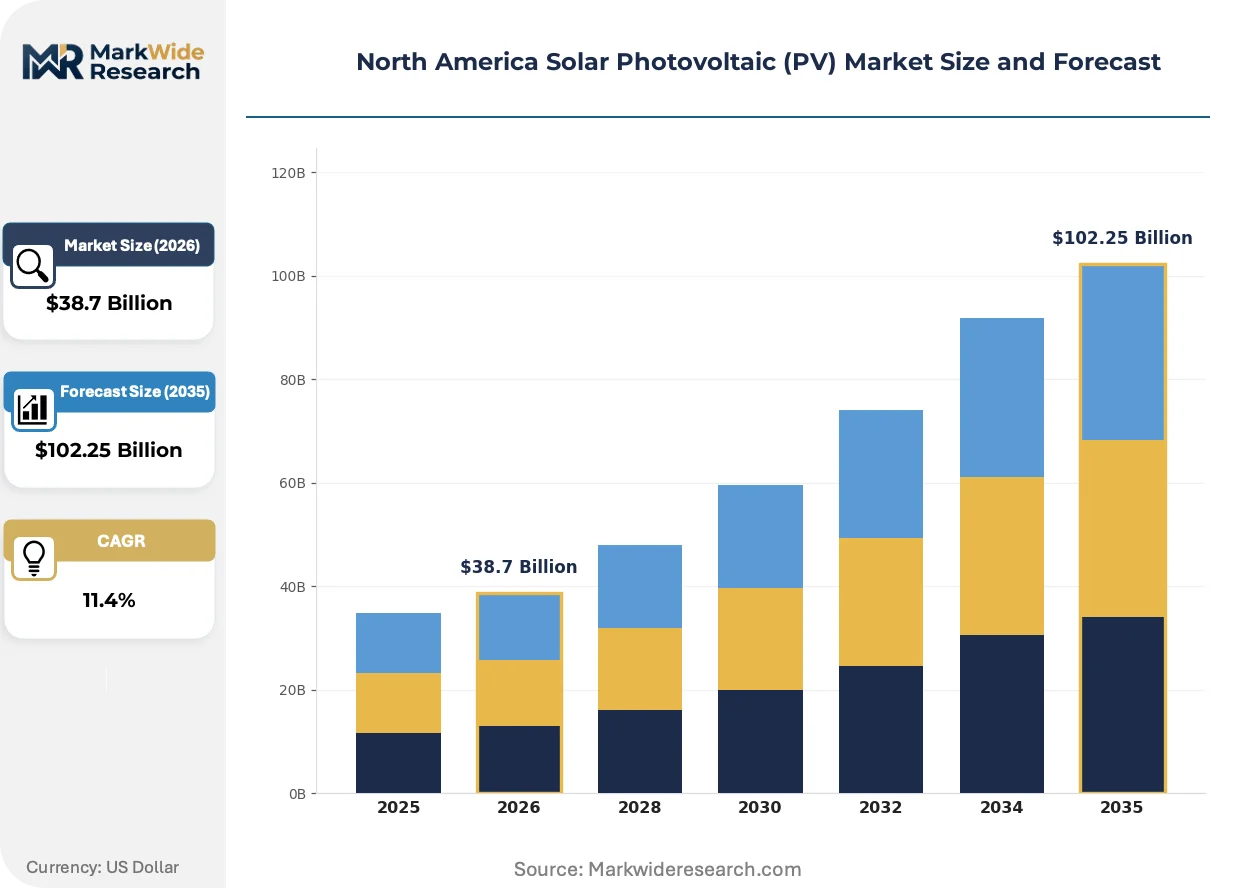
Market Dynamics
Utility-scale procurement is displacing distributed generation as the dominant demand archetype across the North America Solar Photovoltaic (PV) landscape, with interconnection queue concentration in Texas, California, and Arizona reshaping capital allocation and project development timelines.
Growth Catalysts
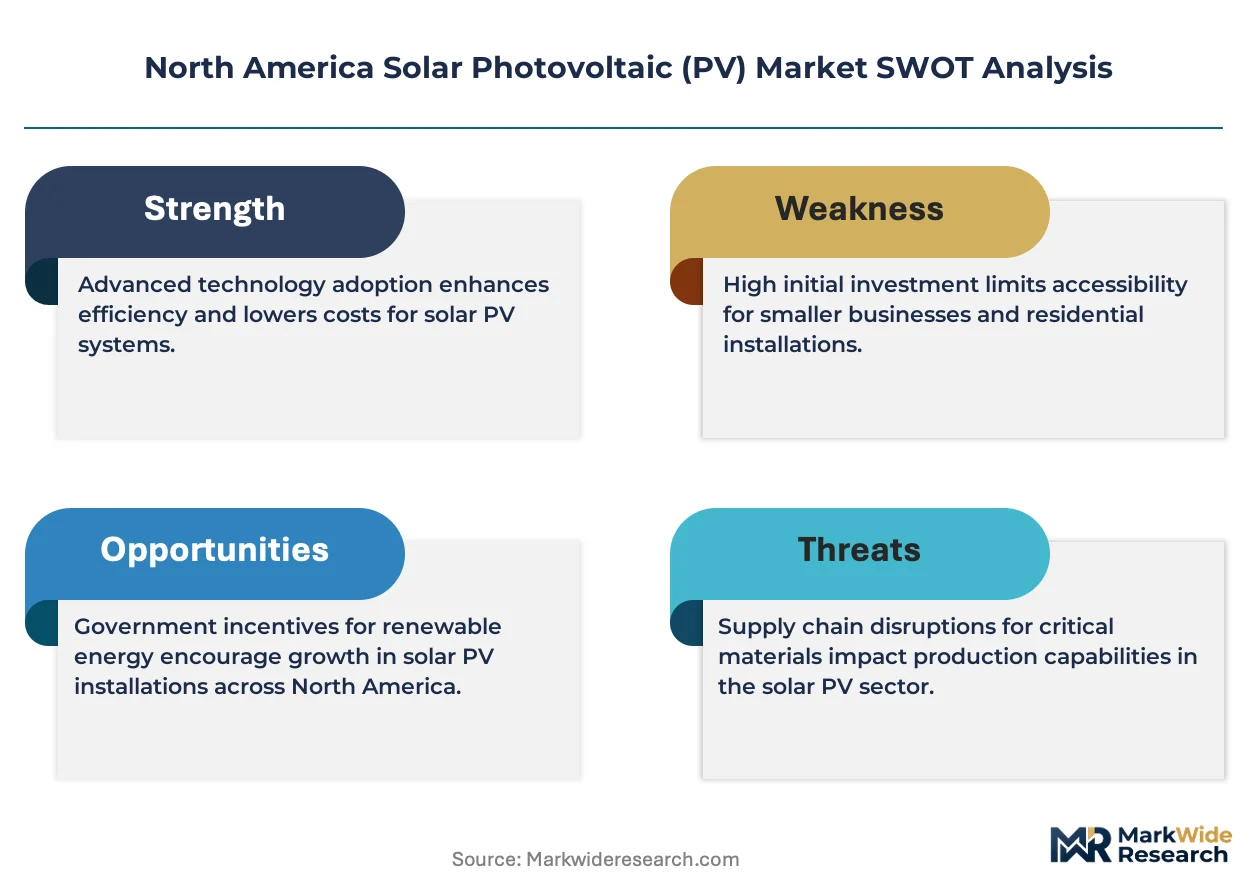
- Inflation Reduction Act Production Tax Credits:Domestic content thresholds redirect module assembly toward US manufacturing corridors, preserving project finance viability for utility-scale developers.
- Texas Interconnection Queue Expansion:ERCOT grid saturation creates captive demand for solar-plus-storage configurations across the ERCOT West and South zones.
- Heterojunction Cell Architectures:Premium efficiency segments capture expanding share as temperature coefficient advantages reduce degradation in arid southwestern climates.
Market Restraints
- Polysilicon Supply Concentration:Xinjiang-sourced polysilicon triggers forced labor due diligence requirements under UFLPA, constraining module availability for US projects.
- Interconnection Cost Allocation:FERC Order 2023 reforms shift network upgrade expenses to interconnecting generators, eroding project returns in congested transmission zones.
- Thin-Film Efficiency Ceiling:Cadmium telluride conversion rates plateau below crystalline silicon mass-production benchmarks, limiting addressable market for certain technology platforms.
Strategic Opportunities
- Community Solar Program Expansion:Regulated state markets in New York, Massachusetts, and Illinois unlock access for renters and multi-tenant buildings excluded from rooftop ownership.
- Solar-Plus-Storage Convergence:Lithium-ion battery cost declines enable merchant dispatch strategies capturing peak pricing volatility in Texas and California nodal markets.
- Domestic Manufacturing Incentives:Section 45X advanced manufacturing credits anchor polysilicon-to-module vertical integration investments in Ohio, Alabama, and Georgia.
Industry Challenges
- Interconnection Engineering Talent Scarcity:Queue reform acceleration outpaces transmission planning workforce expansion, extending study timelines despite procedural streamlining.
- Domestic Content Compliance Verification:IRS safe harbor documentation requirements for IRA credit monetization impose audit complexity on project sponsors and tax equity investors.
- Module Supply Chain Reconfiguration:Southeast Asian tariff circumvention investigations force rapid supplier switching, disrupting construction schedules for contracted projects.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Solar Photovoltaic (PV) Market |
| Market Size in 2026 | $38.7 Billion |
| Market Size in 2035 | $102.25 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: C-Si Modules, Thin-Film Modules, Bifacial Panels, Building-Integrated PV Installation Type: Ground-Mounted, Rooftop, Community Solar, Off-Grid End User: Residential, Commercial, Industrial, Utility Technology: Monocrystalline, Polycrystalline, Heterojunction, Concentrated PV |
| Companies Covered | First Solar, SunPower Corporation, NextEra Energy, Trina Solar, Hanwha Q CELLS USA, TotalEnergies, Canadian Solar, Enphase Energy, AES, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Solar Photovoltaic (PV) Market Evolving Landscape
Technology convergence and procurement model evolution are compressing development cycles and reconfiguring competitive positioning across the North America Solar Photovoltaic (PV) value chain. Three structural shifts merit particular attention.
TOPCon cell architectures are displacing PERC as the utility-scale standard, with tunnel oxide passivated contact designs delivering higher open-circuit voltages and reduced temperature coefficients. Major EPC contractors specify n-type bifacial modules for Texas and Arizona desert installations, where spectral response advantages compound energy yield gains. This transition is displacing legacy p-type capacity and forcing retooling decisions across Southeast Asian cell fabs.
FERC Order 2023 interconnection reforms impose cluster study requirements and ready-for-construction milestones, compressing development timelines for projects in mature queue regions. The rule accelerates withdrawal penalties and cost allocation clarity, pushing developers toward transmission zones with available headroom. ERCOT and CAISO interconnection regions exhibit divergent implementation timelines, creating arbitrage opportunities for developers with regulatory affairs capabilities.
Corporate offtake contracting is fragmenting traditional utility procurement dominance, with data center operators and industrial loads executing virtual PPAs for renewable energy certificates and scope 2 emissions reductions. This buyer segment prioritizes additionality claims and hourly matching capabilities, reshaping developer origination strategies toward 24/7 carbon-free energy products. Texas and Arizona host the densest concentration of these structured transactions.
North America Solar Photovoltaic (PV) Market Segmentation
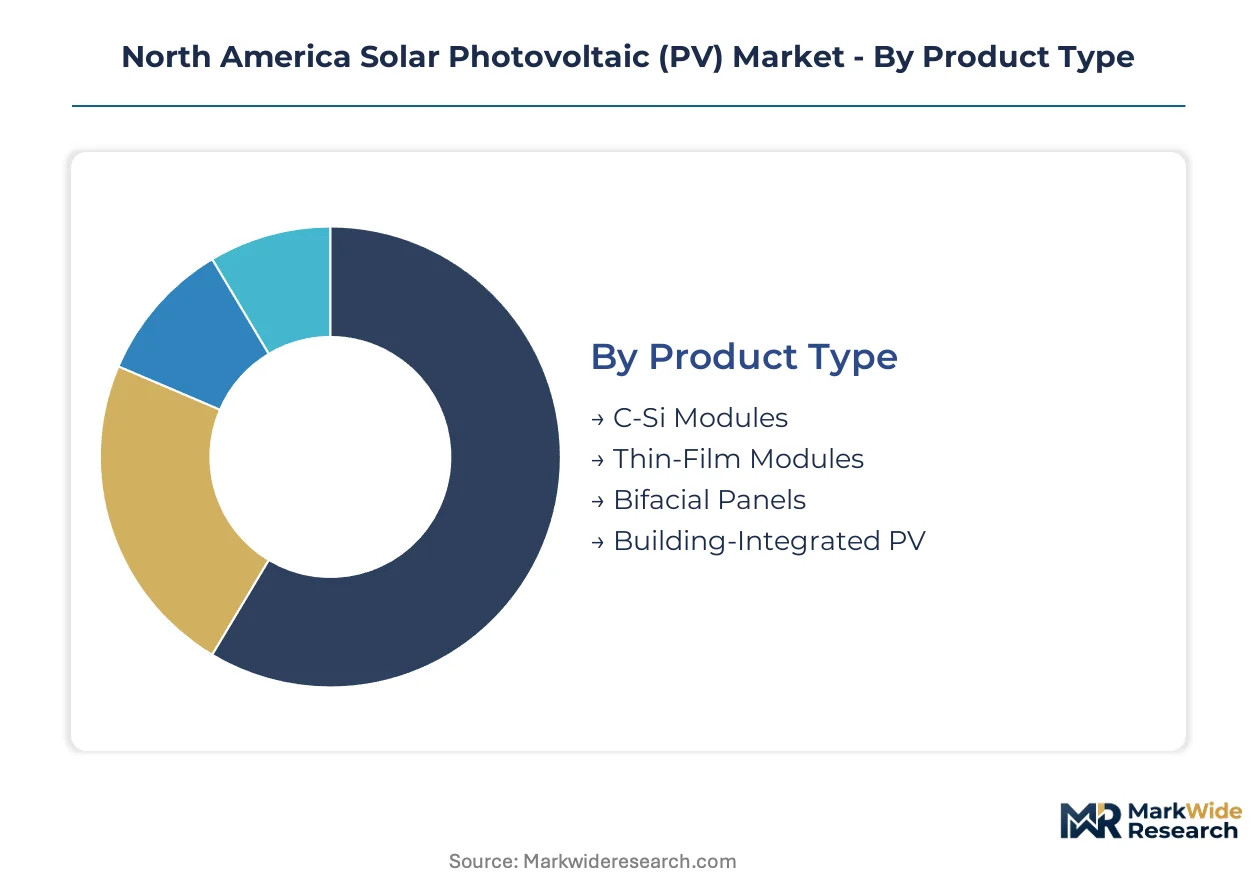
Technology-product pairings and installation configurations determine project bankability, interconnection timelines, and tax credit eligibility across the North America Solar Photovoltaic (PV) value chain. Segment boundaries are blurring as bifacial modules penetrate rooftop applications and heterojunction cells displace legacy architectures in utility procurement.
Product Type:
Margin pools concentrate in high-efficiency module categories that command premium pricing in constrained interconnection zones and satisfy domestic content thresholds for IRA credit monetization.
- C-Si Modules:Crystalline silicon cells dominate mass production with conversion efficiencies above 21% and established supply chain scale across Southeast Asian and emerging US manufacturing corridors. Texas and California utility-scale developers specify these modules for bankable project finance, though Xinjiang polysilicon sourcing triggers UFLPA compliance scrutiny.
- Thin-Film Modules:Cadmium telluride platforms deliver superior temperature coefficients for arid southwestern climates, with First Solar anchoring domestic manufacturing in Ohio and Alabama. The technology captures share where spectral response advantages outweigh efficiency gaps against crystalline benchmarks.
- Bifacial Panels:Dual-sided energy capture gains traction in ground-mounted desert installations.
- Building-Integrated PV:Architectural integration commands premium pricing in commercial facade retrofits.
C-Si Modules holds installed capacity. Bifacial Panels is rotating up the share rankings.
Installation Type:
Capital deployment intensity varies sharply by installation configuration, with ground-mounted projects absorbing the majority of tax equity financing and community solar programs unlocking renter access in regulated state markets.
- Ground-Mounted:Utility-scale configurations concentrate in Texas ERCOT zones and California desert regions, leveraging single-axis tracking and agrivoltaic co-location to optimize land use. Interconnection queue reform under FERC Order 2023 compresses development timelines for these projects.
- Rooftop:Distributed generation spans residential self-consumption and commercial load offset, with Enphase microinverters and module-level power electronics dominating the segment. California NEM 3.0 reforms have shifted economics toward solar-plus-storage pairing.
- Community Solar:Shared arrays in New York, Massachusetts, and Illinois enable subscription models for multi-tenant buildings.
- Off-Grid:Islanded configurations serve remote industrial loads and rural electrification.
Ground-Mounted commands capital deployment. Community Solar is climbing the fastest among installation configurations.
End User:
Procurement scale and contracting structures diverge across customer archetypes, with utility offtake driving manufacturing volume and corporate buyers reshaping origination toward 24/7 carbon-free energy products.
- Utility:Vertically integrated developers like NextEra Energy sustain pipelines from project development through grid interconnection, executing long-term PPAs with investment-grade offtake. ERCOT and CAISO nodal markets exhibit divergent pricing volatility that shapes merchant dispatch strategies.
- Industrial:Data center operators and manufacturing loads execute virtual PPAs for renewable energy certificates and scope 2 emissions reductions, prioritizing additionality claims and hourly matching capabilities.
- Residential:Homeowner-owned systems face interconnection delays in saturated distribution circuits.
- Commercial:Behind-the-meter installations target peak demand charge reduction.
Utility anchors procurement volume. Industrial is gaining share fastest as corporate offtake fragments traditional dominance.
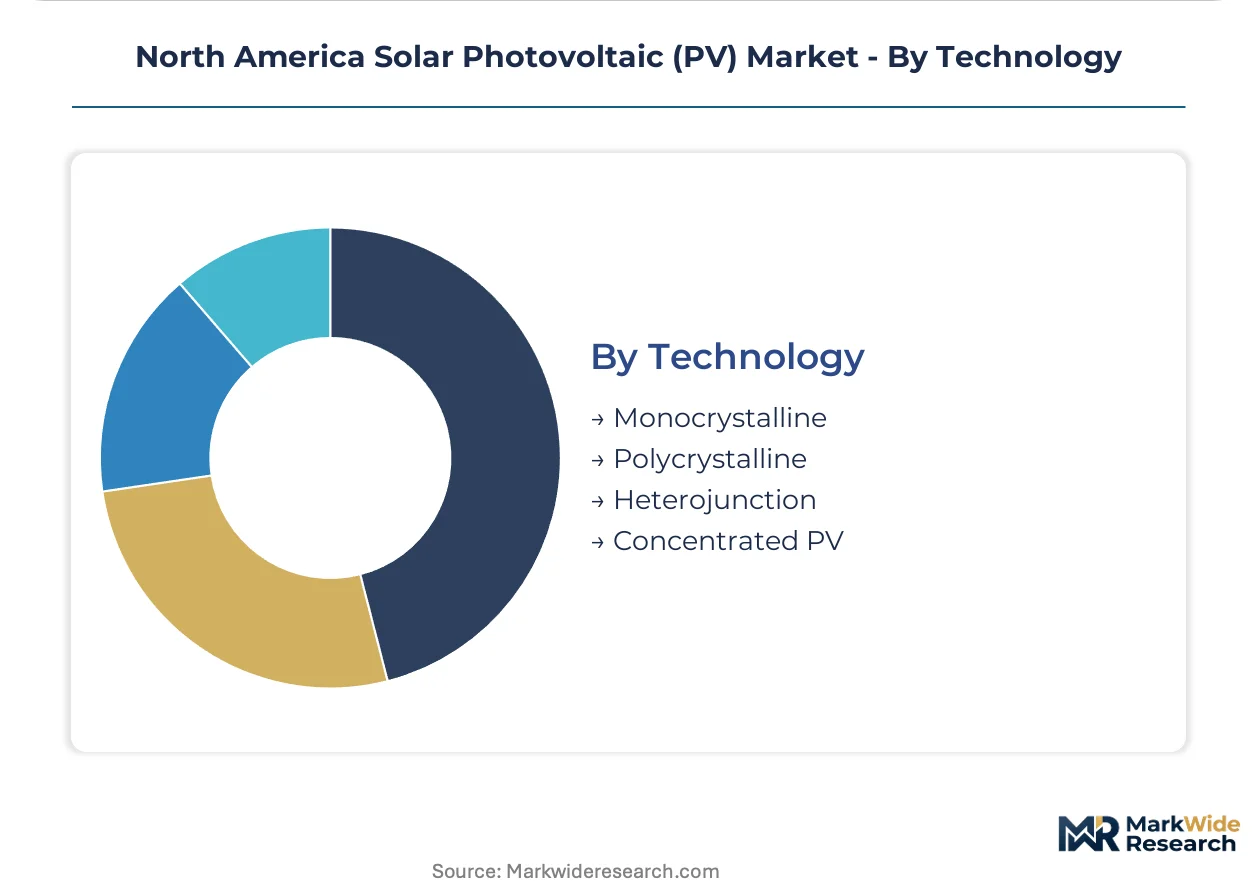
Technology:
Cell architecture transitions are forcing retooling decisions across manufacturing bases, with n-type platforms capturing premium efficiency segments and p-type capacity facing obsolescence risk.
- Monocrystalline:Single-crystal silicon delivers the highest commercial efficiencies and dominates premium module specifications, with PERC giving way to TOPCon and heterojunction successors. Major EPC contractors now specify n-type bifacial variants for southwestern desert installations.
- Heterojunction:Amorphous-crystalline silicon junctions achieve superior open-circuit voltages and reduced temperature coefficients, commanding price premiums in high-irradiance applications where degradation mitigation justifies cost.
- Polycrystalline:Multi-crystal silicon retains cost-sensitive applications.
- Concentrated PV:Optical concentration systems serve niche high-DNI desert locations.
Monocrystalline holds technology leadership. Heterojunction is rotating up the share rankings.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Module assembly concentrates in southwestern US manufacturing corridors and select Canadian provinces, with interconnection queues dictating capital deployment intensity across state-level markets.
United States
ERCOT grid saturation and CAISO nodal pricing volatility drive utility-scale procurement across Texas and California. FERC Order 2023 reforms accelerate cluster study timelines while shifting network upgrade costs to interconnecting generators. Ohio and Alabama host thin-film manufacturing expansion anchored by domestic content thresholds for IRA credit monetization.
Canada
Provincial renewable portfolio standards in Ontario and Alberta sustain distributed generation deployment despite slower utility-scale pipeline development. Natural Resources Canada administers the Smart Renewables and Electrification Pathways Program, channeling capital toward Indigenous-owned projects. Quebec's hydroelectric dominance limits solar penetration, concentrating activity in prairie provinces with merchant exposure.
Mexico
Corporate offtake from maquiladora manufacturing clusters drives private PPA execution in Baja California and Chihuahua. Comisión Reguladora de Energía streamlines self-supply permits for industrial loads seeking tariff relief. Sonora and Durango host emerging project development targeting cross-border transmission capacity into Arizona markets.
North America Solar Photovoltaic (PV) Market Competitive Landscape
Concentration sits with vertically integrated utility-scale developers and domestic thin-film manufacturers that control module supply and interconnection access. The competitive terrain splits between crystalline silicon module suppliers battling UFLPA compliance and thin-film platforms leveraging IRA manufacturing credits. Strategic archetypes include utility-backed developers, domestic cell-and-module fabricators, and distributed generation specialists. Capacity expansion and domestic content vertical integration represent the dominant competitive moves as tariff exposure reshapes sourcing strategies.
Among US-based manufacturers, First Solar anchors thin-film cadmium telluride production for utility-scale deployment, while NextEra Energy exemplifies vertically integrated development-through-interconnection capabilities. Enphase Energy occupies a position within module-level power electronics for distributed generation segments. These three entities represent distinct competitive archetypes: domestic manufacturing, utility vertical integration, and distributed technology specialization.
| Leading Market Players |
|---|
| First Solar |
| SunPower Corporation |
| NextEra Energy |
| Trina Solar |
| Hanwha Q CELLS USA |
| TotalEnergies |
| Canadian Solar |
| Enphase Energy |
| AES |
| Others |
Value Network & Pricing Analysis
Thin-film cadmium telluride substitution for crystalline silicon in utility-scale procurement simultaneously redraws manufacturing geography toward Ohio and Alabama corridors and compresses pricing premiums for domestic content-compliant modules under IRA production tax credit thresholds.
Pricing Analysis
Volume-discount tiering structures separate utility-scale offtake agreements above 100 MW from commercial portfolios and residential single-system sales. Price differentiation rests on domestic content certification tiers and interconnection queue positioning, with FERC Order 2023 network upgrade cost allocations intensifying margin pressure in congested Texas and California transmission zones. Utility buyers exhibit lowest price sensitivity due to long-term PPA anchoring, while residential segments face acute cost compression from NEM 3.0 export credit reductions.
Supply Chain Analysis
Strategic stockpiling of polysilicon and aluminum frames has displaced just-in-time preferences as Southeast Asian tariff circumvention investigations disrupt module delivery schedules. Supply concentrates in Vietnam, Malaysia, and Thailand for cell and module assembly, with raw material dependencies spanning Xinjiang polysilicon, South Korean EVA encapsulant, and Chinese aluminum extrusions. Single-source vulnerability from forced labor due diligence under UFLPA constrains polysilicon availability. Distribution runs through EPC contractor direct procurement and utility developer long-term supply agreements.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a defensive-moat story anchored in regulatory entrenchment: IRA domestic content thresholds and FERC interconnection queue positioning create sticky advantages for incumbents with established manufacturing footprints and transmission access.
For Market Incumbents: Fortify queue position in ERCOT West and CAISO South zones through accelerated cluster study completion under FERC Order 2023 timelines. Deepen backward integration into polysilicon purification to neutralize UFLPA supply risk. Prioritize Ohio and Alabama capacity expansion to capture Section 45X advanced manufacturing credits before safe harbor documentation requirements tighten.
For New Entrants and Emerging Players: Anchor in community solar subscriber acquisition platforms serving New York and Massachusetts regulated markets where incumbent utility relationships carry less weight. Target commercial behind-the-meter solar-plus-storage configurations in California NEM 3.0 transition zones. Pursue origination partnerships with data center operators seeking 24/7 carbon-free energy products and hourly matching capabilities.
For Investors and Strategic Acquirers: The market sits at a manufacturing capacity buildout phase that favors domestic cell-and-module fabricators with verified supply chain documentation. Long-term viability over the next decade hinges on IRA credit monetization durability and interconnection reform implementation pace. Acquisition targets should display polysilicon-to-module traceability systems and established tax equity partnerships. The signal to watch is IRS domestic content percentage escalations that could strand importers against domestic producers.
| Strategic Initiative | Industry Significance |
|---|---|
| Domestic Manufacturing Capacity Buildout | Section 45X credits anchor polysilicon-to-module investments in Ohio, Alabama, and Georgia corridors. |
| Utility-Scale Power Purchase Agreement | Long-term ERCOT and CAISO offtake contracts secure project finance and tax equity participation. |
| Thin-Film Technology Licensing | Cadmium telluride platforms bypass Xinjiang polysilicon exposure while capturing arid climate premiums. |
| Vertical Integration into Battery Storage | Solar-plus-storage convergence enables merchant dispatch strategies in Texas nodal pricing volatility. |
| Domestic Content Certification Program | IRS safe harbor documentation preserves production tax credit eligibility for utility-scale developers. |
Research Methodology
Operator-level perspectives from utility planning officers, IPP project developers, EPC contractors, and grid operators anchored the qualitative base. Primary interviews across these stakeholder roles combined with secondary validation from EIA generation data, FERC interconnection filings, IEA renewable energy reports, and project development databases. Bottom-up capacity and deployment estimates triangulated against top-down regulatory mandate trajectories and tax credit absorption modeling.
Sensitivity analysis across module cost, interconnection timeline, and domestic content compliance scenarios shaped the forecast framework. Segmentation dimensions modeled include technology type, installation configuration, end-user archetype, and regional grid regulatory framework. CAGRs were derived from installed capacity buildout trajectories and average selling price evolution across the projection horizon. Key inputs encompassed IRA credit monetization schedules, state renewable portfolio standard obligations, and FERC Order 2023 implementation timelines.
Underlying assumptions cover sustained IRA production tax credit availability, interconnection queue reform adherence, and polysilicon supply chain reconfiguration pace, with deviation risk concentrated in tariff policy shifts and domestic content percentage escalations. Revision becomes warranted when IRS safe harbor requirements or FERC cost allocation rulings cross thresholds that materially alter project finance viability.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Solar Power Systems
Solar Photovoltaic Ribbon Market
Solar Power Systems
Canada Solar Energy Market
Solar Power Systems
US Residential Solar PV Market
Solar Power Systems
Chile Renewable Energy Market
Solar Power Systems
Rooftop Solar Panels Market
Solar Power Systems
Global EV Solar Modules Market
Solar Power Systems
Frameless Solar Panel Market
Solar Power Systems
Biohybrid Solar Cell Market
Solar Power Systems
New Zealand Solar Energy Market
Solar Power Systems
Solar Microinverter and Power Optimizer Market
Solar Power Systems
Asia-Pacific Solar Photovoltaic (PV) Market
Solar Power Systems
Grid Connected PV Systems Market
Solar Power Systems
Residential Solar Panels Market
Solar Power Systems
Floating Photovoltaics (FPV) Market
Solar Power Systems
Solar Charger Market
Solar Power Systems
DSC Solar Technologies Market