
 Solar Transparent Backsheet Market | 2026-2036
Solar Transparent Backsheet Market Size, Share, and Industry Trends Forecast 2026-2036
Solar Transparent Backsheet Market Insights
Fluoropolymer-grade specification tiers is rotating toward dominance as module manufacturers seek ultraviolet stability and hydrolysis resistance beyond standard PET offerings. DuPont de Nemours Inc. leverages its Tedlar film heritage to anchor premium positioning in North American utility procurement. Isovoltaic AG sustains European manufacturing scale through captive extrusion lines in Austria. Coveme SpA specializes in coated polyester variants for cost-sensitive distributed solar segments.
A solar transparent backsheet is a multi-layer polymeric film laminate, typically 300-350 micrometers thick, comprising a weatherable fluorinated outer layer, a structural PET core, and an EVA-compatible inner sealant, engineered to replace glass in bifacial photovoltaic modules while enabling rear-side light transmission. The product type dimension shows fluoropolymer formulations commanding margin pools in utility-scale installations where 25-year performance warranties are standard, while polyester variants occupy volume leadership in residential rooftops through Hangzhou First Applied Material Co., Ltd.'s integrated cost structure. Application segmentation reveals utility-scale procurement driving fastest expansion as developers optimize levelized cost of energy through bifacial gain capture, with off-grid deployment lagging due to financing constraints.
F-Gas Regulation in Europe and EPA photovoltaic waste guidelines in the United States are reshaping material substitution timelines toward non-fluorinated alternatives. China's GB standards and MIIT circular economy directives enforce domestic recyclability thresholds for module components. India's BIS certification mandates and PLI scheme localization requirements are conditioning market access for imported backsheet films. Stakeholders must monitor regulatory divergence between fluoropolymer restrictions and performance warranty demands to calibrate R&D allocation and regional product portfolios.
Market Dynamics
Utility-scale solar developers in India and China are accelerating fluoropolymer-grade transparent backsheet procurement to replace glass in bifacial modules, compressing supply lead times and forcing material specification tiers to stratify around 25-year performance warranty demands.
Growth Catalysts
- Bifacial module architecture:Rear-side light capture requirements in utility-scale installations are pulling fluoropolymer films into standard procurement specifications, displacing conventional PET-only laminates.
- India's PLI scheme localization:Domestic manufacturing incentives under the Production Linked Incentive framework are conditioning market access for imported backsheet films and accelerating captive extrusion investments.
- F-Gas Regulation compliance pressure:European fluoropolymer restrictions are creating material substitution timelines that favor ultraviolet-stable non-fluorinated alternatives with equivalent hydrolysis resistance.
Market Restraints
- Fluoropolymer feedstock volatility:Perfluorinated monomer supply concentration in Chinese chemical clusters exposes margin structures to input cost swings and export license uncertainty.
- Technical limitation in extreme climates:Standard PET core layers exhibit accelerated hydrolytic degradation in high-humidity tropical installations, compressing addressable market scope for economy-tier products.
- Regulatory friction from EPA photovoltaic waste guidelines:End-of-life recycling mandates in the United States are extending compliance timelines and elevating documentation burdens for imported laminate structures.
Strategic Opportunities
- Underpenetrated distributed solar in Brazil:Residential rooftop segments lack fluoropolymer-grade supply infrastructure, creating first-mover positioning for coated polyester variants with localized distribution partnerships.
- Technology convergence of transparent backsheets with perovskite tandem cells:Next-generation module architectures requiring rear-side photon management are opening specification windows for spectrally optimized multi-layer films.
- Channel innovation through integrated backsheet-to-module production lines:Jiangsu and Zhejiang manufacturing clusters are consolidating supply chain steps, enabling direct OEM relationships that bypass traditional film distributor networks.
Industry Challenges
- Certification timeline compression:BIS certification mandates in India and evolving GB standards in China are extending product qualification cycles, straining R&D resource allocation across multiple regulatory frameworks simultaneously.
- Skill scarcity in fluoropolymer extrusion:Specialized polymer processing expertise for multi-layer coextrusion lines concentrates in Austrian and Chinese technical centers, constraining geographic expansion of manufacturing footprint.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Solar Transparent Backsheet Market |
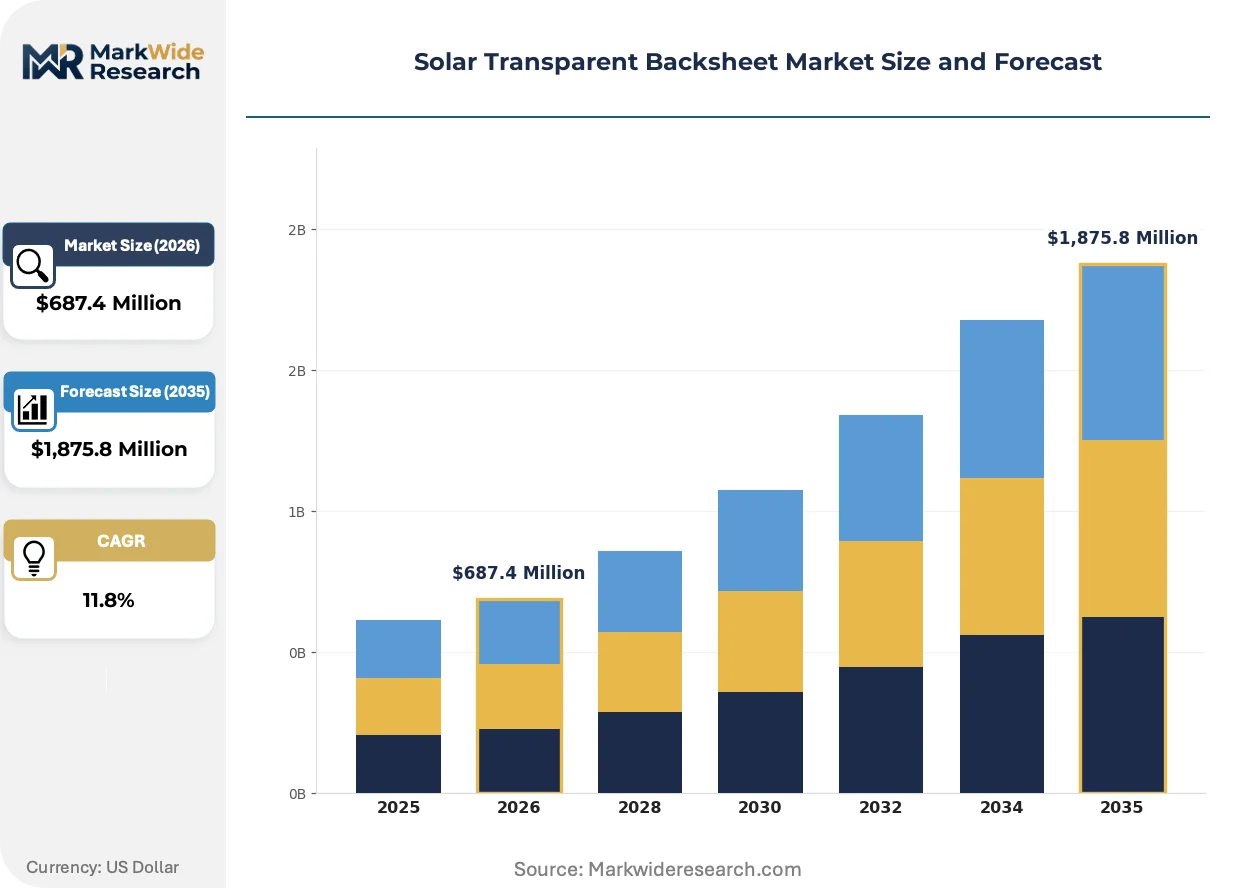
| Market Size in 2026 | $687.4 Million |
| Market Size in 2035 | $1,875.8 Million |
| CAGR (2026 – 2036) | 11.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Polyester, Polyvinyl Fluoride, Polycarbonate, Ethylene Vinyl Acetate Application: Utility Scale, Residential, Commercial, Off-Grid End User: Manufacturers, Installers, Distributors, Energy Providers Distribution Channel: Online, Direct Sales, Retail, Wholesalers |
| Companies Covered | DuPont de Nemours Inc., Isovoltaic AG, Coveme SpA, Hangzhou First Applied Material Co., Ltd., Krempel GmbH, Taiflex Scientific Co. Ltd., Cybrid Technologies, Jolywood, Toppan, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Solar Transparent Backsheet Market Trends and Innovations
Material science advances and regulatory pressure on fluorinated chemistries are actively fragmenting competitive positioning around performance-tier differentiation, with technology roadmaps diverging between premium ultraviolet-stable formulations and cost-optimized coated alternatives.
Co-extruded fluoropolymer-PET multi-layer laminates are bifurcating the product architecture landscape. Utility-scale developers in India and China are specifying these structures for 25-year warranty compliance, while residential distributors in cost-sensitive segments are retreating to coated polyester variants. The technology is bifurcating margin pools between premium fluoropolymer-grade supply and economy-tier alternatives.
Europe's F-Gas Regulation and the EU Green Deal are tightening material compliance requirements for photovoltaic components. Industrial consequence includes accelerated R&D allocation toward non-fluorinated ultraviolet stabilizers and hydrolysis-resistant polymer alternatives. Utility-scale procurement in Germany and Spain is most affected, with developers now requiring full material disclosure documentation and recyclability certification from backsheet suppliers.
Buyer specification behavior is hardening around performance-tier segmentation rather than commodity procurement. Module OEMs in China's Jiangsu cluster are consolidating supplier relationships to integrated film-to-laminate producers, displacing independent backsheet distributors. This concentration is most visible in utility-scale procurement channels where direct technical collaboration with extrusion specialists reduces qualification risk and compresses lead times.
Solar Transparent Backsheet Market Segmentation
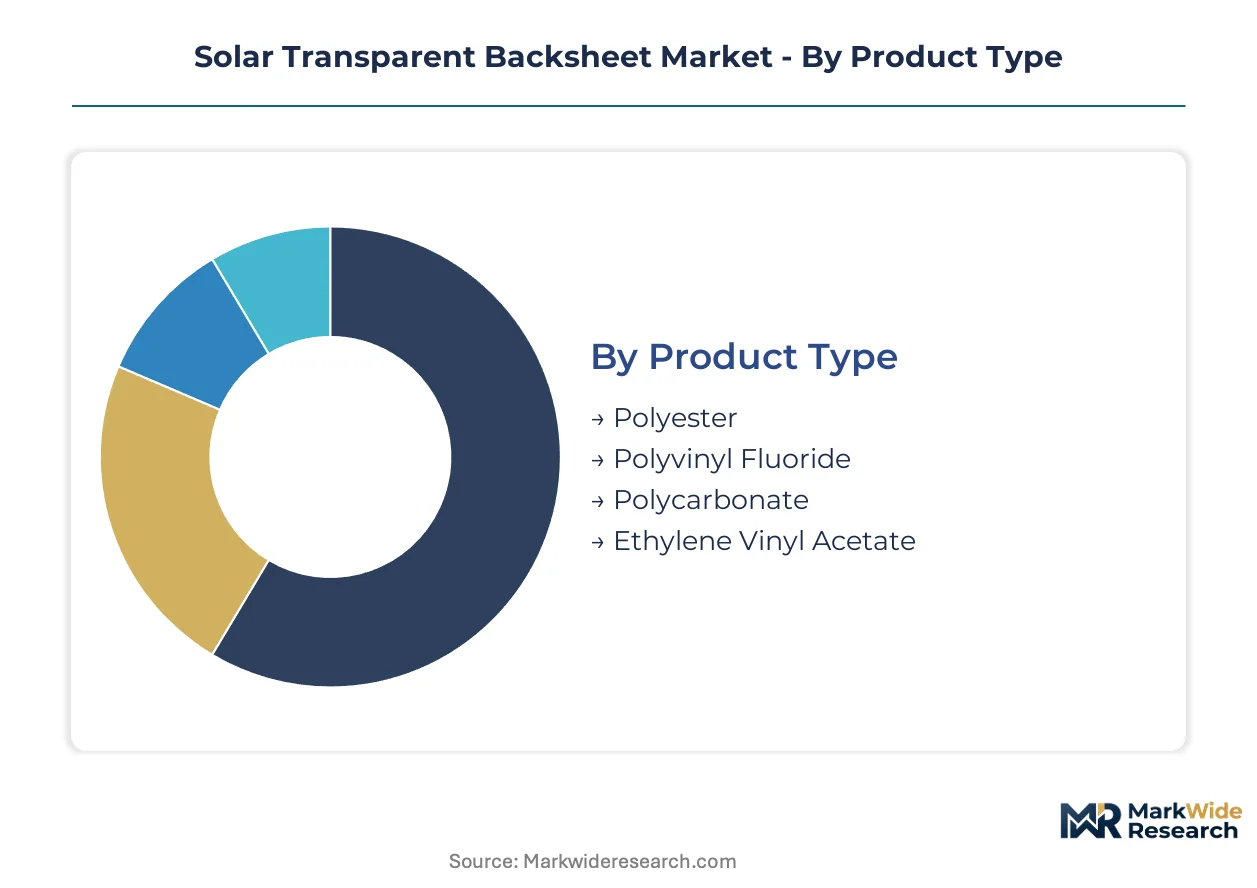
Segmentation in the solar transparent backsheet market tracks how material chemistry, installation scale, and channel structure allocate margin pools across competing specification tiers. Each dimension reveals distinct vulnerability to substitution from glass and non-fluorinated alternatives.
Product Type:
Polyester formulations face the most acute substitution pressure from fluoropolymer-grade laminates as module OEMs extend performance warranties beyond standard PET hydrolysis limits.
- Polyester:Coated PET variants with aluminum oxide or silicon oxide barrier layers dominate residential rooftop procurement through cost-optimized supply chains in China. Hangzhou First Applied Material Co., Ltd. anchors volume leadership here via integrated extrusion-to-module production. India's PLI scheme localization requirements are accelerating domestic polyester backsheet manufacturing to displace imports.
- Polyvinyl Fluoride:Tedlar-based fluoropolymer films from DuPont de Nemours Inc. command premium positioning in North American utility procurement where ultraviolet stability and 25-year hydrolysis resistance are non-negotiable. The F-Gas Regulation in Europe is compressing addressable scope for this chemistry despite superior field performance.
- Polycarbonate:Optical-grade transparent variants serve niche applications requiring high impact resistance and thermal dimensional stability.
- Ethylene Vinyl Acetate:EVA-compatible sealant layers function as inner laminates rather than standalone backsheet structures, integrating with fluoropolymer or polyester outer films.
Polyester anchors the volume base while polyvinyl fluoride gains share at the steepest rate among premium procurement channels.
Application:
Cost tier stratification separates utility-scale developers seeking bifacial gain optimization from distributed solar segments prioritizing upfront capital minimization.
- Utility Scale:Massive solar farms in India and China specify fluoropolymer-grade transparent backsheets to replace glass in bifacial modules, capturing rear-side albedo gains. Procurement concentrates through direct OEM relationships with Jiangsu and Zhejiang manufacturing clusters, bypassing traditional film distributors. BIS certification mandates in India extend qualification timelines for imported laminates.
- Residential:Rooftop installations in cost-sensitive markets favor coated polyester variants where 15-20 year performance horizons align with product lifecycles. Brazil's underpenetrated distributed solar segment lacks fluoropolymer-grade infrastructure, creating positioning windows for economy-tier suppliers.
- Commercial:Mid-scale rooftop and ground-mount projects balance warranty demands against capital constraints through hybrid specification approaches.
- Off-Grid:Remote and rural electrification projects lag due to financing constraints and limited distributor presence in frontier markets.
Utility scale commands the dominant revenue share while residential expands most quickly in emerging distributed solar markets.
End User:
Customer type determines technical collaboration intensity, with manufacturers driving specification standardization while intermediaries fragment procurement authority.
- Manufacturers:Module OEMs in China's manufacturing clusters consolidate supplier relationships to integrated film-to-laminate producers, reducing qualification risk. Direct technical collaboration with extrusion specialists compresses lead times and enables co-development of spectrally optimized multi-layer films for perovskite tandem compatibility.
- Installers:EPC contractors and project developers influence material selection through warranty compliance requirements and bankability standards.
- Distributors:Independent film distributors face displacement as supply chain integration concentrates procurement channels.
- Energy Providers:Utility and IPP procurement teams specify transparent backsheets through long-term supply agreements tied to project finance milestones.
Manufacturers dominate specification authority while energy providers gain procurement influence through direct OEM contracting.
Distribution Channel:
Channel structure reflects supply chain consolidation in manufacturing clusters versus fragmentation in distributed solar markets.
- Direct Sales:Integrated backsheet-to-module production lines in Jiangsu and Zhejiang enable direct OEM relationships that bypass traditional film distributor networks. This channel captures the majority of utility-scale procurement volume through technical collaboration and compressed lead times.
- Online:Digital procurement platforms serve small-scale installers and retrofit projects with standardized product configurations.
- Retail:Local distributors and hardware channels address residential rooftop segments with limited technical specification requirements.
- Wholesalers:Regional inventory aggregation supports commercial and off-grid segments with fragmented demand geography.
Direct sales anchors volume concentration while online channels expand most quickly in distributed solar procurement.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Export-import balances are tilting toward manufacturing self-sufficiency as major solar markets erect localization barriers. Countries with integrated chemical-to-module supply chains capture margin compression from feedstock through finished backsheet, while import-dependent markets face extended qualification timelines and tariff exposure.
China
Jiangsu and Zhejiang manufacturing clusters dominate fluoropolymer-grade extrusion capacity for bifacial module supply. MIIT circular economy directives and GB standards enforce domestic recyclability thresholds that condition market access for imported laminate structures. Yangtze River Delta integrated backsheet-to-module production lines enable direct OEM relationships that bypass traditional film distributor networks entirely.
India
Utility-scale solar farms in Rajasthan and Gujarat are accelerating fluoropolymer-grade procurement to replace glass in bifacial designs. BIS certification mandates and PLI scheme localization requirements extend qualification timelines for imported backsheet films while accelerating captive extrusion investments. Domestic manufacturing incentives are conditioning market access and compressing supply lead times for module OEMs.
United States
North American utility procurement specifies Tedlar-based fluoropolymer films where ultraviolet stability and 25-year hydrolysis resistance are non-negotiable. EPA photovoltaic waste guidelines extend compliance timelines and elevate documentation burdens for imported laminate structures. Southeast manufacturing corridors lack integrated extrusion capacity, creating dependence on Austrian and Chinese technical centers for specialized polymer processing.
Germany
Utility-scale procurement in Bavaria and North Rhine-Westphalia requires full material disclosure documentation under F-Gas Regulation compliance pressure. ECHA and EU Green Deal frameworks are accelerating R&D allocation toward non-fluorinated ultraviolet stabilizers with equivalent hydrolysis resistance. Industrial clusters face compressed addressable scope for fluoropolymer chemistry despite superior field performance in premium applications.
Brazil
Residential rooftop segments in São Paulo and Minas Gerais lack fluoropolymer-grade supply infrastructure, creating positioning windows for economy-tier suppliers. ANVISA and national energy regulator frameworks condition import licensing for photovoltaic component materials. Distributed solar underpenetration favors coated polyester variants through localized distribution partnerships rather than integrated direct sales channels.
Solar Transparent Backsheet Market Competitive Landscape
Concentration sits with integrated chemical-to-module conglomerates that control fluoropolymer feedstock through finished backsheet production. Three to five extrusion specialists anchor premium-tier supply for utility-scale warranty compliance, while mid-scale coated polyester fabricators fragment residential rooftop procurement. Competitive moves center on backward integration into perfluorinated monomer supply and captive capacity expansion in Jiangsu and Zhejiang manufacturing corridors.
Among heritage fluoropolymer specialists, DuPont de Nemours Inc. exemplifies premium-tier positioning through Tedlar film legacy in North American utility procurement. Isovoltaic AG represents European manufacturing scale through captive extrusion lines in Austria. Hangzhou First Applied Material Co., Ltd. anchors volume leadership in coated polyester variants through integrated cost structure in China's manufacturing clusters. These three archetypes—heritage fluoropolymer, European captive extrusion, and Chinese integrated volume—occupy distinct margin pools across specification tiers.
| Leading Market Players |
|---|
| DuPont de Nemours Inc. |
| Isovoltaic AG |
| Coveme SpA |
| Hangzhou First Applied Material Co., Ltd. |
| Krempel GmbH |
| Taiflex Scientific Co. Ltd. |
| Cybrid Technologies |
| Jolywood |
| Toppan |
| Others |
Pricing and Supply Chain Analysis
BIS certification mandates in India gate both supply qualification and price differentiation simultaneously, extending product qualification cycles for imported laminates while compressing margins for economy-tier polyester variants that cannot absorb compliance costs. This regulatory filter stratifies the market into fluoropolymer-grade premium supply and cost-optimized alternatives, with certification burden acting as a simultaneous barrier to entry and pricing lever.
Pricing Analysis
Industrial OEM buyers anchor a three-tier pricing structure across premium, standard, and economy levels in the solar transparent backsheet market. Price differentiation stems from certification grade—specifically BIS and GB standard compliance tiers—and volume scale in direct OEM contracting. Cost compression in polyester variants is intensifying because India's PLI scheme localization accelerates domestic manufacturing capacity additions. Residential distributors in Brazil exhibit the highest price sensitivity, while North American utility procurement teams demonstrate the lowest sensitivity due to 25-year warranty non-negotiability.
Supply Chain Analysis
Inventory cycles compress to eight-to-twelve weeks for fluoropolymer-grade laminates as Jiangsu and Zhejiang manufacturing clusters consolidate integrated backsheet-to-module production. Geographic supply concentration centers on China, Austria, and India, with perfluorinated monomer feedstock and PET resin drawing from Chinese chemical clusters. Single-source vulnerability in specialized fluoropolymer extrusion expertise constrains geographic expansion of manufacturing footprint. Distribution runs through direct OEM relationships that bypass traditional film distributor networks in utility-scale procurement channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The solar transparent backsheet market exhibits cyclical recovery characteristics driven by bifacial module deployment waves in utility-scale solar installations. Procurement cycles correlate with project finance milestones and policy incentive windows, creating predictable demand pulses.
For Market Incumbents: Fortify captive fluoropolymer extrusion capacity in Jiangsu and Zhejiang manufacturing corridors to defend against non-fluorinated substitute technologies accelerated by Europe's F-Gas Regulation. Prioritize backward integration into perfluorinated monomer supply to insulate margin structures from Chinese feedstock volatility. Secure dual certification under BIS and GB standards to compress qualification timelines for cross-border procurement. For New Entrants and Emerging Players: Differentiate on spectrally optimized multi-layer films for perovskite tandem compatibility, targeting technology convergence white space absent from incumbent roadmaps. Brazil's underpenetrated residential rooftop segment offers the most penetrable geography, lacking fluoropolymer-grade infrastructure and favoring coated polyester variants through localized distribution partnerships. Pursue joint development agreements with module OEMs rather than distributor channel penetration. For Investors and Strategic Acquirers: Europe's F-Gas Regulation reshapes the acquisition landscape toward non-fluorinated ultraviolet stabilizer specialists with equivalent hydrolysis resistance credentials. Long-term viability over the next decade hinges on regulatory arbitrage between fluoropolymer restrictions and performance warranty demands. Acquisition target archetype: mid-scale extrusion specialists with captive Austrian or Chinese technical centers and existing utility-scale qualification track records. Monitor BIS certification timeline compression in India as the critical inflection signal for supply chain reconfiguration.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Perfluorinated Monomer Supply | Insulates margin structures from Chinese chemical cluster feedstock volatility and export license uncertainty. |
| Dual Certification Investment (BIS/GB Standards) | Compresses product qualification cycles for cross-border procurement between India and China manufacturing corridors. |
| Perovskite Tandem Compatibility R&D | Opens specification windows for spectrally optimized multi-layer films in next-generation module architectures. |
| Localized Extrusion Capacity in India | Captures PLI scheme incentives while displacing imported laminate structures subject to extended BIS timelines. |
| Non-Fluorinated Alternative Development | Positions supply for Europe's F-Gas Regulation compliance while maintaining ultraviolet stability equivalence. |
Research Methodology
Initial hypotheses were tested against primary input from module OEM procurement directors, fluoropolymer extrusion specialists, utility-scale EPC contractors, and regulatory affairs leads at backsheet manufacturers, and refined through secondary validation. Primary fieldwork encompassed technical collaboration patterns in Jiangsu and Zhejiang manufacturing clusters, warranty compliance requirements from North American utility procurement teams, and certification timeline documentation from BIS and GB standard authorities. Secondary sources included customs and trade data tracking fluoropolymer film imports, MIIT circular economy directive filings, SEC 10-K disclosures from heritage chemical conglomerates, and project development databases for bifacial module deployments. Bottom-up volume triangulation from manufacturing capacity utilization was cross-referenced against top-down demand estimates from utility-scale procurement pipelines.
Variance decomposition across material chemistry tiers, installation scale segments, and regional regulatory clusters structured the analytical framework over the projection horizon. Segmentation dimensions modeled encompassed fluoropolymer versus polyester versus polycarbonate formulations, utility-scale versus residential versus commercial application tiers, and direct sales versus distributor channel structures. CAGRs were derived from installed capacity growth trajectories for bifacial modules, policy incentive phase-out schedules, and substitution elasticity estimates between glass and transparent backsheet architectures. Industry-specific forecast inputs included perfluorinated monomer price indices from Chinese chemical exchanges and BIS certification queue lengths from Indian standards authorities.
The analysis sits within stated boundaries; outcomes outside sustained bifacial module deployment rates, stable fluoropolymer feedstock availability, and consistent enforcement of 25-year performance warranty standards would require recalibration. Forecasts reflect documented assumptions regarding regulatory timeline adherence, technology substitution patterns, and project finance milestone achievement. Supply chain disruption from export license restrictions, extreme climate performance failures, or accelerated non-fluorinated alternative maturation could revise trajectory assumptions. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Solar Power Systems
Solar Sunlight Control System Market
Solar Power Systems
Solar Microgrid Market
Solar Power Systems
Solar Powered Elevator Market
Solar Power Systems
Solar Carport Market
Solar Power Systems
AR Photovoltaic Glass Market
Solar Power Systems
Solar Simulator Market
Solar Power Systems
Ghana Solar Energy Market
Solar Power Systems
North America Rooftop Solar Market
Solar Power Systems
Dual Axis Solar Tracker Market
Solar Power Systems
India Solar Photovoltaic (PV) Market
Solar Power Systems
Solar Panel Cleaning System Market
Solar Power Systems
US Solar PV Market
Solar Power Systems
Philippines Solar Energy Market
Solar Power Systems
Bifacial Solar Market
Solar Power Systems
Solar Power Market
Solar Power Systems
Solar Photovoltaic Ribbon Market