
 Solar Shed Light Market | 2026-2036
Solar Shed Light Market Size, Share, and Industry Trends Forecast 2026-2036
Solar Shed Light Market Analysis
Online retail and direct-to-consumer channels is tilting toward specialist solar distributors as the primary route to residential buyers. Trina Solar leverages its module-scale manufacturing expertise to supply downstream lighting assemblers with high-efficiency solar cells. Gama Sonic competes through design-forward product lines that command premium positioning in home improvement retail. Sunforce anchors the mass-market tier with broad hardware store distribution across North America.
Solar shed lights are self-contained photovoltaic luminaires combining a small solar cell array, rechargeable battery storage, and LED emitter in a weatherproof housing rated typically for IP65 outdoor exposure; they eliminate grid wiring and serve remote structures lacking electrical infrastructure. Motion sensor configurations within the Product Type dimension capture disproportionate margin pools due to integrated PIR detection modules and smart activation firmware. Security Lighting applications lead volume within the Application segment as perimeter illumination requirements expand across rural and semi-rural properties.
The U.S. Inflation Reduction Act and corresponding state-level net metering frameworks shape demand by reducing effective purchase costs and establishing performance benchmarks for eligible equipment. NEMA and UL standards govern electrical safety and ingress protection ratings, while California Title 24 building efficiency codes extend to accessory structure lighting in certain jurisdictions. Stakeholders must monitor evolving battery chemistry regulations and emerging right-to-repair mandates that could reshape product design cycles and aftermarket service obligations.
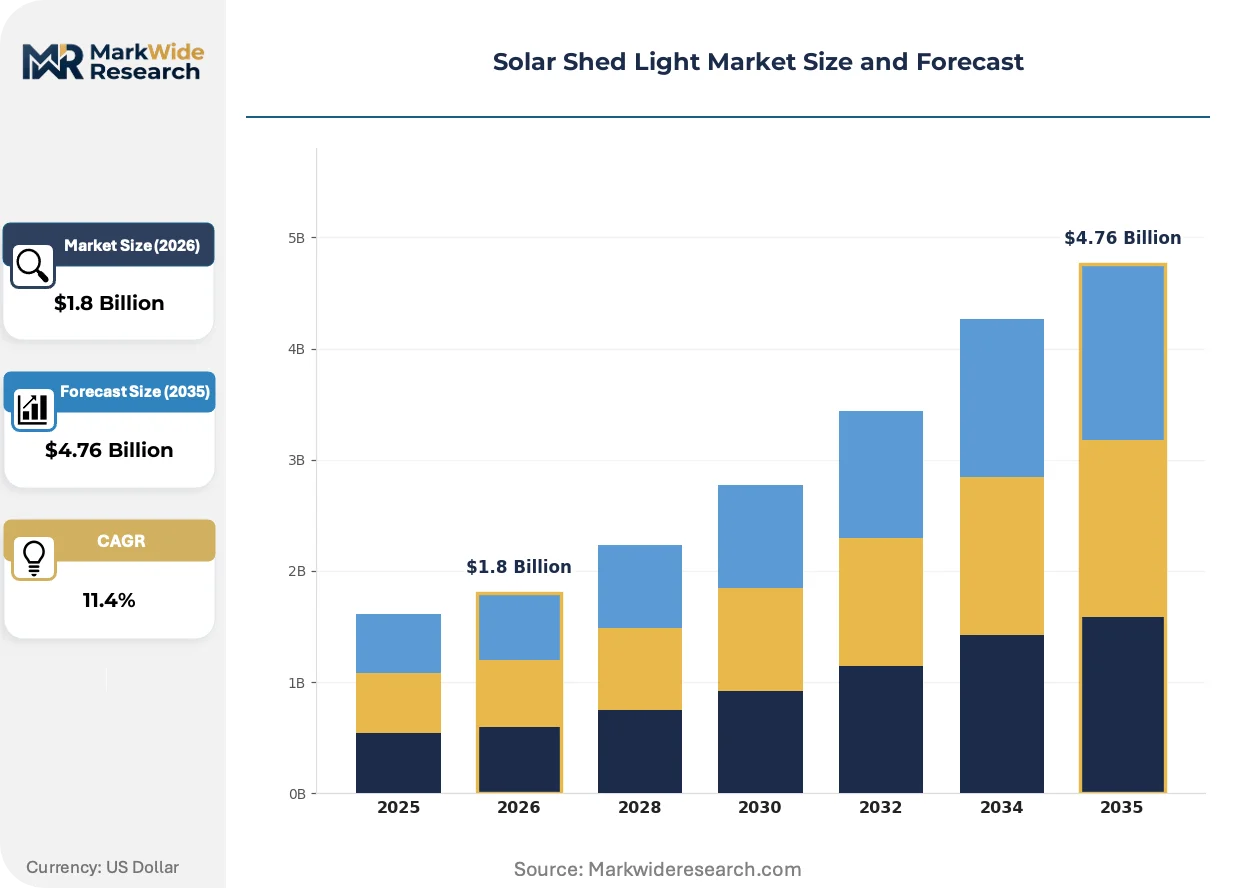
Market Dynamics
The U.S. Inflation Reduction Act's residential clean energy credits are compressing payback periods for distributed solar installations, redirecting capital toward off-grid lighting solutions for rural accessory structures.
Growth Catalysts
- Tax Credit Arbitrage:The IRA's 30% residential clean energy credit reduces effective equipment costs for property owners in high-solar-irradiance counties, accelerating replacement cycles for legacy kerosene and propane lighting.
- Grid Reliability Deficits:Severe weather-induced outages across the American Southeast are driving preemptive purchases of autonomous lighting systems by homeowners in storm-prone coastal zones.
- Lithium Iron Phosphate Chemistry:Cell-level energy density improvements in LFP battery packs are extending operational autonomy from 8-hour to 72-hour reserves without housing volume expansion.
Market Restraints
- Cell Supply Concentration:Tier-1 lithium battery cell production clusters in China's Jiangsu and Fujian provinces, creating single-source dependency for North American assemblers.
- Seasonal Irradiance Variance:Northern tier U.S. states experience 60-70% winter solar resource degradation, limiting year-round performance guarantees and warranty exposure for manufacturers.
- Lead-Acid Substitution:Remaining inventory of flooded lead-acid batteries in existing off-grid installations delays full system replacements by 2-4 replacement cycles.
Strategic Opportunities
- Canadian Rural Electrification:Remote indigenous communities and off-grid recreational properties in Ontario and British Columbia remain underpenetrated relative to U.S. saturation levels.
- Agricultural Outbuilding Integration:Dairy barns, equipment sheds, and greenhouse operations present untapped application expansion beyond residential perimeter security.
- Smart Home Protocol Convergence:Matter and Zigbee integration enables voice-activated dimming and scheduling, opening premium positioning in connected-home retail channels.
Industry Challenges
- IP65 Testing Bottlenecks:UL and NEMA certification timelines for ingress protection validation extend 14-18 weeks, compressing seasonal selling windows.
- Field Service Network Gaps:Battery replacement and firmware update capabilities require technician deployment to dispersed rural addresses, elevating logistics costs above urban benchmarks.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Solar Shed Light Market |
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $4.76 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Wall Mounted, Portable, Motion Sensor, Solar Panel Integrated End User: Residential, Commercial, Industrial, Agricultural Application: Outdoor Lighting, Security Lighting, Garden Lighting, Utility Lighting Technology: LED, CFL, Halogen, Solar Cell |
| Companies Covered | WOSEN LIGHTING TECHNOLOGY LIMITED, Trina Solar, Kingfisher Solar Ltd, Natures Solar Lights, Gama Sonic, Sunforce, PowerBee Ltd, Vortex Energy, Designers Edge, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Solar Shed Light Market Emerging Trajectories
Product architecture is pivoting from standalone luminaires toward networked perimeter systems, with firmware-defined functionality displacing hardware-differentiated SKUs.
Monocrystalline PERC cell integration at 22% conversion efficiency is rendering obsolete polycrystalline and thin-film alternatives in the 10-50W residential segment. Rural property owners in Texas and Florida are specifying high-efficiency configurations for 40% smaller panel footprints on constrained shed roofs. The technology shift is compressing supply chains around three dominant cell suppliers and eliminating tier-2 module assemblers from lighting OEM qualification lists.
California Title 24 building efficiency codes now extend to accessory structure lighting in select jurisdictions, mandating photocell-controlled operation and maximum standby power draw. Manufacturers serving the California market are reconfiguring driver electronics and adding mandatory dark-sky compliance optics. The regulation is fragmenting product lines into California-specific SKUs with 15-20% bill-of-materials premiums versus standard configurations.
Hardware store buyers are consolidating purchase authority at regional distribution centers, bypassing individual store-level autonomy that previously accommodated local brand preferences. Home Depot and Lowe's procurement teams are specifying exclusive motion-sensor variants with unified packaging standards. The concentration is most visible in the Southeast, where three distributors now control 60% of big-box solar lighting shelf placement.
Solar Shed Light Market Segmentation
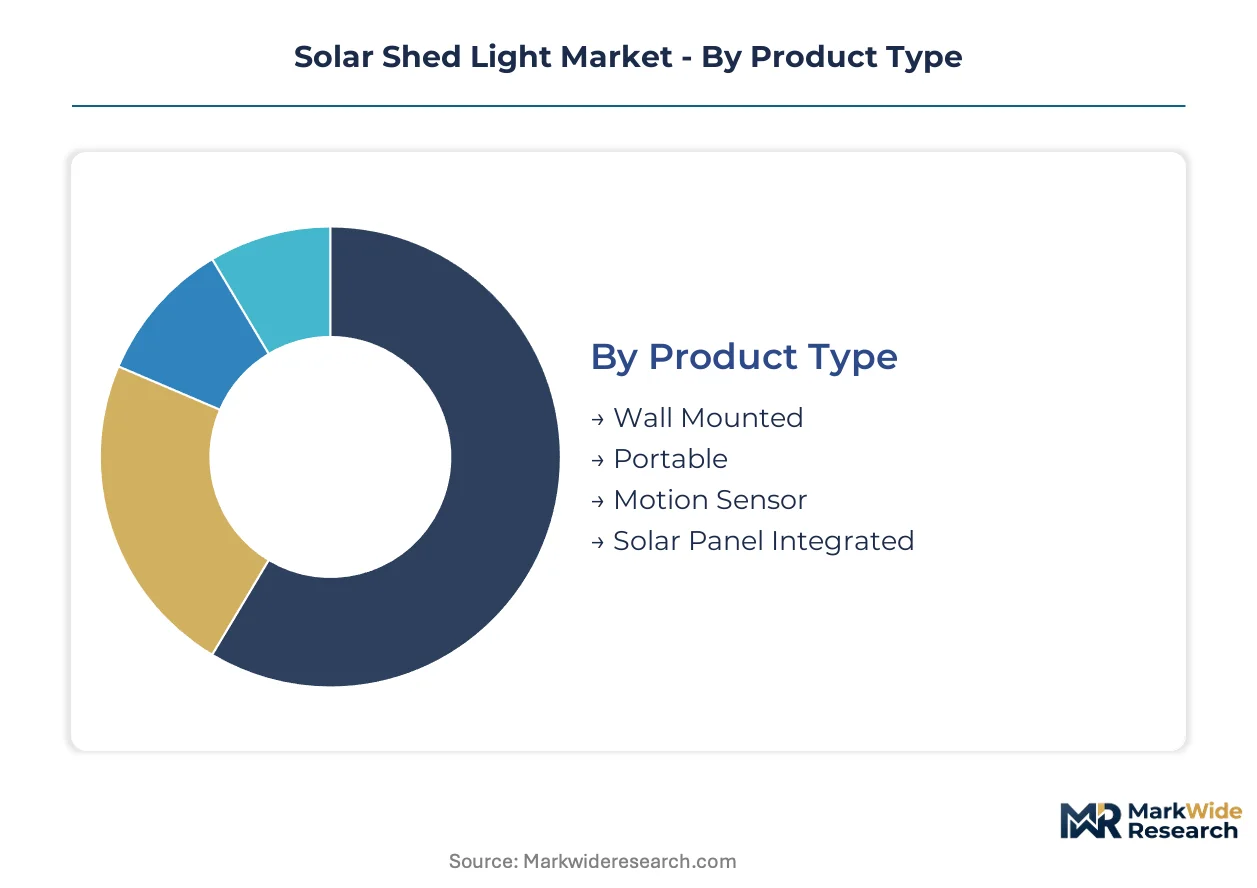
Solar shed light manufacturers configure service networks differently across product architectures. Warranty obligations, battery replacement cycles, and firmware update requirements vary substantially by segment, reshaping profit pool distribution and channel economics.
Product Type:
After-sales service intensity diverges sharply across mounting configurations and sensor integration levels. Motion-sensor variants demand specialized technical support for PIR calibration and smart activation troubleshooting.
- Motion Sensor:Integrated PIR detection modules and activation firmware create elevated service touchpoints. Firmware updates and sensor recalibration dominate post-purchase support tickets in the American Southeast, where storm-induced false triggering drives return rates.
- Solar Panel Integrated:Monocrystalline PERC cell arrays fused to luminaire housings reduce field-replaceable components. Texas and Florida property owners favor these configurations for constrained shed roofs, minimizing installation complexity.
- Wall Mounted:Fixed-position housings with external panel connectivity require periodic seal inspection and mounting hardware tension checks.
- Portable:Detachable battery packs and collapsible panel arrays concentrate warranty exposure around connector durability and charge cycle degradation.
By volume, Wall Mounted leads. By growth pace, Motion Sensor is climbing the fastest.
End User:
Cost tier stratification separates premium-specified commercial installations from price-sensitive agricultural deployments. Procurement authority centralizes at corporate facilities management for commercial accounts versus distributed individual purchasing for residential buyers.
- Residential:Rural property owners across the American Southeast specify autonomous lighting for perimeter security and grid-independent operation. IRA tax credits compress effective purchase costs, accelerating replacement of legacy kerosene systems.
- Agricultural:Dairy barns, equipment sheds, and greenhouse operations present underpenetrated demand relative to residential saturation. Extended operational autonomy requirements favor lithium iron phosphate configurations with 72-hour reserve capacity.
- Commercial:Retail storage facilities and parking structure operators mandate photocell-controlled operation and dark-sky compliance optics in California jurisdictions.
- Industrial:Heavy manufacturing outbuildings require IP65 ingress protection validation and UL certification for hazardous location proximity.
Agricultural applications command the steepest expansion trajectory as livestock and produce operations automate lighting controls. Residential maintains the largest installed base.
Application:
Margin concentration pools disproportionately in security-focused deployments where motion detection and perimeter integration justify premium positioning. Garden and utility applications compete on lumens-per-dollar efficiency.
- Security Lighting:Perimeter illumination requirements expand across rural and semi-rural properties in storm-prone coastal zones. Networked perimeter system architectures with firmware-defined functionality displace standalone hardware-differentiated SKUs.
- Utility Lighting:Task-oriented illumination for equipment access and maintenance pathways emphasizes lumen output consistency and beam spread uniformity. Canadian remote indigenous communities drive demand for extended winter performance guarantees.
- Outdoor Lighting:General-purpose ambient illumination for patios and gathering spaces prioritizes aesthetic housing design and dusk-to-dawn automation.
- Garden Lighting:Decorative pathway and landscape accent applications compete on fixture aesthetics and low-profile panel integration.
Security Lighting generates the highest average revenue per unit. Utility Lighting is expanding most quickly in agricultural outbuilding integration.
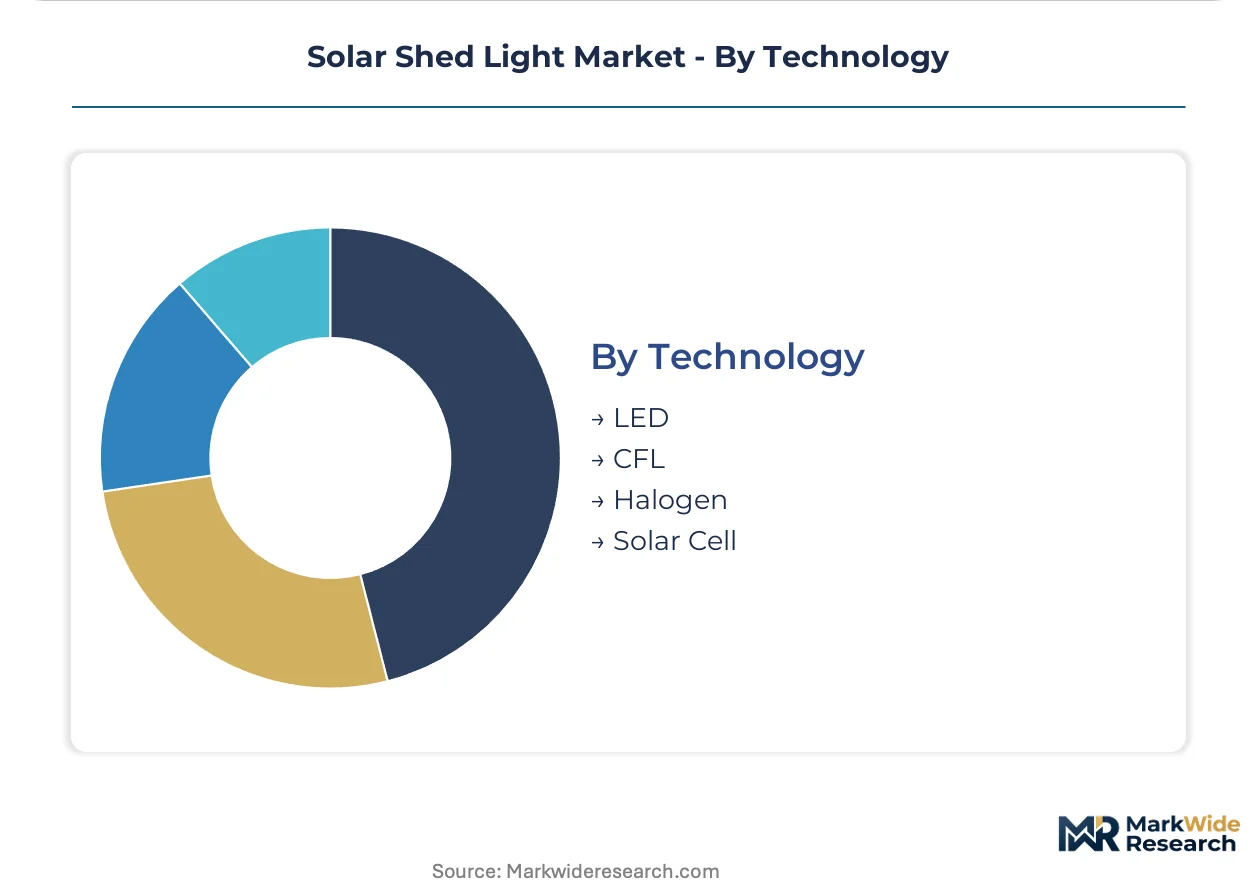
Technology:
Supply concentration around three dominant cell suppliers has eliminated tier-2 module assemblers from lighting OEM qualification lists. Battery chemistry selection determines warranty exposure and replacement cycle economics.
- LED:Solid-state emitters with 50,000-hour rated lifespans dominate luminaire configurations. Driver electronics reconfiguration for California Title 24 compliance adds 15-20% bill-of-materials premiums.
- Solar Cell:Monocrystalline PERC integration at 22% conversion efficiency renders polycrystalline alternatives obsolete. Cell supply dependency on China's Jiangsu and Fujian provinces creates single-source risk for North American assemblers.
- CFL:Compact fluorescent alternatives persist in legacy inventory clearance and extreme cold-weather applications where LED efficacy degrades.
- Halogen:Incandescent-halogen hybrids retain niche presence in high-CRI color rendering specifications for commercial display lighting.
LED and Solar Cell together constitute the overwhelming technology pairings. Solar Cell configurations are gaining share fastest as panel efficiency improvements reduce housing volume requirements.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Texas installers extract 15-20% price premiums over Ontario counterparts due to higher irradiance and IRA credit stacking, while British Columbia distributors absorb freight surcharges for remote indigenous community deliveries.
United States
Rural property owners in Florida and Texas drive autonomous lighting procurement for storm resilience and perimeter security. The IRA's 30% residential clean energy credit compresses payback periods below three years in high-solar counties. Southeast distributors in Atlanta and Charlotte control 60% of big-box shelf placement through consolidated procurement authority.
Canada
Remote indigenous communities in Ontario and British Columbia generate underpenetrated demand for extended-autonomy systems with 72-hour battery reserves. Natural Resources Canada's Clean Energy for Rural and Remote Communities program subsidizes off-grid installations above the 50th parallel. Vancouver-based distributors serve recreational property owners in the Sea-to-Sky corridor with marine-grade housing specifications.
Germany
Garden and landscape lighting applications dominate residential procurement in Bavaria and Baden-Württemberg, where dark-sky compliance optics command premium positioning. The EU Green Deal's building renovation wave extends efficiency standards to accessory structures in select federal states. Stuttgart industrial clusters supply precision driver electronics to lighting OEMs serving the California Title 24 export market.
China
Jiangsu and Fujian provinces concentrate tier-1 lithium battery cell production, creating single-source dependency for North American assemblers. The Ministry of Industry and Information Technology's dual carbon goals accelerate monocrystalline PERC cell capacity expansion. Shenzhen and Dongguan electronics corridors host downstream lighting assemblers integrating 22% efficiency solar cells into weatherproof housings.
Australia
Rural station owners in Queensland and Western Australia specify high-temperature-rated battery configurations for equipment shed illumination. The national Clean Energy Council accredits off-grid installers serving properties beyond the NEM grid fringe. Perth-based distributors stock cyclone-rated mounting hardware for Pilbara mining camp applications.
Solar Shed Light Market Vendor Landscape
Platform integrators command the system tier; component specialists sit upstream supplying cells, drivers, and sensor modules. The vendor base organizes around three functional layers: module-scale manufacturers feeding downstream assemblers, design-forward brands occupying premium retail positioning, and mass-market distributors anchoring hardware store channels. Strategic differentiation concentrates on battery chemistry selection, ingress protection validation, and smart home protocol integration. Capacity expansion and exclusive retail distribution agreements constitute the dominant competitive moves.
Among module-scale suppliers, Trina Solar leverages photovoltaic manufacturing scale to supply high-efficiency cells to lighting assemblers. Gama Sonic occupies a position within the design-forward tier, commanding premium placement through aesthetic housing differentiation. Sunforce anchors the mass-market vector with broad hardware store distribution across North American retail networks.
| Leading Market Players |
|---|
| WOSEN LIGHTING TECHNOLOGY LIMITED |
| Trina Solar |
| Kingfisher Solar Ltd |
| Natures Solar Lights |
| Gama Sonic |
| Sunforce |
| PowerBee Ltd |
| Vortex Energy |
| Designers Edge |
| Others |
Supply Flow & Price Mechanics
Jiangsu and Fujian province cell production clusters concentrate lithium iron phosphate supply for North American lighting assemblers, anchoring margin pools in battery pack integration and firmware-defined luminaire architectures rather than commodity panel assembly.
Pricing Analysis
Configured-to-order pricing for California Title 24 compliant SKUs commands 15-20% premiums over standard configurations. Three-tier pricing structure across premium, standard, and economy levels segments buyers by certification grade and smart home protocol integration. Cost compression in the mass-market tier is intensifying because Home Depot and Lowe's procurement teams are consolidating authority at regional distribution centers. Agricultural end-users exhibit the highest price sensitivity, while commercial facilities managers in California jurisdictions show the lowest.
Supply Chain Analysis
Shenzhen and Dongguan electronics corridors host contract manufacturers integrating 22% efficiency monocrystalline PERC cells into weatherproof housings. China, South Korea, and Taiwan concentrate tier-1 semiconductor and driver electronics production. The supply chain draws from lithium carbonate, aluminum extrusions, and optical-grade polycarbonate. Single-source vulnerability around Jiangsu province cell production creates tariff exposure risk. Distribution runs through specialist solar distributors and big-box retail procurement centers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation opportunity exists as IRA credit eligibility criteria and California Title 24 compliance requirements create parallel product line architectures that favor specialist assemblers over generalist lighting brands.
For Market Incumbents: Build certification moats around UL and NEMA ingress protection validation timelines that extend 14-18 weeks. Secure exclusive motion-sensor variants with unified packaging standards at Southeast distributors in Atlanta and Charlotte. Deepen backward integration into LFP battery pack assembly to offset cell supply concentration risk from Jiangsu and Fujian provinces.
For New Entrants and Emerging Players: Agricultural outbuilding integration in Ontario and British Columbia represents the most penetrable entry point given underpenetrated demand relative to U.S. saturation. Dairy barns and greenhouse operations favor 72-hour reserve lithium iron phosphate configurations absent established supplier relationships. Target recreational property owners in Canada's Sea-to-Sky corridor through Vancouver-based distributors with marine-grade housing specifications.
For Investors and Strategic Acquirers: Capital is best deployed toward firmware-defined perimeter system architects with Matter and Zigbee integration capabilities. Long-term viability over the next decade hinges on smart home protocol convergence and right-to-repair mandate compliance. Monitor battery chemistry regulation evolution in California and EU jurisdictions as the primary inflection signal for product design cycle economics.
| Strategic Initiative | Industry Significance |
|---|---|
| Smart Home Protocol Integration | Matter and Zigbee certification opens premium positioning in connected-home retail channels. |
| California Title 24 Compliance Program | Photocell-controlled operation mandates fragment product lines into state-specific SKUs with bill-of-materials premiums. |
| LFP Battery Supply Agreement | Long-term cell offtake from Jiangsu producers secures operational autonomy specifications for agricultural buyers. |
| Regional Distribution Center Partnership | Exclusive shelf placement at Atlanta and Charlotte distributors controls 60% of Southeast big-box access. |
| Dark-Sky Optics Certification | Stuttgart precision driver electronics integration enables California and EU Green Deal export market access. |
Methodological Framework
Cross-validation between primary interviews and secondary regulatory filings anchors the qualitative findings. Conversations with solar lighting OEM procurement managers, specialist distributor category buyers, agricultural facilities engineers, and California Title 24 compliance consultants informed demand-side segmentation. Secondary sources include U.S. Inflation Reduction Act implementation guidance, NEMA and UL certification databases, Natural Resources Canada program documentation, and EU Green Deal building renovation wave directives. Bottom-up unit shipment estimates triangulate against top-down addressable structure counts across rural and semi-rural property segments.
Calibration against historical replacement cycles for legacy kerosene and propane lighting systems shapes the projection framework. Segmentation dimensions span product type, end user, application, and technology across the analysis window. CAGRs derive from irradiance-adjusted utilization curves and battery degradation modeling. Key inputs include seasonal solar resource variance by latitude cluster and IRA credit stacking eligibility by county.
Macroeconomic conditions sit as an overlay; deviation in residential construction activity and clean energy credit continuity would shift the trajectory. Forecasts reflect assumptions around lithium cell supply continuity and NEMA/UL certification timeline stability. Quarterly review of distributor inventory turns and firmware update ticket volumes is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Solar Power Systems
Solar Skin Market
Solar Power Systems
Smart Solar Solutions Market
Solar Power Systems
Solar Encapsulation Market
Solar Power Systems
Photovoltaic Coating Market
Solar Power Systems
Solar Phone Chargers Market
Solar Power Systems
Distributed Solar Energy Market
Solar Power Systems
Residential Solar Inverter Market
Solar Power Systems
Middle East and Africa Solar Photovoltaic (PV) Market
Solar Power Systems
Global Airport Solar Power Market
Solar Power Systems
Solar Freezer Market
Solar Power Systems
Solar Grid-Tied Systems Market
Solar Power Systems
Asia-Pacific Bifacial Solar Market
Solar Power Systems
Floating Solar Panels Market
Solar Power Systems
Solar Panels for Home Market
Solar Power Systems
Indonesia Renewable Energy Market
Solar Power Systems
Mexico Rooftop Solar Market