
 Robotic Vacuum Cleaner Market | 2026-2036
Robotic Vacuum Cleaner Market Size, Share, and Industry Trends Forecast 2026-2036
Robotic Vacuum Cleaner Market Intelligence
Demand from commercial end-users like facility managers is bifurcating the market, which was previously dominated by homeowners. iRobot Corporation sustains its market presence through a strong brand and extensive patent portfolio in navigation technology. Meanwhile, Ecovacs Robotics competes on innovation with its dual vacuum and mopping systems. Xiaomi Corporation leverages its connected ecosystem to integrate robotic vacuums into a broader smart home strategy.
A robotic vacuum cleaner is an autonomous device designed for floor cleaning, utilizing sensors and programmable logic to navigate spaces. These units typically incorporate LiDAR or camera-based systems for mapping and operate with suction power often measured in Pascals (Pa). In terms of navigation technology, mapping & localization systems are displacing older random navigation models. The residential flooring application remains the largest segment, but commercial cleaning offers higher margin potential for advanced, durable units.
Product market access is governed by electronic safety and materials standards, such as CE marking in Europe and FCC rules in the United States. In China, compliance with national GB standards for electronics is mandatory for all manufacturers. The key strategic decision for vendors involves balancing feature innovation, particularly in AI-driven navigation, against manufacturing cost to maintain competitiveness across different price tiers.
Market Dynamics
The central force shaping the market is the rapid advancement and cost reduction of sensor and AI processing technologies. This dual progression enables manufacturers to embed sophisticated navigation and object recognition capabilities, previously exclusive to high-end models, into mass-market devices.
Growth Catalysts
- Automated Home Care:Demand from the residential flooring segment, particularly among dual-income households and the elderly, accelerates as consumers prioritize convenience and time-saving cleaning solutions.
- Advanced Sensor Fusion:The integration of LiDAR, camera-based vision, and infrared sensors improves navigation accuracy and obstacle avoidance, building consumer confidence in the device's ability to operate autonomously without causing damage.
- Rapid Urbanization in China:A growing middle class in dense urban environments in China seeks compact and efficient cleaning appliances suitable for smaller living spaces, creating a concentrated and high-volume demand center.
Market Restraints
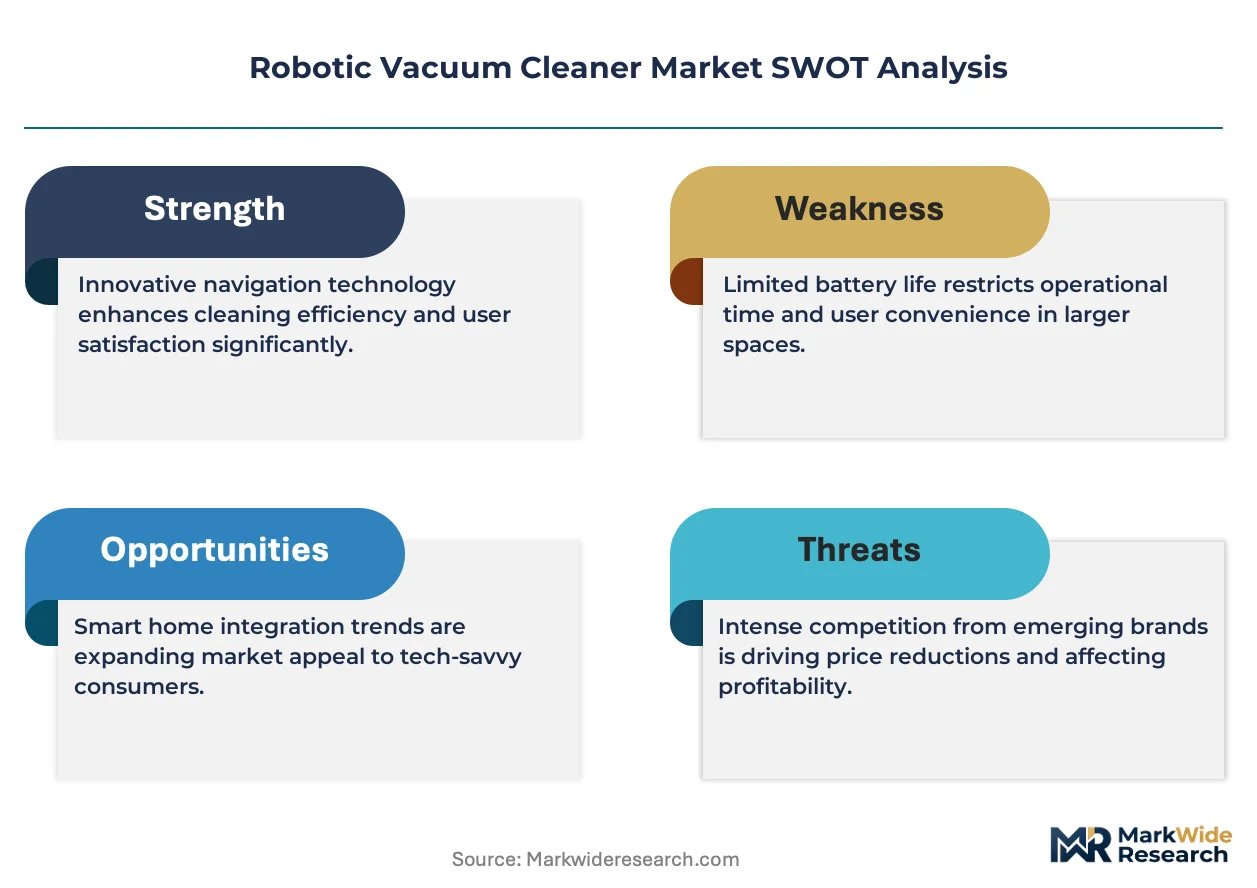
- High Initial Cost:The upfront purchase price for models with advanced navigation and mopping features remains a significant barrier for price-sensitive consumers, limiting adoption in lower-income households.
- Performance on Varied Surfaces:Many robotic vacuums struggle with transitions between hard floors and high-pile carpets, or with avoiding small, low-profile objects, leading to user frustration and a perception of unreliability.
- Data Privacy Concerns:The use of cameras and home mapping technology raises consumer privacy questions regarding data collection, storage, and security, particularly for devices connected to cloud-based services.
Strategic Opportunities
- Commercial Sector Specialization:Developing durable, high-capacity units for specific commercial applications, such as sanitizing in healthcare facilities or overnight cleaning in office buildings, offers a path to higher-margin sales. *Smart Home Ecosystem Integration: Expanding compatibility beyond proprietary apps to open standards like Matter allows robotic vacuums to integrate seamlessly with other smart home devices, enhancing overall automation and user experience.
- Emerging Market Penetration:Targeting middle-class consumers in underpenetrated regions like Latin America and Southeast Asia with affordable, mid-range models presents a significant volume growth opportunity.
Industry Challenges
- Navigating Global Regulations:Manufacturers face complexity in ensuring products comply with a patchwork of international standards, including CE marking in Europe, FCC rules in the US, and GB standards in China.
- Intellectual Property Landscape:A dense field of patents related to core technologies like simultaneous localization and mapping (SLAM) navigation creates potential litigation risks and high licensing costs for new entrants.
- Software and AI Talent Scarcity:Competition for skilled software engineers and AI specialists is intense, challenging vendors' ability to innovate on device intelligence and user interface design.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Robotic Vacuum Cleaner Market |
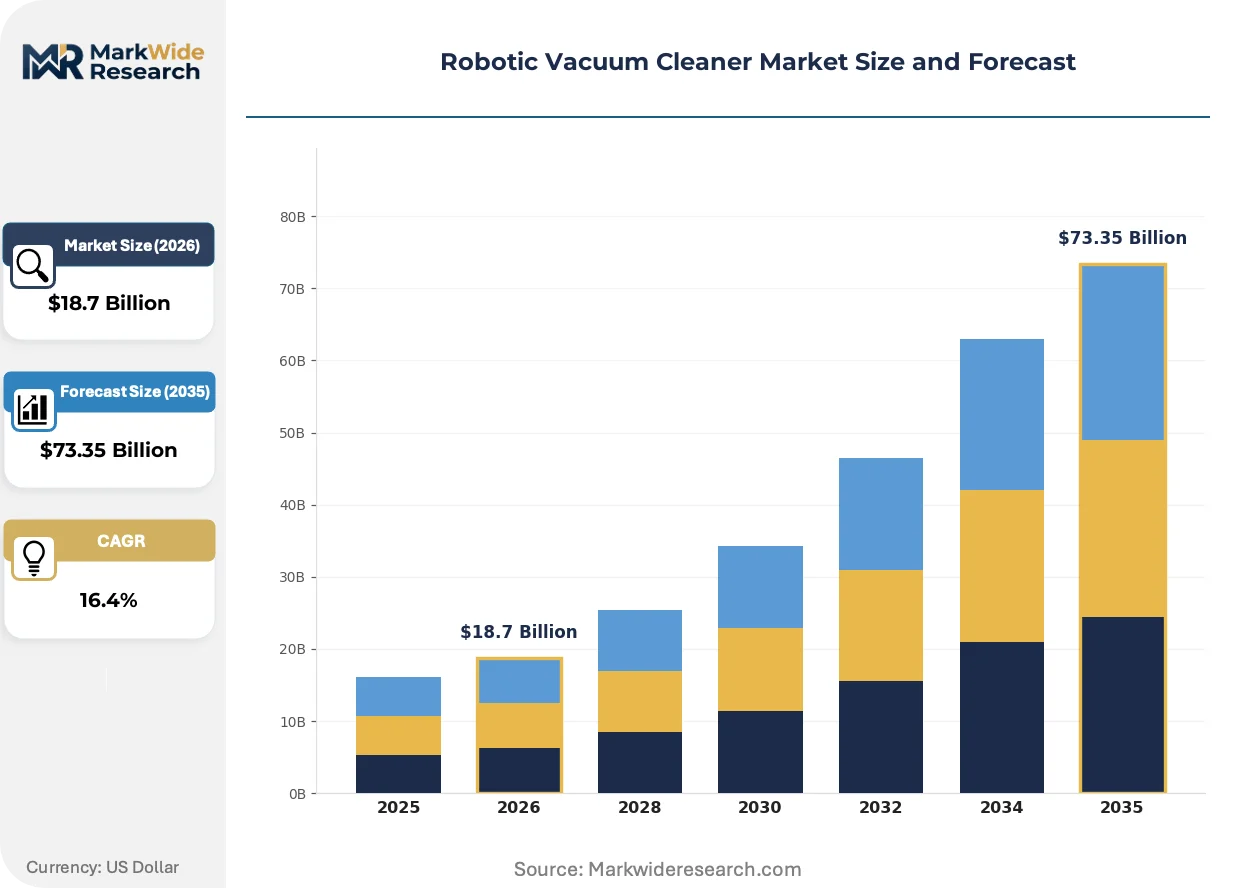
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $73.35 Billion |
| CAGR (2026 – 2036) | 16.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Lidar-Based, Camera-Based, Infrared Sensor, Ultrasonic Sensor Navigation Technology: Random, Systematic, Mapping & Localization, Obstacle Avoidance Application: Residential Flooring, Commercial Cleaning, Hospitality Maintenance, Educational Space Upkeep End User: Homeowners, Facility Managers, Cleaning Service Providers, Property Management Firms |
| Companies Covered | Beijing Roborock Technology Co Ltd, Samsung Electronics Co Ltd, iRobot Corporation, Panasonic Corporation, Dyson Ltd, Ecovacs Robotics, SharkNinja Operating LLC, Haier Group Corporation, Xiaomi Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Robotic Vacuum Cleaner Market Strategic Shifts & Innovations
The market's evolution is defined by a push toward greater autonomy and environmental awareness. Devices are becoming more intelligent in their cleaning logic, while regulatory pressures are forcing manufacturers to consider the entire product lifecycle, from energy use to repairability.
Solid-state LiDAR provides a compact, durable method for creating detailed 3D environmental maps without moving parts. Premium residential and new commercial models are rapidly adopting this technology for its enhanced reliability and precision over mechanical LiDAR. This technology is miniaturizing the complex sensor arrays once limited to industrial robotics, enabling sleeker device designs and lower production costs for consumer electronics.
European Union regulations concerning ecodesign and the right-to-repair are influencing product development globally. These initiatives compel manufacturers to design for improved durability, energy efficiency, and ease of battery replacement. The mid-tier and premium market segments are most affected, as engineering must now prioritize modularity and component accessibility over sealed, disposable designs.
A shift from a single hardware purchase to a hybrid model that includes optional software subscriptions is gaining traction. This disrupts the traditional one-time sales model by creating recurring revenue streams from features like advanced mapping analytics or enhanced security monitoring. This trend is most prominent in North America, where consumers show a higher propensity for adopting subscription-based services for connected devices.
Robotic Vacuum Cleaner Market Segmentation
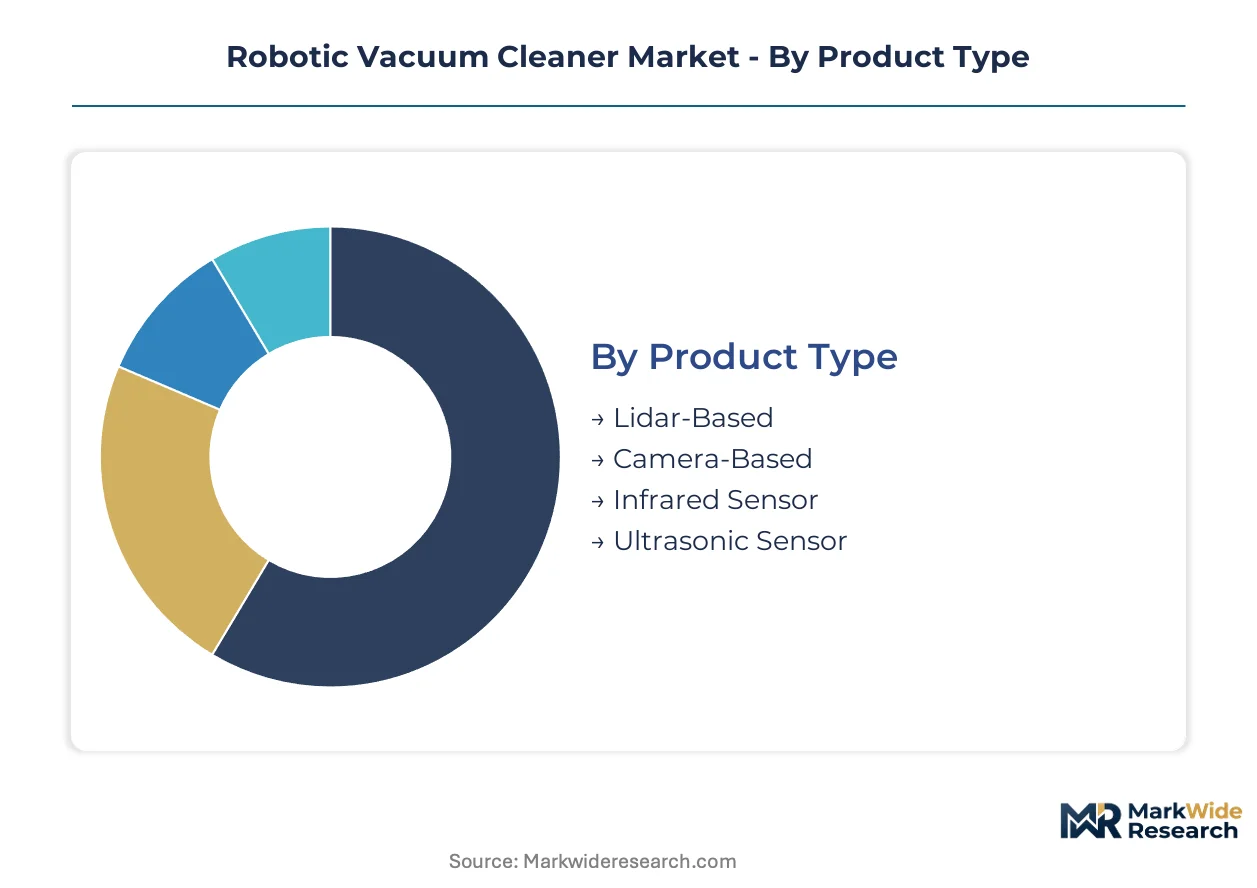
Segmentation analysis reveals the diverse technological foundations and user applications driving the robotic vacuum cleaner market. Understanding these distinct segments helps manufacturers tailor product development and market entry strategies. This granular view clarifies where innovation is concentrated and where established technologies still hold significant share.
Product Type:
Product type segmentation highlights how different sensor technologies are distributed across retail channels and specialized B2B suppliers, influencing procurement decisions.
- Lidar-Based:These robotic vacuum cleaners employ laser light to create precise 3D maps of their environment, enabling highly efficient navigation and obstacle avoidance. Demand concentrates in premium residential and commercial sectors, driven by the need for superior mapping accuracy.
- Camera-Based:Devices utilizing integrated cameras process visual data to map spaces and identify objects, offering a cost-effective solution for navigation and monitoring. Demand is strong in mass-market residential channels, where visual mapping capabilities enhance user convenience.
- Infrared Sensor:These units detect obstacles and navigate using infrared light beams, providing basic collision avoidance and boundary detection.
- Ultrasonic Sensor:Robotic vacuums with ultrasonic sensors emit sound waves to measure distances and map surroundings, offering reliable short-range obstacle detection.
Infrared Sensor models dominate the installed base. Lidar-Based products are where expansion concentrates.
Navigation Technology:
Navigation technology segmentation reflects the varying levels of maturity and sophistication available across device generations, shaping product performance expectations.
- Mapping & Localization:These systems construct and continuously update internal maps of cleaning areas, allowing for systematic coverage and efficient route planning. Demand accelerates in all market tiers as consumers prioritize comprehensive and intelligent cleaning patterns.
- Obstacle Avoidance:Advanced algorithms and sensor fusion enable these robots to detect and maneuver around household items, preventing collisions and device entanglement. This technology is critical for consumer trust and widespread adoption in residential environments.
- Random:Older models employing random navigation move unpredictably, covering areas through chance encounters with obstacles and walls.
- Systematic:These robots follow predefined patterns like parallel lines, ensuring more thorough coverage than random methods but without adaptive mapping.
Random navigation models still hold a presence in entry-level products. Mapping & Localization is expanding most quickly.
Application:
Application segmentation reveals where the highest volume demand originates for robotic vacuum cleaners, influencing manufacturing scale and product durability.
- Residential Flooring:This application covers daily cleaning tasks within homes, focusing on hard floors and low-pile carpets for individual consumers. Demand remains the largest segment, driven by dual-income households seeking time-saving automated solutions.
- Commercial Cleaning:This segment involves larger-scale, more intensive cleaning in business environments like offices or retail spaces, requiring robust and durable units. This application offers higher margin potential due to the need for advanced features and longer operating cycles.
- Hospitality Maintenance:Robotic vacuums support cleaning efforts in hotels and resorts, maintaining public areas and guest rooms efficiently.
- Educational Space Upkeep:These devices assist in cleaning schools and universities, contributing to hygiene standards in high-traffic learning environments.
Residential Flooring drives the largest volume. Commercial Cleaning offers higher margin potential.
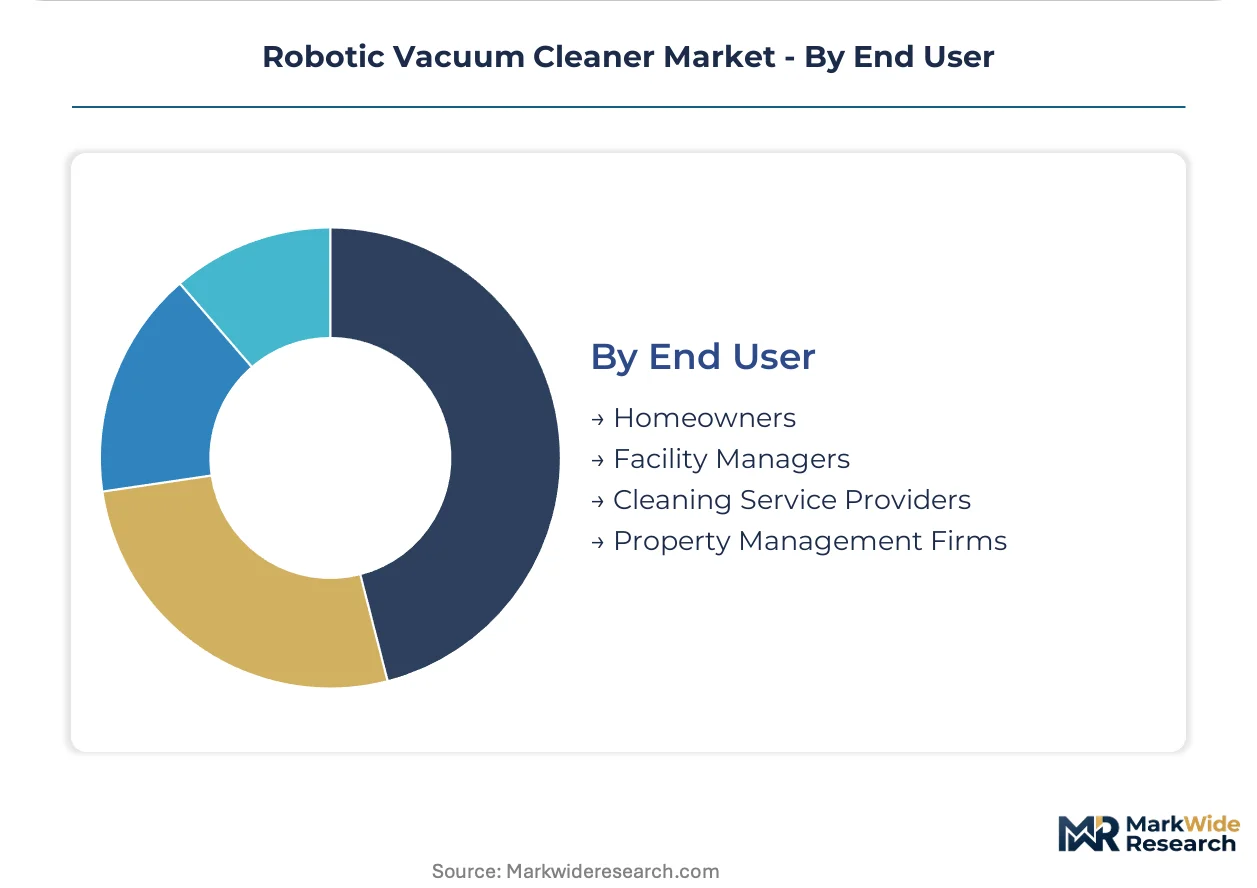
End User:
End user segmentation differentiates purchasing behaviors and specific cleaning requirements across customer types, influencing feature sets and service models.
- Homeowners:Individual consumers purchasing robotic vacuums for personal household cleaning, prioritizing convenience, ease of use, and smart home integration. This group represents the foundational demand for the market, seeking automated home care solutions.
- Facility Managers:Professionals responsible for the upkeep of commercial properties, requiring durable, high-capacity robots capable of covering large areas and specialized tasks. These buyers are bifurcating the market with their demand for advanced, commercial-grade units.
- Cleaning Service Providers:Companies offering professional cleaning services integrate robotic vacuums to enhance efficiency and reduce labor costs for their clients.
- Property Management Firms:These entities deploy robotic cleaners in multi-unit residential or commercial buildings to maintain common areas and vacant units.
Homeowners exert the most significant market influence. Facility Managers are driving product evolution in specific niches.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Homeowners and facility managers drive regional demand for robotic vacuum cleaners. Urbanization and increased disposable incomes influence purchasing patterns across diverse geographies. Regulatory frameworks also shape product market access and innovation.
United States
High consumer disposable income and a preference for smart home integration stimulate demand for advanced robotic vacuums. FCC rules govern electronic device market access, ensuring product safety and electromagnetic compatibility. Silicon Valley in California sees innovation in AI and sensor technologies for autonomous devices.
China
Rapid urbanization, a large consumer electronics market, and dense urban living spaces drive concentrated demand. National GB standards for electronics are mandatory for manufacturers, influencing product design and quality. Shenzhen in Guangdong province is a manufacturing hub for smart home devices, including robotic vacuums.
Germany
Demand for high-quality, durable cleaning solutions and a strong emphasis on energy efficiency characterize this market. CE marking is essential for market entry, alongside ecodesign regulations influencing product development. Munich and Stuttgart regions host engineering talent driving advancements in robotics and automation.
Japan
An aging population seeking automated home care and early adoption of advanced consumer electronics support market expansion. METI oversees industrial product standards, ensuring product safety and quality. Tokyo and Osaka are centers for consumer electronics R&D, fostering innovation in robotic devices.
India
Growing middle-class consumers, increasing disposable income, and a rising interest in smart home appliances are expanding the market. BIS standards for electronic goods are becoming increasingly important for market compliance. Bengaluru and Pune are emerging tech hubs, attracting investment in smart home device development.
Robotic Vacuum Cleaner Market Key Industry Players
Player mix skews toward established consumer electronics brands and specialized robotics firms. The market features both consolidated segments for premium devices and fragmented areas for entry-level models, indicating a diverse competitive landscape. Key strategic archetypes include innovation-driven specialists focused on AI and sensor advancements, ecosystem integrators leveraging smart home platforms, and cost-efficient mass-market producers. Companies frequently pursue portfolio diversification into commercial applications and strategic partnerships to expand their technological capabilities and market reach.
Specialists in advanced navigation systems, iRobot Corporation and Ecovacs Robotics, represent distinct approaches to product development. iRobot Corporation, a US-based entity, anchors its position through extensive patent portfolios in robotics and navigation technology. Ecovacs Robotics, a Chinese company, emphasizes innovation with its dual vacuum and mopping systems, competing on feature differentiation. Xiaomi Corporation, also from China, occupies a position leveraging its broad smart home ecosystem to integrate robotic vacuums into a wider connected device strategy. These companies exemplify the blend of sophisticated hardware and software intelligence driving market evolution across different price tiers.
| Leading Market Players |
|---|
| Beijing Roborock Technology Co Ltd |
| Samsung Electronics Co Ltd |
| iRobot Corporation |
| Panasonic Corporation |
| Dyson Ltd |
| Ecovacs Robotics |
| SharkNinja Operating LLC |
| Haier Group Corporation |
| Xiaomi Corporation |
| Others |
Cost & Logistics Intelligence
Solid-state LiDAR adoption is displacing mechanical counterparts, simultaneously shifting manufacturing focus to specialized sensor fabs and enabling lower device costs across premium and mid-tier segments.
Pricing Analysis
The pricing gap between current-generation LiDAR-based models and prior-generation random navigation units remains significant, reflecting technological advancements. The market primarily uses a transactional per-unit pricing model, with premium-mid-economy differentiation across product tiers. AI navigation capabilities, enhanced durability, and brand premium drive price differentiation. Pricing softness impacts entry-level models due to intense competition and component cost reduction. Lower-income households exhibit high price sensitivity, while commercial facility managers prioritize robust performance and after-sales service over initial purchase price.
Supply Chain Analysis
Inbound logistics costs, particularly for specialized sensor components, influence regional pricing structures. Geographic supply concentrates heavily in China for assembly and South Korea for advanced sensor technologies. The industry draws from critical raw material dependencies like LiDAR modules, AI processors, and high-capacity battery cells. A structural risk involves single-source vulnerability for certain proprietary navigation components. Downstream distribution primarily runs through e-commerce platforms and major consumer electronics retailers for residential units, with specialized B2B channels serving commercial clients.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The robotic vacuum cleaner market represents a significant service-attach opportunity. Software subscriptions for enhanced mapping analytics and security monitoring are expanding faster than hardware unit sales.
For Market Incumbents: Shield core patent portfolios in SLAM navigation against emerging low-cost entrants. Incumbents must invest heavily in AI-driven navigation R&D to maintain technological leadership. Expanding into commercial cleaning applications diversifies revenue streams and leverages existing brand equity. Deepening channel control through exclusive retail partnerships also reinforces market position against new competitors.
For New Entrants and Emerging Players: Lead with affordable, mid-range models featuring robust smart home ecosystem integration. Target underpenetrated emerging markets like Southeast Asia and Latin America, where demand for convenience is rising. Niche commercial applications, such as overnight sanitizing in healthcare facilities, also present high-margin white-space opportunities. A strong go-to-market angle involves emphasizing seamless integration with open smart home standards like Matter.
For Investors and Strategic Acquirers: The market sits at a growth phase that favors innovation-driven specialists with strong intellectual property. Long-term viability remains robust over the next 5-10 years, driven by sustained demand for home automation and commercial efficiency. Acquisition targets should include AI software specialists and advanced sensor technology developers. The signal to watch is the increasing adoption rate of subscription-based features and the evolution of data privacy regulations.
| Strategic Initiative | Industry Significance |
|---|---|
| Develop Solid-State LiDAR Modules | Miniaturizes sensor arrays, enabling sleeker device designs and lower production costs for consumer electronics. |
| Expand Commercial Cleaning Portfolio | Captures higher-margin sales opportunities in specialized environments like healthcare facilities. |
| Integrate with Open Smart Home Standards | Enhances user experience and broadens market reach through seamless compatibility with diverse smart home devices. |
| Offer Software Subscription Tiers | Creates recurring revenue streams from advanced mapping analytics and enhanced security monitoring features. |
| Invest in Battery Swapping Technology | Improves operational uptime for commercial units and extends product lifespan for residential users. |
Research Approach
Findings reconcile primary fieldwork against secondary review of company annual reports, technology patent databases, and government trade statistics. This involved extensive interviews with R&D directors, product managers, facility managers, and consumer electronics retailers. The analysis employed both bottom-up and top-down triangulation to validate market size and growth projections.
Segmentation dimensions modeled include product type, navigation technology, application, end user, and regional market maturity. The analytical framework projects market trajectories across the analysis window, with CAGRs derived from historical trends and future outlooks. Key forecast inputs incorporate AI chip performance roadmaps and urbanization rates in concentrated demand centers like China.
Forecasts assume regulatory continuity in Europe, the United States, and China; material policy shifts would require re-modeling. The projections reflect current assumptions regarding technological advancements and market adoption rates. Outcomes outside this envelope, such as new data privacy legislation, would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Household Items
Aquarium Heaters and Chillers Market
Household Items
Residential Water Purifier Market
Household Items
Pet Safe Cleaners Market
Household Items
North America Liquid Hand Soap Market
Household Items
Waterless Aroma Diffuser Market
Household Items
Plastic Carafe Market
Household Items
Massage Pillow Market
Household Items
Coffin and Cremation Urn Market
Household Items
Japan Faucets Market
Household Items
Asean Cookware Market
Household Items
Latex Mattress Market
Household Items
North America Tankless Water Heater Market
Household Items
Snow Blower Market
Household Items
Paper Towel Dispenser Market
Household Items
Dry Vacuum Cleaner Market
Household Items
Mirror Holder Market