
 Japan Faucets Market | 2026-2036
Japan Faucets Market Size, Share, and Industry Trends Forecast 2026-2036
Japan Faucets Market Insights
Home improvement retail channels in Japan is reconfiguring as digital platforms and consolidated builders merchants redraw how faucets reach end buyers. TOTO leverages its captive showroom network to sustain premium positioning across urban renovation projects. LIXIL Group anchors volume through integrated housing supply contracts with major Japanese developers. KVK Corporation specializes in compact thermostatic designs for the space-constrained Tokyo apartment segment.
A faucet is a valve-controlled plumbing fixture that regulates water discharge through a spout, typically incorporating ceramic disc cartridges rated for hundreds of thousands of cycles and brass or stainless steel bodies with chromium surface finishing for corrosion resistance. Its primary purpose is to deliver tempered water for sanitary, culinary, and industrial washing operations with controlled flow rates. Stainless steel and brass material grades command the structural margin pool due to durability expectations in Japanese residential applications. Single-handle configurations lead volume in new construction, while pull-down and pull-out variants capture growing retrofit demand from aging kitchen renovations.
METI enforces energy-efficiency standards that shape minimum flow-rate specifications, while JIS standards govern dimensional compatibility and material testing protocols for domestic faucet installations. The country's national building code and local prefectural plumbing regulations further constrain product design, particularly for thermostatic mixing valves in multi-unit housing. Stakeholders must monitor how PMDA-adjacent consumer safety reviews and evolving water-efficiency benchmarks will reshape certification requirements for connected and sensor-activated fixtures.
Market Dynamics
Residential renovation activity in Tokyo and Osaka is accelerating replacement demand, while METI energy-efficiency guidelines push manufacturers toward low-flow ceramic disc cartridge technology. This dual pressure from housing stock renewal and regulatory compliance is restructuring competitive positioning across the value chain.
Growth Catalysts
- Regulatory Mandates:METI energy-efficiency guidelines enforce minimum flow-rate specifications that compel manufacturers to upgrade product portfolios toward low-flow ceramic disc cartridge technology.
- Urban Housing Stock Renewal:Housing stock renewal in the Kanto region outpaces other prefectures, concentrating replacement demand in Tokyo's dense apartment and condominium segments.
- Material Durability Expectations:Stainless steel and brass material grades command structural margin pools as Japanese residential applications demand corrosion-resistant chromium surface finishing.
Market Restraints
- Input Cost Volatility:Brass and stainless steel material grades face price pressure from global metal commodity fluctuations, compressing margin pools for mid-tier manufacturers.
- Technical Limitation:Compact thermostatic designs for space-constrained Tokyo apartments require precision engineering that limits supplier base expansion.
- Regulatory Friction:JIS standards and local prefectural plumbing regulations create certification complexity that extends product development timelines.
Strategic Opportunities
- Sensor-Activated Fixtures:PMDA-adjacent consumer safety reviews and evolving water-efficiency benchmarks create certification pathways for connected faucet technologies.
- Retrofit Channel Innovation:Digital platforms and consolidated builders merchants are disintermediating traditional home improvement retail channels.
- Thermostatic Mixing Valves:Multi-unit housing regulations in Osaka and other urban prefectures drive demand for compliant thermostatic configurations.
Industry Challenges
- Certification Timeline Compression:PMDA-adjacent consumer safety reviews and METI guideline updates require continuous compliance investment.
- Supply Chain Reconfiguration:Digital platform integration demands new logistics coordination between manufacturers and consolidated builders merchants.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Japan Faucets Market |
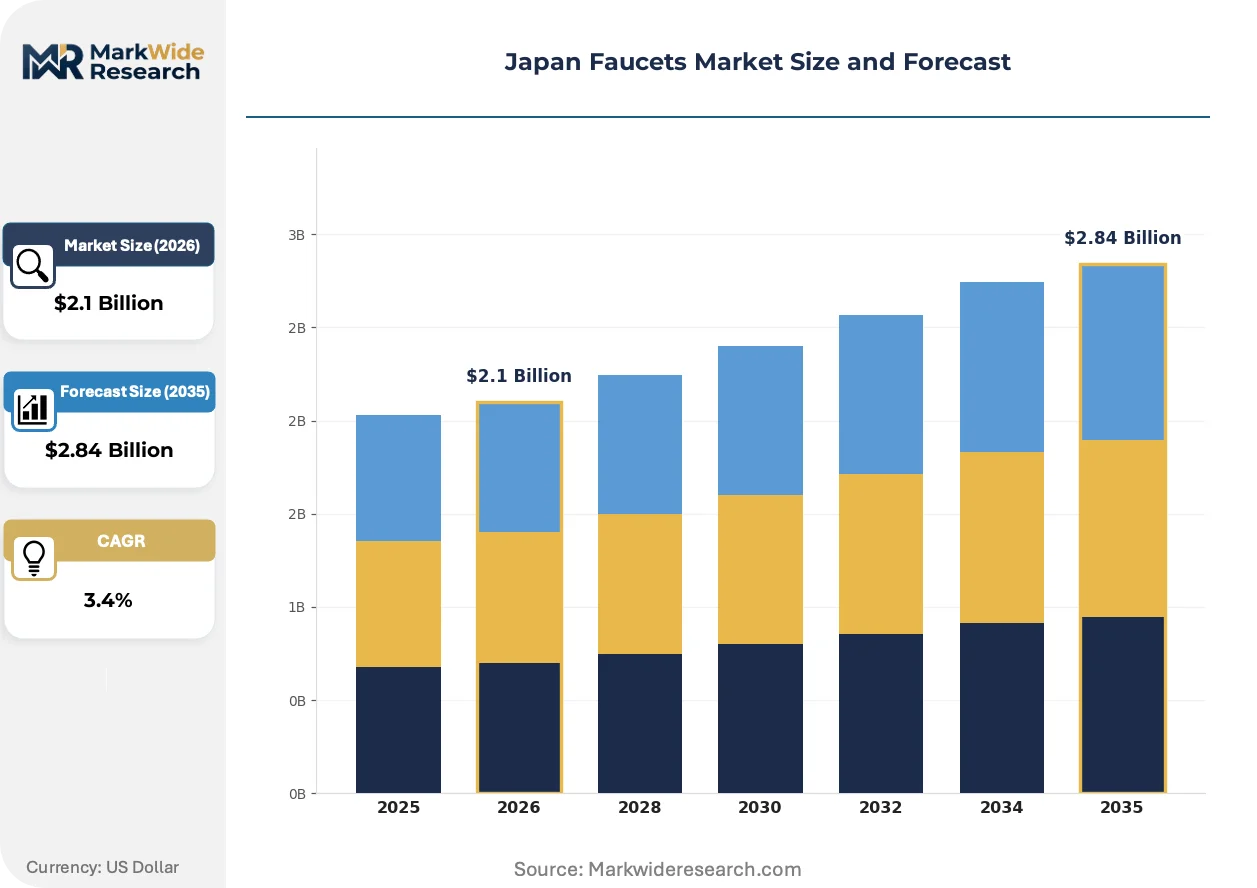
| Market Size in 2026 | $2.1 Billion |
| Market Size in 2035 | $2.84 Billion |
| CAGR (2026 – 2036) | 3.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Pull Down, Pull Out, Single Handle, Two Handle Material: Stainless Steel, Brass, Plastic, Chromium Application: Residential, Commercial, Industrial, Hospitality Installation Type: Wall Mounted, Deck Mounted, Freestanding, Under Sink |
| Companies Covered | TOTO, LIXIL Group, Panasonic, Grohe, Kohler, KVK Corporation, SANEI, INAX, Sanwa Company, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Japan Faucets Market Trends and Innovations
Technology convergence and regulatory tightening are reshaping how Japanese faucet manufacturers design, certify, and distribute products. Three distinct movements are restructuring the competitive landscape.
Touchless sensor activation systems are penetrating premium residential renovations and commercial hygiene applications. High-end Tokyo apartment developers specify these fixtures for new construction at accelerating rates. Conventional two-handle mechanical configurations are rendering obsolete in urban renovation projects where water-efficiency certification drives specification decisions.
METI enforces tightening energy-efficiency standards that reshape minimum flow-rate specifications across domestic faucet installations. Manufacturers must recalibrate ceramic disc cartridge engineering to maintain performance at reduced flow volumes. Thermostatic mixing valves in multi-unit housing face the most stringent compliance pressure, with Kanto-region developers leading specification shifts.
Consolidated builders merchants and digital platforms are capturing share from fragmented home improvement retail channels. Renovation contractors in Osaka and Tokyo increasingly source through integrated procurement portals that bundle fixtures with complementary building materials. This channel migration concentrates buying power and compresses traditional distributor margins.
Japan Faucets Market Segmentation
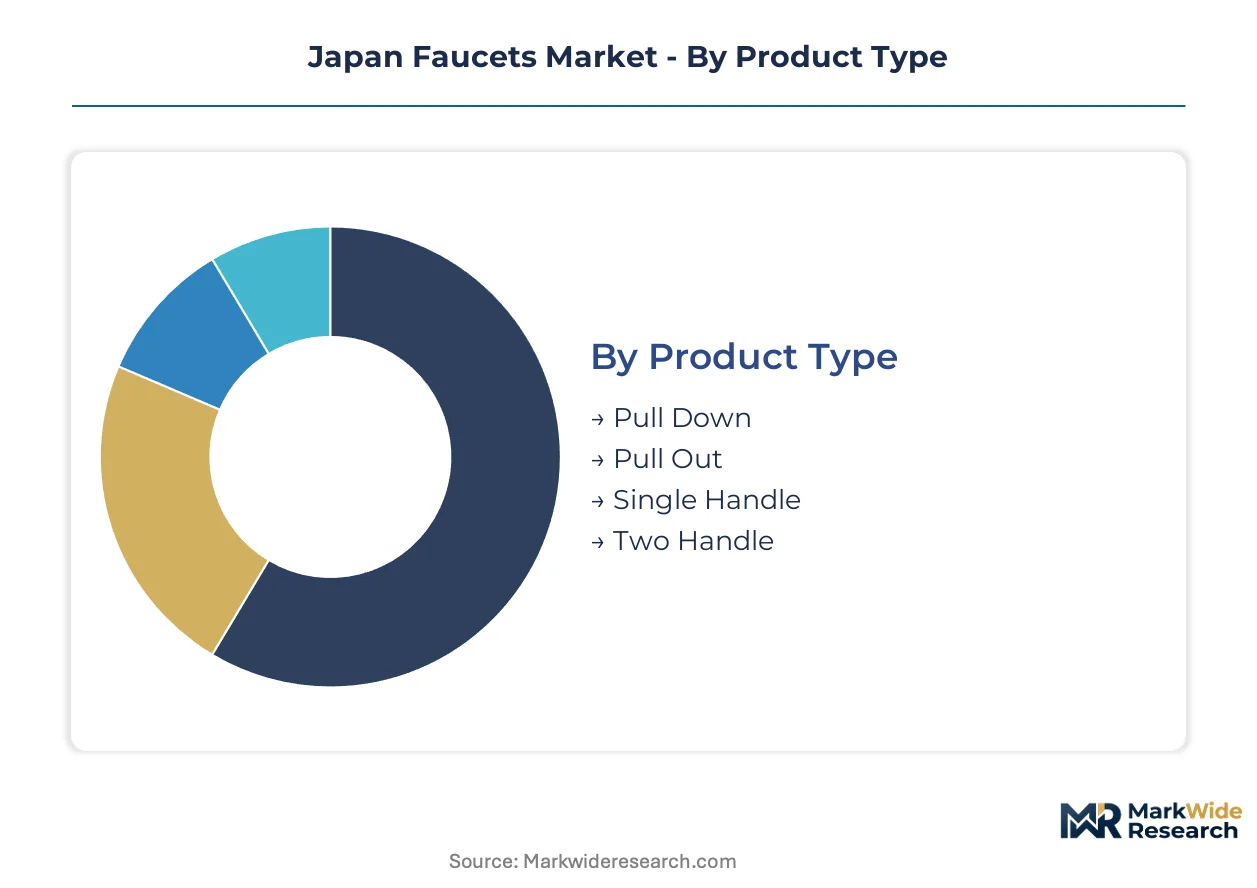
Segmentation in the Japan Faucets Market reveals how product specifications, material grades, and installation requirements diverge across Tokyo apartment renovations, Osaka commercial retrofits, and industrial facilities. Understanding these splits exposes where margin pools concentrate and where certification complexity creates competitive moats.
Product Type:
After-sales-service intensity varies sharply across handle configurations, with thermostatic and sensor-integrated variants demanding specialized technician networks that TOTO and LIXIL maintain through captive service operations.
- Pull Down:Retractable hose systems with magnetic or counterweight docking mechanisms enable extended reach for deep-basin cleaning. Demand concentrates in Tokyo's aging condominium kitchen renovations where space efficiency overrides cost sensitivity, driven by METI water-efficiency benchmarks that reward precision flow control.
- Single Handle:Ceramic disc cartridge mechanisms with 90-degree rotation range dominate new construction specifications for thermal efficiency. Osaka residential developers specify these for volume housing projects, constrained by JIS dimensional compatibility standards that limit supplier qualification.
- Pull Out:Compact spout designs with flexible hose extraction suit space-constrained Tokyo apartment segments.
- Two Handle:Traditional separate hot-cold control persists in heritage property renovations and budget-tier replacements.
Single Handle holds the largest share; momentum sits with Pull Down configurations.
Material:
Cost tier differentiation separates premium corrosion-resistant grades from economy alternatives, with material selection directly determining warranty liability and service life claims that Japanese insurers scrutinize.
- Stainless Steel:SUS304 and SUS316 grades with passivation layers deliver superior chloride resistance for coastal Osaka and Yokohama installations. Kanto region housing stock renewal drives specification, constrained by volatile nickel pricing that compresses mid-tier manufacturer margins.
- Brass:CW617N and CZ132 leaded-free alloys with chromium electroplating dominate volume residential applications. Tokyo renovation contractors specify these for cost-performance balance, pressured by global copper commodity fluctuations that force quarterly price adjustments.
- Plastic:Engineering polymer formulations with glass fiber reinforcement serve temporary and utility applications.
- Chromium:Surface finishing layer rather than structural material, applied as PVD or electroplated coating.
Brass commands the largest installed base; Stainless Steel is climbing the fastest on durability premiums.
Application:
Customer type segmentation separates end-users with distinct procurement rhythms, from fragmented residential renovation decisions to centralized commercial facility management contracts.
- Residential:Single-family and multi-unit housing installations with replacement cycles tied to renovation timing. Tokyo and Osaka metropolitan areas concentrate demand, driven by housing stock age exceeding 30 years in dense urban prefectures.
- Commercial:Office buildings, retail spaces, and institutional facilities with specification through general contractors. Kanto region development pipelines drive volume, constrained by METI energy-efficiency compliance timelines.
- Industrial:Manufacturing and processing facilities with heavy-duty flow requirements and chemical resistance needs.
- Hospitality:Hotels and restaurants with design-forward aesthetic requirements and high-frequency usage patterns.
Residential dominates volume; Commercial shows the steepest expansion trajectory on post-pandemic facility upgrades.
Installation Type:
Volume concentration favors configurations that minimize plumber labor time, with deck-mounted variants enabling faster turnaround in Japan's constrained skilled-trades environment.
- Deck Mounted:Countertop or sink-rim installation with exposed valve bodies and flexible supply connections. New construction specifications in Osaka and Nagoya favor these for installation speed, driven by general contractor pressure to compress mechanical rough-in schedules.
- Wall Mounted:Concealed valve bodies with spout-only exposure for minimalist aesthetic requirements. Tokyo luxury apartment developers specify these for premium positioning, limited by complex rough-in coordination that extends project timelines.
- Freestanding:Floor-mounted pillar designs for vessel sinks and specialty basin configurations.
- Under Sink:Concealed valve placement with remote spout operation for integrated countertop designs.
Deck Mounted holds the largest share; Wall Mounted gains share fastest on design premium capture.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Port of Yokohama's container throughput underwrites Kanto's dominance in imported fixture distribution. Japan's faucet demand clusters around three metropolitan manufacturing belts where housing stock age and renovation velocity diverge sharply.
Kanto/Tokyo
Condominium renovation cycles and single-handle specification dominance drive replacement volume. METI energy-efficiency guidelines enforce low-flow ceramic disc cartridge adoption across new installations. The Tokyo metropolitan corridor concentrates premium pull-down faucet demand from aging 1980s housing stock.
Kansai/Osaka
Commercial facility retrofits and hospitality sector upgrades accelerate thermostatic mixing valve procurement. JIS dimensional compatibility standards constrain supplier qualification for volume housing projects. The Osaka-Kobe industrial corridor anchors brass alloy processing for domestic fixture manufacturing.
Chubu/Nagoya
Automotive supplier spillover engineering capability supports precision cartridge component production. Prefectural plumbing regulations in Aichi and Gifu standardize deck-mounted installation specifications. The Nagoya manufacturing belt supplies ceramic disc mechanisms to Kanto assemblers.
Kyushu
Stainless steel SUS316 coastal corrosion resistance requirements dominate Fukuoka and Kagoshima specifications. Local prefectural codes mandate extended warranty terms for salt-air exposure environments. The Kitakyushu industrial zone processes nickel-alloy feedstock for premium fixture grades.
Hokkaido
Severe winter freeze-thaw cycles drive demand for frost-resistant valve body designs. Sapporo municipal building codes require enhanced thermal insulation for exposed plumbing infrastructure. The island's construction material logistics rely on Otaru Port import channels for specialty fixture components.
Japan Faucets Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream in the cartridge and finishing supply layers. The Japan market exhibits moderate consolidation with three dominant domestic platform holders and a fragmented upstream of brass foundries and ceramic disc mechanism suppliers. Two strategic archetypes predominate: captive showroom network operators and integrated housing supply contract anchors. Competitive moves concentrate on vertical integration into ceramic disc manufacturing and digital platform partnerships with consolidated builders merchants.
Within the integrated housing supply tier, TOTO and LIXIL Group occupy positions that exemplify divergent route-to-market strategies. KVK Corporation represents the compact thermostatic specialization archetype serving space-constrained urban segments. These three Japanese entities anchor the competitive structure without exhaustive claims about their specific strategic actions or market positions.
| Leading Market Players |
|---|
| TOTO |
| LIXIL Group |
| Panasonic |
| Grohe |
| Kohler |
| KVK Corporation |
| SANEI |
| INAX |
| Sanwa Company |
| Others |
Pricing and Supply Chain Analysis
Overcapacity in Chubu-region ceramic disc cartridge production compresses supplier margins while concentrating pricing power with Kanto-based faucet assemblers who command volume commitments. This utilization asymmetry forces upstream component specialists to absorb commodity volatility while downstream integrators capture premium-tier markups.
Pricing Analysis
Volume-discount tiering structures separate consolidated builders merchants from fragmented renovation contractors. Three-tier pricing stratification across premium sensor-activated, standard thermostatic, and economy mechanical configurations reflects METI certification grade and after-sales service bundling. Pricing pressure stems from nickel-alloy feedstock volatility in Kyushu processing zones. Small-scale Tokyo apartment renovators exhibit highest price sensitivity; luxury condominium developers show lowest.
Supply Chain Analysis
Extended payment terms from consolidated builders merchants strain brass foundry cash conversion cycles in the Osaka-Kobe corridor. Japan's faucet manufacturing draws from domestic SUS316 stainless processing, Taiwanese ceramic disc mechanism imports, and Australian nickel-alloy feedstock. Single-source vulnerability concentrates in precision cartridge component supply. Distribution runs through captive showroom networks and integrated procurement portals.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Precision thermostatic engineering talent scarcity constrains supplier base expansion and protects incumbent margin pools. This capability gap amplifies acquisition premiums for compact mixing valve specialists.
For Market Incumbents: Insulate ceramic disc cartridge supply through backward integration into Chubu precision machining capacity. Lock in exclusive distribution terms with consolidated builders merchants before digital platform consolidation accelerates. METI flow-rate specification tightening threatens non-compliant product inventories. For New Entrants and Emerging Players: Compact thermostatic retrofit kits for 1980s Tokyo condominium stock represent the most penetrable entry point. Sensor-activated hospitality fixtures in Osaka commercial retrofits offer second-tier white space. Partner with renovation contractor procurement portals for channel access. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among sensor-activated fixture operators with captive service networks. Five-to-ten year viability favors platform integrators with JIS certification depth. Monitor PMDA-adjacent safety review timelines as inflection signal for connected fixture certification costs.| Strategic Initiative | Industry Significance |
|---|---|
| Ceramic Disc Manufacturing Integration | Captive supply of precision cartridges insulates margins from Chubu foundry pricing volatility. |
| Digital Platform Partnership | Consolidated builders merchant portal access concentrates procurement influence in Tokyo-Osaka corridors. |
| Sensor-Activated Product Launch | PMDA-adjacent certification pathways unlock premium positioning in hygiene-conscious commercial segments. |
| Thermostatic Valve Specialization | Compact designs for space-constrained apartments command durable margin pools in Kanto renovation cycles. |
| Stainless Steel Grade Upgrade | SUS316 specification captures coastal corrosion resistance premiums in Yokohama and Fukuoka markets. |
Research Methodology
Operator-level perspectives from faucet product managers, ceramic disc component engineers, consolidated builders merchant procurement directors, and Tokyo renovation contractors anchored the qualitative base. Primary fieldwork combined with secondary validation from METI energy-efficiency guideline releases, JIS standards documentation, Japan Customs trade statistics, and housing stock renewal databases. Bottom-up demand modeling and top-down macroeconomic triangulation cross-checked volume assumptions.
Scenario-bracketing around regulatory compliance timelines and commodity price bands bounded the projection range across the analysis window. Segmentation dimensions modeled include handle configuration, material grade tier, installation type, and regional prefectural housing stock age. CAGRs derived from fitted growth curves applied to replacement cycle timing and new construction permit trajectories. Forecast inputs incorporated METI flow-rate specification enforcement schedules and nickel-alloy price volatility indices.
Practitioners should monitor METI guideline update announcements and PMDA safety review publication schedules for early signals of certification burden shifts. Forecasts embed assumptions regarding sustained Kanto housing stock renewal velocity and stable JIS dimensional compatibility standards. Macroeconomic contraction, accelerated regulatory tightening, or breakthrough sensor-activation cost reduction would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Household Items
Disposable Cutlery Market
Household Items
High-Efficiency Laundry Liquid Detergent Market
Household Items
Electric Soap Dispenser Market
Household Items
Insulated Lunch Box Market
Household Items
Asia Pacific Residential Vacuum Cleaners Market
Household Items
Washing Capsules Market
Household Items
Household Scales Market
Household Items
Commercial Lawnmower Market
Household Items
North America Tankless Water Heater Market
Household Items
Water Purifier Bottle Market
Household Items
Smart Connected Water Purifier Market
Household Items
Floor-Standing Integrated Smart Toilet Market
Household Items
Hand-Held Vacuum Cleaner Market
Household Items
Can Opener Market
Household Items
Fine Mist Sprayer Market
Household Items
Infrared Sauna Heaters Market