
 Coffin and Cremation Urn Market | 2026-2036
Coffin and Cremation Urn Market Size, Share, and Industry Trends Forecast 2026-2036
Coffin and Cremation Urn Market Insights
Artisan woodworking capacity is rotating toward industrial-scale production as demand for premium hardwood caskets outstrips trained labor supply in traditional manufacturing clusters. Batesville Casket Company leverages its vertically integrated domestic manufacturing network to sustain delivery reliability across funeral home channels. Passages International anchors its position through specialized biodegradable urn designs that compete on environmental certification rather than price. Matthews Aurora Funeral Solutions dominates the memorialization accessories segment, extending its product ecosystem beyond core casket sales.
Coffins and cremation urns constitute funeral containment vessels engineered to specific dimensional, load-bearing, and sealing standards for interment, entombment, or ash preservation, typically fabricated from hardwoods, metals, or engineered composites with interior fabric lining systems. Metal caskets sustain higher margin pools due to gasket-sealed construction and perpetual warranty positioning, while biodegradable material lines lead volume growth as regulatory burial ground requirements shift toward environmental compliance. Funeral homes remain the dominant end-user channel, though online retail is accelerating as direct-to-consumer platforms reduce traditional intermediary dependencies.
FDA oversight of embalming fluid contact materials, EPA guidelines on cemetery land use and burial container biodegradability, and FTC Funeral Rule disclosure requirements collectively shape product labeling, pricing transparency, and material permissibility across the United States market. State-level cemetery regulations add further fragmentation, with Massachusetts and California maintaining distinct container standards for green burial grounds. Stakeholders must monitor evolving compostability certification frameworks and direct-shipping compliance obligations as channel structures fragment beyond traditional funeral home intermediation.
Market Dynamics
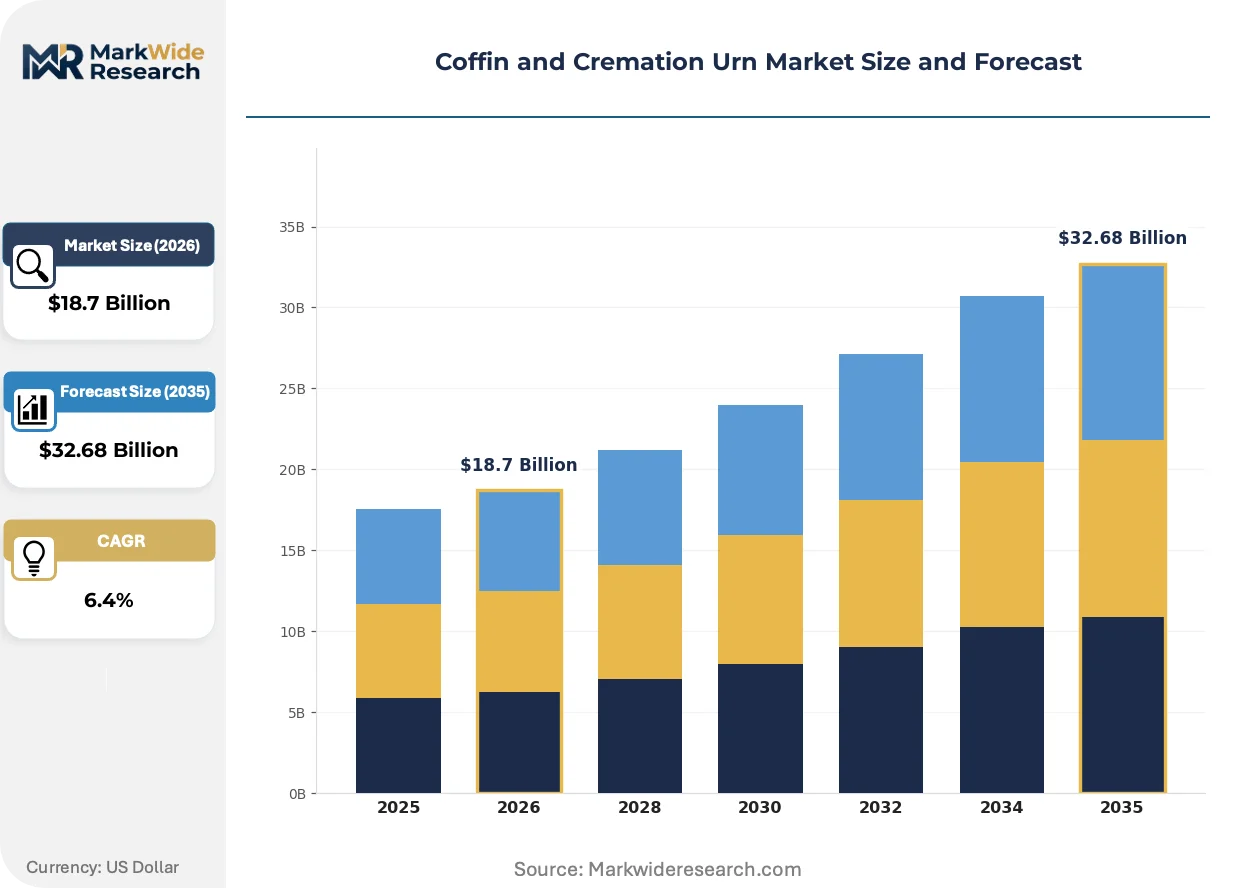
The coffin and cremation urn market is restructuring around channel disintermediation as direct-to-consumer platforms erode funeral home procurement monopolies while biodegradable certification requirements from the EU Green Deal redirect manufacturing investment toward compostable product lines.
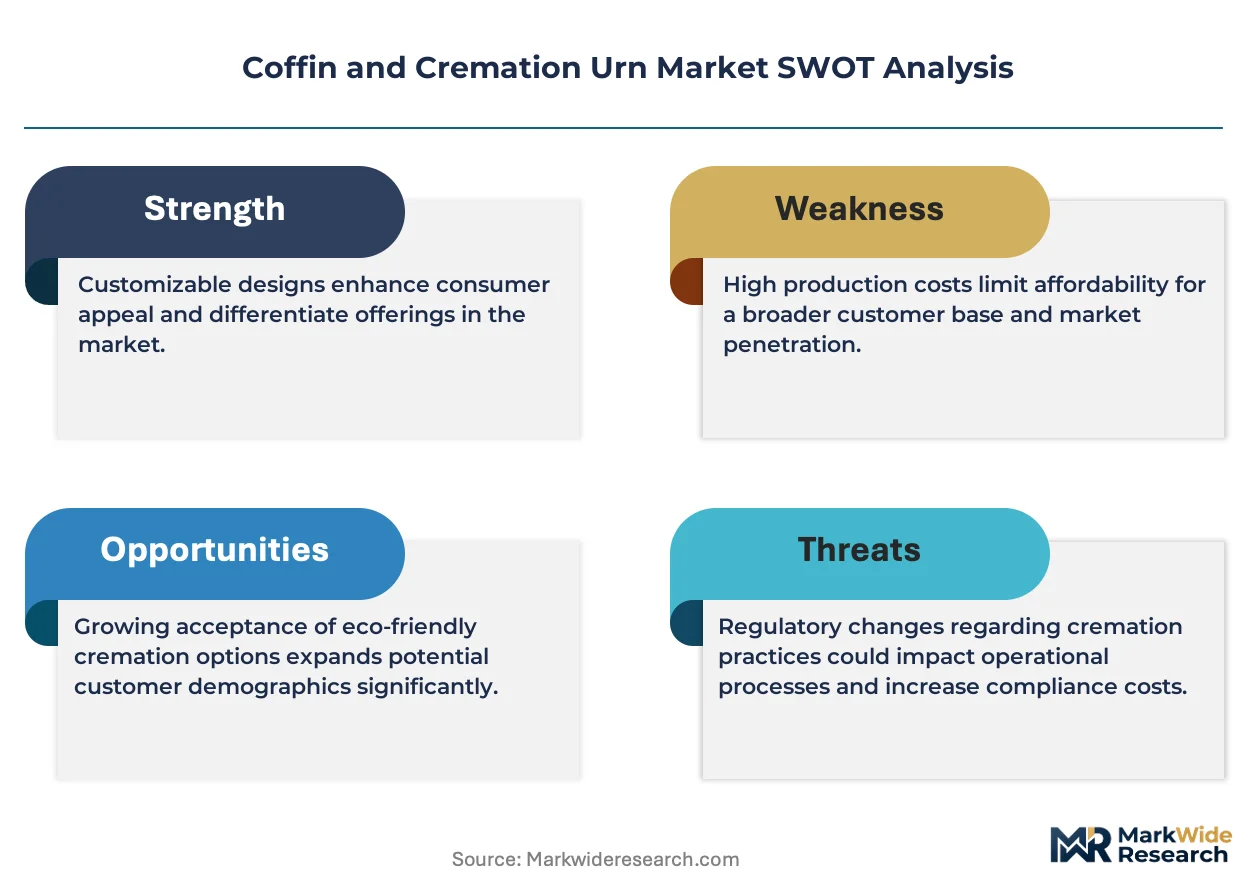
Growth Catalysts
- Cremation Rate Acceleration:Western markets are witnessing sustained shifts toward cremation over traditional burial, expanding addressable demand for urn products and ash-containment vessels across funeral home and retail channels.
- EU Green Deal Certification:Compostability mandates for burial containers are creating compliant product premiums and redirecting R&D budgets toward certified biodegradable material formulations.
- Artisan Cluster Industrialization:Hardwood casket manufacturing hubs in the United States and Europe are scaling from craft workshops to automated production lines to match premium demand.
Market Restraints
- Hardwood Supply Concentration:Premium oak, mahogany, and walnut feedstock availability tightens as sustainable forestry certification requirements restrict supplier pools in North American and European sourcing regions.
- Funeral Home Channel Control:Traditional intermediaries maintain contractual exclusivity arrangements with grieving families, limiting direct manufacturer access to end purchasers.
- Metal Price Volatility:Copper, bronze, and stainless steel input costs fluctuate with commodity cycles, compressing margin stability for gasket-sealed casket manufacturers.
Strategic Opportunities
- Green Burial Ground Expansion:Massachusetts and California are pioneering state-level container standards that favor unembalmed, biodegradable interment, creating first-mover certification advantages for compliant suppliers.
- Online Direct-to-Consumer Platforms:E-commerce channels are capturing share from funeral home intermediation by offering price transparency and customization tools previously gatekept by traditional distributors.
- Memorialization Accessories Convergence:Integration of digital memorial technology with physical urn products creates bundled value propositions beyond containment function alone.
Industry Challenges
- Skilled Woodworking Labor Scarcity:Traditional craft training pipelines fail to replenish retiring artisans, forcing manufacturers to automate joinery and finishing processes without quality degradation.
- Multi-Jurisdictional Compliance Burden:FTC Funeral Rule disclosure requirements, state cemetery regulations, and emerging compostability frameworks impose overlapping documentation and testing obligations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Coffin and Cremation Urn Market |
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $32.68 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Coffins, Urns, Caskets, Vaults Material: Wood, Metal, Biodegradable, Glass End User: Funeral Homes, Individuals, Cemeteries, Memorial Services Distribution Channel: Online Retail, Direct Sales, Wholesale, Specialty Stores |
| Companies Covered | Titan Casket, Midwest Casket Company, Batesville Casket Company, Northwoods Casket Company, Passages International, Matthews Aurora Funeral Solutions, Thacker Caskets, OneWorld Memorials, The Wilbert Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Coffin and Cremation Urn Market Trends and Innovations
Digital memorialization technology is converging with physical containment products, while regulatory pressure on material biodegradability accelerates formulation innovation. Distribution channel fragmentation is simultaneously compressing traditional funeral home intermediation.
Embedded NFC chip technology is miniaturizing within cremation urns to enable dynamic digital tribute access. Funeral homes in metropolitan United States markets are piloting these connected vessels for tech-forward clientele. This capability is miniaturizing the distinction between physical memorialization and online legacy preservation, compressing what were separate purchasing decisions into unified product bundles.
EPA guidelines on cemetery land use and burial container biodegradability are tightening material permissibility standards for interment products. Manufacturers serving United States green burial grounds must now document soil-impact testing and decomposition timelines. Metal casket producers face the steepest compliance recalibration as gasket-sealed construction conflicts with permeability requirements.
Direct-to-consumer purchasing patterns are displacing funeral home channel gatekeeping for cremation urn selection. Bereaved families increasingly research and order containment vessels online before engaging funeral service providers. This behavioral shift concentrates in United States coastal metropolitan markets where price transparency tools and overnight shipping logistics reduce traditional intermediary value.
Coffin and Cremation Urn Market Segmentation
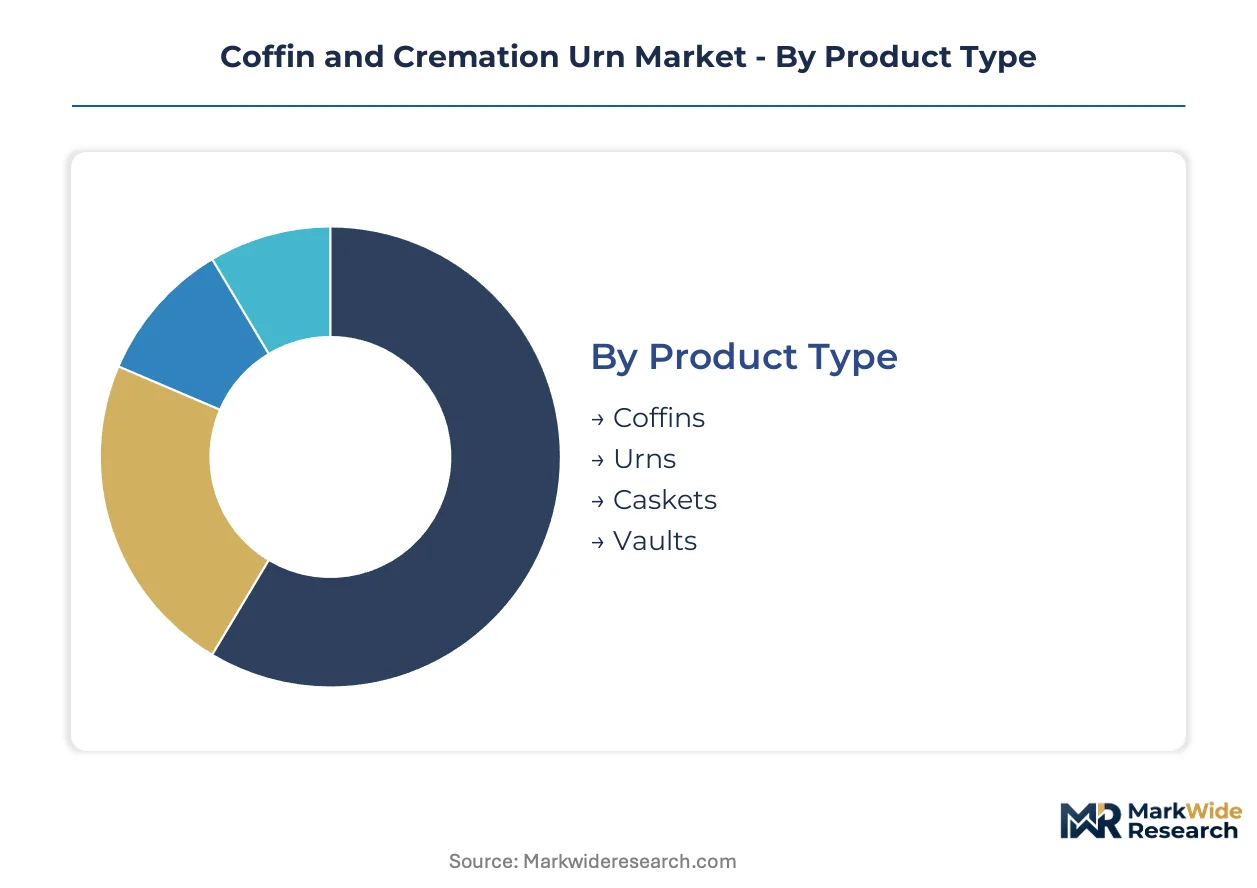
Segmentation in the coffin and cremation urn market reveals how margin pools concentrate in metal caskets and biodegradable urns while distribution channels fragment beyond traditional funeral home intermediation. Understanding these divisions exposes where certification premiums, channel disintermediation, and material innovation reshape competitive positioning.
Product Type:
Margin pools concentrate in metal caskets and urns, where gasket-sealed construction and perpetual warranty positioning sustain premium pricing power.
- Coffins:Tapered hexagonal vessels constructed from hardwoods or fiberboard with fabric-lined interiors, historically dominant in European and Commonwealth burial traditions. Demand concentrates in the United Kingdom and Ireland, where tapered-end construction remains culturally preferred over rectangular casket formats.
- Urns:Ash-containment vessels ranging from 200-400 cubic inches capacity, fabricated from metals, ceramics, biodegradable composites, or glass with threaded or gasket-sealed closures. Cremation rate acceleration across the United States, Canada, and Australia positions urns as the fastest-expanding product line, with direct-to-consumer channels capturing procurement decisions previously controlled by funeral homes.
- Caskets:Rectangular four-sided containers with hinged split lids, constructed from 18-20 gauge steel, copper, bronze, or premium hardwoods with interior sealing systems. Metal casket manufacturers command the highest margin pools through gasket technology and warranty differentiation.
- Vaults:Outer burial containers of reinforced concrete, polymer, or metal designed to prevent ground collapse and protect casket integrity. Cemetery operators in the United States mandate vault installation for lawn maintenance equipment compatibility, sustaining steady demand despite cremation substitution.
Caskets hold installed capacity. Urns are rotating up the share rankings.
Material:
Cost tier stratification separates premium oak and bronze from economy fiberboard and basic steel, with biodegradable materials commanding compliance-driven premiums.
- Wood:Solid hardwood construction from oak, mahogany, cherry, and walnut with dovetail or dowel joinery, fabric-draped interiors, and adjustable bed mechanisms. Artisan woodworking clusters in Indiana and Ohio face labor scarcity as demand outstrips trained craft supply, forcing automation investment.
- Metal:Steel, copper, bronze, and stainless steel fabrication with continuous weld construction, gasket-sealed lids, and adjustable interior beds. Gasket technology and perpetual warranty positioning sustain the highest margin pools, though copper and bronze input volatility compresses manufacturer stability.
- Biodegradable:Compostable formulations from bamboo, willow, seagrass, recycled paper, or plant-based polymers designed for green burial ground compliance. EU Green Deal certification requirements redirect R&D investment toward documented soil-impact testing and decomposition timeline validation.
- Glass:Hand-blown or molded vessels for cremation ash display, often combined with artistic coloration or embedded memorial elements. Specialty glass studios in Venice and Seattle supply limited production runs for premium memorialization segments.
Metal maintains the largest installed base. Biodegradable materials are climbing the fastest.
End User:
Customer type determines procurement control, with funeral homes retaining contractual gatekeeping power while individuals increasingly research and purchase directly.
- Funeral Homes:Licensed funeral service providers maintaining casket showrooms, urn inventory, and contractual arrangements with grieving families. Traditional channel control persists through emotional timing of purchase decisions and regulatory compliance bundling.
- Individuals:Bereaved family members or pre-need purchasers researching containment vessel options independently. Direct purchasing concentrates in United States coastal metropolitan markets where overnight shipping and price transparency tools reduce funeral home intermediary value.
- Cemeteries:Burial ground operators specifying vault requirements and container standards for interment permissibility. Green burial grounds in Massachusetts and California pioneer state-level biodegradable container mandates.
- Memorial Services:Cremation-only providers and celebration-of-life coordinators sourcing urns and scattering vessels without traditional funeral home infrastructure. This segment expands with cremation rate acceleration and secular memorialization preferences.
Funeral homes retain contractual installed base. Individual direct purchasing is gaining share fastest.
Distribution Channel:
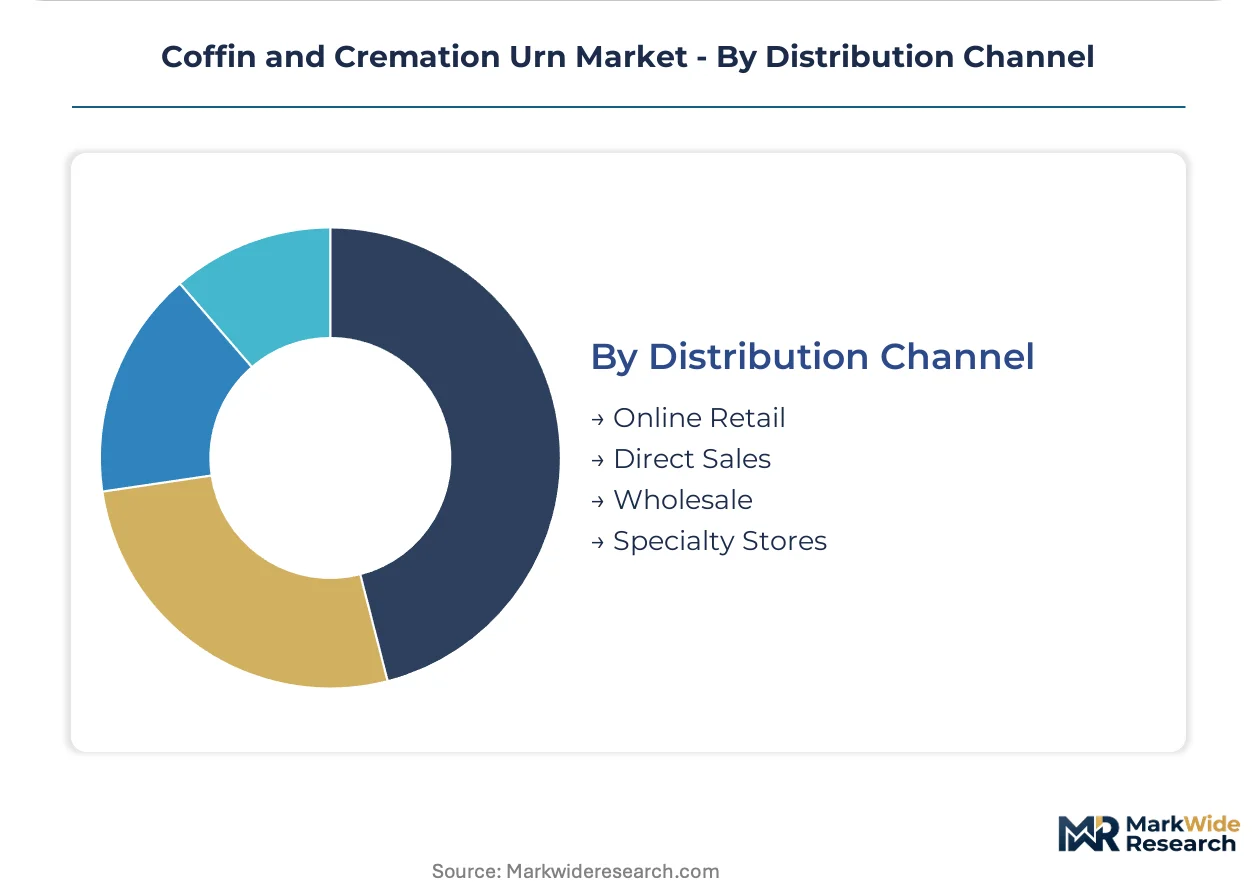
Volume concentration remains with wholesale funeral home supply, though online retail is compressing traditional intermediary dependencies through price transparency.
- Online Retail:E-commerce platforms offering urn catalogs with customization tools, price comparison, and direct-to-consumer shipping. FTC Funeral Rule compliance obligations for pricing disclosure apply to digital channels, creating documentation burdens for marketplace sellers.
- Direct Sales:Manufacturer-direct procurement by large funeral home chains and buying groups, bypassing regional distributors. Batesville Casket Company and Matthews Aurora leverage vertically integrated networks to sustain delivery reliability through captive distribution.
- Wholesale:Regional distributors maintaining funeral home relationships, showroom inventory financing, and local delivery logistics. Wholesale channels retain volume concentration through credit terms and relationship-based procurement habits.
- Specialty Stores:Memorialization boutiques and religious supply retailers serving niche aesthetic preferences and cultural traditions. Limited footprint concentrates in ethnic community centers and historic district retail clusters.
Wholesale maintains volume leadership. Online retail is climbing the channel rankings fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
FTC Funeral Rule disclosure requirements anchor the United States as the dominant geography, where direct-to-consumer online channels are capturing procurement share from funeral home intermediaries. Cremation rate acceleration and biodegradable certification mandates from the EU Green Deal are redirecting manufacturing investment toward compostable product lines across Western markets.
United States
Cremation rates now exceed burial rates in coastal metropolitan markets, expanding urn demand through direct-to-consumer platforms that bypass traditional funeral home gatekeeping. The FTC Funeral Rule mandates itemized price disclosure, enabling price transparency tools that reduce intermediary control. Batesville Casket Company leverages vertically integrated domestic manufacturing clusters in Indiana and Ohio to sustain delivery reliability across funeral home channels.
Germany
Green burial ground expansion in Bavaria and North Rhine-Westphalia is driving demand for EU Green Deal-certified biodegradable containers. The country's national environmental regulator enforces compostability documentation and soil-impact testing for burial products. Artisan woodworking capacity in the Black Forest region is rotating toward industrial-scale production to match premium hardwood casket demand.
United Kingdom
Tapered hexagonal coffin formats retain cultural preference over rectangular caskets, sustaining specialized manufacturing demand in traditional craft clusters. The Environment Agency regulates biodegradable burial container standards for natural burial grounds. Manufacturing concentration in the Midlands and Yorkshire is scaling automated joinery processes to address skilled woodworking labor scarcity.
Japan
Cremation dominates interment practices at rates exceeding Western markets, positioning urns as the primary containment vessel category. METI guidelines shape memorialization product standards and digital tribute integration requirements. Production clusters in Nagoya and Osaka are piloting NFC-embedded urn technology for tech-forward metropolitan clientele.
France
Green burial ground pioneers in the Île-de-France and Provence-Alpes-Côte d'Azur regions are establishing state-level container standards favoring unembalmed, biodegradable interment. ANSM and environmental regulators enforce material permissibility and decomposition timeline documentation. Specialty glass studios in traditional craft centers supply limited production runs for premium artistic memorialization segments.
Coffin and Cremation Urn Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes, with gasket-sealed metal casket specialists commanding premium margin pools while biodegradable material innovators capture compliance-driven growth. The market structures around three tiers: vertically integrated domestic manufacturers sustaining funeral home channel control, specialized biodegradable designers competing on environmental certification, and direct-to-consumer platforms eroding traditional intermediary dependencies. Dominant competitive moves include backward integration into hardwood feedstock and captive supply of gasket technology, alongside geographic expansion into green burial ground markets with pioneering regulatory frameworks.
Among United States-based fabricators, Batesville Casket Company and Matthews Aurora Funeral Solutions occupy positions within the vertically integrated tier, while Passages International exemplifies the biodegradable specialization archetype. These three anchors demonstrate how competitive positioning separates around channel control versus certification-driven product differentiation.
| Leading Market Players |
|---|
| Titan Casket |
| Midwest Casket Company |
| Batesville Casket Company |
| Northwoods Casket Company |
| Passages International |
| Matthews Aurora Funeral Solutions |
| Thacker Caskets |
| OneWorld Memorials |
| The Wilbert Group |
| Others |
Pricing and Supply Chain Analysis
EU Green Deal compostability certification gates both supply qualification and price differentiation simultaneously, forcing manufacturers to document soil-impact testing before accessing premium green burial ground contracts while funeral home intermediaries resist margin compression from direct-to-consumer channels.
Pricing Analysis
United States coastal markets command 15-25% premiums over Midwest funeral home corridors due to shipping logistics and green burial ground density. Three-tier pricing structure across premium gasket-sealed metal, standard hardwood, and economy fiberboard caskets separates funeral home showroom offerings from online direct sales. Cost compression in economy steel tiers intensifies because of commodity spot volatility and Asian import competition. Individual direct purchasers exhibit highest price sensitivity through comparison shopping tools, while grieving families under funeral home contractual arrangements show lowest sensitivity due to emotional timing and bundled service packaging.
Supply Chain Analysis
Just-in-time inventory dominates funeral home channel fulfillment, while strategic stockpiling of certified biodegradable feedstock secures green burial ground contract eligibility. Manufacturing concentrates in the United States, China, and Poland, with hardwood milling anchored in Indiana and Ohio clusters. Raw material dependencies span sustainable-certified oak and mahogany, copper and bronze sheet metal, and bamboo-based polymer composites. Single-source vulnerability concentrates in gasket-sealing technology suppliers serving metal casket assemblers. Distribution runs through wholesale funeral home supply networks, though online retail platforms are bypassing traditional credit-term relationships.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Digital memorialization platform economics are inflecting as NFC-embedded urn technology collapses physical and online tribute purchasing into unified product bundles, creating interoperability standards that reshape procurement control.
For Market Incumbents: Fortify funeral home channel relationships through exclusive certification co-development with green burial ground operators, while accelerating backward integration into sustainable hardwood feedstock to offset artisan labor scarcity. The direct-to-consumer platform threat demands captive supply chain control over biodegradable material formulations to preserve margin pools against price-transparent online competitors. For New Entrants and Emerging Players: Anchor in Massachusetts and California green burial ground segments where state-level container standards favor unembalmed biodegradable interment and incumbent certification lags create procurement openings. Memorial services and cremation-only providers represent the most penetrable end-user segment, accessible through sustainability-forward direct sales teams bypassing funeral home gatekeeping. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting downward across biodegradable urn manufacturing as automated fiber molding displaces hand-craft production, compressing break-even thresholds for mid-scale entrants. Acquisition targets should cluster around EU Green Deal-certified designers with documented soil-impact testing capabilities, not legacy metal casket fabricators facing compliance recalibration. Watch for cremation rate inflection crossing 60% in additional United States states as signal for urn demand acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Biodegradable Certification Investment | EU Green Deal compliance unlocks premium green burial ground contracts in Germany and France. |
| Direct-to-Consumer Platform Launch | Online retail with overnight shipping erodes funeral home procurement monopolies in United States coastal metros. |
| Digital Memorial Integration | NFC-embedded urn technology bundles physical containment with dynamic tribute access for tech-forward clientele. |
| Automated Joinery Scale-Up | Industrial production lines address skilled woodworking labor scarcity in Indiana and Ohio manufacturing clusters. |
| Green Burial Ground Partnership | State-level container standard co-development secures first-mover advantage in Massachusetts and California markets. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted across funeral home proprietors, cemetery operators, biodegradable material formulators, and cremation service directors. Secondary validation drew from EPA burial container guidelines, FTC Funeral Rule disclosure filings, EU Green Deal certification databases, and state cemetery regulation records. Bottom-up segment sizing triangulated against top-down macroeconomic indicators.
Across the analysis window, the forecasting framework modeled product type, material grade, end-user category, and distribution channel dimensions. CAGRs were derived from trend extrapolation of cremation rate trajectories and regulatory adoption curves. Industry-specific inputs included green burial ground expansion pipelines and artisan woodworking labor replenishment rates.
Decision-makers should treat outputs as directional under assumptions of sustained cremation substitution and stable EU Green Deal enforcement; material deviation would warrant model refresh. Revision becomes warranted when biodegradable certification timeline requirements cross implementation thresholds or direct-to-consumer shipping logistics achieve next-day coverage parity with wholesale distribution.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Household Items
Range Hood Cleaning Service Market
Household Items
Smart Faucets Market
Household Items
Shoe Shine Machine Market
Household Items
Kitchen Towel Market
Household Items
Tiki Torch Market
Household Items
Can Opener Market
Household Items
Global Ceramic Tableware Market
Household Items
Asia-Pacific Digital Showers Market
Household Items
US Soap Dispenser Market
Household Items
Germany Induction Hobs Market
Household Items
Kuwait Gas Hobs Market
Household Items
Ceramic Travel Mug Market
Household Items
Smart Fork Market
Household Items
Portable Iron Market
Household Items
Smart Bathroom Products Market
Household Items
Cat Hair Remover Market