
 Carpet Cleaner Market | 2026-2036
Carpet Cleaner Market Size, Share, and Industry Trends Forecast 2026-2036
Carpet Cleaner Market Intelligence
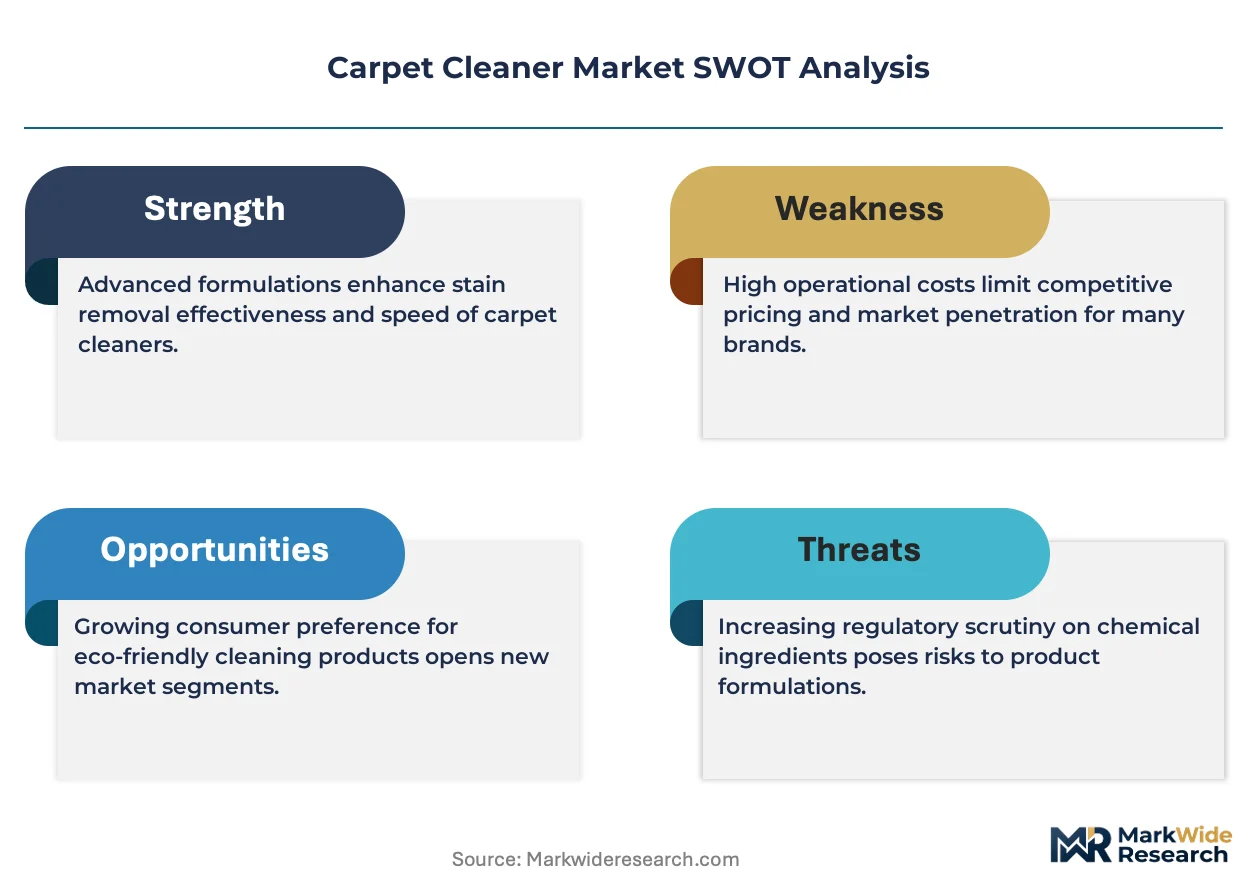
Leasing and rental-service models for commercial-grade extraction equipment is tilting competitive dynamics toward capital-light operators. Rug Doctor LLC leverages its rental kiosk network across North American retail chains to sustain household penetration without direct ownership costs. BISSELL Inc. anchors its position through vertical integration into heated cleaning solution chemistry. Alfred Kärcher SE & Co. KG dominates the commercial service tier with high-pressure hot water extraction systems engineered for extended duty cycles.
A carpet cleaner is a powered appliance or service system designed to dislodge, suspend, and extract soil from textile floor coverings through mechanical agitation combined with heated solution injection and vacuum recovery, typically operating at solution temperatures between 120°F and 220°F depending on fiber compatibility. Its primary purpose spans residential hygiene maintenance, commercial facility upkeep, and hospitality asset preservation where foot traffic accelerates particulate embedding. Upright units lead residential volume due to storage convenience and maneuverability in constrained floor plans, while hot water extraction technology captures the deepest margin pools in commercial contracts because heat transfer improves surfactant efficacy and reduces chemical loading. Spot cleaner portability is gaining traction among apartment dwellers and automotive detailers who prioritize immediate stain response over whole-room coverage.
EPA Safer Choice standards constrain volatile organic compound content in ready-to-use formulations, compelling chemistry suppliers to redesign surfactant packages. OSHA workplace exposure guidelines for cleaning staff influence equipment specifications around noise thresholds and ergonomic lift requirements in commercial procurement. The EU REACH framework restricts certain preservative chemistries in cleaning solutions exported to European markets. Stakeholders must monitor evolving chemical restriction schedules and decide whether to regionalize formulation portfolios or pursue universal compliant chemistries that sacrifice some cleaning performance.
Market Dynamics
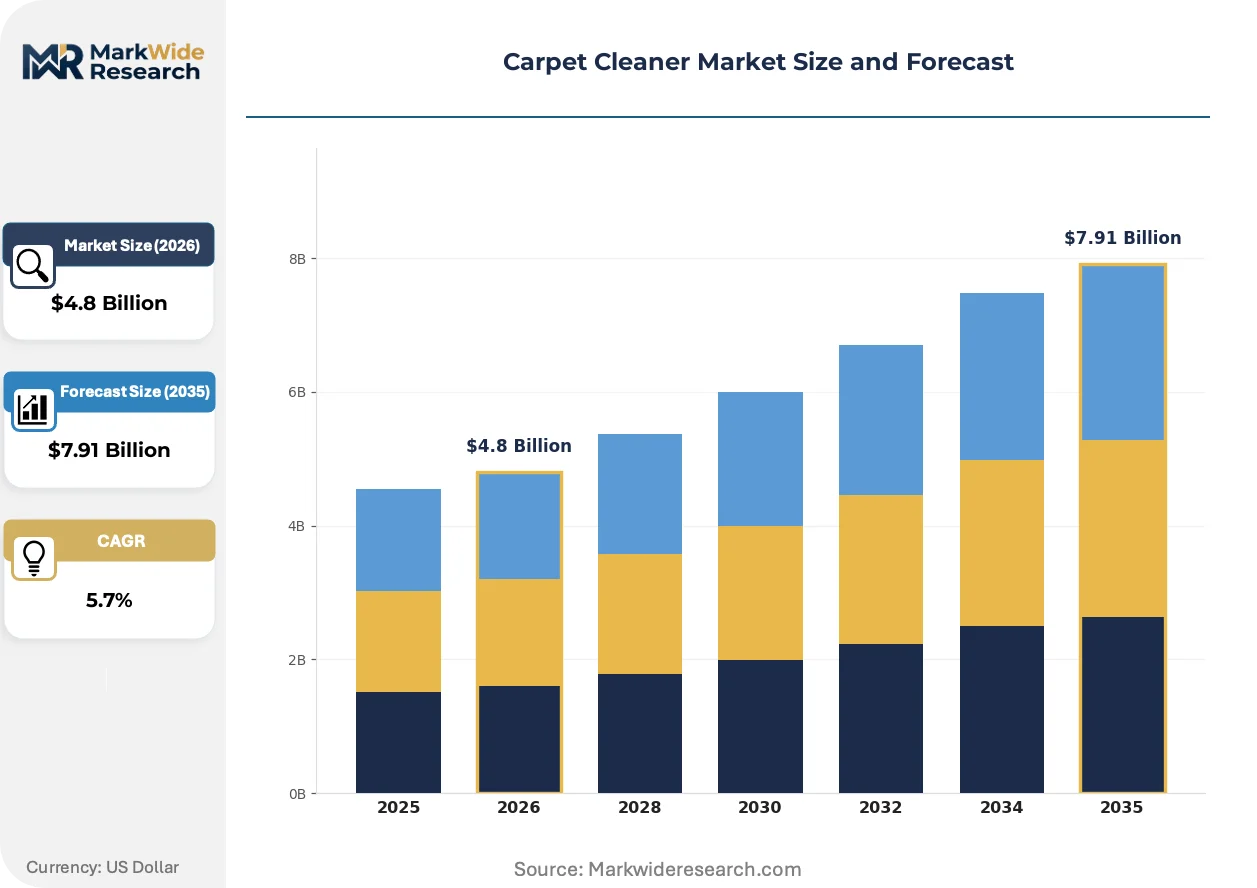
Leasing models for commercial-grade extraction equipment are restructuring competitive dynamics toward capital-light operators, while EPA Safer Choice chemistry mandates force surfactant reformulation across the supply base.
Growth Catalysts
- Commercial hospitality recovery:Occupancy normalization in United States hotels and conference venues is expanding professional cleaning service contracts for deep extraction maintenance.
- REACH framework compliance:European chemistry suppliers redesigning preservative-free formulations are opening premium positioning for compliant solution manufacturers.
- Hot water extraction performance:Heated solution systems operating at 150°F to 220°F demonstrate superior soil suspension versus cold-water alternatives in high-traffic commercial environments.
Market Restraints
- Petrochemical input volatility:Surfactant and polymer resin costs fluctuate with crude oil derivatives, compressing margin stability for formulation specialists.
- German equipment concentration:High-pressure system manufacturing clusters heavily in southwestern Germany, creating geographic supply risk for North American and Asian service networks.
- Steam cleaning substitution:Vapor-phase systems requiring zero chemical loading attract sustainability-focused commercial buyers in Nordic markets and California.
Strategic Opportunities
- Apartment dweller portability demand:Spot cleaner formats with immediate stain response capability remain underpenetrated among urban renters in dense metropolitan housing markets.
- OSHA ergonomic mandates:Workplace exposure guidelines for cleaning staff noise thresholds and lift requirements create specification advantages for lightweight, low-decibel equipment designs.
- Retail kiosk channel expansion:Rental-service distribution through big-box and grocery chains enables household penetration without ownership friction in suburban and exurban geographies.
Industry Challenges
- Multi-jurisdiction chemistry registration:EPA Safer Choice, EU REACH, and state-level VOC restrictions require parallel compliance pathways that extend product launch timelines.
- Legacy fleet integration complexity:Commercial service providers with sunk capital in truck-mounted extraction systems face retrofit friction when adopting portable heated units.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Carpet Cleaner Market |
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $7.91 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Upright, Canister, Spot Cleaners, Steam Cleaners Technology: Hot Water Extraction, Dry Cleaning, Encapsulation, Bonnet Cleaning End User: Residential, Commercial, Automotive, Hospitality Capacity: 1-5 Gallons, 6-10 Gallons, 11-15 Gallons, Above 15 Gallons |
| Companies Covered | Rug Doctor LLC, The Clorox Company, BISSELL Inc., Techtronic Industries Co. Ltd., Church & Dwight Co., Inc., Alfred Kärcher SE & Co. KG, Shark, Stanley Steemer International, Inc., Hoover, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Carpet Cleaner Market Strategic Shifts & Innovations
Equipment miniaturization converging with IoT-enabled maintenance monitoring is redrawing the boundary between professional and consumer-grade carpet cleaning capabilities.
Electrochemical water activation technology is collapsing the distinction between chemical-dependent and chemical-free cleaning efficacy. Hospitality housekeeping departments in Las Vegas and Orlando resorts are piloting onboard electrolysis systems that generate alkaline cleaning solution from tap water. This approach is collapsing recurring chemistry procurement costs and simplifying EPA compliance documentation for large facility operators.
EU F-Gas Regulation phase-down schedules for hydrofluorocarbon propellants are accelerating transition to mechanical pump spray systems in aerosolized spot treatment formulations. Chemistry suppliers serving European markets must reformulate delivery mechanisms by specified reduction milestones. Germany and France represent the most advanced implementation, with retailers already delisting non-compliant pre-spray products.
Automotive detailers and fleet maintenance operations are unbundling after-sales service contracts from equipment purchases, preferring per-use rental arrangements with bundled chemistry replenishment. This pattern compresses switching costs and rewards regional service networks with rapid response capability. The shift is most visible in Texas, Florida, and Southern California where mobile detailing operations concentrate.
Carpet Cleaner Market Segmentation
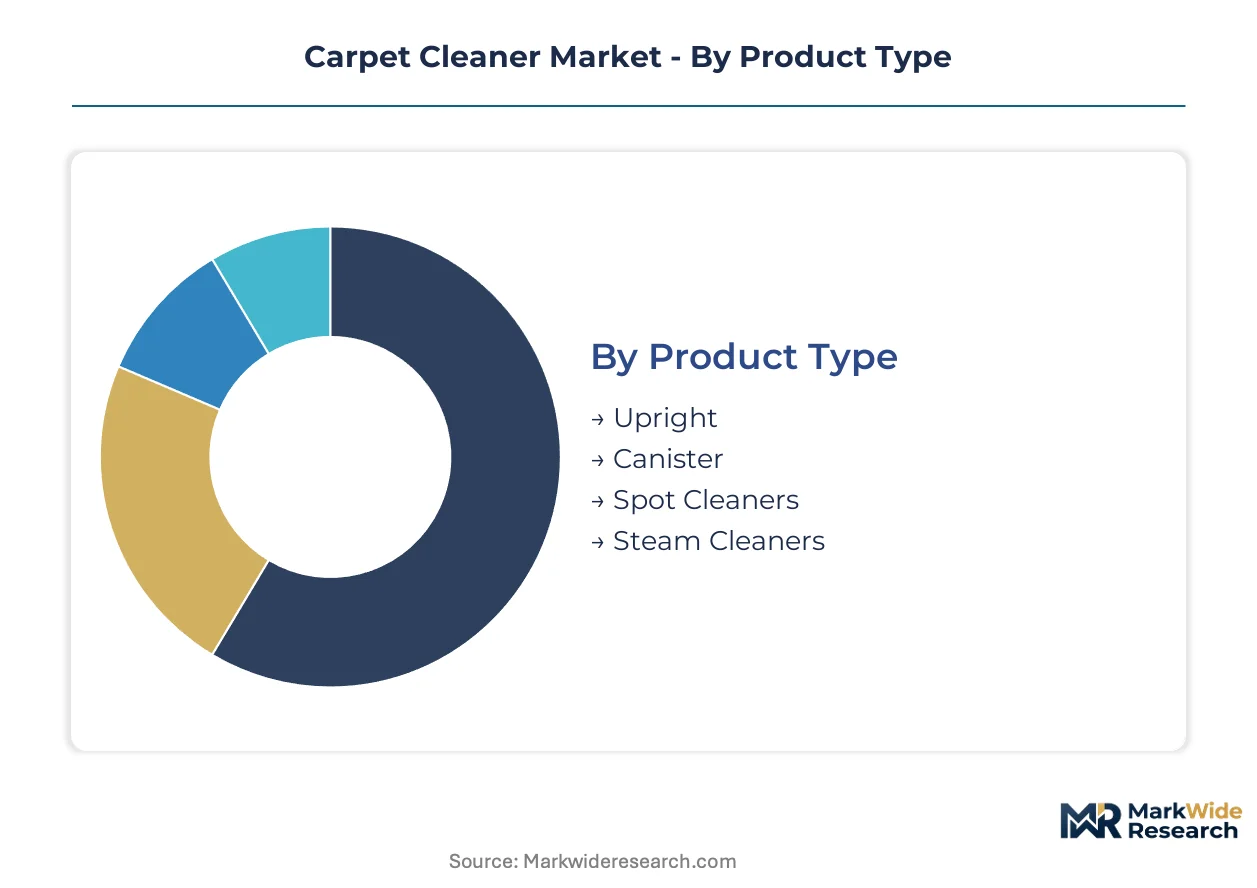
Segmentation in carpet cleaning equipment reveals divergent service intensity requirements across product architectures. After-sales revenue streams vary dramatically between residential units requiring minimal support and commercial systems demanding scheduled maintenance contracts.
Product Type:
After-sales-service intensity climbs sharply as product complexity increases, with upright and canister formats demanding distinct spare parts logistics and technician training investments.
- Upright:Self-contained agitation brush systems with integrated solution tanks dominate household volume due to storage efficiency in constrained floor plans. Demand concentrates in United States suburban markets where homeowners prioritize whole-room coverage capability combined with maneuverability around furniture.
- Canister:Separated motor and wand configurations deliver superior suction performance for deep pile carpets through reduced weight at the cleaning head. German commercial service providers specify canister formats for extended duty cycles in hospitality maintenance contracts.
- Spot Cleaners:Compact portable units target immediate stain response with handheld precision nozzles and heated solution capability.
- Steam Cleaners:Vapor-phase systems operating without chemical loading attract sustainability-focused buyers in California and Nordic markets.
Upright holds the largest share; momentum sits with Spot Cleaners.
Technology:
Cost tier stratification separates premium heated extraction systems from economy dry-cleaning alternatives, with chemistry requirements driving diverging operating expenditure profiles.
- Hot Water Extraction:Heated solution injection between 150°F and 220°F combined with immediate vacuum recovery delivers maximum soil suspension for high-traffic commercial environments. Las Vegas and Orlando hospitality operators specify this technology for casino carpet and conference center maintenance where rapid drying prevents revenue disruption.
- Dry Cleaning:Absorbent compound systems using minimal moisture enable same-day return to service for water-sensitive natural fiber installations. United Kingdom commercial cleaning contractors favor dry methods for heritage building wool carpets subject to shrinkage risk.
- Encapsulation:Polymer crystal formation around soil particles enables low-moisture interim maintenance with crystalline residue vacuum removal.
- Bonnet Cleaning:Rotary pad absorption systems provide surface-level appearance maintenance for commercial facilities with tight turnaround windows.
Hot Water Extraction commands premium pricing; Encapsulation is expanding most quickly in interim maintenance contracts.
End User:
Application context determines equipment durability specifications and chemistry procurement patterns across divergent use intensities.
- Residential:Intermittent use patterns with seasonal deep cleaning cycles drive demand for lightweight storage-friendly designs. United States big-box retail channels concentrate volume through seasonal promotional windows aligned with spring cleaning behavior.
- Commercial:Continuous operation requirements in facility management contracts specify extended-duty components and rapid service response guarantees. German contract cleaning networks anchor demand for truck-mounted extraction systems with onboard heating.
- Automotive:Mobile detailing operations in Texas and Florida favor portable extraction with 12V power compatibility.
- Hospitality:Asset preservation mandates in hotel housekeeping departments prioritize rapid drying to minimize room out-of-service time.
Commercial generates the highest service contract attachment; Hospitality shows the steepest expansion trajectory.
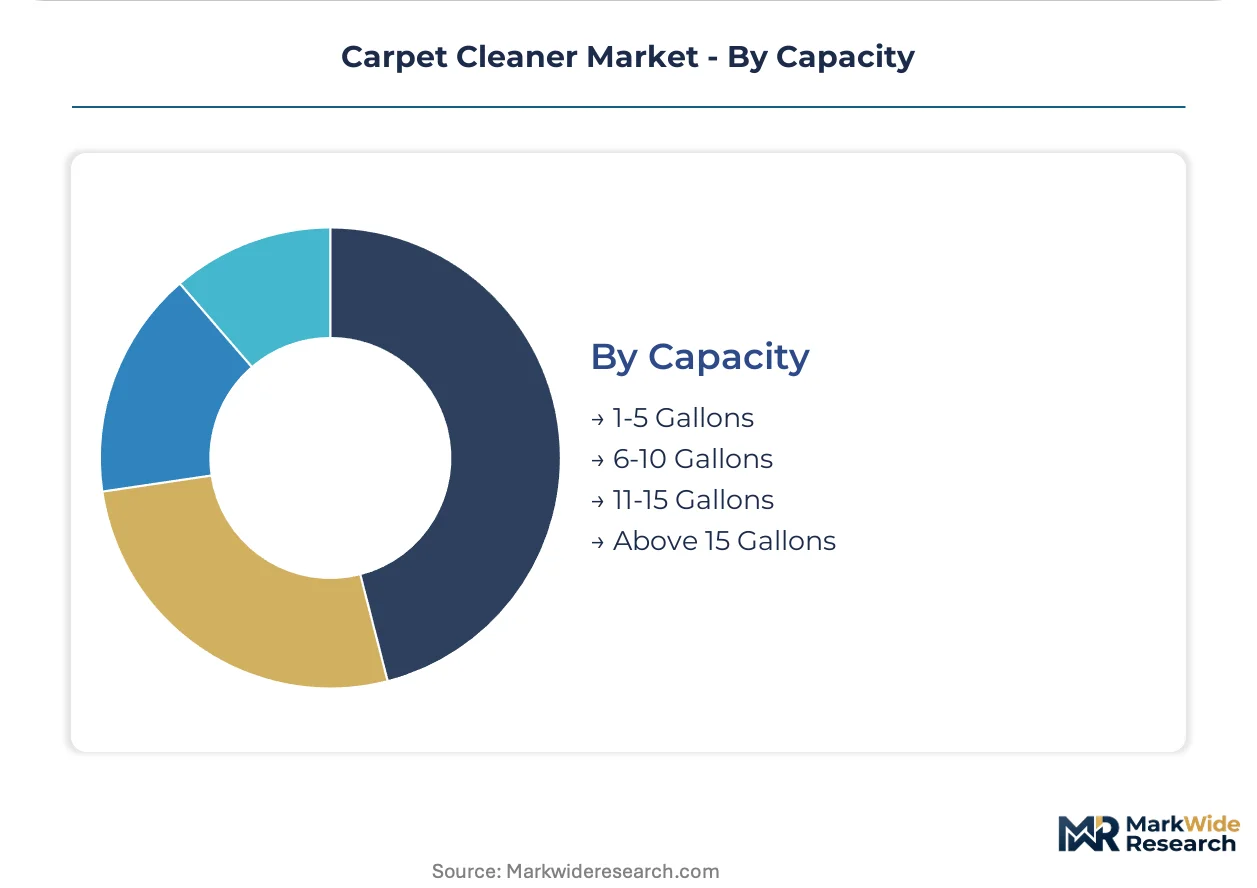
Capacity:
Volume scale directly correlates with mobility constraints and refrequency intervals, segmenting procurement between portable convenience and uninterrupted runtime.
- 1-5 Gallons:Compact tank dimensions enable single-operator transport across multi-level facilities without elevator dependency. Apartment dwellers in dense United States metropolitan markets specify this range for stair-accessible storage.
- 6-10 Gallons:Intermediate capacity balances runtime extension with manageable footprint for mid-size commercial contracts.
- 11-15 Gallons:Extended solution supply reduces refill interruptions for large footprint cleaning operations.
- Above 15 Gallons:Truck-mounted configurations with continuous heating dominate carpet cleaning fleet operations in North American service networks.
6-10 Gallons holds the largest share; Above 15 Gallons is gaining share fastest in fleet consolidation trends.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Export-import dynamics in carpet cleaning equipment tilt toward net importing in North American and Asian markets, while German manufacturing clusters supply high-pressure extraction systems worldwide. Trade flows concentrate around specialized component sourcing from southwestern Germany and chemistry formulation hubs in the United States and Western Europe.
United States
Hospitality sector recovery in Las Vegas and Orlando drives contract cleaning service expansion for deep extraction maintenance. OSHA workplace exposure guidelines for cleaning staff noise thresholds and ergonomic lift requirements shape commercial procurement specifications. EPA Safer Choice certification mandates in California and the Northeast push surfactant reformulation toward volatile organic compound reduction.
Germany
Commercial facility management contracts in Bavaria and Baden-Württemberg sustain demand for truck-mounted extraction systems with continuous heating capability. EU REACH framework restrictions on preservative chemistries force cleaning solution suppliers to redesign formulations for European export compliance. Alfred Kärcher SE & Co. KG anchors a dense service-provider network in the Stuttgart region for commercial carpet maintenance contracts.
China
Urban apartment density in Shanghai and Shenzhen generates spot cleaner demand among renters prioritizing storage-efficient immediate stain response. The country's national environmental regulator enforces volatile organic compound emission standards for household cleaning products in major metropolitan zones. Manufacturing clusters in Guangdong province produce compact extraction units for domestic consumption and Southeast Asian export.
United Kingdom
Heritage building maintenance contractors in London favor dry cleaning methods for water-sensitive wool carpets subject to shrinkage risk. EU F-Gas Regulation phase-down schedules accelerate transition to mechanical pump spray systems in aerosolized spot treatment formulations. Commercial cleaning networks concentrate in the Southeast and Midlands with service contracts extending into hospitality and corporate facility sectors.
Japan
Hotel housekeeping departments in Tokyo and Osaka prioritize rapid-drying extraction technology to minimize guest room out-of-service time. METI energy efficiency standards influence equipment specifications for heated solution systems in commercial applications. Kanto region service providers specify compact canister formats for multi-level facility maintenance with elevator constraints.
Carpet Cleaner Market Key Industry Players
Platform integrators command the system tier; component specialists sit upstream in surfactant chemistry and pump mechanism supply. Market structure fragments across residential appliance manufacturers, commercial service networks, and chemistry formulation houses with limited overlap in customer relationships. Three archetypes dominate: rental-service operators with retail kiosk distribution, vertically integrated appliance-chemistry combinations, and pure-play commercial service contractors with fleet-based deployment. Competitive moves concentrate on strategic partnerships between equipment makers and chemistry suppliers, plus geographic expansion of service networks into underpenetrated metropolitan markets.
Within the rental-service archetype, Rug Doctor LLC exemplifies capital-light household penetration through retail chain partnerships rather than direct ownership models. BISSELL Inc. occupies a position combining appliance manufacturing with in-house production of heated cleaning solution chemistry. Alfred Kärcher SE & Co. KG anchors the commercial service tier representation, with German corporate structure indicating engineering-intensive system design for extended duty cycle applications.
| Leading Market Players |
|---|
| Rug Doctor LLC |
| The Clorox Company |
| BISSELL Inc. |
| Techtronic Industries Co. Ltd. |
| Church & Dwight Co., Inc. |
| Alfred Kärcher SE & Co. KG |
| Shark |
| Stanley Steemer International, Inc. |
| Hoover |
| Others |
Cost & Logistics Intelligence
Stuttgart manufacturing clusters anchor high-pressure extraction system supply, with Alfred Kärcher SE & Co. KG and Kärcher production capacity dictating premium tier pricing power across North American and Asian import markets. This geographic concentration enables coordinated margin defense through controlled component release schedules, while tariff exposure on German-engineered pump assemblies compresses mid-market pricing flexibility for non-integrated assemblers.
Pricing Analysis
Commercial hospitality buyers anchor contract-based long-term offtake structures, with pricing stratifying across EPA Safer Choice certification tiers, heated solution capability, and service bundling intensity. Price differentiation rests on REACH compliance documentation and OSHA ergonomic specification achievement, with California and Northeast procurement teams demonstrating highest sensitivity to chemistry cost volatility while German facility managers prioritize extended duty cycle guarantees over unit economics.
Supply Chain Analysis
Tariff exposure between Germany and the United States dominates supply chain risk planning for high-pressure system importers, with southwestern Baden-Württemberg production clusters feeding North American service network expansion. Component sourcing draws from Chinese motor winding facilities, Italian pump mechanism specialists, and domestic surfactant formulation houses, creating multi-jurisdiction compliance complexity. Distribution runs through rental kiosk networks, direct commercial service contracts, and big-box retail seasonal procurement windows.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market builds defensive moats through regulatory entrenchment, where EPA Safer Choice and EU REACH compliance documentation creates switching costs that lock in chemistry-equipment bundling relationships across multi-year facility contracts.
For Market Incumbents: Entrench position through captive supply of heated cleaning solution chemistry and backward integration into surfactant formulation, neutralizing vapor-phase steam cleaning substitution threats in Nordic markets and California while extending service response guarantees that raise rival capital requirements for commercial contract penetration. For New Entrants and Emerging Players: Establish a beachhead in apartment dweller spot cleaner segments across dense United States metropolitan markets, where immediate stain response portability remains underpenetrated and retail kiosk channel partnerships with grocery chains enable household penetration without direct ownership friction in suburban geographies. For Investors and Strategic Acquirers: Carve-out targets emerge from diversified industrial conglomerates with neglected commercial cleaning equipment divisions, where long-term viability across a 5-10 year window hinges on electrochemical water activation technology adoption curves and the inflection signal to watch is onboard electrolysis system pilot conversion rates in Las Vegas and Orlando hospitality operators.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Surfactant Chemistry | BISSELL Inc. controls heated cleaning solution supply chains, capturing margin pools from formulation specialists. |
| Rental-Service Network Expansion | Rug Doctor LLC kiosk partnerships with North American retail chains reduce household ownership friction. |
| EPA Safer Choice Certification Investment | Compliant manufacturers secure California and Northeast procurement mandates while rivals face reformulation delays. |
| Electrochemical Water Activation Pilot Programs | Las Vegas and Orlando resorts test onboard electrolysis systems that eliminate recurring chemistry procurement costs. |
| Lightweight Ergonomic Equipment Redesign | OSHA workplace exposure guideline compliance creates specification advantages in commercial facility management contracts. |
Research Approach
Two parallel data streams informed the analysis: primary interviews with commercial cleaning service directors, hospitality housekeeping managers, chemistry formulation R&D leads, and retail channel category buyers; and secondary validation through EPA Safer Choice certified product registries, EU REACH restriction schedules, OSHA workplace exposure guidelines, and customs trade flow records. Bottom-up equipment shipment triangulation against top-down contract cleaning service revenue estimates anchored segmentation splits.
Forecast inputs span product type segmentation across upright, canister, spot cleaner, and steam cleaner architectures; technology tiers separating hot water extraction, dry cleaning, encapsulation, and bonnet systems; and end-use intensity differentials between residential intermittent use and commercial continuous operation patterns. CAGRs derive from equipment replacement cycle analysis, hospitality occupancy normalization trajectories, and chemistry procurement cost elasticity modeling across the projection horizon.
Sensitivities concentrate around petrochemical input volatility, REACH framework expansion schedules, and steam cleaning substitution rates in sustainability-focused procurement clusters. Forecasts reflect assumptions on regulatory compliance cost pass-through and fleet consolidation timing. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cleaning Equipment
Consumer Wet Wipes Market
Cleaning Equipment
Liquid Laundry Detergent Market
Cleaning Equipment
Global Laundry Care Products Market
Cleaning Equipment
Laundry Detergent Market
Cleaning Equipment
Commercial Cleaning Service Market
Cleaning Equipment
Cleaning Trolleys Market
Cleaning Equipment
Janitorial Service Market
Cleaning Equipment
Smart Cleaning and Hygiene Market
Cleaning Equipment
Commercial Laundry Detergent Market
Cleaning Equipment
Drain Sponges Market
Cleaning Equipment
Hand Wash Market
Cleaning Equipment
Natural Household Cleaners Market
Cleaning Equipment
Laundry Care Market
Cleaning Equipment
Laundry Scent Booster Market
Cleaning Equipment
Carpet Extraction Cleaner Market
Cleaning Equipment
Global Carpet and Upholstery Cleaning Services Market