
 Mirror Holder Market | 2026-2036
Mirror Holder Market Size, Share, and Industry Trends Forecast 2026-2036
Mirror Holder Market Insights
Asset-light leasing models for precision tooling is fragmenting competitive entry barriers in mirror holder supply chains. Gentex Corporation leverages its captive semiconductor fab capacity to sustain margins on electrochromic mirror assemblies. Magna International anchors North American automotive programs through backward integration into injection-molded bracket production. Ficosa competes in European premium platforms by specializing in camera-mirror system integration.
A mirror holder is a structural mounting assembly, typically fabricated from die-cast aluminum or reinforced polymer composites, designed to secure reflective surfaces while enabling angular adjustment through ball-joint or pivot mechanisms; its primary function is to maintain optical alignment under vibration, thermal cycling, and impact loads across automotive, residential, and commercial environments. Wall mount configurations lead in residential retrofit activity, while adjustable variants command premium positioning in salon and medical applications where ergonomic positioning drives replacement cycles. Metal substrates retain share in automotive exterior applications where crashworthiness standards dominate, though plastic formulations are displacing legacy materials in interior cabin modules where weight reduction takes priority.
FDA device-classification rules for surgical mirror systems and NHTSA Federal Motor Vehicle Safety Standard 111 compliance for rear-visibility equipment create dual compliance burdens for cross-sector suppliers. EPA guidelines on recycled aluminum content and REACH substance restrictions on chromate conversion coatings are forcing substrate and finishing technology transitions. Stakeholders must monitor how evolving automotive camera-monitor system mandates in multiple jurisdictions reshape holder design specifications and qualification timelines.
Market Dynamics
Smart mirror integration in automotive and residential sectors is compressing design cycles while forcing substrate transitions away from chromate conversion coatings under tightening chemical regulations.
Growth Catalysts
- Camera-Monitor System Mandates:NHTSA Federal Motor Vehicle Safety Standard 111 compliance requirements in the United States are accelerating electrochromic and digital mirror assembly adoption across passenger vehicle platforms.
- EV Production Concentration:Domestic electric vehicle manufacturing in China is pulling precision mirror holder imports for both interior cabin modules and exterior camera-integrated systems.
- REACH Substance Restrictions:ECHA regulations on hexavalent chromium and cadmium compounds are forcing finishing technology upgrades that favor advanced polymer composite substrates in European supply chains.
Market Restraints
- Aluminum Price Volatility:LME aluminum contract fluctuations directly compress margins on die-cast exterior mirror bracket production for automotive OEM programs.
- Supplier Concentration Risk:Precision injection molding capacity for glass-filled nylon holders clusters in East Asian tooling houses, creating single-source vulnerabilities for North American tier suppliers.
- Camera Substitution Threat:Exterior mirror elimination under UN Regulation 46 camera-monitor system exemptions threatens long-term holder demand in premium European vehicle segments.
Strategic Opportunities
- Medical Application White Space:FDA device-classification pathways for surgical mirror systems create premium positioning for adjustable holder assemblies in operating theater environments.
- Smart Home Construction Pull:Integrated vanity mirror systems in residential new-builds in China are opening specification channels for precision-adjustment mechanisms previously confined to commercial fit-outs.
- Recycled Content Incentives:EPA guidelines on post-consumer aluminum incorporation reward substrate transitions that align with automotive OEM circular economy commitments.
Industry Challenges
- Dual Certification Burden:Cross-sector suppliers must simultaneously maintain FDA quality system compliance for medical devices and IATF 16949 automotive standards, stretching audit and documentation resources.
- Legacy System Integration:Mechanical mirror holders must interface with digital camera and sensor arrays without compromising crashworthiness or aerodynamic performance, complicating validation protocols.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Mirror Holder Market |
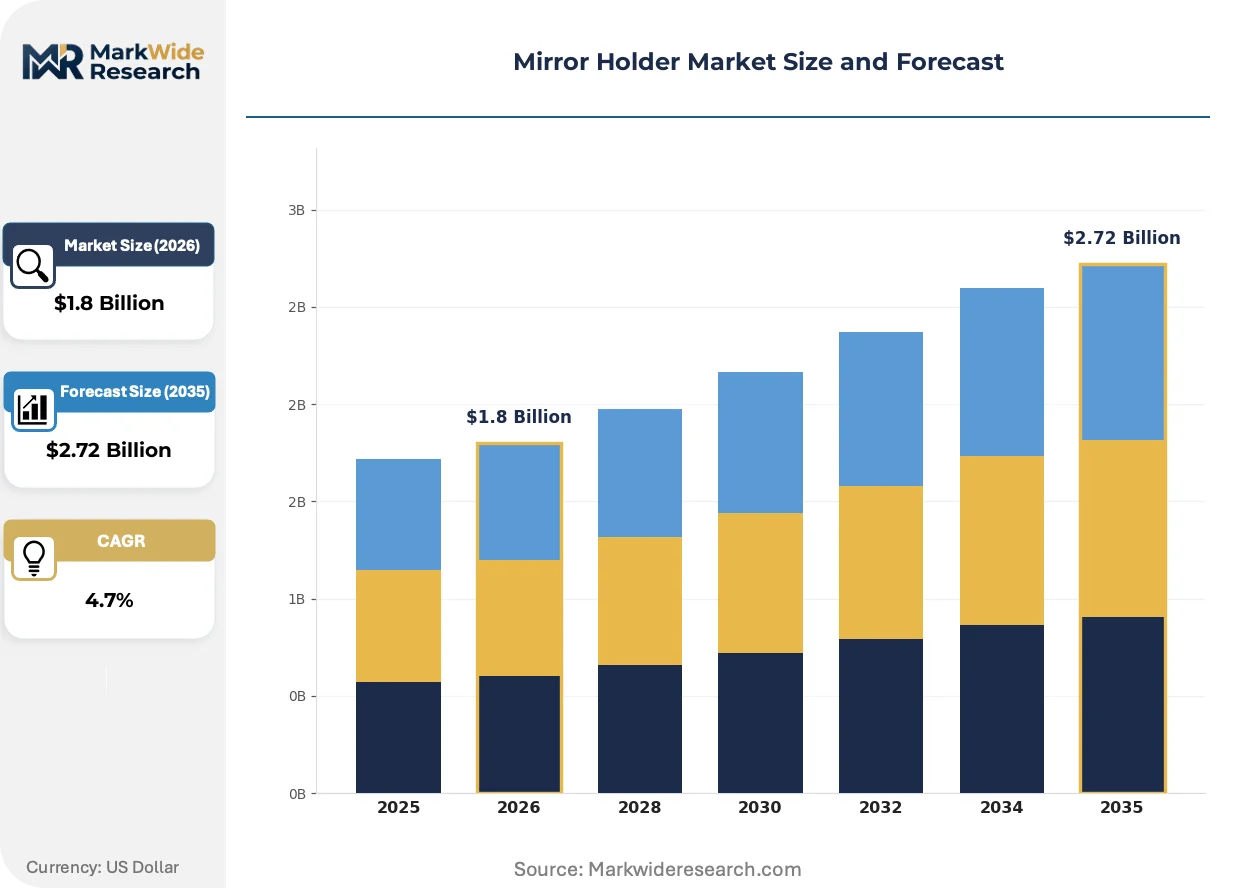
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.72 Billion |
| CAGR (2026 – 2036) | 4.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Wall Mount, Tabletop, Adjustable, Foldable Material: Metal, Plastic, Wood, Glass End User: Households, Salons, Gyms, Automotive Distribution Channel: Online Retail, Specialty Stores, Supermarkets, Wholesale |
| Companies Covered | Gentex Corporation, Magna International, Ficosa, Electric Mirror, Samsung Electronics, Japan Display, Kohler, Seura, Panasonic Holdings, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Mirror Holder Market Trends and Innovations
Material science advances and regulatory chemistry restrictions are converging to reshape substrate selection across automotive, medical, and residential mirror holder applications.
Glass-filled polymer composites are displacing die-cast aluminum in interior cabin mirror modules. Automotive OEMs in China and Germany are specifying these materials for weight reduction targets. The technology is migrating from non-structural trim applications into load-bearing adjustment mechanisms previously reserved for metal substrates.
REACH Annex XVII restrictions on chromium trioxide in conversion coatings are compelling finishing line retrofits across European supplier bases. Surface treatment houses must qualify trivalent chromium or plasma electrolytic oxidation alternatives. Exterior automotive holders face the steepest qualification timelines given salt-spray corrosion requirements.
Asset-light tooling leases are fragmenting competitive entry barriers in precision mirror holder supply chains. Contract manufacturers in China are offering mold-as-a-service arrangements that displace captive capital investment for mid-tier residential fixture brands. North American salon equipment distributors have adopted this procurement model most aggressively, compressing supplier qualification to design capability rather than balance sheet scale.
Mirror Holder Market Segmentation
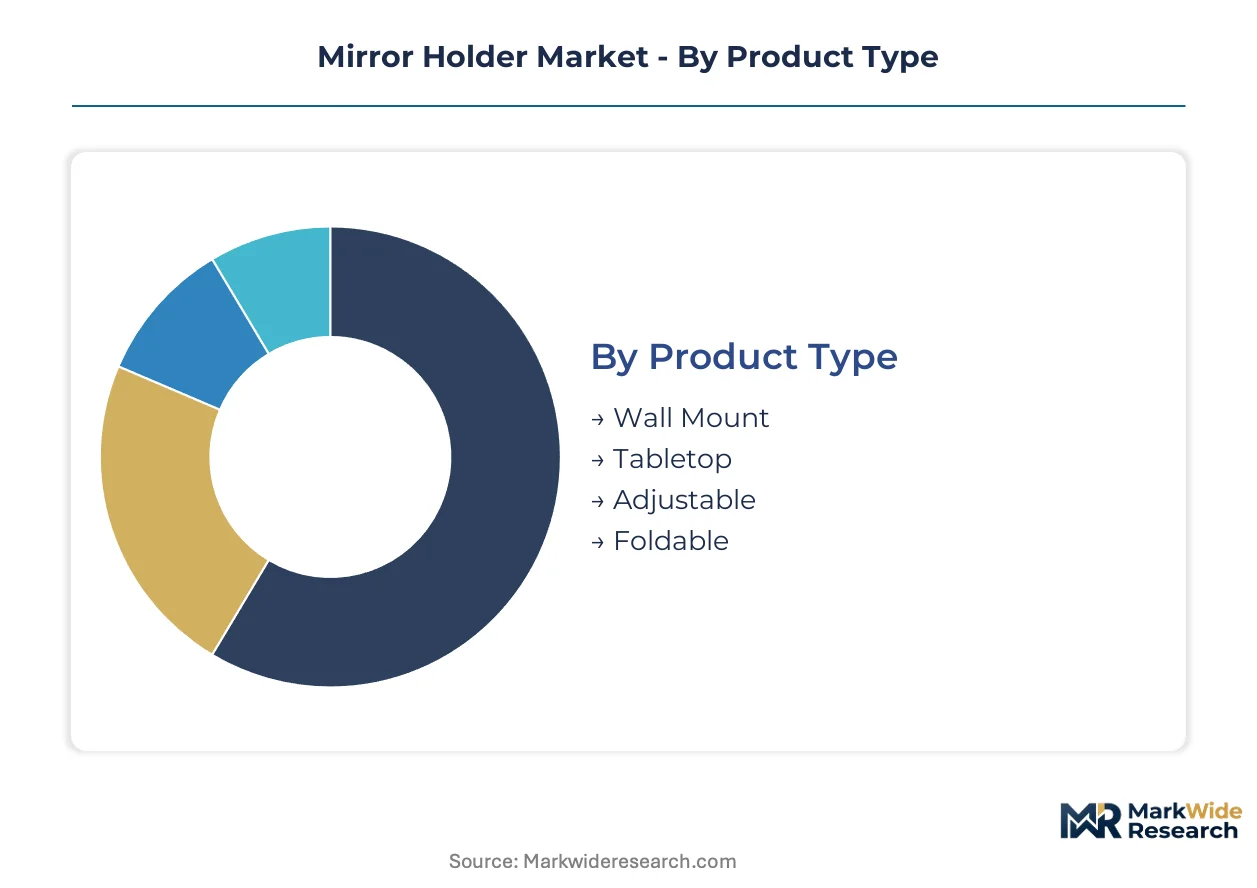
Mirror holder demand fragments across four distinct category axes, each commanding different procurement cadences and margin profiles. Product type and material selection drive the steepest specification divergences, while end-user concentration and channel configuration determine geographic pull patterns and inventory turnover velocity.
Product Type:
Replacement cycles vary dramatically across mounting configurations, with portable formats turning over fastest and fixed installations anchoring long-tail revenue streams.
- Wall Mount:Permanent bracket assemblies dominate residential retrofit activity and commercial fit-outs where structural anchoring to drywall or masonry is specified. Demand concentrates in Chinese smart home construction and North American bathroom renovation channels, with builders favoring integrated LED-compatible designs that reduce separate electrical rough-in costs.
- Adjustable:Articulated arm and ball-joint mechanisms command premium positioning in salon, medical, and industrial inspection environments where ergonomic positioning directly impacts operator productivity. German and Japanese precision manufacturers lead specification for operating theater and quality-control applications.
- Tabletop:Freestanding vanity and cosmetic mirrors serve high-frequency replacement segments in personal care and hospitality sectors.
- Foldable:Collapsible designs address travel and compact living segments with accelerated inventory turns through e-commerce impulse channels.
Wall mount configurations anchor the volume base while adjustable variants gain share at the steepest rate.
Material:
Substrate economics split sharply between weight-driven automotive specifications and aesthetic-driven residential selections, with regulatory chemistry restrictions forcing finishing technology transitions across metal categories.
- Metal:Die-cast aluminum and stainless steel substrates retain dominance in automotive exterior applications where NHTSA Federal Motor Vehicle Safety Standard 111 crashworthiness requirements apply. REACH Annex XVII restrictions on hexavalent chromium conversion coatings are accelerating trivalent chromium and plasma electrolytic oxidation qualification timelines across European supplier bases.
- Plastic:Glass-filled nylon and ABS polymer formulations are displacing legacy metal in interior cabin mirror modules where OEM weight reduction targets take priority. Chinese EV manufacturers specify these materials for dashboard and sun-visor integrated assemblies.
- Wood:Solid and engineered timber substrates serve premium residential and hospitality segments where warm materiality drives specification.
- Glass:Structural glass elements appear in high-end architectural installations and specialized optical equipment mounts.
Metal substrates retain the largest installed base while plastic formulations expand most quickly into load-bearing applications previously reserved for die-cast alloys.
End User:
Customer procurement sophistication spans from price-sensitive mass retail to engineering-intensive automotive qualification protocols, with certification burdens fragmenting supplier competitive sets.
- Automotive:OEM and tier supplier programs demand IATF 16949 quality system compliance, with electrochromic and camera-integrated mirror assemblies requiring simultaneous validation against NHTSA, ECE Regulation 46, and China GB standards. Gentex Corporation and Magna International anchor North American and European supply through backward integration into bracket production.
- Households:Residential demand concentrates in Chinese new-build construction and North American renovation activity, with smart mirror integration pulling precision adjustment mechanisms into mid-market price bands.
- Salons:Professional beauty equipment distributors favor asset-light tooling leases that compress supplier qualification to design capability rather than balance sheet scale.
- Gyms:Fitness facility operators specify vandal-resistant mounting systems with high replacement frequency due to heavy-use wear patterns.
Household demand anchors volume throughput while automotive programs capture the highest per-unit value and longest contract durations.
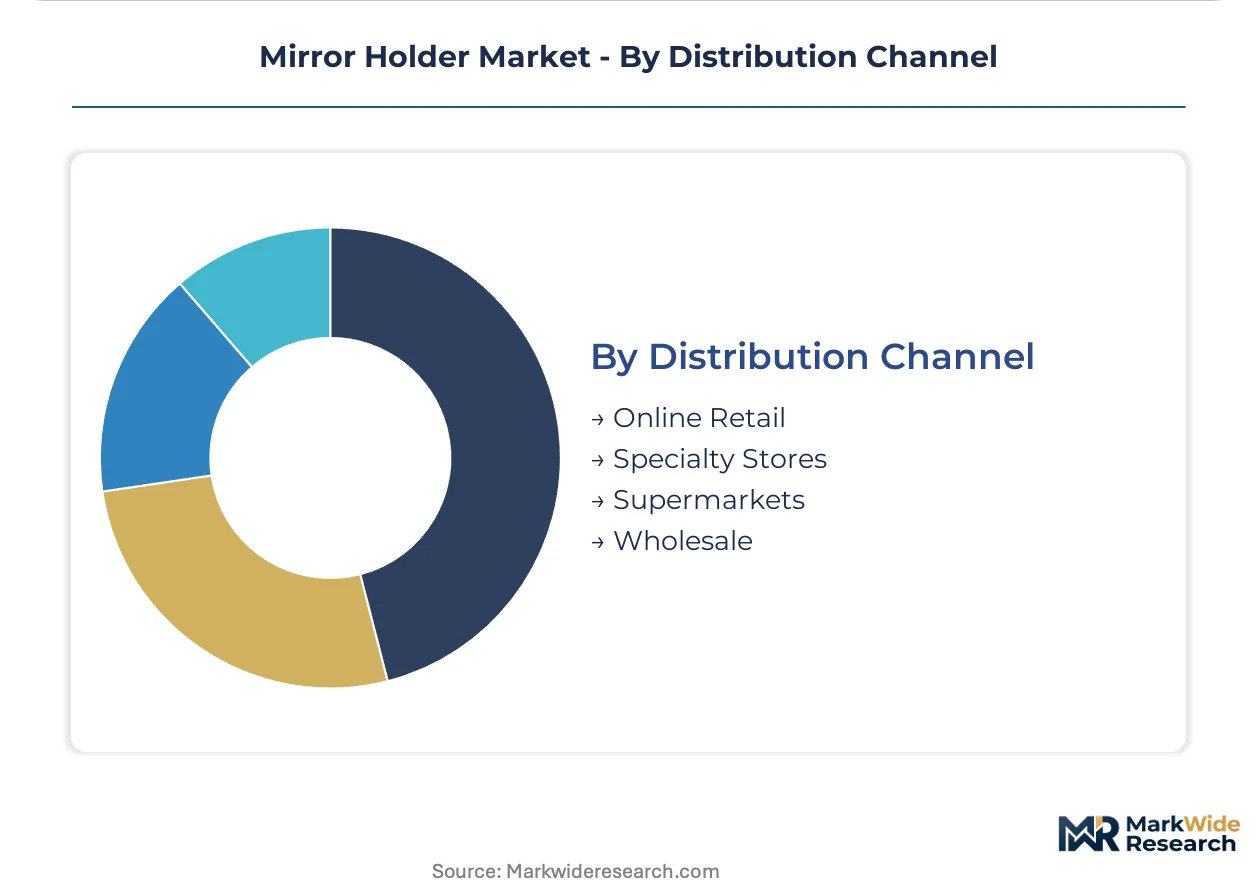
Distribution Channel:
Channel configuration determines geographic reach versus specification support trade-offs, with digital platforms eroding traditional wholesale hierarchies in standardized product categories.
- Online Retail:Direct-to-consumer platforms and marketplace aggregators dominate foldable and tabletop segments where visual merchandising and review velocity drive conversion. Chinese e-commerce ecosystems pull significant cross-border volume for precision adjustment mechanisms.
- Specialty Stores:Bath and lighting showrooms command wall mount and adjustable specification in renovation markets, with trained sales staff influencing material and finish selection.
- Supermarkets:Mass retail channels move high-volume, low-consideration tabletop formats with compressed margin structures.
- Wholesale:Distributor networks retain importance in automotive tier supply and commercial construction where volume commitments and technical support requirements favor relationship-based procurement.
Wholesale channels anchor commercial and automotive volume while online retail climbs fastest in consumer-facing portable segments.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Export flows of precision mirror holders tilt heavily toward manufacturing centers with integrated automotive and electronics ecosystems, while import demand concentrates in markets scaling domestic EV production and smart home construction. The following country-level analysis traces these trade dynamics across the primary demand and supply nodes.
China
Domestic EV manufacturing in the Yangtze River Delta and Pearl River Delta is pulling precision mirror assembly imports for both interior cabin modules and exterior camera-integrated systems. MIIT GB standards for rear-visibility equipment are tightening qualification timelines for foreign suppliers. Shenzhen and Shanghai industrial clusters host expanding injection-molding capacity for glass-filled nylon holders serving BYD and NIO supply chains.
Germany
Premium automotive platforms in Bavaria and Baden-Württemberg anchor European demand for electrochromic mirror assemblies with integrated camera-monitor systems. ECHA REACH Annex XVII restrictions on hexavalent chromium conversion coatings are forcing finishing technology upgrades across supplier bases. Stuttgart and Ingolstadt manufacturing corridors concentrate backward-integrated bracket production for BMW and Audi programs.
United States
NHTSA Federal Motor Vehicle Safety Standard 111 compliance requirements are accelerating digital mirror adoption across passenger vehicle platforms in Michigan and Ohio automotive corridors. EPA guidelines on recycled aluminum content are rewarding substrate transitions aligned with OEM circular economy commitments. Detroit-area tier suppliers are expanding die-cast capacity for exterior mirror brackets despite LME price volatility.
Japan
Precision adjustable mirror holders for medical and industrial inspection applications command premium positioning from METI-supported manufacturing clusters in Nagoya and Osaka. PMDA device-classification pathways for surgical mirror systems are creating regulatory moats for domestic suppliers. Aichi Prefecture tooling houses specialize in ball-joint mechanisms for operating theater environments.
South Korea
Seoul Capital Area electronics integrators are pulling mirror holder components for smart display and vanity mirror systems targeting residential and hospitality export markets. MFDS medical device regulations are streamlining certification for adjustable assemblies in cosmetic surgery applications. Gyeonggi-do manufacturing zones concentrate mold fabrication capacity serving Samsung Electronics and LG Display supply chains.
Mirror Holder Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream in bracket and adjustment mechanism fabrication. The vendor base organizes around three structural tiers: captive automotive tier suppliers with backward integration into injection-molded production, independent precision tooling houses offering asset-light mold-as-a-service arrangements, and residential fixture brands competing on design velocity. Dominant competitive moves include strategic partnerships between electronics integrators and automotive OEMs for camera-monitor system qualification, plus geographic expansion of East Asian molding capacity into European finishing networks.
Among North American automotive suppliers, Gentex Corporation and Magna International exemplify the captive tier-supplier archetype with in-house bracket production capabilities. Ficosa occupies a position within the European premium-platform specialization tier. These three entities anchor the competitive set without exhausting the vendor landscape, as mid-tier residential and medical specialists fragment the remainder across regional tooling clusters.
| Leading Market Players |
|---|
| Gentex Corporation |
| Magna International |
| Ficosa |
| Electric Mirror |
| Samsung Electronics |
| Japan Display |
| Kohler |
| Seura |
| Panasonic Holdings |
| Others |
Pricing and Supply Chain Analysis
LME aluminum contract volatility compresses margins on die-cast exterior mirror bracket production while simultaneously widening the spread between metal-intensive automotive tiers and polymer-based residential alternatives. This commodity-driven cost pressure cascades through supplier qualification timelines and forces tier suppliers to absorb price swings or pass through to OEM programs.
Pricing Analysis
Industrial OEM buyers anchor contract-based long-term offtake structures that span multi-year automotive platform lifecycles. Pricing stratifies across premium, standard, and economy tiers based on IATF 16949 certification grade and volume scale commitments. Cost compression in standard-grade residential fixtures intensifies as Chinese mold-as-a-service arrangements displace captive capital investment. Mass retail tabletop segments exhibit highest price sensitivity while medical device-classified adjustable assemblies command least.
Supply Chain Analysis
Extended payment terms from automotive OEMs strain working capital for precision injection molding houses in East Asian tooling clusters. Die-cast aluminum feeds from Chinese Yangtze River Delta smelters and German Ingolstadt finishing networks. Glass-filled nylon compounding rests on South Korean Gyeonggi-do and Japanese Aichi Prefecture petrochemical supply. Single-source vulnerability concentrates in East Asian mold fabrication capacity for camera-integrated mirror assemblies. Distribution runs through wholesale tier networks in automotive and commercial construction channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Qualified surface treatment capacity for REACH-compliant trivalent chromium and plasma electrolytic oxidation alternatives sits in critically short supply across European supplier bases, fragmenting competitive positioning for exterior automotive programs.
For Market Incumbents: Pre-empt camera-monitor system substitution threats by deepening backward integration into injection-molded bracket production for interior cabin modules. Secure captive semiconductor fab capacity for electrochromic mirror assemblies before smart mirror integration accelerates design cycle compression. Lock long-term aluminum offtake agreements to buffer LME price volatility exposure on exterior programs. For New Entrants and Emerging Players: Pursue medical application white space in surgical mirror systems where FDA device-classification creates regulatory moats against automotive-focused incumbents. Target Chinese smart home construction channels for precision-adjustment mechanisms previously confined to commercial fit-outs. Lead with asset-light tooling lease models that compress supplier qualification to design capability rather than balance sheet scale. For Investors and Strategic Acquirers: The market sits at a substrate transition phase that favors precision polymer composite specialists with proven automotive qualification track records. Five-to-ten year viability hinges on camera-monitor system mandate adoption curves across NHTSA, ECE Regulation 46, and China GB jurisdictions. Monitor ECHA REACH Annex XVII enforcement intensity as inflection indicator for finishing technology upgrade capex cycles.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Injection-Molded Bracket Production | Magna International and Gentex Corporation anchor North American automotive supply through captive polymer compounding capacity. |
| Camera-Monitor System Qualification Partnership | Ficosa competes in European premium platforms by specializing in integrated camera-mirror system validation against ECE Regulation 46. |
| REACH-Compliant Surface Treatment Line Retrofit | European supplier bases must qualify trivalent chromium alternatives as ECHA Annex XVII restrictions eliminate hexavalent chromium conversion coatings. |
| Asset-Light Mold-as-a-Service Expansion | Shenzhen and Shanghai contract manufacturers displace captive capital investment for mid-tier residential fixture brands through leasing arrangements. |
| Medical Device Classification Pathway Investment | Adjustable holder assemblies for operating theater environments command premium positioning under FDA and PMDA regulatory frameworks. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted across primary interview programs with automotive Tier 1 supplier procurement leads, OEM platform engineers, residential fixture brand product managers, and precision tooling house operations directors. Secondary validation drew from NHTSA Federal Motor Vehicle Safety Standard 111 compliance filings, ECHA REACH substance restriction updates, MIIT GB standard publications, and vehicle production databases. Bottom-up segment sizing triangulated against top-down market value reconciliation.
Calibration against historical substitution patterns between metal and polymer substrates shaped the analytical framework across the projection horizon. Segmentation dimensions modeled include product type, material substrate, end-user procurement sophistication, and distribution channel configuration. CAGRs were derived from regression analysis of automotive content-per-vehicle trends and residential construction pull factors. Camera-monitor system mandate adoption curves and smart mirror integration penetration rates served as primary demand-side inputs.
The forecast holds incumbent behavior within observed patterns; aggressive capacity expansion by Chinese state-supported molding conglomerates would shift outcomes beyond modeled ranges. Macroeconomic deviation in aluminum contract pricing, regulatory acceleration of mirror elimination exemptions under UN Regulation 46, or breakthroughs in solid-state camera integration would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Household Items
Non-Stick Cookware Market
Household Items
Germany Induction Hobs Market
Household Items
Asia Pacific Residential Vacuum Cleaners Market
Household Items
Wipes Market
Household Items
Air Purifier Market
Household Items
Saudi Arabia Cookware Market
Household Items
Scouring Pads Market
Household Items
Canada Digital Showers Market
Household Items
Electric Shoe Polisher Market
Household Items
India Air Purifier Market
Household Items
Aquarium Heaters and Chillers Market
Household Items
Mason Jars and Canning Supplies Market
Household Items
Dry and Wet Wipes Market
Household Items
Air Humidifier Market
Household Items
Sorting Hampers Market
Household Items
Ironing Boards Market