
 Aquarium Heaters and Chillers Market | 2026-2036
Aquarium Heaters and Chillers Market Size, Share, and Industry Trends Forecast 2026-2036
Aquarium Heaters and Chillers Market Outlook
EPA energy-efficiency standards for consumer appliances is shifting the cost-of-entry calculus for manufacturers targeting North American distribution. Eheim GmbH & Co. KG leverages its German engineering heritage to sustain premium positioning across European retail channels. Fluval anchors the mid-market segment through extensive pet-store distribution networks in Canada and the United States. Hydor competes on thermal precision in the professional aquarist niche.
Aquarium heaters and chillers constitute electromechanical thermal management devices employing resistive heating elements or vapor-compression refrigeration cycles to maintain aqueous environments within species-specific temperature bands, typically measured in 0.5-degree Celsius tolerances. Their primary commercial purpose spans ornamental fish husbandry, public aquarium operations, and controlled breeding programs where thermal stability directly impacts mortality rates. Submersible heaters dominate unit volume across retail hobbyist channels, while refrigerated chillers command superior margins in commercial aquaculture installations exceeding 1,000-liter capacities. Digital control systems are displacing mechanical thermostats in professional settings where remote monitoring and programmable setpoints reduce labor overhead.
FCC electromagnetic emissions compliance governs digital controller circuitry sold into United States markets, while EU RoHS restrictions on hazardous substances constrain solder and coating selections for products entering European distribution. The EPA and ECHA collectively elevate material compliance costs, favoring manufacturers with established in-house testing laboratories over import-dependent distributors. Stakeholders must weigh certification investment against channel access when prioritizing geographic expansion sequences.
Market Dynamics
Digital thermostat architecture is displacing mechanical bimetallic controls across professional aquaculture installations, compressing labor overhead while tightening thermal precision tolerances to 0.1-degree Celsius. This electromechanical transition is redrawing competitive positioning between legacy component suppliers and integrated system manufacturers.
Growth Catalysts
- EU F-Gas Regulation phase-down:Hydrofluorocarbon refrigerant quotas are accelerating adoption of propane-based cooling circuits in chiller systems sold into European commercial aquaculture.
- Vietnam Mekong Delta corridor expansion:Pangasius and shrimp farming operations exceeding 10,000-liter recirculating systems are standardizing on redundant heater-chiller pairs to buffer thermal shock mortality.
- Submersible titanium heating elements:Corrosion-resistant alloy construction extends service intervals in marine salinity conditions, reducing replacement frequency for public aquarium operators.
Market Restraints
- Copper and nickel price volatility:Heating element substrates and heat exchanger tubing face input cost swings that compress assembler margins on mid-tier product lines.
- Guangdong Province component concentration:Printed circuit board and sensor module sourcing clusters create single-point vulnerability for brands without secondary supplier qualification.
- Mechanical thermostat reliability ceiling:Bimetallic strip drift limits calibration stability beyond 18-month cycles, constraining warranty terms on economy-grade submersible units.
Strategic Opportunities
- Brazilian ornamental aquaculture underpenetration:Discus and angelfish breeding collectives in Amazonas state lack distributed chiller infrastructure for temperature-sensitive strain development.
- IoT-enabled predictive maintenance:Cloud-connected thermal loggers allow service contracts to displace spot replacement revenue in institutional aquarium contracts.
- India PLI scheme for white goods:Component-level manufacturing incentives could localize compressor assembly for domestic aquaculture equipment producers.
Industry Challenges
- FCC Part 15 certification timelines:Digital controller electromagnetic compliance testing creates 4-6 month lead times for new product introductions targeting United States distribution.
- Legacy 4-20mA integration:Building management system retrofit requirements complicate sales cycles for commercial installations with pre-existing SCADA infrastructure.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Aquarium Heaters and Chillers Market |
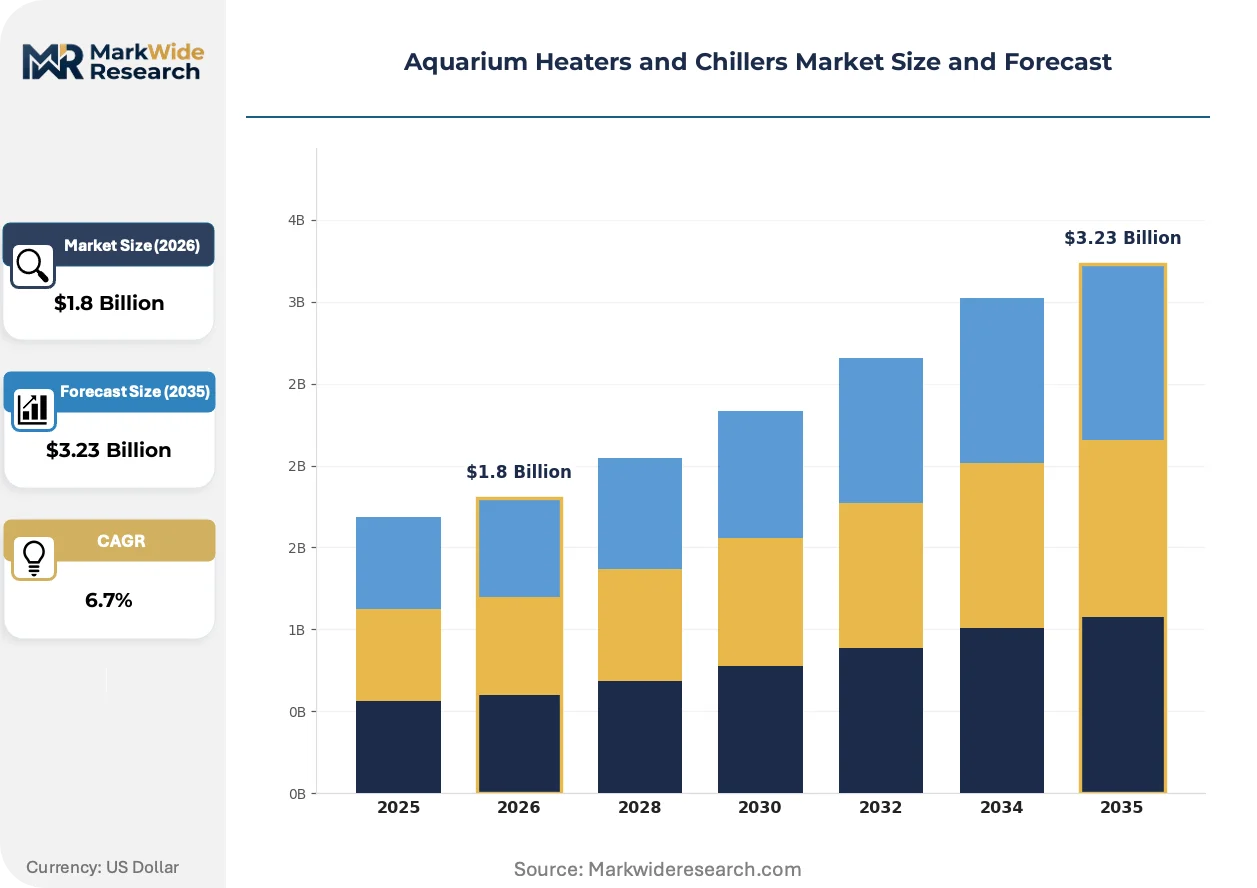
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Immersion Heaters, Submersible Heaters, In-Line Heaters, Refrigerated Chillers Technology: Thermostatic Control, Digital Control, Mechanical Control, Energy Efficient Systems End User: Retail Hobbyists, Professional Aquarists, Research Institutions, Commercial Aquaculture Capacity: 50W-100W, 101W-200W, 201W-300W, 301W and Above |
| Companies Covered | Eheim GmbH & Co. KG, Fluval, Hydor, Aqueon Products, TECO, JBJ, Cobalt Aquatics, Finnex, AquaEuro USA, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Aquarium Heaters and Chillers Market Strategic Shifts
Thermal management hardware is converging with telemetry platforms, compressing the boundary between electromechanical components and software-defined environmental control. This fusion is redrawing supplier capability requirements and procurement evaluation criteria.
Silicon-controlled rectifier phase-angle modulation is integrating with submersible heater architectures to eliminate mechanical relay contact wear. Professional aquaculture operators in Denmark and the Netherlands are adopting these solid-state units for 24/7 breeding facility deployment. The technology is integrating predictive failure algorithms that flag resistive element degradation before thermal runaway, reducing stock mortality exposure.
REACH Annex XVII restrictions on cadmium and lead in electrical contacts are forcing solder alloy reformulation for controller assemblies entering European distribution. Manufacturers with in-house materials laboratories are compressing reformulation cycles while import-dependent distributors face extended compliance verification delays. Submersible heater product lines with legacy tin-lead internal joints are most affected, accelerating end-of-life redesign investments.
Facility managers at public aquariums and research stations are consolidating vendor relationships around full-system environmental platform providers. Discrete heater and chiller procurement is yielding to integrated recirculating system contracts specifying thermal, filtration, and lighting coordination. This concentration is most visible in German and Japanese institutional markets, where long-term service agreements now outweigh upfront equipment pricing in selection criteria.
Aquarium Heaters and Chillers Market Segmentation
Thermal management procurement decisions diverge sharply across user profiles, with certification requirements and capacity thresholds filtering accessible product tiers. Equipment specifications must align with species-specific tolerances and facility scale, creating distinct procurement workflows for hobbyist retail channels versus institutional buyers.
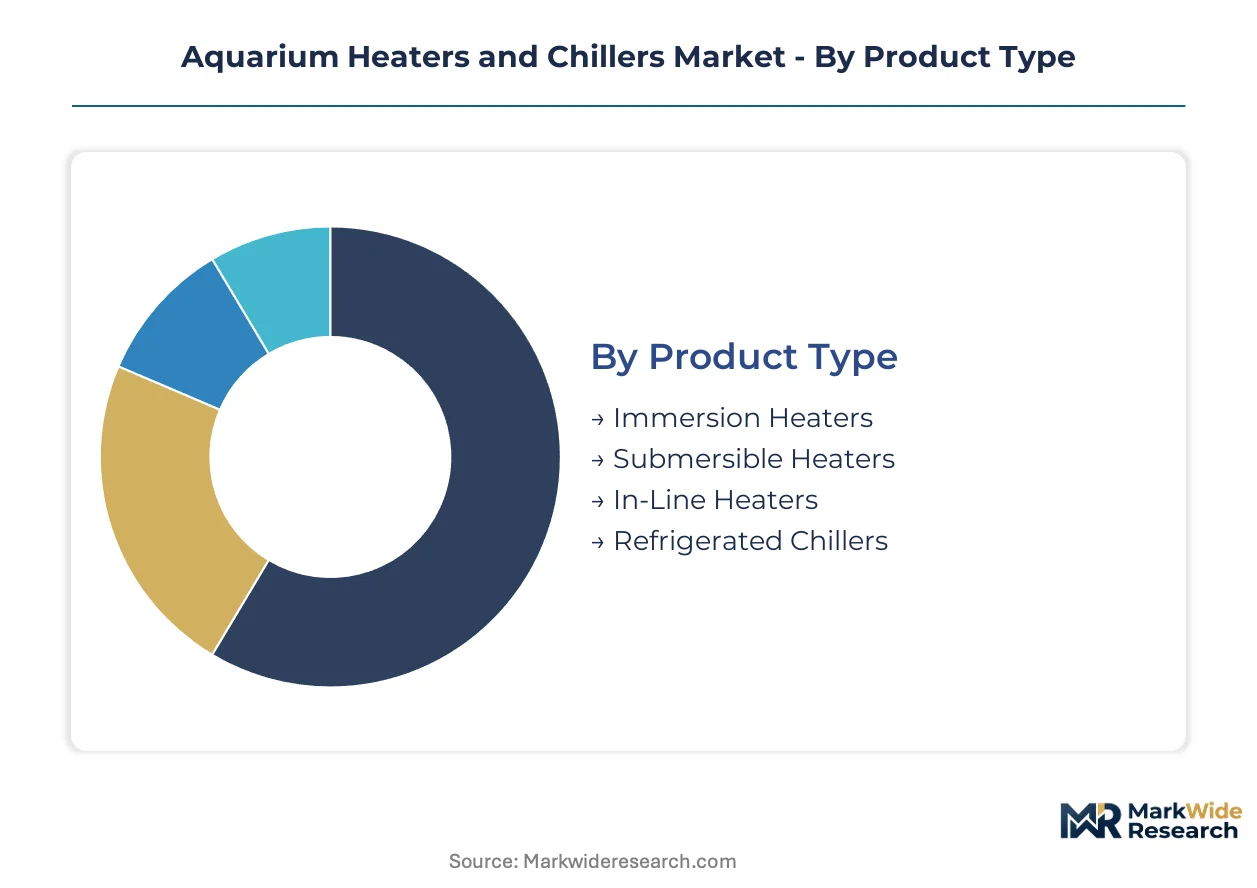
Product Type:
FCC Part 15 electromagnetic compliance governs digital controller circuitry in submersible and in-line heaters sold into United States distribution, while EU RoHS restrictions constrain solder selections across all four product categories entering European markets.
- Immersion Heaters:Partially submerged resistive elements with glass or quartz shrouding dominate economy-tier retail channels. Demand concentrates in North American pet-store networks where mechanical thermostat simplicity reduces price points for entry-level hobbyists.
- Submersible Heaters:Fully waterproof titanium or stainless-steel enclosures with silicon-controlled rectifier modulation achieve 0.1-degree Celsius precision. Vietnamese Mekong Delta pangasius farms exceeding 10,000-liter systems are standardizing on redundant submersible pairs to buffer thermal shock mortality in recirculating aquaculture.
- In-Line Heaters:External plumbing integration with canister filtration loops serves marine reef systems where in-tank equipment disrupts aesthetic presentation. German public aquarium contractors specify these units for display tank thermal management.
- Refrigerated Chillers:Vapor-compression cooling circuits using hydrofluorocarbon or propane refrigerants handle thermal loads above 500 watts. EU F-Gas Regulation phase-down quotas are accelerating propane-based adoption in European commercial aquaculture installations.
Leading the category by volume: Submersible Heaters. Expanding most quickly: Refrigerated Chillers.
Technology:
Cost stratification separates legacy mechanical architectures from solid-state digital platforms, with professional aquaculture operators absorbing premium pricing for telemetry integration and predictive failure algorithms.
- Thermostatic Control:Bimetallic strip or thermistor-actuated switching maintains temperature bands within 0.5-degree Celsius variance. Brazilian ornamental breeding collectives in Amazonas state deploy these units where digital infrastructure remains underdeveloped.
- Digital Control:Microprocessor-managed PID loops with LCD interfaces and programmable setpoints achieve 0.1-degree precision. Danish and Netherlands breeding facilities are adopting these units for 24/7 deployment with cloud-connected thermal logging.
- Mechanical Control:Analog dial thermostats with no electronic components avoid FCC certification timelines but suffer calibration drift beyond 18-month cycles. Warranty terms compress on economy-grade submersible units using this architecture.
- Energy Efficient Systems:Solid-state relay phase-angle modulation eliminates contact wear while reducing standby consumption. EPA energy-efficiency standards for consumer appliances are shifting cost-of-entry calculus for manufacturers targeting North American distribution.
Dominant by installed base: Thermostatic Control. Gaining share fastest: Digital Control.
End User:
Procurement authority and technical specification complexity scale with facility sophistication, from individual hobbyist discretion to institutional procurement committees with multi-year service contract frameworks.
- Retail Hobbyists:Individual consumers purchasing through pet-store or e-commerce channels prioritize price accessibility and plug-and-play installation. Volume concentrates in United States and Canadian distribution networks where Fluval anchors mid-market positioning.
- Professional Aquarists:High-end private collectors and breeding specialists demand titanium-element durability and redundant thermal management. Hydor competes on thermal precision within this niche through specialized distribution.
- Research Institutions:Universities and marine biology stations require calibration documentation and 4-20mA building management system integration. German and Japanese institutional markets now weight long-term service agreements above upfront equipment pricing.
- Commercial Aquaculture:Pangasius, shrimp, and salmon farming operations in Vietnam, Indonesia, and India drive procurement of 301W-plus chiller-heater systems with remote monitoring capabilities.
Highest unit volume: Retail Hobbyists. Steepest expansion trajectory: Commercial Aquaculture.
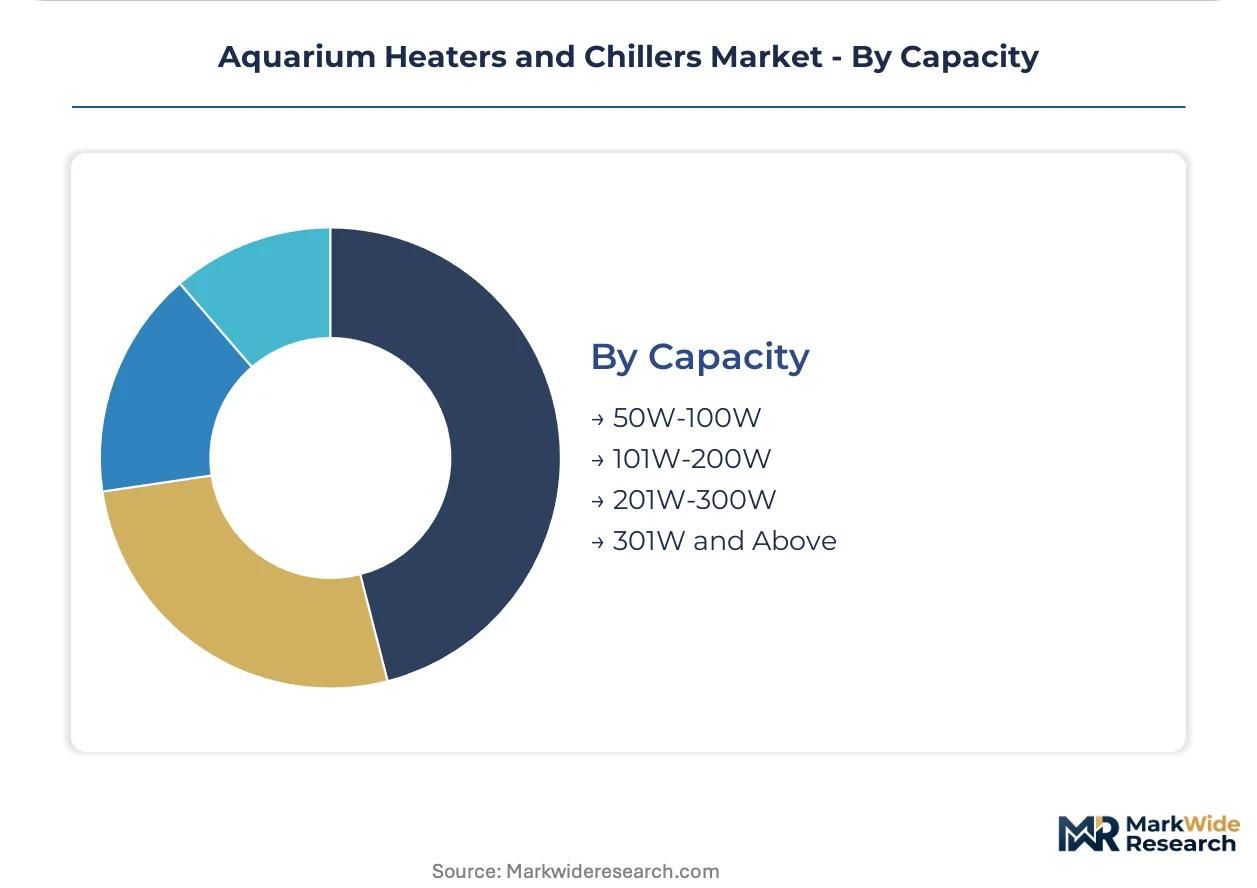
Capacity:
Wattage bands correlate directly with tank volume and species thermal sensitivity, with commercial installations requiring modular redundancy rather than single high-capacity units.
- 50W-100W:Nano aquarium and betta habitat heating for retail hobbyist applications under 40 liters. Eheim GmbH & Co. KG leverages German engineering heritage to sustain premium positioning in this compact segment across European retail channels.
- 101W-200W:Standard community tank and small reef systems between 40-150 liters. REACH Annex XVII cadmium and lead restrictions are forcing solder alloy reformulation for controller assemblies in this high-volume tier.
- 201W-300W:Large display aquariums and small breeding systems requiring precise thermal stability. Copper and nickel price volatility in heating element substrates compress assembler margins on mid-tier product lines in this band.
- 301W and Above:Commercial recirculating systems, public aquariums, and aquaculture facilities requiring multiple units or dedicated chiller integration. India's PLI scheme for white goods component manufacturing could localize compressor assembly for domestic producers at this capacity tier.
Leading by shipment volume: 101W-200W. Climbing the fastest: 301W and Above.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Vietnam's Mekong Delta special economic zones for aquaculture infrastructure are concentrating equipment procurement among pangasius and shrimp farming operations exceeding 10,000-liter recirculating systems.
United States
EPA energy-efficiency standards for consumer appliances are elevating compliance costs for manufacturers targeting North American distribution. FCC Part 15 certification timelines for digital controller electromagnetic compliance create 4-6 month lead times for new product introductions. Demand concentrates in California and Florida ornamental fish breeding corridors where professional aquarists require redundant thermal management systems.
Germany
ECHA REACH Annex XVII restrictions on cadmium and lead in electrical contacts are forcing solder alloy reformulation for controller assemblies entering European distribution. EU F-Gas Regulation phase-down quotas accelerate propane-based cooling circuit adoption in chiller systems. Public aquarium contractors in Berlin and Munich specify in-line heaters for display tank thermal management with long-term service agreement frameworks.
Vietnam
Pangasius and shrimp farming operations in the Mekong Delta corridor are standardizing on redundant heater-chiller pairs to buffer thermal shock mortality. The country's aquaculture infrastructure incentives support recirculating system expansion beyond 10,000-liter capacities. Equipment procurement clusters in Can Tho and An Giang provinces where commercial operators demand remote monitoring capabilities.
India
PLI scheme incentives for white goods component manufacturing could localize compressor assembly for domestic aquaculture equipment producers. Commercial farming operations in Andhra Pradesh and Tamil Nadu drive procurement of 301W-plus chiller-heater systems. The Central Electricity Authority efficiency mandates are tightening product compliance thresholds for imported thermal management devices.
Brazil
Discus and angelfish breeding collectives in Amazonas state lack distributed chiller infrastructure for temperature-sensitive strain development. ANVISA equipment registration requirements extend verification timelines for imported digital controllers. Demand potential concentrates in São Paulo and Rio de Janeiro metropolitan corridors where ornamental aquaculture clubs are expanding controlled breeding programs.
Aquarium Heaters and Chillers Market Competitive Environment
Diversified conglomerates compete with focused pure-play specialists across tiered market positions. The vendor base separates into three strategic archetypes: German-engineering heritage brands commanding premium retail positioning, mid-market players leveraging extensive pet-store distribution networks, and thermal precision specialists serving professional aquarist niches. Dominant competitive moves include geographic expansion into underpenetrated aquaculture corridors and technology licensing for solid-state control architectures.
Within the premium-engineering tier, Eheim GmbH & Co. KG exemplifies heritage-focused positioning across European retail channels. Fluval occupies a position anchoring mid-market accessibility through North American pet-store networks. Hydor sits within the precision-specialist archetype competing on thermal accuracy for professional aquarists requiring species-specific temperature tolerances.
| Leading Market Players |
|---|
| Eheim GmbH & Co. KG |
| Fluval |
| Hydor |
| Aqueon Products |
| TECO |
| JBJ |
| Cobalt Aquatics |
| Finnex |
| AquaEuro USA |
| Others |
Value Chain & Pricing Dynamics
Copper and nickel price volatility on the London Metal Exchange cascades through heating element substrate costs into assembler margin compression across mid-tier product lines, forcing brands to recalibrate tier boundaries between economy mechanical thermostats and premium digital control architectures.
Pricing Analysis
Short lead-time premiums of 15-20 percent apply to digital controller orders bypassing standard FCC Part 15 certification queues, while spot inventory discounts move legacy mechanical thermostat stock. Three-tier pricing structure across premium, standard, and economy levels separates titanium-element submersible units with predictive algorithms from glass-shrouded immersion heaters with bimetallic strips. Pricing pressure stems from Guangdong Province component concentration exposing assemblers to PCB and sensor module supply interruptions. Retail hobbyists exhibit highest price sensitivity, while German public aquarium contractors absorb premiums for long-term service agreement bundling.
Supply Chain Analysis
Workforce availability constraints in Guangdong Province, Zhejiang Province, and Vietnam's Bac Ninh industrial zones are compressing production flexibility for controller assembly and titanium element fabrication. Raw material dependencies center on copper-nickel heating alloys, refrigerant-grade propane, and RoHS-compliant solder formulations. Single-source vulnerability concentrates in printed circuit board substrate sourcing clusters. Distribution runs through North American pet-store networks, European specialty aquatics retailers, and Vietnamese aquaculture equipment dealers serving Mekong Delta farming corridors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market is a vertical-integration race where captive control over titanium alloy foundries and in-house FCC testing laboratories determines who captures margin compression resilience and certification timeline advantages.
For Market Incumbents: Extend service contract penetration in German and Japanese institutional markets to lock out integrated system competitors, while securing secondary supplier qualification outside Guangdong Province to buffer PCB concentration risk. Eheim GmbH & Co. KG and Fluval must defend against solid-state relay specialists by accelerating predictive failure algorithm deployment. For New Entrants and Emerging Players: Launch via direct-to-farm distribution in Brazil's Amazonas state discus breeding collectives, where ANVISA registration delays have stranded incumbent digital controllers and thermostatic simplicity meets underdeveloped infrastructure. Target Brazilian ornamental aquaculture clubs in São Paulo metropolitan corridors with economy-grade submersible units bypassing electromagnetic compliance complexity. For Investors and Strategic Acquirers: Distressed-cycle entries favor mid-tier assemblers with qualified secondary supplier networks in Vietnam and India, where PLI scheme localization incentives are compressing domestic equipment cost structures. Watch for copper-nickel price inflection signals as the trigger for margin restoration versus further assembler consolidation.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Titanium Foundries | Captive alloy supply secures marine-grade element quality and buffers raw material price swings. |
| In-House FCC Testing Laboratory Buildout | Internal electromagnetic compliance verification compresses 4-6 month certification timelines for digital controllers. |
| Propane-Based Cooling Circuit Transition | EU F-Gas Regulation compliance opens European commercial aquaculture procurement channels. |
| IoT-Enabled Predictive Maintenance Platform | Cloud-connected thermal loggers displace spot replacement revenue with recurring service contracts. |
| Mekong Delta Distribution Partnership | Direct farm equipment supply relationships capture Vietnam pangasius and shrimp farming standardization. |
Study Parameters
Independent corroboration across equipment procurement managers at Vietnamese pangasius farms, German public aquarium contractors, and North American pet-store category buyers underwrites the qualitative findings. Primary interviews with thermal management R&D directors, aquaculture facility engineers, and regulatory compliance officers combined with secondary validation from EPA appliance efficiency filings, EU ECHA REACH substance restriction updates, and Vietnamese Ministry of Agriculture aquaculture infrastructure reports. Bottom-up shipment data triangulation against top-down equipment value estimates anchored the market sizing.
Comparable-period anchoring linked historical submersible heater and chiller shipment patterns across the projection horizon to derive capacity expansion trajectories. Segmentation modeling spanned product architecture, control technology, end-user sophistication, and wattage capacity tiers. CAGR derivation rested on equipment replacement cycle analysis, species-specific thermal tolerance standardization rates, and commercial aquaculture recirculating system adoption curves.
The model assumes a particular technology adoption path; alternative pathways for solid-state relay phase-angle modulation displacing mechanical thermostat architectures would alter the outlook. Forecasts reflect assumptions on EU F-Gas Regulation enforcement stringency, copper-nickel price band stability, and Indian PLI scheme localization uptake. Material deviation in Vietnamese Mekong Delta infrastructure incentive continuity or FCC certification timeline extension warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Household Items
Domestic Sauna Heaters Market
Household Items
Global Electronic Bidet Seats Market
Household Items
Latex Mattress Market
Household Items
Range Hood Cleaning Service Market
Household Items
Beach Towel Market
Household Items
Cookware Market
Household Items
Wet Wipes and Toilet Paper Market
Household Items
Drain Cleaners Market
Household Items
Toilet Care Wipes Market
Household Items
Smart Bathroom Market
Household Items
North America Tankless Water Heater Market
Household Items
Steam Cleaners Market
Household Items
Industrial Floor Mats Market
Household Items
Smart Fork Market
Household Items
Alarm Clocks Market
Household Items
Liquid Hand Soap Market