
 Latex Mattress Market | 2026-2036
Latex Mattress Market Size, Share, and Industry Trends Forecast 2026-2036
Latex Mattress Market Outlook
Thailand is narrowing its dominance in natural latex processing as plantation-to-factory infrastructure expands around Hat Yai and Surat Thani. Latexco NV leverages captive rubber sourcing across Southeast Asian cooperatives to sustain cost discipline. Avocado Mattress, LLC anchors its premium positioning through GOLS-certified organic lines and direct-to-consumer channel control. Saatva, Inc. competes on white-glove delivery integration and extended home-trial policies that reduce return friction.
A latex mattress is a sleep surface constructed from vulcanized rubber foam derived from Hevea brasiliensis sap or styrene-butadiene polymerization, typically engineered to densities between 60 and 95 kg/m³ for pressure relief and spinal alignment. Its primary commercial purpose is to serve health-conscious consumers and institutional buyers seeking hypoallergenic, durable alternatives to petroleum-based polyurethane. Natural latex commands the highest margin pool among product types due to certification scarcity and plantation supply constraints. Online retail represents the fastest-expanding distribution channel as mattress-in-a-box logistics compress working capital requirements. Residential users dominate volume, though hospitals represent a structurally sticky segment where antimicrobial specifications and long replacement cycles lock in supplier relationships.
FDA flammability standards, EPA VOC emissions protocols, and EU REACH chemical restrictions collectively shape material formulation, testing burdens, and cross-border market access for latex mattress producers. Certification complexity functions as a de facto barrier that favors scaled manufacturers with dedicated compliance teams over import-assemblers. Stakeholders must monitor divergence between U.S. state-level chemical disclosure laws and EU harmonized standards to avoid duplicative testing costs that erode export competitiveness.
Market Dynamics
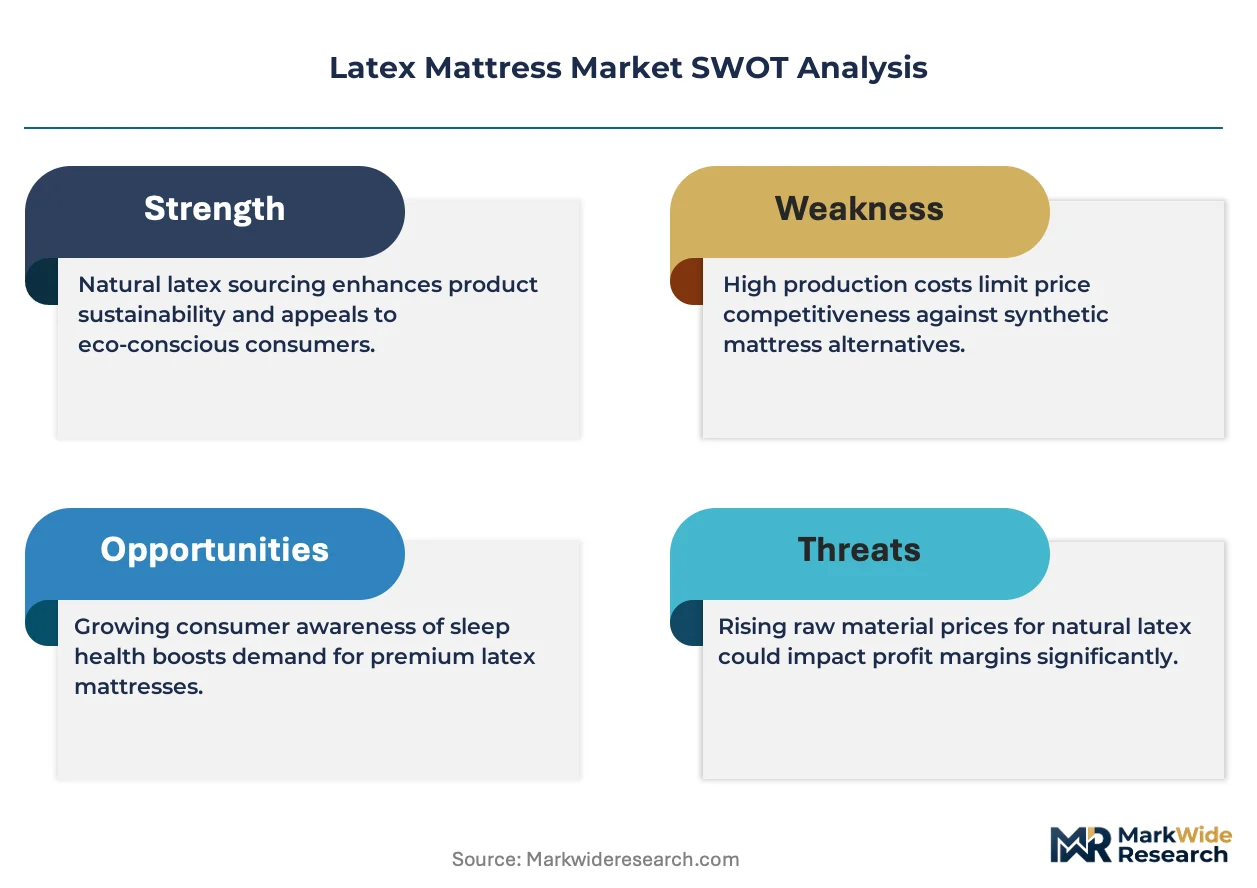
Certification scarcity around plantation-sourced natural latex is compressing supply elasticity and amplifying margin dispersion between GOLS-certified producers and synthetic-blend assemblers across wholesale and direct channels.
Growth Catalysts
- EU Green Deal procurement mandates:Eco-certified hotel chains in Germany and France now require sustainable bedding in new property fit-outs, pulling certified natural latex volumes through hospitality distribution.
- Antimicrobial specification lock-in:Hospital procurement teams specify latex surfaces meeting EPA VOC protocols, creating sticky supplier relationships with 7-10 year replacement cycles.
- Plantation-to-factory infrastructure:Rubber processing clusters around Hat Yai and Surat Thani are shortening raw material transit times and improving batch consistency for vulcanized foam production.
Market Restraints
- Hevea brasiliensis supply concentration:Thailand, Indonesia, and Vietnam control over 80% of global natural rubber tapping, exposing processors to climate-driven yield volatility and export quota disruptions.
- EU F-Gas Regulation compliance costs:Foam producers importing into Europe face expanded testing burdens for blowing agents and flame retardants, favoring scaled manufacturers with dedicated regulatory teams.
- Petroleum-based polyurethane substitution:Memory foam alternatives continue capturing price-sensitive residential segments through lower unit economics and compressed delivery logistics.
Strategic Opportunities
- India specialist retail penetration:Certified organic sleep products remain underdistributed through multi-brand outlets in Mumbai, Bangalore, and Delhi, creating whitespace for GOLS-anchored positioning.
- Online mattress-in-a-box channel expansion:Compressed latex logistics reduce working capital requirements and enable direct-to-consumer margin capture previously reserved for foam alternatives.
- REACH chemical restriction alignment:Producers achieving full material traceability gain preferential access to EU specialist retail chains as disclosure requirements tighten under harmonized standards.
Industry Challenges
- GOLS certification timeline compression:Plantation-to-retail audit cycles now exceed 14 months, constraining product launch velocity for new market entrants without existing cooperative relationships.
- Vulcanization equipment capex intensity:Continuous production lines for Dunlop and Talalay processes require specialized reactor investments that strain mid-scale manufacturer balance sheets.
- State-level chemical disclosure fragmentation:Divergence between California Proposition 65, Washington State reporting laws, and EU REACH creates duplicative testing costs that erode export competitiveness for cross-border suppliers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Latex Mattress Market |
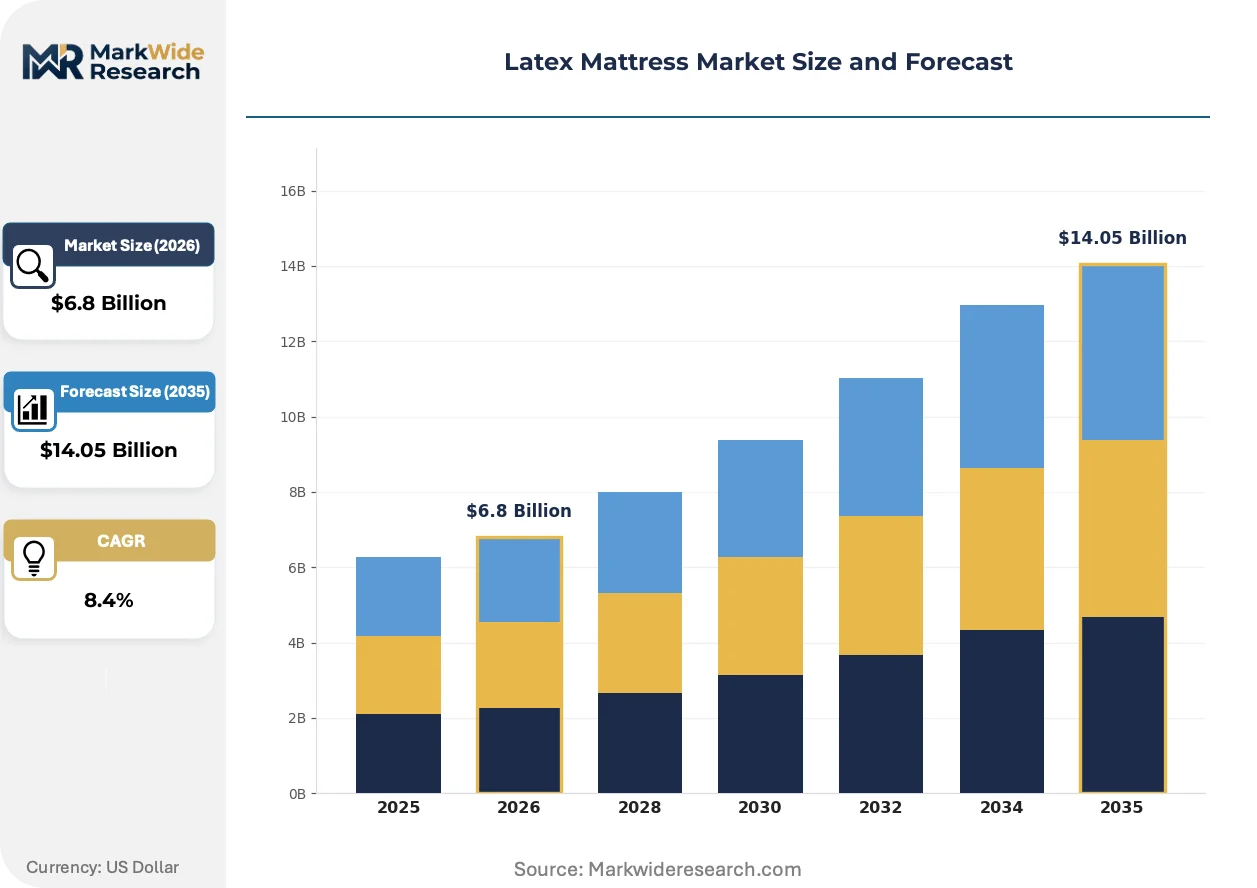
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $14.05 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Natural Latex, Synthetic Latex, Blended Latex, Organic Latex Distribution Channel: Online Retail, Specialty Stores, Department Stores, Discount Stores Customer Type: Residential Users, Hotels, Hospitals, Commercial Facilities Size: Single, Double, Queen, King |
| Companies Covered | PlushBeds, Inc., Sleep On Latex, Spring Air International, Avocado Mattress, LLC, Latexco NV, Royal-Pedic Mattress, Tempur Sealy International, Serta Simmons Bedding LLC, Saatva, Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Latex Mattress Market Strategic Shifts
Material science advances and channel restructuring are converging to redefine competitive positioning across natural and synthetic latex segments, with certification authenticity emerging as the primary differentiation axis.
Dunlop-Talalay hybrid processing is hybridizing foam density gradients within single mattress cores, enabling zoned pressure relief previously achievable only through layered assembly. Boutique hotel procurement teams in Germany and Austria are specifying these constructions for premium room categories. The technology is hybridizing cost structures by reducing labor-intensive layering steps while preserving customization depth.
EU F-Gas Regulation phase-down schedules are forcing reformulation of synthetic latex blowing agents and flame retardant packages ahead of 2030 reduction targets. Producers serving hospitality and healthcare verticals face accelerated retesting cycles for existing product lines. German specialist retailers are responding by consolidating supplier relationships around manufacturers with pre-validated REACH dossiers.
Direct-to-consumer trial period extension is displacing traditional showroom-dependent purchase patterns across residential segments. Mattress-in-a-box logistics now support 365-night return policies that reduce consumer switching friction. This behavioral shift is most visible in US and UK urban markets where white-glove delivery integration anchors brand loyalty beyond initial transaction economics.
Latex Mattress Market Segmentation
Segmentation in the latex mattress market reveals how certification tiers, channel economics, and end-use durability requirements split demand across radically different margin pools and procurement cycles. Understanding these fault lines exposes where GOLS-certified producers command pricing power versus where synthetic blends compete on logistics efficiency.
Product Type:
Material composition determines certification eligibility, plantation sourcing requirements, and exposure to EU REACH chemical restrictions across the use-case spectrum.
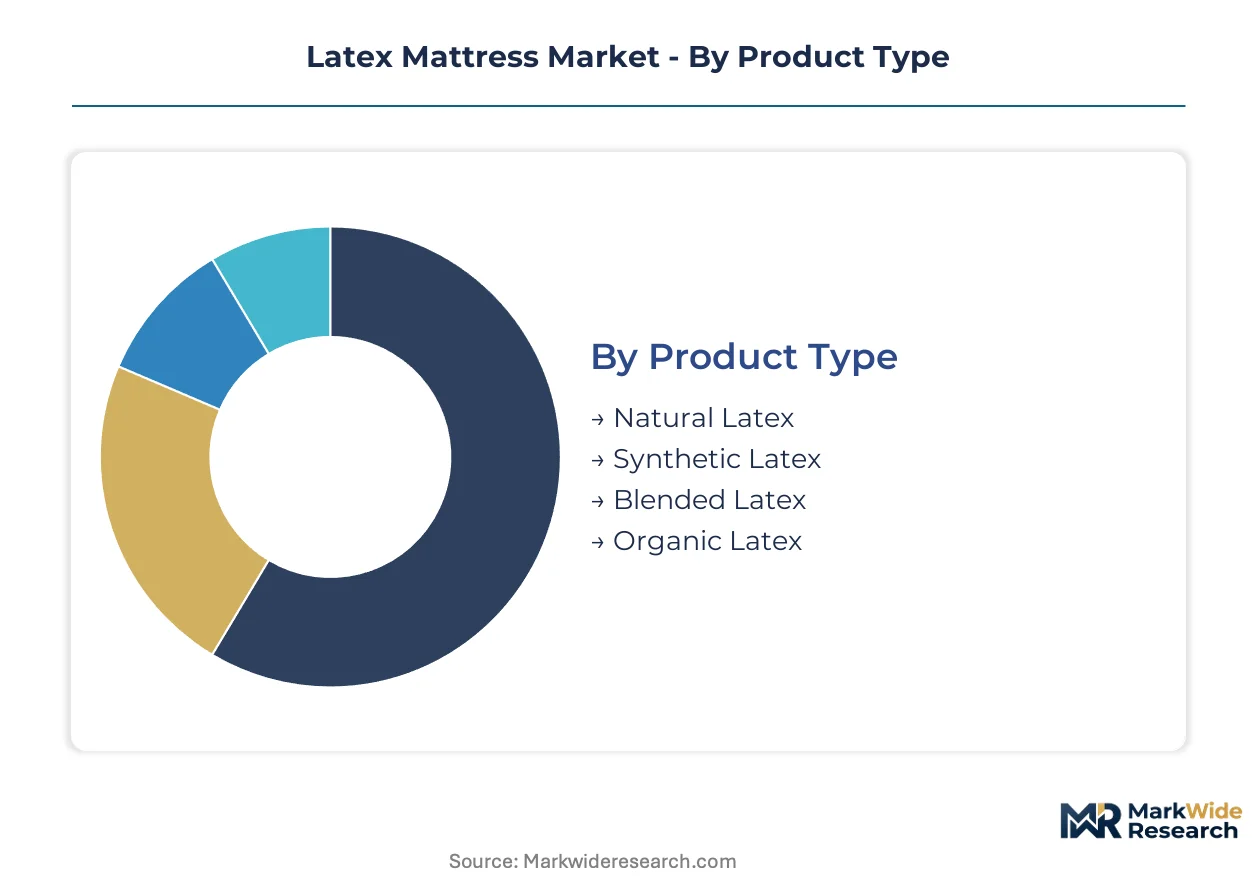
- Natural Latex:Derived from Hevea brasiliensis sap through vulcanized Dunlop or Talalay processing, typically engineered to densities between 60 and 95 kg/m³. Hospital procurement teams in Germany and France specify these surfaces for antimicrobial durability and 7-10 year replacement cycles that lock in supplier relationships.
- Synthetic Latex:Manufactured through styrene-butadiene polymerization with petroleum-derived feedstocks, offering batch consistency unconstrained by climate-driven yield volatility. Price-sensitive residential segments in the US and UK absorb these volumes through compressed mattress-in-a-box logistics that reduce working capital requirements for distributors.
- Blended Latex:Combines natural rubber content with synthetic polymerization to balance cost discipline against hypoallergenic claims; popular among mid-tier hospitality fit-outs seeking durability without GOLS certification premiums.
- Organic Latex:Plantation-to-retail supply chains meeting GOLS audit standards for chemical-free processing; boutique hotel chains in Austria and Germany now mandate these specifications under EU Green Deal procurement mandates.
The dominant share belongs to Natural Latex, while Synthetic Latex is closing the gap fastest through online retail channel expansion.
Distribution Channel:
Channel selection dictates margin capture, return policy economics, and exposure to working capital compression across residential and institutional buyer types.
- Online Retail:Compressed latex logistics enable 365-night trial periods and white-glove delivery integration that reduces consumer switching friction. UK and US urban markets show the steepest expansion trajectory here as direct-to-consumer brands bypass wholesale markups.
- Specialty Stores:Physical showrooms in Germany, Austria, and Switzerland anchor premium positioning for GOLS-certified organic lines through tactile evaluation and sleep consultant staffing. These channels absorb higher inventory carrying costs but sustain margin premiums unavailable through digital routes.
- Department Stores:Multi-brand aggregation points for mid-tier blended and synthetic offerings; facing displacement as online trial policies erode the traditional showroom-dependent purchase pattern.
- Discount Stores:Volume clearing channels for synthetic and entry-level blended constructions; procurement concentrates around price-sensitive residential replacement cycles with minimal certification requirements.
Specialty Stores retain margin leadership in certified organic segments, though Online Retail is gaining share fastest among residential buyers under 45.
Customer Type:
End-use durability specifications and procurement cycle length create divergent supplier stickiness across health, hospitality, and residential verticals.
- Residential Users:Individual consumers purchasing through online or retail channels; trial period extension and white-glove delivery now dominate purchase decisions in US and UK metropolitan markets.
- Hotels:Boutique and eco-certified chains in Germany and France require sustainable bedding fit-outs under tightening EU Green Deal mandates; procurement teams specify plantation-sourced natural latex with full REACH traceability.
- Hospitals:Institutional buyers locking in 7-10 year replacement cycles through antimicrobial specifications meeting EPA VOC protocols; supplier relationships prove structurally sticky once validated.
- Commercial Facilities:Corporate wellness centers, student housing, and elder care operations prioritizing durability and fire safety compliance over organic certification premiums.
Residential Users dominate volume throughput, while Hotels are expanding most quickly as sustainability mandates tighten across EU hospitality procurement.
Size:
Dimension selection correlates with channel economics, shipping logistics constraints, and regional bedroom architecture standards across key demand clusters.
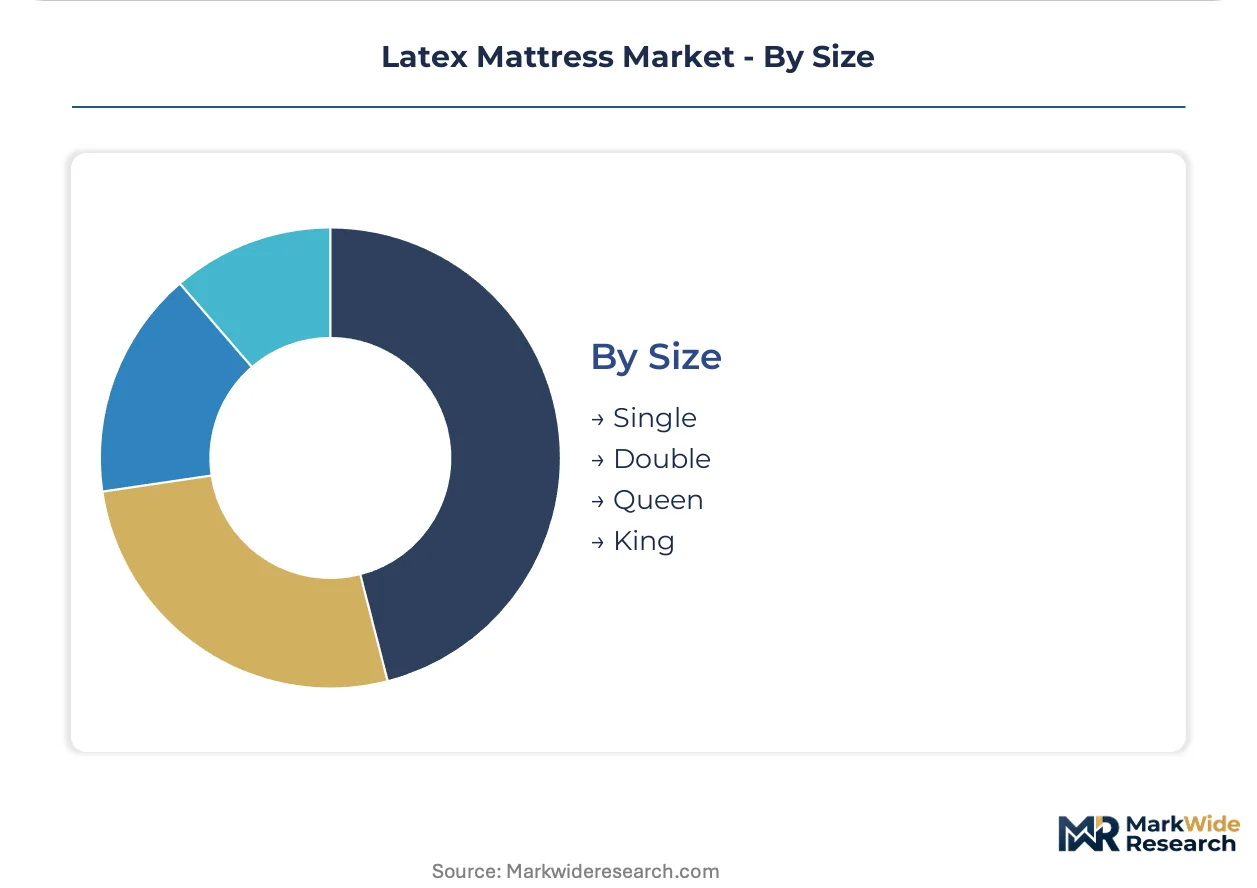
- Single:Compact dimensions suited to student housing, elder care facilities, and urban apartments in dense European and Asian cities; compressed logistics enable efficient online fulfillment.
- Double:Transitional sizing popular in UK and German guest accommodations where space constraints limit queen-scale deployment; hospitality procurement favors these for standard room categories.
- Queen:North American residential standard anchoring premium online retail margins; white-glove delivery integration concentrates around this dimension in US urban markets.
- King:Master bedroom specification in US and Australian residential construction; requires specialized freight handling that limits discount channel penetration and sustains specialty store relevance.
Queen dimensions command the largest revenue pool in North America, while King sizing is climbing the fastest in Australian residential new-build specifications.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Port of Hamburg anchors European latex mattress distribution, handling containerized foam imports from Southeast Asian processing clusters while EU Green Deal procurement mandates reshape continental demand patterns.
Germany
Specialist retail chains in Munich and Stuttgart drive certified organic positioning as hospitality procurement teams mandate sustainable bedding fit-outs. The EU F-Gas Regulation imposes expanded testing burdens on imported foam products. The Cologne-Düsseldorf corridor concentrates white-glove logistics infrastructure serving direct-to-consumer brands.
United States
California Proposition 65 chemical disclosure laws and Washington State reporting requirements fragment compliance obligations for mattress importers. The EPA VOC emissions protocol shapes antimicrobial specifications for hospital procurement. The Los Angeles-Long Beach port complex processes compressed mattress-in-a-box volumes from Asian contract manufacturers.
Thailand
Plantation-to-factory infrastructure around Hat Yai and Surat Thani shortens raw material transit times for vulcanized foam production. The country's national rubber regulator oversees export quota allocations that influence global natural latex pricing. Bangkok-based processors supply GOLS-certified organic lines to German and Austrian specialist retailers.
India
Mumbai and Bangalore multi-brand outlets remain underdistributed for certified organic sleep products, creating whitespace for premium positioning. The Bureau of Indian Standards (BIS) governs flammability testing requirements for domestic mattress sales. The Kerala rubber belt feeds processing facilities in Tamil Nadu with plantation-sourced latex.
United Kingdom
Urban markets in London and Manchester show steep expansion in online retail channels as 365-night trial policies displace showroom-dependent purchase patterns. The UK REACH alignment with EU chemical restrictions maintains material traceability requirements post-Brexit. The Midlands distribution hub anchors compressed logistics for direct-to-consumer mattress brands.
Latex Mattress Market Competitive Environment
Platform integrators command the system tier; component specialists sit upstream with captive rubber sourcing and certification infrastructure. The vendor base stratifies between scaled manufacturers with dedicated compliance teams and import-assemblers facing duplicative testing costs. Three archetypes dominate: plantation-integrated processors, direct-to-consumer platform brands, and hospitality-focused contract manufacturers. M&A activity concentrates on cooperative relationships with Southeast Asian rubber tappers, while capacity expansion targets vulcanization reactor investments for Dunlop and Talalay processes.
Within the plantation-integrated tier, Latexco NV represents European processing scale with cooperative sourcing across Southeast Asia. Avocado Mattress, LLC and Saatva, Inc. anchor the direct-to-consumer platform segment, occupying positions defined by certification authenticity and white-glove delivery integration respectively. These three exemplify how supply chain control and channel economics split competitive positioning across premium and mass-market vectors.
| Leading Market Players |
|---|
| PlushBeds, Inc. |
| Sleep On Latex |
| Spring Air International |
| Avocado Mattress, LLC |
| Latexco NV |
| Royal-Pedic Mattress |
| Tempur Sealy International |
| Serta Simmons Bedding LLC |
| Saatva, Inc. |
| Others |
Value Chain & Pricing Dynamics
Thailand's plantation-to-factory clusters around Hat Yai and Surat Thani concentrate raw material access, anchoring margin pools downstream with GOLS-certified processors who command premiums from German specialist retailers and EU hospitality procurement teams.
Pricing Analysis
EU REACH chemical restrictions dictate the pricing tier structure across import channels, separating GOLS-certified organic lines from synthetic-blend alternatives. Certification grade and volume scale drive price differentiation, with plantation-audited natural latex capturing the widest spreads. Cost compression in mid-tier blended segments is intensifying because petroleum-based polyurethane alternatives erode residential price tolerance. Price-sensitive buyers cluster in US and UK online retail channels, while least-sensitive procurement concentrates in German hospital systems and Austrian boutique hotel chains.
Supply Chain Analysis
Hevea brasiliensis sap feeds from Thailand, Indonesia, and Vietnam, with vulcanized foam production anchored in Southeast Asian processing clusters. Raw material dependencies center on plantation rubber tapping, sulfur vulcanization agents, and Dunlop or Talalay reactor equipment. Single-source vulnerability runs through Thai export quota allocations administered by the national rubber regulator. Distribution runs through Hamburg for EU specialist retail, Los Angeles-Long Beach for US mattress-in-a-box fulfillment, and direct cooperative relationships for hospitality contract manufacturers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Incumbents face a substitution defense against petroleum-based polyurethane memory foam, which continues capturing price-sensitive residential segments through compressed logistics and lower unit economics.
For Market Incumbents: Insulate certified organic positioning through captive plantation relationships that compress GOLS audit timelines below 14-month industry averages. Backward integration into Surat Thani processing infrastructure defends margin pools against synthetic-blend assemblers while EU F-Gas Regulation compliance costs filter out import-dependent competitors. For New Entrants and Emerging Players: Pursue whitespace in Indian multi-brand retail channels across Mumbai, Bangalore, and Delhi where certified organic sleep products remain underdistributed. A GOLS-anchored positioning strategy, combined with mattress-in-a-box logistics adapted to compressed latex economics, unlocks penetration without incumbent showroom infrastructure. For Investors and Strategic Acquirers: Capital is best deployed toward plantation-integrated processors with pre-validated REACH dossiers and established cooperative sourcing across Southeast Asian rubber tappers. Long-term viability hinges on vulcanization reactor ownership that locks in batch consistency for hospitality and healthcare verticals. Watch EU Green Deal procurement mandate expansion as the signal for accelerated certified natural latex demand inflection.| Strategic Initiative | Industry Significance |
|---|---|
| Captive Plantation Sourcing | Secures GOLS certification velocity against 14-month audit cycles for new entrants. |
| REACH Dossier Pre-validation | Unlocks preferential EU specialist retail access as chemical disclosure requirements tighten. |
| Mattress-in-a-box Logistics Adaptation | Enables 365-night trial economics previously reserved for polyurethane foam competitors. |
| Vulcanization Reactor Investment | Locks in Dunlop and Talalay process control for hospital procurement durability specifications. |
| White-glove Delivery Integration | Anchors brand loyalty in US and UK urban markets beyond initial transaction economics. |
Study Parameters
Operator-level perspectives from mattress procurement managers at German and Austrian boutique hotel chains, hospital biomedical engineers specifying antimicrobial surfaces, and Southeast Asian plantation cooperative directors anchored the qualitative base. These primary inputs combined with secondary validation from EU F-Gas Regulation implementation documents, EPA VOC emissions protocol filings, and customs trade data tracking containerized foam imports through Hamburg and Los Angeles-Long Beach. Bottom-up channel volume estimates and top-down macroeconomic sizing triangulated across the analysis window.
Scenario-bracketing around EU Green Deal mandate acceleration, climate-driven Hevea yield volatility, and petroleum feedstock price swings structured the analytical framework. Segmentation dimensions modeled include material composition tier, distribution channel economics, end-use durability requirements, and regional regulatory cluster. CAGRs derived from elasticity-adjusted demand curves incorporating hospitality fit-out cycles, hospital replacement timelines, and residential trial-period conversion rates.
Macroeconomic conditions sit as an overlay; deviation in euro-dollar exchange rates, Southeast Asian export quota allocations, or EU chemical restriction enforcement intensity would shift the trajectory. Cross-checking against hospital procurement database benchmarks and hospitality FF&E spend patterns is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Household Items
Portable Vacuum Cleaner Market
Household Items
Window Rain Guards Market
Household Items
Europe Electric Cordless Lawn and Garden Tools Market
Household Items
Bladeless Neck Fan Market
Household Items
Robot Mops Market
Household Items
Wax Removal Aids Market
Household Items
Sanitary Metal Ware Market
Household Items
Trash Can Market
Household Items
Barbecue Grill Market
Household Items
Smart Connected Water Purifier Market
Household Items
Stainless Steel Thermos Cup Market
Household Items
Global Aluminum Cookware Market
Household Items
Soap Dispenser Market
Household Items
Europe Coin-Operated Laundries Market
Household Items
Stainless Steel Water Bottles Market
Household Items
Shoe Shine Machine Market