
 North America Small Home Appliances Market | 2026-2036
North America Small Home Appliances Market Size, Share, and Industry Trends Forecast 2026-2036
North America Small Home Appliances Market Analytics
E-commerce channel strategy is tilting toward direct-to-consumer platforms and curated online marketplaces. Ninja leverages aggressive social-media marketing and influencer partnerships to sustain brand visibility among younger buyers. Hamilton Beach anchors its position through broad retail distribution and value-oriented product lines across big-box channels.
North America Small Home Appliances encompass electrically powered countertop and portable devices, typically operating at 120V with rated capacities from 300W to 1,500W, designed for food preparation, beverage brewing, and limited cooking functions in residential and light commercial settings. Coffee makers and blenders command the largest revenue pools, reflecting sustained consumer investment in at-home beverage rituals. The premium price tier captures disproportionate margin contribution as buyers trade up for connected features and professional-grade performance.
The U.S. Department of Energy and Health Canada enforce efficiency and safety standards that elevate compliance costs but also filter out low-quality imports, tightening competitive dynamics. The U.S. Consumer Product Safety Commission monitors recall patterns and fire-risk incidents, pressuring manufacturers toward improved thermal management and cord safety designs. Stakeholders must weigh whether to prioritize smart-home integration investments or double down on durability claims as the basis for price positioning.
Market Dynamics
Residential kitchen electrification and U.S. Department of Energy efficiency mandates are compressing product development cycles while elevating compliance costs for manufacturers serving the North American market.
Growth Catalysts
- Appliance efficiency standards:The U.S. Department of Energy's escalating wattage caps for countertop devices push manufacturers toward brushless motor designs and advanced thermal management systems.
- Urban apartment densification:Northeast corridor households prioritize 120V compact appliances under 1,500W, creating sustained pull for space-optimized form factors.
- At-home beverage ritual retention:Coffee preparation and smoothie consumption behaviors established during 2020-2021 continue driving replacement demand across residential segments.
Market Restraints
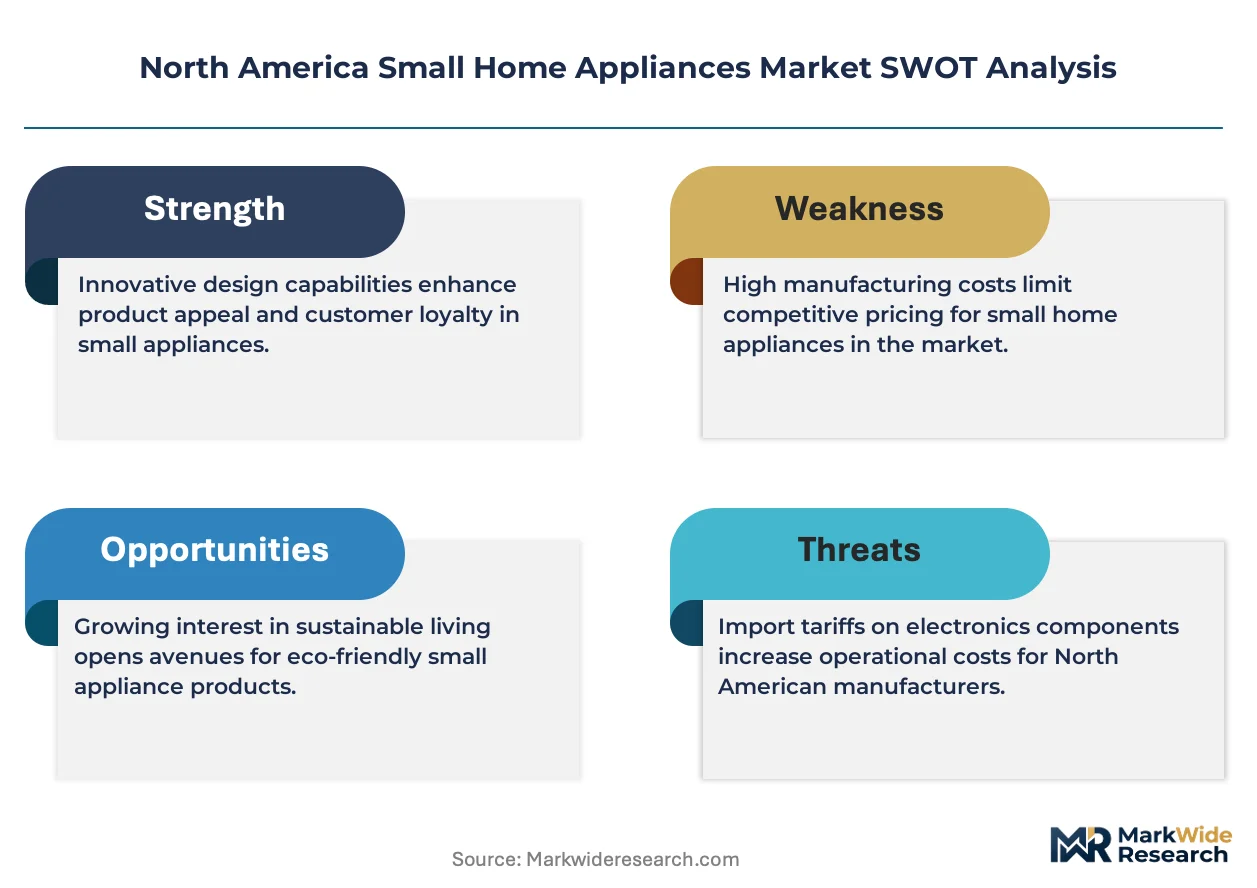
- Copper and rare-earth magnet volatility:Motor winding materials and neodymium prices fluctuate with energy transition demand, compressing gross margins on mid-tier product lines.
- Asian component concentration:Power electronics and heating element supply chains cluster in Guangdong and Zhejiang provinces, exposing North American assemblers to transpacific logistics friction.
- 120V thermal ceiling:North American voltage standards cap heating element output below European and Asian equivalents, limiting performance parity for cooking-adjacent appliances.
Strategic Opportunities
- Canadian regulatory alignment:Health Canada's harmonized efficiency standards with U.S. DOE rules create cross-border product platform economies for compliant manufacturers.
- Smart-home protocol convergence:Matter certification is enabling unified control interfaces across Amazon Alexa, Google Home, and Apple HomeKit ecosystems.
- Direct-to-consumer refurbishment:Curated online marketplaces for certified pre-owned appliances address price-sensitive entry buyers without diluting primary channel positioning.
Industry Challenges
- Embedded systems engineering scarcity:Firmware development for connected appliances competes with automotive and industrial IoT sectors for constrained talent pools.
- UL 1026 certification timelines:Safety testing for household cooking appliances extends 16-24 weeks, delaying seasonal product launches.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Small Home Appliances Market |
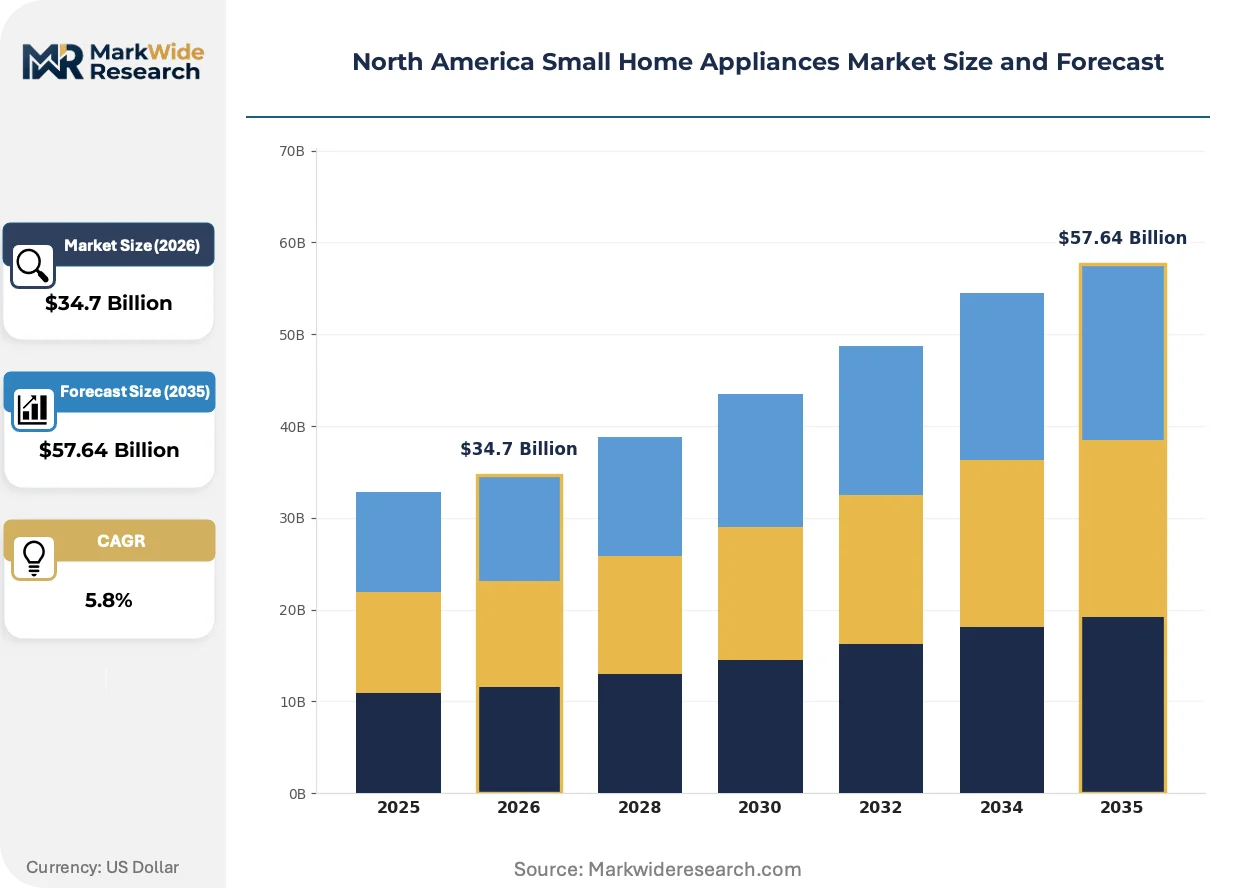
| Market Size in 2026 | $34.7 Billion |
| Market Size in 2035 | $57.64 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Blenders, Coffee Makers, Toasters, Microwaves End User: Residential, Offices, Hospitality, Retail Distribution Channel: Online, Hypermarkets, Specialty Stores, Discount Stores Price Tier: Budget, Mid-Range, Premium, Luxury |
| Companies Covered | Ninja (SharkNinja, LLC), Hamilton Beach, Cuisinart, Panasonic Corporation, GE Appliances (a Haier company), Whirlpool Corporation, Electrolux AB, BSH Hausgeräte GmbH, Dyson, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Small Home Appliances Market Evolving Landscape
Sensor fusion and connectivity integration are redefining product value propositions across the North American small appliance landscape, compressing the traditional hardware replacement cycle.
Precision temperature sensing paired with PID control algorithms is digitizing brewing and cooking workflows previously dependent on user judgment. Premium coffee maker lines now embed SCAA-certified brewing profiles adjustable via smartphone interfaces. This capability is digitizing the specialty coffee preparation segment, enabling appliance brands to capture recurring revenue through subscription bean services.
The U.S. Department of Energy's amended standby power regulations took effect in 2025, mandating sub-1-watt idle consumption for most countertop categories. Manufacturers have responded with redesigned power supply architectures and modified microcontroller sleep states. Single-serve beverage systems face disproportionate redesign burden given their always-on heating element requirements.
Younger household formation patterns favor rental-friendly appliances with modular storage and transportability. Urban consumers prioritize compact footprints and multi-function consolidation over single-purpose devices. This preference rotation concentrates demand in the U.S. Northeast and Pacific Northwest metropolitan corridors where apartment dwellers constitute dominant buyer segments.
North America Small Home Appliances Market Segmentation
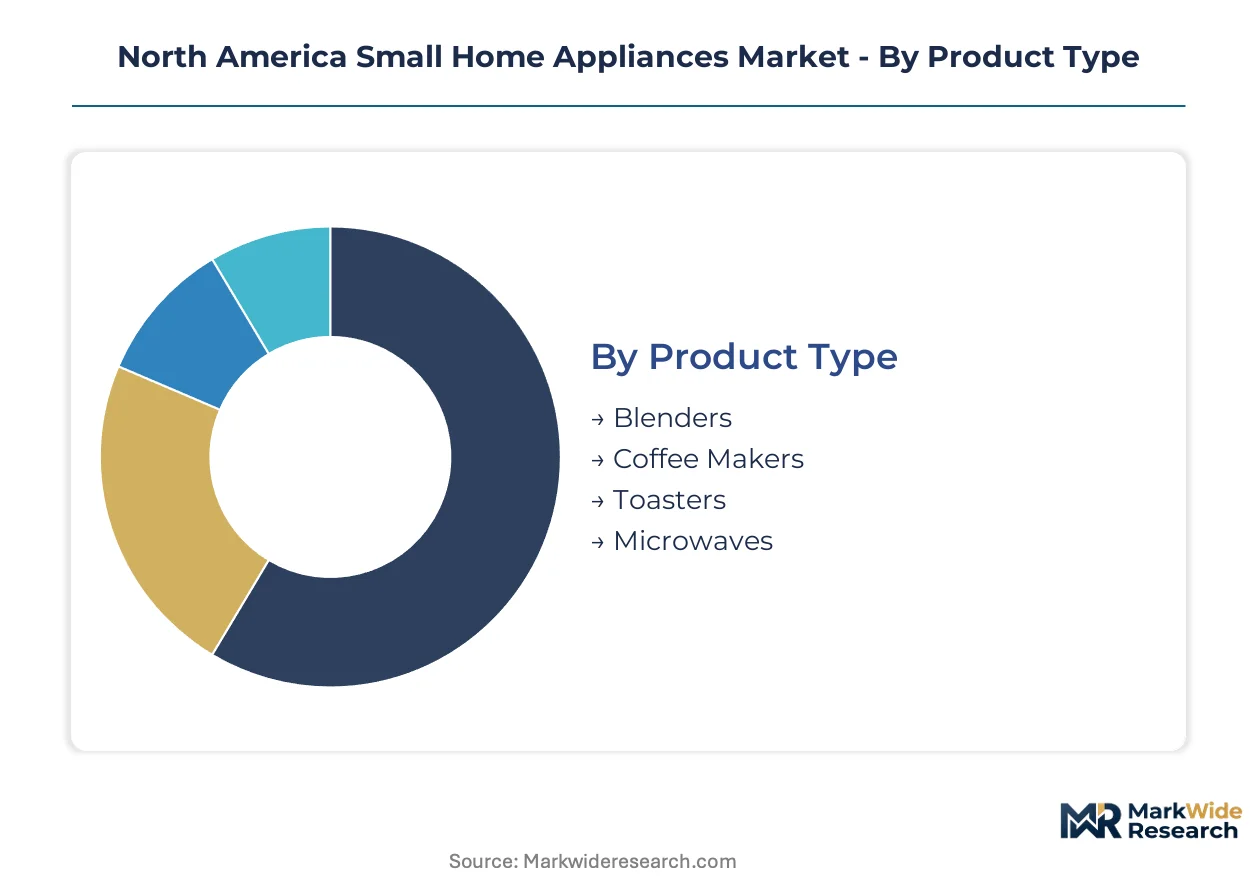
Segmentation in North American small home appliances reveals distinct service intensity patterns across product categories. Warranty claims and replacement part availability vary sharply between beverage systems and heating appliances, shaping manufacturer margin structures and channel relationships differently.
Product Type:
After-sales service intensity diverges materially across appliance categories, with motorized blending systems requiring more frequent component replacement than passive heating devices.
- Coffee Makers:These systems integrate heating elements, water pumps, and electronic controls that demand periodic descaling and seal replacement. Demand concentrates in the U.S. Northeast corridor, where apartment dwellers prioritize single-serve and precision-brew formats that minimize countertop footprint while maintaining beverage quality.
- Blenders:High-RPM brushless motors and hardened blade assemblies define the technical specification tier. Canadian metropolitan markets show particular appetite for professional-grade pitcher capacities, driven by health-conscious household smoothie preparation routines and small commercial kitchen applications.
- Toasters:Nichrome heating elements and mechanical timing mechanisms dominate this category. U.S. Pacific Northwest households favor extended-slot designs accommodating artisan bread formats.
- Microwaves:Magnetron power supplies and control panel interfaces determine replacement cycle economics. Budget-conscious replacement demand persists across Southern U.S. states where rental turnover accelerates appliance depreciation.
By volume, Coffee Makers leads. By growth pace, Blenders is ahead.
End User:
Cost tier stratification across end-use segments creates divergent procurement patterns, with commercial buyers prioritizing durability specifications over residential aesthetic preferences.
- Residential:Individual household purchasing decisions dominate absolute volume, with kitchen renovation cycles and appliance replacement timelines driving transaction timing. U.S. Department of Energy efficiency ratings influence selection criteria among environmentally conscious buyers.
- Offices:Corporate procurement departments negotiate fleet pricing for break-room installations, with reliability metrics outweighing feature depth. Health Canada workplace safety guidelines inform electrical specification requirements for Canadian installations.
- Hospitality:Boutique hotels and extended-stay properties require in-room appliance configurations balancing guest satisfaction with housekeeping durability concerns. Urban corridor properties favor compact form factors that maximize usable floor space.
- Retail:Food service counters and convenience store operators select appliances for high-cycle durability under commercial warranty terms. California and Texas retail density supports concentrated regional demand.
Residential commands absolute volume. Hospitality shows the steepest expansion trajectory among commercial segments.
Distribution Channel:
Volume concentration varies sharply by channel, with digital platforms capturing replacement-cycle purchases while physical retail dominates first-time buyer education and trial.
- Online:Direct-to-consumer platforms and curated marketplaces enable specification comparison and subscription accessory bundling. Younger household formation in dense metropolitan corridors favors this channel for space-constrained product research.
- Hypermarkets:Big-box retail chains provide tactile evaluation opportunities and immediate fulfillment for urgent replacement needs. Midwest U.S. population centers maintain strong hypermarket preference patterns.
- Specialty Stores:Kitchenware boutiques and department store appliance galleries emphasize premium positioning and extended warranty offerings. Northeast corridor urban consumers value staff expertise for complex brewing systems.
- Discount Stores:Value-oriented channels serve price-sensitive entry buyers and secondary residence provisioning. Southern border states show elevated discount channel penetration.
Hypermarkets lead by transaction count. Online is gaining share fastest.
Price Tier:
Margin structure stratification across pricing tiers determines manufacturer portfolio prioritization, with connected features and professional-grade materials justifying premium positioning.
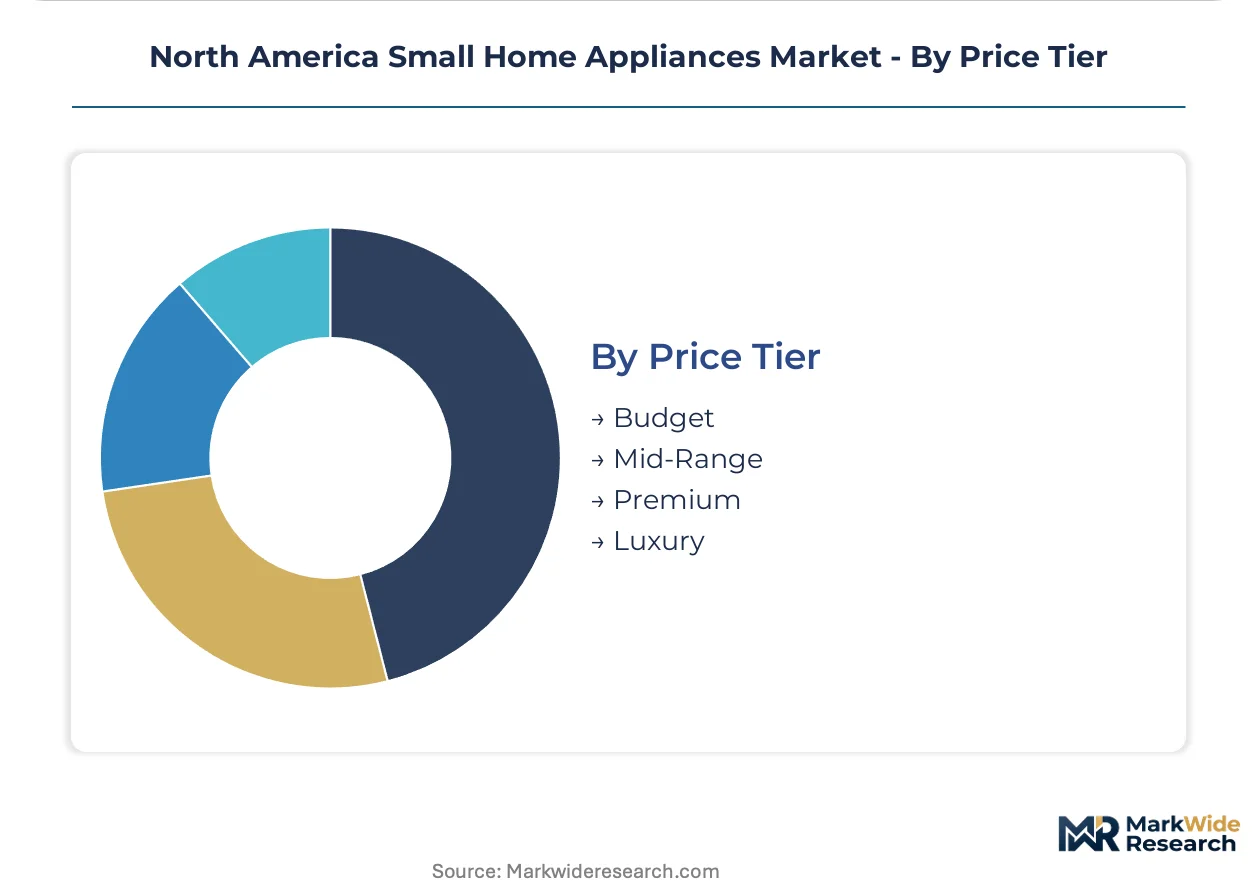
- Premium:PID temperature control, smartphone connectivity, and commercial-grade materials define this specification band. U.S. West Coast metropolitan markets demonstrate willingness to pay for smart-home integration and SCAA-certified brewing precision.
- Mid-Range:Balanced feature sets with selective connectivity options target kitchen renovation cycles and gift purchase occasions. Canadian suburban households concentrate demand in this tier.
- Budget:Essential functionality without connectivity or advanced sensing capabilities serves replacement urgency and secondary residence markets. Price elasticity is highest in this segment.
- Luxury:Design-forward aesthetics and limited-edition collaborations with culinary personalities command collector-oriented purchasing. Manhattan and Los Angeles postal codes show disproportionate concentration.
Mid-Range dominates unit volume. Premium is expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The U.S. Department of Energy's escalating efficiency mandates and Health Canada's harmonized standards are compressing product development cycles across North American markets while elevating compliance costs for countertop appliance manufacturers.
United States
Apartment densification in the Northeast corridor sustains demand for sub-1,500W compact appliances designed for 120V circuits. The U.S. Department of Energy's amended standby power regulations mandate sub-1-watt idle consumption for most countertop categories. Chicago and Boston metropolitan clusters concentrate procurement for space-optimized coffee makers and blenders targeting urban rental households.
Canada
Health-conscious households in Toronto and Vancouver drive professional-grade blender demand for smoothie preparation routines. Health Canada enforces workplace safety guidelines that inform electrical specifications for commercial installations. The Greater Toronto Area anchors distribution infrastructure serving cross-border product platform economies with U.S. DOE-aligned efficiency standards.
Mexico
Manufacturing assembly operations in Nuevo León and Baja California serve North American market supply requirements for motor windings and power electronics. The country's national energy regulator implements efficiency labeling programs that parallel U.S. appliance standards. Tijuana and Monterrey industrial corridors house contract manufacturers producing heating elements and control assemblies for U.S. brands.
North America Small Home Appliances Market Competitive Landscape
On the supply side, the industry is moderately consolidated around diversified appliance conglomerates and specialized small-appliance pure-plays competing across distinct price-performance tiers. The vendor base stratifies into three strategic archetypes: mass-market volume leaders, premium-feature specialists, and design-forward lifestyle brands. Dominant competitive moves include portfolio diversification into adjacent beverage and food-prep categories and strategic partnerships with smart-home ecosystem providers for Matter certification.
Within the premium-feature specialist tier, Ninja and Cuisinart exemplify archetypes competing on programmable precision and professional-grade performance claims. Hamilton Beach anchors the mass-market volume position through value-oriented product lines and broad retail distribution. Panasonic Corporation occupies a position bridging mid-range and premium segments with Japanese-engineered reliability positioning.
| Leading Market Players |
|---|
| Ninja (SharkNinja, LLC) |
| Hamilton Beach |
| Cuisinart |
| Panasonic Corporation |
| GE Appliances (a Haier company) |
| Whirlpool Corporation |
| Electrolux AB |
| BSH Hausgeräte GmbH |
| Dyson |
| Others |
Value Network & Pricing Analysis
Guangdong and Zhejiang province manufacturing clusters for power electronics and heating elements concentrate upstream bargaining power with Asian component suppliers, compressing margin capture for North American assemblers who must absorb transpacific logistics friction while defending retail price points.
Pricing Analysis
Volume-discount tiering structures separate premium connected-appliance lines with Matter certification and SCAA-certified brewing precision from standard-tier products lacking smart-home integration, with economy offerings stripped to essential thermal functions. Price differentiation rests on UL 1026 safety certification status and brushless motor specification grade. Cost compression in mid-range segments is intensifying because copper and rare-earth magnet volatility feeds through to bill-of-materials pressure. Budget-tier buyers in Southern U.S. states and discount-channel shoppers exhibit highest price elasticity, while West Coast metropolitan purchasers of premium connected systems show lowest sensitivity.
Supply Chain Analysis
Export-control regime scrutiny on advanced power semiconductors and magnetron technology limits certain heating-element controller flows from specified Asian manufacturing jurisdictions. Motor winding materials and neodymium permanent magnets draw from concentrated Chinese and Vietnamese processing capacity, with Taiwanese foundries supplying key microcontroller components. Single-source vulnerability runs through Guangdong-based power electronics assembly. Distribution runs through big-box retail chains for tactile evaluation and immediate fulfillment, complemented by direct-to-consumer platforms capturing replacement-cycle purchases.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a defensive-moat story anchored in regulatory entrenchment: U.S. Department of Energy efficiency mandates and UL 1026 certification timelines create structural barriers that favor incumbents with established compliance infrastructure and capitalized testing relationships.
For Market Incumbents: Harden certification infrastructure through captive UL 1026 pre-testing capabilities and accelerated seasonal launch timelines to outpace smaller competitors. Deepen backward integration into brushless motor winding and PID control firmware development to offset Asian component concentration. Threat of direct-to-consumer refurbishment platforms and subscription bean services from agile entrants demands defensive channel control.
For New Entrants and Emerging Players: Build out certified pre-owned marketplace positioning targeting price-sensitive entry buyers in Northeast corridor apartment markets, where space-constrained product research favors digital discovery. White-space concentrates in hospitality in-room configurations balancing guest satisfaction with housekeeping durability, and in Canadian commercial installations requiring Health Canada workplace safety alignment. Go-to-market leverage: Matter-certified smart-home integration partnerships with ecosystem providers.
For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed appliance pure-plays possessing established retail distribution but limited connected-product R&D depth. Long-term viability favors platforms with cross-border Health Canada-U.S. DOE regulatory alignment and subscription-accessory recurring revenue potential. Signal to monitor: Matter protocol adoption velocity as inflection indicator for smart-home integration premium capture.
| Strategic Initiative | Industry Significance |
|---|---|
| Matter Certification Investment | Unified control interfaces across Amazon Alexa, Google Home, and Apple HomeKit ecosystems reduce fragmentation. |
| Direct-to-Consumer Refurbishment Platform | Certified pre-owned channels address price-sensitive entry buyers without diluting primary retail positioning. |
| Brushless Motor Backward Integration | In-house winding capabilities offset copper and rare-earth magnet volatility compressing mid-tier margins. |
| Subscription Accessory Bundling | Recurring bean services and replacement part programs digitize specialty coffee preparation revenue streams. |
| Cross-Border Product Platform Harmonization | Health Canada-aligned efficiency standards with U.S. DOE rules create Canadian market expansion economies. |
Research Methodology
Operator-level perspectives from appliance brand product managers, big-box retail category buyers, UL certification engineers, and contract manufacturing procurement heads anchored the qualitative base. Primary interview findings combined with secondary validation drawn from U.S. Department of Energy appliance standard filings, Health Canada regulatory notices, U.S. Consumer Product Safety Commission recall databases, and customs import records for heating elements and power electronics. Bottom-up shipment modeling by product category and top-down market sizing triangulated volume estimates.
Scenario-bracketing around copper price volatility bands, Matter protocol adoption velocity assumptions, and standby power regulation compliance cost trajectories framed the analytical approach across the projection horizon. Segmentation dimensions modeled include product type, end-use segment, distribution channel, and price-performance tier. CAGRs derived from regression analysis against residential household formation patterns and kitchen renovation cycle timing, with inputs from appliance replacement rate studies and urban apartment densification indices.
Stress conditions across rare-earth magnet supply disruption, transpacific logistics cost spikes, and smart-home protocol fragmentation were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions regarding efficiency mandate implementation timing and consumer trade-up willingness. Material shifts in U.S. Department of Energy standby power thresholds or Health Canada electrical specification harmonization would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Home Appliances
Italy Small Home Appliances Market
Home Appliances
Household Induction Cooktops Market
Home Appliances
Europe Washing Machine Market
Home Appliances
Refrigerator Market
Home Appliances
Colombia Home Appliances Market
Home Appliances
Russia Laundry Appliances Market
Home Appliances
Home Laundry Appliances Market
Home Appliances
Egypt Small Home Appliances Market
Home Appliances
South Korea Home Appliances Market
Home Appliances
Sweden Home Appliances Market
Home Appliances
Global Residential Microwave Oven Market
Home Appliances
Range Hood Market
Home Appliances
Mexico Small Home Appliances Market
Home Appliances
Portable Dehumidifier Market
Home Appliances
Saudi Arabia Major Home Appliances Market
Home Appliances
North America Home Appliances Market