
 Asean Cookware Market | 2026-2036
Asean Cookware Market Size, Share, and Industry Trends Forecast 2026-2036
Asean Cookware Market Insights
Vietnam is narrowing its cookware supply gap through northern industrial zone expansion near Hai Phong. Meyer Thailand leverages vertical integration across forging and coating operations to sustain margin control. PT Kedaung Indah Can anchors Indonesian domestic demand through nationwide distributor networks. Sunhouse Group differentiates via ceramic-coated aluminum specialization for Indochina markets.
Asean cookware encompasses vessels engineered for thermal conduction, typically fabricated from alloys with wall thicknesses between 2.5 mm and 5.0 mm, designed for stovetop or oven-based food preparation in residential and commercial kitchens. Stainless steel cookware dominates institutional procurement across Southeast Asian hotels and catering services due to durability requirements under intensive use cycles. Non-stick aluminum frying pans capture fastest volume expansion through supermarket and online retail channels serving Vietnamese and Filipino households. Cast iron retains premium positioning in specialty stores targeting artisanal cooking segments with extended heat retention specifications.
Thailand's Industrial Standards Institute mandates heavy metal migration limits for food-contact metal alloys, compelling reformulation of lower-grade aluminum offerings. Vietnam's Ministry of Science and Technology aligns cookware labeling with ASEAN harmonized standards, streamlining cross-border trade but raising compliance costs for informal producers. Indonesia's National Standardization Agency enforces nickel-content disclosure rules for stainless steel imports. Stakeholders must track evolving national implementation timelines for these overlapping regulatory frameworks.
Market Dynamics
Thailand's Board of Investment incentives for stainless steel processing are compressing regional manufacturing costs and triggering capacity relocation from higher-cost Northeast Asian suppliers into Southeast Asian industrial zones.
Growth Catalysts
- Hotel construction clusters:Ho Chi Minh City hospitality development is generating concentrated procurement demand for institutional-grade stainless steel cookware with 2.5-5.0 mm wall thickness specifications.
- Thailand's BOI processing incentives:Tax holidays and import duty exemptions for stainless steel fabrication are attracting forging and coating operations to Rayong and Chonburi provinces.
- Ceramic coating technology:Advanced sol-gel formulations are displacing traditional PTFE non-stick surfaces in Vietnamese and Filipino retail channels due to perceived safety advantages.
Market Restraints
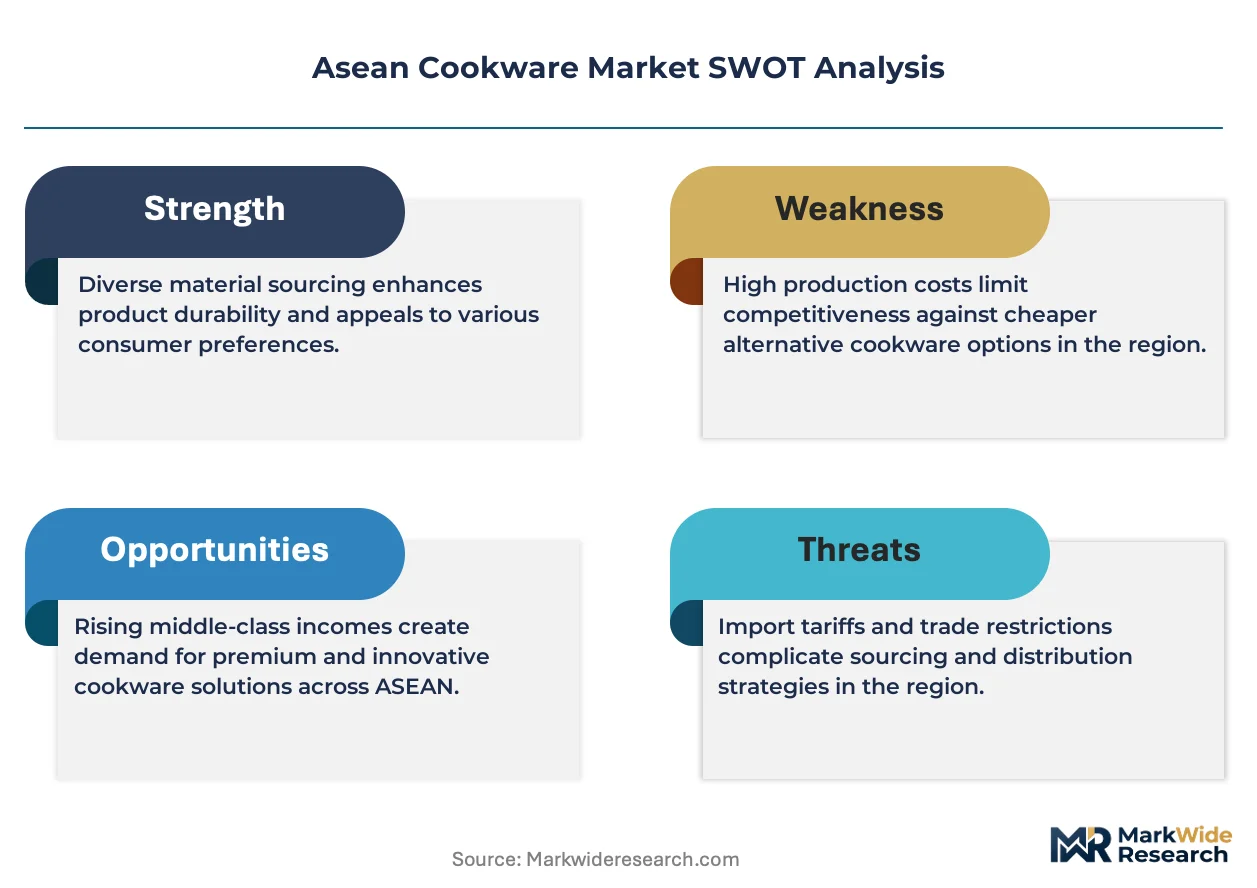
- Nickel price volatility:Stainless steel 304-grade input costs fluctuate with London Metal Exchange nickel contract movements, squeezing margin stability for Thai and Vietnamese fabricators.
- Indonesian nickel-content disclosure:BSN enforcement of SNI disclosure rules for imported stainless steel creates documentation friction and delays at Tanjung Priok port.
- Aluminum heavy metal migration limits:Thailand's TISI reformulation mandates for food-contact aluminum alloys are forcing product line retirements among informal producers.
Strategic Opportunities
- Philippine archipelago distribution gaps:Mindanao and Visayas island clusters remain underserved by organized cookware retail, creating white space for regional distributor partnerships.
- ASEAN harmonized labeling standards:Vietnam's MOST alignment with regional technical regulations is streamlining cross-border trade and reducing multi-country certification burdens.
- Induction-compatible aluminum forging:Ferromagnetic base lamination technology is opening penetration into Singapore and Malaysian households with glass-ceramic cooktop installations.
Industry Challenges
- Coating technician scarcity:Sol-gel ceramic application expertise concentrates in Thai and Vietnamese industrial zones, creating wage inflation and retention difficulties for Indonesian and Philippine facilities.
- Multi-jurisdiction compliance timelines:Simultaneous TISI, SNI, and STAMEQ certification requirements extend product launch cycles by 8-14 months for pan-regional product lines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asean Cookware Market |
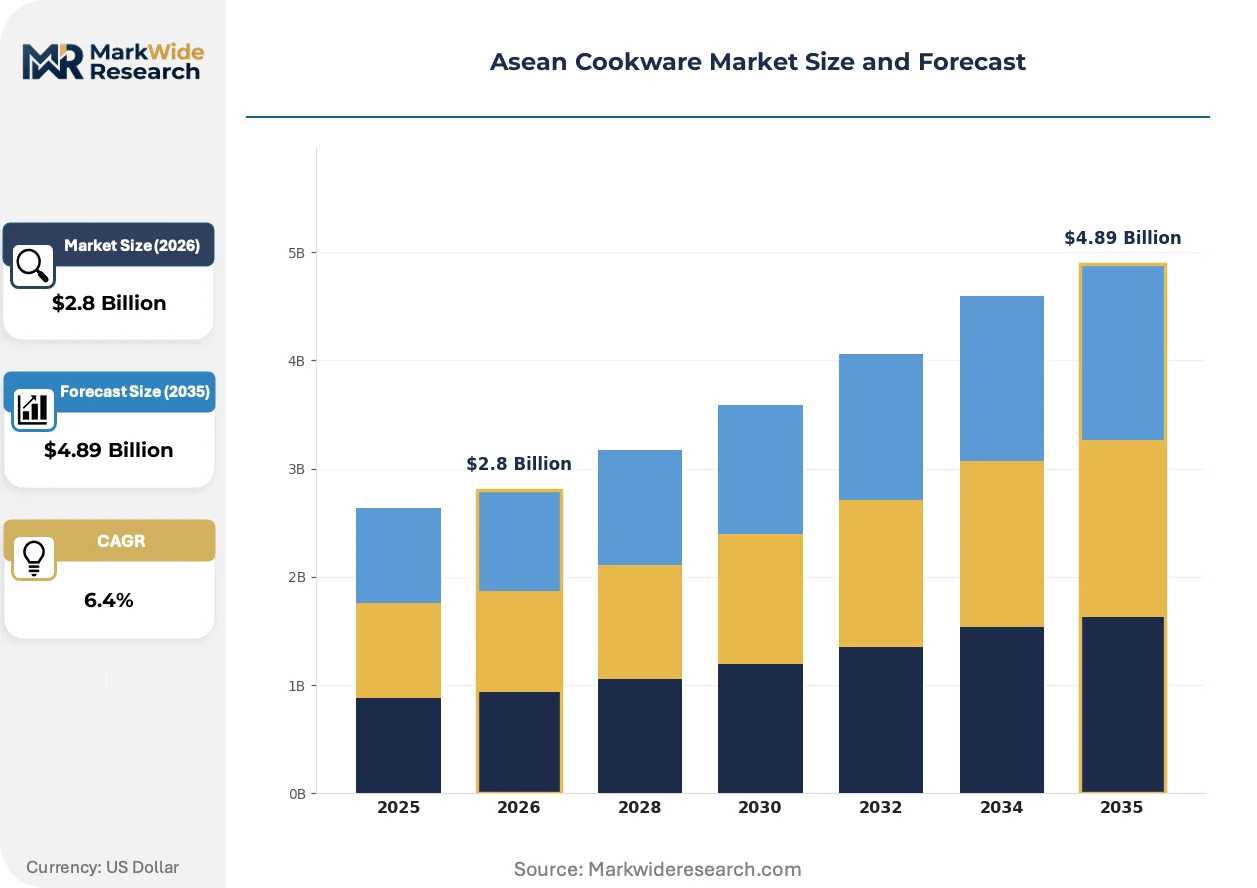
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $4.89 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Cookware Sets, Frying Pans, Saucepans, Bakeware Material: Stainless Steel, Cast Iron, Non-Stick, Copper Distribution Channel: Online Retail, Supermarkets, Specialty Stores, Wholesale End User: Households, Restaurants, Hotels, Catering Services |
| Companies Covered | PT Kedaung Indah Can, Meyer Thailand, Myrex Thailand, Satien Stainless Steel, Sunhouse Group, Heap Seng Group of Companies, PT KEDAWUNG SETIA INDUSTRIAL Ltd., Aluminum Chue Chin Hua Co., Ltd., ASD Cookware, Others |
| Regions Covered | Southeast Asia: Indonesia, Thailand, Vietnam, Philippines, Malaysia, Singapore, Myanmar, Cambodia, Rest of Southeast Asia |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asean Cookware Market Trends and Innovations
Digital manufacturing control systems and surface engineering advances are compressing product development cycles while regulatory harmonization efforts reshape competitive entry barriers across Southeast Asian markets.
Advanced thermal simulation software is virtualizing traditional prototype testing for cookware heat distribution optimization. Malaysian and Thai manufacturers are adopting computational fluid dynamics to reduce physical mold iterations by sixty percent. This virtualization is compressing time-to-market for new product geometries while lowering upfront tooling capital requirements.
Thailand's TISI heavy metal migration limits for food-contact metal alloys are forcing alloy reformulation across aluminum cookware supply chains. Foundries in Samut Sakhon and Pathum Thani are retooling smelting processes to reduce cadmium and lead trace content below 0.01 ppm thresholds. Indonesian and Vietnamese exporters targeting Thai hospitality procurement must now carry third-party laboratory certification to maintain supplier status.
Supermarket private-label cookware is displacing traditional distributor-led brand building in Vietnamese and Philippine mass retail. Central Retail Vietnam and SM Retail Philippines are consolidating shelf space under captive brands, compressing marketing margins for established manufacturers. This channel concentration is most visible in Ho Chi Minh City and Metro Manila, where organized retail penetration exceeds forty percent of cookware volume.
Asean Cookware Market Segmentation
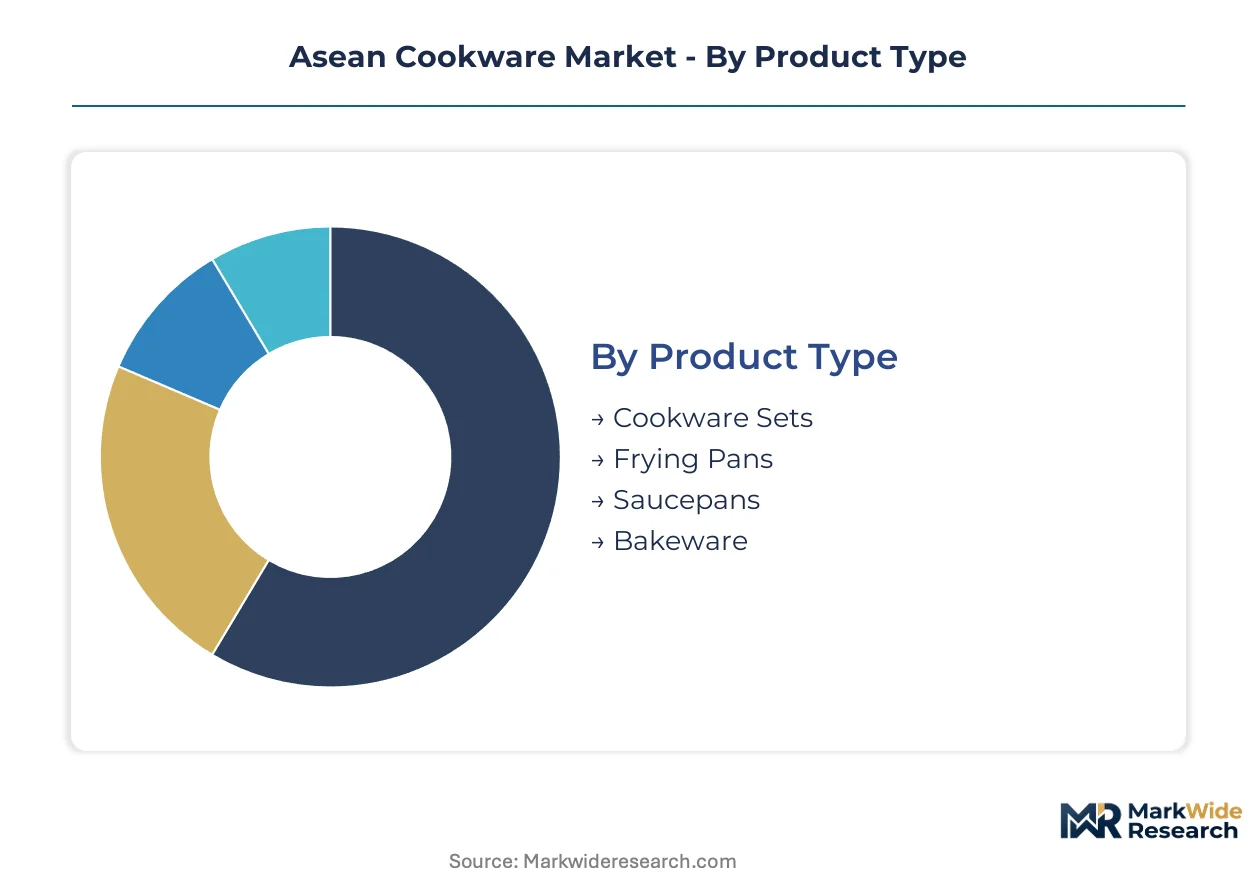
Cookware procurement patterns diverge sharply between institutional buyers with specification-driven purchasing and household consumers prioritizing aesthetics and price accessibility. Material composition and wall thickness specifications create distinct service intensity requirements across end-use segments. Distribution channel selection directly determines margin realization and brand positioning for manufacturers operating across Southeast Asian markets.
Product Type:
After-sales-service intensity varies dramatically across cookware formats, with multi-piece sets demanding warranty complexity that single-item categories avoid entirely.
- Cookware Sets:Multi-vessel configurations with coordinated lids and nesting storage profiles command premium positioning in Thai and Vietnamese department stores. Hotel procurement teams in Ho Chi Minh City specify 10-12 piece stainless steel sets with uniform wall thickness for kitchen standardization.
- Frying Pans:Non-stick aluminum skillets with 2.5-3.5 mm base thickness dominate Filipino and Vietnamese supermarket volumes. Ceramic-coated variants from Central Retail Vietnam's private-label program are displacing traditional PTFE surfaces through perceived safety differentiation.
- Saucepans:Medium-capacity vessels with pour spouts and helper handles serve simmering and reduction tasks in residential kitchens across Jakarta and Bangkok.
- Bakeware:Oven-rated aluminum and carbon steel forms with silicone grips address growing home baking participation in Malaysian urban households.
By volume, Frying Pans leads. By growth pace, Cookware Sets is expanding most quickly.
Material:
Cost tier stratification separates premium-positioned metals from mass-market alternatives with divergent margin profiles.
- Stainless Steel:304-grade and 316-grade alloys with 3.0-5.0 mm wall thickness satisfy institutional durability requirements. Thailand's BOI processing incentives are compressing regional fabrication costs for hospitality-grade specifications.
- Cast Iron:Pre-seasoned and enameled variants with extended heat retention properties command specialty store premiums in artisanal cooking segments. Vietnamese ceramic-coated aluminum competition is constraining volume expansion outside premium positioning.
- Non-Stick:Sol-gel ceramic and advanced PTFE formulations on aluminum substrates capture fastest household volume through organized retail channels.
- Copper:Tin-lined and stainless-clad variants with superior thermal responsiveness serve professional kitchen niches in Singapore and Bangkok fine-dining establishments.
By volume, Non-Stick leads. By margin contribution, Stainless Steel is ahead.
Distribution Channel:
Customer type concentration determines channel selection, with institutional buyers bypassing retail infrastructure entirely.
- Online Retail:Platform-native brands and direct-to-consumer fulfillment are capturing Vietnamese and Filipino household demand through Lazada and Shopee storefronts. Logistics infrastructure gaps in Mindanao and Visayas constrain penetration outside Luzon and major urban centers.
- Supermarkets:Central Retail Vietnam and SM Retail Philippines are consolidating shelf space under captive private-label programs, compressing marketing margins for established manufacturers in Ho Chi Minh City and Metro Manila.
- Specialty Stores:Staff-assisted selling environments with demonstration capabilities support premium material education for cast iron and copper categories.
- Wholesale:Distributor-led bulk procurement serves restaurant and hotel procurement through established trade relationships in Jakarta and Bangkok hospitality clusters.
By transaction volume, Supermarkets leads. By value realization, Wholesale is ahead.
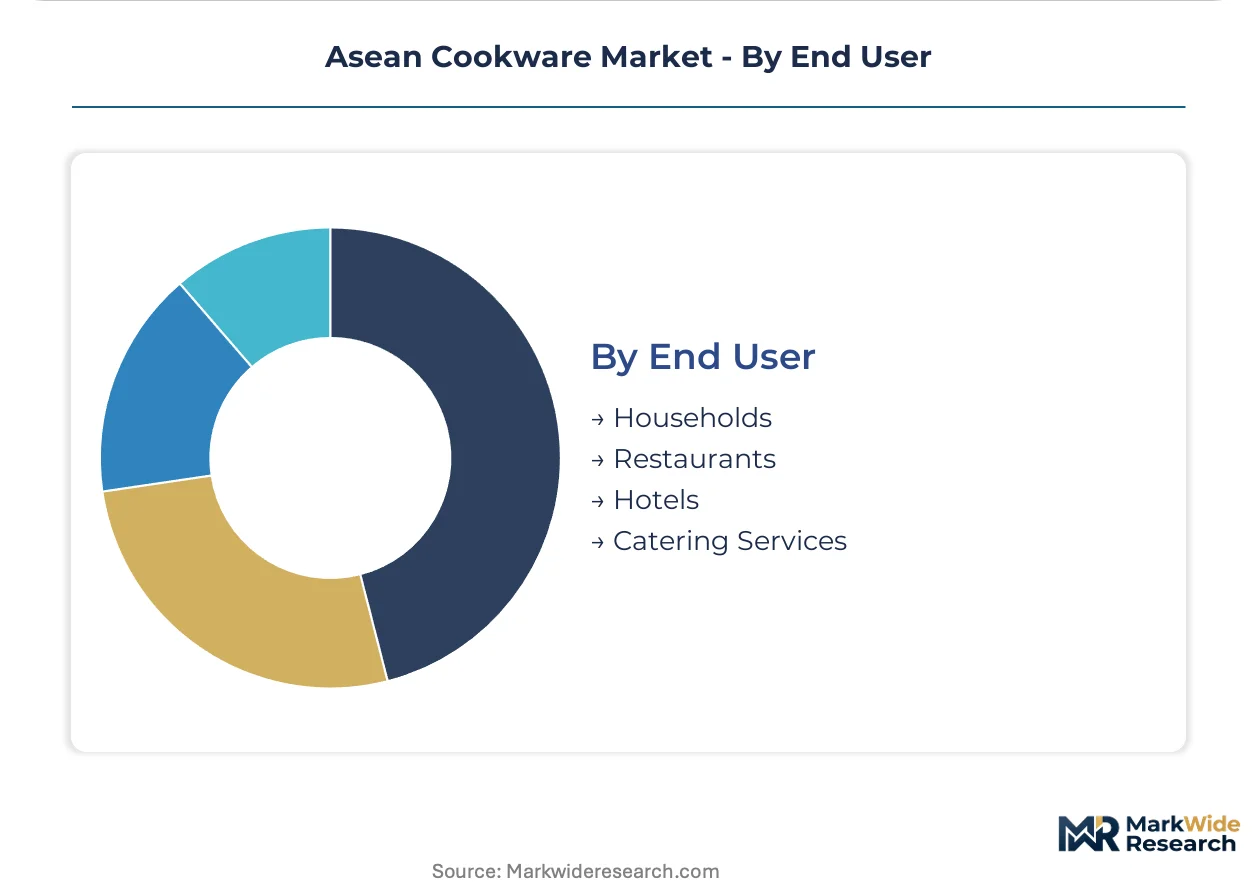
End User:
Application context dictates specification stringency, with commercial use cycles demanding durability that residential usage patterns do not require.
- Households:Aesthetic-driven purchasing with price sensitivity concentrated in mass-market aluminum and ceramic-coated segments. Filipino and Vietnamese consumers prioritize visual finish and ergonomic handle design over thermal performance specifications.
- Restaurants:High-frequency use cycles with intensive cleaning protocols drive stainless steel procurement in Bangkok and Jakarta independent dining establishments. Wall thickness minimums of 3.0 mm are standard for wok and stockpot categories.
- Hotels:Brand standardization requirements across property portfolios create volume concentration for specified product lines. Ho Chi Minh City hospitality development is generating concentrated procurement demand for institutional-grade specifications.
- Catering Services:Large-batch preparation requirements with transport durability needs favor heavy-gauge aluminum and stainless steel configurations for off-premise food service operations.
By unit volume, Households leads. By specification rigor, Hotels is ahead.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Thailand's Industrial Standards Institute anchors the regulatory framework shaping regional cookware manufacturing, with its heavy metal migration limits forcing alloy reformulation across Southeast Asian supply chains. Vietnam and Indonesia operate under distinct national standardization regimes that create overlapping compliance obligations for pan-regional producers.
Thailand
Rayong and Chonburi provinces attract stainless steel forging operations through Board of Investment tax holidays and import duty exemptions. The Industrial Standards Institute mandates cadmium and lead thresholds below 0.01 ppm for food-contact aluminum alloys. Samut Sakhon foundries retool smelting processes to maintain hospitality procurement contracts.
Vietnam
Ho Chi Minh City hospitality clusters generate concentrated demand for institutional-grade cookware with 3.0-5.0 mm wall thickness specifications. The Ministry of Science and Technology aligns labeling with ASEAN harmonized standards, streamlining cross-border trade. Northern industrial zones near Hai Phong expand forging capacity to narrow domestic supply gaps.
Indonesia
Jakarta's independent dining establishments drive stainless steel procurement for high-frequency use cycles. The National Standardization Agency enforces nickel-content disclosure rules for imported stainless steel, creating documentation friction at Tanjung Priok port. PT Kedaung Indah Can leverages nationwide distributor networks to anchor domestic demand.
Philippines
Metro Manila's organized retail penetration exceeds forty percent of cookware volume through SM Retail Philippines' private-label consolidation. Logistics infrastructure gaps constrain online retail penetration in Mindanao and Visayas island clusters. Central Retail Vietnam's ceramic-coated aluminum competition pressures traditional PTFE market share.
Malaysia
Kuala Lumpur and Penang households with glass-ceramic cooktop installations drive induction-compatible aluminum forging demand. Ferromagnetic base lamination technology opens penetration into premium kitchen renovation segments. Singapore cross-border procurement channels influence specification standards for southern Malaysian fabricators.
Asean Cookware Market Competitive Landscape
Vertically integrated specialists and distributor-anchored domestic champions split the market between margin-controlled manufacturing and reach-intensive retail networks. The vendor base concentrates in Thai industrial zones where coating expertise and forging capacity cluster, while Indonesian and Philippine players compete through distribution depth rather than production scale. Two archetypes dominate: BOI-incentivized stainless steel processors with captive forging operations, and private-label suppliers serving consolidated supermarket channels. Capacity relocation from Northeast Asian sources and ceramic coating technology licensing represent the primary competitive vectors.
Among Thai-based fabricators, Meyer Thailand exemplifies the vertically integrated archetype through its control across forging and coating operations. Sunhouse Group occupies a specialist position in ceramic-coated aluminum for Indochina markets. PT Kedaung Indah Can anchors the distributor-anchored model through its Indonesian nationwide network.
| Leading Market Players |
|---|
| PT Kedaung Indah Can |
| Meyer Thailand |
| Myrex Thailand |
| Satien Stainless Steel |
| Sunhouse Group |
| Heap Seng Group of Companies |
| PT KEDAWUNG SETIA INDUSTRIAL Ltd. |
| Aluminum Chue Chin Hua Co., Ltd. |
| ASD Cookware |
| Others |
Pricing and Supply Chain Analysis
The Laem Chabang-Hai Phong maritime corridor's freight cost volatility compresses margins for Thai stainless steel processors while amplifying price differentiation between BOI-incentivized domestic production and import-dependent Vietnamese fabricators. Nickel contract movements on the London Metal Exchange transmit directly into regional cookware pricing tiers, with Thai vertical integrators capturing cost advantages that import-reliant competitors cannot match.
Pricing Analysis
Thai-manufactured stainless steel cookware commands a fifteen to twenty-five percent premium over Vietnamese alternatives in Ho Chi Minh City hospitality procurement, driven by TISI certification tier and wall thickness specification grade. Three-tier pricing structure across premium certified, standard commercial, and economy unbranded levels segments the market by compliance burden and after-sales warranty bundling. Cost compression in economy aluminum segments is intensifying because supermarket private-label consolidation in Metro Manila and Ho Chi Minh City removes brand premium capture. Filipino household buyers exhibit highest price sensitivity, while Bangkok hotel procurement teams prioritize specification compliance over unit cost.
Supply Chain Analysis
Tariff exposure between Indonesian nickel ore exports and Thai stainless steel fabrication dominates supply chain risk planning for regional cookware manufacturers. Raw material sourcing concentrates in Indonesian nickel laterite, Chinese ferrochrome, and Australian alumina bauxite feeds. Thai Rayong-Chonburi industrial zones and Vietnamese Hai Phong northern corridors anchor forging and coating capacity, with sol-gel ceramic application expertise creating single-source vulnerability for Indonesian and Philippine assemblers. Distribution runs through Jakarta and Bangkok wholesale hospitality channels for institutional volumes, while supermarket private-label programs and Lazada-Shopee storefronts capture household demand in Vietnam and the Philippines.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
ASEAN cookware markets are experiencing high-growth disruption as ceramic coating technology displaces PTFE surfaces and Thailand's BOI incentives trigger capacity relocation from Northeast Asian suppliers. The intersection of regulatory harmonization and coating expertise concentration is reshaping competitive entry barriers across Southeast Asian markets.
For Market Incumbents: Build certification moats around TISI heavy metal compliance and ASEAN harmonized labeling standards to defend against informal Vietnamese and Indonesian producers. Anchor procurement relationships with Ho Chi Minh City hospitality developers through specification engineering and volume commitment structures. Expand captive forging capacity in Rayong industrial zones to offset nickel price volatility exposure. For New Entrants and Emerging Players: Build out distribution partnerships in Mindanao and Visayas island clusters where organized retail penetration remains below Luzon levels and logistics gaps constrain incumbent reach. Target Philippine archipelago white space through regional distributor alliances rather than direct retail investment. Penetrate via induction-compatible aluminum forging for Malaysian glass-ceramic cooktop replacement cycles. For Investors and Strategic Acquirers: Carve-out targets emerge from conglomerate-held cookware divisions lacking vertical integration depth or ceramic coating capability. Five-to-ten year viability favors BOI-incentivized Thai fabricators with captive forging and sol-gel application expertise over import-dependent assemblers. Monitor nickel LME contract volatility as inflection indicator for margin compression timing across stainless steel-dependent players.| Strategic Initiative | Industry Significance |
|---|---|
| Ceramic Coating Technology Licensing | Sol-gel formulation access separates premium-positioned Thai and Vietnamese manufacturers from PTFE-dependent competitors. |
| Backward Integration into Forging | Captive Rayong and Chonburi forging operations insulate Meyer Thailand and peers from nickel price volatility transmission. |
| Induction-Compatible Base Lamination | Ferromagnetic aluminum forging opens Malaysian and Singaporean household penetration for glass-ceramic cooktop installations. |
| Private-Label Supply Agreements | Central Retail Vietnam and SM Retail Philippines consolidation creates volume concentration for compliant manufacturers. |
| Multi-Jurisdiction Certification Investment | Simultaneous TISI, SNI, and STAMEQ compliance accelerates product launch cycles for pan-regional cookware lines. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with Thai stainless steel forging plant managers, Vietnamese hospitality procurement directors, Indonesian distributor network heads, and Filipino supermarket category buyers. Secondary validation drew from Thailand's Industrial Standards Institute regulatory filings, Vietnam's Ministry of Science and Technology harmonization announcements, Indonesian National Standardization Agency import disclosure records, and ASEAN trade flow databases. Bottom-up volume modeling across product type, material grade, distribution channel, and end-user segments was triangulated against top-down regional market sizing.
Calibration against historical volume trajectories and input cost elasticity patterns anchored the analytical framework across the projection horizon. Segmentation dimensions modeled include cookware format, alloy composition, wall thickness specification, distribution channel type, and end-user procurement intensity. CAGRs were derived from regression-based trend extrapolation adjusted for regulatory implementation timelines and technology substitution curves. Nickel LME price volatility coefficients and ceramic coating adoption rates served as industry-specific forecast inputs.
The forecast holds incumbent behavior within observed patterns; aggressive capacity expansion by Chinese stainless steel processors or accelerated PTFE regulatory bans would shift outcomes beyond modeled ranges. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Household Items
Gas Hobs Market
Household Items
Dosage Spoon Market
Household Items
Russia Residential Water Heaters Market
Household Items
Coin-Operated Laundries Market
Household Items
Electric Clothes Drying Hanger Market
Household Items
Book Light Market
Household Items
Toilet Paper Market
Household Items
Moving Supplies Market
Household Items
Global Buddhist Supplies Market
Household Items
Middle East and Africa B2B Air Care Market
Household Items
Smart Shower Market
Household Items
US Soap Dispenser Market
Household Items
Barbeque Grill Market
Household Items
Drinkware Market
Household Items
Global Rimless Toilets Market
Household Items
Wax Removal Aids Market