
 Paper Towel Dispenser Market | 2026-2036
Paper Towel Dispenser Market Size, Share, and Industry Trends Forecast 2026-2036
Paper Towel Dispenser Market Outlook
The EU Green Deal is realigning procurement criteria for commercial hygiene fixtures across European member states. Kimberly-Clark leverages its North American tissue and dispenser integration to control channel economics in high-traffic facilities. Essity anchors European market development through specialized stainless steel and touchless automatic lines designed for healthcare and foodservice compliance.
A paper towel dispenser is a mechanical or electromechanical fixture engineered to store, dispense, and control the release of paper towels through manual lever action, sensor-activated motors, or gravity-fed mechanisms, typically constructed from ABS plastic, 304-grade stainless steel, or aluminum extrusions with wall-mounted or countertop configurations. Its primary commercial purpose centers on reducing cross-contamination risk, controlling consumption volume, and ensuring compliance with restroom accessibility standards in public and institutional environments. Automatic and wall-mounted product types command premium positioning in healthcare and airport segments where touchless operation and space optimization drive specification decisions. Stainless steel material segments sustain higher margin pools due to durability requirements in food processing and heavy-use commercial settings, while plastic variants dominate volume in educational and light commercial applications.
The EPA WaterSense program and FDA Food Code sanitation standards shape product design requirements for water-adjacent and foodservice installations in the United States. REACH compliance and CE marking obligations govern chemical content and electrical safety for automatic dispensers distributed across European Union member states. Stakeholders must monitor evolving accessibility mandates from the Department of Justice and emerging state-level procurement preferences for recycled content to anticipate specification shifts in institutional buying channels.
Market Dynamics
Touchless sensor technology and stainless steel specification mandates are compressing replacement cycles across commercial restroom infrastructure, forcing manufacturers to realign production toward electromechanical platforms and antimicrobial-grade materials.
Growth Catalysts
- Healthcare Infection Control:Hospital-acquired infection protocols in the United States and Germany mandate sensor-activated dispensers in patient-facing zones, accelerating specification of automatic units over manual alternatives.
- ADA Compliance Deadlines:The Department of Justice accessibility enforcement in American airports and educational campuses drives systematic retrofit programs for lever-action and reach-range compliant fixtures.
- Recycled Material Mandates:EU Green Deal procurement criteria require minimum recycled content thresholds in public sector tenders, redirecting polymer sourcing toward post-consumer ABS and stainless steel feedstock.
Market Restraints
- Stainless Steel Input Volatility:Nickel and chromium price swings in commodity markets compress margin stability for European manufacturers specializing in foodservice-grade 304-grade dispenser housings.
- Electronics Supply Concentration:Infrared sensor modules and motor assemblies concentrate in East Asian component ecosystems, exposing automatic dispenser producers to single-source vulnerability.
- Air Dryer Substitution:High-velocity hand dryer installations in Scandinavian and British commercial buildings displace paper towel specification in sustainability-focused facility management contracts.
Strategic Opportunities
- Indian Infrastructure Buildout:Metro rail expansion and airport privatization in Mumbai, Delhi, and Bangalore create specification windows for touchless dispenser platforms in high-traffic transit hubs.
- IoT Convergence:Integration of consumption sensors with facility management software enables predictive restocking and usage analytics, opening recurring revenue streams for dispenser-as-a-service models.
- Bioplastic Material Innovation:Polylactic acid and hemp-fiber composite development offers pathway to meet EU single-use plastic directives while differentiating product lines in environmentally scored tenders.
Industry Challenges
- Electromechanical Skill Gap:Shortage of firmware engineers and sensor calibration technicians delays automatic dispenser product development cycles and field service responsiveness.
- Multi-Certification Overlap:Simultaneous pursuit of CE marking, FCC Part 15 compliance, and WaterSense certification extends time-to-market for platforms targeting transatlantic distribution.
- Legacy Manual Stock Rationalization:Distributor inventory of gravity-fed and lever-action units creates channel conflict during manufacturer-led transitions to sensor-activated product generations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Paper Towel Dispenser Market |
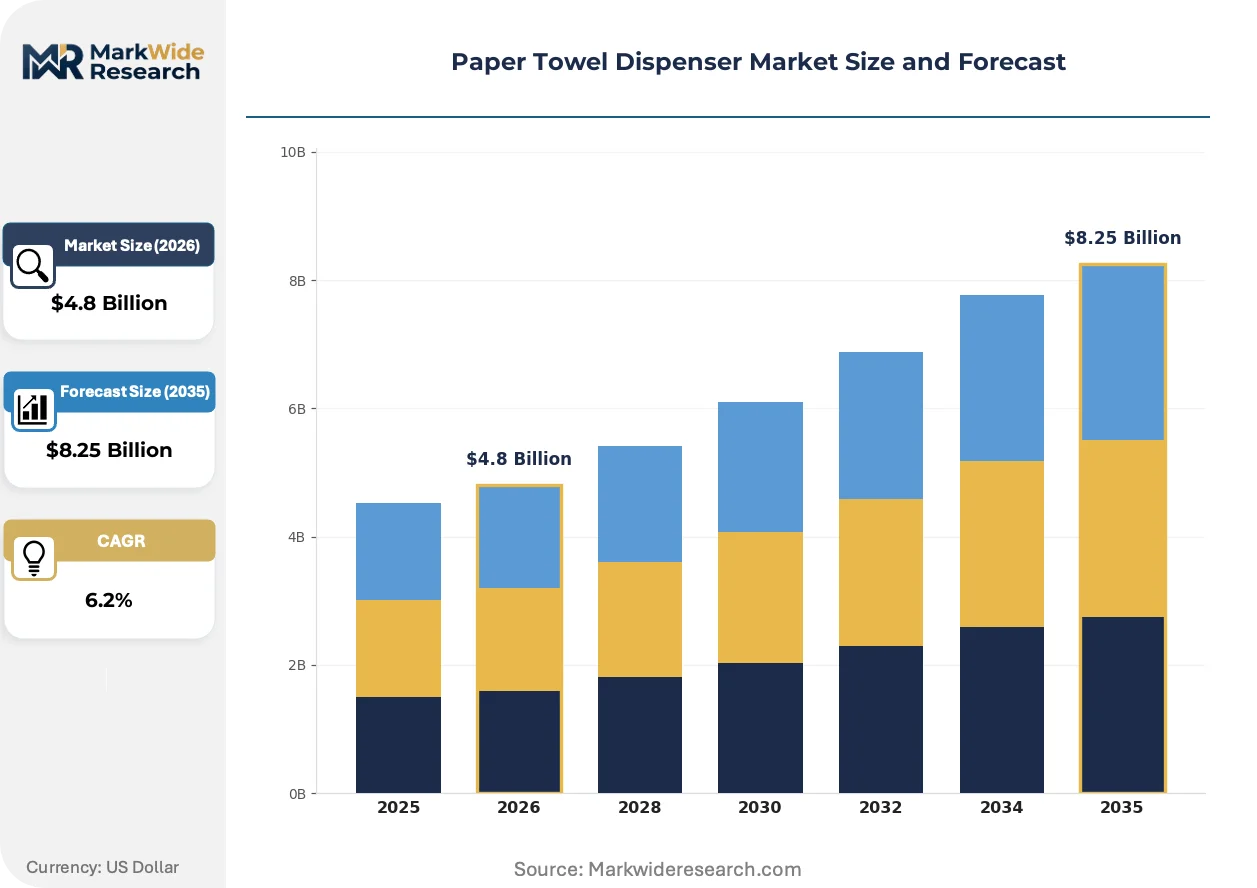
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.25 Billion |
| CAGR (2026 – 2036) | 6.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Manual, Automatic, Wall-Mounted, Countertop Material: Plastic, Stainless Steel, Aluminum, Wood End User: Commercial, Residential, Healthcare, Educational Distribution Channel: Online, Retail, Wholesale, Direct Sales |
| Companies Covered | Bobrick, Rentokil Initial, Kimberly-Clark, Carlisle (San Jamar), Hagleitner, Essity, Bradley, American Specialties (ASI), Georgia-Pacific, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Paper Towel Dispenser Market Strategic Shifts
Electromechanical platform evolution and material science advancement are restructuring competitive advantage around modularity, compliance automation, and service-integrated revenue models rather than hardware shipment volume alone.
Sensor-activated dispensing systems are modularizing around swappable motor cartridges and standardized infrared detection arrays. Healthcare facilities in the United States and Germany specify these platforms for rapid field repair and protocol upgrade without full fixture replacement. The architecture compresses total cost of ownership calculations and locks in long-term supplier relationships through proprietary cartridge formats.
REACH chemical content restrictions and impending CSRD supply chain disclosure requirements are forcing reformulation of ABS plastic additives and surface coatings across European supply chains. Manufacturers serving German and French hospital networks now document full material provenance to preempt tender disqualification. The regulatory burden favors integrated producers with captive polymer compounding capabilities over assembly-only competitors.
Facility management outsourcing consolidation is compressing direct purchasing relationships between end-users and dispenser manufacturers. Large contract service providers in American airport and educational verticals now specify platforms through centralized procurement frameworks, displacing fragmented distributor relationships. This channel concentration rewards manufacturers with dedicated national account teams and configurable fleet management software integration.
Paper Towel Dispenser Market Segmentation
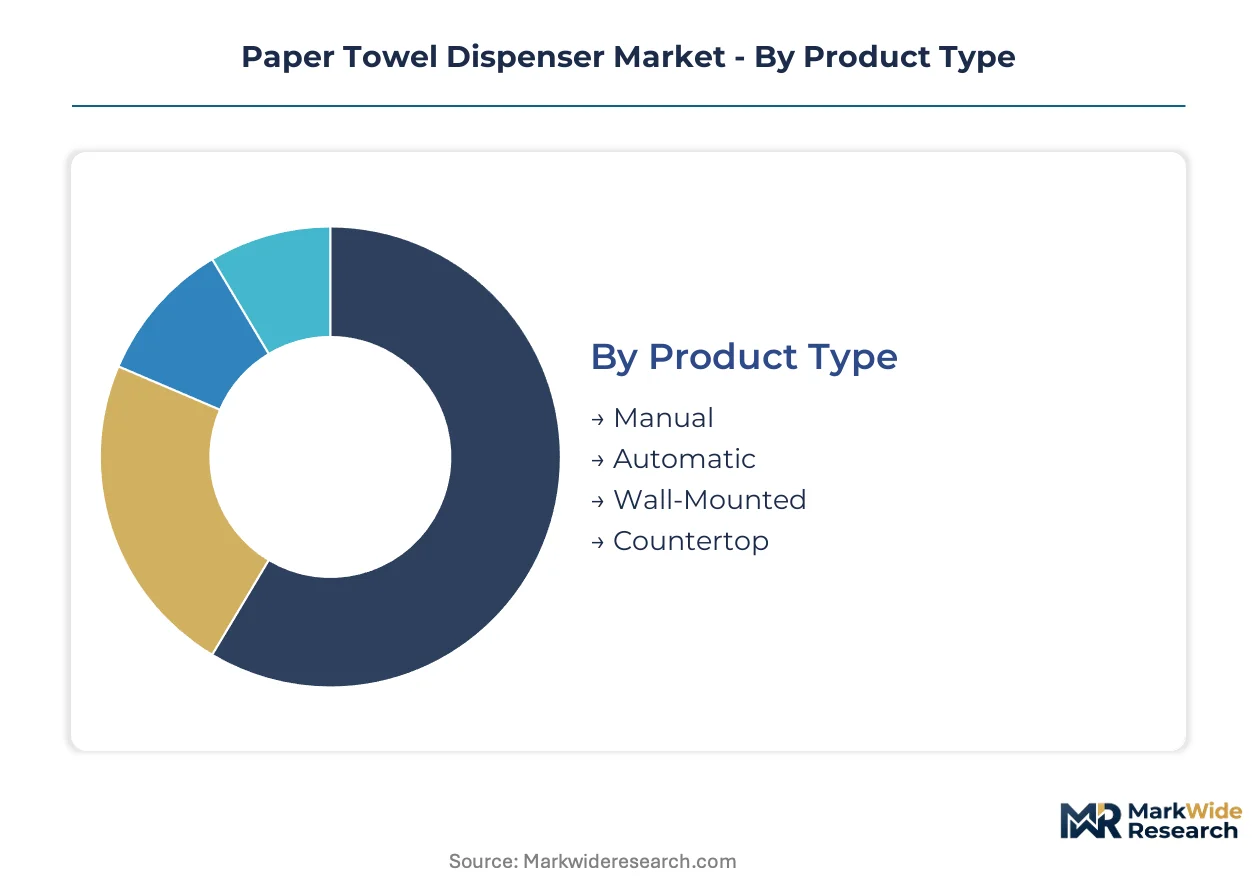
Segmentation in paper towel dispensers reveals how specification power concentrates in high-traffic institutional buyers rather than fragmented consumer channels. Material and activation technology choices directly determine compliance eligibility for healthcare and foodservice procurement frameworks.
Product Type:
Supply concentration in electromechanical components favors manufacturers with captive sensor calibration and motor assembly capabilities over pure mechanical fabricators.
- Automatic:Infrared sensor arrays and brushless motor drives enable touchless activation protocols mandated by hospital-acquired infection prevention standards in the United States and Germany. Demand concentrates in airport terminals and healthcare campuses where ADA reach-range compliance and hygiene specifications converge.
- Wall-Mounted:Space-optimized housings with recessed or surface-mount configurations dominate restroom renovation cycles in educational facilities and commercial office towers. Specification velocity accelerates where building codes enforce maximum fixture protrusion limits in circulation corridors.
- Manual:Lever-action and gravity-fed mechanisms retain volume in cost-constrained educational and light commercial installations where electromechanical maintenance infrastructure is absent.
- Countertop:Freestanding units with weighted bases serve foodservice prep areas and temporary event infrastructure where wall penetration is prohibited or impractical.
Today's leader: Wall-Mounted. Tomorrow's challenger: Automatic.
Material:
Cost tier stratification separates specification-grade stainless steel from commodity polymer alternatives across institutional procurement channels.
- Stainless Steel:304-grade austenitic formulations with brushed or polished finishes withstand corrosive cleaning regimens in food processing plants and healthcare sterilization zones. European hospital networks and North American airport concessionaires specify these housings for durability under continuous sanitization cycles.
- Plastic:ABS and polypropylene injection-molded housings dominate volume shipments through retail and wholesale channels serving educational and municipal facilities. REACH-compliant additive packages and post-consumer recycled content thresholds increasingly govern EU public sector tender eligibility.
- Aluminum:Extruded and die-cast configurations balance weight reduction with corrosion resistance in transportation and outdoor recreational facility installations.
- Wood:Solid and veneer-faced options serve hospitality and premium residential segments where aesthetic integration with interior finishes overrides hygiene-critical specifications.
Stainless steel commands margin leadership. Plastic retains volume dominance.
End User:
Application-specific compliance requirements fragment procurement authority across facility management, infection control, and accessibility coordination functions.
- Healthcare:Acute care hospitals and outpatient clinics specify touchless automatic platforms with antimicrobial surface treatments to satisfy Joint Commission and CDC hand hygiene protocol audits. Sensor-activated dispensing reduces cross-contamination vectors in patient-facing zones.
- Commercial:Corporate campuses, retail chains, and hospitality properties drive replacement cycles through restroom renovation programs and sustainability scorecard commitments. Centralized procurement by national facility management firms compresses vendor selection timelines.
- Educational:K-12 districts and university systems balance vandal resistance with ADA compliance in high-abuse environments, favoring robust manual and semi-automatic platforms with locked housing designs.
- Residential:Single-family and multi-unit housing markets absorb countertop and compact wall-mounted units through home improvement retail and e-commerce channels, with limited specification complexity.
Healthcare sets technical standards. Commercial scales procurement volume.
Distribution Channel:
Customer type concentration in institutional buyers reshapes channel economics away from fragmented retail toward direct national account relationships.
- Direct Sales:Manufacturer field organizations engage airport authorities, hospital procurement consortia, and educational purchasing cooperatives with configurable fleet management platforms and service-integrated contracts. Channel control enables specification lock-in through proprietary consumable compatibility.
- Wholesale:Janitorial and sanitation supply distributors serve mid-market commercial and municipal accounts with inventory availability and local service responsiveness. Regional warehousing networks compete on fill rates and emergency replacement capability.
- Online:E-commerce platforms capture residential and small commercial demand with standardized SKU availability and price transparency, though specification complexity limits penetration in healthcare and large institutional verticals.
- Retail:Big-box and specialty home improvement channels move countertop and residential-grade wall-mounted units through physical showroom presence and immediate fulfillment.
Direct sales capture specification value. Wholesale retains geographic coverage.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The paper towel dispenser industry traces its commercial origins to mid-20th century American restroom fixture manufacturing, with Wisconsin and Ohio emerging as early centers of metalworking and institutional supply production. European stainless steel fabrication developed parallel expertise through German and Swiss precision engineering traditions.
United States
Airport terminal renovations and hospital infection-control retrofits drive specification velocity for touchless automatic platforms. The Department of Justice enforces ADA reach-range compliance deadlines across educational campuses and federal facilities. Chicago and Dallas-Fort Worth airport authorities deploy centralized procurement frameworks for restroom infrastructure upgrades.
Germany
Healthcare networks mandate sensor-activated dispensers under hospital-acquired infection protocols aligned with ECDC guidelines. REACH chemical content restrictions and impending CSRD supply chain disclosures govern ABS plastic formulation. Stuttgart and Munich industrial clusters specialize in 304-grade stainless steel fabrication for foodservice-grade housings.
China
Metro rail expansion in Shanghai, Beijing, and Guangzhou creates specification windows for high-traffic touchless platforms. GB standards and MIIT quality certification requirements shape electromechanical component sourcing. Shenzhen and Dongguan electronics ecosystems concentrate infrared sensor module and brushless motor assembly capacity.
India
Airport privatization in Mumbai, Delhi, and Bangalore accelerates restroom modernization in transit hubs. BIS certification and FSSAI foodservice sanitation standards influence material selection for commercial installations. Gujarat and Maharashtra manufacturing corridors develop domestic stainless steel forming and polymer compounding capabilities.
United Kingdom
High-velocity hand dryer substitution in sustainability-focused facility contracts displaces paper towel specification in London and Manchester commercial buildings. CE marking obligations persist for Northern Ireland distribution channels post-Brexit. Birmingham metalworking districts sustain legacy lever-action and gravity-fed mechanical fabrication for cost-constrained municipal accounts.
Paper Towel Dispenser Market Competitive Environment
Premium-margin players sit above commodity-margin players across material grade and activation technology tiers. The vendor base stratifies between integrated tissue-dispenser platforms, specialized stainless steel fabricators, and electromechanical component assemblers. Three archetypes dominate: multinational hygiene conglomerates with captive consumable ecosystems, regional metalworking specialists with healthcare certification depth, and Asian electronics integrators leveraging sensor module cost advantages. Competitive moves concentrate on M&A-driven portfolio diversification and backward integration into polymer compounding and motor assembly.
Within the multinational hygiene tier, Kimberly-Clark and Essity occupy positions defined by North American tissue-dispenser integration and European stainless steel specialization respectively. Bobrick exemplifies the precision metalworking archetype through its century-long institutional fixture heritage. Hagleitner anchors the Austrian-German regional specialist cluster with concentrated healthcare and foodservice compliance expertise. These named entities represent structural positioning rather than exhaustive market enumeration.
| Leading Market Players |
|---|
| Bobrick |
| Rentokil Initial |
| Kimberly-Clark |
| Carlisle (San Jamar) |
| Hagleitner |
| Essity |
| Bradley |
| American Specialties (ASI) |
| Georgia-Pacific |
| Others |
Value Chain & Pricing Dynamics
Captive integration of sensor module assembly and stainless steel fabrication anchors both supply security and margin protection for automatic dispenser platforms serving healthcare and airport verticals. Manufacturers with in-house motor calibration capabilities and 304-grade housing production command pricing power against assembly-only competitors exposed to nickel price volatility and single-source electronics dependencies.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels separates specification-grade stainless steel automatic units from ABS plastic manual alternatives and entry-level countertop configurations. Certification depth under FDA Food Code and CE marking protocols drives price differentiation alongside volume scale and after-sales service bundling. Cost compression in plastic manual tiers is intensifying because of recycled content mandate compliance burdens and distributor inventory liquidation. Educational procurement cooperatives exhibit highest price sensitivity; hospital infection control committees prioritize total cost of ownership over unit price.
Supply Chain Analysis
Direct-to-institutional channels handle specification-grade demand from airport authorities and hospital procurement consortia, while wholesale distributors serve cost-constrained municipal and educational accounts. Manufacturing concentrates in China for infrared sensor modules and brushless motor assemblies, Germany for precision stainless steel fabrication, and the United States for electromechanical platform integration. Raw material flows draw from nickel-chromium alloy feedstock, post-consumer ABS polymer streams, and semiconductor-grade infrared detector substrates. Single-source vulnerability in East Asian electronics ecosystems exposes automatic dispenser producers to tariff exposure and logistics chokepoint risk.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The paper towel dispenser market functions as a stable compounder anchored by mandatory infection control protocol upgrades across healthcare infrastructure worldwide. Replacement cycle compression from touchless technology mandates sustains predictable demand visibility.
For Market Incumbents: Lock in long-term supplier relationships through proprietary cartridge formats for sensor-activated platforms, preventing field repair migration to third-party service providers. Deepen backward integration into polymer compounding to preempt REACH compliance disqualification in European hospital tenders. High-velocity hand dryer substitution in Scandinavian markets threatens paper towel specification share.
For New Entrants and Emerging Players: Regional airport authorities in Indian metro rail and privatized airport hubs represent underserved buyer archetypes with specification windows opening before incumbent national account teams consolidate relationships. Target touchless platform demand in Mumbai, Delhi, and Bangalore transit infrastructure with BIS-certified electromechanical assemblies. Pursue facility management outsourcing consolidation as direct entry channel.
For Investors and Strategic Acquirers: Roll-up economics work for regional stainless steel fabricators with healthcare certification depth because specification authority fragments across infection control, accessibility compliance, and procurement coordination functions. Five-to-ten year viability rests on IoT convergence and dispenser-as-a-service recurring revenue capture. Monitor infrared sensor module supply concentration as inflection indicator for margin compression risk.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Polymer Compounding | REACH compliance and CSRD disclosure requirements favor captive additive formulation capabilities in EU supply chains. |
| IoT Platform Integration | Consumption sensor deployment with facility management software enables predictive restocking revenue streams. |
| Bioplastic Material Transition | Polylactic acid and hemp-fiber composite development addresses EU single-use plastic directive compliance. |
| Healthcare Certification Investment | Joint Commission and CDC protocol alignment locks in specification for acute care hospital networks. |
| Regional Manufacturing Footprint | Gujarat and Maharashtra corridor development reduces import dependency for Indian airport privatization projects. |
Study Parameters
Direct dialogue with facility management directors, hospital procurement committee members, airport authority engineering staff, and janitorial supply distributors grounded qualitative assessment in operational decision-making realities. Secondary validation drew from EPA WaterSense program documentation, FDA Food Code sanitation standards, EU Green Deal procurement criteria, and customs trade data for ABS polymer and stainless steel feedstock flows. Bottom-up segment sizing triangulated against top-down macroeconomic indicators across the analysis window.
Segmentation-level projections spanning activation technology, material grade, end-use vertical, and distribution channel structure fed into analytical framework outputs across the modeling period. CAGRs derived from replacement cycle velocity, regulatory mandate enforcement timelines, and infrastructure investment pipeline tracking. Electromechanical component cost curves and recycled content threshold evolution served as industry-specific forecast inputs.
Underlying measurement precision varies by segment; automatic touchless platforms in healthcare settings carry tighter precision than fragmented residential countertop demand. Forecasts reflect assumptions regarding ADA compliance enforcement intensity, nickel price volatility, and hand dryer substitution rates. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Household Items
Bladeless Neck Fan Market
Household Items
Mosquito Repellent Candles Market
Household Items
Turkey Cookware Market
Household Items
Coin-Operated Laundries Market
Household Items
Desktop Air Purifier Market
Household Items
Electric Brooms Market
Household Items
Indoor Humidifier Market
Household Items
Deodorizer Bag Market
Household Items
Household Scales Market
Household Items
United States Barbeque Grill Market
Household Items
United Kingdom Air Purifier Market
Household Items
Washing Capsules Market
Household Items
Electric Blankets Market
Household Items
Global Aluminum Cookware Market
Household Items
Global Refrigerator Water Filters Market
Household Items
Kuwait Gas Hobs Market