
 Vacuum Cleaner Market | 2026-2036
Vacuum Cleaner Market Size, Share, and Industry Trends Forecast 2026-2036
Vacuum Cleaner Market Intelligence
HEPA-grade filtration and self-emptying dock specifications is reorganizing the premium tier of the vacuum cleaner industry. Dyson sustains its position through cyclone airflow engineering and direct-to-consumer channel control. iRobot dominates autonomous navigation patents and smart home ecosystem partnerships. SharkNinja competes aggressively on price-performance ratios in the cordless stick segment.
A vacuum cleaner is an electromechanical appliance that generates negative pressure via a motor-driven fan to extract particulate matter from surfaces, typically operating at suction pressures between 15 and 25 kPa for household units. Its primary commercial purpose spans residential debris removal, industrial dust extraction, and controlled-environment sanitization in healthcare and food-processing facilities. Robotic units with LiDAR mapping and Wi-Fi connectivity represent the fastest-expanding product category, while corded upright models retain the largest installed base in North American households. Cordless lithium-ion variants are capturing margin pools in European and Asian urban markets where storage constraints favor compact designs.
The EPA regulates vacuum cleaner energy consumption and particulate emissions under appliance efficiency frameworks, while the EU Ecodesign Directive and REACH constrain motor wattage and material composition in European markets. China's GB standards and SAMR certification requirements shape import access and domestic manufacturing specifications for units sold through e-commerce channels. Stakeholders must monitor how tightening energy efficiency thresholds and right-to-repair mandates alter product architecture, component sourcing, and warranty cost structures across their target geographies.
Market Dynamics
The vacuum cleaner market is reconfiguring around motor efficiency mandates and the shift from corded to battery-powered architectures, compressing traditional supply chains while opening margin pools in smart home integration and filtration certification.
Growth Catalysts
- EU Ecodesign Directive:Tightening motor wattage caps are forcing manufacturers to redesign airflow systems, creating competitive advantage for firms with advanced aerodynamic engineering capabilities.
- Suburban residential replacement cycles:Homeowners in the United States, Germany, and China are retiring corded upright units after shortened 5-7 year lifespans, accelerating demand for cordless lithium-ion and robotic alternatives.
- HEPA filtration mandates in healthcare:Controlled-environment sanitization requirements in hospitals and food-processing facilities are pulling industrial-grade extraction systems into premium residential tiers.
Market Restraints
- Lithium-ion cell supply concentration:Battery pack sourcing depends on concentrated Asian cell manufacturers, exposing cordless vacuum margins to raw material volatility and logistics bottlenecks.
- REACH material constraints:The EU's chemical registration framework restricts certain plastics and coatings in motor housings, forcing costly reformulation of legacy product lines.
- Technical limitation in autonomous navigation:Robotic units still struggle with threshold transitions and low-ambient-light mapping, constraining addressable floor plans in multi-level dwellings.
Strategic Opportunities
- India's underpenetrated robotic segment:Urban middle-class households in Mumbai and Bangalore show rising appetite for Wi-Fi-enabled cleaning automation, with local assembly partnerships reducing import duties.
- Right-to-repair mandates in France and Germany:National legislation requiring spare part availability and repair documentation is creating aftermarket service revenue streams and brand loyalty mechanisms.
- LiDAR-to-camera sensor convergence:Cost declines in visual SLAM algorithms are enabling mid-tier robotic vacuums to offer mapping precision previously confined to premium price bands.
Industry Challenges
- Embedded software talent scarcity:Firmware engineering for autonomous navigation and smart home protocol integration commands premium compensation, stretching R&D budgets at mid-tier manufacturers.
- SAMR certification timelines in China:Extended approval cycles for wireless-connected appliances delay product launches and compress selling seasons for imported brands.
- Legacy corded inventory write-downs:Distributors holding pre-2023 upright stock face margin erosion as consumer preference shifts decisively toward cordless architectures.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Vacuum Cleaner Market |
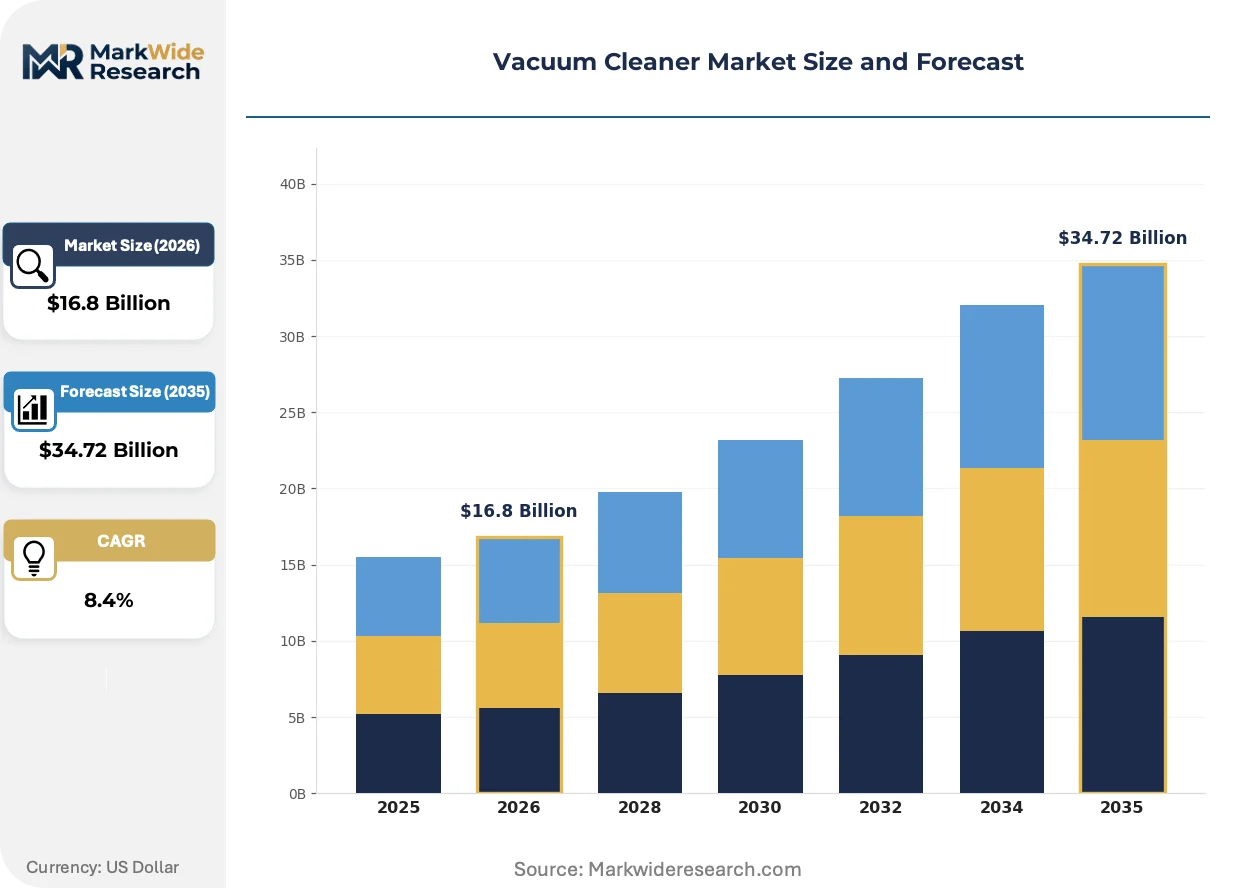
| Market Size in 2026 | $16.8 Billion |
| Market Size in 2035 | $34.72 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Upright, Canister, Robotic, Handheld Power Source: Corded, Cordless, Battery, Electric Application: Home, Commercial, Industrial, Automotive Connectivity: Smart, Wi-Fi Enabled, Bluetooth, Wired |
| Companies Covered | iRobot, LG Electronics, Dyson, Electrolux, Miele, Bissell, Samsung, Philips, SharkNinja, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Vacuum Cleaner Market Strategic Shifts & Innovations
Active innovation clusters are compressing product lifecycles and redrawing competitive boundaries through sensor miniaturization, regulatory-driven material substitution, and direct-to-consumer channel capture.
Autonomous navigation stacks are decomposing the premium tier's exclusivity over mapping-enabled cleaning. Visual SLAM and time-of-flight sensors, once confined to flagship robotic units, now penetrate mid-range SKUs priced for mass-market adoption. This technology diffusion is collapsing the historical three-tier price architecture into a compressed premium-mid band, forcing incumbents to defend margin through software subscription services rather than hardware differentiation alone.
REACH and the EU Ecodesign Directive are accelerating motor redesign cycles across European manufacturing footprints. The framework's material restrictions and efficiency minimums render legacy universal-motor platforms economically unviable, compelling suppliers to retool for brushless DC architectures. Cordless stick and handheld categories bear the highest compliance burden, with German and Italian OEMs leading the transition to rare-earth-reduced magnet designs.
Direct-to-consumer channel capture is displacing traditional retail distribution in North American and Western European markets. SharkNinja and Dyson's owned-commerce platforms now handle majority transaction volume, extracting margin previously captured by big-box intermediaries. This shift concentrates customer data ownership with manufacturers, enabling predictive replacement marketing and accessory attach-rate optimization in suburban United States households.
Vacuum Cleaner Market Segmentation
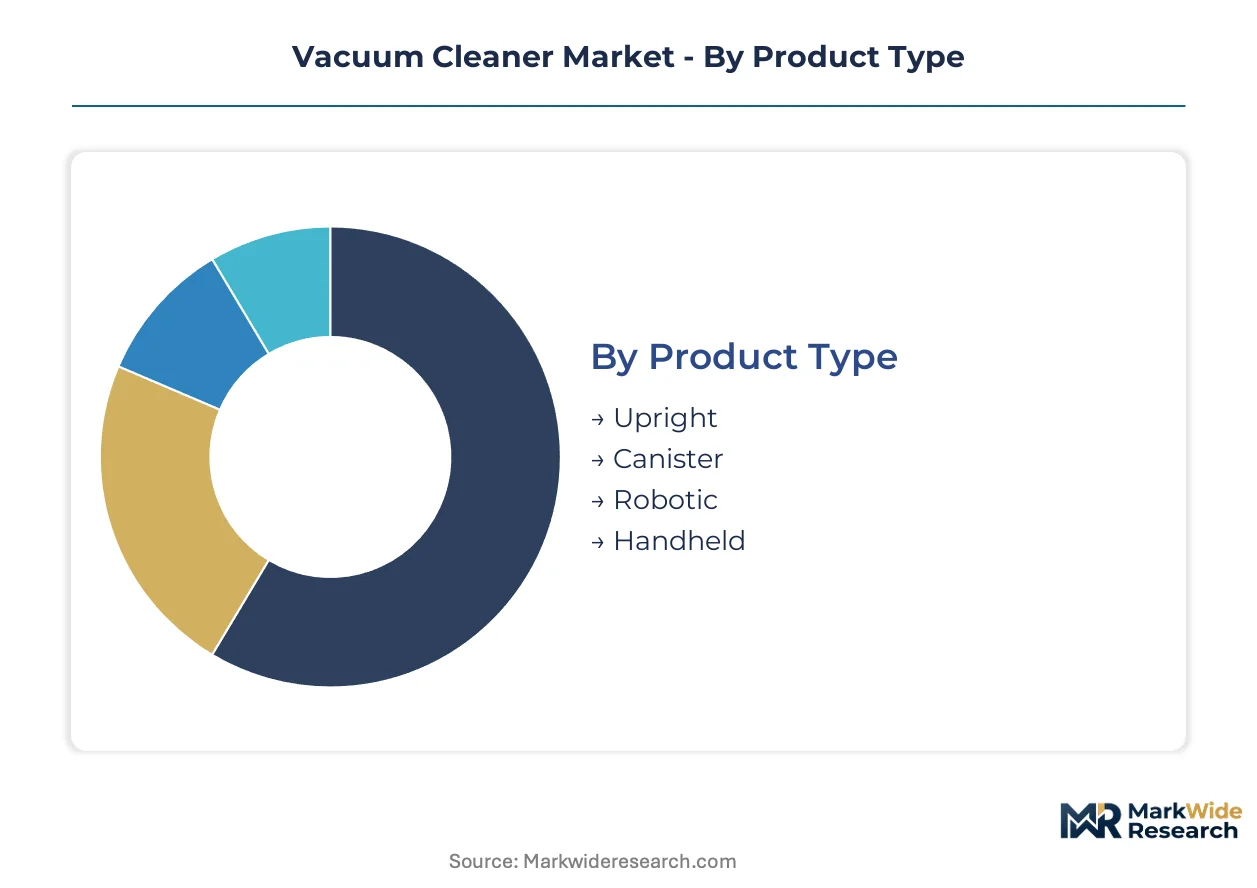
Vacuum cleaner manufacturers engineer product architectures around distinct use environments and power constraints. Segment boundaries determine component sourcing, certification pathways, and channel strategy for competing firms.
Product Type:
Margin pools concentrate in robotic and cordless stick configurations where sensor miniaturization and battery pack integration command premium positioning.
- Upright:Motor-fan assemblies mounted vertically above cleaning heads dominate North American residential installed base. Demand concentrates in suburban United States households with wall-to-wall carpeting, though replacement cycles are compressing as cordless alternatives capture attention.
- Robotic:Autonomous units integrate LiDAR mapping, visual SLAM, and self-emptying dock systems. Germany, China, and United States urban households are driving specification upgrades toward HEPA-grade filtration and multi-floor mapping capability.
- Canister:Separate motor units connected to wheeled cleaning heads via flexible hoses retain share in European and Asian markets with hard flooring prevalence.
- Handheld:Compact lithium-ion units target automotive interiors and quick-clean scenarios in space-constrained Japanese and South Korean apartments.
Upright configurations hold installed capacity. Robotic units are rotating up the share rankings.
Power Source:
Volume distribution tilts toward cordless architectures as lithium-ion energy density improvements close performance gaps with corded alternatives.
- Cordless:Removable battery packs enable stick and handheld form factors without tether constraints. European Union Ecodesign Directive efficiency minimums are accelerating brushless DC motor adoption across German and Italian manufacturing footprints.
- Corded:Continuous AC power sustains maximum suction for deep-cleaning applications in United States and Canadian households with pet ownership and allergy concerns.
- Battery:Integrated cell systems in robotic units depend on concentrated Asian cell manufacturer supply, exposing margins to cobalt and lithium carbonate volatility.
- Electric:Industrial extraction systems in food-processing and healthcare facilities require three-phase power connections and certified grounding.
Corded systems retain volume leadership in North America. Cordless configurations are gaining share fastest across European and Asian urban markets.
Application:
End-use specifications diverge sharply between residential convenience priorities and industrial compliance mandates.
- Home:Residential units prioritize noise reduction, storage footprint, and smart home protocol compatibility. Suburban replacement cycles in United States, Germany, and China are shortening toward five-to-seven year horizons.
- Commercial:Hospitality and office cleaning contracts demand runtime durability and rapid filter serviceability. EPA and OSHA particulate exposure limits shape procurement specifications in United States facility management.
- Industrial:Heavy-duty extraction systems handle metal shavings, chemical dust, and combustible particulate in manufacturing environments. REACH material restrictions constrain housing plastics and motor coatings in European deployments.
- Automotive:Detailing shops and assembly plants require specialized attachments for crevice extraction and upholstery conditioning.
Home applications anchor volume. Industrial specifications are climbing the technology ladder fastest as HEPA mandates diffuse from healthcare into premium tiers.
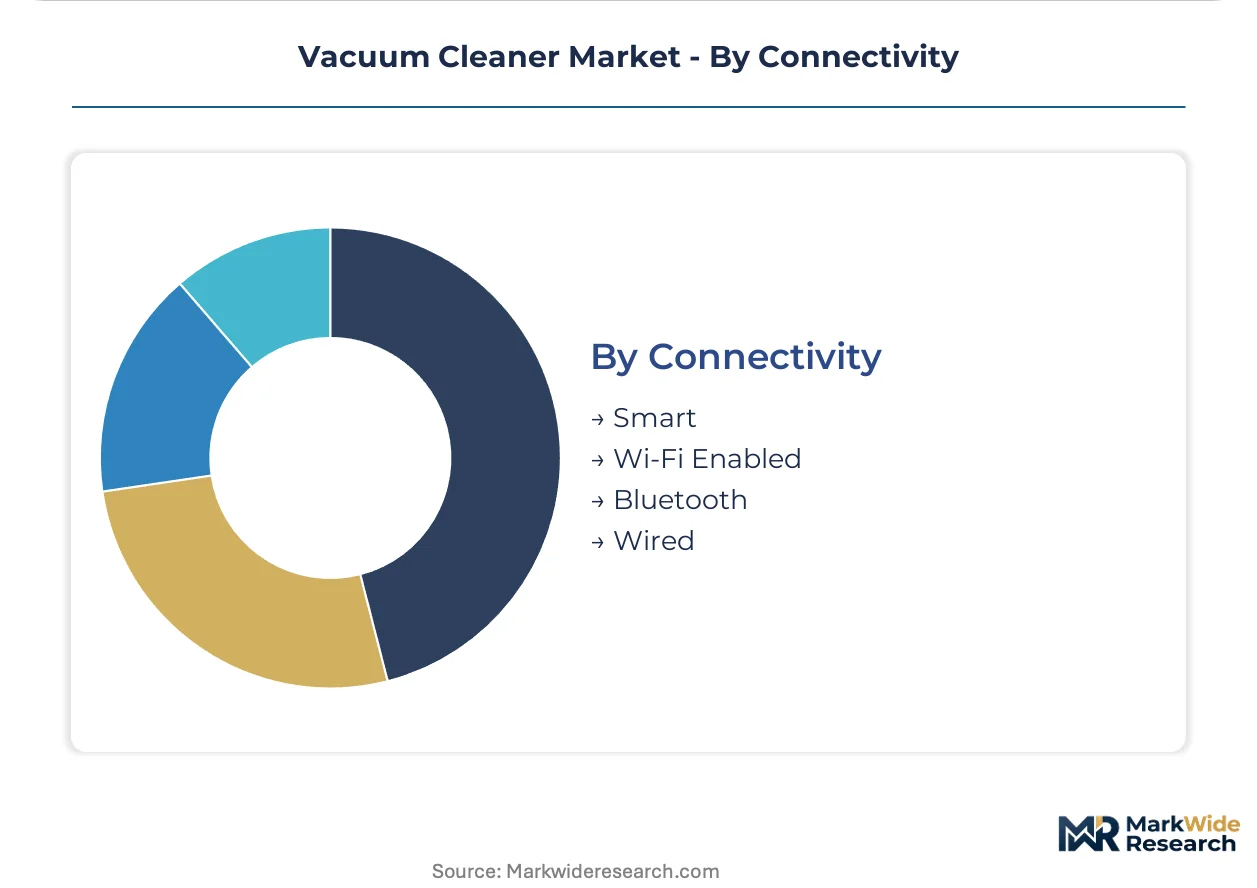
Connectivity:
Smart feature penetration separates price tiers and determines aftermarket revenue potential through subscription services and accessory ecosystems.
- Smart:App-controlled scheduling, zone mapping, and usage analytics command premium positioning in United States and German markets. Firmware engineering talent scarcity stretches R&D budgets for mid-tier manufacturers attempting feature parity.
- Wi-Fi Enabled:Cloud-connected units integrate with Amazon Alexa and Google Home ecosystems, enabling voice-activated cleaning routines in tech-forward households.
- Bluetooth:Local device pairing supports basic remote control without internet dependency, appealing to privacy-conscious European consumers.
- Wired:Non-connected units dominate entry-level price bands and industrial deployments where network security policies prohibit IoT devices.
Wired connectivity retains the largest installed base. Smart configurations are expanding most quickly as direct-to-consumer channels concentrate data ownership with manufacturers.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Brushless DC motor manufacturing clusters in China, Germany, and South Korea supply the cordless and robotic vacuum architectures reshaping household cleaning worldwide. Component sourcing for lithium-ion battery packs and precision sensors concentrates in East Asian electronics corridors, while European regulatory frameworks drive efficiency certification requirements.
United States
Suburban households in Texas and Florida are retiring corded upright units on compressed five-to-seven year cycles. The EPA's appliance efficiency frameworks constrain motor wattage and particulate emissions for units sold through e-commerce channels. The Dallas-Fort Worth metroplex anchors distribution infrastructure for direct-to-consumer brands targeting carpet-heavy residential markets.
Germany
EU Ecodesign Directive efficiency minimums are accelerating brushless DC motor adoption across Baden-Württemberg manufacturing footprints. REACH chemical registration restricts housing plastics and motor coatings, forcing reformulation of legacy product lines. Stuttgart's engineering clusters specialize in rare-earth-reduced magnet designs for cordless stick configurations.
China
Shenzhen and Dongguan electronics corridors dominate LiDAR sensor and visual SLAM algorithm production for robotic vacuum navigation stacks. SAMR certification requirements and GB standards shape wireless-connected appliance specifications for domestic e-commerce platforms. The Yangtze River Delta concentrates lithium-ion cell assembly for battery pack integration.
Japan
Tokyo and Osaka metropolitan households favor compact handheld units for space-constrained apartments with tatami and hardwood flooring. METI energy efficiency labeling programs and JIS standards govern motor performance claims and noise reduction specifications. Nagoya's industrial belt supplies precision injection molding for lightweight canister housings.
India
Mumbai and Bangalore urban middle-class households show rising appetite for Wi-Fi-enabled cleaning automation with localized app interfaces. BIS certification requirements and DGFT import duty structures shape pricing for foreign brands versus local assembly partnerships. Tamil Nadu's electronics manufacturing zones host contract assembly for mid-tier robotic units.
Vacuum Cleaner Market Key Industry Players
Concentration sits with diversified consumer electronics conglomerates and specialized home appliance engineers competing across distinct technology vectors. The vendor base spans three tiers: premium engineering houses with proprietary motor and filtration platforms, mass-market electronics brands leveraging scale and distribution density, and emerging specialists in autonomous navigation software. M&A activity targets sensor fusion startups and battery management system developers, while strategic partnerships with smart home ecosystem providers determine voice-control and scheduling integration.
Among diversified technology conglomerates, Samsung and LG Electronics occupy positions spanning component supply through finished goods. Dyson exemplifies the premium engineering archetype with cyclone airflow intellectual property and owned-channel control. iRobot anchors the autonomous navigation specialist tier with mapping patent portfolios and smart home ecosystem partnerships. SharkNinja represents the price-performance aggressive challenger model in cordless stick segments.
| Leading Market Players |
|---|
| iRobot |
| LG Electronics |
| Dyson |
| Electrolux |
| Miele |
| Bissell |
| Samsung |
| Philips |
| SharkNinja |
| Others |
Cost & Logistics Intelligence
Long-term offtake contracts for lithium-ion battery packs lock in both supply access and price visibility for cordless vacuum manufacturers, insulating German and Chinese OEMs from cobalt carbonate volatility while compressing margin flexibility for smaller competitors lacking procurement scale.
Pricing Analysis
EU Ecodesign Directive dictates the pricing tier structure across European markets, forcing brushless DC motor adoption that separates premium engineering houses from standard-tier assemblers. Pricing stratifies across HEPA-certified premium, efficiency-compliant standard, and entry-level wired tiers. Cost compression in cordless stick segments intensifies as Samsung and LG Electronics leverage captive battery supply. Price-sensitive mass-market buyers in India and Southeast Asia resist subscription software bundles, while German households accept premium positioning for filtration certification.
Supply Chain Analysis
Yangtze River Delta port congestion threatens just-in-time delivery of LiDAR sensors and visual SLAM modules to robotic vacuum assembly lines. Manufacturing gravity centers on Shenzhen for navigation electronics, Dongguan for precision molding, and Stuttgart for rare-earth-reduced motor magnets. Sourcing rests on concentrated Asian cell manufacturers for lithium-ion packs, Japanese optics suppliers for time-of-flight sensors, and Italian injection molders for lightweight housings. Single-source vulnerability in cobalt refining exposes margins to commodity swings. Distribution runs through direct-to-consumer platforms for Dyson and SharkNinja, while traditional retail channels retain hold in North American big-box.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Firmware engineering talent for autonomous navigation and smart home protocol integration commands compensation premiums that outstrip R&D budget growth at mid-tier manufacturers, creating a capability bottleneck that rewards early movers with dedicated embedded software teams.
For Market Incumbents: Consolidate patent portfolios in visual SLAM and multi-floor mapping algorithms to defend against sensor fusion startups eroding premium-tier exclusivity. Deepen backward integration into brushless DC motor production within Baden-Württemberg engineering clusters to satisfy EU Ecodesign Directive efficiency minimums without supplier margin extraction. Lock in long-term offtake for lithium-ion cells before cobalt price volatility reshapes cordless vacuum economics. For New Entrants and Emerging Players: Anchor in India's underpenetrated robotic segment through Tamil Nadu contract assembly partnerships that neutralize DGFT import duty disadvantages. Target Mumbai and Bangalore urban middle-class households with localized app interfaces and Wi-Fi-enabled automation priced below iRobot's premium positioning. Pursue white-label partnerships with Korean electronics conglomerates for navigation stack licensing rather than proprietary R&D. For Investors and Strategic Acquirers: Autonomous navigation software specialists with mapping patent portfolios and smart home ecosystem integrations offer the strongest acquisition rationale as hardware margins compress across the analysis window. Sensor fusion startups developing cost-reduced visual SLAM algorithms signal inflection when their modules penetrate mid-tier robotic SKUs below flagship price bands. Battery management system developers with rare-earth-reduced magnet expertise present defensive positioning against supply concentration risks.| Strategic Initiative | Industry Significance |
|---|---|
| Direct-to-Consumer Channel Expansion | Owned-commerce platforms extract margin previously captured by big-box intermediaries in suburban United States households. |
| Brushless DC Motor Manufacturing Scale-Up | EU Ecodesign Directive efficiency minimums render legacy universal-motor platforms economically unviable across German footprints. |
| Smart Home Ecosystem Partnership | Voice-control integration with Amazon Alexa and Google Home determines scheduling automation adoption in tech-forward households. |
| Right-to-Repair Compliance Investment | France and Germany spare part mandates create aftermarket service revenue streams and brand loyalty mechanisms. |
| LiDAR-to-Camera Sensor Convergence | Cost declines in visual SLAM algorithms enable mid-tier robotic vacuums to offer mapping precision previously confined to premium price bands. |
Research Approach
Initial hypotheses were tested against primary input from R&D directors at motor engineering houses, procurement leads at cordless vacuum OEMs, smart home platform integration specialists, and aftermarket service managers at European distributors, then refined against secondary validation from SAMR certification databases, EU Ecodesign Directive compliance filings, EPA appliance efficiency frameworks, and lithium-ion trade flow records. Bottom-up unit shipment estimates by product configuration and power source architecture were triangulated against top-down market value reconstruction.
Variance decomposition across the projection horizon isolates volume, price, and mix effects within each segmentation dimension: product type, power source, application environment, and connectivity tier. CAGRs were derived from installed base replacement cycle analysis and specification upgrade elasticity in Germany, China, and the United States. Forecast inputs include motor efficiency compliance cost curves, battery energy density improvement trajectories, and smart home penetration rates by metropolitan household archetype.
Material uncertainties — lithium carbonate price spikes, REACH material restriction expansions, and SAMR certification timeline extensions — sit outside the modeled envelope. Forecasts reflect assumptions about regulatory enforcement consistency and consumer willingness to pay for HEPA-grade filtration upgrades. Practitioners should keep alternative scenarios live as EU Ecodesign Directive implementation timelines and right-to-repair mandate geographies evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Appliances
Intelligent Electric Rice Cooker Market
Appliances
Fully Automatic Dishwasher Market
Appliances
Laundry Kiosk Market
Appliances
Body Dryer Market
Appliances
Japan Massage Equipment Market
Appliances
Built-In Large Cooking Appliance Market
Appliances
Kuwait Microwave Ovens Market
Appliances
North America Personal Care Appliances Market
Appliances
UK Residential Vacuum Cleaner Market
Appliances
Cooker Hoods Market
Appliances
Water Dispenser Market
Appliances
Kuwait Dishwasher Market
Appliances
GCC Dishwashers Market
Appliances
Minibar Refrigerators Market
Appliances
United Kingdom Handheld Vacuum Cleaners Market
Appliances
Bhutan and Nepal White Goods Market