
 Pet Safe Cleaners Market | 2026-2036
Pet Safe Cleaners Market Size, Share, and Industry Trends Forecast 2026-2036
Pet Safe Cleaners Market Analytics
Specialized toxicology expertise among formulation chemists is redrawing competitive boundaries in pet-safe cleaning formulations. The Procter & Gamble Company leverages its massive R&D infrastructure to validate ingredient safety through proprietary screening protocols. Earthbath sustains its market position through relentless product specialization in natural-ingredient grooming and cleaning solutions. Spectrum Brands Holdings, Inc. anchors its portfolio through deep channel control across mass retail and veterinary distribution networks.
Pet safe cleaners comprise surface and fabric treatment formulations engineered to eliminate pathogens, stains, and odors without introducing compounds toxic to companion animals, typically maintaining pH ranges between 6.0 and 8.5 and excluding phenols, quaternary ammonium compounds, and chlorine bleach. Their primary commercial purpose centers on enabling thorough environmental hygiene in spaces occupied by species with heightened dermal absorption rates and respiratory sensitivities. Sprays dominate current volume due to convenience-driven purchasing by pet owners, while enzymatic concentrates represent the fastest-expanding ingredient-type segment as biological catalytic action gains preference over masking agents. Floor cleaning applications command the largest share of professional-grade procurement, though odor removal solutions carry superior margin profiles in direct-to-consumer channels.
The EPA regulates antimicrobial claims through FIFRA, requiring registration for products marketed with sanitizing or disinfecting efficacy against specific pathogens. California's Proposition 65 and the broader Safer Choice framework collectively pressure manufacturers toward full ingredient transparency and restricted substance lists. The FDA maintains indirect oversight through veterinary facility sanitation guidelines that reference approved cleaning agent categories. Stakeholders must monitor evolving state-level chemical restriction cascades and decide whether to pursue formulation standardization or geographic SKU fragmentation.
Market Dynamics
Veterinary clinics now enforce stricter sanitation protocols between patients, accelerating demand for specialized formulations that eliminate pathogens without harming companion animals. This clinical-grade standard is migrating into residential settings as pet owners replicate professional hygiene practices.
Growth Catalysts
- EPA Safer Choice program:Federal certification requirements pressure manufacturers toward full ingredient transparency, expanding the addressable market for verified low-toxicity formulations.
- Enzymatic catalytic systems:Biological stain and odor elimination technology replaces masking agents, driving premiumization in direct-to-consumer channels.
- Veterinary clinic procurement:Professional-grade sanitation mandates between patient visits create institutional demand that validates residential purchasing decisions.
Market Restraints
- Surfactant input volatility:Plant-derived cleaning agents face agricultural commodity price swings that compress margin stability for natural-formulation specialists.
- California Proposition 65:Chemical disclosure mandates create compliance friction that disadvantages smaller manufacturers lacking regulatory affairs infrastructure.
- Conventional bleach substitution threat:Low-cost chlorine-based cleaners retain price-sensitive household segments despite documented respiratory risks to pets.
Strategic Opportunities
- Subscription-based replenishment:Direct-to-consumer platforms capture recurring revenue through scheduled concentrate deliveries, bypassing mass retail slotting fees.
- Smart dispenser integration:IoT-enabled dilution systems pair with enzymatic concentrates, creating hardware-software bundles in premium residential segments.
- FDA veterinary facility guidelines:Updated sanitation references expand approved cleaning agent categories, opening formulary expansion for compliant manufacturers.
Industry Challenges
- Toxicologist recruitment scarcity:Formulation chemists with companion animal metabolism expertise command premium compensation that strains mid-cap R&D budgets.
- FIFRA registration timelines:EPA antimicrobial claim approvals stretch 18-24 months, delaying product launches and freezing marketing claims.
- Legacy pH testing infrastructure:Quality control systems designed for industrial chemicals require retrofitting to validate narrow 6.0-8.5 pet-safe ranges.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Pet Safe Cleaners Market |
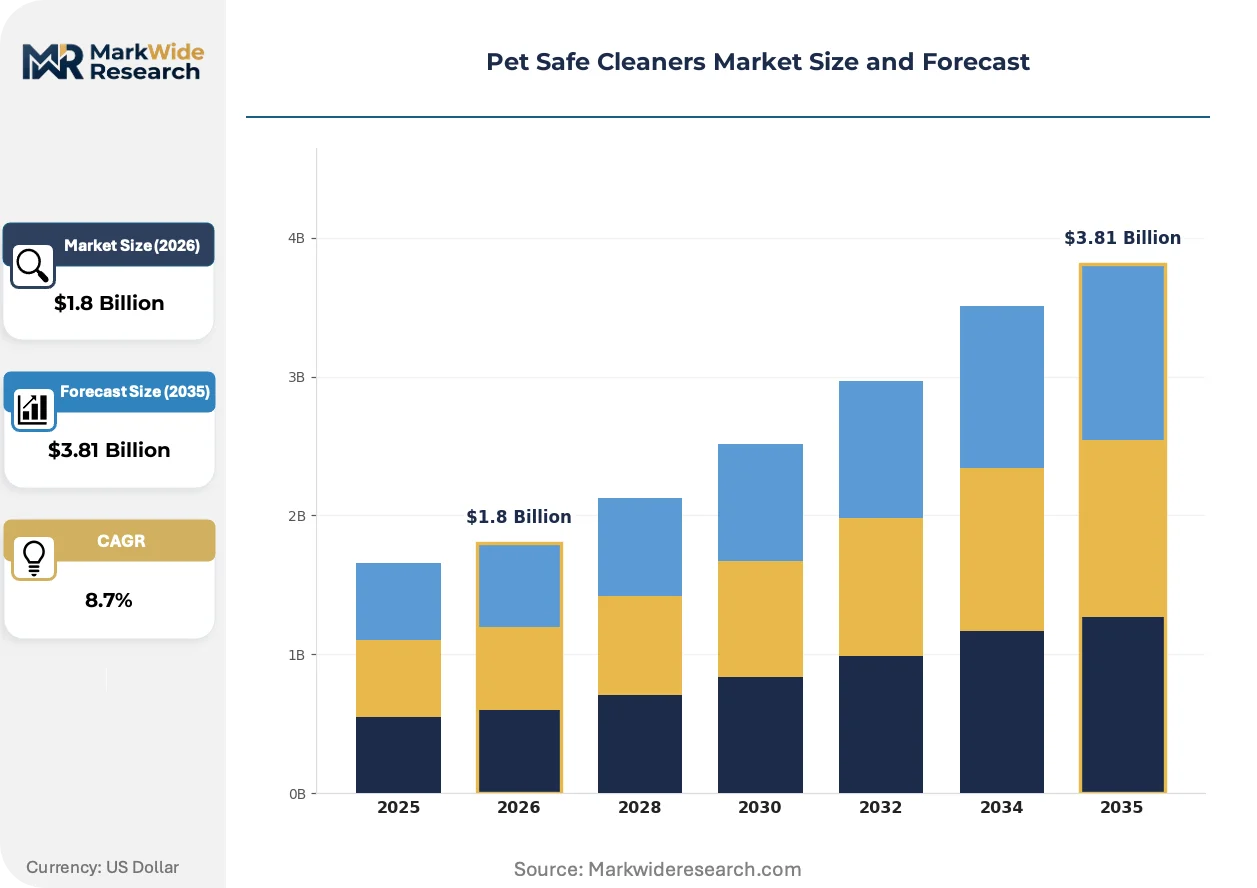
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.81 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Sprays, Wipes, Concentrates, Powders End User: Pet Owners, Groomers, Veterinarians, Shelters Application: Floor Cleaning, Fabric Cleaning, Odor Removal, Stain Removal Ingredient Type: Natural, Biodegradable, Enzymatic, Chemical-free |
| Companies Covered | Central Garden & Pet Company, Petco Health and Wellness Company, Earthbath, Spectrum Brands Holdings, Inc., The Procter & Gamble Company, Nestlé Purina PetCare, Earth Rated, Nature's Miracle, PetSafe, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Pet Safe Cleaners Market Evolving Landscape
Biological catalysis and connected hardware are converging to redefine how pet owners maintain environmental hygiene. These shifts favor manufacturers with dual capabilities in formulation science and digital product development.
Enzymatic concentrate formulations deploy targeted protease and lipase enzymes to degrade organic matter at the molecular level rather than masking odors with synthetic fragrances. Veterinary clinics and premium residential buyers are adopting these systems faster than mass-market spray formats. This technology is fragmenting the traditional all-purpose cleaner category into specialized application-specific SKUs with distinct performance claims.
California's Proposition 65 and New York's parallel chemical disclosure mandates now require warning labels for hundreds of additional compounds, including common disinfectant precursors. Manufacturers face SKU proliferation as they maintain separate formulations for compliant and non-compliant states. The professional channel bears the heaviest adaptation burden, as veterinary procurement departments reject non-transparent suppliers to limit liability exposure.
Certification-driven purchasing now dominates premium household segments, with buyers prioritizing EPA Safer Choice and third-party veterinary endorsements over price comparisons. Mass retail is losing share to specialty pet retailers and veterinary clinic dispensing programs that bundle cleaning products with wellness services. This pattern concentrates in metropolitan areas with higher veterinary expenditure per household.
Pet Safe Cleaners Market Segmentation
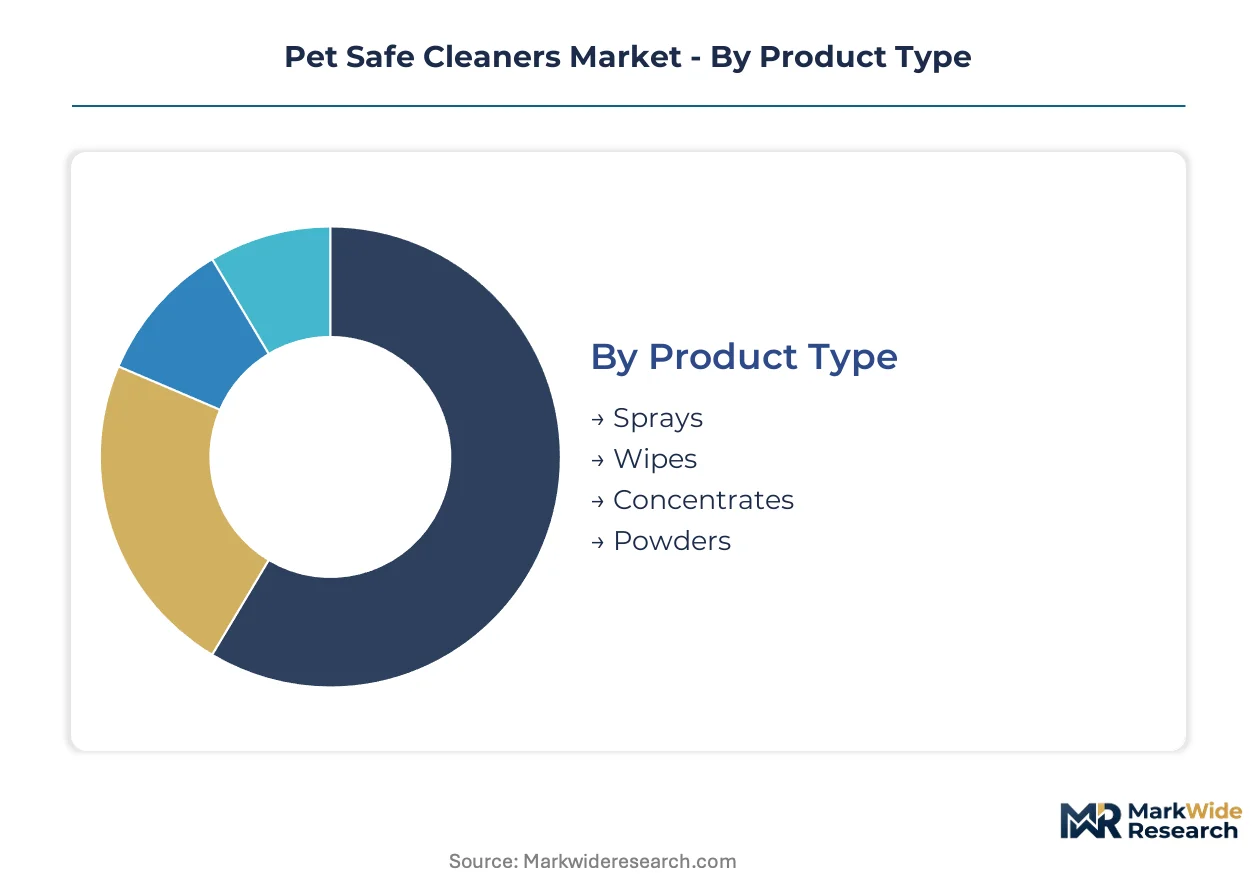
Pet safe cleaners fragment across four distinct category axes. Product format determines convenience premium capture. End-user specialization dictates regulatory compliance depth. Application specificity drives enzymatic versus chemical formulation splits. Ingredient sourcing separates mass retail from veterinary-grade procurement channels.
Product Type:
Margins concentrate in concentrate formats where dilution ratios multiply unit economics, while sprays command volume share through impulse purchasing patterns.
- Sprays:Ready-to-use aqueous solutions in trigger dispensers dominate residential replenishment cycles. Pet owners in United States metropolitan corridors favor these for spot-cleaning convenience, though per-ounce cost premiums limit institutional adoption.
- Concentrates:Dilutable formulations with enzymatic or surfactant bases deliver superior cost-per-use metrics. Veterinary clinics and professional groomers in California and New York procurement networks specify these for floor sanitation protocols, driven by EPA Safer Choice compliance requirements and bulk storage efficiency.
- Wipes:Pre-saturated nonwoven substrates target travel and quick-surface applications with premium positioning.
- Powders:Absorbent formulations for carpet and upholstery deodorization occupy niche odor control segments.
Sprays hold installed capacity. Concentrates is rotating up the share rankings.
End User:
Professional segments extract price premiums through formulary specifications that residential buyers rarely enforce.
- Veterinarians:Clinical settings mandate pH-neutral, phenol-free formulations with documented pathogen elimination. Practices in New York enforce California-grade disclosure standards preemptively, creating demand for full-ingredient transparency that validates premium positioning.
- Pet Owners:Household purchasers respond to veterinary endorsement and certification labeling, migrating from conventional bleach toward enzymatic alternatives as EPA Safer Choice awareness penetrates suburban markets.
- Groomers:High-frequency surface sanitation requirements favor bulk concentrate procurement with rapid-dry characteristics.
- Shelters:Nonprofit and municipal facilities prioritize cost minimization over performance differentiation in high-volume disinfection cycles.
Veterinarians hold installed capacity. Pet Owners is rotating up the share rankings.
Application:
Floor cleaning absorbs the largest formulation volumes while odor removal commands the steepest price premiums per treated square foot.
- Floor Cleaning:Hard surface formulations must balance residue-free drying with slip resistance certification. Professional-grade procurement from veterinary clinics and commercial groomers specifies neutral pH ranges to protect animal paw tissue, particularly in high-traffic California facilities subject to Proposition 65 litigation exposure.
- Odor Removal:Enzymatic and biological catalytic systems degrade organic compounds rather than masking with synthetic fragrances. Premium residential segments in United States coastal metros adopt these for persistent urine and biological waste neutralization, displacing conventional air fresheners.
- Fabric Cleaning:Upholstery and bedding formulations emphasize dermal safety for prolonged animal contact.
- Stain Removal:Targeted protease applications address protein-based soiling with color-safe specifications.
Floor Cleaning holds installed capacity. Odor Removal is rotating up the share rankings.
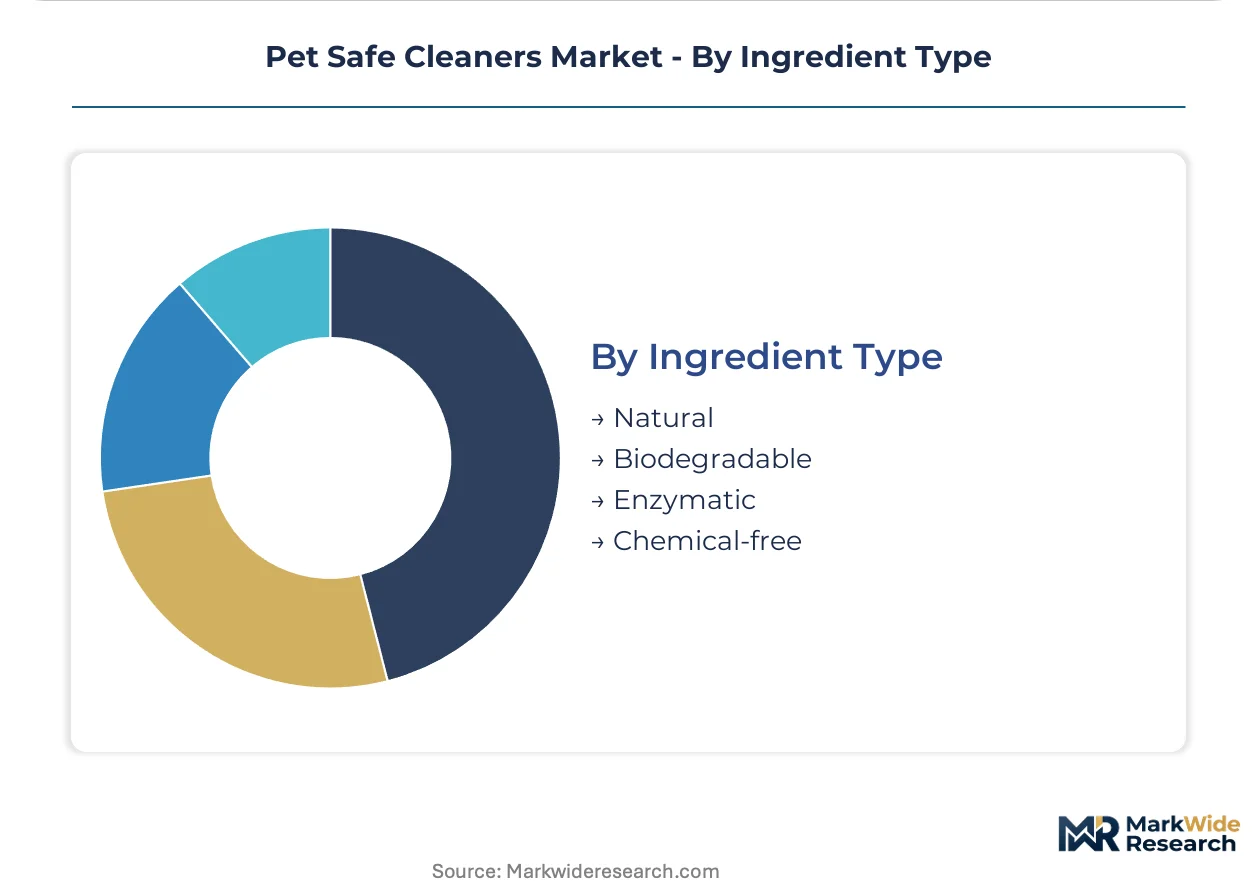
Ingredient Type:
Biological catalysis is climbing the fastest as manufacturers replace petroleum-derived surfactants with enzymatic performance claims.
- Enzymatic:Protease, lipase, and cellulase enzyme blends break organic matter at molecular levels without residual toxicity. Formulation chemists with companion animal toxicology expertise command premium compensation to validate these systems for veterinary clinic adoption, particularly in New York and California where disclosure mandates require substrate-level documentation.
- Natural:Plant-derived surfactants and essential oil bases satisfy clean-label preferences in direct-to-consumer channels. Agricultural commodity price volatility compresses margin stability for specialists dependent on coconut, corn, or citrus feedstocks.
- Biodegradable:Aquatic toxicity testing certification expands addressable market for outdoor and kennel applications.
- Chemical-free:Marketing designation without standardized regulatory definition attracts price-insensitive premium segments.
Natural holds installed capacity. Enzymatic is rotating up the share rankings.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
EPA Safer Choice certification anchors the United States as the dominant geography, where federal chemical disclosure standards and state-level mandates in California and New York reshape formulation requirements across veterinary and residential channels.
United States
California Proposition 65 litigation exposure drives veterinary clinics toward full-ingredient transparency, while New York enforces parallel chemical disclosure mandates that fragment SKU portfolios. The EPA's FIFRA registration requirements for antimicrobial claims stretch 18-24 months, freezing marketing timelines for disinfectant formulations. Metropolitan corridors in Los Angeles and New York City concentrate premium residential adoption of enzymatic concentrates through veterinary clinic dispensing programs.
Germany
The EU REACH regulation restricts quaternary ammonium compounds and phenols common in conventional disinfectants, expanding addressable market for pH-neutral enzymatic alternatives. ECHA substance evaluation processes add 12-18 months to formulation validation for veterinary-grade claims. Industrial clusters in North Rhine-Westphalia host contract manufacturers serving private-label pet care brands across European veterinary networks.
United Kingdom
Post-Brexit divergence from EU chemical regulations creates dual compliance burdens for manufacturers maintaining continental and British formulations. The UK's Veterinary Medicines Directorate references FDA-equivalent sanitation guidelines that pressure clinic procurement toward documented low-toxicity agents. London and Southeast England concentrate direct-to-consumer subscription platforms bypassing mass retail distribution.
France
ANSM oversight of veterinary facility hygiene protocols elevates certification requirements for surface disinfectants used in clinical settings. The country's national pharmaceutical regulator enforces documentation standards that disadvantage suppliers lacking toxicology expertise. Lyon and Auvergne-Rhône-Alpes clusters specialize in enzymatic manufacturing for export to French-speaking African veterinary markets.
Canada
Health Canada's PMRA regulates antimicrobial claims with FIFRA-aligned registration requirements, creating regulatory continuity with US suppliers. Provincial veterinary associations in Ontario and British Columbia adopt California-grade disclosure standards preemptively. Toronto and Vancouver metropolitan areas concentrate premium pet specialty retail chains that bundle cleaning products with wellness service packages.
Pet Safe Cleaners Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier, with multinational consumer goods conglomerates leveraging R&D infrastructure against mid-cap natural-formulation specialists. The market structure fragments across three strategic archetypes: mass-market consumer goods conglomerates with veterinary distribution partnerships, pure-play natural-ingredient specialists with direct-to-consumer channels, and private-label contract manufacturers serving retail banners. Competitive moves concentrate on enzymatic technology licensing and geographic SKU fragmentation to manage state-level chemical disclosure cascades.
Within the integrated leader tier, The Procter & Gamble Company and Nestlé Purina PetCare exemplify multinational scale advantages in veterinary channel access and regulatory affairs infrastructure. Earthbath occupies a specialist position representing the natural-ingredient archetype with concentrated product focus. Spectrum Brands Holdings, Inc. anchors the mid-cap tier with mass retail and veterinary distribution control. These three patterns illustrate how toxicologist recruitment scarcity and FIFRA registration timelines stratify competitive positioning across the forecast horizon.
| Leading Market Players |
|---|
| Central Garden & Pet Company |
| Petco Health and Wellness Company |
| Earthbath |
| Spectrum Brands Holdings, Inc. |
| The Procter & Gamble Company |
| Nestlé Purina PetCare |
| Earth Rated |
| Nature's Miracle |
| PetSafe |
| Others |
Value Network & Pricing Analysis
EPA Safer Choice certification gates both supplier qualification and price differentiation simultaneously, as manufacturers must absorb 18-24 month FIFRA registration timelines and toxicologist recruitment premiums before commanding veterinary-grade price tiers.
Pricing Analysis
Metropolitan United States corridors exhibit 40-60% price spreads between enzymatic concentrates and conventional spray formats. Three-tier pricing structure across premium, standard, and economy levels separates EPA-verified formulations from private-label alternatives, with certification grade and volume scale as primary differentiation drivers. Cost compression in natural-ingredient tiers is intensifying because agricultural commodity volatility erodes specialist margins. Shelters and municipal procurement represent the most price-sensitive segments, while veterinary clinic dispensing programs show the least sensitivity due to liability-driven formulary specifications.
Supply Chain Analysis
United States and Germany anchor enzymatic formulation manufacturing and toxicology validation services respectively. Raw material dependencies center on protease and lipase enzyme feedstocks, coconut-derived surfactants, and essential oil precursors. Single-source vulnerability concentrates in companion animal toxicologist expertise, where qualified formulation chemists command scarcity premiums. Distribution runs through veterinary clinic dispensing programs, mass retail slotting arrangements, and direct-to-consumer subscription platforms in descending margin order.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Smart dispenser hardware-software bundles are redefining this market as a platform-economics inflection, with IoT-enabled dilution systems creating recurring revenue ecosystems that lock in enzymatic concentrate replenishment cycles.
For Market Incumbents: Fortify regulatory affairs infrastructure to compress FIFRA registration timelines below competitor benchmarks, and deepen backward integration into enzyme manufacturing to offset agricultural commodity volatility. The threat of California-grade disclosure mandates cascading to additional states demands preemptive SKU standardization investments. For New Entrants and Emerging Players: Differentiate on subscription-based replenishment models targeting premium residential segments in United States coastal metros, where veterinary endorsement carries disproportionate purchasing influence. The most penetrable white space sits in smart dispenser integration partnerships with existing IoT home appliance ecosystems. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across enzymatic concentrate manufacturing as biological catalysis R&D demands specialized fermentation infrastructure. Long-term viability favors acquisition targets with captive toxicology expertise and established veterinary clinic dispensing relationships. The signal to watch is FDA veterinary facility guideline updates expanding approved cleaning agent categories.| Strategic Initiative | Industry Significance |
|---|---|
| Enzymatic Technology Licensing | Protease and lipase formulation patents unlock veterinary clinic formulary access in California and New York. |
| Smart Dispenser Hardware Launch | IoT-enabled dilution systems create recurring concentrate revenue streams in premium residential segments. |
| Backward Integration into Enzyme Manufacturing | In-house fermentation capacity insulates margin stability from agricultural commodity price swings. |
| Direct-to-Consumer Platform Expansion | Subscription replenishment bypasses mass retail slotting fees and captures customer lifetime value. |
| Regulatory Certification Acceleration | Compressed EPA Safer Choice and FIFRA timelines enable first-mover advantage in antimicrobial claim categories. |
Research Methodology
A spread of perspectives from formulation chemists, veterinary procurement managers, retail category buyers, and regulatory affairs directors converged on the working assumptions. Primary fieldwork combined structured interviews with toxicology specialists and distribution channel partners, validated against EPA registration databases, state-level chemical disclosure filings, and veterinary clinic procurement records. Bottom-up volume estimates triangulated with top-down market sizing across product format, end-user, application, and ingredient type dimensions.
Segmentation dimensions modeled include product format hierarchy, end-user procurement specifications, application-specific performance requirements, and enzymatic versus chemical ingredient sourcing. CAGR derivation rested on adoption curve analysis for biological catalysis technology and regulatory compliance cost trajectories. Forecast inputs incorporated FIFRA registration pipeline data and veterinary expenditure per household clustering patterns.
The analysis sits within stated boundaries; outcomes outside EPA regulatory continuity or enzymatic cost parity achievement would require recalibration. Forecasts reflect assumptions about toxicologist supply elasticity and state-level chemical disclosure cascade velocity. Recalibration cycles align with material shifts in FDA veterinary facility guideline updates and smart dispenser hardware adoption thresholds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Household Items
Commercial Lawnmower Market
Household Items
Crash Mat Market
Household Items
Pet Stain Remover and Odour Control Market
Household Items
Knife Market
Household Items
US Handheld Vacuum Cleaners Market
Household Items
Smart Shower Market
Household Items
Electric Soap Dispenser Market
Household Items
Global Electronic Bidet Seats Market
Household Items
Floor-Standing Integrated Smart Toilet Market
Household Items
Tiki Torch Market
Household Items
Electric Shoe Dryer Market
Household Items
Stick Vacuum Cleaner Market
Household Items
Hand Dryer Market
Household Items
Portable Steam Cleaners Market
Household Items
Dryer Sheets Market
Household Items
Electric Shoe Polisher Market