
 North America Liquid Hand Soap Market | 2026-2036
North America Liquid Hand Soap Market Size, Share, and Industry Trends Forecast 2026-2036
North America Liquid Hand Soap Market Analytics
Mexico's manufacturing corridor is reshaping regional supply dynamics for surfactant-based personal care products. Procter & Gamble leverages integrated supply chains spanning Cincinnati and Monterrey to sustain cost competitiveness in standard liquid formulations. GOJO Industries specializes in healthcare-grade antimicrobial soaps, anchoring its position through captive distribution to hospital networks across the Midwest and Ontario. Unilever competes aggressively on sustainability credentials, differentiating its natural-formulation portfolio through RSPO-certified palm oil sourcing and concentrated refill formats.
Liquid hand soap comprises aqueous surfactant solutions, typically formulated with anionic or nonionic detergents at active-matter concentrations between 10% and 20%, designed for manual degerming and soil removal in hygiene-critical environments. Foam soap systems, which aerate diluted formulations through specialized dispensers, lead volume in commercial installations due to reduced per-use consumption and lower water requirements during rinsing. The antibacterial segment commands premium positioning in healthcare and foodservice channels, though natural-formulation demand accelerates fastest among household buyers seeking paraben-free and sulfate-free alternatives. Supermarkets remain the dominant distribution channel for household replenishment, while specialty stores capture margin-rich natural and fragrance-free SKUs.
The FDA governs cosmetic and over-the-counter drug claims for hand soaps, distinguishing between cosmetic cleansing products and antiseptic washes subject to monograph compliance. EPA jurisdiction extends to antimicrobial pesticide claims, creating dual regulatory exposure for manufacturers marketing germ-killing efficacy. Health Canada and PMRA maintain parallel oversight for products distributed north of the border, with divergent ingredient disclosure requirements complicating cross-border SKU rationalization. Stakeholders must monitor evolving state-level chemical restriction bills in California and New York that increasingly outpace federal timelines, forcing accelerated reformulation cycles ahead of any harmonized North American standard.
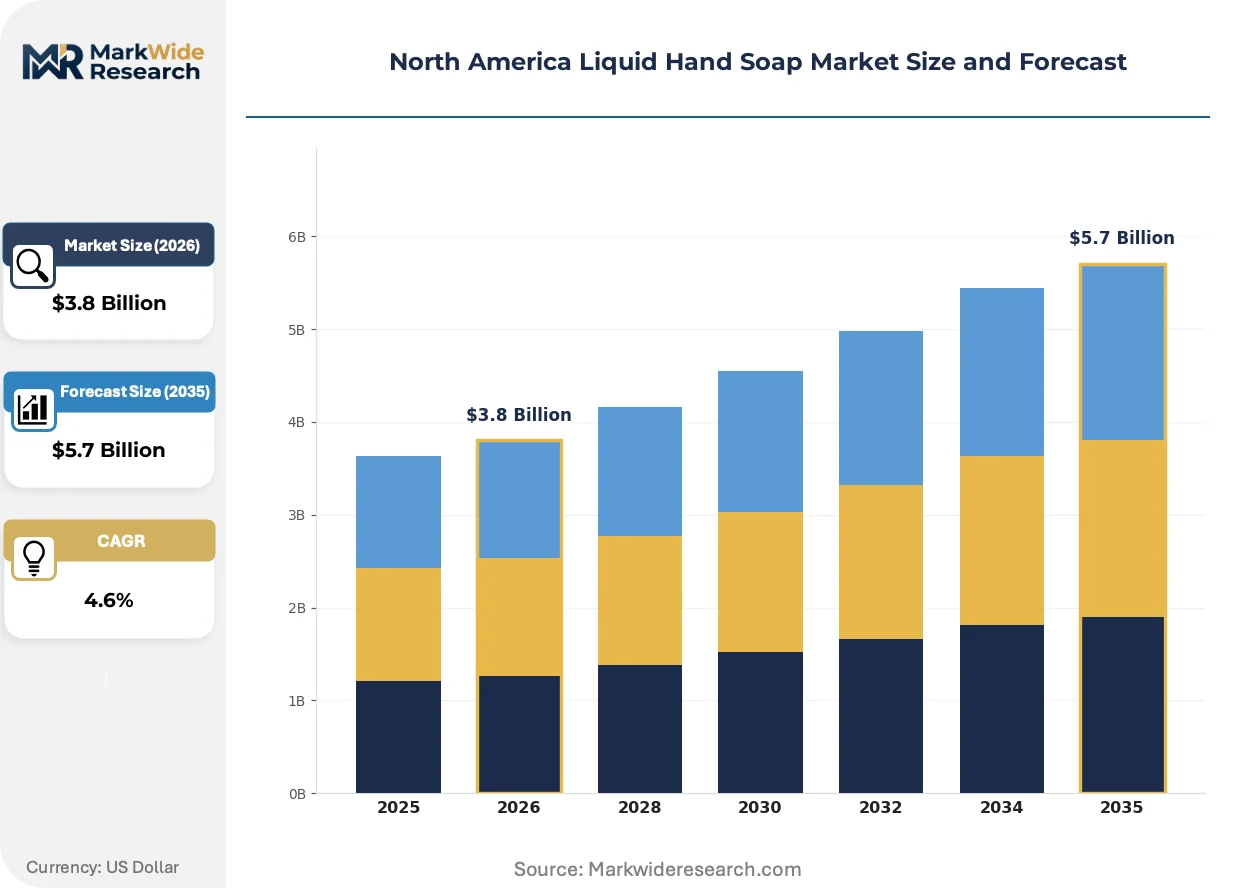
Market Dynamics
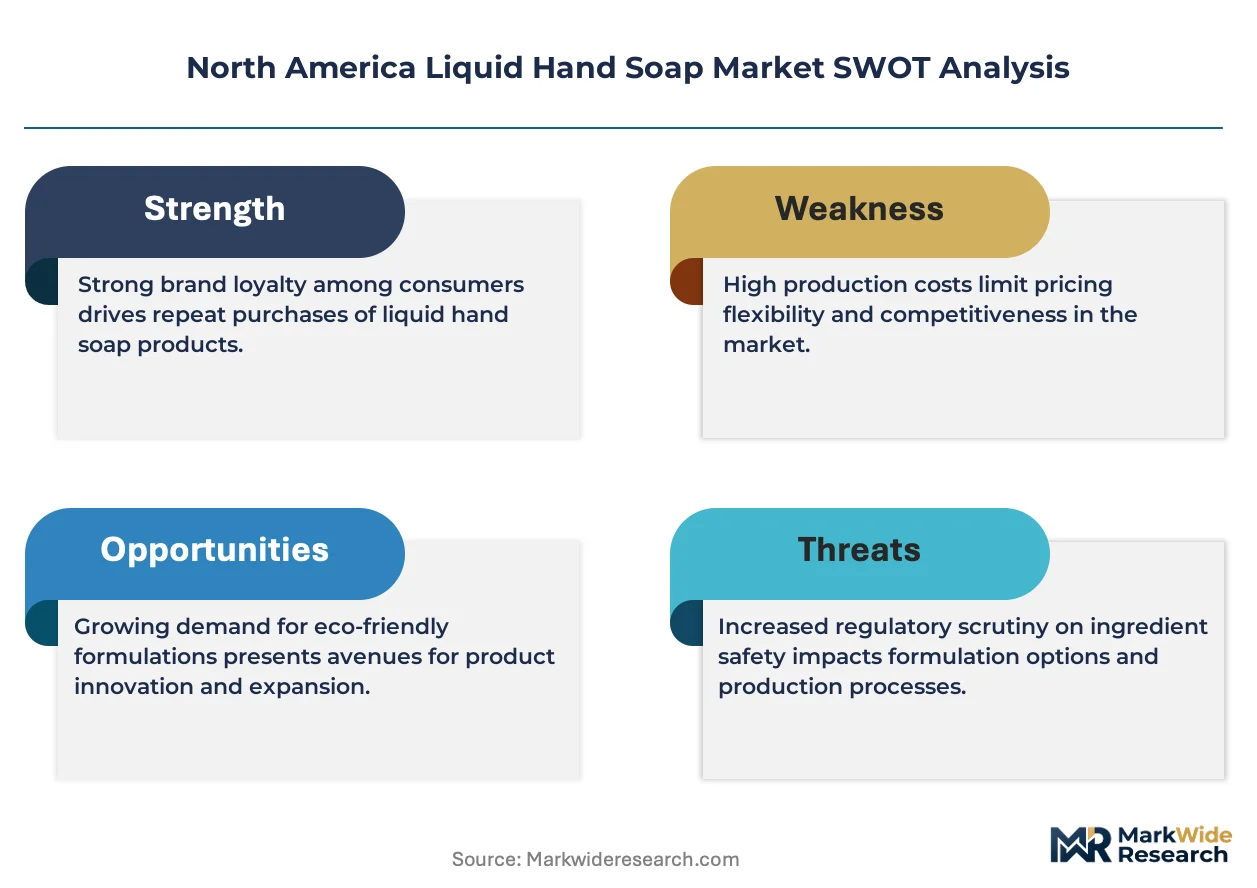
FDA's ongoing safety review of triclosan and triclocarban is forcing accelerated reformulation cycles across antimicrobial soap portfolios, redirecting R&D investment toward benzalkonium chloride and novel biocidal alternatives.
Growth Catalysts
- Joint Commission hygiene protocols:Healthcare facilities across the United States are expanding procurement of antibacterial formulations to meet accreditation standards, sustaining institutional demand for hospital-grade products.
- Foam soap dispenser technology:Aerated delivery systems reduce per-use surfactant consumption by 30-40% versus conventional liquid formats, lowering operational costs for commercial installations.
- Northeast corridor density:Concentrated hospital networks and corporate office complexes in Boston, New York, and Philadelphia sustain bulk purchasing volumes unmatched elsewhere in the region.
Market Restraints
- Palm oil price volatility:RSPO-certified sustainable palm kernel oil commands 15-25% premiums over conventional grades, compressing margins for natural-formulation portfolios.
- Cross-border regulatory friction:Divergent ingredient disclosure requirements between FDA and Health Canada complicate SKU rationalization for manufacturers distributing across the U.S.-Canada border.
- Alcohol-based sanitizer substitution:Hand sanitizer gel formats continue displacing liquid soap in foodservice quick-service environments where speed of use outweighs cleansing efficacy.
Strategic Opportunities
- Concentrated refill formats:Unilever and specialty brands are capturing margin-rich household segments through dilutable concentrates that reduce plastic packaging intensity.
- Mexico manufacturing corridor:Monterrey-based production assets offer tariff-advantaged supply to U.S. Southwest markets with lower logistics costs versus Asian imports.
- California and New York state chemical restriction bills:Accelerating state-level legislation ahead of federal timelines creates first-mover advantage for reformulation-ready suppliers.
Industry Challenges
- Antimicrobial efficacy testing capacity:FDA's evolving monograph requirements for benzalkonium chloride-based claims have created bottlenecks at third-party testing laboratories, extending product launch timelines.
- Legacy dispenser incompatibility:Foam soap systems require specialized aerating mechanisms that cannot retrofit standard liquid dispensers, complicating facility-wide conversions.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Liquid Hand Soap Market |
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $5.7 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Foam Soap, Gel Soap, Liquid Soap, Antibacterial Soap Distribution Channel: Online Retail, Supermarkets, Convenience Stores, Specialty Stores End User: Household, Commercial, Healthcare, Educational Institutes Formulation Type: Natural, Synthetic, Fragrance-Free, Moisturizing |
| Companies Covered | Unilever, SC Johnson & Son Inc., Colgate-Palmolive Company, Dr. Bronner's Magic Soaps, GOJO Industries, Henkel AG & Co. KGaA, Reckitt Benckiser Group PLC, EO Products, Procter & Gamble, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Liquid Hand Soap Market Evolving Landscape
Connected dispensing infrastructure is digitizing inventory management across commercial hygiene contracts, while regulatory fragmentation accelerates formulation diversification and sustainability credentials reshape procurement evaluation criteria.
Smart sensor-equipped dispensers are digitizing consumption tracking and automated replenishment workflows. Facility management contractors across U.S. healthcare and education verticals are deploying these systems at accelerating rates. The technology is digitizing service contract structures toward usage-based pricing models that tie vendor compensation to actual consumption rather than fixed scheduled deliveries.
EPA's jurisdiction over antimicrobial pesticide claims continues intersecting with FDA cosmetic-drug boundaries, creating dual compliance exposure for germ-killing efficacy marketing. Manufacturers must navigate overlapping testing protocols and divergent label requirements. Healthcare-grade products face the most stringent documentation burdens, with hospital procurement committees now requiring EPA registration numbers alongside FDA facility registration.
Household buyers are prioritizing paraben-free and sulfate-free ingredient declarations over brand loyalty, compressing switching costs. Specialty stores and direct-to-consumer channels are capturing these preference shifts through subscription refill models. This behavior is most visible in Pacific Coast metropolitan markets where clean-label certification carries premium pricing power.
North America Liquid Hand Soap Market Segmentation
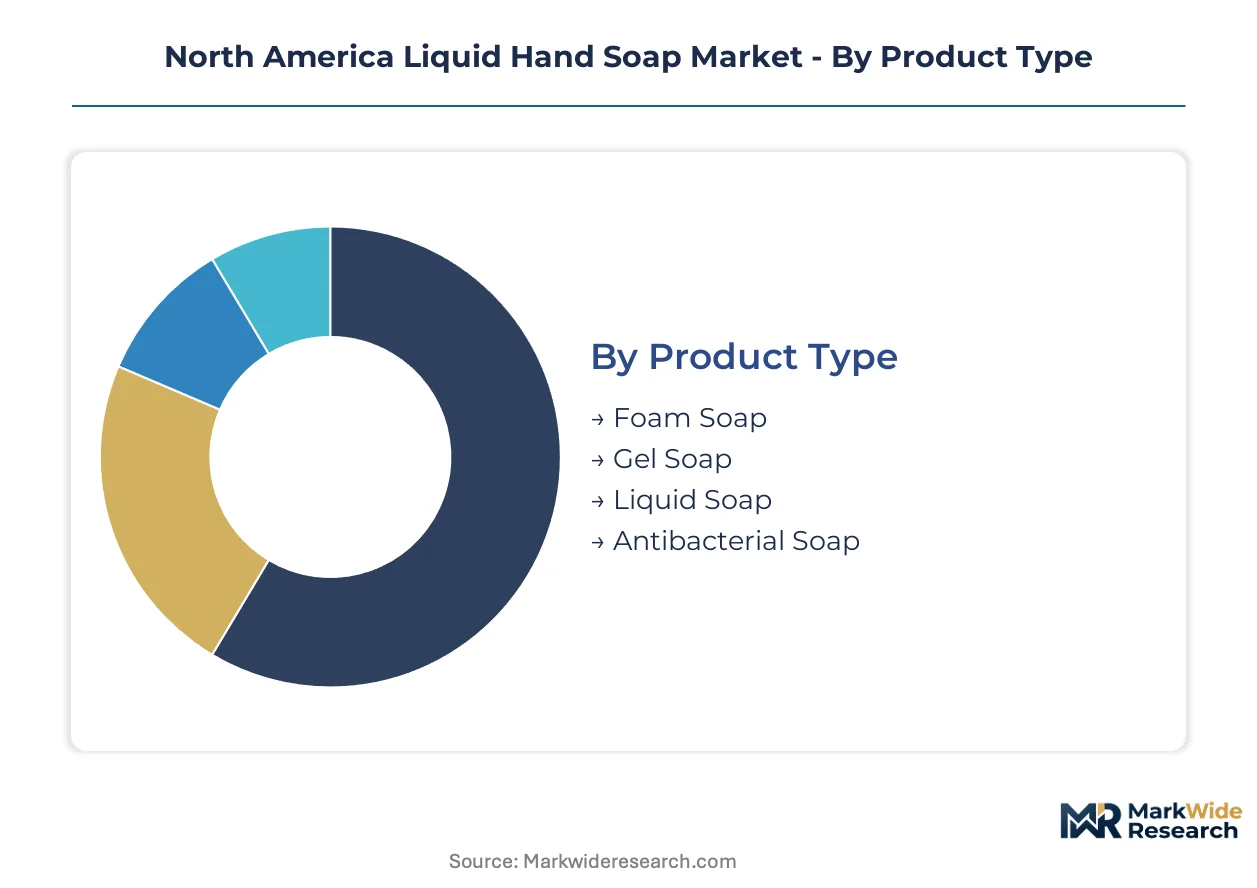
Liquid hand soap segmentation in North America reflects divergent procurement logics across institutional buyers and household consumers. Product format, distribution channel, and end-use application each shape margin structures and reformulation priorities differently.
Product Type:
Cost tier differentiation separates commodity surfactant formats from premium antimicrobial and aerated delivery systems.
- Foam Soap:Diluted surfactant formulations aerated through specialized dispenser mechanisms reduce per-use consumption by 30-40% versus conventional liquids. Healthcare and education facilities across the U.S. Northeast corridor favor foam systems for operational cost control and reduced water usage during rinsing cycles.
- Antibacterial Soap:Benzalkonium chloride-based formulations dominate hospital-grade procurement, though FDA safety reviews of legacy actives force continuous reformulation. Joint Commission accreditation standards sustain institutional demand despite regulatory uncertainty around antimicrobial efficacy claims.
- Gel Soap:Thickened aqueous formulations with higher viscosity appeal to residential preferences for tactile richness and controlled dispensing.
- Liquid Soap:Standard pourable surfactant solutions remain the volume baseline for household replenishment through supermarket channels.
Foam soap commands the established base in commercial installations. The steepest expansion runs through antibacterial formulations as healthcare procurement tightens.
Distribution Channel:
Customer type and purchase frequency determine channel economics, with bulk institutional contracts diverging sharply from household replenishment patterns.
- Supermarkets:Dominant channel for household volume, capturing routine replenishment through high-frequency shopping trips. Standard liquid and gel formats concentrate here.
- Online Retail:Subscription refill models and concentrated formats gain traction among Pacific Coast metropolitan buyers prioritizing clean-label credentials and packaging reduction.
- Specialty Stores:Premium natural-formulation SKUs with RSPO-certified palm oil sourcing and paraben-free positioning command margin-rich positioning.
- Convenience Stores:Travel-size and impulse-purchase formats serve transient demand with limited SKU depth.
Supermarkets anchor the volume base. The steepest growth trajectory flows through online retail as subscription mechanics reshape household purchasing.
End User:
Application environment dictates formulation specification, with hygiene-critical settings imposing antimicrobial requirements absent from residential use.
- Healthcare:Hospital networks require EPA-registered antimicrobial products with documented efficacy against nosocomial pathogens. Procurement committees demand dual FDA facility and EPA registration documentation.
- Commercial:Corporate office complexes and foodservice operations balance cost efficiency with visible hygiene compliance, favoring foam dispenser systems for per-use economy.
- Household:Paraben-free and sulfate-free preference shifts compress brand loyalty, with buyers prioritizing ingredient transparency over established labels.
- Educational Institutes:K-12 and university facilities deploy connected dispenser infrastructure for usage-based service contracting and automated replenishment.
Healthcare commands the premium tier. The steepest climb occurs in household segments as clean-label certification gains pricing power.
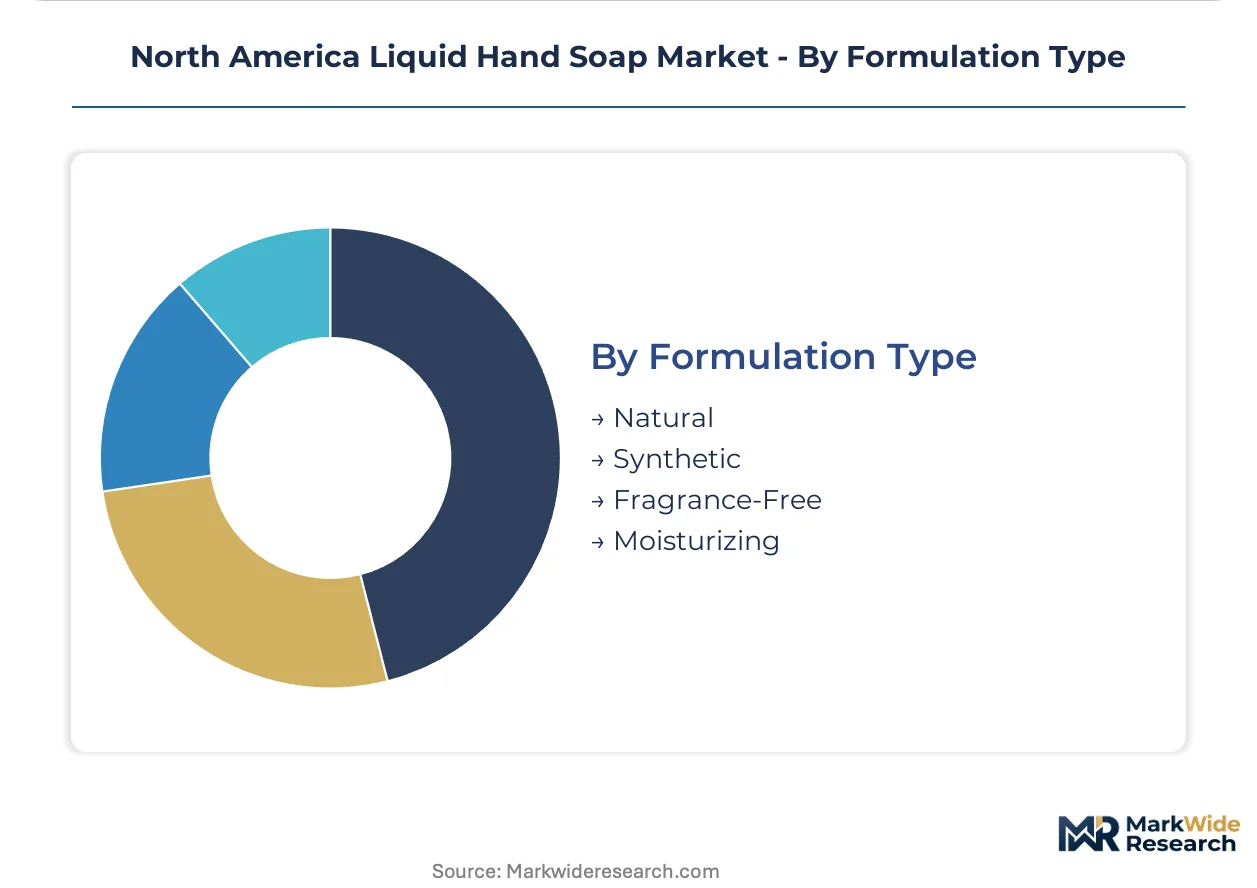
Formulation Type:
Margin structure stratifies across certification tiers, with sustainable sourcing credentials commanding 15-25% raw material premiums.
- Natural:Plant-derived surfactants and RSPO-certified palm kernel oil formulations target sustainability-motivated buyers. Unilever and specialty competitors differentiate through concentrated refill formats that reduce plastic intensity.
- Fragrance-Free:Hypoallergenic positioning captures sensitive-skin and clinical environments where dermatological safety outweighs sensory experience.
- Synthetic:Petrochemical-derived surfactants maintain cost competitiveness in standard liquid and foam applications.
- Moisturizing:Added emollients and glycerin blends address frequent-wash environments where skin barrier protection complements cleansing function.
Synthetic formulations hold the volume base. Natural products are gaining share fastest as state-level chemical restriction bills accelerate ahead of federal timelines.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Ambassador Bridge and Detroit River crossing infrastructure underwrites North America's integrated consumer goods supply chains, connecting Midwest manufacturing clusters with Ontario distribution hubs and sustaining just-in-time replenishment across the Great Lakes corridor.
United States
FDA facility registration requirements and EPA antimicrobial pesticide claims govern formulation compliance for hospital-grade products. Joint Commission accreditation standards drive procurement volumes across the Northeast corridor from Boston to Philadelphia. Dense hospital networks and corporate office complexes in New York Metro sustain bulk institutional purchasing unmatched elsewhere in the region.
Canada
Health Canada and PMRA maintain parallel oversight with divergent ingredient disclosure requirements complicating cross-border SKU rationalization. Provincial health authorities in Ontario and Quebec enforce institutional hygiene protocols aligned with but distinct from U.S. standards. Toronto and Montreal anchor distribution networks serving healthcare systems across the Windsor-Quebec City corridor.
Mexico
Monterrey-based production assets offer tariff-advantaged supply positioning for U.S. Southwest markets. Federal consumer protection standards under PROFECO govern labeling requirements distinct from FDA and Health Canada frameworks. The Bajío Region and Mexico City Metro concentrate manufacturing capacity for surfactant-based personal care products serving domestic and export demand.
North America Liquid Hand Soap Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream supplying surfactant actives and dispensing hardware. The North America liquid hand soap market structures around three tiers: multinational consumer goods conglomerates with integrated supply chains, healthcare-focused specialists with captive distribution networks, and natural-formulation challengers competing on sustainability credentials. Strategic moves concentrate on M&A to secure dispensing technology assets and geographic expansion through Mexico manufacturing corridors to capture tariff advantages.
Among the tiered competitive set, Procter & Gamble exemplifies scale-driven platform integration with cross-border supply chain architecture spanning Cincinnati and Monterrey. GOJO Industries occupies the healthcare-specialist archetype through hospital network distribution concentration in the Midwest and Ontario. Unilever represents the sustainability-differentiation vector, competing on RSPO-certified sourcing and concentrated refill formats that reduce packaging intensity.
| Leading Market Players |
|---|
| Unilever |
| SC Johnson & Son Inc. |
| Colgate-Palmolive Company |
| Dr. Bronner's Magic Soaps |
| GOJO Industries |
| Henkel AG & Co. KGaA |
| Reckitt Benckiser Group PLC |
| EO Products |
| Procter & Gamble |
| Others |
Value Network & Pricing Analysis
Overcapacity in Mexico's Monterrey manufacturing corridor is compressing contract manufacturing margins while simultaneously enabling aggressive pricing postures for U.S. Southwest market penetration. This utilization dynamic feeds a bifurcated supplier landscape where integrated multinationals wield cost advantages against specialty formulators burdened by RSPO-certified palm oil premiums.
Pricing Analysis
Volume-discount tiering structures separate healthcare procurement contracts from household retail replenishment. Three-tier pricing stratification across antimicrobial hospital-grade, commercial foam-system, and standard liquid formulations reflects certification intensity and Joint Commission compliance documentation. Cost compression in natural-formulation segments intensifies as sustainable palm kernel oil premiums squeeze margin structures for RSPO-certified portfolios. Healthcare facilities demonstrate lowest price sensitivity due to accreditation mandates, while household buyers exhibit highest elasticity as clean-label preferences override brand loyalty.
Supply Chain Analysis
Tariff exposure between Mexico and the United States dominates supply chain risk calculus for surfactant-based personal care production. Manufacturing concentration spans Mexico's Bajío Region, the U.S. Midwest, and Ontario's Windsor corridor, with surfactant actives, specialized dispenser mechanisms, and RSPO-certified palm derivatives anchoring raw material dependencies. Single-source vulnerability concentrates in benzalkonium chloride supply for antimicrobial formulations. Distribution runs through integrated captive networks for healthcare contracts and wholesale-retail channels for household replenishment.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation opportunity crystallizes around divergent regulatory timelines between state-level chemical restriction bills and federal harmonization delays, creating niche windows for reformulation-ready suppliers.
For Market Incumbents: Harden antimicrobial efficacy testing capabilities ahead of FDA monograph finalization for benzalkonium chloride claims. Deepen backward integration into Mexico manufacturing assets to capture tariff-advantaged supply positioning against Asian import competition. For New Entrants and Emerging Players: Build out concentrated refill format capabilities targeting Pacific Coast metropolitan subscription demand. The household natural-formulation segment offers lowest competitive density. Pursue direct-to-consumer channels with clean-label certification as primary differentiation lever. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among connected dispenser infrastructure providers serving educational and healthcare facilities through usage-based service contracts. Long-term viability favors platform integrators with captive distribution networks over component specialists exposed to commodity surfactant cycles. Monitor California and New York state chemical restriction bill passage as inflection signal for accelerated reformulation demand.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Mexico Manufacturing | Captures tariff advantages and reduces logistics costs versus Asian surfactant imports. |
| Connected Dispenser Infrastructure Deployment | Transforms service contracts toward usage-based pricing tied to actual consumption metrics. |
| RSPO-Certified Sourcing Transition | Aligns procurement evaluation criteria with sustainability mandates from institutional buyers. |
| Antimicrobial Reformulation Investment | Addresses FDA safety review redirection toward benzalkonium chloride and novel biocidal alternatives. |
| Concentrated Refill Format Launch | Reduces plastic packaging intensity while capturing margin-rich household subscription segments. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of FDA facility registration databases, EPA antimicrobial pesticide filings, Health Canada ingredient disclosure records, and Nielsen retail audit data. Primary interviews engaged supply chain directors at healthcare GPOs, formulation chemists at surfactant manufacturers, procurement managers at hospital networks, and category buyers at supermarket chains. Bottom-up demand modeling triangulated against top-down trade flow analysis across the U.S.-Canada-Mexico corridor.
Forecast inputs incorporate product format adoption curves, regulatory compliance cost trajectories, and raw material price dynamics across the projection horizon. Segmentation dimensions modeled include formulation type, end-use application, distribution channel, and geographic procurement cluster. CAGRs were derived through regression analysis of historical volume trends against macroeconomic drivers and industry-specific demand shifters including Joint Commission accreditation expansion and state-level chemical restriction legislation.
Stress conditions across palm oil price volatility, FDA monograph timeline acceleration, and healthcare procurement budget compression were modeled; outcomes outside those bands fall beyond the analytical envelope. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Household Items
Insulated Water Bottles Market
Household Items
Robot Mops Market
Household Items
Global Paper Towels Market
Household Items
Smart Air Purifier Market
Household Items
France Digital Showers Market
Household Items
Pet Safe Cleaners Market
Household Items
Copper Water Bottle Market
Household Items
South Korea Cookware Market
Household Items
Toilet Hygiene Products Market
Household Items
Barbecue Grill Market
Household Items
Germany Digital Showers Market
Household Items
Global Refrigerator Water Filters Market
Household Items
Wax Removal Aids Market
Household Items
Thermos Bottle Market
Household Items
Aquarium Hydrometers Market
Household Items
Plastic Carafe Market