
 Intelligent Electric Rice Cooker Market | 2026-2036
Intelligent Electric Rice Cooker Market Size, Share, and Industry Trends Forecast 2026-2036
Intelligent Electric Rice Cooker Market Insights
REACH compliance in Europe is shifting the cost-of-entry calculus for manufacturers seeking to export ceramic-coated inner pots and electronic heating components. Panasonic Corporation leverages vertical integration across its sensor supply chain to absorb these regulatory burdens without margin erosion. Zojirushi Corporation anchors its premium positioning through sustained R&D intensity in fuzzy logic algorithms, while Cuckoo Electronics dominates the Korean domestic channel through direct-to-consumer distribution control.
An intelligent electric rice cooker is a microprocessor-controlled appliance that uses thermal sensors, induction heating coils or resistive elements, and programmable logic to automate water absorption, temperature curves, and resting phases for optimal starch gelatinization. Micom units with multi-stage temperature profiling now lead volume shipments, though induction models command the deepest margin pools due to copper coil costs and precision cooking claims. Smart Control technology with Wi-Fi connectivity and app-based recipe libraries represents the fastest-growing segment, while Conventional Control faces gradual displacement in urban households but sustains volume in price-sensitive rural markets.
Japan's METI enforces stringent standby power regulations that force redesigns of always-connected units, while China's SAMR oversees compulsory energy efficiency labeling that gates market access for imported brands. The EU's Ecodesign Directive and F-Gas Regulation constrain refrigerant-based cooling mechanisms in multi-function cookers, compressing design flexibility. Stakeholders must monitor how fragmented national efficiency benchmarks reshape component sourcing decisions and determine which assembly footprints can serve multiple regulatory jurisdictions without redundant certification costs.
Market Dynamics
Induction heating coil shortages and copper price volatility are compressing margin structures for precision-cooking models while accelerating supplier consolidation around Japanese and Korean component specialists.
Growth Catalysts
- Japan's METI standby power regulations:Mandatory efficiency redesigns force component upgrades that differentiate compliant brands in premium urban channels.
- Urban household densification:Space-constrained East Asian apartments favor multi-function appliances with programmable starch profiles over single-purpose units.
- Fuzzy logic algorithm refinement:Thermal sensor arrays with multi-stage temperature curves now enable automated texture customization that commands price premiums.
Market Restraints
- Copper coil supply concentration:Japanese and Korean smelters control induction heating component supply, exposing assemblers to input cost spikes.
- REACH ceramic coating compliance:ECHA substance restrictions on non-stick inner pot materials add certification layers that delay European market entry.
- Conventional resistive heating substitution:Lower-cost thermal element cookers retain volume in price-sensitive rural markets, capping premium model penetration.
Strategic Opportunities
- India's BIS energy labeling expansion:Mandatory efficiency grades for small appliances create first-mover positioning for certified smart cooker imports.
- Voice-activated recipe integration:Convergence of Wi-Fi connectivity with Alexa and Google Home protocols opens kitchen automation cross-selling.
- Direct-to-consumer appliance subscription:Korean channel innovators bundle hardware with consumable rice delivery, locking recurring revenue streams.
Industry Challenges
- Embedded systems firmware talent scarcity:Shortage of engineers fluent in thermal control algorithms and IoT security protocols delays product cycles.
- Multi-jurisdiction certification stacking:Separate GB standard testing for China, METI filings for Japan, and CE marking for Europe fragment launch timelines.
- Legacy resistive heating inventory stranding:Conventional control model stockpiles lose value as urban buyers migrate to app-connected units.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Intelligent Electric Rice Cooker Market |
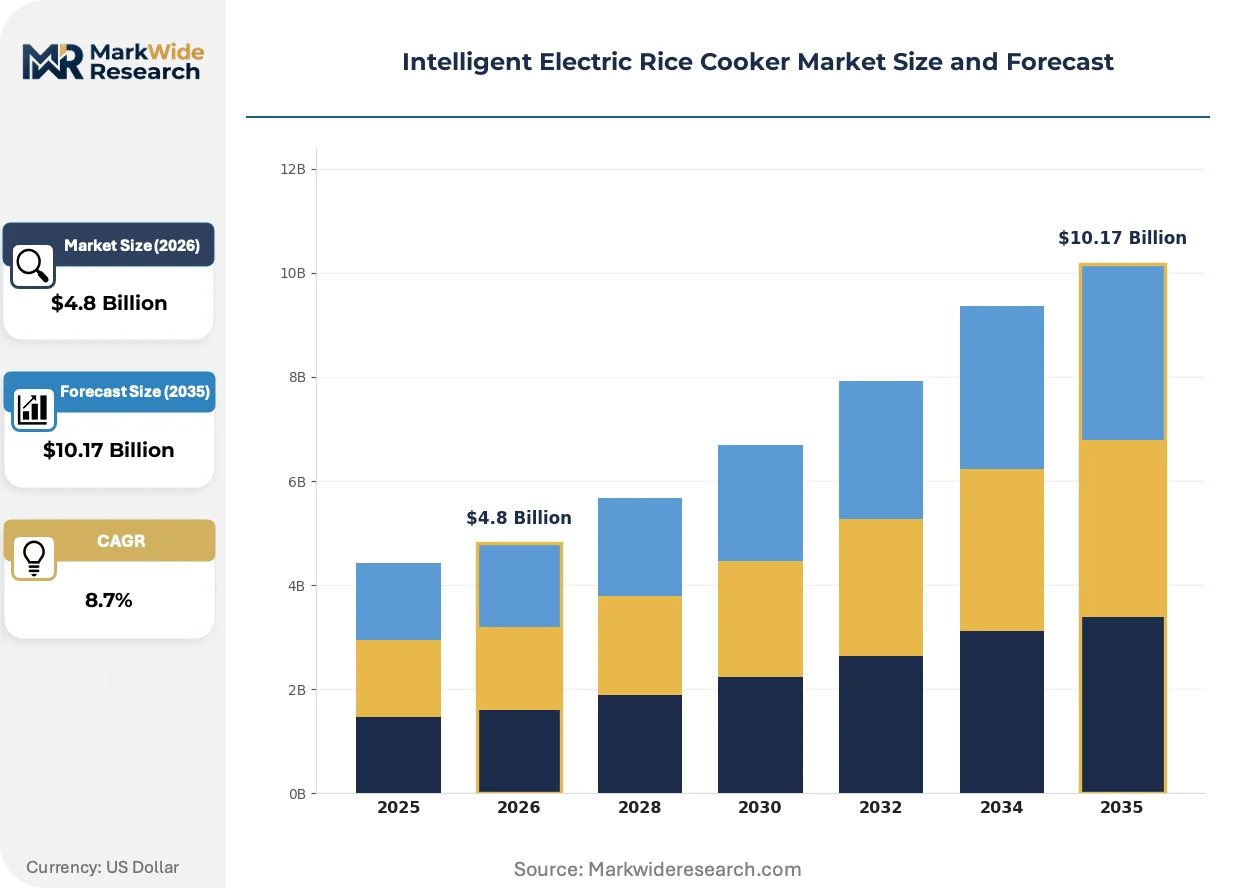
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $10.17 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Induction, Micom, Conventional, Steam Technology: Smart Control, Conventional Control, Programmable, Touchscreen End User: Households, Restaurants, Catering Services, Food Trucks Distribution Channel: Online Retail, Hypermarkets, Specialty Stores, Direct Sales |
| Companies Covered | Panasonic Corporation, Zojirushi Corporation, Tiger Corporation, Cuckoo Electronics Co., Ltd., Midea Group Co., Ltd., Xiaomi Corporation, Koninklijke Philips N.V., Breville Group Limited, Hamilton Beach Brands Holding Company, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Intelligent Electric Rice Cooker Market Trends and Innovations
Smart kitchen ecosystems are rewiring how cooking appliances integrate with grocery logistics and meal-planning platforms, shifting competitive advantage from hardware specs to data-layer stickiness.
Multi-stage pressure induction is decentralizing thermal control from centralized heating elements to distributed coil arrays that adjust zone temperatures independently. Premium Korean households are adopting these systems fastest, with apartment-dwelling dual-income families replacing conventional units within three-year cycles. This architecture is decentralizing manufacturing concentration by enabling modular assembly from standardized sensor and coil subsystems rather than integrated heating platforms.
China's SAMR compulsory energy efficiency labeling is tightening minimum performance thresholds for imported and domestic brands alike. The regulation forces redesigns of always-on Wi-Fi modules to reduce phantom power draw below prescribed wattage ceilings. Induction models with smart connectivity face the steepest engineering burden, with manufacturers absorbing certification costs to maintain urban shelf presence.
Urban buyer preference for app-based recipe libraries is fragmenting traditional retail dependence. Korean and Japanese consumers now research starch texture profiles and automated cooking programs before store visits, compressing the consideration phase. This behavioral shift is most pronounced in Seoul and Tokyo, where direct brand engagement through subscription services outperforms big-box conversion rates.
Intelligent Electric Rice Cooker Market Segmentation
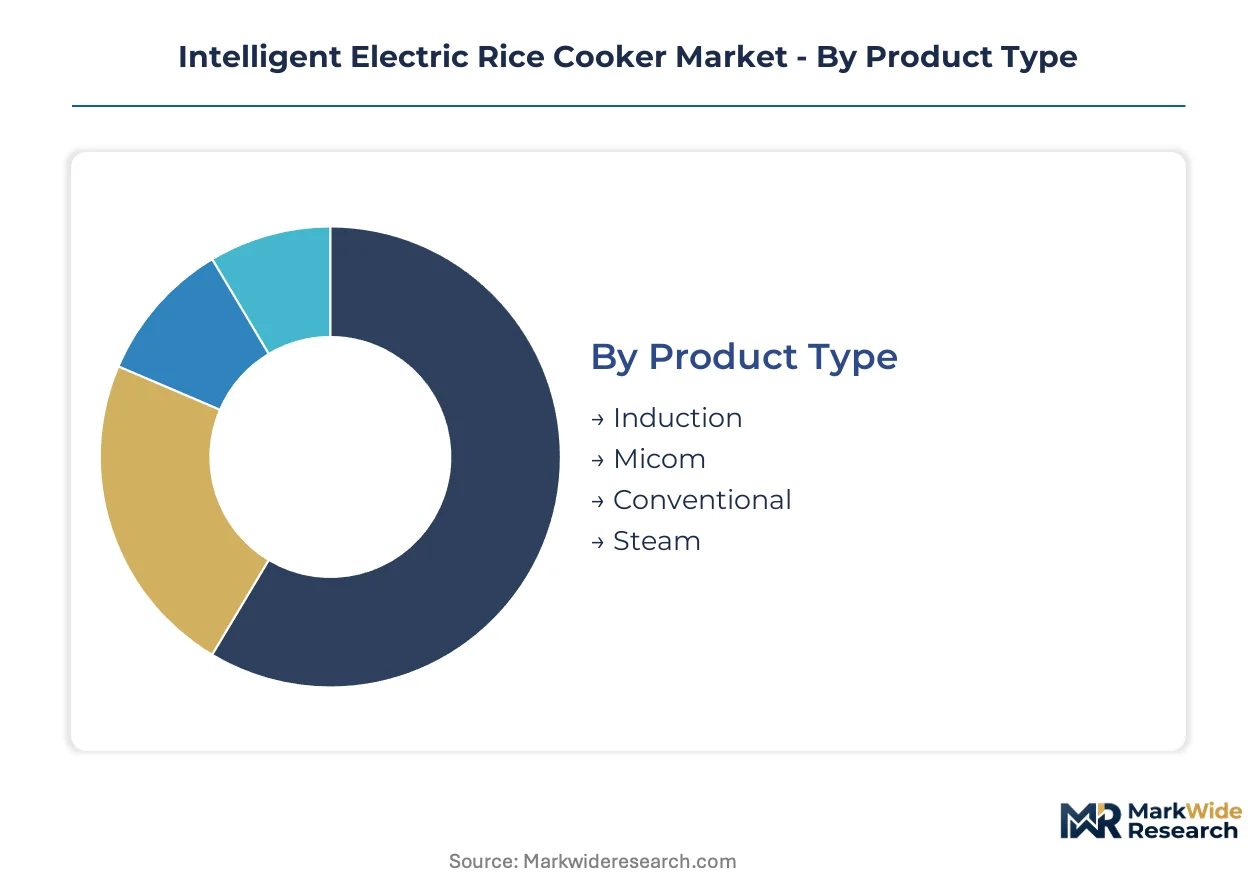
Segmentation in the intelligent electric rice cooker market reveals how cooking precision, connectivity, and channel access stratify buyer willingness to pay. Manufacturers configure component mixes and firmware capabilities differently across these divides to capture margin pools without fragmenting production economics.
Product Type:
Heating mechanism sophistication anchors price tier placement and determines which regulatory efficiency benchmarks each model must clear.
- Induction:Copper coil arrays generate magnetic fields that heat the inner pot directly, enabling precise zone temperature control. Seoul's premium apartment households absorb these units fastest as SAMR efficiency labeling and METI standby power rules squeeze conventional alternatives out of urban retail.
- Micom:Microprocessor-controlled thermal sensors automate multi-stage temperature curves for starch gelatinization without induction's coil costs. Micom units dominate shipment volumes across East Asian mass retail, though margin compression intensifies as basic fuzzy logic becomes commoditized.
- Conventional:Resistive heating elements with bimetallic thermostat switches serve price-sensitive rural markets in China and Southeast Asia where GB standard compliance suffices and app connectivity holds limited value.
- Steam:Dedicated steam injection chambers enable parallel vegetable and protein preparation. Health-conscious urban buyers in Tokyo and Osaka adopt these for meal-prep efficiency in compact kitchens.
Volume sits with Micom; growth tilts toward Induction.
Technology:
Control interface sophistication determines firmware development costs and IoT security exposure for manufacturers.
- Smart Control:Wi-Fi modules paired with app-based recipe libraries and voice assistant integration. Korean direct-to-consumer brands monetize these through consumable subscription bundles that lock recurring revenue.
- Conventional Control:Physical button panels with fixed program cycles and no connectivity. These sustain volume in India's emerging BIS-certified efficiency tiers where price elasticity remains acute.
- Programmable:LCD displays with user-defined temperature and timing sequences without cloud connectivity. Mid-tier Chinese households favor these for texture customization without smart home infrastructure investment.
- Touchscreen:Capacitive glass interfaces with visual feedback on cooking stages. Japanese premium retail channels stock these for design-conscious urban buyers seeking appliance-as-furniture aesthetics.
Conventional Control still moves the most units; Smart Control climbs the fastest as kitchen automation ecosystems mature.
End User:
Usage intensity and batch size requirements dictate heating element durability ratings and pot capacity configurations.
- Households:Single-family units with 1-10 cup capacities and emphasis on texture consistency for daily meals. East Asian dual-income households with limited cooking time represent the core revenue pool.
- Restaurants:Commercial-grade induction systems with 20+ cup capacities and rapid-cycle thermal recovery. Korean barbecue chains and Japanese izakaya networks standardize on these for rice quality consistency across locations.
- Catering Services:High-volume batch cooking with programmable delay starts for event timing. China's institutional foodservice sector sources these through B2B procurement platforms.
- Food Trucks:Compact 12V-compatible units with vibration-resistant construction. Urban mobile food operators in Seoul and Tokyo adopt these where space and power constraints intersect.
Households generate the revenue base; Restaurants deliver the steepest expansion trajectory as chain standardization accelerates.
Distribution Channel:
Channel selection determines margin capture, brand narrative control, and post-sale data access for firmware updates.
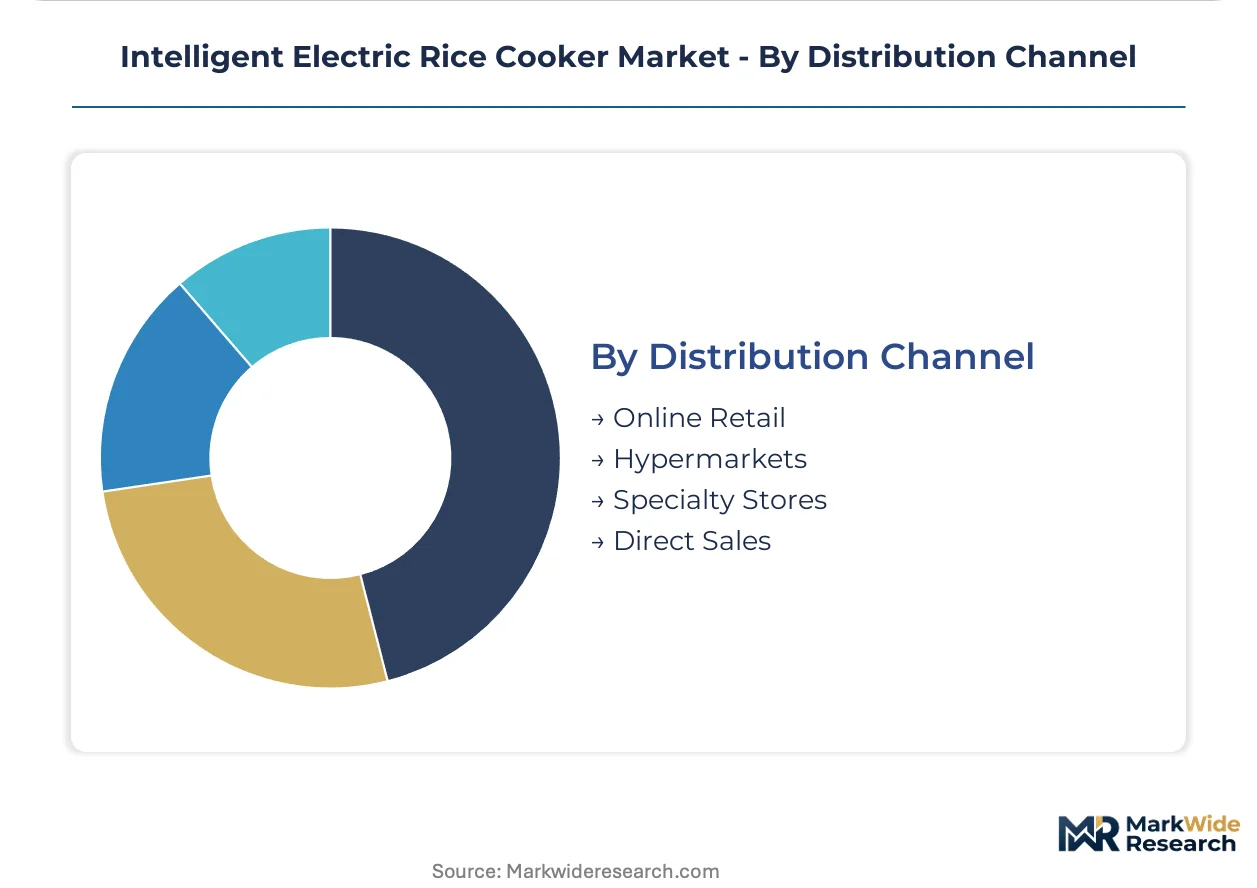
- Online Retail:E-commerce platforms with algorithmic recommendation engines and subscription bundling capabilities. Korean domestic brands dominate here through captive logistics networks.
- Hypermarkets:Big-box retail with tactile display units and immediate inventory availability. Chinese urban shoppers still validate smart cooker purchases in-store before ordering online.
- Specialty Stores:Kitchen appliance boutiques with trained staff demonstrating fuzzy logic and induction differences. Tokyo's Ginza and Seoul's Gangnam districts concentrate these for premium positioning.
- Direct Sales:Manufacturer-owned channels with trade-in programs and extended warranty bundles. Cuckoo Electronics leverages this structure in Korea to control pricing and capture customer relationship data.
Hypermarkets move the most volume; Direct Sales expands most quickly as subscription models reshape appliance economics.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Urban households in East Asia generate the steepest demand concentration for intelligent electric rice cookers, with Seoul, Tokyo, and Shanghai metro areas driving premium adoption cycles. Regulatory fragmentation across national efficiency regimes is reshaping which assembly footprints can serve multiple jurisdictions without redundant certification costs.
China
Dual-income households in Shanghai and Shenzhen are replacing conventional units with app-connected induction models at accelerated rates. SAMR's compulsory energy efficiency labeling gates market access for imported brands and forces redesigns of always-on Wi-Fi modules to reduce phantom power draw. The Yangtze River Delta manufacturing corridor hosts the densest concentration of component suppliers serving both domestic brands and export assembly.
Japan
Tokyo and Osaka apartment dwellers favor multi-function appliances with programmable starch profiles over single-purpose units as kitchen space contracts. METI enforces stringent standby power regulations that force component upgrades differentiating compliant brands in premium urban channels. The Kansai industrial belt maintains specialized production of fuzzy logic control systems and thermal sensor arrays.
South Korea
Seoul's premium apartment households absorb induction heating units fastest as connected cooking devices command sustained consumer loyalty. The country's national efficiency regulator mandates performance thresholds that compress design flexibility for multi-function cookers. Cuckoo Electronics anchors domestic channel control through direct-to-consumer distribution networks concentrated in the Seoul Capital Area.
United States
Asian-American households in California and New York Metro drive niche demand for high-end fuzzy logic and induction models. The FCC regulates Wi-Fi connectivity modules in smart kitchen appliances, adding certification layers for brands entering the market. West Coast electronics distributors are building specialty retail partnerships to serve this concentrated buyer segment.
India
Middle-class households in Maharashtra and Karnataka represent emerging demand as BIS energy labeling expansion creates first-mover positioning for certified smart cooker imports. The Bureau of Indian Standards mandates efficiency grades for small appliances that reshape procurement decisions for domestic distributors. Mumbai and Bangalore retail channels are testing premium positioning for Wi-Fi-enabled units ahead of broader market development.
Intelligent Electric Rice Cooker Market Competitive Landscape
Japanese producers anchor the premium tier; Korean specialists hold domestic channel dominance; Chinese fabricators capture volume scale. The vendor base stratifies across three functional tiers: technology licensors with captive sensor supply chains, direct-to-consumer subscription innovators, and contract assemblers serving price-sensitive markets. Strategic archetypes include fuzzy logic algorithm developers, induction coil specialists, and smart home ecosystem integrators. Competitive moves center on backward integration into component supply and geographic licensing partnerships to bypass certification stacking.
Among Japanese electronics conglomerates, Panasonic Corporation and Zojirushi Corporation occupy positions exemplifying vertical control over sensor supply chains and sustained R&D intensity in thermal control algorithms. Cuckoo Electronics Co., Ltd. represents the direct-to-consumer archetype, anchoring Korean domestic market positioning through captive distribution infrastructure.
| Leading Market Players |
|---|
| Panasonic Corporation |
| Zojirushi Corporation |
| Tiger Corporation |
| Cuckoo Electronics Co., Ltd. |
| Midea Group Co., Ltd. |
| Xiaomi Corporation |
| Koninklijke Philips N.V. |
| Breville Group Limited |
| Hamilton Beach Brands Holding Company |
| Others |
Pricing and Supply Chain Analysis
Firmware engineering talent shortages in the Yangtze River Delta and Kansai industrial belt widen pricing-tier spreads, as manufacturers absorb premium labor costs for IoT-thermal control specialists while standard Micom assembly migrates to lower-cost geographies. This labor-cost differential separates induction smart-control premiums from conventional resistive-heating economy tiers.
Pricing Analysis
Volume sits with Micom units while margins concentrate in induction smart-control models. Three-tier pricing structure across premium, standard, and economy levels separates app-connected induction systems with fuzzy logic customization from basic programmable Micom cookers and conventional resistive units. Price differentiation stems from certification grade—GB standard compliance versus METI standby power redesigns—and copper coil integration costs. Pricing pressure stems from copper price volatility compressing induction margins. Rural Chinese households exhibit acute price sensitivity; Seoul premium apartment buyers absorb connected-device premiums with minimal elasticity.
Supply Chain Analysis
Firmware engineering availability constrains production scaling in Japan's Kansai belt and South Korea's Seoul Capital Area, where thermal control algorithm specialists concentrate. Component supply draws from Japan for fuzzy logic sensors, South Korea for induction coil arrays, and China for resistive heating elements and Wi-Fi modules. Raw material dependencies center on copper for precision induction, ceramic coatings for inner pots, and semiconductor chips for smart connectivity. Single-source vulnerability runs through Japanese and Korean smelter concentration for copper coil supply. Distribution runs through Korean direct-to-consumer networks, Chinese hypermarket validation-to-online fulfillment, and Japanese specialty retail demonstration channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market is consolidating as multi-jurisdiction certification stacking forces smaller assemblers to exit or sell to integrated players with redundant testing infrastructure.
For Market Incumbents: Anchor premium positioning through captive fuzzy logic R&D in Kansai and backward integration into thermal sensor supply chains. Absorb METI and SAMR compliance costs to strand conventional-control inventory held by price-competitive rivals. Defend against emerging contract assemblers from China's Yangtze Delta by locking Seoul and Tokyo direct-to-consumer channel control. For New Entrants and Emerging Players: Begin with India's BIS-certified efficiency tier expansion, where first-mover positioning for smart cooker imports remains penetrable. Target Maharashtra and Karnataka middle-class households ahead of broader market development. Pursue voice-activated recipe integration with Alexa and Google Home protocols as the go-to-market wedge against established hardware brands. For Investors and Strategic Acquirers: Re-rating potential sits with induction coil specialists given copper supply concentration and Korean appliance brand loyalty. Long-term viability favors manufacturers with in-house fuzzy logic firmware capabilities and multi-jurisdiction certification infrastructure. Watch India's BIS enforcement rigor as the inflection signal for emerging market premiumization timing.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Sensor Supply | Panasonic's captive thermal sensor production absorbs METI compliance costs without margin erosion. |
| Direct-to-Consumer Subscription Launch | Cuckoo's rice-delivery bundling locks recurring revenue and captures customer relationship data in Seoul. |
| Voice Assistant Protocol Integration | Alexa and Google Home convergence opens kitchen automation cross-selling for Wi-Fi-enabled induction models. |
| Multi-Jurisdiction Certification Pre-Investment | Parallel GB standard, METI filing, and CE marking testing prevents launch timeline fragmentation. |
| Modular Coil Array Architecture Shift | Distributed zone-temperature systems enable assembly from standardized subsystems rather than integrated platforms. |
Research Methodology
Multi-period observation of copper price volatility, regulatory filing timelines, and smart kitchen adoption rates anchored the trend analysis, supplemented by interviews with appliance R&D directors, thermal sensor procurement leads, channel sales heads at Korean direct-to-consumer networks, and regulatory affairs specialists at Japanese electronics conglomerates. Secondary validation drew from SAMR energy efficiency labeling databases, METI standby power compliance filings, customs records for induction coil trade flows, and SEC 10-K disclosures from listed appliance manufacturers. Bottom-up shipment modeling and top-down consumer expenditure triangulation cross-checked volume estimates.
Segment-weighting across heating mechanism, control technology, end-user intensity, and distribution channel dimensions shaped the analytical framework over the projection horizon. CAGRs derived from fitted growth curves applied to urban household penetration rates and replacement cycle compression in East Asian metro areas. Industry-specific inputs included fuzzy logic algorithm patent filings, copper coil supplier concentration indices, and app-connected recipe library adoption metrics.
Underlying measurement precision varies by segment; smart-control technology and Seoul-Tokyo household demand carry tighter precision than rural conventional-control volumes and emerging Indian market development. Forecasts reflect assumptions about regulatory enforcement continuity, copper supply stability, and firmware engineering labor availability. Material deviation in BIS certification rigor, METI standby power threshold adjustments, or induction coil supplier consolidation warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Appliances
Europe Garment Steamers Market
Appliances
Microwave Oven Market
Appliances
Tumble Dryer Market
Appliances
Under Counter Dishwasher Market
Appliances
Household Beauty Appliances Market
Appliances
Qatar Dishwashers Market
Appliances
Kuwait Dishwasher Market
Appliances
Consumer Appliances Market
Appliances
Smart Washing Machine Market
Appliances
Microwave Market
Appliances
Water Heater Market
Appliances
Household Vacuum Cleaners Market
Appliances
Middle East Portable Washing Machines Market
Appliances
United Kingdom Compact Dishwasher Market
Appliances
Saudi Arabia Water Heater Market
Appliances
Garments Steamer Market