
 Plastic Carafe Market | 2026-2036
Plastic Carafe Market Size, Share, and Industry Trends Forecast 2026-2036
Plastic Carafe Market Analytics
REACH compliance is consolidating the cost-of-entry calculus for European suppliers of food-contact plastic carafes. Berry Global Inc. leverages its multi-site extrusion footprint to sustain compliance testing economies across EU member states. Amcor plc anchors its position through in-house migration testing protocols that preempt regulatory delays. ALPLA competes on blow-molding scale, converting rPET flake into carafe preforms at integrated Central European facilities.
A plastic carafe denotes a molded polymer vessel, typically 0.5–2.0 liters in capacity, engineered from PET, polycarbonate, or ABS via injection stretch blow molding or extrusion blow molding, designed for repeated liquid storage and tabletop service. Kitchen carafes dominate unit volume among product types, though beverage dispensers command wider diameter specifications and thicker wall sections that elevate per-unit resin content. Household use anchors demand within applications, while catering services represent the fastest-expanding channel as event operators replace glass with shatter-resistant alternatives. Polycarbonate grades sustain premium positioning in hospitality due to thermal shock tolerance and clarity retention, whereas polyethylene terephthalate occupies mainstream retail through lower material cost and established recycling infrastructure.
FDA food-contact notification requirements govern US market entry, while ECHA REACH restrictions on bisphenol-A migration constrain polycarbonate formulation choices across Europe. BIS certification for food-grade plastics shapes access protocols for suppliers targeting Indian institutional buyers. Stakeholders must monitor evolving state-level extended producer responsibility frameworks and decide whether to regionalize material specifications or pursue universal resin platforms that absorb compliance variance.
Market Dynamics
EU Single-Use Plastics Directive enforcement is redirecting commercial procurement toward durable polymer alternatives, compressing demand for disposable beverage containers while elevating certified reusable carafes in hospitality and institutional channels.
Growth Catalysts
- REACH compliance consolidation:ECHA migration testing protocols are raising barriers for non-specialized molders, concentrating volume among suppliers with captive laboratory infrastructure.
- rPET flake conversion scale:Integrated blow-molding facilities in Central Europe are converting post-consumer flake into food-contact preforms at throughput levels that undercut virgin resin economics.
- German hospitality procurement:Institutional catering chains in Germany favor certified polycarbonate carafes for thermal shock tolerance and operational longevity in front-of-house service.
Market Restraints
- Polycarbonate formulation constraints:ECHA bisphenol-A migration limits are constraining resin choices for premium hospitality grades, forcing reformulation cycles that extend development timelines.
- Resin input volatility:PET and polycarbonate pellet pricing fluctuates with crude oil derivatives and recycled flake availability, compressing margin predictability for converters.
- Glass substitution persistence:High-end sommelier service and wine tourism operators retain preference for borosilicate glass despite shatter-risk premiums, capping polymer penetration in prestige segments.
Strategic Opportunities
- Indian institutional certification:BIS food-grade plastic certification protocols are creating first-mover advantages for suppliers establishing testing partnerships with domestic laboratories.
- Extended producer responsibility frameworks:State-level EPR mandates in multiple US jurisdictions are incentivizing closed-loop takeback programs that lock in long-term supply agreements.
- Smart dispensing integration:RFID-enabled carafe bases are converging with IoT beverage management systems in corporate catering, enabling usage-based service models.
Industry Challenges
- Migration testing backlog:FDA food-contact notification queues and ECHA substance evaluation delays are extending time-to-market for novel polymer grades.
- Multi-site compliance synchronization:Suppliers operating extrusion networks across EU member states must harmonize batch testing protocols to prevent regulatory fragmentation.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Plastic Carafe Market |
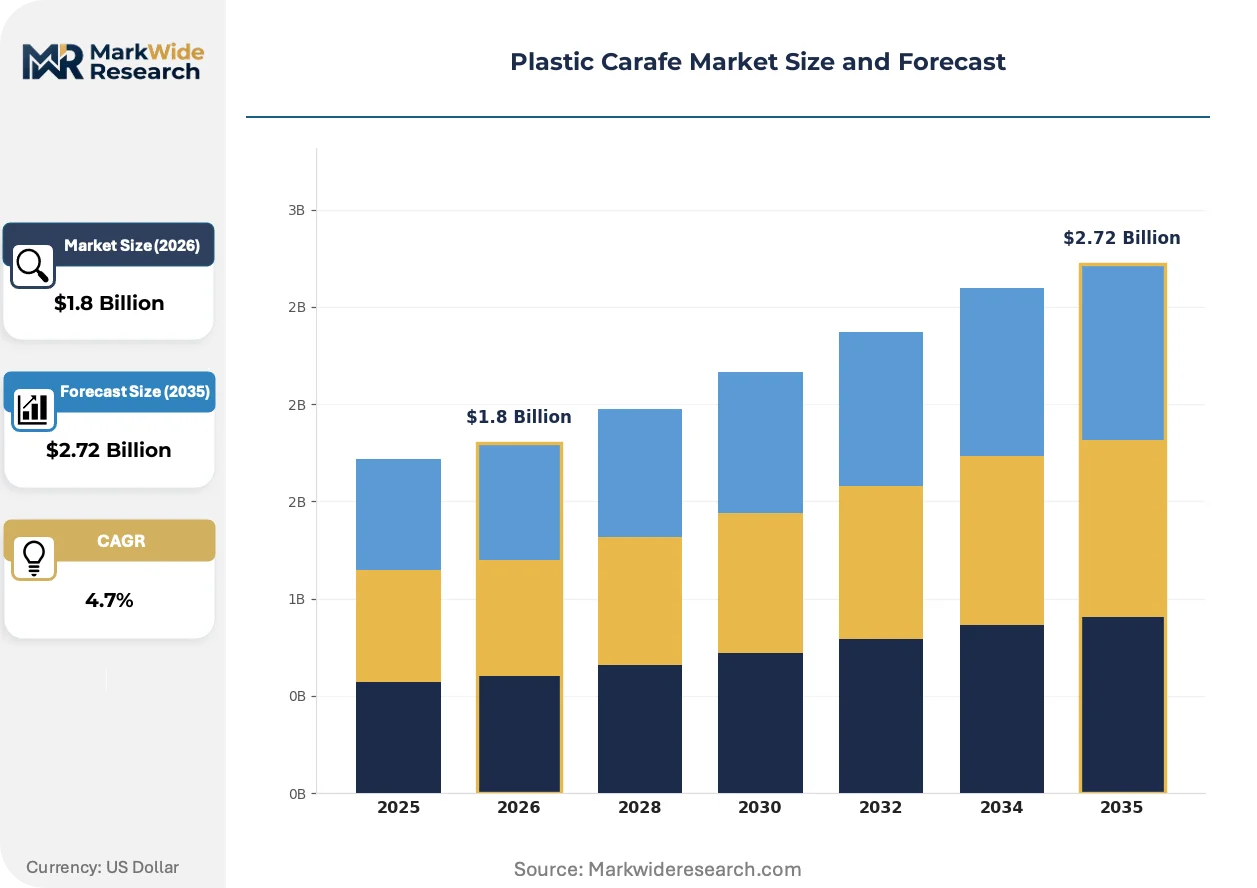
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.72 Billion |
| CAGR (2026 – 2036) | 4.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Kitchen Carafes, Beverage Dispensers, Water Bottles, Wine Containers Application: Household Use, Catering Services, Restaurants, Events End User: Individuals, Hospitality Industry, Retail Stores, Wholesale Distributors Material: Polyethylene Terephthalate, Polycarbonate, Acrylonitrile Butadiene Styrene, Others |
| Companies Covered | Berry Global Inc., Amcor plc, ALPLA, Plastipak Packaging, Sonoco Products Company, Alpha Packaging, Greiner Packaging, Graham Packaging, Altium Packaging, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Plastic Carafe Market Evolving Landscape
Active material science advances and regulatory chemistry restrictions are simultaneously enabling and constraining product development trajectories in food-contact polymer vessels.
Injection stretch blow molding automation is converging with inline vision inspection systems to enable zero-defect output at cycle speeds below four seconds per carafe unit. Tier-one hospitality suppliers in Germany and France are adopting these integrated lines to satisfy chain-level quality agreements. The technology is converging with predictive maintenance algorithms that compress unplanned downtime and extend asset utilization rates.
EU F-Gas Regulation phase-down schedules are pressuring refrigeration-dependent beverage dispenser formats, indirectly elevating ambient-service carafe designs that eliminate cooling hardware. Polycarbonate grades with enhanced thermal insulation properties are capturing specification share in self-serve catering installations. German event operators are responding by procuring double-wall carafes that maintain serving temperature without auxiliary power.
Certification-driven specification lock-in is displacing price-first procurement in European institutional channels. Catering procurement officers now mandate REACH-compliant documentation and migration test certificates prior to vendor qualification, compressing the approved supplier base. This pattern is most visible in French and Dutch hospital and university foodservice contracts, where compliance documentation outweighs unit cost in award criteria.
Plastic Carafe Market Segmentation
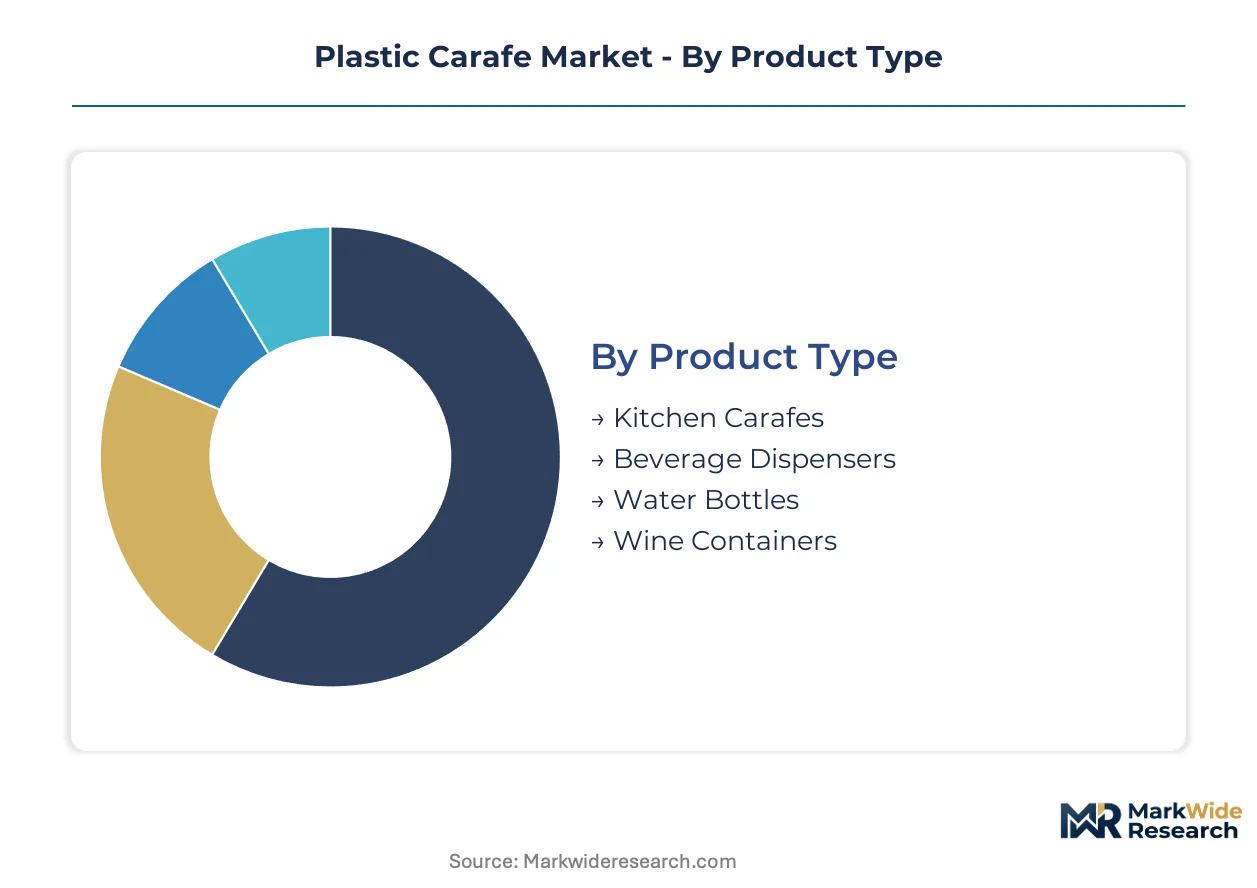
Carafe procurement patterns diverge sharply across use environments. Material selection and wall-thickness specifications determine compliance pathways and replacement cycles. Understanding segment-specific capital requirements illuminates where converters earn durable margin premiums versus commodity throughput.
Product Type:
Capital intensity escalates with vessel diameter and wall-section complexity. Injection stretch blow molding lines for wide-mouth beverage dispensers demand higher clamp-force machinery and longer cooling cycles than narrow-neck kitchen formats.
- Kitchen Carafes:Narrow-neck vessels of 0.5–1.5 liter capacity dominate unit economics through high-cavity molds and sub-four-second cycle times. German household retailers specify these for countertop water service with EFSA-compliant PET grades.
- Beverage Dispensers:Wide-diameter formats with 2.0+ liter capacity require thicker wall sections and integrated tap hardware that elevates per-unit resin content by 40–60%. French institutional catering contracts specify these for self-serve installations.
- Water Bottles:Portable formats with threaded closures compete on lightweighting efficiency and thread-precision molding.
- Wine Containers:Specialty shapes with UV-barrier additives target hospitality preservation applications.
Most installed capacity flows through Kitchen Carafes. Expansion is steepest in Beverage Dispensers.
Application:
Procurement authority concentrates differently across use cases. Household buyers prioritize shelf price and dishwasher durability. Commercial operators weight total cost of ownership including breakage replacement and compliance documentation.
- Household Use:Mass-market retail channels in the US and Germany absorb high-volume PET carafes for daily beverage storage. FDA food-contact notification requirements govern shelf placement.
- Catering Services:Event operators across France and the Netherlands specify shatter-resistant polycarbonate for outdoor service where glass liability costs exceed polymer premiums. ECHA migration certificates are mandatory in contract awards.
- Restaurants:Front-of-house service demands clarity retention and thermal shock tolerance for hot-fill applications.
- Events:Temporary installations favor lightweight disposable-adjacent formats with minimal post-event recovery obligations.
Volume concentrates in Household Use. Catering Services are climbing the fastest as single-use plastics directives redirect procurement.
End User:
Buying power and specification sophistication vary dramatically across customer types. Wholesale distributors aggregate fragmented demand while hospitality chains centralize technical requirements.
- Individuals:Price-sensitive consumers in retail environments drive commoditization of standard PET carafes with minimal feature differentiation.
- Hospitality Industry:German hotel chains and French restaurant groups mandate REACH-compliant documentation and batch traceability, consolidating supply among qualified molders with captive testing labs.
- Retail Stores:Private-label programs demand flexible tooling for seasonal shape variations and color matching.
- Wholesale Distributors:Inventory pooling across multiple end-use segments requires generic specifications that trade performance optimization for SKU efficiency.
Procurement volume flows through Hospitality Industry channels. Retail Stores are gaining share fastest as private-label programs expand.
Material:
Resin selection governs thermal performance, clarity, and regulatory compliance scope. Each polymer platform carries distinct testing burdens and recycling pathway economics.
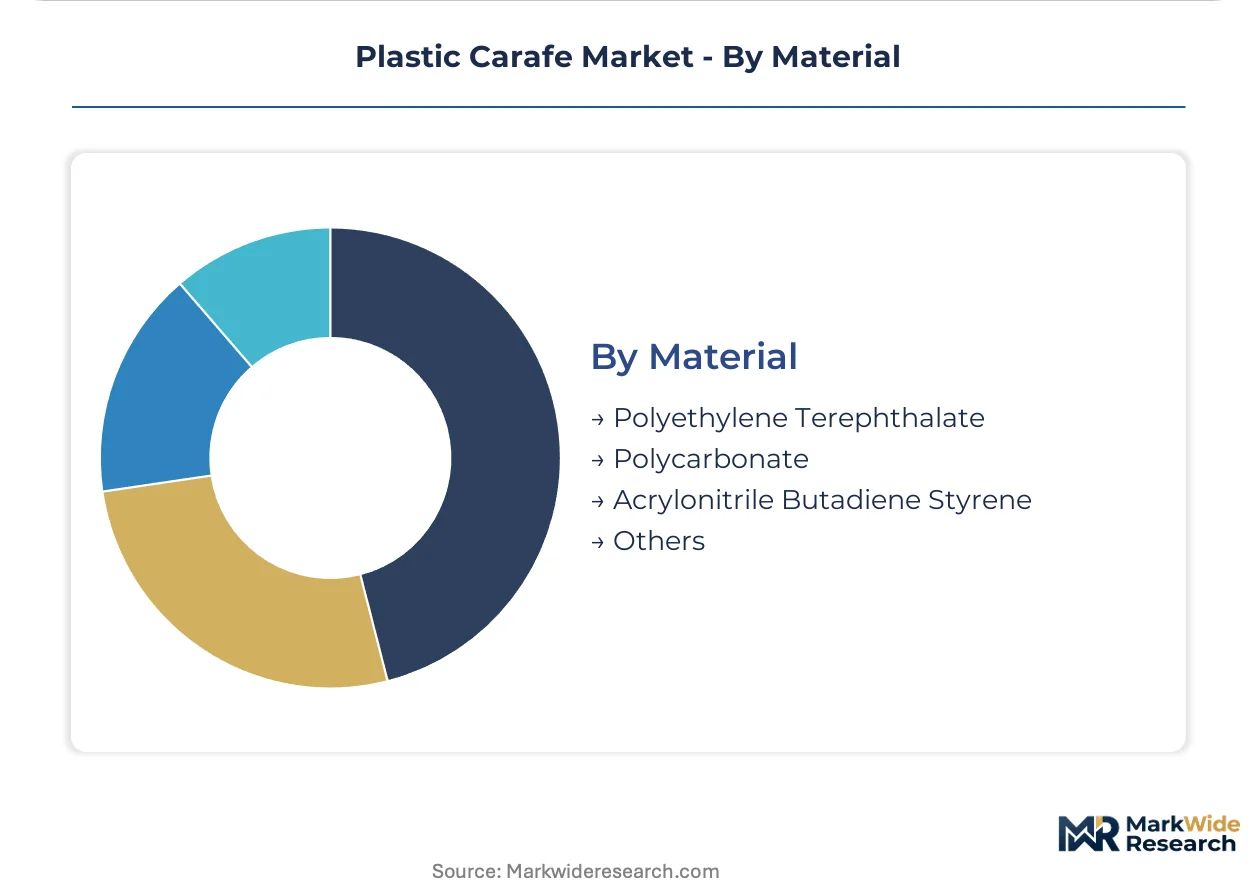
- Polyethylene Terephthalate:Virgin and rPET grades dominate mainstream retail through lower material cost and established mechanical recycling infrastructure. Central European converters achieve cost parity with virgin resin at integrated flake-to-preform facilities.
- Polycarbonate:Premium hospitality specifications in Germany leverage thermal shock tolerance and optical clarity for hot-beverage service. ECHA bisphenol-A migration limits constrain formulation flexibility and extend development timelines.
- Acrylonitrile Butadiene Styrene:Lower-cost opaque formats target utility storage applications where clarity is non-critical.
- Others:Bio-based and copolyester alternatives occupy niche sustainability-positioned segments with limited volume scale.
Production capacity concentrates in Polyethylene Terephthalate. Polycarbonate is expanding most quickly in premium hospitality channels.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Skilled polymer engineering talent clusters in Germany's Ruhr industrial corridor and China's Yangtze River Delta anchor global production capacity for food-contact molded vessels. Technical workforce density in these regions sustains advanced blow-molding automation and regulatory compliance infrastructure that smaller markets cannot replicate.
Germany
Hospitality procurement officers at institutional catering chains prioritize certified polycarbonate carafes for thermal shock performance in front-of-house service. ECHA REACH compliance mandates migration testing documentation that consolidates supply among qualified molders with captive laboratory infrastructure. Manufacturing concentrates in North Rhine-Westphalia, where integrated extrusion facilities convert rPET flake into food-contact preforms at scale.
United States
Event operators and corporate catering services are replacing glass with shatter-resistant polymer alternatives to reduce liability exposure and breakage replacement costs. FDA food-contact notification requirements govern shelf placement in mass-market retail channels. Production gravity sits in Ohio and Illinois, where multi-site extrusion networks serve household and commercial demand through established distribution corridors.
France
Hospital and university foodservice contracts now mandate REACH-compliant documentation and migration test certificates prior to vendor qualification, compressing the approved supplier base. EU F-Gas Regulation phase-down schedules are elevating ambient-service carafe designs that eliminate cooling hardware. Industrial activity clusters in Île-de-France, where procurement officers specify double-wall polycarbonate formats for self-serve catering installations.
India
Institutional buyers in hospitality and catering channels are redirecting procurement toward durable polymer alternatives as single-use plastics face mounting regulatory pressure. BIS certification for food-grade plastics shapes access protocols for suppliers targeting domestic commercial buyers. Manufacturing expansion concentrates in Maharashtra and Gujarat, where converters are establishing testing partnerships with domestic laboratories to secure first-mover positioning.
China
Export-oriented molders serving European and North American private-label programs are investing in inline vision inspection systems to satisfy chain-level quality agreements. GB standards for food-contact plastics govern domestic market entry, while dual carbon goals are pressuring energy-intensive extrusion operations toward efficiency upgrades. Production concentrates in the Yangtze River Delta, where automation convergence with predictive maintenance algorithms is compressing unplanned downtime.
Plastic Carafe Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across tiered market positions. Consolidation pressure is elevating scale requirements for REACH compliance testing and multi-site batch protocol harmonization. Three archetypes dominate: integrated resin-to-carafe converters with captive flake processing, specialized hospitality-grade molders with thermal shock formulation expertise, and private-label contract manufacturers serving retail channel volatility. Competitive moves center on backward integration into rPET flake supply and geographic expansion through qualified supplier status in institutional procurement frameworks.
Within the diversified packaging conglomerate tier, Berry Global Inc., Amcor plc, and ALPLA exemplify scale-driven positions. Berry Global leverages multi-site extrusion footprints to sustain compliance testing economies across EU member states. Amcor anchors positioning through in-house migration testing protocols that preempt regulatory delays. ALPLA competes on blow-molding scale, converting rPET flake into carafe preforms at integrated Central European facilities. These three represent the compliance-capable supplier base that institutional procurement officers in Germany and France increasingly favor.
| Leading Market Players |
|---|
| Berry Global Inc. |
| Amcor plc |
| ALPLA |
| Plastipak Packaging |
| Sonoco Products Company |
| Alpha Packaging |
| Greiner Packaging |
| Graham Packaging |
| Altium Packaging |
| Others |
Value Network & Pricing Analysis
Polymer engineering talent clustering in Germany's Ruhr industrial corridor and China's Yangtze River Delta anchors labor-cost differentials that widen pricing-tier spreads between premium REACH-certified polycarbonate carafes and commodity PET formats.
Pricing Analysis
Bundled compliance documentation and migration testing certificates separate premium hospitality procurement from unbundled retail transactions. Three-tier pricing structure across certified premium, standard food-grade, and economy utility levels reflects EFSA compliance grade and volume scale. Price differentiation hinges on thermal shock tolerance certification and captive laboratory infrastructure. Catering services in France and Germany exhibit lowest price sensitivity due to total-cost-of-ownership procurement frameworks, while individual retail buyers drive commoditization of standard PET formats.
Supply Chain Analysis
Domestic-content mandates in India's Maharashtra and Gujarat states are reshaping sourcing protocols for BIS-certified food-grade carafes. Manufacturing concentrates in Germany, China, and India. Raw material flows draw from virgin PET pellet producers, rPET flake processors, and polycarbonate resin compounders. Single-source vulnerability in ECHA-certified laboratory capacity creates bottleneck risk for European qualification pathways. Distribution runs through wholesale distributors pooling inventory across hospitality chains and retail private-label programs.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The plastic carafe market functions as a stable compounder, with regulatory-driven replacement cycles in European institutional channels delivering predictable procurement volumes.
For Market Incumbents: Extend captive migration testing infrastructure to preempt FDA notification queues and ECHA substance evaluation delays. Deepen backward integration into rPET flake supply through Central European preform conversion facilities. Consolidate multi-site batch protocol harmonization to defend against regulatory fragmentation penalties.
For New Entrants and Emerging Players: Begin with BIS certification partnerships in Maharashtra and Gujarat to capture Indian institutional catering procurement redirection. Target event operator segments in France and the Netherlands where shatter-resistant specifications displace glass. Pursue private-label contract manufacturing for retail channel volatility absorption.
For Investors and Strategic Acquirers: Packaging conglomerates with food-contact compliance capabilities are the most active acquirer in this space. Five-to-ten year viability rests on REACH certification moats and rPET conversion scale. Acquisition targets include specialized hospitality-grade molders with thermal shock formulation expertise. Monitor state-level extended producer responsibility framework adoption as inflection signal for closed-loop takeback program economics.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into rPET Flake | Central European converters achieve cost parity with virgin resin through captive flake-to-preform facilities. |
| REACH Compliance Certification Investment | German hospital and university foodservice contracts mandate migration documentation prior to vendor qualification. |
| Smart Dispensing IoT Integration | RFID-enabled carafe bases converge with corporate catering beverage management systems for usage-based service models. |
| Indian BIS Testing Partnership | Maharashtra and Gujarat laboratory collaborations secure first-mover positioning in institutional procurement redirection. |
| Extended Producer Responsibility Program | State-level EPR mandates in US jurisdictions incentivize closed-loop takeback agreements locking in long-term supply. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window. Primary fieldwork engaged blow-molding plant managers, hospitality procurement officers at German and French institutional chains, rPET flake processors, and retail private-label program directors. Secondary validation drew from ECHA substance evaluation databases, FDA food-contact notification filings, EU customs trade records, and BIS certification registries. Bottom-up segment sizing and top-down macroeconomic anchoring were triangulated for convergence.
Segment-weighting approaches distributed volume and value across material grade tiers, application environments, and regional regulatory clusters throughout the forecast period. Kitchen carafes, beverage dispensers, and portable formats were modeled separately with distinct replacement cycle assumptions. CAGRs were derived from installed base growth and per-unit resin content trajectories. Inputs included EU Single-Use Plastics Directive enforcement schedules and F-Gas Regulation phase-down impacts on dispenser format demand.
Caveats apply where ECHA bisphenol-A migration limit revisions or PET pellet price volatility could materially shift the outlook. Forecasts reflect assumptions about regulatory enforcement continuity and rPET flake supply scaling. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Household Items
Cast Iron Cookware Market
Household Items
Coin-Operated Laundries Market
Household Items
Turkey Cookware Market
Household Items
Global Humidifier Market
Household Items
Sanitary Napkin Receptacles Market
Household Items
United States Smart Shower Market
Household Items
Smart Bathroom Products Market
Household Items
Air Humidifier Market
Household Items
France Digital Showers Market
Household Items
Brazil Cookware Market
Household Items
Shoe Shine Machine Market
Household Items
Cat Hair Remover Market
Household Items
Dry and Wet Wipes Market
Household Items
Command Hooks Market
Household Items
Global Buddhist Supplies Market
Household Items
North America Glassware Market