
 Gravity Conveyor Market | 2026-2036
Gravity Conveyor Market Size, Share, and Industry Trends Forecast 2026-2036
Gravity Conveyor Market Foresight
The distributor channel for gravity conveyor systems is narrowing as direct manufacturer engagement with large end-users intensifies. Interroll Holding AG leverages its modular platform strategy to capture specification authority at the project design stage. Daifuku Co., Ltd. anchors its position through captive relationships with automotive OEMs in high-volume assembly environments. Hytrol Conveyor Company, Inc. differentiates by sustaining domestic manufacturing scale that supports rapid custom configuration turnaround.
A gravity conveyor is an unpowered materials handling system that relies on gravitational force and slight downward inclination to move goods across rollers, skate wheels, or sliding surfaces, typically operating at slopes between 1.5 and 5 degrees depending on load weight and surface material. Its primary industrial purpose centers on cost-efficient transport, accumulation, and sortation of unit loads in environments where powered automation proves economically unjustified or where energy minimization constitutes an operational priority. Roller conveyors dominate permanent installations in heavy manufacturing due to their load-bearing capacity and durability under continuous cycling, while flexible and skate wheel variants capture growth in portable and modular configurations driven by seasonal demand fluctuation and temporary facility layouts. The logistics end-user segment exhibits the most dynamic expansion as third-party fulfillment operators reconfigure warehouse footprints to accommodate SKU proliferation and same-day delivery commitments.
The Occupational Safety and Health Administration in the United States and the EU Machinery Directive govern guardrail spacing, emergency stop placement, and load rating disclosure, compelling manufacturers to certify designs against pinch-point and entrapment hazards before market entry. ISO 340 and EN 12882 standards for conveyor belting and roller fire resistance further constrain material selection in airports, underground mining, and cold-storage applications. Stakeholders must monitor evolving carbon-border adjustment mechanisms and embodied-carbon disclosure rules that threaten to reclassify steel-intensive conveyor systems as taxable imports in key European markets.
Market Dynamics
Warehouse operators are compressing conveyor replacement cycles as e-commerce fulfillment velocity demands force infrastructure obsolescence within five-to-seven-year horizons rather than the traditional fifteen-year depreciation schedules.
Growth Catalysts
- OSHA ergonomic mandates:The US Occupational Safety and Health Administration has tightened manual lifting limits in distribution centers, accelerating specification of gravity-fed accumulation systems that reduce worker strain during parcel sortation.
- Modular retrofit architectures:Flexible skate wheel and expandable roller configurations enable seasonal warehouse reconfiguration without structural modification, capturing demand from third-party logistics providers managing holiday volume spikes.
- Germany's automotive corridor:Dense clustering of final assembly plants along the Baden-Württemberg to Bavaria axis sustains demand for heavy-duty roller conveyors in just-in-sequence component delivery.
Market Restraints
- Steel price volatility:Galvanized steel roller tubes constitute sixty percent of system material cost, exposing manufacturers to scrap metal index fluctuations that compress bid-quote validity windows.
- Substitution by AMR fleets:Autonomous mobile robots with conveyor-top modules are capturing light-load transport tasks previously assigned to fixed gravity lines in micro-fulfillment centers.
- REACH substance restrictions:The European Chemicals Agency has classified certain zinc coating processes as Substances of Very High Concern, forcing reformulation of corrosion-resistant roller finishes.
Strategic Opportunities
- India's warehouse modernization:The country's PLI scheme for logistics infrastructure is subsidizing automation capex in emerging e-commerce hubs around Mumbai and Bangalore.
- Cold-chain pharmaceutical handling:Temperature-controlled vaccine distribution networks require stainless steel gravity systems with FDA-compliant sanitary designs for biologics staging.
- Carbon border adjustment arbitrage:EU importers of Chinese-manufactured conveyors face embodied-carbon tariffs, creating opening for domestic European fabricators with verified low-carbon steel sourcing.
Industry Challenges
- Conveyor integration complexity:Retrofitting gravity lines into existing WMS-controlled environments requires custom PLC programming that stretches project timelines and strains systems integrator capacity.
- Fire certification backlogs:ISO 340 and EN 12882 testing queue delays at notified bodies are extending product launch timelines by four to six months for mining and airport applications.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Gravity Conveyor Market |
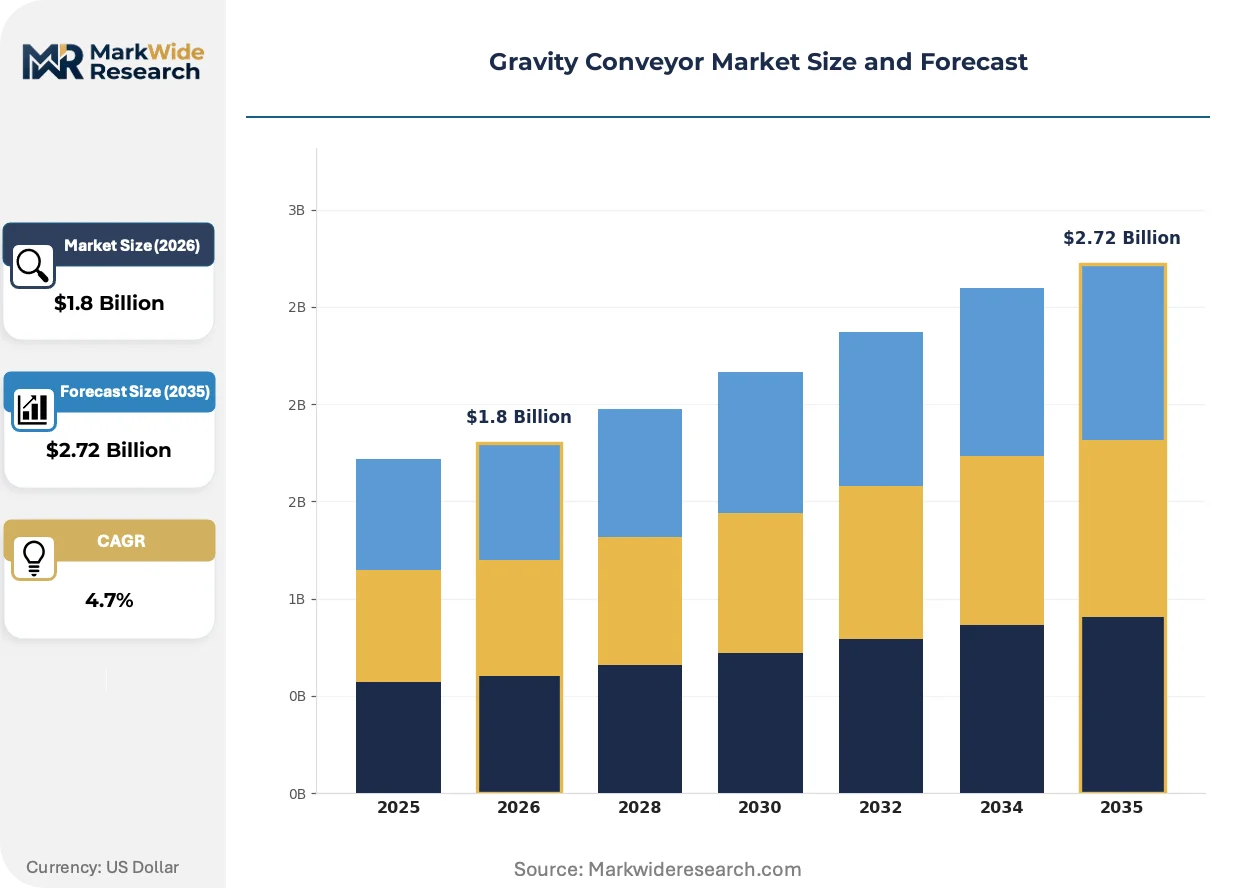
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.72 Billion |
| CAGR (2026 – 2036) | 4.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Roller Conveyor, Skate Wheel Conveyor, Flexible Conveyor, Pallet Conveyor End User: Manufacturing, Logistics, Automotive, Retail Installation: Permanent, Portable, Customizable, Modular Conveyor Size: Small, Medium, Large, Extra Large |
| Companies Covered | Interroll Holding AG, Daifuku Co., Ltd., Hytrol Conveyor Company, Inc., Dematic, Honeywell Intelligrated, SSI Schaefer, LEWCO Inc., Fives Group, TGW Logistics Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Gravity Conveyor Market Shifts & Advancements
Gravity conveyor engineering is pivoting from static infrastructure toward adaptive systems that reconfigure without mechanical disassembly, driven by warehouse operators treating floor space as a dynamically allocated resource rather than fixed capital.
Composite polymer rollers with embedded fiber reinforcement are rendering obsolete traditional steel tube designs in corrosive environments. Chemical processors and coastal distribution centers in the Netherlands and Singapore have adopted these modules for salt-air and caustic washdown resistance. The shift is compressing supplier margins on metal-forming equipment while elevating compound formulation chemistry as a core competency.
The EU Machinery Directive's 2023 amendment on collaborative human-robot interfaces now mandates light-curtain and pressure-sensitive edge guarding on all new gravity installations exceeding two meters in elevation. German system integrators have responded by pre-certifying modular guardrail kits that reduce site-specific engineering. French and Italian end-users face six-month compliance retrofit deadlines on legacy lines.
Third-party logistics operators are unbundling conveyor procurement from turnkey material handling contracts, establishing direct specification relationships with component manufacturers. This disintermediation is visible most acutely in the Netherlands' Rotterdam port logistics cluster, where fulfillment operators now issue separate RFPs for roller modules, frames, and controls. Distributor margins are compressing as a result.
Gravity Conveyor Market Segmentation
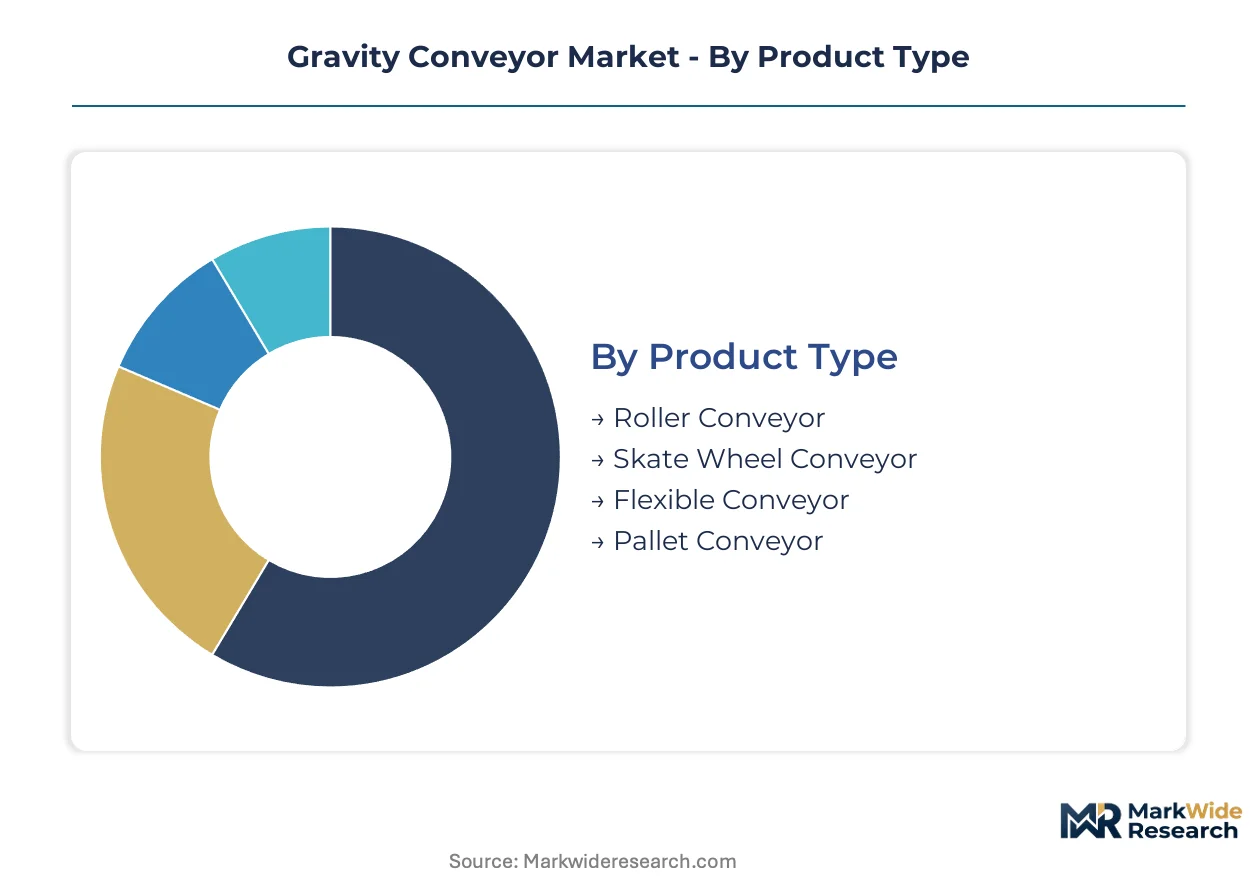
Gravity conveyor procurement patterns diverge sharply across product architectures and deployment contexts. End-user operational tempo and facility lifecycle expectations determine specification authority and supplier engagement models.
Product Type:
Mature roller designs dominate capital-intensive installations while emerging flexible formats capture seasonal reconfiguration demand.
- Roller Conveyor:Steel or polymer tube assemblies mounted on precision bearings handle unit loads exceeding 50 kilograms across continuous duty cycles. German automotive assembly plants along the Baden-Württemberg corridor specify heavy-duty galvanized variants for just-in-sequence component delivery, though steel price volatility compresses manufacturer margins. Roller conveyors retain volume leadership; flexible conveyors hold the steepest expansion curve.
- Skate Wheel Conveyor:Multiple free-rotating wheels on common axles reduce rolling resistance for lightweight parcel handling. Third-party logistics operators in Netherlands fulfillment clusters deploy skate wheel modules for rapid seasonal lane reconfiguration without structural modification, driven by same-day delivery velocity requirements.
- Flexible Conveyor:Collapsible accordion frames with skate wheel or roller surfaces enable temporary layout adaptation. E-commerce peak season demand in China's Yangtze River Delta logistics hubs accelerates procurement of expandable units.
- Pallet Conveyor:Reinforced roller chains or heavy-duty tube assemblies engineered for 1,000+ kilogram palletized loads. Cold-storage pharmaceutical distributors specify stainless steel variants for FDA-compliant biologics staging.
Roller conveyors retain volume leadership; flexible conveyors hold the steepest expansion curve.
End User:
Application intensity separates high-throughput continuous operations from intermittent handling environments.
- Logistics:Third-party fulfillment operators reconfigure warehouse footprints to accommodate SKU proliferation and delivery compression mandates. OSHA ergonomic mandates in US distribution centers accelerate gravity-fed accumulation system deployment for parcel sortation strain reduction.
- Manufacturing:Assembly line feed and work-in-process buffering rely on fixed-gradient roller systems. REACH substance restrictions on zinc coating processes force reformulation of corrosion-resistant finishes for European industrial deployments.
- Automotive:Final assembly plants require precision-timed component delivery synchronized to takt time. Daifuku maintains captive relationships with Japanese and German OEMs for high-volume assembly environment specifications.
- Retail:Back-of-store receiving and cross-dock operations utilize portable configurations for variable throughput. Seasonal volume spikes in North American retail distribution drive rental and lease procurement models.
Logistics commands specification authority; automotive maintains the highest per-installation value concentration.
Installation:
Capital commitment horizons distinguish permanent infrastructure from operational expenditure flexibility.
- Permanent:Anchored steel frame construction with fixed elevation gradients designed for fifteen-year depreciation cycles. Heavy manufacturing in Germany's automotive corridor sustains demand for welded-frame roller systems.
- Portable:Castor-mounted units repositionable without facility modification. Temporary e-commerce fulfillment pop-ups in India's emerging logistics hubs around Mumbai leverage portable configurations for PLI-subsidized automation trials.
- Modular:Standardized connection interfaces enable component-level replacement and lane reconfiguration. Interroll's platform strategy captures specification authority through pre-certified module interoperability.
- Customizable:Engineered-to-order dimensions and load ratings for unique material handling challenges. Integration complexity with existing WMS-controlled environments stretches project timelines for custom PLC programming requirements.
Permanent installations retain installed base dominance; modular architectures gain share fastest in greenfield fulfillment construction.
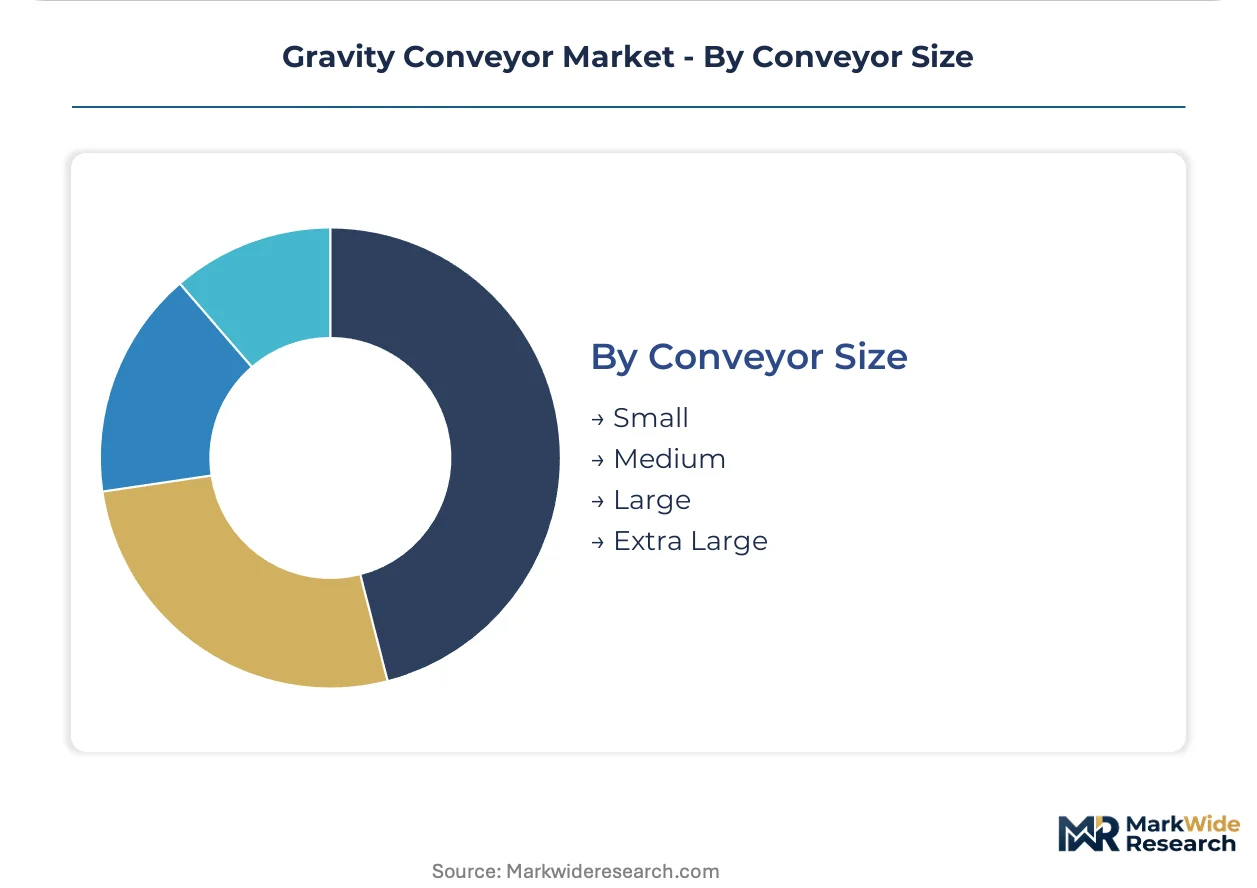
Conveyor Size:
Load dimension and weight profiles determine frame engineering and drive component specification.
- Large:Frame widths exceeding 800 millimeters accommodate palletized goods and bulk container handling. EU Machinery Directive guardrail mandates for installations above two meters elevation elevate safety system costs.
- Medium:Standard parcel and carton dimensions dominate e-commerce fulfillment specifications. Hytrol's domestic US manufacturing scale supports rapid custom configuration turnaround in this segment.
- Small:Compact envelope designs for pharmaceutical vial handling and electronics component transport. FDA-compliant sanitary designs constrain material selection for biologics staging applications.
- Extra Large:Specialized mining and airport baggage systems requiring ISO 340 and EN 12882 fire resistance certification. Testing queue delays at notified bodies extend product launch timelines by four to six months.
Medium formats retain shipment volume leadership; extra large specifications hold the steepest expansion curve in cold-chain pharmaceutical networks.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Port of Rotterdam's automated container handling infrastructure underwrites the Netherlands' central role in European gravity conveyor deployment, while China's Yangtze River Delta logistics corridor anchors Asia-Pacific throughput capacity.
United States
OSHA ergonomic mandates in e-commerce fulfillment centers accelerate gravity-fed accumulation system procurement for parcel sortation strain reduction. The Inflation Reduction Act's warehouse automation tax incentives subsidize capital expenditure in distribution networks. Chicago's Midwest logistics hub sustains demand for medium-format roller configurations serving same-day delivery networks.
Germany
Baden-Württemberg's automotive manufacturing corridor drives heavy-duty roller conveyor specifications for just-in-sequence component delivery synchronized to takt time. The EU Machinery Directive's 2023 amendment on collaborative human-robot interfaces mandates light-curtain guarding on elevated installations. Bavarian final assembly plants maintain fifteen-year depreciation cycles for welded-frame permanent installations.
China
Yangtze River Delta logistics hubs procure flexible expandable units to accommodate seasonal e-commerce volume spikes. The country's dual carbon goals pressure steel-intensive conveyor manufacturers toward low-carbon sourcing verification. Shanghai's port automation cluster integrates gravity lines with WMS-controlled environments despite custom PLC programming complexity.
India
Mumbai and Bangalore emerging logistics hubs leverage PLI scheme subsidies for automation capex trials in temporary portable configurations. The Bureau of Indian Standards constrains material selection through national safety certification requirements. Maharashtra's warehouse modernization programs disintermediate distributors through direct manufacturer engagement.
Netherlands
Rotterdam port logistics cluster operators unbundle conveyor procurement from turnkey contracts, issuing separate RFPs for roller modules and controls. REACH substance restrictions on zinc coating processes force reformulation of corrosion-resistant roller finishes. Chemical processors in the Antwerp-Rotterdam port range adopt composite polymer rollers for caustic washdown resistance.
Gravity Conveyor Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream supplying modular subassemblies to project-specific configurations. Market structure consolidates around three strategic archetypes: captive automotive suppliers, domestic-scale fabricators, and multinational platform orchestrators. Competitive positioning hardens through specification authority capture at design stage and rapid custom configuration turnaround capability. M&A activity concentrates in controls integration assets, while geographic expansion targets India's PLI-subsidized automation trials.
Within the multinational platform tier, Interroll Holding AG and Daifuku Co., Ltd. exemplify divergent anchoring strategies—Swiss modular standardization against Japanese captive automotive relationships. Hytrol Conveyor Company, Inc. occupies a position among domestic-scale US fabricators sustaining rapid turnaround advantage. These three represent archetype endpoints rather than exhaustive market coverage, with each sitting within distinct competitive vectors around specification timing, geographic proximity, and vertical relationship depth.
| Leading Market Players |
|---|
| Interroll Holding AG |
| Daifuku Co., Ltd. |
| Hytrol Conveyor Company, Inc. |
| Dematic |
| Honeywell Intelligrated |
| SSI Schaefer |
| LEWCO Inc. |
| Fives Group |
| TGW Logistics Group |
| Others |
Supply & Pricing Matrix
The Port of Rotterdam's container handling cost dynamics compress margin buffers for gravity conveyor manufacturers sourcing galvanized steel from Chinese mills, concentrating supply power among European fabricators with verified low-carbon sourcing while forcing downstream price differentiation between premium-certified and standard-grade system tiers.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels dominates procurement, with ISO 340 fire certification and EU Machinery Directive compliance separating premium tiers from uncertified economy alternatives. Price differentiation hinges on certification grade and volume scale, with large e-commerce fulfillment operators extracting steepest discounts through direct manufacturer engagement. Cost compression in economy-tier roller modules is intensifying because REACH-mandated zinc coating reformulations elevate material processing expenses. Third-party logistics operators exhibit highest price sensitivity due to seasonal reconfiguration demands, while pharmaceutical cold-chain distributors prioritize certification over cost.
Supply Chain Analysis
Tariff exposure between China and the European Union dominates supply chain risk calculations for steel-intensive gravity conveyor systems facing embodied-carbon border adjustments. Manufacturing concentrates in China, Germany, and the United States, with precision bearing assemblies drawing from Japanese and German component specialists. Raw material dependencies rest on galvanized steel tube stock, polymer compound formulations, and precision bearing supply. Distribution runs through direct manufacturer engagement with large end-users, disintermediating traditional distributor channels in Netherlands logistics clusters and North American e-commerce hubs.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The gravity conveyor market is entering a cyclical recovery phase as warehouse automation capex rebounds from post-pandemic normalization, with e-commerce fulfillment velocity demands driving replacement cycle compression as the primary cyclical driver.
For Market Incumbents: Pre-empt autonomous mobile robot substitution by embedding sensor-ready interfaces into modular roller platforms, capturing specification authority before AMR fleet deployments displace fixed gravity lines. Deepen backward integration into low-carbon steel sourcing to defend margin position against EU carbon border adjustment arbitrage opportunities for domestic European fabricators. Accelerate pre-certification of guardrail kits under the EU Machinery Directive's 2023 amendment to compress competitor compliance timelines. For New Entrants and Emerging Players: India's warehouse modernization under PLI scheme subsidies offers the most penetrable geographic entry point, with Mumbai and Bangalore emerging logistics hubs seeking portable configuration trials for seasonal demand spikes. Target cold-chain pharmaceutical handling as the highest-value application white space, where FDA-compliant sanitary designs and stainless steel construction create certification barriers for incumbent commodity producers. Establish direct specification relationships with third-party logistics operators through component-level RFP participation, bypassing distributor channel compression in Netherlands and North American markets. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors controls integration specialists with WMS-compatible PLC programming capabilities, as retrofit complexity stretches systems integrator capacity and creates acquisition value in scarce engineering talent pools. Long-term viability over the next decade rests on platform orchestrators capturing modular standardization rents rather than project-specific custom fabricators. Watch fire certification backlog durations at notified bodies as the critical inflection signal—testing queue extensions beyond six months indicate regulatory capacity constraints that favor pre-certified module suppliers.| Strategic Initiative | Industry Significance |
|---|---|
| Modular Platform Standardization | Interroll's pre-certified module interoperability captures specification authority at project design stage across European logistics hubs. |
| Backward Integration into Low-Carbon Steel | Domestic European fabricators with verified sourcing arbitrage EU carbon border tariffs on Chinese-manufactured competing systems. |
| Controls Integration Acquisition | WMS-compatible PLC programming capabilities address retrofit complexity stretching project timelines in existing warehouse environments. |
| Direct End-User Engagement | Disintermediation of distributor channels in Netherlands and North America compresses margins while accelerating specification capture. |
| Fire Certification Pre-Approval | ISO 340 and EN 12882 pre-certification at notified bodies circumvents four-to-six-month testing queue delays for mining and airport applications. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with warehouse automation directors, plant engineers at automotive OEMs, third-party logistics procurement leads, and aftermarket service heads at conveyor system integrators. Secondary validation drew from customs and trade databases, SEC 10-K filings of listed material handling equipment manufacturers, OSHA regulatory dockets, and EU Machinery Directive implementation guidance. Bottom-up shipment data triangulated against top-down capital expenditure surveys across e-commerce fulfillment, automotive assembly, and pharmaceutical distribution verticals.
Calibration against historical replacement cycle data and announced warehouse automation projects anchored the analytical framework across the projection horizon. Segmentation dimensions modeled include product architecture, installation type, end-user industry, conveyor size format, and regional regulatory cluster. CAGRs were derived from elasticity-adjusted demand curves incorporating steel price volatility indices and e-commerce fulfillment velocity benchmarks. Industry-specific forecast inputs encompassed OSHA ergonomic mandate implementation timelines and EU carbon border adjustment mechanism phase-in schedules.
Macroeconomic conditions sit as an overlay; deviation in steel scrap metal indices, e-commerce growth trajectories, or warehouse construction permitting would shift the trajectory materially. Forecasts reflect documented assumptions regarding regulatory compliance deadlines and technology substitution rates. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Material Handling Equipment
Eye and Eye Turnbuckle Market
Material Handling Equipment
Cable Conduit Systems Market
Material Handling Equipment
Forklift Work Platforms Market
Material Handling Equipment
Bridge Cable Sockets Market
Material Handling Equipment
Industrial Racking Systems Market
Material Handling Equipment
Apron Feeder Market
Material Handling Equipment
Industrial Counterweights Market
Material Handling Equipment
Conveyor Belt Market
Material Handling Equipment
Forklift Truck Market
Material Handling Equipment
Steel Coil Handling Equipment Market
Material Handling Equipment
Selective Pallet Racking System Market
Material Handling Equipment
Rolling Mill Machine Market
Material Handling Equipment
Material Handling Equipment Market
Material Handling Equipment
Asia Pacific Automated Material Handling and Storage Systems Market
Material Handling Equipment
Vibrating Screen Market
Material Handling Equipment
Precision Gearbox Machinery Market