
 Automated Material Handling (AMH) Market | 2026-2036
Automated Material Handling (AMH) Market Size, Share, and Industry Trends Forecast 2026-2036
Automated Material Handling (AMH) Market Outlook
A capital-intensity divergence between Tier 1 integrators and mid-tier regional vendors is reorganizing competitive dynamics in automated material handling. Daifuku Co. Ltd leverages its captive semiconductor cleanroom expertise to dominate high-precision verticals. KION Group sustains manufacturing scale across forklift-to-robotics portfolios through centralized European production. Dematic differentiates via software-defined orchestration layers that control heterogeneous hardware fleets.
Automated material handling encompasses electromechanical systems, sensor networks, and control software that transport, sort, store, and retrieve goods with minimal human intervention, typically operating at throughputs exceeding 15,000 units per hour in large distribution hubs. Conveyors and sortation systems anchor mature infrastructure investments where margin pools have compressed to maintenance and retrofit contracts. Robotics and automated guided vehicles represent the fastest-expanding technology categories as labor cost arbitrage and SKU proliferation force warehouses to adopt flexible, reconfigurable automation rather than fixed-path equipment.
OSHA enforces worker-safety proximity standards around autonomous mobile robots in US facilities, while the EU Machinery Directive mandates CE-marked functional safety for collaborative robot installations. Japan's METI promotes JIS-standardized interoperability protocols to reduce integration friction between Japanese and European equipment vendors. Stakeholders must monitor how evolving regional certification requirements affect cross-border procurement decisions and system upgrade cycles.
Market Dynamics
E-commerce fulfillment networks are compressing order cycle times from hours to minutes, forcing warehouses to abandon fixed-path conveyors for reconfigurable robotic systems that adapt to SKU volatility without infrastructure overhaul.
Growth Catalysts
- EU Machinery Directive:CE-marked functional safety mandates for collaborative robot installations are accelerating certified system deployments in German automotive assembly plants and third-party logistics hubs.
- Semiconductor cleanroom demand:High-precision verticals in East Asia require contamination-free automated transport, pulling investment into specialized AMH architectures.
- Labor cost arbitrage:SKU proliferation in North American distribution centers is forcing adoption of robotic picking over manual sortation to maintain throughput above 15,000 units per hour.
Market Restraints
- Steel and rare-earth input volatility:Permanent magnet costs for AGV drivetrains fluctuate with Chinese export quotas, compressing integrator margins on fixed-price contracts.
- Control software concentration:Proprietary orchestration layers from dominant vendors create vendor lock-in that limits mid-tier warehouse operators to retrofit-only upgrade paths.
- OSHA proximity standard compliance:Worker-safety zone requirements around autonomous mobile robots extend deployment timelines and require redundant sensor arrays that inflate system costs.
Strategic Opportunities
- India warehousing modernization:PLI scheme incentives for domestic manufacturing are pulling Japanese and European AMH vendors to establish local integration partnerships for e-commerce fulfillment networks.
- 5G-enabled fleet coordination:Ultra-reliable low-latency communication is converging with edge AI to enable real-time traffic management across heterogeneous robot populations without centralized control infrastructure.
- Retrofit services:Mature conveyor installations in North American and European distribution hubs represent recurring revenue pools as operators seek to extend asset life rather than greenfield replacement.
Industry Challenges
- Mechatronics talent scarcity:Integration of servo drives, machine vision, and safety-rated PLCs requires cross-functional engineering teams that command premium compensation and extend project staffing timelines.
- Legacy WMS interoperability:Decades-old warehouse management software architectures lack API-native interfaces, forcing middleware development that delays robotic system commissioning by months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Automated Material Handling (AMH) Market |
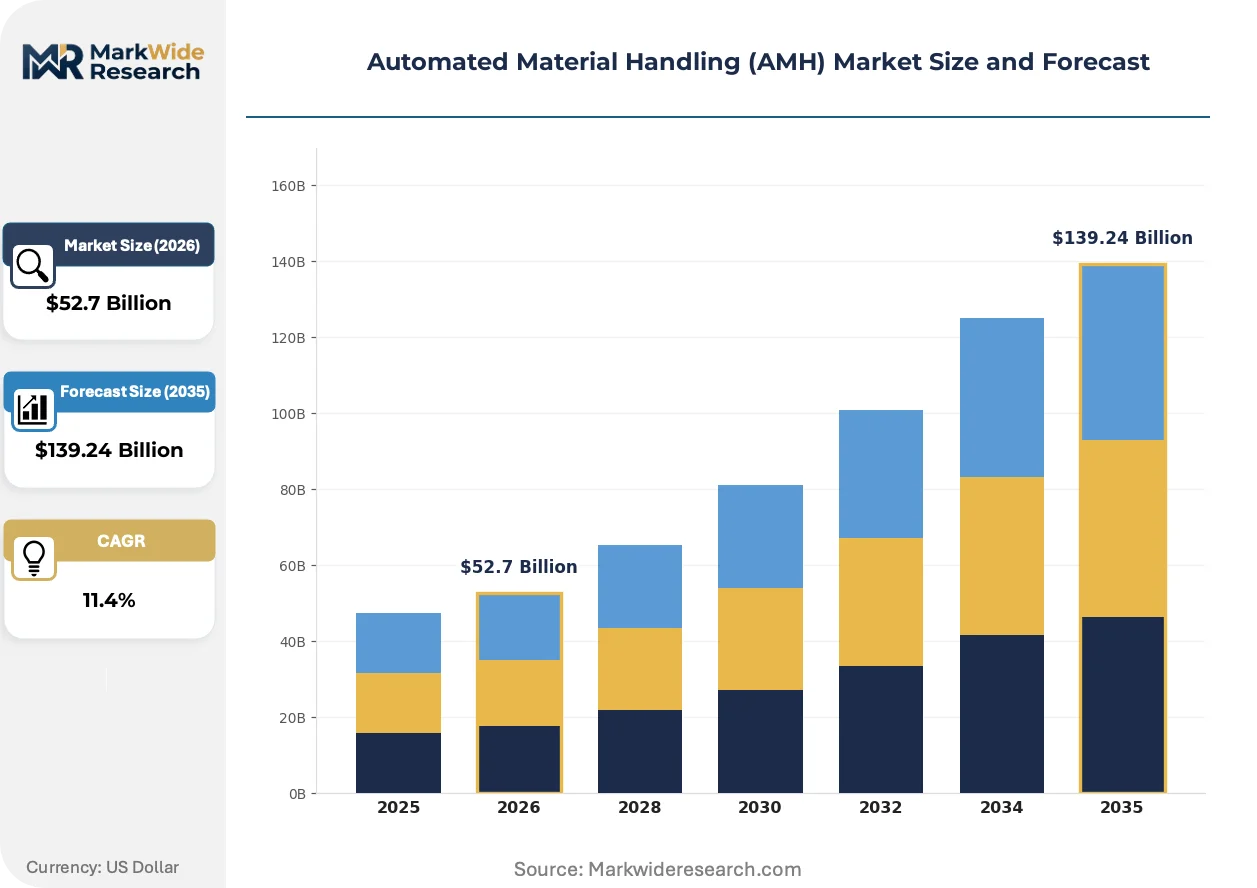
| Market Size in 2026 | $52.7 Billion |
| Market Size in 2035 | $139.24 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: Automated Guided Vehicles, Conveyors, Robotics, Sortation Systems Application: Warehouses, Manufacturing, Distribution Centers, Retail End User: E-commerce, Automotive, Aerospace, Food & Beverage Service Type: Integration, Maintenance, Support, Consulting |
| Companies Covered | Daifuku Co. Ltd, KION Group, SSI Schaefer, Honeywell International Inc., Dematic, Toyota Industries Corporation, Jungheinrich AG, Kardex Group, Murata Machinery Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Automated Material Handling (AMH) Market Strategic Shifts
Autonomous mobile robot architectures are fragmenting into specialized form factors, with each variant optimized for discrete operational tasks rather than general-purpose material transport.
Robotic manipulation technology is bifurcating into two distinct performance tiers. High-speed parallel kinematics dominate pharmaceutical and electronics kitting operations where cycle time determines line economics. Collaborative articulated arms with force-limiting joints penetrate food handling and apparel sortation where product variability exceeds rigid automation tolerances. This split is compressing mid-range articulated robot demand as buyers align capital commitments with specific throughput or safety requirements rather than purchasing general-purpose platforms.
Japan's METI interoperability protocols are mandating JIS-standardized communication interfaces between mobile robot fleets and host control systems. Industrial consequence includes reduced integration friction for multi-vendor installations, particularly in automotive assembly plants sourcing equipment from both Japanese and European suppliers. German automotive OEMs are responding by specifying METI-compliant middleware in procurement tenders to preserve supplier diversification without custom engineering overhead.
Third-party logistics operators are unbundling after-sales service contracts from initial system procurement, selecting specialized maintenance providers based on mean-time-to-repair performance rather than OEM affiliation. This disintermediation is most visible in North American e-commerce fulfillment networks where facility operators prioritize uptime guarantees over brand loyalty. Independent service organizations are capturing margin pools previously retained by original equipment manufacturers through predictive maintenance subscriptions priced against operational availability metrics.
Automated Material Handling (AMH) Market Segmentation
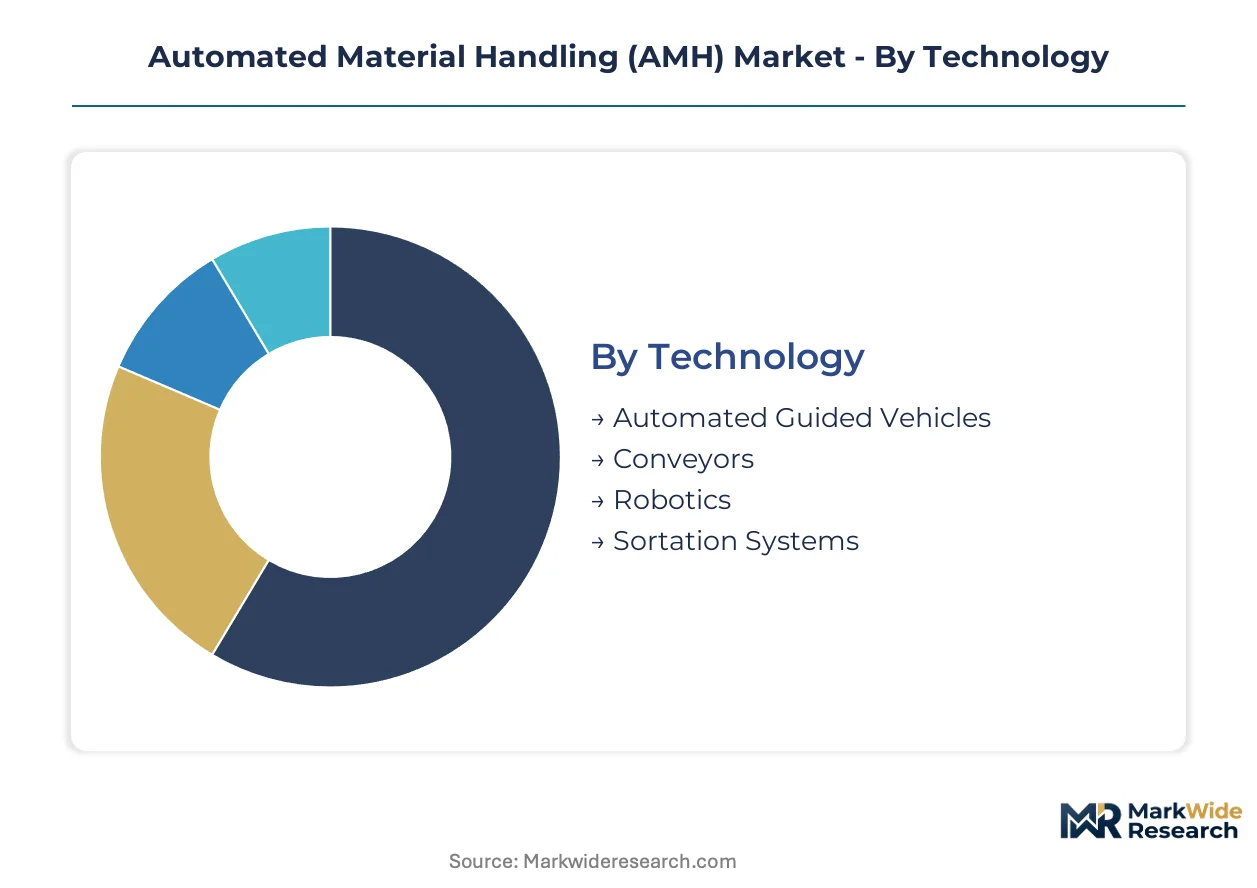
AMH procurement patterns diverge sharply between capital-intensive greenfield deployments and retrofit upgrades, with technology selection driven by throughput requirements and labor substitution economics rather than brand loyalty. Segment boundaries blur as converged systems—robotics mounted on AGV platforms, sortation integrated with conveyor networks—reshape traditional category definitions.
Technology:
Domestic demand concentrates in robotics and AGVs for flexible fulfillment, while conveyor and sortation exports flow heavily to industrializing Asian markets building distribution infrastructure.
- Robotics:Articulated and parallel kinematic systems execute pick-and-place operations at cycle times under 0.5 seconds in pharmaceutical kitting and electronics assembly. German automotive plants and North American e-commerce fulfillment centers drive demand as SKU proliferation exceeds fixed automation tolerances.
- Automated Guided Vehicles:Laser-guided and vision-navigated mobile robots transport palletized loads across warehouse floors without fixed infrastructure. Third-party logistics operators in the United States and Germany deploy expanding fleets to compress order cycle times from hours to minutes.
- Conveyors:Belt and roller systems remain the backbone of mature distribution hubs handling high-volume, low-variability SKUs.
- Sortation Systems:Cross-belt and tilt-tray sorters achieve throughputs exceeding 15,000 units per hour in large-scale e-commerce operations.
Conveyors hold the largest installed base; momentum sits with robotics and AGVs as reconfigurable automation displaces fixed-path equipment.
Application:
Cost-tier stratification separates premium integrated systems in manufacturing from standardized modular deployments in retail and mid-tier warehousing.
- Warehouses:Multi-level automated storage and retrieval systems maximize cubic utilization in land-constrained urban fulfillment nodes. Japanese and European operators prioritize systems with METI-compliant interoperability protocols to preserve supplier diversification.
- Distribution Centers:Heterogeneous robot fleets—AGVs, AMRs, and robotic arms—coordinate through software-defined orchestration layers. OSHA proximity standards and EU Machinery Directive safety mandates extend deployment timelines but accelerate certified system adoption.
- Manufacturing:Cleanroom-compatible transport systems serve semiconductor and pharmaceutical production requiring contamination-free material flow.
- Retail:Back-of-store automation handles replenishment and reverse logistics in omnichannel fulfillment models.
Distribution centers command the highest investment intensity; warehouses are expanding most quickly as e-commerce fulfillment networks proliferate.
End User:
Customer-type concentration pits high-volume, price-sensitive e-commerce operators against specification-driven aerospace and automotive buyers demanding custom engineering.
- E-commerce:Order profiles characterized by extreme SKU volatility and sub-24-hour delivery windows force adoption of robotic picking and AGV fleets. Amazon, Alibaba, and regional fulfillment networks drive technology roadmaps through scale procurement.
- Automotive:Just-in-sequence assembly lines require AGV systems with millimeter positioning accuracy and seamless WMS integration. German OEMs specify METI-compliant middleware to enable multi-vendor equipment sourcing.
- Food & Beverage:Collaborative robots with force-limiting joints penetrate handling operations where product variability and hygiene requirements exclude rigid automation.
- Aerospace:Low-volume, high-mix production environments demand specialized AGV systems for large component transport.
E-commerce holds the dominant share; food and beverage is gaining share fastest as collaborative robotics penetrates handling applications previously resistant to automation.
Service Type:
Margin pools are migrating from upfront integration toward recurring maintenance and software subscriptions as installed bases mature.
- Integration:System design, installation, and commissioning services require cross-functional mechatronics teams combining servo drives, machine vision, and safety-rated PLCs. Talent scarcity extends project staffing timelines and inflates labor costs.
- Maintenance:Predictive maintenance subscriptions priced against operational availability metrics capture margin pools previously retained by OEMs. North American third-party logistics operators unbundle service contracts to select providers based on mean-time-to-repair performance.
- Support:Remote diagnostics and software updates address legacy WMS interoperability challenges that delay robotic system commissioning.
- Consulting:Warehouse automation strategy services guide retrofit decisions for mature conveyor installations seeking asset life extension.
Integration represents the largest revenue pool; maintenance is climbing the fastest as operators prioritize uptime guarantees over initial procurement cost.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Export flows of automated material handling systems favor German and Japanese integrators supplying cleanroom-compatible transport architectures to East Asian semiconductor fabrication facilities. Import demand concentrates in India and Southeast Asia where domestic warehousing infrastructure modernization lags fulfillment network expansion. Cross-border procurement decisions increasingly hinge on METI-compliant interoperability certifications and CE-marked functional safety credentials.
United States
Third-party logistics operators deploy expanding AGV fleets to compress e-commerce order cycle times below one hour. OSHA enforces worker-safety proximity standards around autonomous mobile robots that extend deployment timelines but accelerate certified system adoption. The Inland Empire distribution cluster in Southern California anchors the highest concentration of robotic picking installations serving same-day delivery networks.
Germany
Automotive OEMs modernize just-in-sequence assembly lines with millimeter-accurate AGV systems integrated through METI-compliant middleware. The EU Machinery Directive mandates CE-marked functional safety for collaborative robot installations in Stuttgart and Wolfsburg assembly plants. Bavaria's third-party logistics hubs drive demand for software-defined orchestration layers controlling heterogeneous hardware fleets.
China
Domestic e-commerce fulfillment networks source automated sortation systems achieving throughputs exceeding 15,000 units per hour. MIIT promotes GB-standardized interoperability protocols to reduce integration friction between local and European equipment vendors. The Yangtze River Delta concentration of semiconductor fabrication facilities pulls investment into contamination-free automated transport architectures.
Japan
METI-mandated JIS-standardized communication interfaces enable multi-vendor mobile robot fleet deployments without custom engineering overhead. High-precision verticals in Kyushu and Tohoku require specialized cleanroom-compatible AMH systems for semiconductor and pharmaceutical production. Domestic integrators leverage captive expertise to dominate regional supply for contamination-free material transport.
India
PLI scheme incentives for domestic manufacturing pull Japanese and European AMH vendors to establish local integration partnerships. The country's national industrial safety regulator tightens requirements for human-robot collaboration zones in Maharashtra and Karnataka warehousing operations. Delhi-NCR and Mumbai fulfillment networks drive the fastest regional adoption of reconfigurable robotic systems over fixed-path conveyors.
Automated Material Handling (AMH) Market Competitive Environment
Concentration sits with diversified industrial conglomerates and specialized material handling integrators competing across technology tiers. Tier 1 players sustain manufacturing scale through centralized production and captive supply of critical subsystems. Mid-tier regional vendors compete on retrofit services and maintenance contracts. Dominant competitive moves include strategic partnerships for interoperability certification and portfolio diversification into software-defined orchestration layers.
Within the diversified conglomerate tier, Daifuku Co. Ltd and Toyota Industries Corporation occupy positions anchored by captive vertical expertise and manufacturing scale respectively. KION Group represents the integrated European production archetype sustaining forklift-to-robotics portfolios through centralized manufacturing. Dematic exemplifies the software-defined differentiation vector controlling heterogeneous hardware fleets through proprietary orchestration layers. Jungheinrich AG and SSI Schaefer sit within the specialized regional integration tier competing on retrofit service capabilities and aftermarket maintenance contracts.
| Leading Market Players |
|---|
| Daifuku Co. Ltd |
| KION Group |
| SSI Schaefer |
| Honeywell International Inc. |
| Dematic |
| Toyota Industries Corporation |
| Jungheinrich AG |
| Kardex Group |
| Murata Machinery Ltd. |
| Others |
Value Chain & Pricing Dynamics
Twenty-six-week lead times for safety-rated PLC modules compress integrator margins and concentrate pricing power with German and Japanese subsystem suppliers who maintain finished-goods inventory. Days-of-inventory figures at Tier 1 vendors reflect captive production of servo drives and machine vision components, insulating them from spot-market volatility that erodes regional competitor bids.
Pricing Analysis
The customization-premium spread between configured-to-order AGV fleets and standard conveyor modules runs three-to-one, with project-based pricing dominating greenfield deployments while maintenance contracts shift toward subscription-tiered SaaS models. Price differentiation hinges on CE-marked functional safety certification and software-defined orchestration capability, with uncertified mid-tier systems facing price erosion as OSHA proximity compliance extends deployment timelines. Cost compression in standard conveyor retrofits is intensifying because steel input volatility and rare-earth magnet quotas compress fixed-price contract margins. E-commerce fulfillment operators exhibit the highest price sensitivity, prioritizing uptime guarantees over initial procurement cost, while semiconductor fabs demonstrate the lowest sensitivity due to contamination-free transport requirements.
Supply Chain Analysis
Inbound logistics costs from Shanghai to Hamburg via the Suez corridor fluctuate with container availability, compressing margins on European-bound AGV shipments and forcing inventory pre-positioning at Rotterdam. Component supply concentrates in Germany, Japan, and China, with servo motors drawing from Bavarian and Nagoya production clusters while steel framing feeds from Chinese mill capacity. Permanent magnets for AGV drivetrains rest on Chinese rare-earth processing, creating single-source vulnerability around export quota announcements. Distribution runs through OEM-direct channels for large automotive contracts and specialized integrator networks for mid-tier warehousing retrofits.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The AMH market sits in early-cycle expansion as e-commerce fulfillment networks abandon fixed-path infrastructure for reconfigurable robotic systems. SKU proliferation and sub-one-hour delivery windows pull capital toward AGV and robotic picking deployments that displace mature conveyor investments.
For Market Incumbents: Consolidate software-defined orchestration capabilities through acquisition of edge-AI startups, defending against emerging cloud-native fleet management entrants. Deepen captive production of safety-rated PLCs in Germany to insulate margin positions from rare-earth input volatility and Chinese export quota shocks.
For New Entrants and Emerging Players: Differentiate on METI-compliant interoperability middleware, targeting Indian warehousing modernization where PLI scheme incentives pull Japanese and European vendors into local integration partnerships. Focus go-to-market efforts on predictive maintenance subscriptions priced against operational availability metrics, capturing margin pools that third-party logistics operators are unbundling from OEM service contracts.
For Investors and Strategic Acquirers: Long-term, this sits as a consolidation play because vendor lock-in around proprietary orchestration layers creates acquisition targets with sticky installed bases and recurring revenue expansion. Monitor 5G-enabled fleet coordination deployments as the signal indicating inflection toward real-time traffic management without centralized control infrastructure.
| Strategic Initiative | Industry Significance |
|---|---|
| Software-Defined Orchestration Layer Development | Proprietary control systems lock in heterogeneous robot fleet management, creating recurring SaaS revenue from e-commerce operators. |
| CE-Marked Functional Safety Certification Investment | EU Machinery Directive compliance accelerates certified system deployment in Stuttgart and Wolfsburg automotive assembly plants. |
| Local Integration Partnership Formation | India PLI scheme incentives pull Japanese and European vendors into Delhi-NCR and Mumbai fulfillment network modernization. |
| Predictive Maintenance Subscription Launch | Uptime guarantees priced against operational availability metrics capture margin pools from unbundled OEM service contracts. |
| 5G-Enabled Fleet Coordination Deployment | Ultra-reliable low-latency communication converges with edge AI for real-time traffic management across heterogeneous robot populations. |
Study Parameters
A standing panel of warehouse operations directors, AGV fleet managers, automotive assembly plant engineers, and aftermarket service heads provided ongoing calibration across the study. Primary interviews with system integrators and procurement leads at third-party logistics operators combined with secondary validation from OSHA enforcement databases, EU Machinery Directive implementation reports, METI JIS standard publications, and SEC filings of listed material handling conglomerates. Bottom-up unit shipment estimates triangulated against top-down capital expenditure tracking across e-commerce fulfillment networks.
Consistency checks against external benchmarks validated volume and value outputs across the projection horizon. The analytical framework modeled technology segmentation by reconfigurability, application segmentation by throughput requirement, end-user segmentation by SKU volatility tolerance, and service-type segmentation by revenue recurrence. CAGRs derived from installed base expansion rates and replacement cycle compression in mature conveyor infrastructure. Industry-specific forecast inputs included semiconductor cleanroom transport demand from Yangtze River Delta fabrication capacity and labor cost arbitrage thresholds in North American distribution centers.
The analysis sits within stated boundaries; outcomes outside sustained e-commerce fulfillment network expansion or prolonged rare-earth export restriction would require recalibration. Forecasts reflect assumptions around OSHA proximity standard enforcement intensity and METI interoperability protocol adoption velocity. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Material Handling Equipment
Air/Pneumatic Balancers Market
Material Handling Equipment
Air Classifying Mill Market
Material Handling Equipment
Selective Pallet Racking System Market
Material Handling Equipment
Reach Stacker Market
Material Handling Equipment
Dynamic Compactor Market
Material Handling Equipment
Gas Connectors and Gas Hoses Market
Material Handling Equipment
Copper and Aluminum Welding Bar Market
Material Handling Equipment
Drum Dumper Market
Material Handling Equipment
Europe Automated Material Handling (AMH) Market
Material Handling Equipment
Chute Liners Market
Material Handling Equipment
Pick and Carry (PNC) Crane Market
Material Handling Equipment
Vertical Platform Lift Market
Material Handling Equipment
Material Handling Monorails Market
Material Handling Equipment
Overhead Conveyor Systems Market
Material Handling Equipment
Truck Loader Crane Market
Material Handling Equipment
Industrial Bag Dust Filter Market