
 Robotic Palletizers Market | 2026-2036
Robotic Palletizers Market Size, Share, and Industry Trends Forecast 2026-2036
Robotic Palletizers Market Analytics
Robot-as-a-service and equipment leasing is rewriting capital deployment patterns for mid-size warehouses that previously deferred automation. FANUC Corporation leverages its controller ecosystem to anchor long-term service revenue streams. KUKA AG competes through deep integration with automotive OEM lines. ABB Ltd. differentiates via its modular palletizing cells that reduce commissioning cycles.
Robotic palletizers are articulated, SCARA, delta, or collaborative manipulators equipped with end-of-arm tooling that arranges unit loads onto shipping platforms according to programmed patterns, typically handling payloads from 10 kg to over 2,000 kg at throughputs exceeding 30 cycles per minute. Their primary purpose is to replace manual case handling in high-volume distribution and manufacturing environments where ergonomic injury risk and labor inconsistency degrade operational performance. Articulated robots dominate heavy-load applications in beverage and bulk consumer goods due to reach and payload capacity. Collaborative robots are expanding fastest in pharmaceutical end-use where lot-size flexibility and ISO-class cleanroom compatibility command premium system pricing. Vision systems and sensor integration increasingly determine competitive positioning as mixed-SKU palletizing becomes standard.
ISO 10218 and the EU Machinery Directive shape product safety certification requirements, while OSHA workplace ergonomics guidelines in the United States accelerate replacement of manual lifting stations. The EU AI Act will impose conformity obligations on AI-based control modules that dynamically optimize pallet patterns. Stakeholders must monitor how regulatory divergence between European CE marking and emerging state-level automation safety codes in the United States affects platform development roadmaps.
Market Dynamics
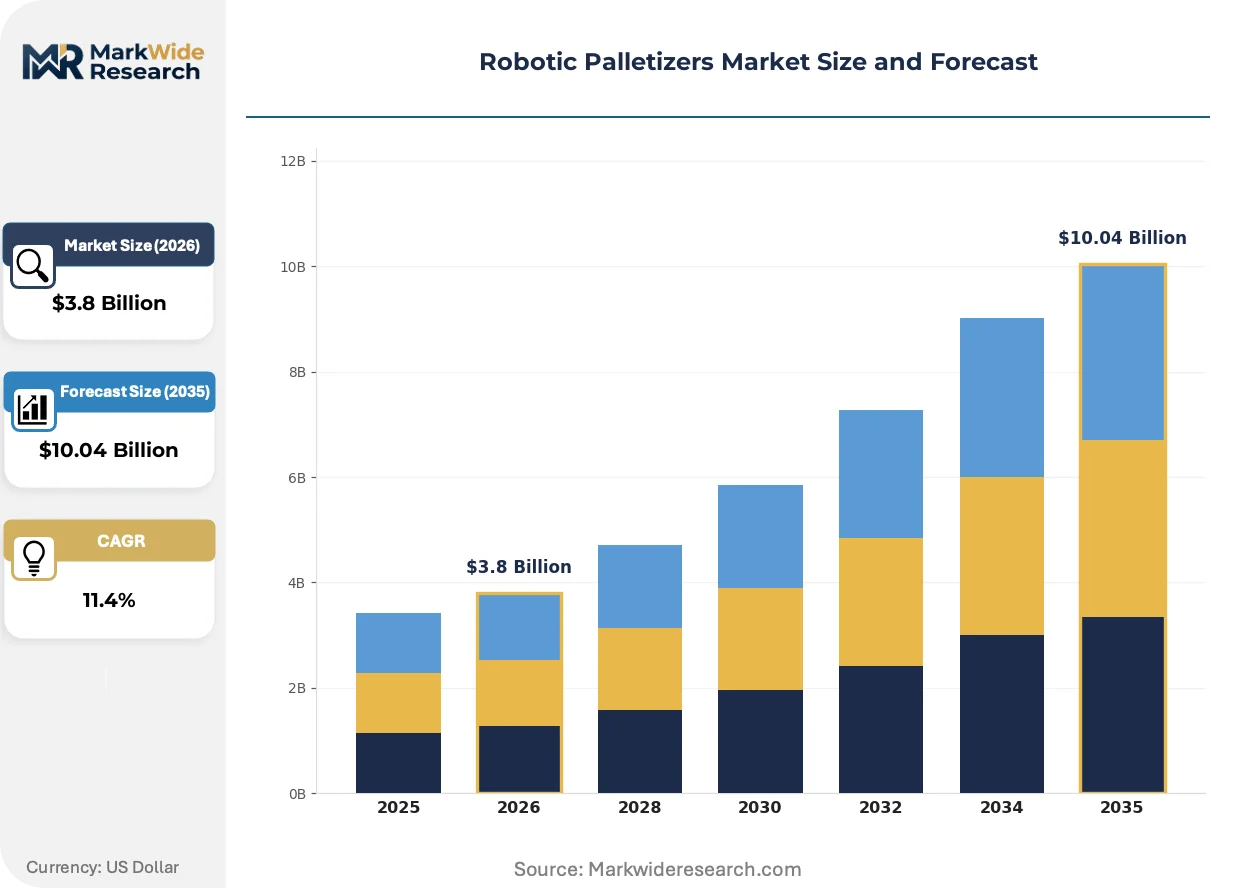
Robot-as-a-service financing models are compressing capital barriers for mid-size warehouses that previously deferred automation investments, while ISO 10218 and EU Machinery Directive compliance costs are redistributing competitive advantage toward integrated platform vendors.
Growth Catalysts
- OSHA workplace ergonomics guidelines:Beverage distributors in the United States face escalating injury liability from manual case handling, accelerating replacement of lifting stations with articulated palletizing arms.
- Food and beverage throughput targets:Manufacturers confront persistent labor shortages in high-volume packaging operations, forcing automation procurement even at premium system pricing.
- Pharmaceutical lot-size flexibility:Collaborative robots with ISO-class cleanroom compatibility capture demand from biologics packagers requiring rapid changeover between small-batch SKUs.
Market Restraints
- Controller and servo motor supply concentration:Premium motion control components concentrate among Japanese and German suppliers, exposing lead time vulnerability to semiconductor allocation shocks.
- EU AI Act conformity obligations:AI-based pallet pattern optimization modules face emerging certification requirements that extend commissioning timelines and inflate engineering costs.
- Fixed-base articulated robot footprint:Legacy facility layouts with constrained floor space cannot accommodate traditional gantry or pedestal installations without structural retrofit.
Strategic Opportunities
- Indian pharmaceutical export manufacturing:CDSCO-regulated facilities serving European and North American markets underinvest in automated end-of-line handling, creating first-mover advantage for compliant system integrators.
- Vision-guided mixed-SKU palletizing:Convergence of 3D depth cameras with machine learning pattern generation enables dynamic case handling without pre-programmed product dimensions.
- Robot-as-a-service channel expansion:Equipment leasing through third-party fleet operators penetrates mid-cap logistics providers that lack balance sheet capacity for capital purchase.
Industry Challenges
- Multi-axis programming expertise scarcity:System integrators and end-users compete for technicians capable of FANUC, KUKA, and ABB controller environments, inflating deployment labor costs.
- CE marking and state-level safety code divergence:Platform developers must engineer dual certification pathways for European conformity and emerging United States automation safety standards, fragmenting R&D resource allocation.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Robotic Palletizers Market |
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $10.04 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Articulated Robots, SCARA Robots, Delta Robots, Collaborative Robots End User: Food & Beverage, Pharmaceuticals, Consumer Goods, Electronics Technology: Vision Systems, AI-Based Control, Sensor Integration, Automation Software Installation: On-Site, Integrated Systems, Mobile Units, Modular Installations |
| Companies Covered | Yaskawa Electric Corporation, KION Group AG, FANUC Corporation, Schneider Packaging Equipment Company, Inc., Honeywell International Inc., KUKA AG, Krones AG, Beumer Group GmbH & Co. KG, ABB Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Robotic Palletizers Market Evolving Landscape
Software-defined pallet pattern generation and sensor fusion architectures are compressing the traditional boundary between fixed automation and adaptive handling systems, forcing hardware vendors to recalibrate platform roadmaps around data-centric value capture.
Machine learning-based case recognition systems trained on synthetic SKU libraries are rendering obsolete the conventional teach-pendant programming model that required physical product samples for every new pallet configuration. Pharmaceutical contract packagers in Switzerland and Germany are deploying these systems to compress changeover intervals from hours to minutes. The structural consequence is collapsing differentiation for traditional integrators that relied on proprietary motion libraries as competitive moats.
The EU AI Act imposes conformity assessment obligations on control modules that dynamically optimize load stability and shipping density based on real-time weight distribution feedback. Industrial software vendors must now document algorithmic decision pathways and risk mitigation protocols previously treated as proprietary intellectual property. Automotive parts distributors in Bavaria and Baden-Württemberg are prioritizing platform vendors with pre-certified AI control stacks to avoid deployment delays.
Mid-size warehouse operators are unbundling after-sales service contracts from initial equipment procurement, instead purchasing predictive maintenance subscriptions from third-party IoT platform providers. This behavior disrupts the traditional captive service revenue model that anchored long-term profitability for major robot OEMs. The shift is most visible among United States third-party logistics providers operating multi-site networks where vendor-agnostic fleet management commands procurement preference.
Robotic Palletizers Market Segmentation
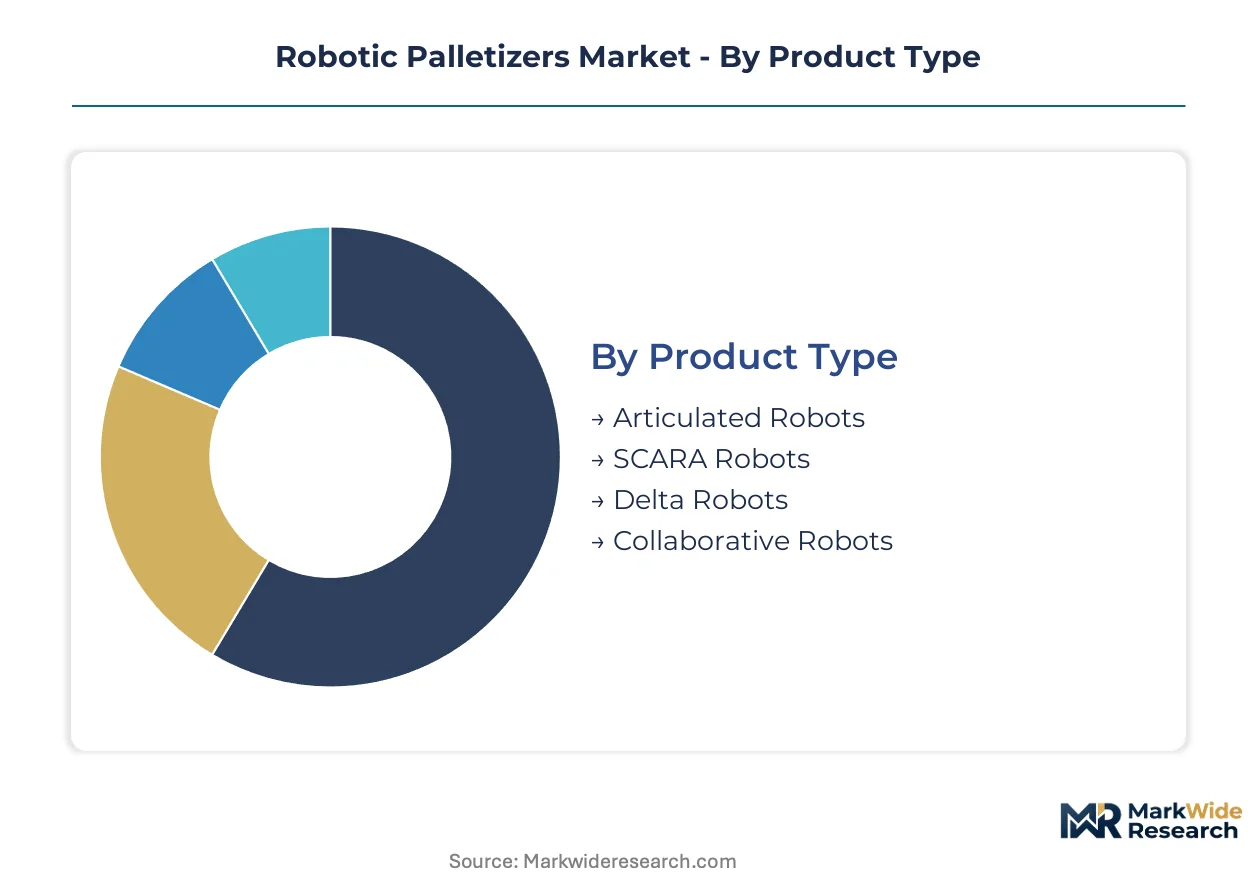
Segmentation in robotic palletizers reveals divergent service intensity profiles across hardware architectures, with articulated platforms demanding intensive predictive maintenance contracts while collaborative systems shift toward software-centric support models. Understanding these patterns enables vendors to calibrate aftermarket revenue strategies and deployment resource allocation.
Product Type:
After-sales service intensity varies dramatically by kinematic architecture, with multi-axis articulated systems generating recurring maintenance revenue streams that often exceed original equipment margins over a ten-year lifecycle.
- Articulated Robots:Six-axis serial manipulators with rotary joints deliver payload capacity exceeding 2,000 kg and reach envelopes up to 3.5 meters. Beverage bottlers in Germany deploy these systems for high-speed case handling where FANUC and KUKA controller ecosystems lock in long-term service contracts. Preventive maintenance intervals every 2,000 operating hours sustain captive revenue streams for OEM service divisions.
- Collaborative Robots:Force-limited manipulators with ISO/TS 15066-compliant safety architectures enable fenceless deployment alongside human operators. Swiss pharmaceutical packagers prioritize these systems for cleanroom-compatible biologics handling where rapid SKU changeover commands premium system pricing. Software updates and safety recertification cycles generate recurring revenue distinct from traditional mechanical maintenance.
- SCARA Robots:Selective compliance assembly robot arms provide high-speed planar motion for lightweight payload sorting in electronics fulfillment.
- Delta Robots:Parallel kinematic structures achieve throughputs exceeding 150 picks per minute for confectionery and snack food primary packaging.
By volume, Articulated Robots leads. By growth pace, Collaborative Robots is ahead.
End User:
End-use concentration determines commissioning complexity and integration partner selection, with pharmaceutical deployments requiring validated documentation packages that extend project timelines relative to consumer goods implementations.
- Food & Beverage:High-volume producers of bottled water, beer, and shelf-stable packaged goods operate continuous-shift environments where palletizing throughput directly constrains line efficiency. German automotive suppliers entering beverage logistics demand automotive-grade reliability metrics. Labor shortage pressures in United States distribution centers accelerate replacement of manual lifting stations regardless of capital recovery timelines.
- Pharmaceuticals:Biologics manufacturers and contract packagers handle temperature-sensitive, high-value products where lot traceability and contamination control override speed optimization. Bavarian facilities serving European export markets under EU GMP Annex 1 guidelines specify stainless steel construction and ISO Class 7 cleanroom compatibility. Validation documentation packages add 15-25% to total project cost versus food applications.
- Consumer Goods:Personal care and household product distributors prioritize flexibility for seasonal demand surges and promotional pack configurations.
- Electronics:Semiconductor and consumer electronics manufacturers demand electrostatic discharge protection and precision handling for fragile components.
Food & Beverage captures the largest installed base. Pharmaceuticals demonstrates the steepest expansion trajectory.
Technology:
Technology stack composition increasingly determines competitive differentiation as hardware commoditization pressures traditional robot OEM margins toward software and data services.
- Vision Systems:3D depth cameras and structured light sensors enable mixed-SKU palletizing without pre-programmed product dimensions. United States third-party logistics providers operating multi-site networks prioritize vision-guided platforms for e-commerce fulfillment where SKU proliferation renders fixed automation obsolete. Machine learning model training on synthetic libraries compresses commissioning from weeks to days.
- AI-Based Control:Reinforcement learning algorithms dynamically optimize pallet patterns for load stability and shipping density in real time. EU AI Act conformity obligations impose documentation requirements on algorithmic decision pathways that extend engineering costs for European deployments. Automotive parts distributors in Baden-Württemberg pre-qualify vendors with certified AI control stacks to avoid deployment delays.
- Sensor Integration:Force-torque sensors and weight verification modules ensure payload integrity for pharmaceutical serialization requirements.
- Automation Software:Fleet management platforms enable vendor-agnostic monitoring across heterogeneous robot populations.
Vision Systems commands the broadest addressable market. AI-Based Control faces the steepest regulatory compliance gradient.
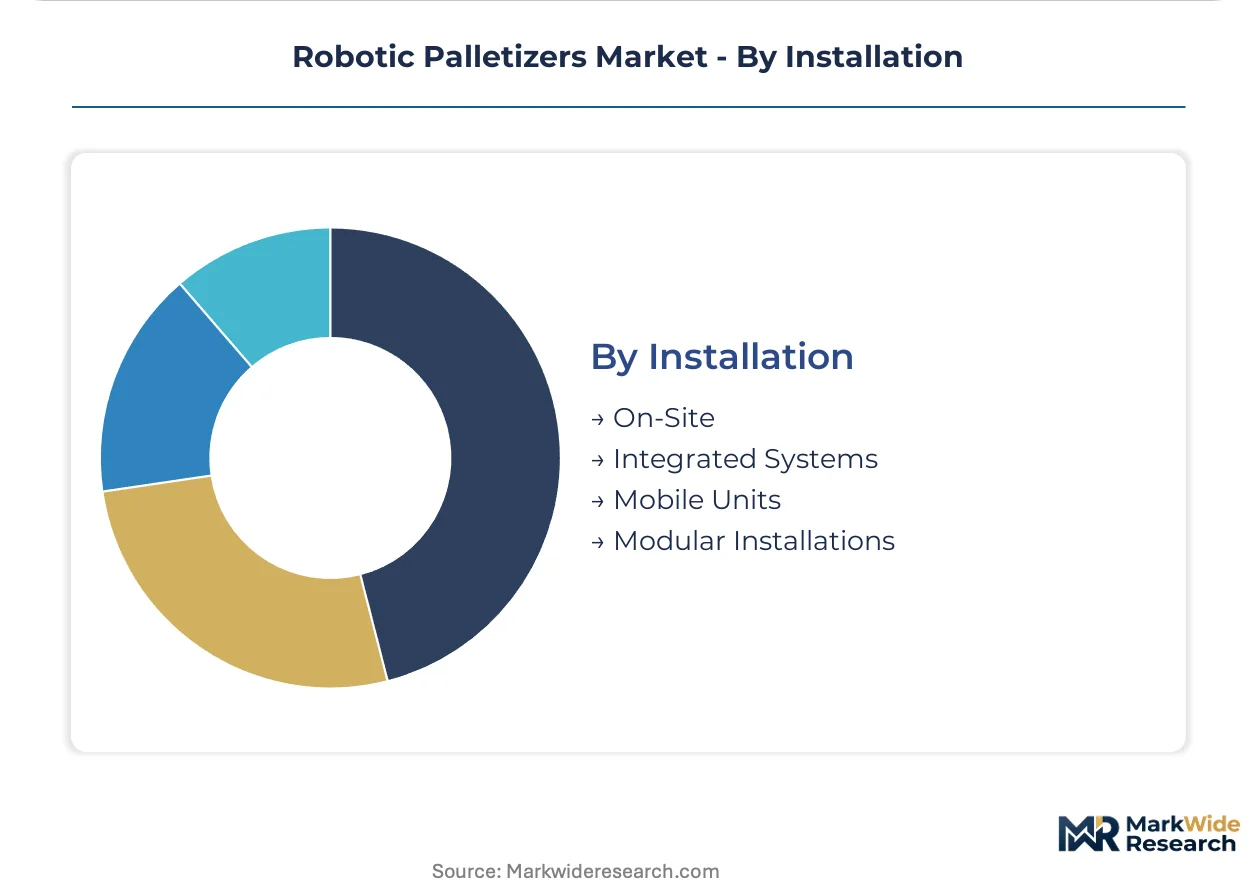
Installation:
Installation modality shapes capital deployment patterns and facility retrofit requirements, with mobile and modular architectures penetrating brownfield sites where fixed infrastructure investment is constrained.
- On-Site:Traditional fixed-base pedestal or gantry installations require structural foundations and permanent utility connections. Legacy beverage production facilities in the United States Midwest face concrete cutting and seismic anchoring costs that can match equipment purchase price. These deployments generate the highest lifetime service revenue concentration for OEM field engineering teams.
- Modular Installations:Pre-engineered cells with standardized mechanical, electrical, and software interfaces compress commissioning cycles from months to weeks. German automotive suppliers favor these platforms for satellite parts distribution centers where rapid operational startup outweighs customization flexibility. Reconfiguration for line changes preserves asset value across product lifecycle transitions.
- Integrated Systems:Turnkey palletizing lines incorporating upstream case packers and downstream stretch wrappers minimize interface risk for end-users.
- Mobile Units:Autonomous mobile robots with palletizing end-effectors enable flexible repositioning across warehouse zones.
On-Site retains the largest revenue share. Modular Installations is gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
EU Machinery Directive enforcement and OSHA workplace ergonomics guidelines are accelerating capital deployment across manufacturing clusters, while semiconductor supply constraints expose regional lead-time vulnerabilities in motion control procurement.
Germany
Automotive and beverage logistics clusters in Bavaria and Baden-Württemberg drive premium articulated robot procurement for high-throughput distribution centers. EU Machinery Directive compliance costs favor integrated platform vendors with pre-certified safety architectures. Stuttgart-based automotive suppliers entering beverage logistics demand automotive-grade reliability metrics and compressed commissioning cycles.
United States
OSHA workplace ergonomics guidelines expose beverage distributors to escalating injury liability from manual case handling, accelerating replacement of lifting stations with automated arms. State-level automation safety codes in California and Illinois are diverging from federal baselines, fragmenting certification requirements. Midwest legacy production facilities face concrete cutting and seismic anchoring costs that can match equipment purchase price for fixed-base installations.
China
Dual carbon goals and MIIT industrial automation directives are tightening energy efficiency standards for manufacturing equipment procurement. Yangtze River Delta electronics fulfillment centers prioritize vision-guided platforms for e-commerce SKU proliferation. Shanghai-based system integrators compete on compressed commissioning timelines for export-oriented consumer goods manufacturers.
Switzerland
Swissmedic-regulated pharmaceutical contract packagers prioritize collaborative robots with ISO-class cleanroom compatibility for biologics handling. Validation documentation packages add substantial project cost versus food applications, extending timelines. Basel and Zurich clusters command premium system pricing for rapid changeover between small-batch SKUs.
India
CDSCO-regulated pharmaceutical export facilities serving European and North American markets underinvest in automated end-of-line handling, creating first-mover advantage for compliant system integrators. Maharashtra and Gujarat manufacturing corridors face technician scarcity for multi-axis programming environments. Mumbai-based logistics providers lack balance sheet capacity for capital purchase, favoring equipment leasing structures.
Robotic Palletizers Market Competitive Landscape
Channel-controlling players compete with product-specialist players across a tiered structure where controller ecosystem lock-in determines long-term service revenue capture. The vendor base clusters around three strategic archetypes: integrated robot OEMs with captive software stacks, modular palletizing cell specialists, and third-party fleet operators delivering robot-as-a-service financing. Dominant competitive moves include M&A to secure motion control component supply and strategic partnerships to compress commissioning cycles for brownfield deployments.
Among Japanese and German motion control specialists, Yaskawa Electric Corporation, FANUC Corporation, and KUKA AG exemplify the integrated OEM archetype. Yaskawa and FANUC represent controller ecosystem anchors that lock in long-term service revenue through proprietary programming environments. KUKA occupies a position within the automotive-integrated tier, where deep OEM line integration commands procurement preference. These three companies illustrate how supply concentration in premium servo motors and controllers shapes competitive positioning across regional deployment cycles.
| Leading Market Players |
|---|
| Yaskawa Electric Corporation |
| KION Group AG |
| FANUC Corporation |
| Schneider Packaging Equipment Company, Inc. |
| Honeywell International Inc. |
| KUKA AG |
| Krones AG |
| Beumer Group GmbH & Co. KG |
| ABB Ltd. |
| Others |
Value Network & Pricing Analysis
Rotterdam-Antwerp freight corridors transmit semiconductor logistics cost volatility directly into servo motor landed costs, compressing margins for system integrators while amplifying price spreads between CE-certified premium platforms and uncertified economy alternatives. This cost transmission mechanism forces buyers to weigh total cost of ownership against upfront capital deployment, reshaping procurement patterns across European distribution networks.
Pricing Analysis
Certification level (ISO/CE/FDA-grade) creates the primary spread between system tiers, with pharmaceutical-grade installations commanding substantial premiums over food-handling equivalents. Three-tier pricing structure across premium, standard, and economy levels reflects bundling intensity of predictive maintenance contracts and AI control module pre-certification. Pricing pressure stems from robot-as-a-service financing compressing upfront recoverable margins for traditional capital sales. Mid-size warehouse operators exhibit highest price sensitivity, while automotive OEM procurement teams prioritize reliability metrics over unit cost.
Supply Chain Analysis
Export control regimes restricting high-precision servo motor technology limit component flows from Japan and Germany into Chinese system integrators, fragmenting global availability. Manufacturing concentration centers on Japan, Germany, and China for controllers, precision gearboxes, and structural steel frames respectively. Supply chains draw from rare earth magnet suppliers for motor assemblies, optical sensor fabs for vision systems, and specialty aluminum extruders for lightweight arm construction. Single-source vulnerability concentrates in harmonic drive manufacturing. Distribution runs through captive OEM service networks, third-party integrators, and emerging fleet operators delivering equipment-as-a-service.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Deployment velocity in this market hinges on technician density for multi-axis programming environments, a capability gap that constrains system integrator expansion and inflates labor costs for end-users. This scarcity dynamic rewards stakeholders who secure talent pipelines or eliminate programming complexity through software abstraction layers.
For Market Incumbents: Pre-empt margin erosion from robot-as-a-service competitors by embedding predictive maintenance subscriptions into controller firmware, locking in recurring revenue before third-party IoT platforms capture aftermarket relationships. Accelerate backward integration into servo motor production to insulate against semiconductor allocation shocks that currently extend lead times. Prioritize pre-certification of AI control stacks under EU AI Act conformity pathways to capture automotive parts distributor procurement in Baden-Württemberg. For New Entrants and Emerging Players: Build out vision-guided mixed-SKU palletizing capabilities targeting United States third-party logistics providers operating multi-site e-commerce fulfillment networks, where SKU proliferation renders fixed automation obsolete. Penetrate Indian pharmaceutical export manufacturing corridors in Maharashtra and Gujarat, where CDSCO-regulated facilities currently underinvest in automated end-of-line handling. Lead with equipment leasing structures that bypass balance sheet constraints limiting Mumbai-based logistics providers. For Investors and Strategic Acquirers: Carve-out targets emerge from diversified industrial conglomerates with underoptimized robotic palletizing divisions lacking software-centric revenue models. Long-term viability favors vendors with installed bases large enough to sustain subscription transitions and captive component supply securing margin defense. Monitor technician certification program graduation rates as inflection indicator for deployment capacity constraints.| Strategic Initiative | Industry Significance |
|---|---|
| AI Control Stack Pre-Certification | EU AI Act compliance accelerates procurement preference from Bavarian automotive distributors. |
| Robot-as-a-Service Channel Buildout | Equipment leasing penetrates mid-cap warehouses lacking capital purchase capacity. |
| Vision System Integration Partnership | 3D depth camera convergence enables dynamic mixed-SKU handling for e-commerce fulfillment. |
| Servo Motor Supply Security | Backward integration insulates against Japanese and German component lead time volatility. |
| Technician Training Program Expansion | FANUC, KUKA, and ABB controller expertise scarcity inflates deployment labor costs. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of regulatory filings, trade flow databases, and OEM procurement disclosures through structured interviews with plant engineers, aftermarket service heads, OEM procurement teams, and system integrators. Primary data collection targeted maintenance directors at beverage bottling facilities, robotics R&D directors at motion control specialists, and fleet managers at third-party logistics providers. Secondary validation drew from EU Machinery Directive implementation reports, OSHA workplace injury statistics, SEC 10-K equipment procurement disclosures, and customs records for servo motor trade flows. Bottom-up unit deployment estimates triangulate against top-down manufacturing capacity assessments.
Forecast inputs span robot kinematic architecture, end-use industry concentration, technology stack composition, and installation modality across the projection horizon. Segmentation dimensions model payload capacity tiers, cleanroom compatibility grades, AI control module integration depth, and regional regulatory cluster stringency. CAGRs derive from logistic curve penetration modeling calibrated to historical automation adoption rates in comparable manufacturing equipment categories. Industry-specific inputs include pharmaceutical lot-size flexibility requirements and e-commerce SKU proliferation trajectories.
The forecast holds incumbent behavior within observed patterns; aggressive moves by Chinese system integrators or sudden export control expansions would shift outcomes materially. Cross-checking against equipment finance origination data and technician certification program enrollment trends is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Material Handling Equipment
Forklift Tire Market
Material Handling Equipment
Trommel Screen Market
Material Handling Equipment
Global Hopper Loader Market
Material Handling Equipment
Vibrating Screen Market
Material Handling Equipment
Pneumatic Conveying Diverters Market
Material Handling Equipment
Overhead Hoist Transport (OHT) Market
Material Handling Equipment
Global Hydraulic Equipment Market
Material Handling Equipment
Industrial Hoists Market
Material Handling Equipment
Asia-Pacific Forklift Truck Market
Material Handling Equipment
Swivel Coupler Market
Material Handling Equipment
Automated Material Handling (AMH) Equipment Market
Material Handling Equipment
Clinching Machines Market
Material Handling Equipment
Enclosed Belt Conveyors Market
Material Handling Equipment
Electric Hoist Market
Material Handling Equipment
Pipe Jacking Machines Market
Material Handling Equipment
Forklift Work Platforms Market