
 Chain-Driven Roller Conveyors Market | 2026-2036
Chain-Driven Roller Conveyors Market Size, Share, and Industry Trends Forecast 2026-2036
Chain-Driven Roller Conveyors Market Insights
The EU Green Deal is pivoting material sourcing toward low-carbon steel and aluminum grades across conveyor manufacturing. Daifuku Co., Ltd. anchors its position through extensive R&D intensity in automated sortation integration. Hytrol Conveyor Company, Inc. dominates North American distribution with tightly controlled regional channel networks. Interroll Group differentiates through modular platform architectures that reduce field installation time.
Chain-driven roller conveyors employ sprocket-and-chain power transmission to rotate parallel rollers, typically achieving speeds of 30–150 feet per minute for palletized or containerized loads. The system uses precision roller bearings and heat-treated drive chains to maintain positive traction under heavy-duty cycling. Powered roller configurations command the widest installed base across automotive assembly and parcel sortation hubs. Steel construction retains dominance in high-load applications, while aluminum and composite variants gain share in food-grade and cleanroom environments where washdown compliance and weight reduction matter. End-user demand skews heavily toward warehousing and distribution centers as omnichannel fulfillment networks expand footprint density.
OSHA lockout/tagout standards and the EU Machinery Directive 2006/42/EC enforce emergency stop integration and guarding protocols that elevate system design complexity. REACH chemical restrictions and RoHS substance limits further constrain coating and lubricant selections for rollers and chains. Stakeholders must monitor how evolving carbon-border adjustments and energy-efficiency labeling reshape supplier qualification criteria and total cost of ownership calculations.
Market Dynamics
E-commerce fulfillment networks are compressing installation timelines and forcing conveyor suppliers to pre-integrate controls and diagnostics off-site. This pressure is restructuring how chain-driven roller systems are specified, procured, and commissioned across warehousing and automotive assembly.
Growth Catalysts
- OSHA Ergonomic Mandates:US warehouse operators are retrofitting manual roller lines with powered chain-driven units to reduce lifting injuries and comply with updated enforcement priorities in distribution hubs.
- Aluminum Roller Adoption:Food-grade and pharmaceutical cleanrooms are specifying anodized aluminum variants to meet washdown protocols while cutting dead weight for overhead conveyor configurations.
- EU Green Deal Material Rules:Low-carbon steel sourcing requirements are accelerating supplier qualification programs among German automotive OEMs and their Tier-1 integrators.
Market Restraints
- Heat-Treated Drive Chain Volatility:Specialty alloy steel prices fluctuate with scrap metal and energy markets, compressing margin predictability for mid-tier system integrators.
- Precision Bearing Supply Concentration:Japanese and German bearing houses control high-load roller bearing supply, exposing buyers to 12-16 week lead times during capacity tightness.
- REACH Coating Restrictions:Chromium and certain epoxy formulations face ECHA scrutiny, forcing reformulation of roller surface treatments and extending qualification cycles.
Strategic Opportunities
- India Logistics Modernization:PLI scheme incentives for warehousing infrastructure are attracting conveyor OEMs to establish local assembly for domestic e-commerce and automotive sectors.
- Automated Sortation Convergence:Integration of chain-driven rollers with machine vision and robotic pick stations opens specification channels in parcel hubs previously served by belt conveyors alone.
- EU Carbon Border Adjustments:Early compliance with embedded carbon tracking creates preferential positioning for European manufacturers against import competition in intra-EU projects.
Industry Challenges
- Controls Integration Talent Gap:Shortage of PLC programmers and motion control specialists delays commissioning of smart conveyor networks in brownfield facilities.
- Legacy Pneumatic Retrofit Complexity:Replacing air-powered diverters with electric alternatives on existing chain-driven frames requires mechanical redesign and extended downtime windows.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Chain-Driven Roller Conveyors Market |
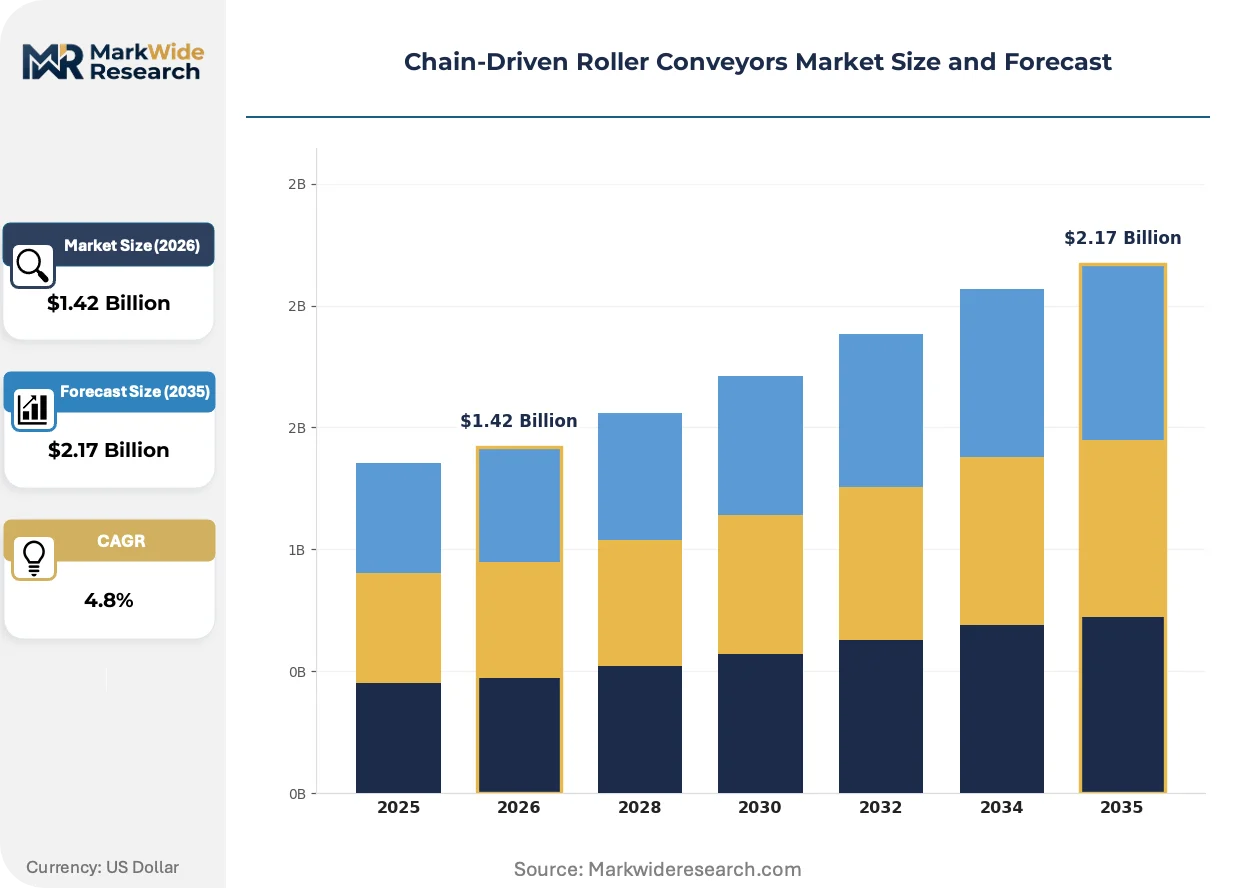
| Market Size in 2026 | $1.42 Billion |
| Market Size in 2035 | $2.17 Billion |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Gravity Roller, Powered Roller, Accumulating Roller, Adjustable Roller End User: Manufacturing, Warehousing, Logistics, Distribution Centers Material: Steel, Aluminum, Plastic, Composite Application: Automotive, Packaging, Food & Beverage, Pharmaceuticals |
| Companies Covered | BEUMER Group, Daifuku Co., Ltd., Dematic, Continental AG, FlexLink, Hytrol Conveyor Company, Inc., Interroll Group, Titan Conveyors, Regal Rexnord Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Chain-Driven Roller Conveyors Market Trends and Innovations
Modular platform architectures are displacing custom-engineered conveyor lines as buyers prioritize speed-to-install and future reconfigurability over bespoke designs.
Plug-and-play roller segments with standardized motor-roller units and tool-less side rail adjustments are modularizing how distribution centers expand capacity. Amazon and Walmart fulfillment contractors are specifying these configurations for 90-day ramp schedules. This approach is modularizing supplier value capture toward recurring module sales and away from one-time engineering fees.
EU Machinery Directive 2006/42/EC amendments are tightening emergency stop response time requirements and mandating redundant safety PLC architectures. System integrators must now source certified safety components from a shrinking approved vendor list. Automotive assembly plants in Germany and Czechia are absorbing the highest compliance costs, driving consolidation toward full-service suppliers with in-house safety certification teams.
Lifecycle service contracts are displacing transactional spare parts purchasing as buyers seek guaranteed uptime over ownership of inventory. Third-party logistics operators in the US Southeast are leading this shift, bundling roller replacement and chain tensioning into per-pallet-handled fees. Food-grade facilities face the tightest service integration timelines due to FDA-mandated preventive maintenance documentation requirements.
Chain-Driven Roller Conveyors Market Segmentation
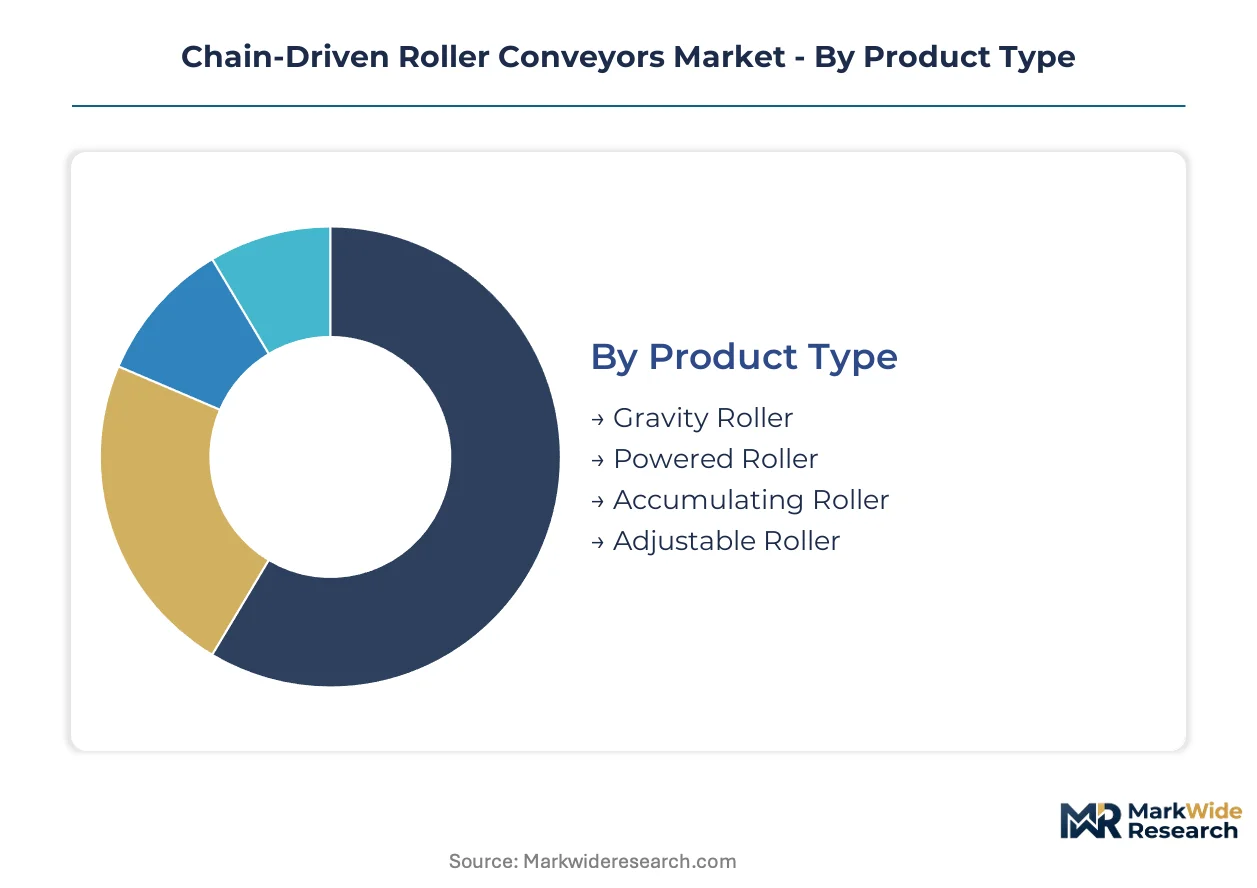
Segmentation in chain-driven roller conveyors reflects divergent engineering priorities across load requirements, environmental exposure, and regulatory compliance. Buyers configure systems around material durability, power transmission method, and washdown protocols rather than optimizing single variables.
Product Type:
Customization intensity varies sharply across this category, from fully standardized gravity units to engineered accumulating systems with zone-control logic.
- Powered Roller:Motorized sprocket-and-chain drive achieves 30–150 feet per minute for palletized loads. Demand concentrates in automotive assembly plants across Germany, Michigan, and South Carolina where OSHA ergonomic mandates are forcing retrofits of manual lines.
- Accumulating Roller:Zone-controlled accumulation buffers use photoelectric sensors and pneumatic stops to prevent product collisions. E-commerce fulfillment networks in China and the United States specify these for high-density sortation hubs requiring dynamic flow control.
- Gravity Roller:Unpowered decline transport for cost-sensitive operations with fixed routing.
- Adjustable Roller:Width-modular frames accommodate mixed container sizes in third-party logistics facilities.
Leading the category by volume: Powered Roller. Growing fastest: Accumulating Roller.
End User:
Volume concentration tracks capital deployment cycles, with logistics outpacing manufacturing on greenfield automation spend.
- Logistics:Parcel sortation hubs and express delivery networks drive specification of high-speed chain-driven systems with redundant drive chains. The EU Green Deal's low-carbon steel requirements are reshaping supplier qualification for German integrators serving DHL and DB Schenker contracts.
- Warehousing:Omnichannel fulfillment centers prioritize plug-and-play modular configurations for 90-day ramp schedules. Amazon and Walmart contractors in the US Southeast are bundling lifecycle service contracts into per-pallet-handled fees.
- Distribution Centers:Cross-dock operations with mixed SKU profiles require adjustable-width roller sections.
- Manufacturing:Assembly line integration favors heavy-duty steel construction for automotive and appliance production.
Highest capital intensity: Logistics. Fastest contract velocity: Warehousing.
Material:
Material selection trades structural load capacity against corrosion resistance and weight constraints in overhead configurations.
- Steel:Heat-treated alloy construction dominates high-load applications above 2,000 pounds per linear foot. REACH coating restrictions on chromium formulations are forcing reformulation of surface treatments and extending qualification cycles for European suppliers.
- Aluminum:Anodized variants meet FDA washdown protocols in food-grade facilities while cutting dead weight for ceiling-mounted systems. Pharmaceutical cleanrooms in Switzerland and the United States specify these for overhead conveyor configurations.
- Composite:Glass-reinforced polymer rollers gain traction in corrosive chemical processing environments.
- Plastic:Injection-molded rollers serve light-duty packaging lines with minimal load requirements.
Dominant by installed base: Steel. Expanding most quickly: Aluminum.
Application:
Application-driven specification diverges on sanitation grade, speed precision, and integration with robotic workstations.
- Automotive:Heavy-duty chain-driven systems with precision indexing serve engine assembly and body-in-white lines. German OEMs and Tier-1 integrators are accelerating supplier qualification programs under EU Green Deal low-carbon steel sourcing rules.
- Food & Beverage:Stainless steel and aluminum construction with sealed bearings satisfies FDA preventive maintenance documentation and washdown protocols. US poultry and dairy processors face the tightest service integration timelines.
- Pharmaceuticals:Cleanroom-grade systems with ionized air integration and particulate monitoring.
- Packaging:Standard-duty configurations for case handling and palletizing operations.
Largest contract value: Automotive. Steepest specification upgrade cycle: Food & Beverage.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Detroit-Warren-Dearborn corridor anchors North American demand for heavy-duty chain-driven systems serving automotive body-in-white and powertrain assembly lines.
United States
E-commerce fulfillment networks in the Southeast and Midwest are compressing installation timelines to 90-day ramps. OSHA ergonomic enforcement priorities are accelerating retrofits of manual roller lines in distribution hubs across Georgia and Tennessee. Amazon and Walmart contractors in the Dallas-Fort Worth metroplex are bundling lifecycle service contracts into per-pallet-handled fee structures.
Germany
Automotive OEMs in Stuttgart and Wolfsburg are accelerating supplier qualification programs under EU Green Deal low-carbon steel sourcing mandates. The EU Machinery Directive 2006/42/EC amendments are tightening emergency stop response requirements. Bavarian integrators serving DHL and DB Schenker contracts face the highest compliance cost absorption in European conveyor procurement.
China
Parcel sortation hubs in the Yangtze River Delta and Pearl River Delta are specifying high-speed accumulating systems for Singles Day and Mid-Year Shopping Festival volume surges. MIIT industrial upgrading guidelines are pressuring domestic fabricators toward precision bearing localization. Shenzhen-based logistics operators are integrating chain-driven rollers with machine vision stations for robotic pick applications.
India
PLI scheme incentives for warehousing infrastructure are attracting conveyor OEMs to establish local assembly for domestic e-commerce and automotive sectors. CDSCO and BIS quality certifications are extending qualification cycles for food-grade pharmaceutical applications. The Mumbai-Pune industrial corridor is seeing concentrated demand from third-party logistics operators modernizing cross-dock facilities.
Japan
Precision bearing supply concentration from Osaka and Kobe manufacturing clusters exposes buyers to extended lead times during capacity tightness. METI energy-efficiency labeling is reshaping supplier qualification criteria for intra-Asian export projects. Automotive assembly plants in Toyota City and Yokohama maintain specification authority for heavy-duty indexing systems serving hybrid powertrain lines.
Chain-Driven Roller Conveyors Market Competitive Landscape
The competitive structure tilts toward full-service system integrators with in-house safety certification capabilities. Tier-1 automotive contracts and parcel hub specifications are consolidating around suppliers offering modular platform architectures and lifecycle service bundling. Two strategic archetypes dominate: European engineering-intensive specialists with embedded carbon tracking compliance, and North American distribution-focused fabricators with tightly controlled regional channel networks. Competitive moves center on pre-integrated controls off-site and geographic expansion into India via PLI-scheme warehousing incentives.
Among Japanese and German precision engineering houses, Daifuku Co., Ltd. and Interroll Group occupy positions exemplifying automated sortation convergence and modular platform specialization respectively. Hytrol Conveyor Company, Inc. anchors the North American distribution-focused tier with regional channel density. These three represent the spectrum from controls-integrated system integration to speed-to-install modular configurations.
| Leading Market Players |
|---|
| BEUMER Group |
| Daifuku Co., Ltd. |
| Dematic |
| Continental AG |
| FlexLink |
| Hytrol Conveyor Company, Inc. |
| Interroll Group |
| Titan Conveyors |
| Regal Rexnord Corporation |
| Others |
Pricing and Supply Chain Analysis
PLC programmers and motion control specialists in the US Southeast and German automotive corridors command wage premiums that compress margin predictability for mid-tier integrators, forcing three-tier pricing stratification across premium certified-safety, standard modular, and economy gravity configurations.
Pricing Analysis
Per-pallet-handled fee structures now anchor value-based pricing for warehousing contractors bundling lifecycle service contracts. Three-tier pricing separates CE-certified safety-integrated systems from standard modular configurations from economy gravity lines. Pricing pressure stems from REACH coating reformulation costs extending qualification cycles. Third-party logistics operators exhibit highest price sensitivity, while pharmaceutical cleanrooms absorb premium tiers for FDA washdown compliance.
Supply Chain Analysis
Dual-sourcing requirements for precision roller bearings now mandate Japanese and German supplier qualification alongside emerging Taiwanese alternatives. Heat-treated drive chains draw from Chinese and South Korean specialty alloy mills. Single-source vulnerability concentrates in high-load bearing supply during capacity tightness. Distribution runs through regional system integrators with in-house safety certification teams serving automotive OEMs and parcel hubs.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market consolidates around full-service integrators as EU Machinery Directive amendments and OSHA ergonomic enforcement force weaker players without safety certification capabilities to exit.
For Market Incumbents: Anticipate margin compression from aluminum roller adoption in food-grade applications by deepening backward integration into anodized finishing capacity. Secure redundant safety PLC component sourcing before the approved vendor list shrinks further under EU amendments. Channel control in the US Southeast lifecycle service market offers defensive positioning against modular platform specialists. For New Entrants and Emerging Players: Enter via India's PLI-scheme warehousing incentives where local assembly gaps persist for domestic e-commerce fulfillment networks. White-space concentrates in pharmaceutical cleanroom configurations requiring ionized air integration expertise. Machine vision convergence with chain-driven rollers offers specification channels in Shenzhen parcel hubs previously served by belt conveyors alone. For Investors and Strategic Acquirers: Re-rating potential sits with European engineering-intensive specialists given EU Carbon Border Adjustment compliance creating preferential positioning against import competition. Five-to-ten year viability favors targets with embedded carbon tracking systems and in-house safety certification teams. Monitor German automotive OEM supplier qualification program acceleration as inflection signal for consolidation timing.| Strategic Initiative | Industry Significance |
|---|---|
| Modular Platform Standardization | Reduces field installation time for Amazon and Walmart 90-day ramp schedules. |
| Backward Integration into Anodized Aluminum | Captures margin from FDA washdown protocol compliance in poultry processing. |
| Safety Certification Capacity Buildout | Secures Tier-1 automotive contracts under EU Machinery Directive amendments. |
| Lifecycle Service Contract Bundling | Converts transactional spare parts revenue to recurring per-pallet-handled fees. |
| Geographic Expansion via India PLI Incentives | Establishes local assembly for domestic e-commerce and automotive demand. |
Research Methodology
Trade association filings, customs and import-export records, and SEC 10-K disclosures formed the secondary backbone, cross-referenced with primary interviews across maintenance directors at automotive assembly plants, procurement leads at third-party logistics operators, aftermarket service heads at regional integrators, and plant engineers at food-grade facilities. Bottom-up unit economics and top-down sector sizing were triangulated to anchor volume estimates.
Historical trendline analysis of capital expenditure cycles across logistics, warehousing, and manufacturing end-uses informed the projection framework. Segmentation dimensions spanned product type, material grade, end-user industry, and application sanitation requirements. CAGRs were derived from fitted growth curves incorporating MIIT industrial upgrading guidelines, EU Green Deal material sourcing mandates, and OSHA enforcement priority shifts across the analysis window.
Forecast precision tightens around the base case; tail outcomes carry wider variance under precision bearing supply disruptions or abrupt REACH coating restriction amendments. Deviation in EU Carbon Border Adjustment implementation timelines would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Material Handling Equipment
Electric Hoist Market
Material Handling Equipment
Overhead Conveyor Systems Market
Material Handling Equipment
Global Loaders Market
Material Handling Equipment
Pipe Jacking Machines Market
Material Handling Equipment
Industrial Carts Market
Material Handling Equipment
Global Rolling Mill Rolls Market
Material Handling Equipment
Material Handling Monorails Market
Material Handling Equipment
Mill Liner Market
Material Handling Equipment
Pallet Circulation System Market
Material Handling Equipment
Vibrating Screen Market
Material Handling Equipment
Dry Bulk Handling System Market
Material Handling Equipment
Loader Crane Market
Material Handling Equipment
Material Handling Equipment Telematics Market
Material Handling Equipment
Froth Flotation Equipment Market
Material Handling Equipment
Hydraulic Cylinder Rod Market
Material Handling Equipment
Autonomous Warehouse Equipment Market