
 Metal Plain Washer Market | 2026-2036
Metal Plain Washer Market Size, Share, and Industry Trends Forecast 2026-2036
Metal Plain Washer Market Insights
Heavy machinery OEMs is unwinding procurement concentration from construction contractors as renewable energy developers scale wind turbine and solar tracking installations. Solon Manufacturing Co. leverages captive forging capacity to anchor North American supply for critical infrastructure grades. MISUMI Group Inc. dominates catalog distribution across precision-engineered sizes in Asia-Pacific industrial corridors. Bossard sustains European market presence through vendor-managed inventory programs tied to automotive tier-one suppliers.
A metal plain washer is a flat annular disc with a central hole, manufactured through stamping, laser cutting, or CNC machining from sheet or coil stock, typically with outer diameters ranging from 3 mm to 300 mm and thickness tolerances of ±0.05 mm to ±0.25 mm depending on application class. Its primary function is to distribute clamping load over a larger bearing surface, prevent fastener loosening under vibration, and protect assembled materials from galling or surface damage. Steel variants command the largest volume share due to cost efficiency in construction and general industrial applications, while stainless steel grades capture premium margin pools in marine and food processing environments where passivation and chloride resistance determine specification. Surface treatment selection—zinc plating versus powder coating versus anodizing—directly shapes supplier qualification pathways and end-user approval cycles across electrical equipment and aerospace manufacturing segments.
ISO 898-1 governs mechanical properties of carbon steel fasteners and their associated washers in international trade, while ASTM F436 specifies hardened steel washers for structural steel joints in North American building codes. The EU Green Deal and associated CSRD disclosure requirements are pressuring construction and heavy machinery buyers to document embodied carbon in fastener assemblies, redirecting sourcing toward mills with verified scrap-recycling content. Stakeholders must monitor evolving national building code amendments that incorporate seismic load factors, as these revisions will redefine washer hardness and dimensional specifications for infrastructure resilience.
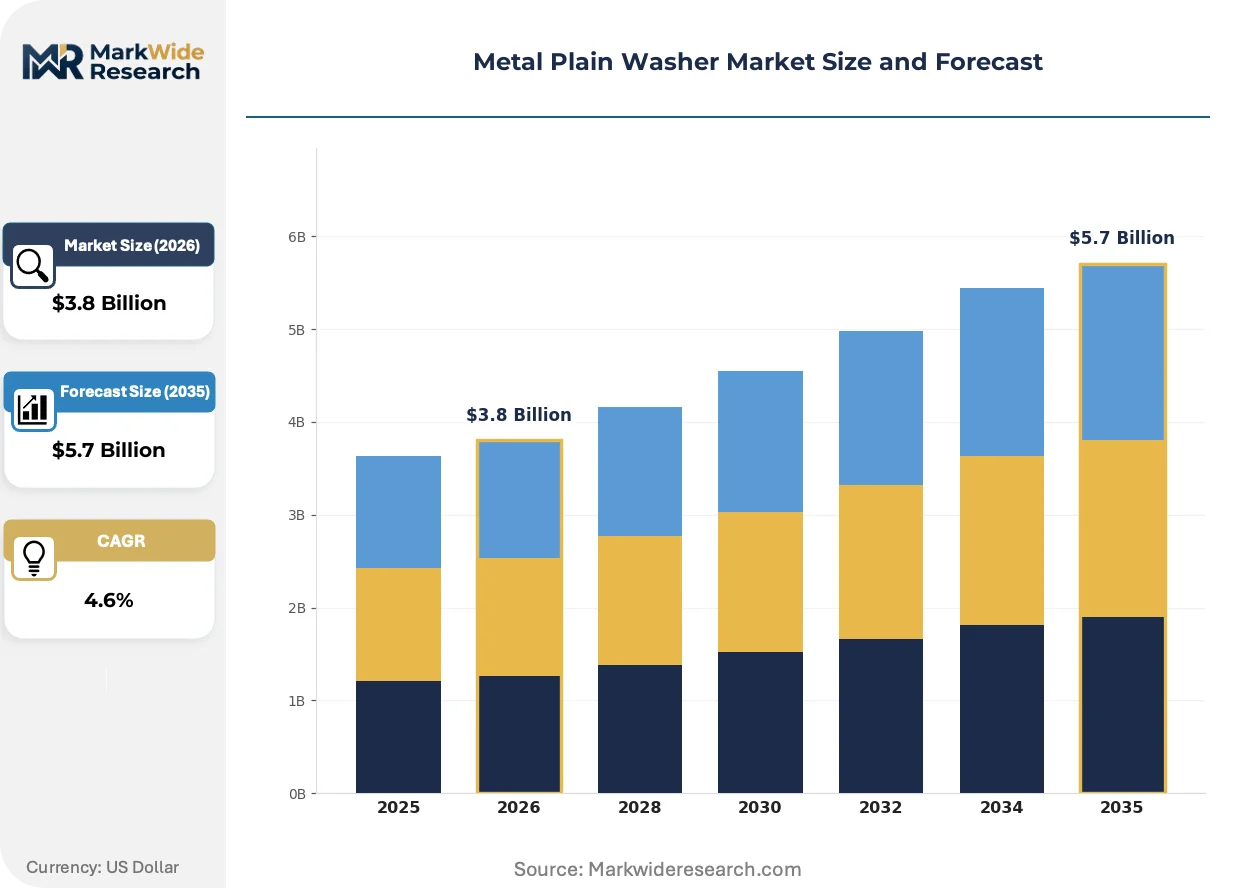
Market Dynamics
The EU Green Deal's embodied carbon disclosure mandates are redirecting procurement toward scrap-recycled steel mills, compressing qualification timelines for traditional zinc-plated suppliers while elevating stainless steel specifications across construction and heavy machinery verticals.
Growth Catalysts
- Wind turbine OEM procurement:Renewable energy developers in Germany's industrial belt around Stuttgart and Dortmund are scaling washer volumes for solar tracking systems and nacelle assemblies.
- REACH and RoHS compliance:European chemical safety regulations are phasing out hexavalent chromium treatments, accelerating stainless steel substitution in food processing and marine environments.
- Equipment refurbishment cycles:Heavy machinery fleets in North American mining and agriculture are extending service lives through systematic fastener replacement programs.
Market Restraints
- Steel coil price volatility:Input cost swings from energy-intensive electric arc furnace operations compress margin predictability for stampers serving construction contractors.
- Automotive tier-one concentration:Vendor-managed inventory programs at Bossard and similar distributors lock smaller stampers out of just-in-time supply chains for precision-engineered sizes.
- Polymer composite substitution:Glass-reinforced nylon washers are displacing metal in electrical insulation and lightweighting applications below 50 N clamping loads.
Strategic Opportunities
- CSRD-aligned carbon accounting:European construction buyers now require mill-specific scrap content documentation, creating first-mover advantage for recyclers with verified mass-balance systems.
- Seismic code amendments:Japan's METI and California's building standards are tightening hardness specifications for structural joints, opening premium tiers for hardened ASTM F436 grades.
- Digital catalog platforms:MISUMI Group Inc.'s Asia-Pacific distribution model demonstrates scalable penetration of precision sizes through parametric search and same-day fulfillment.
Industry Challenges
- Heat treatment certification backlog:Third-party validation of case-hardened washers for structural applications faces 12-16 week queue times at accredited laboratories.
- Legacy ERP integration:Vendor-managed inventory systems require real-time EDI connectivity that mid-tier stampers lack, excluding them from automotive tier-one supplier networks.
- Passivation chemistry expertise:Stainless steel grades for chloride-rich marine environments demand specialized nitric acid processing knowledge that constrains supplier expansion.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Metal Plain Washer Market |
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $5.7 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Material Type: Steel, Stainless Steel, Brass, Copper, Aluminum, Titanium End User Industry: Construction, Electrical Equipment, Shipbuilding, Aerospace Manufacturing, Heavy Machinery, Renewable Energy Product Size: Small, Medium, Large, Extra Large, Custom Dimensions Surface Treatment: Zinc Plating, Phosphating, Anodizing, Passivation, Powder Coating, Electroplating |
| Companies Covered | Solon Manufacturing Co., The Hillman Group, Willie Washer Manufacturing Corporation, Bossard, Jergens Inc., Essentra PLC, MISUMI Group Inc., Rivit Srl, Gris Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Metal Plain Washer Market Trends and Innovations
Laser cutting systems and precision stamping lines are diverging into separate capability tiers, with capital intensity determining which suppliers can serve infrastructure-grade versus precision-engineered demand pools.
Stainless steel washer production is bifurcating between commodity 304 grades for general corrosion resistance and duplex 2205 alloys for high-chloride marine and chemical processing environments. Offshore wind developers in the North Sea are specifying duplex grades for monopile connection hardware, compressing volume share for traditional 316L suppliers while opening margin pools for mills with vacuum arc remelting capacity.
CSRD disclosure requirements are forcing construction and heavy machinery buyers to document Scope 3 embodied carbon in fastener assemblies, redirecting sourcing toward electric arc furnace mills with verified scrap-recycling content. German industrial buyers around Stuttgart now reject blast-furnace material lacking Environmental Product Declarations, compressing qualification pathways for integrated steel producers.
Heavy machinery OEMs are unwinding procurement concentration from construction contractors as renewable energy developers scale direct sourcing for wind turbine and solar tracking installations. Solon Manufacturing Co.'s captive forging capacity anchors North American supply for critical infrastructure grades, while catalog distributors capture precision-engineered sizes through parametric specification tools.
Metal Plain Washer Market Segmentation
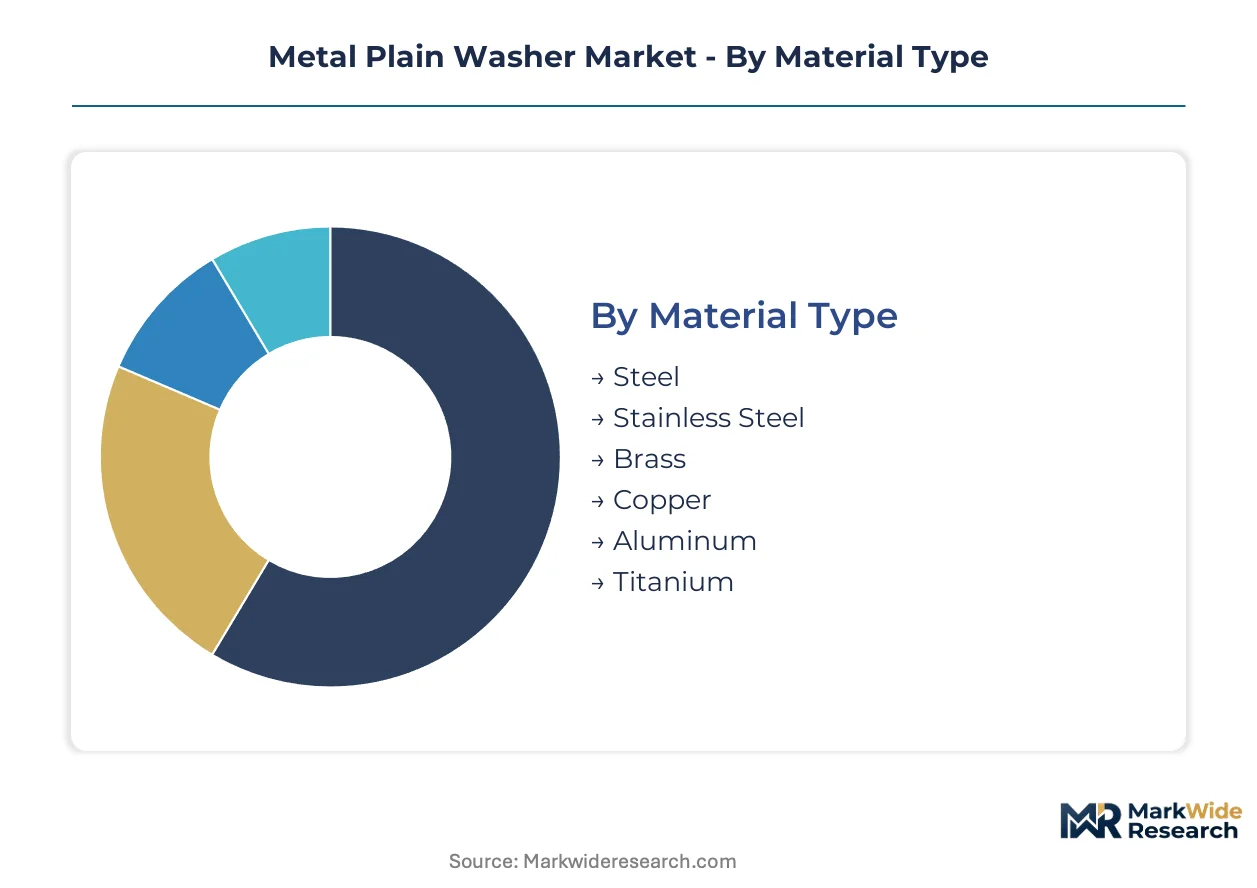
Metal plain washer procurement patterns diverge sharply across material grades and surface treatments, with regulatory compliance in the European Union and seismic code amendments in Japan and California fragmenting supplier qualification pathways. Specification complexity increases downstream as end-users document embodied carbon under CSRD mandates and trace mill-specific scrap content.
Material Type:
REACH and RoHS compliance timelines in Europe favor materials with inherent corrosion resistance over surface-treated alternatives, while seismic code amendments in Japan's METI framework and California building standards elevate hardness requirements for structural grades.
- Steel:Carbon and alloy grades dominate construction and heavy machinery procurement due to cost efficiency in high-volume stamping operations. German industrial buyers around Stuttgart and Dortmund now reject blast-furnace material lacking Environmental Product Declarations, compressing qualification pathways for integrated producers.
- Stainless Steel:304 grades serve general corrosion resistance in food processing; duplex 2205 alloys capture offshore wind monopile connections in the North Sea. Passivation chemistry expertise for chloride-rich marine environments constrains supplier expansion beyond established European mills.
- Brass:Copper-zinc alloys serve electrical conductivity requirements in switchgear and terminal block assemblies.
- Copper:Pure grades address grounding applications and electromagnetic shielding in aerospace cable harnesses.
- Aluminum:Lightweight grades penetrate solar tracking systems where mass reduction improves motor efficiency.
- Titanium:Aerospace-grade specifications command premium positioning for satellite and defense hardware with extreme temperature cycling.
Established volume favors Steel; emerging adoption favors Stainless Steel.
End User Industry:
Customer procurement concentration varies by capital expenditure cycle, with renewable energy developers scaling direct sourcing while automotive tier-one suppliers lock vendor-managed inventory relationships.
- Construction:Structural steel joints under ASTM F436 and ISO 898-1 govern international trade, with seismic load factor revisions redefining hardness specifications. North American building code amendments are elevating demand for hardened grades in infrastructure resilience programs.
- Heavy Machinery:Equipment refurbishment cycles in mining and agriculture extend service lives through systematic fastener replacement. Solon Manufacturing Co.'s captive forging capacity anchors North American supply for critical infrastructure grades facing extended lead times.
- Renewable Energy:Wind turbine OEMs and solar tracking developers in Germany's industrial belt scale washer volumes for nacelle assemblies and racking systems.
- Electrical Equipment:Insulation requirements and conductivity specifications split procurement between metal and polymer composite alternatives.
- Shipbuilding:Marine classification societies specify duplex stainless grades for saltwater exposure in hull and superstructure connections.
- Aerospace Manufacturing:Precision tolerances and traceability requirements exclude catalog distributors from qualification pathways.
Procurement consolidation favors Heavy Machinery; direct sourcing momentum favors Renewable Energy.
Product Size:
Capital intensity in production equipment separates suppliers serving infrastructure-grade demand from those capturing precision-engineered specifications through digital catalog platforms.
- Small:Precision-engineered sizes below 20 mm outer diameter serve electronics and instrumentation with ±0.05 mm tolerances. MISUMI Group Inc.'s parametric search and same-day fulfillment demonstrates scalable penetration of this tier across Asia-Pacific industrial corridors.
- Medium:General industrial applications from 20 mm to 100 mm outer diameter capture the largest volume share in construction and machinery assembly.
- Large:Structural joints from 100 mm to 200 mm outer diameter face heat treatment certification backlogs of 12-16 weeks at accredited laboratories.
- Extra Large:Specialized forging capacity serves infrastructure applications above 200 mm with limited supplier base.
- Custom Dimensions:Non-standard geometries require CNC machining or laser cutting with extended lead times and premium positioning.
Volume concentration favors Medium; margin expansion favors Custom Dimensions.
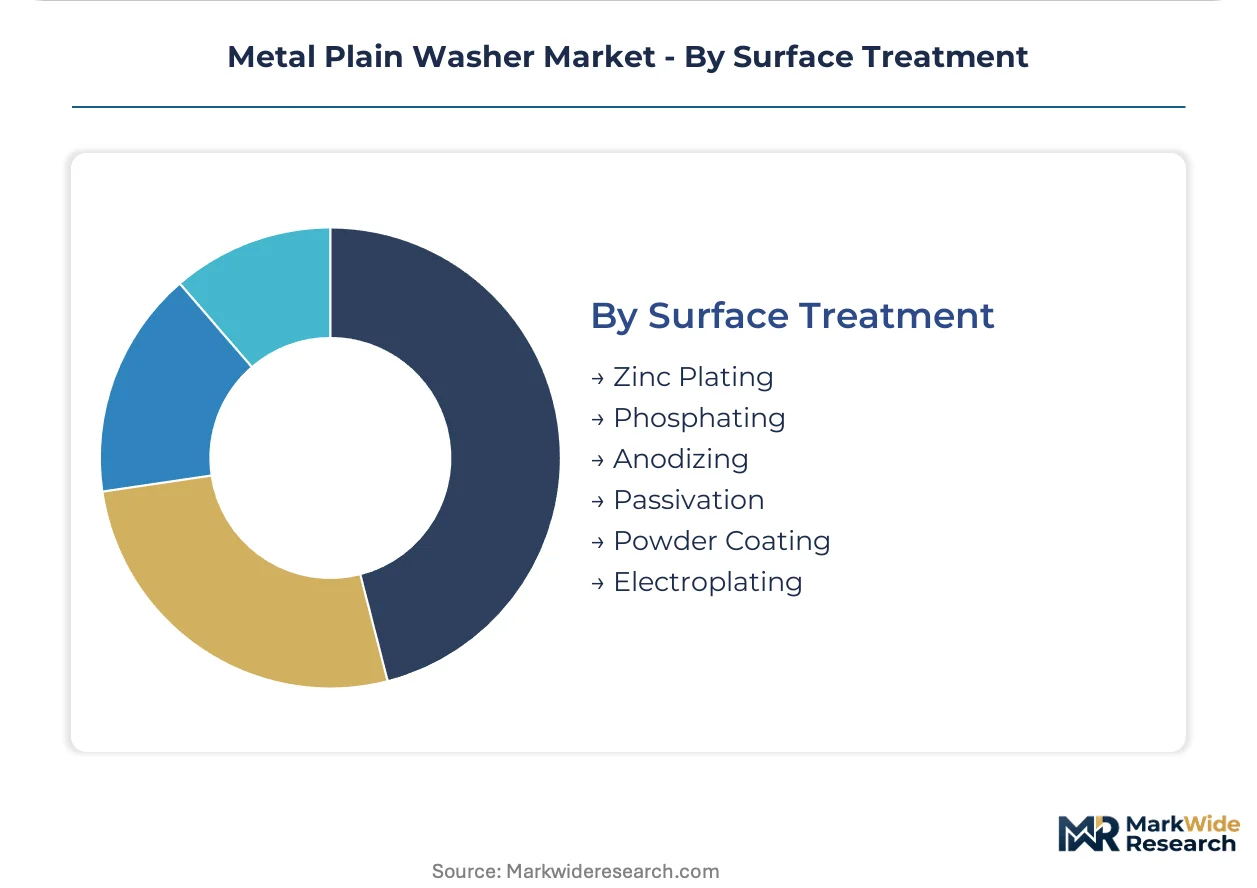
Surface Treatment:
Chemical safety regulations in Europe are phasing out hexavalent chromium treatments, accelerating specification shifts that elevate material-grade solutions over applied coatings.
- Zinc Plating:Traditional hexavalent chromium processes face REACH phase-out timelines, compressing qualification timelines for conventional suppliers. German construction buyers now prioritize mills with verified scrap-recycling content over surface-treated alternatives.
- Passivation:Nitric acid processing for stainless steel grades addresses chloride resistance in marine and chemical processing without coating delamination risk.
- Phosphating:Manganese and zinc phosphate layers improve paint adhesion in automotive and machinery applications.
- Anodizing:Electrochemical oxide layers on aluminum grades enhance wear resistance in solar tracking hardware.
- Powder Coating:Thermoplastic and thermoset applications serve electrical insulation requirements with thicker film builds than electroplating.
- Electroplating:Nickel and tin deposits address conductivity and solderability in electrical terminal applications.
Regulatory pressure favors Passivation; cost-sensitive construction favors Powder Coating.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German mills supply precision-grade stainless washers to offshore wind developers in Denmark and the Netherlands, while Chinese stampers serve Southeast Asian solar tracker manufacturers through direct export channels.
United States
ASTM F436 structural grades face elevated procurement from California infrastructure resilience programs and Texas renewable energy installations. OSHA and state-level building code amendments tighten hardness documentation requirements. Heavy machinery refurbishment clusters in Illinois and Ohio drive systematic fastener replacement cycles.
Germany
REACH and RoHS compliance deadlines accelerate stainless steel substitution in Stuttgart and Dortmund industrial corridors. The EU Green Deal's CSRD disclosure mandates reject blast-furnace material lacking Environmental Product Declarations. Offshore wind developers in the North Sea specify duplex 2205 alloys for monopile connections.
China
MIIT standards and GB certification frameworks govern structural washer exports to Belt and Road infrastructure projects. Dual carbon goals redirect domestic procurement toward electric arc furnace mills with verified scrap content. Yangtze River Delta stampers scale laser cutting capacity for solar tracking hardware.
Japan
METI seismic code amendments tighten hardness specifications for structural joints in Kanto and Kansai building markets. JIS standards differentiate precision-engineered sizes for electronics from infrastructure grades. Chubu region automotive suppliers maintain vendor-managed inventory relationships with tier-one distributors.
India
BIS certification requirements and PLI scheme incentives attract stainless steel stamping capacity for domestic solar and wind installations. CDSCO and central bank infrastructure lending expand construction fastener demand. Maharashtra and Gujarat industrial zones concentrate equipment refurbishment procurement for mining and agriculture machinery.
Metal Plain Washer Market Competitive Landscape
Player mix skews toward mid-cap specialists with captive forging or precision stamping capabilities, creating a tiered structure where scale-driven distributors compete against material-grade specialists. Strategic archetypes include catalog-platform distributors with parametric search infrastructure, stainless steel specialists with vacuum arc remelting partnerships, and captive forgers serving critical infrastructure grades. Consolidation moves center on backward integration into heat treatment certification and geographic expansion through vendor-managed inventory programs.
Within the catalog distribution tier, MISUMI Group Inc. and Bossard occupy positions exemplifying scalable penetration of precision-engineered sizes through digital platforms and same-day fulfillment infrastructure. Solon Manufacturing Co. represents the captive forging archetype, anchoring North American supply for infrastructure grades with extended lead time requirements. These three entities collectively illustrate how capability specialization—whether in distribution technology, material processing, or forging scale—determines competitive positioning across construction, renewable energy, and heavy machinery verticals.
| Leading Market Players |
|---|
| Solon Manufacturing Co. |
| The Hillman Group |
| Willie Washer Manufacturing Corporation |
| Bossard |
| Jergens Inc. |
| Essentra PLC |
| MISUMI Group Inc. |
| Rivit Srl |
| Gris Group |
| Others |
Pricing and Supply Chain Analysis
Heat treatment certification queues stretching 12-16 weeks at accredited laboratories concentrate pricing power with forgers holding captive capacity, while spot buyers face cost premiums for expedited structural grades. This lead-time compression rewards integrated mills with in-house validation, squeezing margin predictability for stampers dependent on third-party testing.
Pricing Analysis
Three-tier pricing structure across precision-engineered, infrastructure-grade, and commodity levels separates catalog distributors from captive forgers and spot-market stampers. Price differentiation rests on certification tier—ASTM F436 structural validation commands premium positioning over general industrial grades—and volume scale, with automotive tier-one contracts locking in long-term offtake. Cost compression in commodity carbon steel is intensifying because electric arc furnace input volatility passes through to construction contractors. Renewable energy developers show least price sensitivity due to project-financing structures, while maintenance-repair-operations procurement faces acute budget constraints.
Supply Chain Analysis
Strait of Malacca transit underwrites Southeast Asian solar tracker component flows, creating vulnerability to port congestion and customs delays. Raw material sourcing concentrates in China, Germany, and India for steel coil feedstock, with passivation chemistry for duplex grades drawing from specialized European mills. Scrap-recycling verification requirements under CSRD disclosure mandates introduce single-source vulnerability for blast-furnace-dependent stampers. Distribution runs through vendor-managed inventory programs at automotive tier-one suppliers and digital catalog platforms for precision-engineered sizes.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is concentrating among renewable energy developers scaling direct sourcing, fragmenting procurement relationships that previously ran through construction contractor intermediaries. This shift elevates specification influence for project developers while compressing margin pools for distributor-dependent stampers.
For Market Incumbents: Secure backward integration into heat treatment certification to bypass laboratory queue bottlenecks. Lock long-term scrap-supply agreements with electric arc furnace mills to satisfy CSRD disclosure requirements from German industrial buyers. Defend against polymer composite substitution in electrical insulation applications by emphasizing clamping-load reliability above 50 N thresholds.
For New Entrants and Emerging Players: Digital catalog infrastructure gaps in precision-engineered sizes below 20 mm present white-space entry points. Target solar tracking hardware procurement in the Yangtze River Delta, where laser cutting capacity scales faster than quality validation. Enter through parametric search platforms offering same-day fulfillment, mirroring MISUMI Group Inc.'s Asia-Pacific penetration model.
For Investors and Strategic Acquirers: Carve-out targets emerge from diversified industrial conglomerates with under-optimized washer divisions lacking CSRD-aligned carbon accounting. Five-to-ten-year viability favors stainless steel specialists with vacuum arc remelting partnerships over commodity carbon stampers. Monitor seismic code amendment progress at Japan's METI and California's building standards as inflection indicators for hardened-grade demand acceleration.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Heat Treatment Certification | Bypasses 12-16 week laboratory queues that constrain structural-grade supply. |
| CSRD-Aligned Scrap Content Verification | Secures qualification pathways with Stuttgart and Dortmund industrial buyers. |
| Digital Catalog Platform Development | Captures precision-engineered demand through parametric search infrastructure. |
| Duplex 2205 Alloy Capacity Expansion | Serves North Sea offshore wind monopile specifications displacing 316L grades. |
| Vendor-Managed Inventory Program Deployment | Locks automotive tier-one supply relationships against spot-market competitors. |
Research Methodology
Initial hypotheses were tested against primary input from heavy machinery procurement directors, fastener distributor category managers, renewable energy project developers, and steel mill technical sales leads and refined through secondary validation. Sources included customs trade databases for steel coil and washer shipments, SEC filings from listed industrial distributors, REACH and RoHS regulatory filings, and ISO 898-1 certification records. Bottom-up demand modeling across end-use industries triangulated against top-down steel consumption forecasts.
Variance decomposition across material grade, surface treatment, end-use vertical, and regional regulatory cluster shaped the analytical framework. CAGRs were derived from segment-level volume trajectories weighted by value-per-unit differentials. Key inputs encompassed electric arc furnace capacity expansion timelines, seismic code amendment adoption curves, and wind turbine installation forecasts.
Forecasts assume regulatory continuity in EU Green Deal implementation and METI seismic standards; material policy shifts would require re-modeling. Steel coil price volatility and polymer composite substitution rates in electrical applications represent primary revision risks. Practitioners should keep alternative scenarios live as REACH compliance timelines and offshore wind procurement cycles evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Material Handling Equipment
Container Handler Market
Material Handling Equipment
High-Pressure Die Casting Market
Material Handling Equipment
Industrial Sheaves and Pulleys Market
Material Handling Equipment
Japan Conveyor Belt Market
Material Handling Equipment
Carry Deck Crane Market
Material Handling Equipment
Dynamic Compactor Market
Material Handling Equipment
Telehandler Market
Material Handling Equipment
Rough Terrain Lift Truck Market
Material Handling Equipment
Precision Gearbox Machinery Market
Material Handling Equipment
Europe Forklift Truck Market
Material Handling Equipment
Manual Lifting Mobile Light Tower Market
Material Handling Equipment
Heavy Equipment Movers Market
Material Handling Equipment
Truck Loader Crane Market
Material Handling Equipment
Wood Chipper Market
Material Handling Equipment
Selective Pallet Racking System Market
Material Handling Equipment
Pick and Carry (PNC) Crane Market