
 Hook Loader Market | 2026-2036
Hook Loader Market Size, Share, and Industry Trends Forecast 2026-2036
Hook Loader Market Analytics
EU Stage V emissions compliance is hardening the cost-of-entry calculus for diesel-powered hook loader manufacturers. Meiller Group leverages its Munich engineering base to sustain premium positioning in heavy-duty hydraulic systems. Hyva Group anchors its competitive stance through backward integration into cylinder manufacturing, while PALFINGER Group differentiates via modular container handling architectures that span multiple payload classes.
A hook loader is a hydraulically actuated truck-mounted mechanism designed to lift, transport, and demount interchangeable roll-off containers using a curved arm and hook engagement system, typically rated for payloads from 5 to 20 tons depending on chassis configuration. Its primary industrial purpose is enabling efficient multimodal logistics where a single prime mover cycles through specialized containers for construction debris, municipal waste, or bulk materials. Heavy-duty hook loaders command the deepest margin pools owing to longer replacement cycles and aftermarket parts dependency, whereas electric hook loaders represent the fastest-expanding product category as fleet operators confront urban low-emission zone mandates. Rental services as an end-user segment exhibit structural growth as capital-light procurement models displace direct ownership among mid-sized contractors.
EMA equipment standards, EU F-Gas Regulation for hydraulic refrigerants, and national type-approval frameworks administered by Germany's KBA collectively shape product certification pathways and cross-border market access for hook loader OEMs. EPA Tier 4 Final requirements in the United States impose parallel compliance burdens on exported diesel-hydraulic units, compressing development timelines for dual-certification programs. Stakeholders must monitor how battery-electric chassis integration standards evolve, since powertrain interoperability will determine which suppliers retain specification control in next-generation municipal tenders.
Market Dynamics
EU Stage V emissions mandates and zero-emission zone expansions are compressing the diesel hook loader replacement cycle while accelerating electric platform development timelines. Manufacturers face simultaneous pressure to certify dual powertrain architectures and absorb battery supply chain volatility.
Growth Catalysts
- EU Green Deal landfill diversion targets:German waste management fleets are expanding hook loader deployment to meet mandatory waste sorting and recycling quotas, creating sustained equipment demand.
- Nordic municipal silent operation mandates:Oslo, Stockholm, and Copenhagen procurement specifications now prioritize electric hook loaders for urban waste collection routes.
- Construction debris volume growth:Infrastructure renewal programs across Western Europe are generating roll-off container turnover that requires flexible prime mover utilization.
Market Restraints
- High-voltage battery cost volatility:Lithium-ion cell price fluctuations compress margin visibility for electric hook loader OEMs developing municipal fleet offerings.
- Hydraulic component supply concentration:Precision cylinder and valve manufacturing clusters in Southern Germany create single-source vulnerability for mid-tier assemblers.
- Dual certification burden:EPA Tier 4 Final and EU Stage V parallel compliance extends development timelines and freezes platform architecture decisions.
Strategic Opportunities
- Underpenetrated Nordic rental markets:Norway and Finland exhibit low hook loader rental penetration relative to equipment utilization rates, suggesting channel expansion potential.
- Battery-electric chassis interoperability standards:Emerging OEM-agnostic powertrain interfaces could open specification control to hydraulic system specialists.
- EU F-Gas Regulation refrigerant transition:Hydraulic fluid thermal management redesign creates aftermarket service attachment opportunities for compliant system retrofits.
Industry Challenges
- Electromechanical integration skill scarcity:Fleet maintenance departments lack technicians trained on high-voltage hook loader diagnostics and battery thermal management.
- Homologation timeline compression:Germany's KBA type-approval backlogs delay market entry for new electric platform variants.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Hook Loader Market |
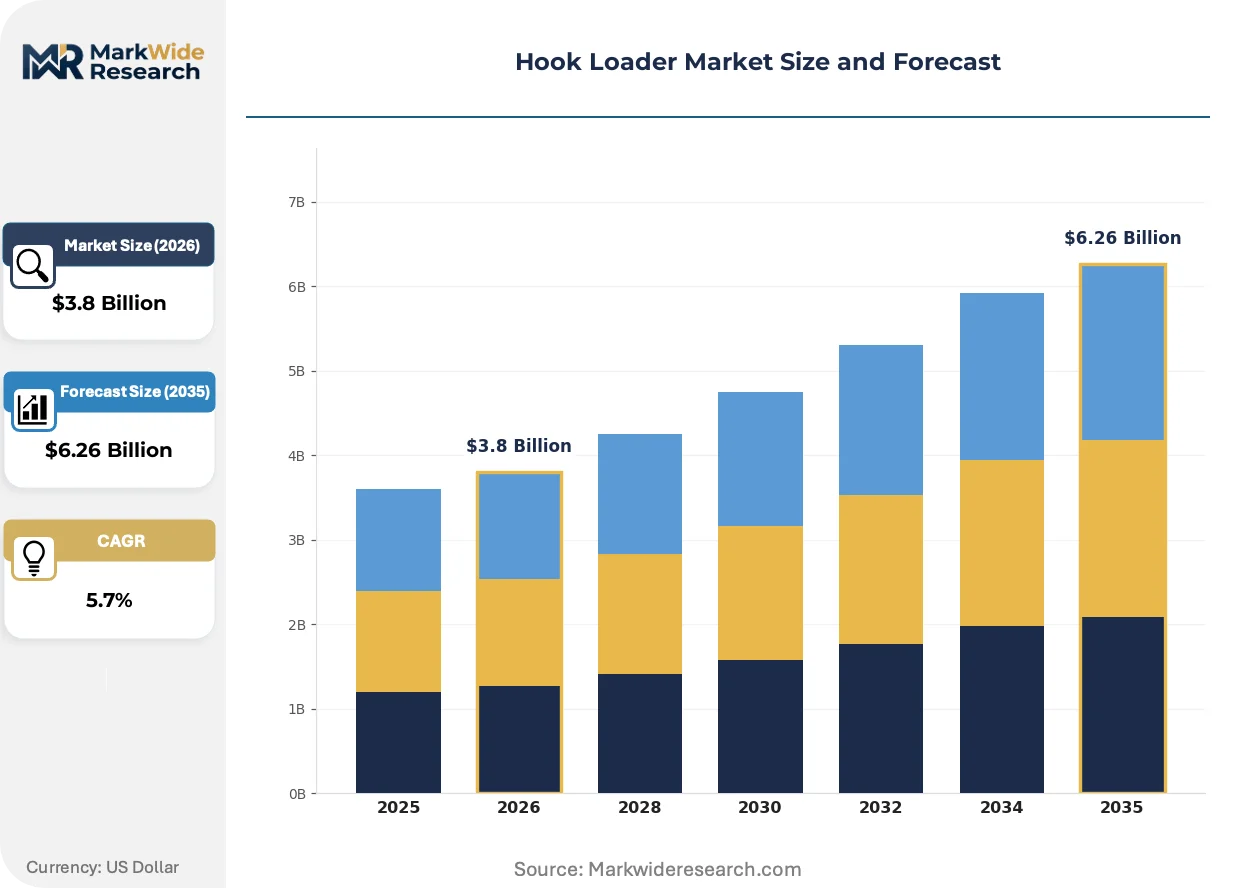
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.26 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Standard Hook Loader, Heavy-Duty Hook Loader, Mini Hook Loader, Electric Hook Loader End User: Construction, Waste Management, Rental Services, Municipalities Deployment: On-Road, Off-Road, Trailer Mounted, Stationary Capacity: 5 Ton, 10 Ton, 15 Ton, 20 Ton |
| Companies Covered | Meiller Group, Stellar Industries, Marrel Corporation, Hyva Group, Galbreath, Cargotec Corporation, B.O.B. Sistemi Idraulici, VDL Containersystemen, PALFINGER Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Hook Loader Market Evolving Landscape
Electrification is fragmenting the hook loader competitive landscape as hydraulic specialists confront powertrain integration decisions. Three developments are redefining product architecture and go-to-market approaches.
Lithium-iron-phosphate battery packs are absorbing thermal stability requirements that previously constrained electric hook loader duty cycles. Municipal fleet operators in Denmark and Sweden are specifying these chemistries for year-round container handling operations. The technology is absorbing range anxiety barriers that previously limited electric platform adoption in heavy-lift applications.
EU F-Gas Regulation phase-down schedules are forcing refrigerant transitions in hydraulic cooling systems. Equipment OEMs must redesign thermal management architectures to accommodate lower-global-warming-potential alternatives. Germany's KBA certification pathway is tightening documentation requirements for these system modifications.
Mid-sized contractors are abandoning direct equipment ownership for rental and lease-to-service arrangements. Equipment finance providers are consolidating specification influence previously held by fleet procurement departments. This behavioral shift concentrates most visibly in Benelux construction markets where project-based contracting dominates equipment utilization patterns.
Hook Loader Market Segmentation
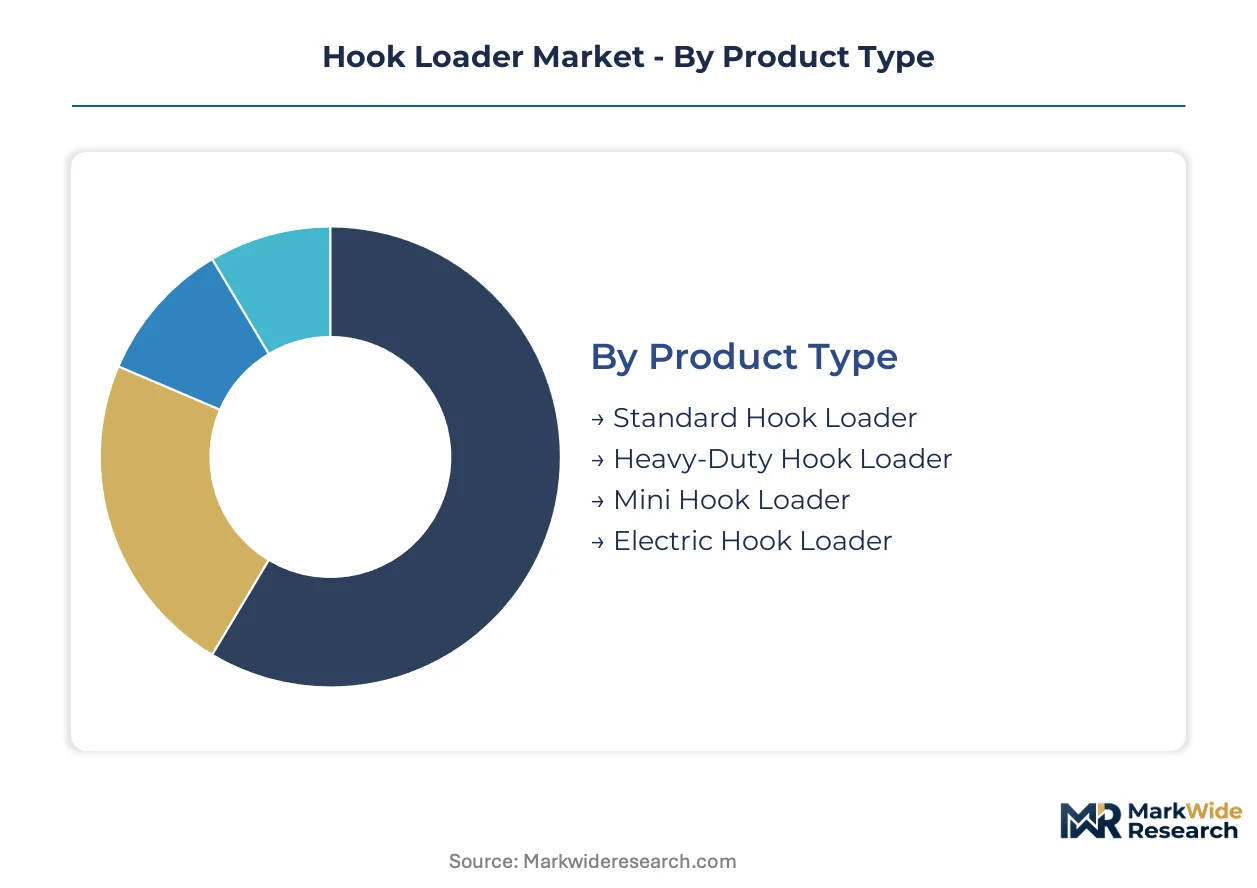
Hook loader procurement patterns diverge sharply across payload ratings, powertrain architectures, and ownership models. Fleet operators segment equipment choices by route density, emission zone exposure, and container turnover frequency rather than upfront capital cost alone.
Product Type:
Supply concentration in hydraulic cylinder manufacturing favors established European OEMs serving heavy-duty and electric platform categories.
- Heavy-Duty Hook Loader:Rated for 15-20 ton payloads with reinforced chassis mounting and high-pressure hydraulic circuits. German waste-to-energy fleets and Scandinavian timber transport operators specify these units for continuous-duty cycles exceeding 16 hours daily. Replacement parts dependency sustes aftermarket revenue streams across decade-long service intervals.
- Electric Hook Loader:Battery-electric powertrain integration with regenerative braking and silent hydraulic pump operation. Oslo, Stockholm, and Copenhagen municipal tenders now mandate zero-emission hook loaders for urban core waste collection routes. Lithium-iron-phosphate thermal stability enables year-round Nordic deployment.
- Standard Hook Loader:Mid-range 8-12 ton payload rating serving generalist contractors across Benelux construction markets.
- Mini Hook Loader:Compact 3-5 ton units for restricted-access urban sites and narrow rural roadways.
Today's leader: Heavy-Duty Hook Loader. Tomorrow's challenger: Electric Hook Loader.
End User:
Capital deployment patterns separate ownership-intensive users from rental-dependent segments.
- Waste Management:Integrated collection-to-treatment operators running dedicated container fleets under long-term municipal concessions. EU Green Deal landfill diversion mandates in Germany and France are accelerating equipment refresh cycles. Route electrification timelines concentrate procurement authority at regional environmental agency level.
- Rental Services:Equipment finance providers and specialized lessors absorbing capital-light demand from mid-sized contractors. Benelux markets exhibit highest rental penetration rates as project-based contracting displaces fleet ownership. Specification influence is consolidating with lessor procurement departments.
- Construction:Debris handling at infrastructure renewal sites across Western Europe drives roll-off container turnover.
- Municipalities:Direct fleet ownership persists in smaller Nordic and Alpine cities with stable long-term waste collection mandates.
Volume concentrates with Waste Management. Margin expansion sits with Rental Services.
Deployment:
Regulatory homologation pathways diverge between road-certified and off-highway equipment categories.
- On-Road:Full EU type-approval under Germany's KBA framework with Stage V emission certification or electric equivalent. Urban low-emission zone expansion across Paris, London, and Milan is compressing diesel platform residual values. Battery-electric chassis interoperability standards remain unresolved.
- Trailer Mounted:Modular prime mover attachment enabling flexible fleet utilization across seasonal demand peaks. German agricultural cooperatives and Austrian forestry operations deploy these for intermittent bulk material transport. KBA certification treats trailer-mounted hydraulic systems as distinct from integrated chassis installations.
- Off-Road:Quarries, mines, and unimproved construction sites without highway speed requirements.
- Stationary:Fixed-position container transfer stations with grid-connected power supply.
Homologation burden heaviest for On-Road. Flexibility premium commands Trailer Mounted.
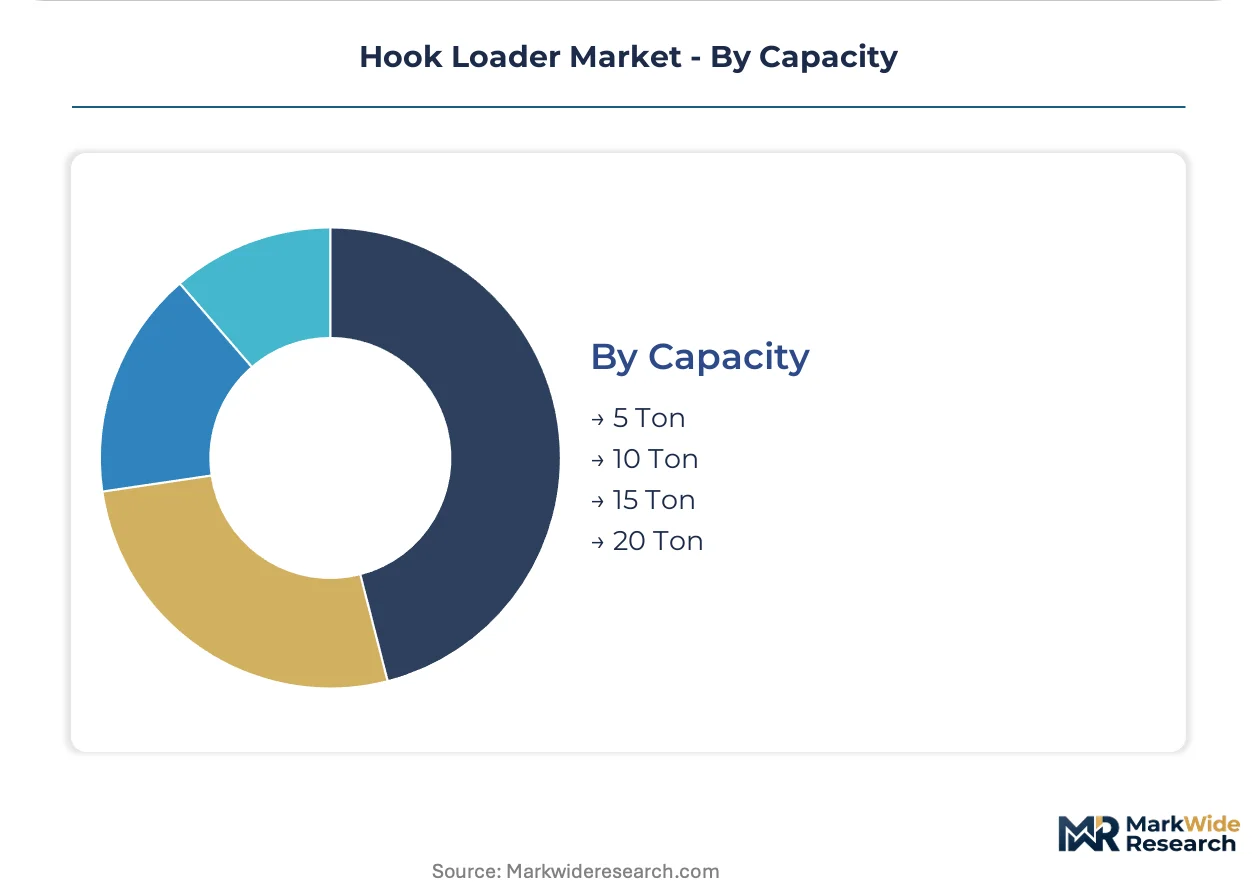
Capacity:
Payload rating determines hydraulic system specification, chassis integration complexity, and aftermarket parts dependency.
- 20 Ton:Maximum rating for standard EU road-legal configurations with tridem axle chassis. Heavy construction debris and industrial waste streams in Germany's Ruhr industrial corridor generate concentrated demand. Cylinder seal replacement intervals and boom fatigue monitoring sustain service contract attachment rates.
- 10 Ton:Versatile mid-range specification balancing route maneuverability with container volume efficiency. Danish and Dutch municipal fleets standardize on this rating for mixed residential-commercial collection. Dual-certification burden for EPA Tier 4 Final and EU Stage V compliance falls most heavily at this volume tier.
- 5 Ton:Restricted-access urban and narrow rural applications with single-axle chassis limitations.
- 15 Ton:Regional specialization for high-density waste streams and timber transport in Nordic markets.
Aftermarket value pools deepest at 20 Ton. Specification standardization centers on 10 Ton.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German hydraulic engineering talent clusters around Munich and Stuttgart anchor European hook loader innovation. Nordic municipal procurement teams in Oslo and Stockholm drive electric platform specification. Benelux rental finance providers concentrate equipment ownership influence in Antwerp and Rotterdam.
Germany
Waste-to-energy fleet operators in the Ruhr industrial corridor refresh heavy-duty units under EU Green Deal landfill diversion mandates. KBA type-approval frameworks govern cross-border equipment certification for road-legal configurations. Munich-based hydraulic system specialists supply precision cylinders to domestic OEMs serving 20-ton payload segments.
Sweden
Stockholm municipal tenders mandate silent electric hook loaders for urban core waste collection routes. EU F-Gas Regulation phase-down schedules force refrigerant transitions in hydraulic cooling architectures. Göteborg equipment lessors consolidate specification influence as project-based contracting displaces direct fleet ownership among mid-sized contractors.
France
Paris low-emission zone expansion compresses diesel platform residual values and accelerates battery-electric procurement timelines. EMA equipment standards shape hydraulic system certification pathways for cross-border market access. Lyon construction debris handlers drive roll-off container turnover at infrastructure renewal sites across the Auvergne-Rhône-Alpes region.
Netherlands
Rotterdam rental services exhibit structural growth as capital-light procurement models displace direct ownership. Benelux municipal fleets standardize on 10-ton payload ratings for mixed residential-commercial collection routes. Eindhoven region equipment finance providers absorb specification authority previously held by fleet procurement departments.
United States
EPA Tier 4 Final requirements impose parallel compliance burdens on exported diesel-hydraulic units. Infrastructure renewal programs generate construction debris volume requiring flexible prime mover utilization. Midwest equipment distributors face dual-certification timeline compression for platforms serving both domestic and European export markets.
Hook Loader Market Competitive Landscape
The competitive structure tilts toward hydraulic system specialists with captive manufacturing capabilities. European OEMs dominate premium-tier positioning through backward integration into precision component production. Three archetypes define the field: integrated hydraulic specialists controlling cylinder supply, modular architecture providers spanning payload classes, and rental-channel-focused assemblers serving capital-light demand. Capacity expansion in Nordic electric platforms and strategic partnerships around battery-electric chassis interoperability represent dominant competitive vectors.
Among Munich-based engineering houses, Meiller Group occupies a position exemplifying premium hydraulic system integration. Hyva Group anchors the integrated manufacturing archetype through in-house cylinder production capabilities. PALFINGER Group sits within the modular architecture tier, representing specification flexibility across multiple payload ratings. These three European entities collectively illustrate how geographic proximity to German automotive and industrial clusters shapes competitive positioning in road-legal equipment categories.
| Leading Market Players |
|---|
| Meiller Group |
| Stellar Industries |
| Marrel Corporation |
| Hyva Group |
| Galbreath |
| Cargotec Corporation |
| B.O.B. Sistemi Idraulici |
| VDL Containersystemen |
| PALFINGER Group |
| Others |
Value Network & Pricing Analysis
Nordic municipal silent operation mandates are compressing procurement timelines for electric hook loader platforms, forcing manufacturers to absorb battery supply chain volatility while repositioning hydraulic system pricing around thermal management redesign costs.
Pricing Analysis
Equipment-as-a-service bundling separates capital-light rental arrangements from direct ownership models. Three-tier pricing structure across premium, standard, and economy levels reflects EU Stage V certification tiers and aftermarket service attachment depth. Pricing pressure stems from lithium-ion cell cost fluctuations compressing margin visibility for electric platform OEMs. Rental services exhibit lowest price sensitivity owing to consolidated specification influence, whereas mid-sized contractors in Benelux markets drive hardest bargain hunting.
Supply Chain Analysis
Regional distribution centers in Southern Germany anchor hub-and-spoke patterns for precision hydraulic components. Manufacturing concentrates in Germany, Italy, and the Netherlands for cylinder and valve assemblies. Raw material dependencies span high-grade steel alloys, specialized hydraulic seals, and lithium-iron-phosphate battery cells. Single-source vulnerability in Southern German precision manufacturing clusters creates structural risk. Distribution runs through OEM-direct channels for heavy-duty units and specialized lessor networks for rental fleet deployment.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
EU Green Deal landfill diversion mandates create geographic-arbitrage potential between German waste-to-energy fleet refresh cycles and underpenetrated Nordic rental markets where procurement criteria diverge sharply.
For Market Incumbents: Cement hydraulic system specification control through backward integration into cylinder manufacturing and captive thermal management R&D. Battery-electric chassis interoperability standards threaten to disintermediate hydraulic specialists from municipal tender authority. Priority lever rests on KBA certification pathway acceleration for electric platform variants. For New Entrants and Emerging Players: Begin with trailer-mounted modular configurations in Norwegian and Finnish agricultural cooperatives where rental penetration lags utilization rates. White space concentrates in seasonal bulk material transport segments currently served by improvised prime mover attachments. Go-to-market angle emphasizes flexible lease-to-service arrangements displacing direct ownership. For Investors and Strategic Acquirers: Asymmetric upside sits with hydraulic component specialists possessing KBA certification expertise and electric platform thermal management IP. Long-term viability hinges on specification retention as battery-electric chassis standards crystallize. Acquisition target archetype: mid-tier assemblers with dormant KBA approvals and regional service networks. Signal to watch: Oslo and Stockholm tender documents dropping diesel compatibility requirements.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Cylinder Manufacturing | Hyva Group's captive supply chain insulates margin pools from Southern German component concentration risk. |
| Electric Platform KBA Certification Acceleration | Meiller Group's Munich engineering base positions for first-mover advantage in municipal zero-emission tenders. |
| Modular Container Handling Architecture Expansion | PALFINGER Group's payload-spanning designs capture specification flexibility across 10-ton and 20-ton fleet segments. |
| Nordic Rental Channel Partnership Development | VDL Containersystemen's Benelux lessor relationships provide template for Norway and Finland market entry. |
| Hydraulic Cooling System F-Gas Compliance Retrofit | EU refrigerant phase-down schedules create aftermarket service attachment opportunities for compliant system redesign. |
Research Methodology
Bottom-up municipal fleet procurement modeling reconciled against top-down hydraulic component production tracking forms the analytical core. Primary interviews with waste management fleet directors, municipal tender specification officers, hydraulic system procurement leads, and equipment finance provider portfolio managers combined with secondary validation from KBA type-approval databases, EU F-Gas Regulation implementation reports, EMA equipment standards documentation, and national waste diversion statistics. Triangulation across stakeholder perspectives and regulatory filings grounds volume and value estimates.
Input-output matrices map hook loader deployment to container turnover frequency, route electrification timelines, and chassis replacement cycles across the projection horizon. Segmentation dimensions include payload rating, powertrain architecture, ownership model, and regional regulatory cluster. CAGRs derive from equipment refresh cycle compression under emission mandates and rental penetration trajectory modeling. Industry-specific forecast inputs incorporate battery-electric chassis interoperability standard evolution and hydraulic refrigerant transition cost curves.
Several conditions sit outside the modeled scope, including unannounced regulatory timeline accelerations, battery chemistry disruptions beyond lithium-iron-phosphate, and chassis OEM vertical integration into hydraulic systems. Forecasts reflect documented assumptions about tender award patterns and fleet operator procurement behavior. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Material Handling Equipment
US Forklift Market
Material Handling Equipment
High Pressure Grinding Rollers Market
Material Handling Equipment
Rubber Tyre Gantry Crane Market
Material Handling Equipment
Die Casting Market
Material Handling Equipment
Explosion Proof Crane Market
Material Handling Equipment
Dump Tubs Market
Material Handling Equipment
Slag Handling Machine Market
Material Handling Equipment
High-Pressure Die Casting Market
Material Handling Equipment
Belt Weigh Feeder Market
Material Handling Equipment
Enclosed Belt Conveyors Market
Material Handling Equipment
North America Forklift Market
Material Handling Equipment
Push-Back Racking System Market
Material Handling Equipment
Machined Springs Market
Material Handling Equipment
Drum Handling Equipment Market
Material Handling Equipment
Sweep Depalletizers Market
Material Handling Equipment
Trencher Attachments Market