
 France Light Commercial Vehicles Market | 2026-2036
France Light Commercial Vehicles Market Size, Share, and Industry Trends Forecast 2026-2036
France Light Commercial Vehicles Market Foresight
Subscription-based fleet management software is restructuring how light commercial vehicles generate recurring revenue for manufacturers and leasing firms. Groupe Renault leverages its domestic manufacturing footprint to anchor contract maintenance programs for small business owners. Mercedes-Benz differentiates through integrated telematics platforms that extend vehicle utility beyond the initial sale. Peugeot S.A. competes on localized service networks that sustain uptime guarantees for urban delivery operators.
Light commercial vehicles in France comprise rigid-body trucks and vans with gross vehicle weights typically below 3.5 tonnes, engineered with unibody or ladder-frame construction for payload durability and maneuverability in dense urban corridors. Panel vans dominate fleet procurement for parcel logistics, while electric powertrains represent the fastest-expanding fuel category as total cost of ownership equations shift under tightening emissions enforcement. Courier services constitute the most concentrated end-user pool, driving standardized vehicle specifications that compress margin variation across manufacturers.
France's Crit'Air vignette system, administered by the Ministry of Ecological Transition, progressively excludes older diesel vans from metropolitan access and redirects procurement toward zero-emission platforms. The European Union's CO2 standards for light commercial vehicles, enforced by national type-approval authorities, mandate manufacturer fleet-average reductions that reshape powertrain development budgets. ANSM and CNIL oversight of connected-vehicle data governance adds compliance layers to telematics service offerings. Stakeholders must weigh residual value risk against electrification timing as regulatory thresholds tighten without uniform urban implementation schedules.
Market Dynamics
The Crit'Air emissions classification system is progressively excluding diesel vans from French metropolitan zones, forcing fleet operators toward electrified platforms and restructuring procurement priorities across urban logistics networks.
Growth Catalysts
- Urban Low-Emission Zones:Crit'Air vignette restrictions in Paris, Lyon, and Grenoble block older diesel vehicles, compelling courier services to accelerate zero-emission fleet turnover.
- Total Cost of Ownership Compression:Battery-electric powertrains achieve operational parity with diesel equivalents under France's carbon taxation and maintenance cost structures.
- Last-Mile E-Commerce Density:Parcel delivery operators concentrate vehicle deployment in Île-de-France, creating standardized demand pools that simplify manufacturer production planning.
Market Restraints
- Charging Infrastructure Gaps:Depot and on-street charging capacity lags electrified fleet expansion in secondary French cities beyond Paris.
- Residual Value Uncertainty:Battery degradation curves and technology obsolescence compress second-hand electric van valuations, elevating leasing risk premiums.
- Grid Connection Delays:ERDF grid reinforcement timelines extend fleet electrification project horizons for small logistics operators.
Strategic Opportunities
- Vehicle-to-Grid Integration:Bidirectional charging protocols enable fleet operators to monetize battery storage through RTE demand-response programs.
- Provincial City Expansion:Crit'Air zone expansion to Toulouse, Nice, and Strasbourg creates replication markets for proven Parisian electrification models.
- Software-Defined Fleets:Over-the-air update capabilities and usage-based insurance products unlock recurring revenue streams from hardware assets.
Industry Challenges
- Technician Training Deficits:High-voltage certification requirements outpace vocational program output, constraining service network capacity for electric powertrain maintenance.
- Interoperability Fragmentation:Proprietary telematics protocols from competing manufacturers complicate mixed-fleet management for multi-brand operators.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | France Light Commercial Vehicles Market |
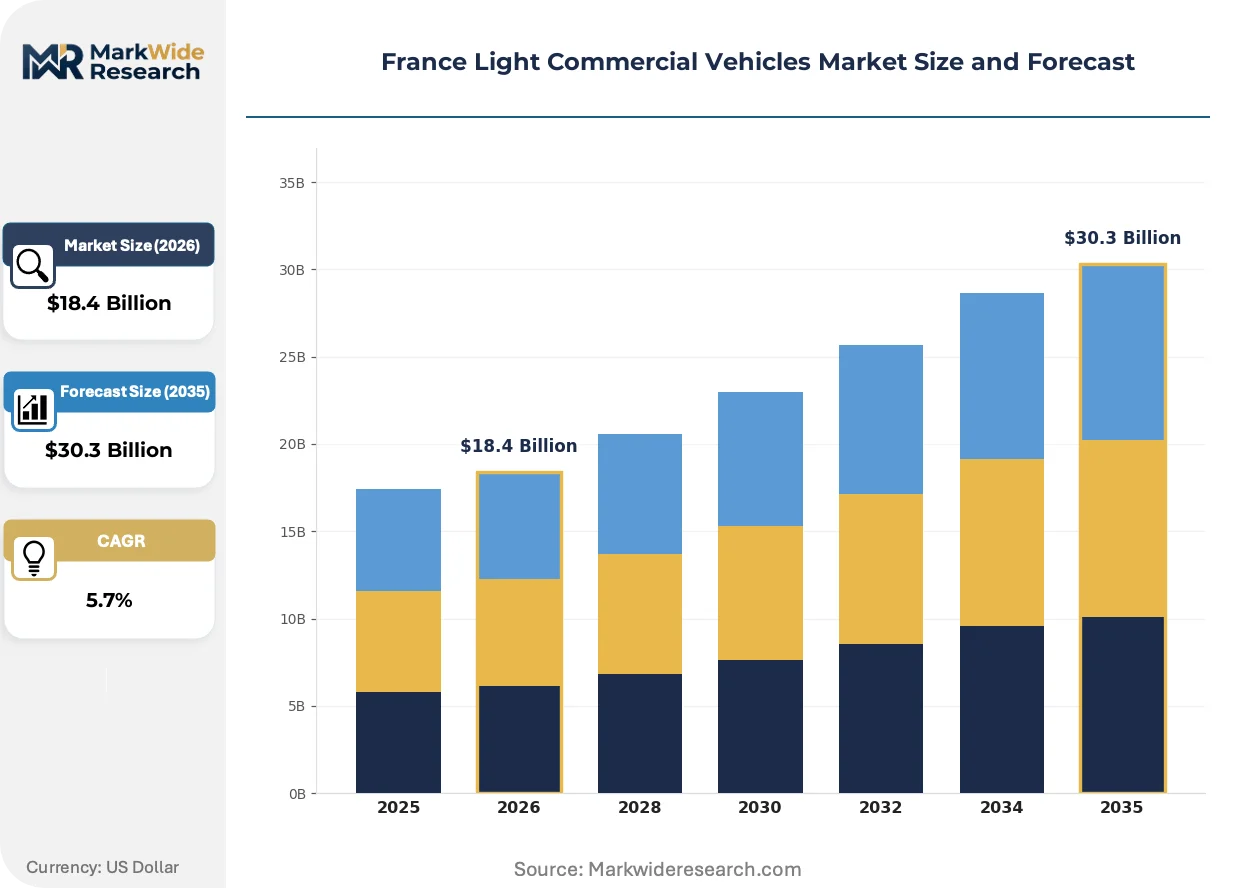
| Market Size in 2026 | $18.4 Billion |
| Market Size in 2035 | $30.3 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Vehicle Type: Pickup Trucks, Panel Vans, Minivans, Flatbed Trucks Fuel Type: Diesel, Petrol, Electric, Hybrid, Compressed Natural Gas End User: Courier Services, Construction Companies, Food & Beverage Distributors, Maintenance Providers Sales Channel: Dealerships, Fleet Sales, Online Platforms, Lease Companies |
| Companies Covered | Mercedes-Benz, Volkswagen AG, Groupe Renault, Toyota Motor Corporation, IVECO S.p.A, Peugeot S.A., Fiat Chrysler Automobiles N.V, Citroën, Ford Motor Company, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
France Light Commercial Vehicles Market Shifts & Advancements
French light commercial vehicle development is pivoting from mechanical durability toward software-enabled service architectures, with electrification and connectivity redefining how value is captured across the vehicle lifecycle.
Modular battery architectures are electrifying fleet procurement economics. Courier operators in Paris and Lyon adopt swappable-cell platforms to minimize downtime during route shifts. This technology is electrifying residual value calculations by decoupling battery ownership from vehicle chassis financing.
France's Ministry of Ecological Transition enforces progressively stringent Crit'Air access tiers through 2030. Municipal police now automate vignette verification via license-plate recognition cameras at zone boundaries. Urban delivery fleets bear the primary compliance burden, accelerating retirement schedules for Euro 5 and earlier diesel platforms.
Subscription-based fleet management contracts displace traditional vehicle ownership among small logistics enterprises. Leasing firms capture maintenance and telematics revenue through bundled per-kilometer pricing. This shift concentrates most visibly in Île-de-France, where standardized urban routes enable precise usage forecasting.
France Light Commercial Vehicles Market Segmentation
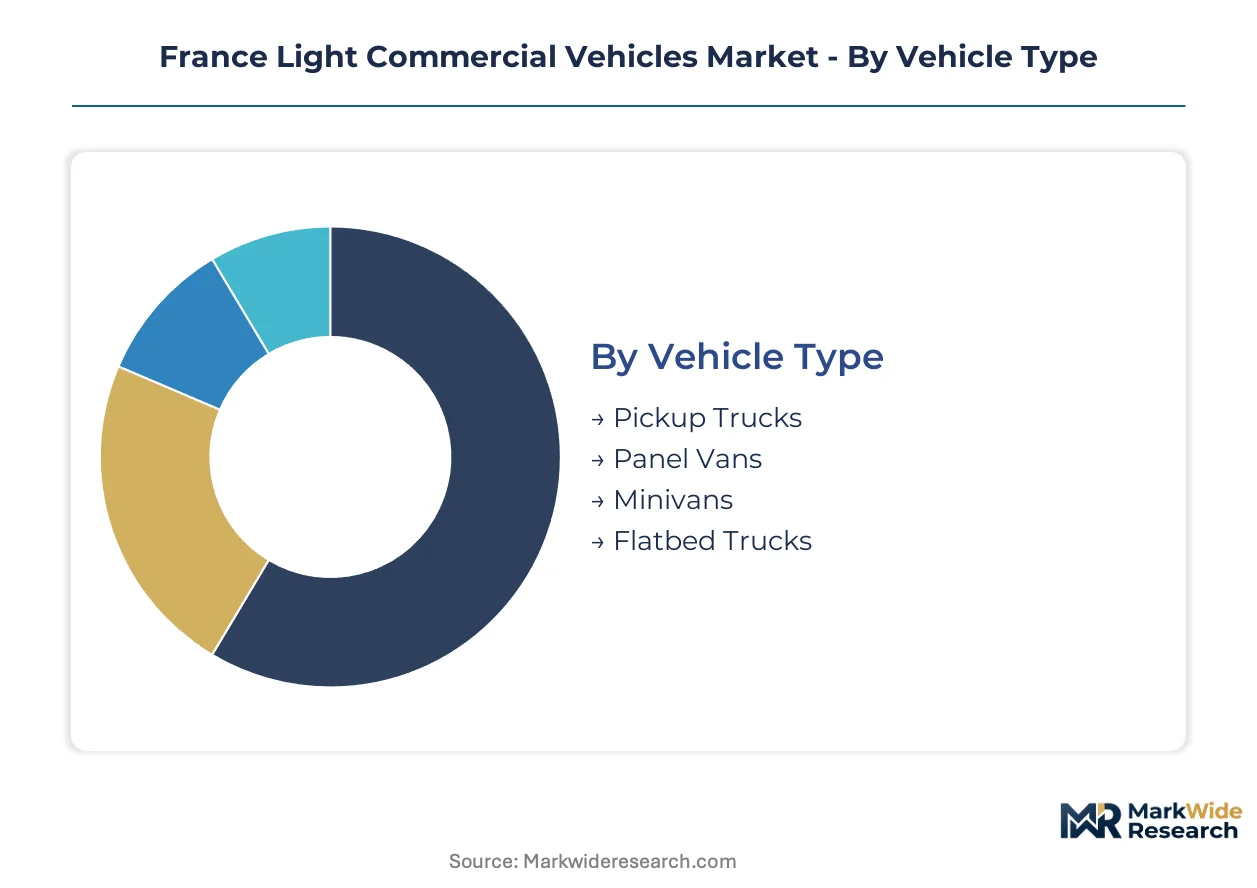
Segmentation in the France light commercial vehicles market reveals how Crit'Air compliance tiers, powertrain economics, and route standardization reshape procurement patterns across urban logistics networks. Each dimension carries distinct certification burdens and total cost of ownership profiles that determine fleet operator choices.
Vehicle Type:
Panel vans and flatbed trucks require type-approval from France's national automotive regulator under EU Whole Vehicle Type Approval frameworks, while pickup trucks face additional payload certification for commercial registration.
- Panel Vans:Rigid-body unibody construction optimized for parcel density in urban corridors. Courier services in Île-de-France standardize on medium-roof configurations to maximize cubic capacity under Crit'Air access rules.
- Pickup Trucks:Ladder-frame chassis with open cargo beds suited for construction material transport. Demand concentrates in peri-urban zones around Lyon and Marseille where diesel access restrictions remain less severe.
- Minivans:Compact passenger-derived platforms with blended commercial utility. Food and beverage distributors favor these for refrigerated last-mile delivery in pedestrianized city centers.
- Flatbed Trucks:Open-deck configurations for oversized or palletized freight. Maintenance providers deploy these for equipment transport across multi-site service contracts.
Leading the category by volume: Panel Vans. Growing fastest: Electric variants of Panel Vans.
Fuel Type:
Powertrain selection directly determines Crit'Air vignette eligibility and metropolitan zone access, with diesel platforms facing progressive exclusion while electric and hybrid systems secure unrestricted urban entry.
- Electric:Battery-electric powertrains with zero tailpipe emissions qualifying for Crit'Air Class 1 access. Courier services in Paris accelerate fleet conversion as depot charging infrastructure expands.
- Diesel:Compression-ignition engines dominating legacy fleet composition. Euro 6 and earlier platforms face automated license-plate recognition enforcement at zone boundaries in Grenoble and Lyon.
- Hybrid:Mild and full-hybrid architectures bridging range and emissions requirements. Lease companies promote these for operators with intermittent urban duty cycles.
- Petrol:Spark-ignition engines limited to light-duty applications. Small maintenance providers favor these for low-mileage service routes.
- Compressed Natural Gas:Dedicated or bi-fuel CNG systems qualifying for Crit'Air Class 1 or 2. Municipal fleets in Toulouse pilot these for refuse collection and utility services.
Volume leadership: Diesel (declining share). Steepest expansion trajectory: Electric.
End User:
Fleet scale and route predictability determine whether end users purchase outright, lease, or subscribe to mobility services, with courier services driving standardization through aggregated demand.
- Courier Services:Parcel and express delivery operators with high-frequency urban routes. These firms concentrate procurement in Île-de-France and pressure manufacturers for uniform specifications.
- Construction Companies:Project-based operators requiring payload flexibility and all-terrain capability. Demand clusters in Grand Est and Auvergne-Rhône-Alpes where infrastructure investment accelerates.
- Food & Beverage Distributors:Temperature-controlled logistics specialists with strict delivery windows. These operators prioritize refrigerated panel vans with telematics integration.
- Maintenance Providers:Multi-site service technicians carrying tools and parts inventory. Route variability drives preference for compact vans with modular interior configurations.
Procurement volume concentrates with: Courier Services. Fastest-growing requirements: Electric refrigeration for Food & Beverage Distributors.
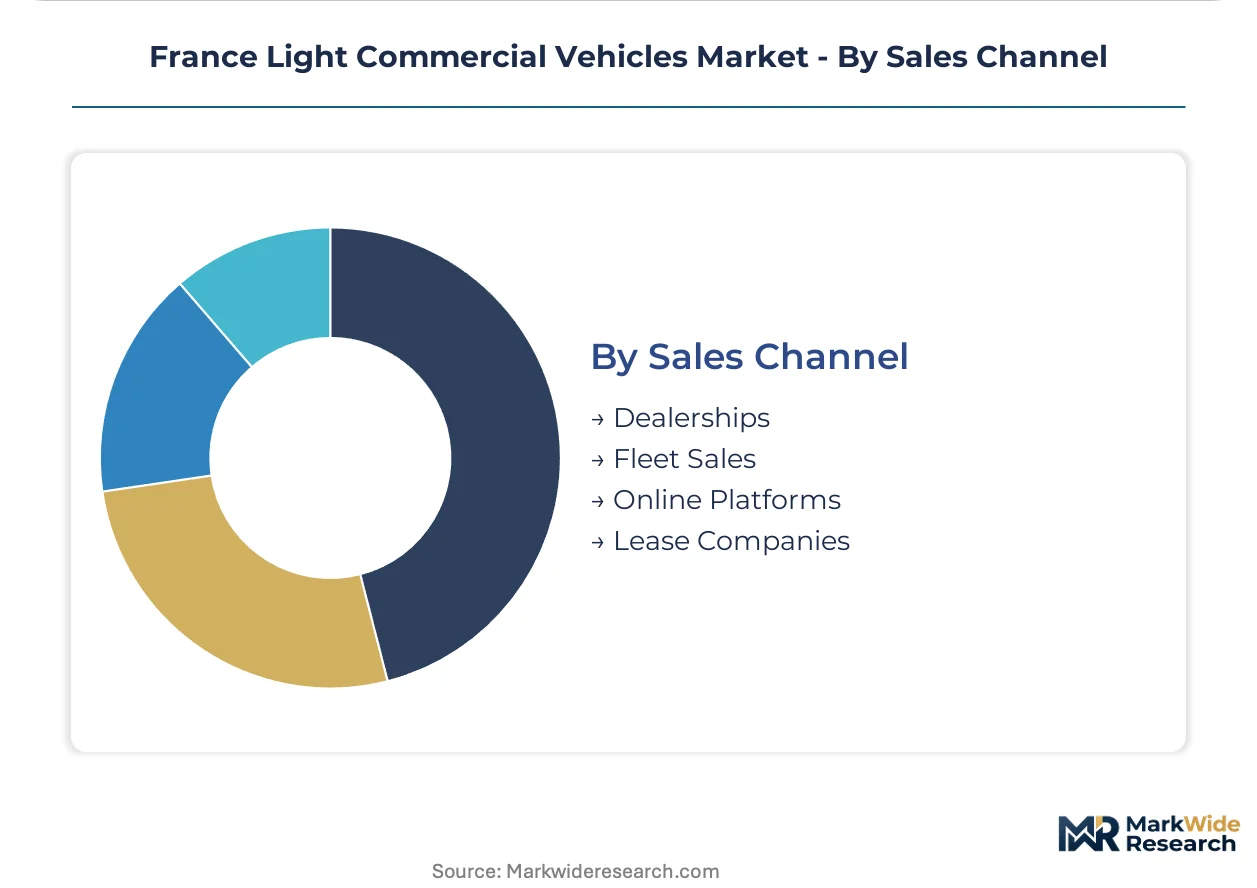
Sales Channel:
Channel selection reflects fleet size and capital structure, with large operators bypassing retail networks while small enterprises rely on bundled service packages.
- Fleet Sales:Direct manufacturer or importer relationships for volume purchasers. Courier services negotiate standardized specifications and maintenance inclusion.
- Lease Companies:Full-service contracts covering vehicle, maintenance, and telematics. Small logistics enterprises in secondary cities adopt subscription models to transfer residual value risk.
- Dealerships:Retail network transactions for owner-operators and micro-fleets. These channels emphasize localized service capacity and parts availability.
- Online Platforms:Digital configurators and reservation systems for transparent pricing. Younger fleet managers use these to compare total cost of ownership scenarios.
Transaction volume leader: Fleet Sales. Channel expanding most quickly: Online Platforms.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
France's light commercial vehicle production clusters in northern manufacturing belts while consumption concentrates in Parisian logistics corridors and Mediterranean port zones. Domestic assembly plants supply domestic demand with limited export orientation.
Île-de-France
Courier services dominate procurement volume in the Paris metropolitan zone. Crit'Air restrictions enforced by municipal police block diesel vans from central arrondissements. Roissy-Charles de Gaulle logistics parks anchor electrified last-mile distribution networks serving e-commerce fulfillment centers.
Auvergne-Rhône-Alpes
Lyon's expanding low-emission zone redirects fleet procurement toward hybrid and electric platforms. Construction material distributors in Grenoble face overlapping Alpine access restrictions. Saint-Étienne manufacturing subcontractors maintain mixed diesel-electric fleets for intercity component delivery.
Provence-Alpes-Côte d'Azur
Marseille-Fos port logistics drive flatbed truck demand for containerized freight distribution. Nice implements automated license-plate recognition for Crit'Air enforcement along coastal routes. Temperature-controlled van procurement accelerates for pharmaceutical distribution from Sophia Antipolis clusters.
Hauts-de-France
Lille's cross-border logistics position generates demand for dual-registered commercial vehicles serving Belgian markets. Dunkirk industrial zones retain diesel dependency longer than national averages due to heavy freight corridors. Renault's Douai manufacturing presence anchors regional supplier networks for electric powertrain components.
Nouvelle-Aquitaine
Bordeaux wine logistics sustain specialized refrigerated van demand with strict delivery windows. Toulouse aerospace supply chains require compact vans for precision component transport. Biogas and CNG infrastructure expansion supports municipal fleet conversion in medium-density urban centers.
France Light Commercial Vehicles Market Competitive Landscape
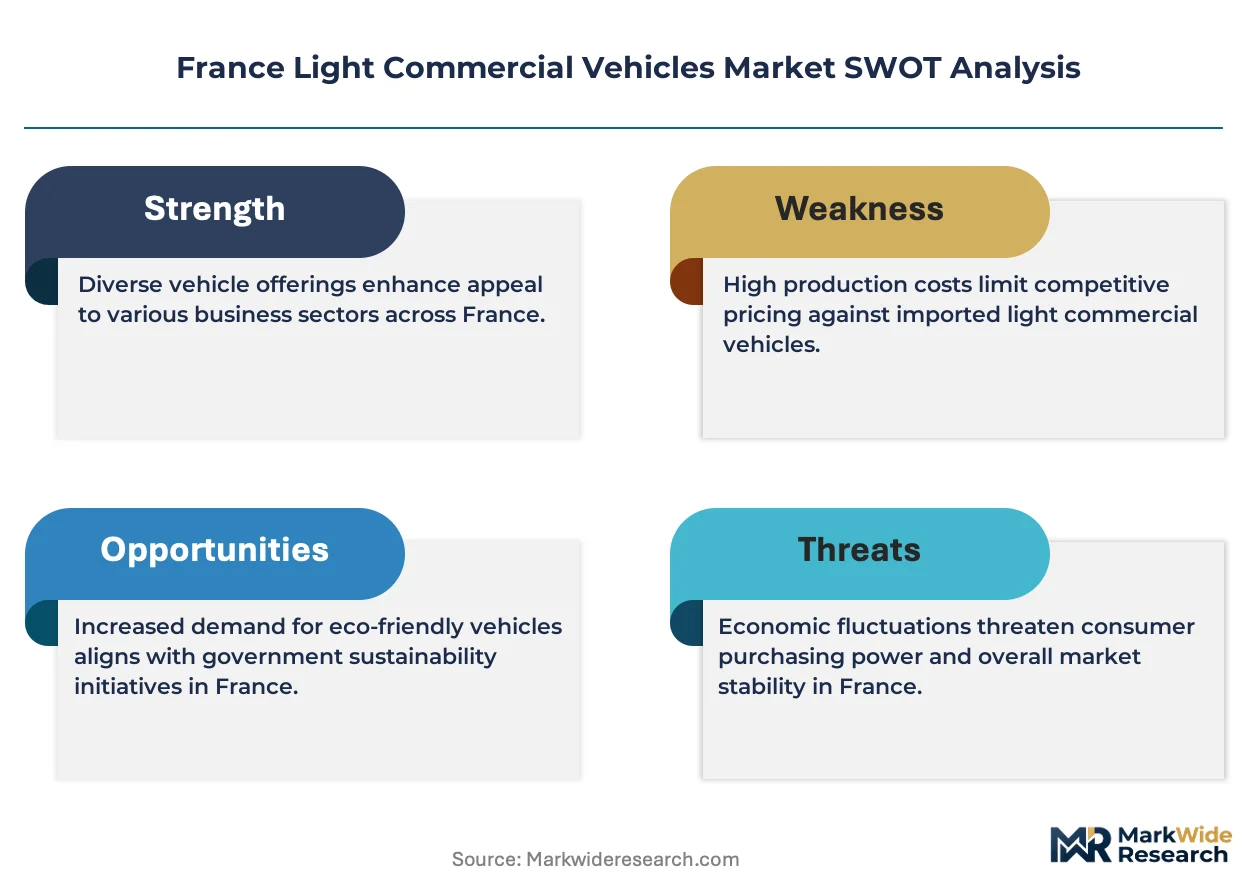
Top-tier vendors anchor premium electrification segments, while mid-market specialists compete on service network density and lease financing terms. The competitive structure stratifies across three tiers: legacy European manufacturers with domestic French production, Asian conglomerates with hybrid technology portfolios, and commercial-vehicle specialists with vocational customization capabilities. Consolidation pressure intensifies as battery platform development costs force alliance formation and shared powertrain sourcing.
Among legacy European manufacturers, Groupe Renault, Mercedes-Benz, and Peugeot S.A. occupy positions that exemplify divergent strategic responses to electrification mandates. Renault leverages domestic manufacturing proximity to anchor contract maintenance programs. Mercedes-Benz represents the integrated telematics archetype with software-enabled service layering. Peugeot S.A. sits within the localized service network tier, emphasizing uptime guarantees through dense aftermarket presence. These three anchors illustrate how French market incumbents partition competitive terrain without direct confrontation on identical value propositions.
| Leading Market Players |
|---|
| Mercedes-Benz |
| Volkswagen AG |
| Groupe Renault |
| Toyota Motor Corporation |
| IVECO S.p.A |
| Peugeot S.A. |
| Fiat Chrysler Automobiles N.V |
| Citroën |
| Ford Motor Company |
| Others |
Supply & Pricing Matrix
High-voltage technician certification programs in Île-de-France and Auvergne-Rhône-Alpes feed labor-cost differentials that widen pricing-tier spreads between premium electrified platforms and standard diesel-equivalent configurations.
Pricing Analysis
Margin tightening in economy-tier diesel vans reflects residual value collapse as Crit'Air enforcement accelerates fleet retirement schedules. Three-tier pricing structure across premium electric, standard hybrid, and economy diesel levels stratifies by certification grade and after-sales service bundling. Cost-down pressure on mid-tier hybrids intensifies because courier services demand operational parity proofs before contract renewal. Small logistics operators exhibit highest price sensitivity, while national parcel carriers absorb premium electric pricing through volume-negotiated maintenance inclusion.
Supply Chain Analysis
Battery cell supply rests on South Korean and Chinese producers, with European module assembly concentrated in Poland and Hungary. Lithium carbonate and nickel sulfate feedstock dependencies create single-source vulnerability from Australian mining and Indonesian processing corridors. Semiconductor content for powertrain controllers and telematics modules sources from Taiwan and Germany. Distribution runs through Renault's Douai manufacturing complex for domestic French assembly, with Tier 1 supplier networks anchored in Hauts-de-France industrial corridors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
France's light commercial vehicle sector constitutes a consolidation play as battery platform development costs force alliance formation and shared powertrain sourcing, eliminating sub-scale domestic assemblers.
For Market Incumbents: Anchor service network density in secondary cities ahead of Crit'Air zone expansion to Toulouse and Strasbourg. Deepen backward integration into battery pack assembly through Douai facility upgrades to defend against Korean conglomerate entry. Lock courier services into multi-year subscription contracts before residual value uncertainty peaks. For New Entrants and Emerging Players: Swappable-battery technology platforms offer entry wedge into Parisian courier fleets seeking minimized route downtime. Target food and beverage distributors in pedestrianized city centers with compact refrigerated electric vans underserved by legacy panel van configurations. Pursue lease-company partnerships rather than direct fleet sales to transfer residual value risk. For Investors and Strategic Acquirers: Re-rating potential sits with mid-tier leasing firms possessing captive maintenance infrastructure given subscription revenue predictability. Long-term viability favors operators with software-defined fleet management capabilities and RTE demand-response integration. Monitor Crit'Air vignette enforcement automation as inflection indicator for electrification pace.| Strategic Initiative | Industry Significance |
|---|---|
| Battery Supply Agreement | Cell sourcing from Korean producers secures capacity for Renault's Douai electric van assembly lines. |
| Software-Defined Vehicle Investment | Over-the-air update capabilities enable Peugeot to monetize telematics through usage-based insurance products. |
| Charging Infrastructure Partnership | Depot charging collaboration with ERDF accelerates grid connection timelines for Île-de-France courier fleets. |
| Platform Standardization | Modular battery architectures across van classes compress development costs for Mercedes-Benz French operations. |
| Geographic Manufacturing Footprint | Douai facility expansion anchors domestic production against Asian import penetration under EU CO2 standards. |
Research Methodology
French automotive registration databases, ERDF grid connection filings, and Crit'Air enforcement statistics formed the secondary backbone, supplemented by primary interviews with fleet procurement managers at national courier services, aftermarket service directors at Renault and Peugeot networks, and leasing company risk officers. Bottom-up and top-down triangulation validated vehicle volume estimates against manufacturer production disclosures and regional logistics employment data.
Bottom-up modeling aggregated segment-level demand across vehicle type, powertrain architecture, and end-user category, while top-down cross-checks applied macroeconomic freight activity indices. CAGRs derived from regression analysis of historical electrification penetration rates against regulatory threshold timing. Forecast inputs incorporated Crit'Air zone expansion schedules, battery cost curves, and depot charging infrastructure buildout timelines across the analysis window.
Several conditions sit outside the modeled scope, including potential suspension of Crit'Air enforcement, abrupt lithium supply disruptions, and technology leapfrogging to hydrogen fuel cell platforms. Forecasts reflect assumptions about subsidy continuity and grid reinforcement pacing. A small set of named triggers warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Commercial Vehicles
Europe Van Market
Commercial Vehicles
Waste or Garbage Collection Vehicle Market
Commercial Vehicles
UAE Commercial Vehicles Market
Commercial Vehicles
Chile Commercial Vehicle Market
Commercial Vehicles
Global Commercial Vehicle Fuel Tank Market
Commercial Vehicles
Asia Pacific Non Passenger Vehicle Market
Commercial Vehicles
Cryogenic Liquid Transport Vehicle Market
Commercial Vehicles
Aerial Work Platform (AWP) Truck Market
Commercial Vehicles
Flatbed Semi-Trailer Market
Commercial Vehicles
Hopper Car Market
Commercial Vehicles
Service Truck Market
Commercial Vehicles
Middle East Vacuum Truck Market
Commercial Vehicles
Electric Garbage Van Market
Commercial Vehicles
Automated Truck Market
Commercial Vehicles
Truck Market
Commercial Vehicles
Canada Commercial Vehicles Market