
 Road Assistance Insurance Market | 2026-2036
Road Assistance Insurance Market Size, Share, and Industry Trends Forecast 2026-2036
Road Assistance Insurance Market Analysis
The EU Green Deal is pivoting road assistance insurers toward electrification-ready service networks. Progressive leverages its telematics infrastructure to anchor competitive positioning in usage-based assistance products. State Farm sustains brand strength through captive agency distribution across rural markets where traditional roadside response remains essential. AAA differentiates through vertical integration into its own towing and battery service fleets, controlling response times in high-density corridors.
Road assistance insurance constitutes a specialized property and casualty product covering emergency vehicle recovery, mechanical breakdown response, and driver mobility continuation. Policies typically specify response-time guarantees, geographic coverage radii, and per-incident claim limits calibrated to vehicle class and policy tier. Towing services command the largest share of claim frequency across service type segments, while mobile app integration represents the fastest-growing technology dimension as policyholders expect real-time dispatcher visibility. Comprehensive coverage plans capture disproportionate margin pools compared to basic tiers, reflecting bundled add-on services and higher retention rates.
FCC guidelines on wireless emergency communications and state-level insurance department regulations in the United States shape product disclosure and claims handling standards. NHTSA vehicle safety mandates indirectly drive assistance demand through connected-car requirements that enable automatic crash notification. The EU AI Act and GDPR compliance obligations in Europe constrain how automated dispatch algorithms process driver location data. Stakeholders must weigh capital allocation between legacy call-center infrastructure and predictive analytics platforms that preempt breakdown events through vehicle telemetry.
Market Dynamics
Connected vehicle mandates and predictive maintenance algorithms are compressing traditional breakdown response models into proactive intervention systems, forcing insurers to reallocate capital from call-center infrastructure toward telemetry-based dispatch platforms.
Growth Catalysts
- Fleet electrification mandates:Commercial operators face tightening uptime requirements for electric vehicle fleets, expanding demand for specialized recovery services and mobile charging units integrated into assistance coverage.
- EU eCall regulation:Automatic crash notification systems embedded in new vehicles create embedded distribution channels for assistance products at point of manufacture.
- Telematics penetration:Usage-based insurance platforms generate real-time vehicle health data, enabling predictive dispatch before mechanical failure immobilizes drivers.
Market Restraints
- Towing capacity concentration:Independent towing operators in rural United States territories lack electrification training and specialized equipment for EV recovery, creating service gaps.
- Labor cost inflation:Certified roadside technicians command premium wages amid shortage of dual-qualified mechanical and electrical specialists.
- GDPR data friction:EU privacy constraints limit granular location tracking for automated dispatch algorithms, degrading response-time optimization.
Strategic Opportunities
- India commercial vehicle segment:Underpenetrated assistance coverage for long-haul trucking fleets creates white space for telematics-integrated products.
- Subscription bundling:OEMs embed multi-year assistance contracts into vehicle financing, capturing lifetime value at point of sale.
- AI Act compliance services:European insurers monetize algorithmic transparency tools for fleet operators navigating automated decision-making disclosures.
Industry Challenges
- Legacy system integration:Incumbent insurers face technical debt from decades-old claims management platforms incompatible with real-time telemetry feeds.
- Skill bifurcation:Dispatch centers require retraining for telemetry interpretation while field networks need electrical safety certification for high-voltage vehicle handling.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Road Assistance Insurance Market |
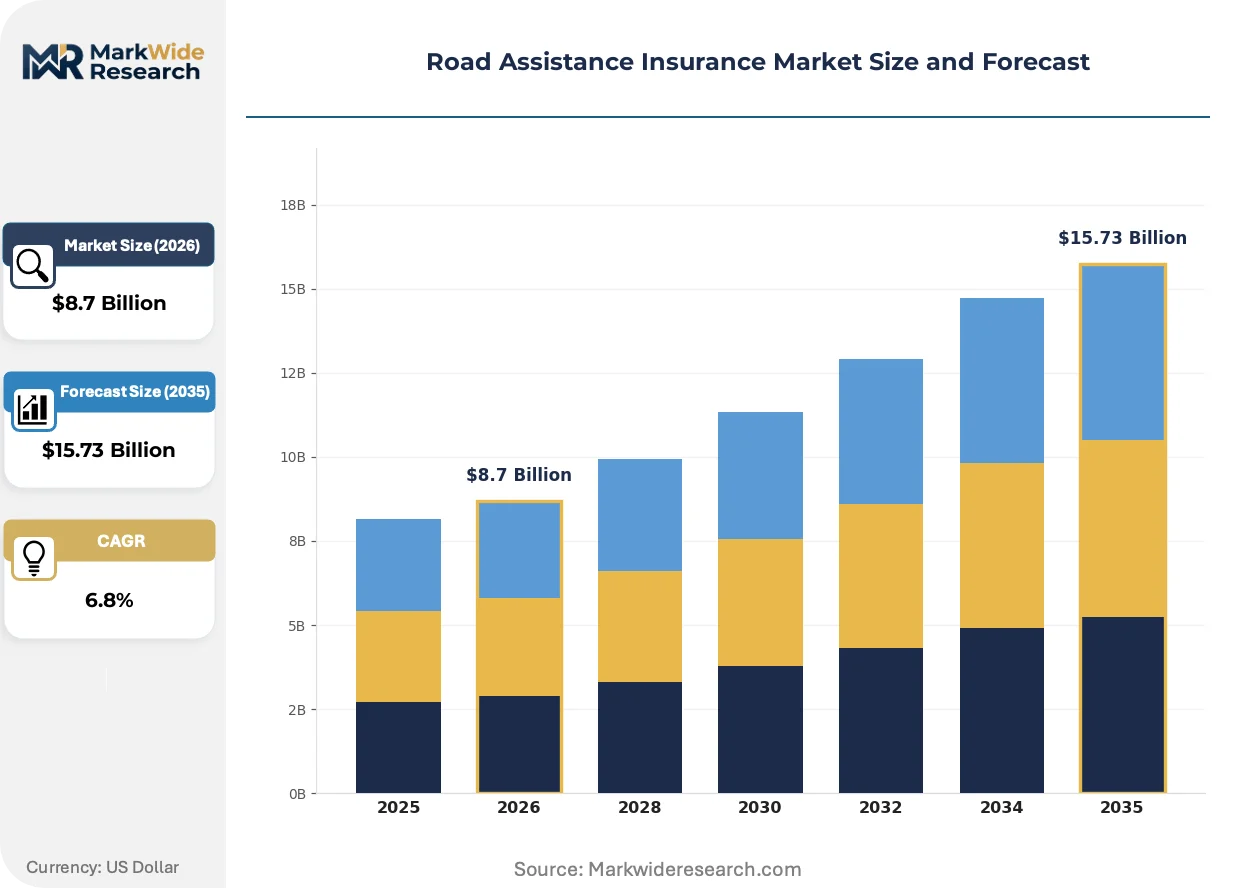
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $15.73 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Towing, Battery Jump Start, Flat Tire Change, Fuel Delivery Customer Type: Individual Policyholders, Fleet Operators, Businesses, Families Coverage Type: Basic Coverage, Comprehensive Coverage, Premium Coverage, Add-On Services Technology: Mobile App Integration, GPS Tracking, Automated Dispatch, Telemetry Systems |
| Companies Covered | Progressive, State Farm, AAA, OnStar, Better World Club, Allstate, Geico, Travelers, Good Sam, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Road Assistance Insurance Market Emerging Trajectories
Digital dispatch platforms are compressing the traditional emergency response chain, eliminating dispatcher intermediaries through direct vehicle-to-service-provider communication protocols.
Predictive breakdown algorithms powered by engine control unit data streams are overtaking reactive call-center models. Fleet operators now prioritize insurers offering preemptive maintenance alerts over historical incident response. This capability compression threatens traditional assistance providers lacking direct vehicle data partnerships.
The EU AI Act imposes explainability requirements on automated dispatch systems processing driver location and behavioral data. Insurers must document algorithmic decision trails for regulatory audits. European assistance platforms are responding by hybridizing human oversight with machine learning outputs to satisfy transparency mandates.
Commercial fleet procurement now favors integrated mobility continuity packages over standalone towing coverage. Large logistics operators negotiate enterprise assistance contracts bundling rental replacement, alternative routing, and cargo preservation services. This unbundling of traditional roadside products is most visible in United States long-haul trucking corridors where downtime costs exceed premium differentials.
Road Assistance Insurance Market Segmentation
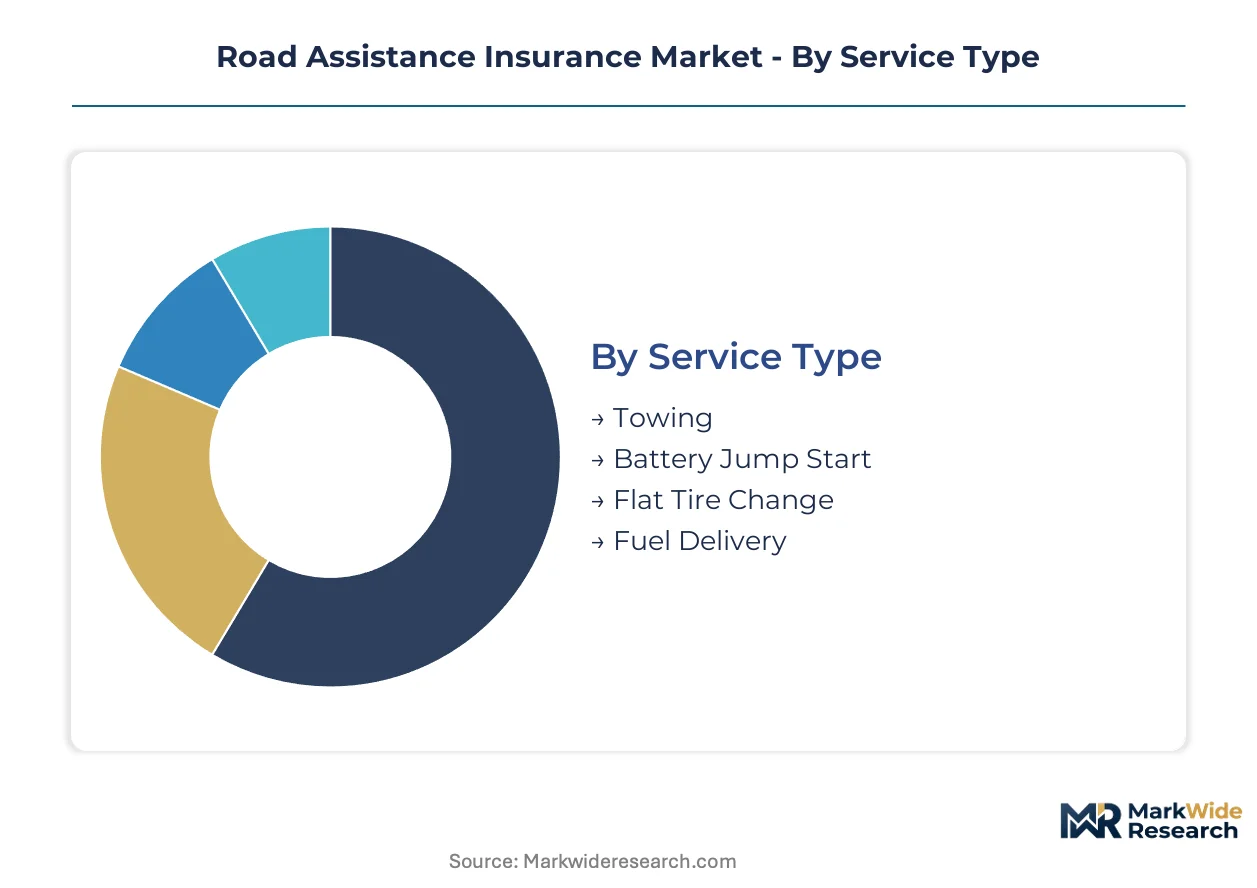
Segmentation in road assistance insurance reveals how capital allocation, risk pooling, and service delivery models diverge across customer profiles and technical capabilities. Distinct segments command different margin structures and technology integration requirements.
Service Type:
Supply concentration in towing infrastructure shapes competitive dynamics across emergency response categories, with equipment specialization and labor certification creating segment-specific barriers.
- Towing:Emergency vehicle recovery to repair facilities or designated locations requires heavy-duty flatbeds and wheel-lift configurations calibrated to vehicle class. Demand concentrates in United States rural interstate corridors where distances to service centers stretch response windows and amplify downtime costs for commercial fleets.
- Battery Jump Start:Mobile power delivery and electrical system diagnostics address the most frequent assistance request category, particularly for aging vehicle populations in cold-climate states. Fleet operators in Minnesota and Wisconsin prioritize insurers with rapid battery response capabilities to minimize frozen-start immobilization.
- Flat Tire Change:Spare tire installation or temporary mobility solutions address run-flat and conventional tire failures. Roadside technicians require torque specification training for alloy wheel configurations common in premium vehicle segments.
- Fuel Delivery:Emergency gasoline or diesel delivery resolves range miscalculation incidents, with demand clustering in remote highway stretches lacking service station density.
Towing absorbs the bulk of installed capacity; battery jump start is expanding most quickly.
Customer Type:
Cost tier differentiation separates mass-market retail products from enterprise contracts with negotiated response-time guarantees and dedicated account management.
- Individual Policyholders:Single-vehicle coverage purchased through direct channels or agency networks carries per-incident claim limits and geographic radius restrictions. Demand clusters in suburban United States markets where vehicle dependence and commute distances amplify assistance utility.
- Fleet Operators:Commercial vehicle pools require uptime guarantees, cargo preservation protocols, and alternative mobility arrangements. Long-haul trucking fleets traversing Texas-to-California corridors negotiate enterprise contracts bundling towing with rental replacement and load transfer services.
- Businesses:Corporate vehicle pools serving sales and service personnel prioritize consolidated billing and national coverage uniformity over per-vehicle customization.
- Families:Multi-driver household policies bundle coverage across registered vehicles, with demand concentrating in dual-income suburban households maintaining three or more automobiles.
Fleet operators absorb the bulk of installed capacity; individual policyholders are expanding most quickly.
Coverage Type:
Margin structure varies sharply across tiers, with bundled add-on services and higher retention rates concentrating in upper coverage levels.
- Basic Coverage:Limited service calls per annum with restricted geographic radius and standard response-time windows. Price-sensitive purchasers in United States Sun Belt states favor stripped-down policies for occasional peace of mind.
- Comprehensive Coverage:Expanded service menu including trip interruption benefits, lockout assistance, and winching services. Fleet procurement teams in Ohio and Michigan prioritize this tier for seasonal weather exposure.
- Premium Coverage:Unlimited service calls, concierge-level response coordination, and international coverage extensions. High-net-worth individuals in California and New York metropolitan areas drive demand for white-glove assistance products.
- Add-On Services:Modular enhancements including RV coverage, motorcycle towing, and electric vehicle charging delivery. Tesla and Rivian owners in Washington and Colorado purchase EV-specific charging add-ons for range anxiety mitigation.
Comprehensive coverage absorbs the bulk of installed capacity; add-on services are expanding most quickly.
Technology:
Maturity gradients separate legacy call-center dispatch from predictive platforms requiring direct vehicle data partnerships and algorithmic infrastructure investment.
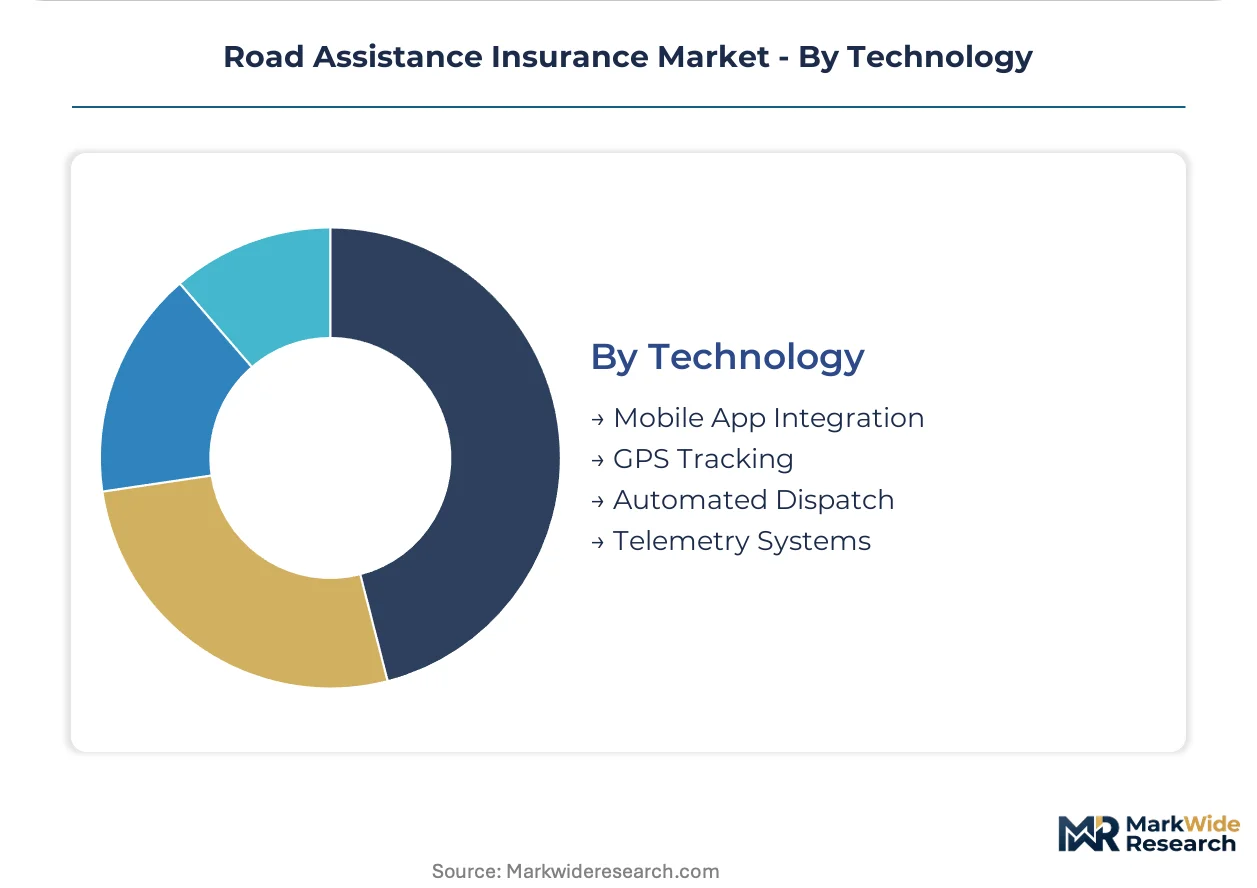
- Mobile App Integration:Real-time dispatcher visibility, service provider tracking, and digital claim submission replace voice-only interaction. United States policyholders under age 45 reject insurers lacking smartphone-native service access.
- GPS Tracking:Precise location transmission compresses dispatch coordination time and enables dynamic service provider routing. Rural United States territories with sparse addressing infrastructure rely on coordinate-based dispatch for accuracy.
- Automated Dispatch:Algorithmic service provider matching eliminates human dispatcher intermediaries, reducing per-incident handling costs. GDPR constraints in European markets limit deployment granularity for location-inferred behavioral scoring.
- Telemetry Systems:Direct engine control unit data streams enable predictive breakdown alerts before immobilization occurs. Commercial fleets in Illinois and Pennsylvania prioritize insurers with OEM telematics partnerships for preemptive maintenance scheduling.
Mobile app integration absorbs the bulk of installed capacity; telemetry systems are expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Detroit's automotive corridor anchors North American road assistance insurance density, with fleet electrification mandates and connected vehicle rollouts concentrating insurer operational investment across three metropolitan clusters.
United States
Long-haul trucking fleets traversing Texas-to-California corridors drive enterprise contract demand for uptime-guaranteed assistance products. NHTSA vehicle safety mandates accelerate connected-car requirements enabling automatic crash notification. The Midwest manufacturing belt surrounding Chicago and Detroit concentrates insurer telematics partnership development with OEM assembly plants.
Germany
Commercial vehicle operators along the Rhine-Ruhr industrial corridor prioritize predictive maintenance integration into assistance coverage. EU eCall regulation mandates automatic crash notification systems in new vehicles, embedding distribution channels at point of manufacture. Bavaria's automotive engineering cluster around Munich hosts insurer algorithm development centers for automated dispatch platforms.
China
Electric vehicle fleet operators in the Yangtze River Delta generate demand for specialized recovery services and mobile charging units. MIIT connected vehicle standards accelerate telematics infrastructure deployment across passenger and commercial segments. Shenzhen's technology corridor concentrates insurer partnerships with battery-electric OEMs for predictive breakdown alerts.
India
Long-haul trucking fleets operating the Delhi-Mumbai Industrial Corridor create underpenetrated white space for telematics-integrated assistance products. The country's national automotive regulator pushes commercial vehicle safety mandates that indirectly expand breakdown response requirements. Maharashtra's logistics hubs around Mumbai and Pune concentrate fleet operator procurement of bundled mobility continuity packages.
United Kingdom
Insurance distribution through captive agency networks persists strongest in rural England and Scotland where traditional roadside response remains essential. GDPR compliance obligations constrain granular location tracking for automated dispatch algorithms. London's financial services cluster hosts insurer headquarters prioritizing mobile app integration for policyholder real-time visibility.
Road Assistance Insurance Market Vendor Landscape
The competitive structure tilts toward vertically integrated service networks controlling response times through captive towing and battery service fleets. Market concentration remains moderate, with national insurers competing against specialized roadside assistance clubs and OEM-embedded service providers. Three archetypes dominate: telematics-anchored usage-based insurers, agency-distributed traditional carriers, and vertically integrated assistance clubs. Competitive moves center on OEM partnership formation for embedded distribution and predictive analytics platform acquisition.
Among telematics-anchored carriers, Progressive exemplifies algorithmic infrastructure deployment for usage-based assistance products. State Farm occupies a position representing agency-distributed traditional coverage with rural market penetration. AAA anchors the vertically integrated assistance club archetype through captive supply of towing and battery service fleets. These three players collectively illustrate the strategic divergence between technology-driven prediction and service network control.
| Leading Market Players |
|---|
| Progressive |
| State Farm |
| AAA |
| OnStar |
| Better World Club |
| Allstate |
| Geico |
| Travelers |
| Good Sam |
| Others |
Supply Flow & Price Mechanics
Fleet operator procurement consolidation around uptime-guaranteed contracts forces insurers to absorb specialized towing capacity costs, compressing margins in basic tiers while amplifying premium tier pricing power through bundled mobility continuity services.
Pricing Analysis
Uptime-based pricing anchors enterprise contracts where fleet operators pay premiums tied to vehicle availability guarantees rather than per-incident fees. Three-tier pricing structure across premium, standard, and economy levels separates comprehensive coverage with trip interruption benefits from basic towing-only policies. Cost compression in economy tiers intensifies because rural towing operator consolidation limits competitive supply alternatives. Individual policyholders in Sun Belt states exhibit highest price sensitivity, while commercial fleets traversing Texas-to-California corridors prioritize response-time reliability over premium differentials.
Supply Chain Analysis
Dual-sourcing requirements from commercial fleet procurement teams mandate insurers qualify multiple towing operators per corridor to mitigate single-point failure risks. Equipment and technician capacity concentrates in the United States, Germany, and China, with specialized EV recovery infrastructure scaling fastest in Shenzhen and Munich. Battery-electric vehicle components, high-voltage safety equipment, and telematics hardware constitute critical input dependencies. Single-source vulnerability runs through independent rural towing networks lacking electrification certification. Distribution runs through captive agency networks in suburban United States markets and direct OEM embedding at point of manufacture in EU jurisdictions.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Specialized technician shortages and towing fleet electrification requirements create supply-constrained conditions that prop pricing power for insurers controlling certified capacity.
For Market Incumbents: Anticipate telematics-native entrants displacing traditional call-center models by accelerating predictive maintenance platform deployment through OEM data partnerships. Captive supply of battery service fleets and high-voltage technician certification programs defend margin position against vertical integration moves by assistance clubs. For New Entrants and Emerging Players: OEM embedded distribution channels offer lowest customer acquisition friction for multi-year assistance contracts bundled at vehicle financing. India's Delhi-Mumbai Industrial Corridor presents the most penetrable white space for telematics-integrated commercial fleet products. Telematics platform licensing agreements with battery-electric OEMs provide the most viable go-to-market angle against established agency networks. For Investors and Strategic Acquirers: The window for entry favors vertically integrated assistance clubs with captive towing capacity and algorithmic dispatch infrastructure. Long-term viability hinges on predictive analytics platform ownership rather than legacy call-center assets. Watch for NHTSA connected vehicle mandate acceleration as the signal indicating embedded distribution channel inflection.| Strategic Initiative | Industry Significance |
|---|---|
| OEM Telematics Partnership | Progressive's vehicle data integration anchors usage-based assistance product differentiation. |
| High-Voltage Technician Certification | AAA's captive battery service fleets control response times for electrified vehicle recovery. |
| Predictive Dispatch Platform Acquisition | State Farm's algorithmic infrastructure investment defends rural market positioning against digital entrants. |
| Embedded Distribution Channel | EU eCall regulation mandates automatic crash notification, creating manufacturer-anchored assistance access. |
| Mobile Charging Unit Deployment | Fleet electrification mandates in the Yangtze River Delta expand specialized recovery service demand. |
Methodological Framework
Trade association data, regulatory filings, and customs records anchored secondary inputs for this road assistance insurance analysis. Primary interviews with fleet procurement managers, roadside technician training directors, OEM telematics partnership leads, and insurance product development executives combined with NHTSA safety mandate documentation, EU eCall regulatory filings, and FCC wireless emergency communications guidelines. Bottom-up policyholder segmentation triangulated against top-down premium volume estimates from state insurance department disclosures.
Granularity-level modeling operated at service type, customer archetype, coverage tier, and technology platform dimensions across the projection horizon. CAGRs derived from historical premium growth patterns, fleet electrification mandate timelines, and connected vehicle penetration curves. Vehicle class stratification and regional regulatory cluster differentiation informed segment-specific trajectory assumptions throughout the forecast period.
Caveats apply where NHTSA mandate acceleration, EU AI Act enforcement stringency, or EV fleet adoption velocity could materially shift the outlook. Forecasts reflect assumptions about technician certification scaling and telematics partnership exclusivity terms. Deviation in fleet electrification investment cycles would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Insurance
Intellectual Property Liability Insurance Market
Insurance
Business Travel Accident Insurance Market
Insurance
India Health and Medical Insurance Market
Insurance
Cloud Computing in Insurance Market
Insurance
Crop Insurance Market
Insurance
Internet of Things Insurance Market
Insurance
China Parametric Insurance Market
Insurance
Cannabis Crop Insurance Market
Insurance
Reinsurance Market
Insurance
US Extended Warranty Market
Insurance
Consumer Electronics Extended Warranty Market
Insurance
Canada Property and Casualty Insurance Market
Insurance
Medical Professional Liability Insurance Market
Insurance
North America Car Insurance Aggregators Market
Insurance
Microinsurance Market
Insurance
United States Commercial Insurance Market