
 Business Travel Accident Insurance Market | 2026-2036
Business Travel Accident Insurance Market Size, Share, and Industry Trends Forecast 2026-2036
Business Travel Accident Insurance Market Insights
Comprehensive medical evacuation coverage is bifurcating the competitive landscape between premium-tier global underwriters and regional specialists. AXA leverages its international assistance networks to sustain cross-border claims capabilities. Chubb anchors high-limit corporate programs through specialized risk engineering services. AIG differentiates with integrated security intelligence and crisis response bundled into master policy structures.
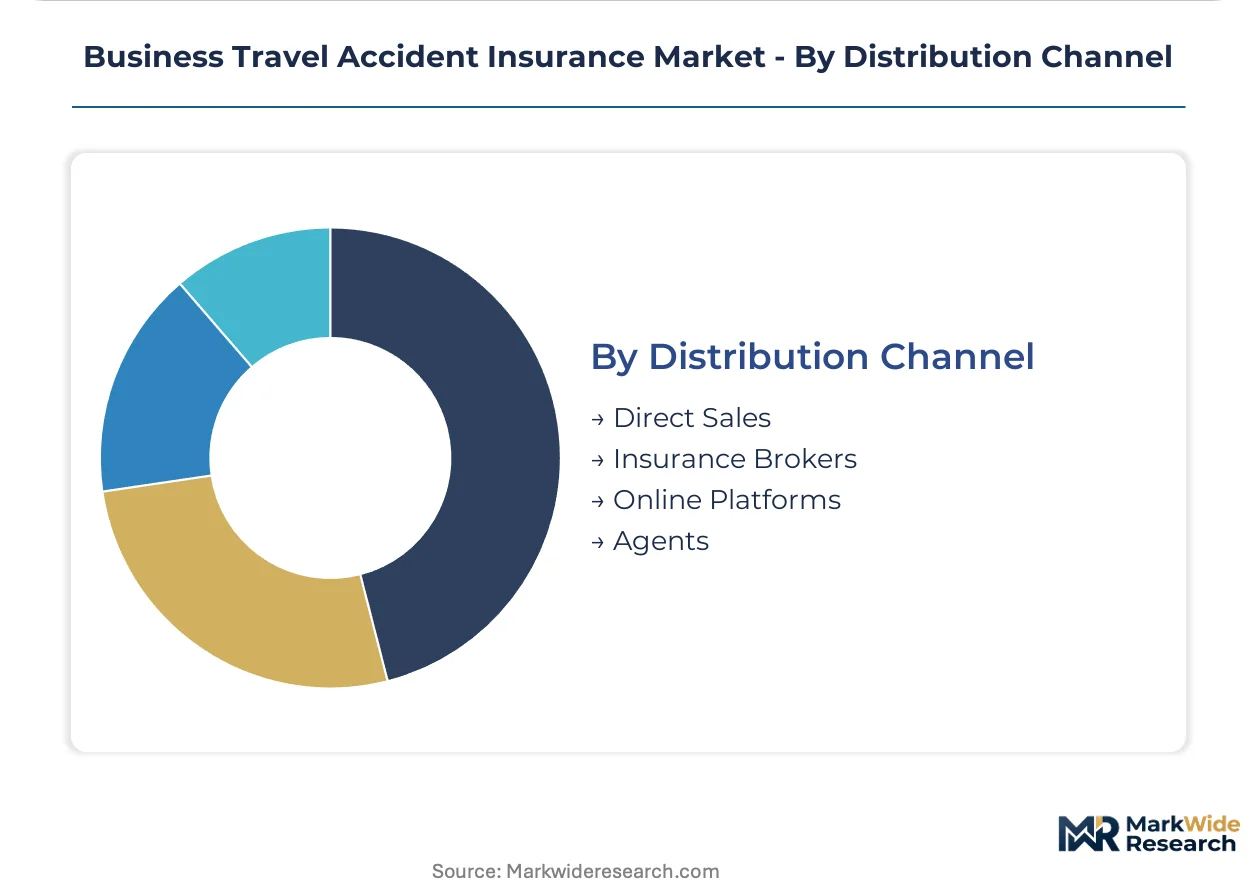
Business travel accident insurance provides financial protection against death, dismemberment, and medical costs arising from accidents during employer-sponsored trips, typically covering 24-hour periods from departure through return with benefit schedules tied to salary multiples or flat indemnity tables. The policy type dimension shows annual multi-trip contracts commanding the deepest margin pools as enterprises consolidate fragmented single-trip purchases into negotiated master agreements. Distribution channel dynamics reveal insurance brokers capturing the largest share of corporate placements due to their role in designing multinational compliance architectures, while online platforms are gaining traction among small enterprises seeking standardized instant-quote products.
OSHA workplace safety guidelines, the EU's duty-of-care directives under the Posted Workers Enforcement Directive, and Japan's METI occupational accident compensation standards collectively shape product minimums and employer liability exposure. Insurers must calibrate territorial rating models against divergent national healthcare cost bases and local compulsory social insurance offsets. Stakeholders should monitor how artificial intelligence-driven travel risk scoring tools reshape underwriting granularity and policy personalization at the individual traveler level.
Market Dynamics
Corporate duty-of-care obligations are tightening across jurisdictions, forcing employers to expand coverage mandates and integrate real-time risk monitoring into travel accident programs. The EU's Corporate Sustainability Reporting Directive and Japan's METI standards now require documented employee protection protocols during international assignments.
Growth Catalysts
- CSRD Mandates:The EU's Corporate Sustainability Reporting Directive compels employers to disclose workforce protection metrics, directly expanding coverage procurement for cross-border assignments.
- Technology Sector Expansion:Silicon Valley and Bangalore-based enterprises are standardizing 24-hour accident coverage for engineering teams on client-site deployments.
- Posted Workers Enforcement Directive:This EU framework tightens employer liability for staff on temporary foreign assignments, elevating minimum coverage thresholds.
Market Restraints
- Healthcare Cost Divergence:Territorial rating models face compression as US medical evacuation costs diverge sharply from Germany's statutory health insurance offsets.
- Reinsurance Capacity Concentration:London and Bermuda markets control catastrophic loss coverage, creating bottleneck risk for high-limit corporate programs.
- Social Insurance Overlap:Japan's workers' accident compensation insurance reduces employer demand for supplemental private coverage in domestic travel scenarios.
Strategic Opportunities
- India's Underpenetrated SME Segment:Small enterprises in Mumbai and Bangalore lack structured travel protection, presenting white space for digital distribution platforms.
- AI-Driven Personalization:Machine learning risk scoring enables individual traveler pricing, displacing one-size-fits-all corporate rate cards.
- Embedded Distribution:Integration with corporate travel management systems like Concur and SAP Ariba creates frictionless policy attachment at booking.
Industry Challenges
- Actuarial Talent Scarcity:Underwriters with expertise in multi-jurisdictional claims adjudication remain concentrated in Zurich, London, and New York.
- Legacy System Integration:Carriers struggle to embed real-time travel intelligence APIs into decades-old policy administration platforms.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Business Travel Accident Insurance Market |
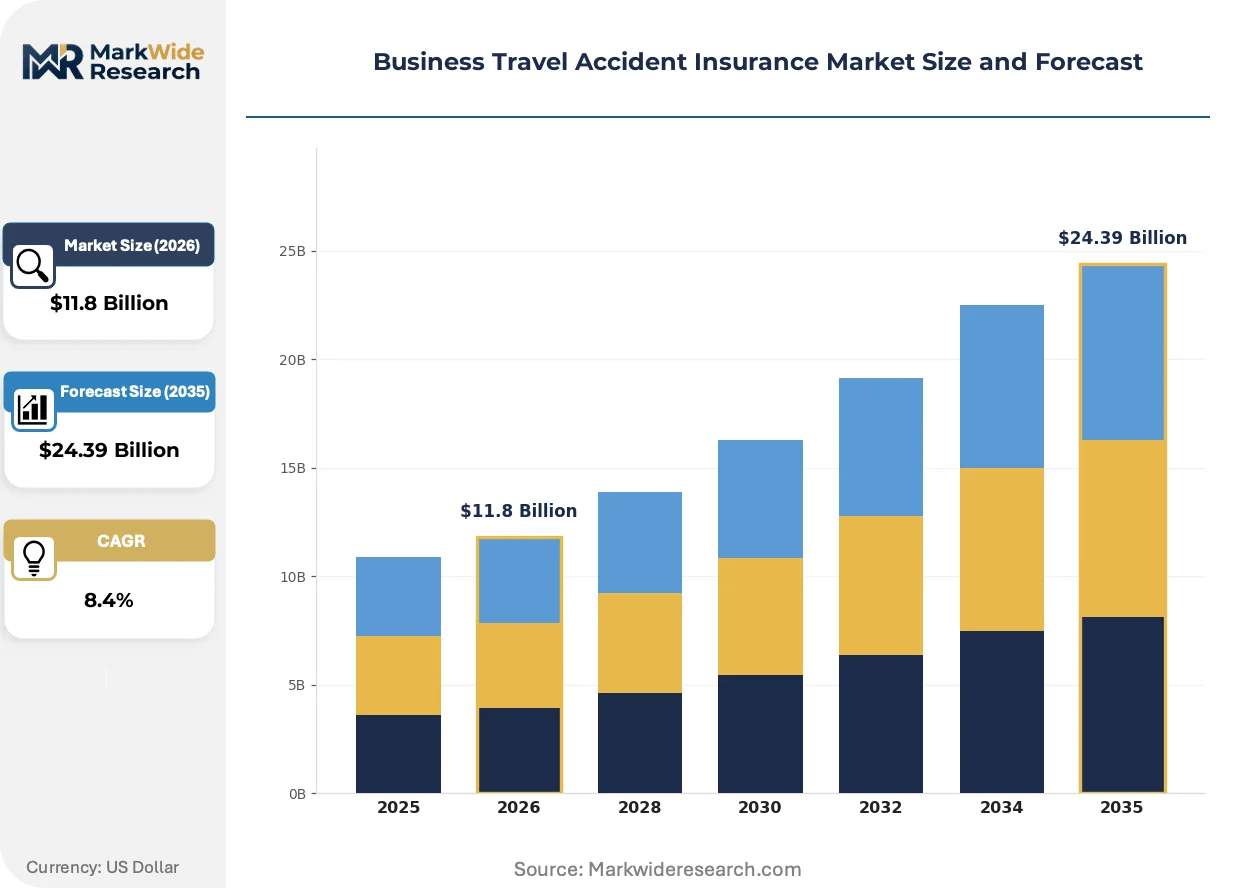
| Market Size in 2026 | $11.8 Billion |
| Market Size in 2035 | $24.39 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Policy Type: Single Trip, Annual Multi-Trip, Group Policy, Corporate Package Coverage Scope: Medical Expenses, Accidental Death, Disability Benefits, Trip Cancellation Client Type: Small Enterprises, Corporations, Government Agencies, Nonprofits Distribution Channel: Direct Sales, Insurance Brokers, Online Platforms, Agents |
| Companies Covered | AXA, Chubb, AIG, Zurich Insurance Group, Allianz, MetLife, The Hartford, Assicurazioni Generali, Tokio Marine Holdings, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Business Travel Accident Insurance Market Trends and Innovations
Real-time risk intelligence and automated claims processing are reconfiguring how underwriters price and service travel accident coverage. Three developments are compressing traditional underwriting cycles and reshaping buyer expectations.
Parametric triggers tied to GPS-verified incident locations are displacing manual claims documentation for medical evacuation and repatriation benefits. Large technology employers in Seattle and Austin are piloting instant-payout structures for hospitalization events. This compression is eliminating 30-day adjudication lags that previously strained employee relations.
REACH chemical safety disclosures and the EU AI Act are mandating algorithmic transparency in automated underwriting decisions. Insurers deploying AI-driven risk scoring must now document training data provenance and bias testing. German and French carriers are restructuring their model governance frameworks to preempt regulatory enforcement.
Consolidated master agreements are replacing fragmented single-trip purchases among professional services firms. Risk managers at London and New York headquarters are mandating centralized procurement to capture volume discounts and standardize duty-of-care documentation. This concentration favors carriers with multinational compliance architectures over regional specialists.
Business Travel Accident Insurance Market Segmentation
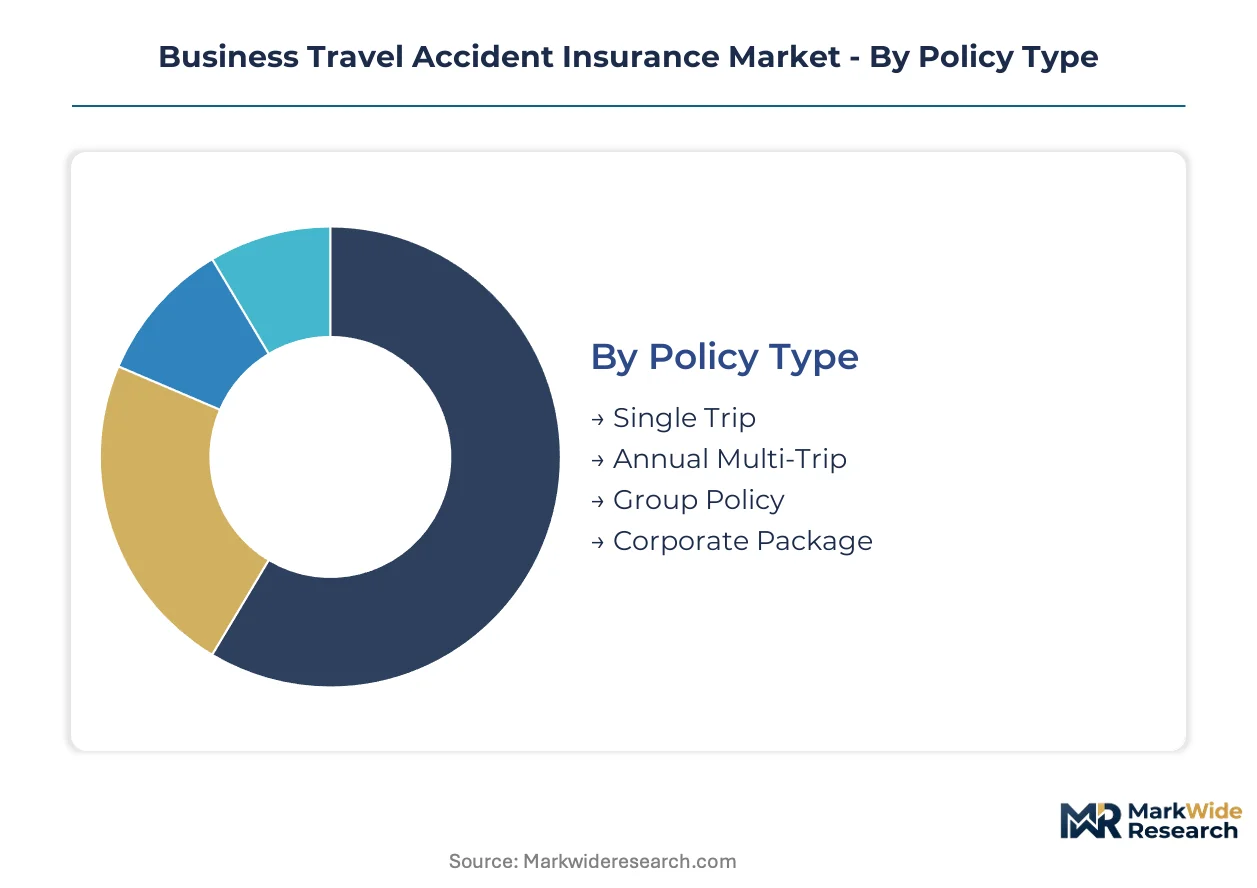
Segmentation in business travel accident insurance determines pricing architecture and distribution strategy. Policy structure and client scale create distinct margin profiles that carriers must calibrate against duty-of-care compliance requirements.
Policy Type:
Margin pools concentrate in recurring revenue structures that reduce acquisition costs and stabilize loss ratios.
- Annual Multi-Trip:Master agreements covering unlimited journeys within a 12-month period. Technology firms in Seattle and Austin standardize these contracts for engineering teams on recurring client deployments, capturing volume discounts while satisfying OSHA documentation requirements.
- Corporate Package:Customized umbrella structures integrating accident coverage with security intelligence and crisis response. Professional services headquarters in London and New York mandate these for partner-level protection during high-risk jurisdiction assignments.
- Single Trip:Ad-hoc coverage for isolated journeys with premium loading per departure.
- Group Policy:Cohort-based structures for project teams traveling to shared destinations.
Annual Multi-Trip holds installed capacity. Corporate Package is rotating up the share rankings.
Coverage Scope:
Benefit configuration separates premium-tier global underwriters from regional specialists competing on price.
- Medical Expenses:Reimbursement for emergency treatment, hospitalization, and evacuation costs. Demand concentrates in the United States where healthcare cost divergence from Germany's statutory offsets creates pricing complexity for territorial rating models.
- Accidental Death:Lump-sum indemnity tied to salary multiples or flat schedules. Japanese multinationals leverage METI occupational standards to calibrate these benefits against workers' accident compensation insurance offsets.
- Disability Benefits:Income replacement for permanent or temporary impairment.
- Trip Cancellation:Reimbursement for non-refundable travel expenditures.
Medical Expenses commands the deepest actuarial resources. Accidental Death is rotating up the share rankings.
Client Type:
Procurement sophistication determines distribution channel selection and policy customization depth.
- Corporations:Multinational enterprises with centralized risk management functions. These buyers in Germany and Japan drive master agreement consolidation, mandating compliance documentation for EU CSRD disclosure requirements.
- Small Enterprises:Organizations with fragmented travel purchasing and limited risk staff. Mumbai and Bangalore-based technology startups represent white space for digital distribution platforms offering instant-quote standardization.
- Government Agencies:Public sector employers with statutory procurement protocols.
- Nonprofits:Mission-driven organizations with constrained budgets and high-duty-of-care exposure.
Corporations hold installed capacity. Small Enterprises is expanding most quickly.
Distribution Channel:
Placement mechanics shape carrier access to risk information and pricing leverage.
- Insurance Brokers:Intermediaries designing multinational compliance architectures. These channels capture the largest share of corporate placements by integrating duty-of-care documentation with policy structures across United States, Germany, and Japan procurement pools.
- Online Platforms:Digital interfaces enabling instant quoting and binding. Small enterprises seeking standardized products without advisory fees are migrating to these channels, particularly in India's underpenetrated SME segment.
- Direct Sales:Carrier-employed representatives targeting large accounts.
- Agents:Local intermediaries serving relationship-driven smaller buyers.
Insurance Brokers hold installed capacity. Online Platforms is rotating up the share rankings.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Underwriting capacity concentrates in London, Zurich, and New York where catastrophic risk pools and multinational compliance expertise cluster. Territorial rating complexity and divergent healthcare cost bases fragment pricing models across jurisdictions.
United States
Corporate headquarters density in Manhattan and Chicago drives master agreement procurement for engineering teams on domestic and international deployments. OSHA workplace safety guidelines mandate documented duty-of-care protocols, elevating minimum coverage thresholds for cross-border assignments. Seattle and Austin technology firms standardize annual multi-trip contracts with integrated security intelligence for high-risk jurisdiction travel.
Germany
Frankfurt and Munich-based multinational enterprises consolidate fragmented single-trip purchases into negotiated umbrella structures. The EU's Corporate Sustainability Reporting Directive compels employers to disclose workforce protection metrics, directly expanding coverage procurement for posted workers. Düsseldorf insurance clusters anchor continental underwriting expertise for multi-jurisdictional claims adjudication.
Japan
Tokio Marine Holdings and domestic carriers face compression from METI occupational accident compensation standards that reduce employer demand for supplemental private coverage in domestic travel scenarios. Osaka and Nagoya manufacturing headquarters drive outbound business travel volumes for client-site deployments. METI standards calibrate accidental death benefits against statutory workers' accident compensation insurance offsets.
India
Mumbai and Bangalore technology startups represent white space for digital distribution platforms offering instant-quote standardization without advisory fees. Small enterprises with fragmented travel purchasing lack structured protection programs, creating penetration opportunities for online platforms. The country's central bank and insurance regulator shape foreign partnership structures for global underwriters seeking local distribution access.
United Kingdom
London headquarters of professional services firms mandate centralized procurement to capture volume discounts and standardize duty-of-care documentation. The Posted Workers Enforcement Directive tightens employer liability for staff on temporary foreign assignments, elevating minimum coverage thresholds. Lloyd's syndicates and specialty carriers anchor catastrophic loss coverage capacity for high-limit corporate programs.
Business Travel Accident Insurance Market Competitive Landscape
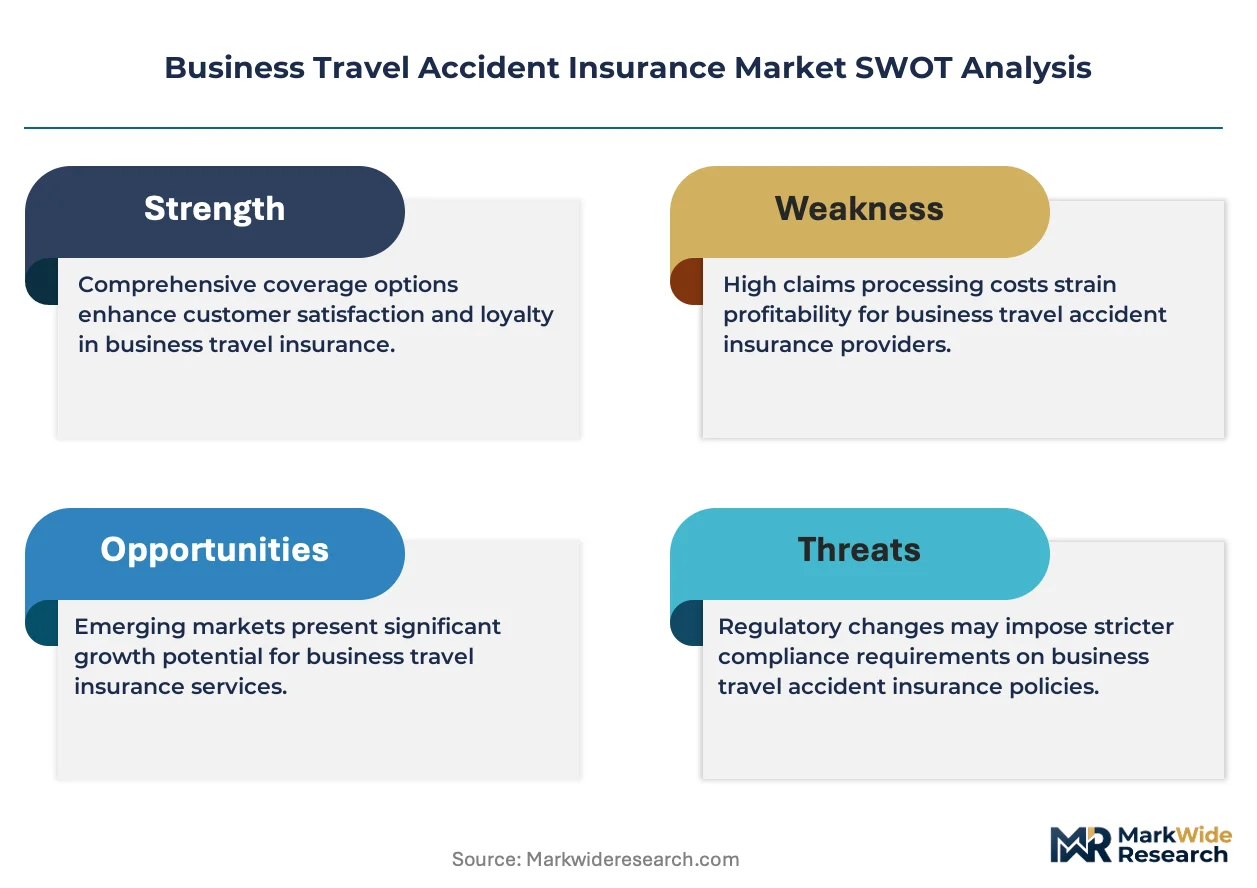
Concentration sits with global underwriters possessing international assistance networks and multinational compliance architectures. Three archetypes dominate: premium-tier global carriers with integrated security intelligence, regional specialists competing on price in domestic travel segments, and digital platforms targeting underpenetrated SME markets. Competitive moves center on embedded distribution partnerships with corporate travel management systems and AI-driven personalization capabilities that displace one-size-fits-all corporate rate cards.
Among European-based global carriers, AXA, Chubb, and Allianz occupy positions exemplifying the premium-tier archetype with cross-border claims capabilities and specialized risk engineering services. These carriers represent the underwriting concentration in London and Zurich markets, anchoring high-limit corporate programs through master policy structures. Regional specialists and digital platforms sit within fragmented tiers competing for standardized instant-quote products among small enterprises.
| Leading Market Players |
|---|
| AXA |
| Chubb |
| AIG |
| Zurich Insurance Group |
| Allianz |
| MetLife |
| The Hartford |
| Assicurazioni Generali |
| Tokio Marine Holdings |
| Others |
Pricing and Supply Chain Analysis
Reinsurance capacity utilization in London and Bermuda markets concentrates catastrophic risk coverage, creating scale economies that anchor price floors for high-limit corporate programs while compressing margins for regional specialists lacking treaty access. This concentration forces carriers to calibrate territorial rating models against divergent national healthcare cost bases, with US medical evacuation expenses commanding premium loading far above Germany's statutory health insurance offsets.
Pricing Analysis
OSHA workplace safety guidelines dictate the pricing tier structure for US corporate placements, mandating documented duty-of-care protocols that elevate minimum coverage thresholds. Three-tier pricing structure across premium, standard, and economy levels separates global underwriters with integrated security intelligence from regional specialists competing on domestic travel segments. Cost compression in the standard tier is intensifying because social insurance overlap in Japan reduces employer demand for supplemental private coverage. Small enterprises in India's underpenetrated SME segment exhibit highest price sensitivity, while multinational headquarters in Germany and Japan demonstrate lowest sensitivity due to CSRD compliance mandates.
Supply Chain Analysis
Container availability constraints on Asia-Europe trade lanes complicate the inbound logistics for medical evacuation services requiring rapid cross-border deployment. Underwriting capacity concentrates in London, Zurich, and New York, drawing from reinsurance treaties, actuarial talent pools, and international assistance networks. The supply chain rests on specialized risk engineering services, AI-driven travel intelligence platforms, and legacy policy administration systems. Single-source vulnerability sits with London and Bermuda markets controlling catastrophic loss coverage for high-limit programs. Distribution runs through insurance brokers designing multinational compliance architectures, with online platforms gaining downstream traction among price-sensitive SME segments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market represents an early-cycle expansion story as corporate duty-of-care obligations tighten across jurisdictions, with the EU's CSRD mandates and Japan's METI standards creating structural tailwinds in coverage procurement for international assignments.
For Market Incumbents: Secure treaty capacity in London and Bermuda markets to defend catastrophic loss coverage positioning against emerging digital platforms. Anchor high-limit corporate programs through specialized risk engineering services, while investing in AI-driven personalization capabilities that displace one-size-fits-all corporate rate cards threatened by machine learning risk scoring entrants. For New Entrants and Emerging Players: ISO 31030 travel risk management certification fast-track enables credibility acceleration for white-space targeting in India's underpenetrated SME segment. Mumbai and Bangalore technology startups lack structured travel protection programs, presenting penetration opportunities through digital distribution platforms offering instant-quote standardization without advisory fees. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among annual multi-trip master agreement providers serving technology sector enterprises with recurring client-site deployments. Long-term viability centers on carriers with embedded distribution partnerships in corporate travel management systems, with AI-driven underwriting granularity serving as the inflection indicator for competitive positioning shifts.| Strategic Initiative | Industry Significance |
|---|---|
| Embedded Distribution Partnership | Integration with Concur and SAP Ariba creates frictionless policy attachment at booking. |
| AI-Driven Personalization Investment | Machine learning risk scoring enables individual traveler pricing displacing corporate rate cards. |
| Reinsurance Treaty Expansion | London and Bermuda capacity access anchors high-limit corporate program competitiveness. |
| Certification Fast-Track Program | ISO 31030 travel risk management credentials accelerate credibility in SME segments. |
| Legacy System Modernization | Real-time travel intelligence API integration compresses underwriting cycles for competitive service. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with risk managers at multinational headquarters, insurance brokers designing compliance architectures, underwriting executives at global carriers, and digital platform product managers. Secondary validation drew from OSHA regulatory filings, EU CSRD disclosure frameworks, METI occupational safety standards, SEC insurance carrier 10-K filings, and Lloyd's market capacity reports. Bottom-up policy volume estimates triangulated against top-down premium pool calculations derived from corporate travel expenditure databases.
Across the analysis window, the forecasting framework modeled segmentation dimensions including policy type structure, coverage scope configuration, client scale tier, and distribution channel mechanics. CAGRs were computed through regression analysis of historical premium growth trajectories against corporate travel volume indices and regulatory mandate adoption curves. Industry-specific inputs incorporated duty-of-care litigation frequency trends, medical evacuation cost inflation differentials across territorial rating zones, and SME penetration rate assumptions for digital distribution platforms.
Decision-makers should treat outputs as directional under base assumptions of sustained regulatory tightening in EU and Japanese jurisdictions; material deviation would warrant model refresh. Specific risk factors that could revise forecasts include repeal of CSRD disclosure requirements, harmonization of social insurance offsets reducing supplemental coverage demand, or breakthrough automation in claims adjudication compressing loss ratios beyond projected bounds. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Insurance
US Extended Warranty Market
Insurance
Europe Travel Insurance Market
Insurance
Usage-Based Insurance for Automotive Market
Insurance
Commercial Cyber Insurance Market
Insurance
United Kingdom Car Insurance Market
Insurance
UK Travel Insurance Market
Insurance
United States Dental Insurance Market
Insurance
Boiler Insurance Market
Insurance
Business Insurance Market
Insurance
China Liability Insurance Market
Insurance
Identity Theft Insurance Market
Insurance
Group Health Insurance Market
Insurance
Income Protection Insurance Market
Insurance
Financial Protection Market
Insurance
Global Cargo Transportation Insurance Market
Insurance
South Korea Liability Insurance Market