
 United States Commercial Insurance Market | 2026-2036
United States Commercial Insurance Market Size, Share, and Industry Trends Forecast 2026-2036
United States Commercial Insurance Market Intelligence
Texas is reshaping commercial insurance capacity through its energy-sector risk concentration and catastrophe-exposed property growth. Travelers Companies Inc. leverages its middle-market underwriting expertise to sustain pricing discipline across volatile lines. Berkshire Hathaway Insurance anchors long-tail liability portfolios with exceptional capital depth. Progressive Insurance Group competes aggressively in commercial auto through data-driven loss-cost segmentation.
United States Commercial Insurance constitutes risk-transfer contracts underwritten to protect businesses against property damage, liability exposure, and operational interruption, with policies typically structured on occurrence or claims-made bases and priced through actuarial loss-cost modeling. General Liability coverage dominates premium volume as litigation frequency elevates severity trends in slip-and-fall and product defect exposures. Workers' Compensation retains structural importance in high-wage states despite multi-decade rate adequacy cycles. Small Businesses represent the fastest-expanding policyholder segment as gig-economy formations and remote-work structures multiply insurable entities.
National Association of Insurance Commissioners coordinates state-level solvency standards while state insurance departments enforce rate filing adequacy, collectively shaping carrier capital requirements and market entry barriers. Federal Risk Management Agency flood rules and emerging SEC climate disclosure mandates are forcing commercial buyers to reconcile physical risk transparency with coverage procurement strategies. Stakeholders must monitor how state-by-state regulatory fragmentation affects multi-jurisdictional program structuring and captive domicile selection.
Market Dynamics
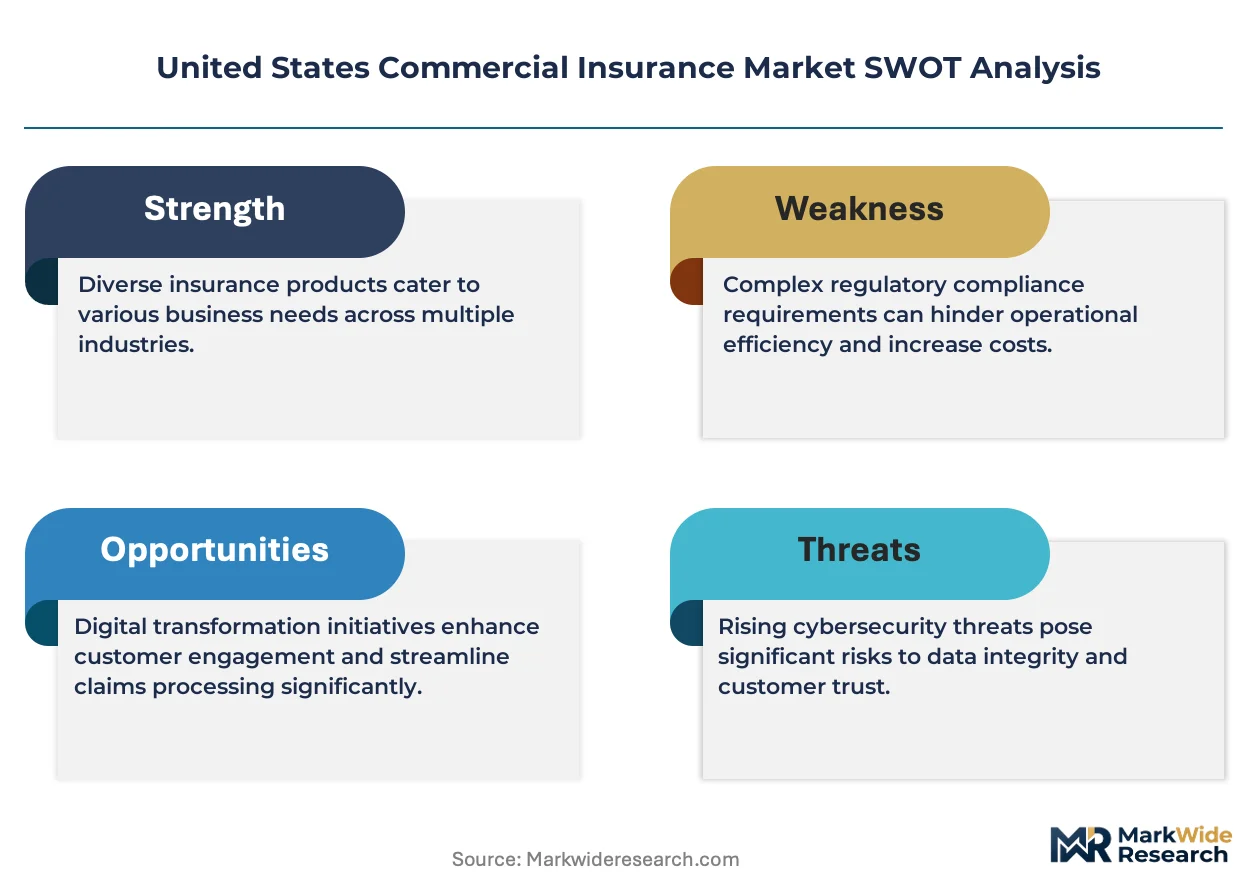
State-level cyber risk mandates and SEC climate disclosure rules are compressing coverage procurement timelines while forcing carriers to rebuild underwriting models around intangible asset exposures.
Growth Catalysts
- Healthcare expansion:Hospital systems and outpatient networks are expanding professional liability and cyber coverage procurement as HIPAA enforcement intensifies and patient data breaches multiply.
- OSHA workplace safety mandates:Stricter federal enforcement of workplace injury reporting is elevating Workers' Compensation premium adequacy in manufacturing-heavy states.
- Texas energy corridor concentration:Permian Basin drilling activity and Gulf Coast petrochemical expansion are generating concentrated demand for property and environmental liability capacity.
Market Restraints
- Reinsurance capacity tightening:Catastrophe bond spreads and collateral requirements have hardened following consecutive hurricane seasons, compressing primary carrier deployment limits.
- Long-tail liability reserve volatility:Asbestos and environmental remediation claims continue deteriorating actuarial confidence in occurrence-based General Liability portfolios.
- Litigation funding expansion:Third-party litigation finance is elevating claim severity in commercial auto and premises liability lines through prolonged discovery tactics.
Strategic Opportunities
- Parametric coverage innovation:Index-triggered policies for business interruption and supply chain disruption are penetrating middle-market manufacturing buyers previously excluded from traditional indemnity structures.
- Embedded insurance distribution:Commercial insurance products integrated into SaaS platforms and payroll systems are capturing micro-business formations in California's technology corridor.
- IRA clean energy incentives:Federal tax credits for solar and battery storage deployment are expanding insurable asset bases for property and construction risk underwriters.
Industry Challenges
- Actuarial talent scarcity:P&C carriers face acute shortages of predictive modelers capable of integrating satellite imagery and IoT sensor data into dynamic pricing engines.
- Legacy system integration friction:Policy administration platforms built on 1990s architectures resist API connectivity with InsurTech data streams, delaying real-time underwriting deployment.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | United States Commercial Insurance Market |
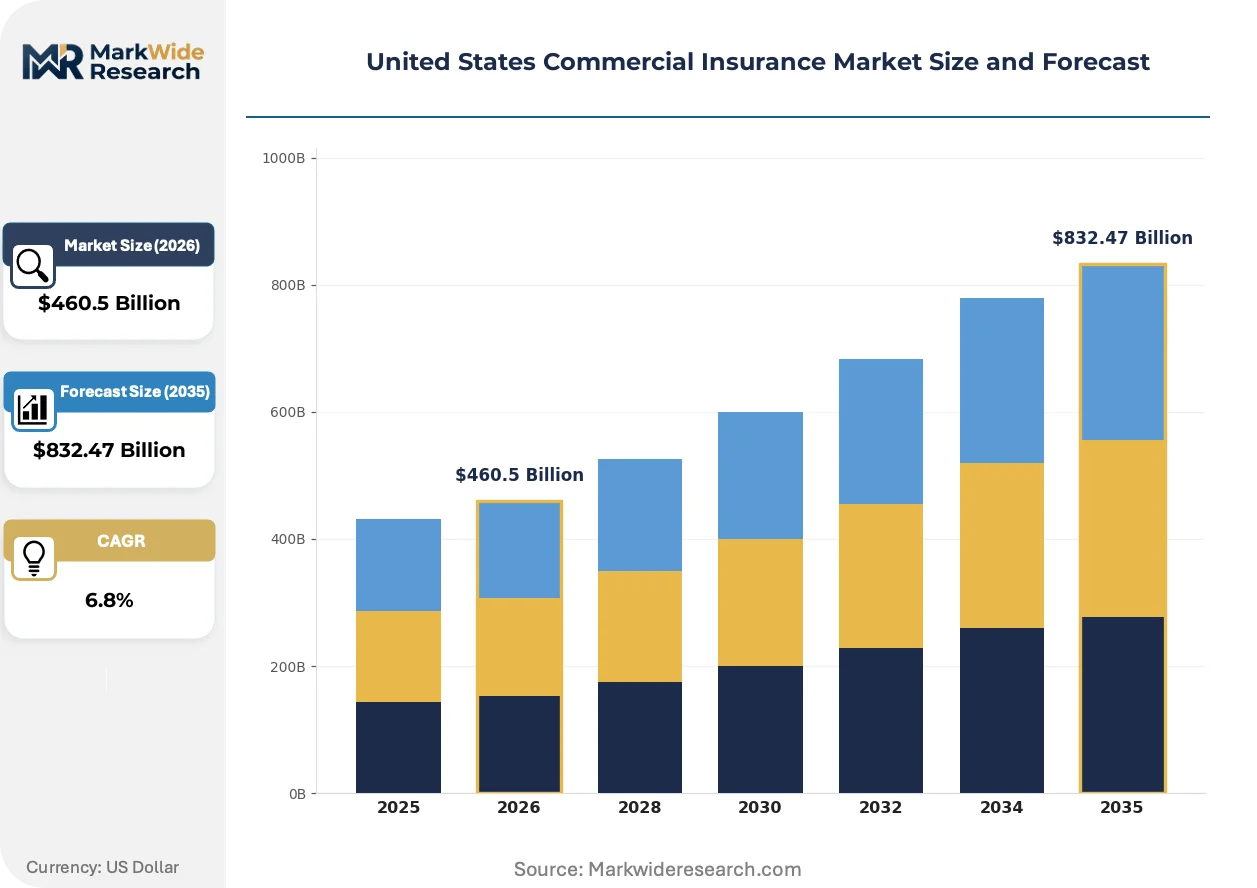
| Market Size in 2026 | $460.5 Billion |
| Market Size in 2035 | $832.47 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Coverage Type: General Liability, Property, Professional Liability, Workers' Compensation Policyholder Type: Small Businesses, Corporations, Non-profits, Government Entities Distribution Channel: Direct Sales, Brokers, Online Platforms, Agents Industry Vertical: Construction, Healthcare, Retail, Transportation |
| Companies Covered | State Farm Group, Allstate Insurance Group, Travelers Companies Inc., USAA Group, Berkshire Hathaway Insurance, Chubb Ltd., Progressive Insurance Group, CNA Insurance Companies, Liberty Mutual Insurance Companies, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
United States Commercial Insurance Market Strategic Shifts & Innovations
Telematics and satellite imagery are compressing information asymmetries between carriers and policyholders, enabling dynamic pricing models that adjust to real-time risk conditions rather than static annual renewals.
Telematics hardware paired with fleet management software is virtualizing commercial auto underwriting. Long-haul trucking operators and last-mile delivery fleets are adopting driver-behavior monitoring at accelerating rates. This sensor infrastructure is virtualizing the traditional premium calculation cycle from annual retrospection to continuous adjustment.
SEC climate disclosure mandates are forcing publicly traded buyers to quantify physical asset exposure. Industrial manufacturers and real estate investment trusts must now reconcile flood and wildfire risk transparency with coverage procurement strategies. California and Florida property markets are experiencing the earliest compression effects as disclosure timelines accelerate.
Small business buyers are consolidating procurement through digital brokerage platforms. Traditional independent agent channels face displacement as gig-economy formations and remote-work structures multiply insurable entities. Texas and Georgia metropolitan areas exhibit the highest platform adoption velocity among middle-market commercial purchasers.
United States Commercial Insurance Market Segmentation
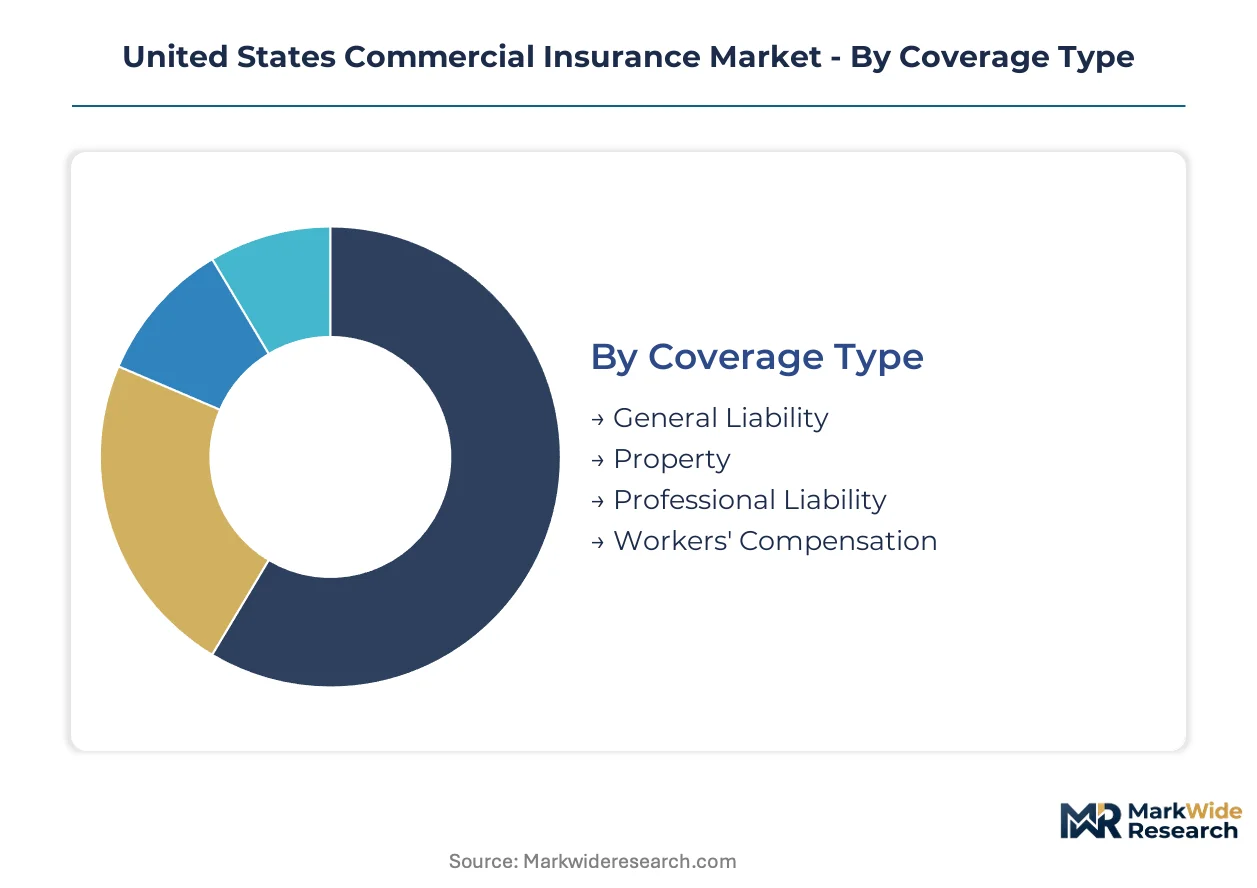
Commercial insurance segmentation in the United States reflects divergent risk profiles across coverage types, policyholder scale, and industry exposure. Carriers calibrate capital deployment and pricing models through these dimensions, with each segment demanding distinct underwriting expertise and distribution economics.
Coverage Type:
After-sales service intensity varies sharply across coverage lines, with claims frequency and settlement complexity driving carrier operational investments.
- General Liability:Occurrence-based contracts covering third-party bodily injury and property damage from business operations. Slip-and-fall litigation in California retail corridors and product defect exposure in Texas manufacturing sustain premium volume leadership despite deteriorating loss-cost trends.
- Property:First-party coverage for physical asset damage from perils including fire, wind, and flood. Gulf Coast petrochemical facilities and California wildland-urban interface properties are compressing capacity as catastrophe modeling tightens underwriting standards.
- Professional Liability:Claims-made policies indemnifying errors and omissions in specialized services. Healthcare systems expanding cyber coverage procurement under HIPAA enforcement elevate demand concentration.
- Workers' Compensation:Statutory coverage for workplace injury medical costs and wage replacement. OSHA enforcement intensity in Midwest manufacturing states supports rate adequacy cycles.
By volume, General Liability leads. By growth pace, Professional Liability is expanding most quickly.
Policyholder Type:
Cost tier stratification across policyholder segments shapes carrier expense ratios and retention strategies.
- Small Businesses:Gig-economy formations and remote-work structures are multiplying insurable entities. Embedded distribution through payroll platforms and SaaS integrations is capturing micro-business formations in Texas and Georgia metropolitan areas.
- Corporations:Multi-line program buyers with captive insurance alternatives and complex international exposures. SEC climate disclosure mandates are forcing reconciliation of physical risk transparency with coverage procurement strategies.
- Non-profits:Social service and cultural institutions with constrained risk management staffing. Volunteer liability and directors-and-officers exposure concentrate demand in healthcare-adjacent organizations.
- Government Entities:Municipal and state purchasers with sovereign immunity complications and statutory procurement requirements. Infrastructure project bonding and public official liability dominate placement activity.
Small Businesses dominate policy count. Corporations command premium concentration.
Distribution Channel:
Application-specific channel selection reflects policyholder sophistication and coverage complexity thresholds.
- Direct Sales:Carrier-employed producers targeting Fortune 500 accounts with captive program structures. Travelers and Berkshire Hathaway deploy dedicated underwriting teams for middle-market and large corporate placements.
- Brokers:Independent intermediaries with market access across multiple carriers. Retail brokerage consolidation is compressing commission structures while elevating placement sophistication requirements.
- Online Platforms:Digital-first distribution capturing micro-business formations through algorithmic underwriting. California technology corridor exhibits highest platform adoption velocity among middle-market purchasers.
- Agents:Exclusive and independent producers with localized relationship networks. Traditional independent agent channels face displacement as digital procurement habits harden among younger policyholders.
Brokers retain premium volume leadership. Online Platforms are gaining share fastest.
Industry Vertical:
Customer-type concentration across verticals determines carrier sector specialization and loss-cost benchmarking intensity.
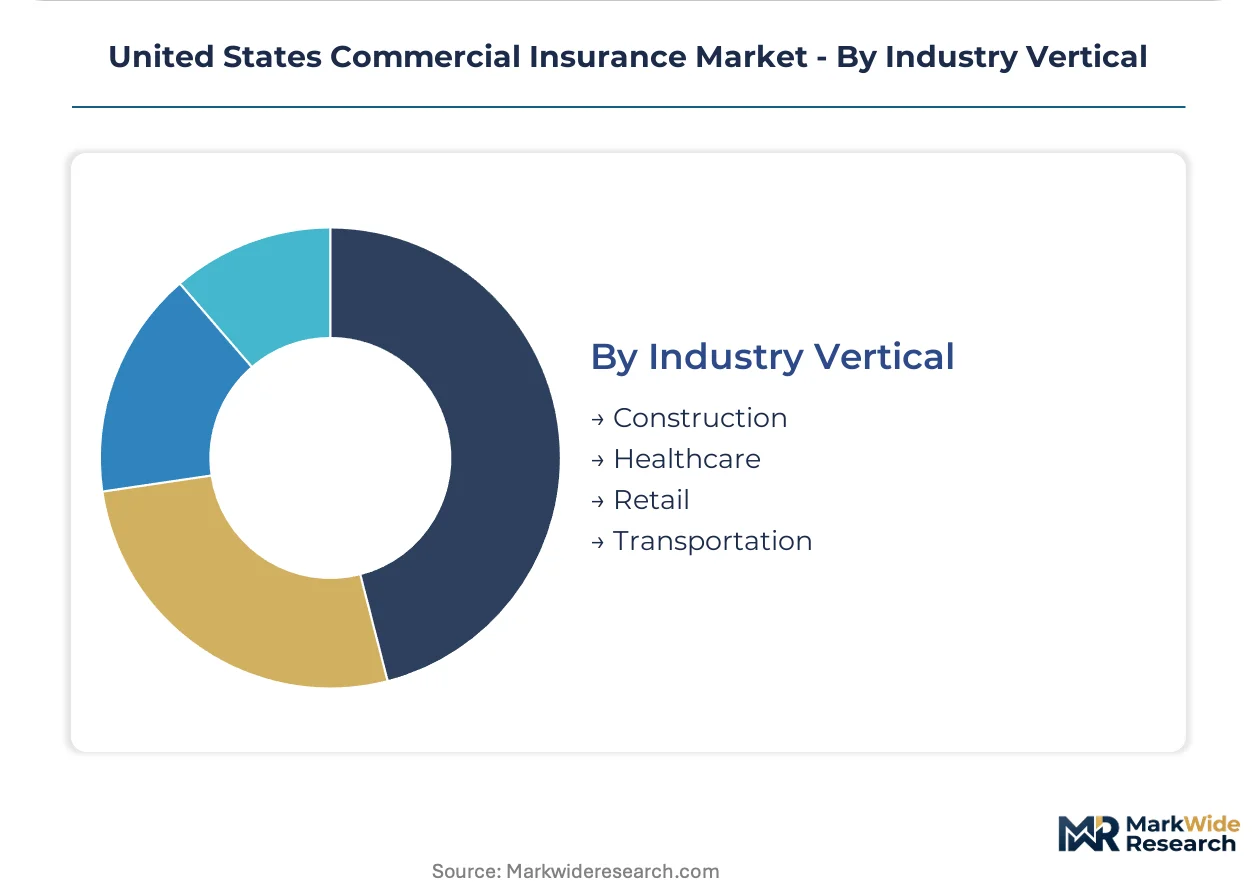
- Construction:Surety bonding and wrap-up liability programs for project-specific exposures. Permian Basin drilling activity and Gulf Coast petrochemical expansion are generating concentrated property and environmental liability demand.
- Healthcare:Hospital systems and outpatient networks expanding professional liability and cyber coverage procurement. HIPAA enforcement intensification and patient data breach frequency elevate severity trends.
- Retail:Premises liability and product liability coverage for storefront and e-commerce operations. Slip-and-fall litigation frequency in high-traffic California corridors sustains General Liability premium flow.
- Transportation:Commercial auto and cargo coverage for fleet operators. Telematics hardware paired with fleet management software is virtualizing underwriting from annual retrospection to continuous adjustment.
Healthcare leads premium growth trajectory. Construction retains the steepest loss-cost volatility.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
NAIC coordinates solvency standards across state insurance departments while Texas and California concentrate premium volume through energy and technology sector risk pools.
Texas
Permian Basin drilling activity and Gulf Coast petrochemical expansion generate concentrated property and environmental liability demand. OSHA workplace safety mandates elevate Workers' Compensation premium adequacy in manufacturing-heavy counties. Houston anchors energy-sector risk concentration with catastrophe-exposed property growth compressing carrier capacity.
California
Technology corridor formations and HIPAA enforcement intensification drive professional liability and cyber coverage procurement. SEC climate disclosure mandates force real estate investment trusts to reconcile flood and wildfire risk transparency with coverage strategies. San Francisco Bay Area exhibits highest digital brokerage platform adoption velocity among middle-market purchasers.
New York
Financial services sector consolidation and directors-and-officers exposure elevate specialty lines demand. State insurance department rate filing adequacy enforcement shapes carrier capital deployment limits. Manhattan anchors captive insurance program structuring for multi-national corporations with complex international exposures.
Florida
Gulf Coast hurricane exposure and flood risk concentration compress property capacity as catastrophe modeling tightens underwriting standards. Federal Risk Management Agency flood rules force commercial buyers into supplemental coverage procurement. Miami-Dade commercial real estate markets experience earliest disclosure timeline compression effects.
Illinois
Midwest manufacturing density and OSHA enforcement intensity sustain Workers' Compensation rate adequacy cycles. Transportation sector fleet operators adopt telematics hardware for commercial auto underwriting virtualization. Chicago anchors logistics and distribution center property coverage demand with supply chain disruption exposure growth.
United States Commercial Insurance Market Key Industry Players
Mutual insurers and stock carriers split the market through divergent capital structures and distribution economics. The competitive landscape exhibits tiered consolidation with national multi-line writers, regional specialists, and direct-to-consumer platforms occupying distinct strategic positions. Capital depth and underwriting discipline separate sustainable participants from price-driven competitors. Dominant competitive moves include portfolio diversification into specialty lines and embedded insurance distribution partnerships with SaaS platforms.
Within the capital-anchored tier, Berkshire Hathaway Insurance and Travelers Companies Inc. exemplify underwriting discipline through long-tail liability portfolio management and middle-market expertise. Progressive Insurance Group occupies a position on the data-driven segmentation vector, competing through telematics-enabled loss-cost modeling in commercial auto. These three carriers represent divergent strategic archetypes: exceptional capital depth, traditional underwriting excellence, and technology-enabled pricing precision.
| Leading Market Players |
|---|
| State Farm Group |
| Allstate Insurance Group |
| Travelers Companies Inc. |
| USAA Group |
| Berkshire Hathaway Insurance |
| Chubb Ltd. |
| Progressive Insurance Group |
| CNA Insurance Companies |
| Liberty Mutual Insurance Companies |
| Others |
Cost & Logistics Intelligence
The I-10 freight corridor linking Houston to Los Angeles compresses delivery economics for policy documentation and claims-adjusting equipment, concentrating carrier procurement leverage in Texas and California hubs while feeding premium differentiation between catastrophe-exposed and inland risk territories.
Pricing Analysis
Geographic price spreads between Gulf Coast catastrophe zones and Midwest inland territories exceed 40% for equivalent property limits. Three-tier pricing structure across admitted, excess and surplus, and captive-fronted levels stratifies buyers by capitalization and risk retention capacity. Pricing pressure stems from reinsurance collateral demands following consecutive hurricane seasons. Small businesses exhibit highest price sensitivity, while Fortune 500 captives demonstrate capacity to absorb volatility.
Supply Chain Analysis
Third-party administrators and independent adjusting firms hold concentrated capacity in Florida, Texas, and California, with Crawford and Sedgwick anchoring catastrophe response deployment. Actuarial talent draws from university programs in Illinois, Pennsylvania, and Massachusetts, while underwriting technology feeds from InsurTech clusters in New York and San Francisco. Single-source vulnerability concentrates in legacy policy administration platforms resisting API modernization. Distribution runs through independent agent networks, direct carrier sales forces, and emerging embedded insurance partnerships.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is concentrating through digital brokerage platform consolidation, with small commercial purchasers consolidating procurement through algorithmic marketplaces that fragment traditional agent relationships.
For Market Incumbents: Build data moat superiority through telematics integration and satellite imagery deployment. Invest in backward integration into predictive modeling capabilities to offset actuarial talent scarcity. Defend against InsurTech entrants by controlling distribution APIs with payroll and SaaS platforms. Prioritize captive domicile diversification across Vermont, Delaware, and Texas to retain large corporate relationships. For New Entrants and Emerging Players: Middle-market transportation fleets in Georgia and Illinois represent the most penetrable entry point for telematics-enabled commercial auto underwriting. Embedded distribution partnerships with fleet management software providers offer lowest customer acquisition cost pathway. Target parametric coverage for supply chain disruption in manufacturing-heavy Midwest corridors as alternative to traditional indemnity structures. For Investors and Strategic Acquirers: Carve-out targets emerge from legacy mutual insurers with undervalued long-tail liability portfolios and stagnant distribution technology. Five-to-ten-year viability hinges on successful platform modernization and talent acquisition. Monitor catastrophe bond spread compression as inflection indicator for primary carrier capital deployment capacity.| Strategic Initiative | Industry Significance |
|---|---|
| Telematics Integration Partnership | Progressive and Travelers leverage driver-behavior data to virtualize commercial auto underwriting cycles. |
| Embedded Insurance Distribution | SaaS platform integrations capture micro-business formations in California technology corridor with minimal acquisition cost. |
| Captive Domicile Expansion | Vermont and Texas regulatory frameworks attract corporate self-insurance structures seeking rate adequacy control. |
| Parametric Coverage Development | Index-triggered policies penetrate middle-market manufacturing buyers excluded from traditional indemnity structures. |
| Legacy System Modernization | API connectivity with InsurTech data streams enables real-time underwriting deployment for competitive positioning. |
Research Approach
Two parallel data streams informed the analysis: structured interviews with underwriting executives, actuarial directors, and digital distribution heads; and secondary validation through NAIC statutory filings, SEC insurance subsidiary disclosures, and state insurance department rate filing databases. Primary fieldwork encompassed discussions with captive managers, reinsurance brokers, and InsurTech platform operators across Texas, California, New York, and Illinois. Bottom-up policy count and premium volume estimates triangulated against top-down carrier reported data.
Forecast inputs incorporated coverage type segmentation, policyholder scale tiers, and distribution channel dynamics across the analysis window. Modeled dimensions included general liability, property, professional liability, and workers compensation lines intersected with small business, corporate, and non-profit buyer archetypes. CAGRs derived from actuarial loss-cost trend analysis, regulatory mandate implementation timelines, and sector-specific exposure growth patterns in energy, healthcare, and technology verticals.
Stress conditions across hurricane frequency, litigation funding expansion, and reinsurance capacity contraction were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions regarding regulatory enforcement intensity and cyber incident severity trends. Quarterly review of catastrophe bond issuance spreads and state-level rate filing approval velocity is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Insurance
Endowment Insurances Market
Insurance
Global Healthcare Claims Management Market
Insurance
US Long-Term Care Private Insurance Market
Insurance
Asia-Pacific Family Floater Health Insurance Market
Insurance
Global Home Insurance Market
Insurance
Asia-Pacific Mobile Phone Insurance Market
Insurance
Canada Health and Medical Insurance Market
Insurance
Agricultural Insurance Market
Insurance
Usage-Based Insurance for Automotive Market
Insurance
Bancassurance Market
Insurance
Logistics Insurance Market
Insurance
Property Insurance Market
Insurance
Horse Insurance Market
Insurance
Saudi Arabia Health & Medical Insurance Market
Insurance
Green Insurance Market
Insurance
Auto Extended Warranty Market