
 Cloud Computing in Insurance Market | 2026-2036
Cloud Computing in Insurance Market Size, Share, and Industry Trends Forecast 2026-2036
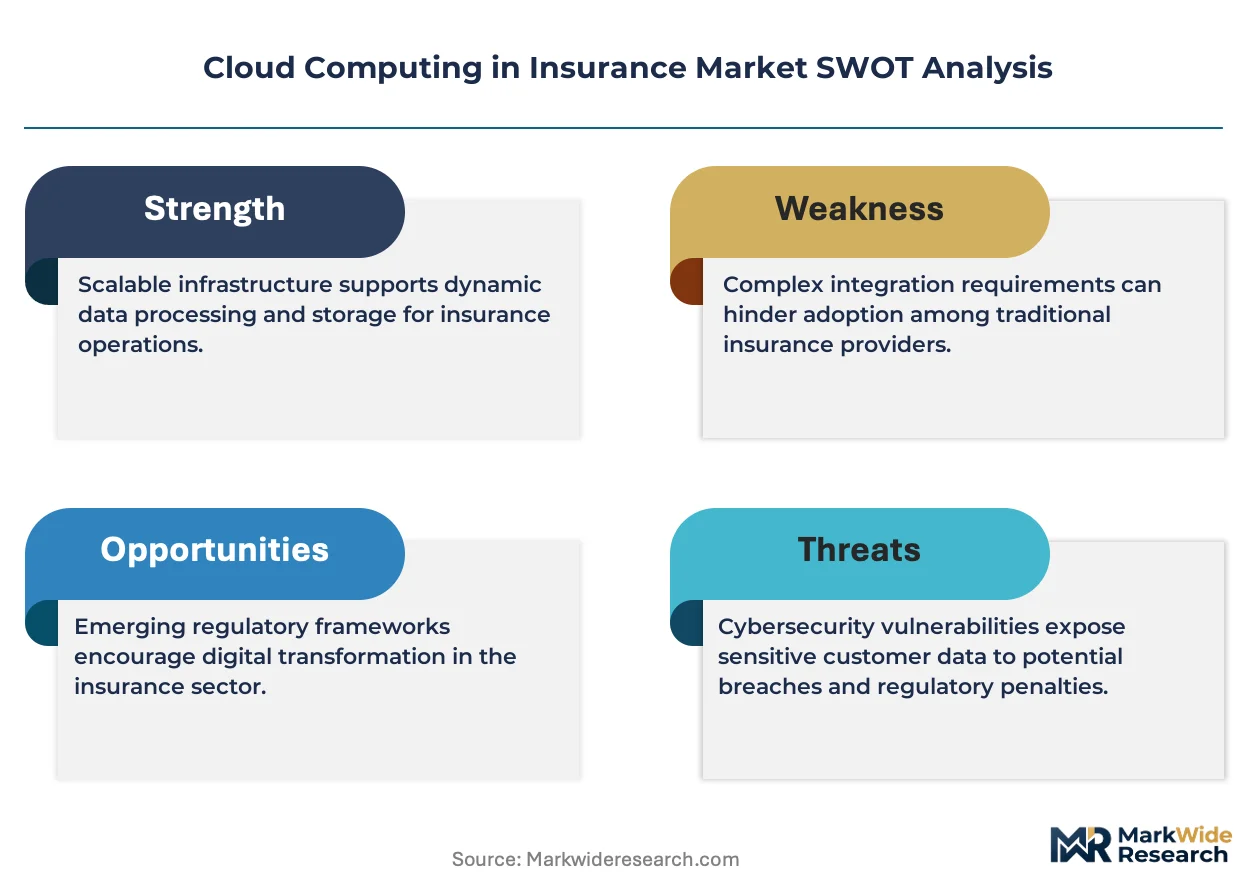
Cloud Computing in Insurance Market Analysis
The EU Green Deal and CSRD disclosure mandates is recalibrating how European insurers provision IT infrastructure, with sustainability-linked procurement criteria now embedded in vendor selection. Microsoft Azure dominates sovereign cloud deployments across continental carriers, leveraging dedicated EU data residency zones. Amazon Web Services anchors catastrophic risk modeling workloads for North American property insurers, sustaining elastic compute contracts that spike during hurricane seasons. IBM Cloud specializes in mainframe-to-cloud modernization for legacy actuarial systems, competing on regulatory audit trails that satisfy state-level insurance commissioners.
Cloud computing in insurance denotes the delivery of on-demand computing resources—encompassing distributed storage, serverless processing, and API-orchestrated microservices—over networked infrastructure to carriers, brokers, and managing general agents. Its primary purpose centers on replacing capital-intensive on-premises data centers with usage-metered platforms that scale premium processing, claims adjudication, and regulatory reporting without fixed hardware commitments. Hybrid Cloud deployments now capture the widest carrier adoption as insurers retain sensitive policyholder data in private nodes while bursting actuarial analytics into public environments. SaaS functionality concentrates margin pools in policy administration and claims management, where Guidewire Software and Duck Creek Technologies have built vertically integrated application layers atop hyperscaler infrastructure.
FDA guidelines on software-as-medical-device increasingly intersect with health insurance cloud platforms that process wearable-derived risk data, while HIPAA mandates encryption standards for protected health information traversing multi-tenant architectures. State insurance departments in California and New York impose separate cybersecurity examination protocols that elevate compliance costs for cloud vendors serving admitted carriers. Stakeholders must monitor how fragmented supervisory frameworks across federal and state jurisdictions reshape vendor qualification criteria and data-architecture decisions.
Market Dynamics
Property insurers are migrating core systems to cloud-native platforms to accelerate claims processing, while the EU AI Act and GDPR compliance requirements are forcing carriers to adopt sovereign cloud architectures that fragment vendor selection criteria across jurisdictions.
Growth Catalysts
- Data-Localization Mandates:Germany's BaFin requires actuarial systems to reside within national borders, creating captive demand for sovereign cloud infrastructure among continental carriers.
- Elastic Compute for Catastrophic Risk:Hurricane-season volatility drives North American property insurers toward usage-metered platforms that burst processing capacity without fixed hardware commitments.
- Microservices Orchestration:API-driven policy administration is displacing monolithic core systems as carriers modernize claims adjudication workflows.
Market Restraints
- Multi-Jurisdictional Compliance Costs:HIPAA encryption standards for health data and state-level cybersecurity examination protocols in California and New York elevate vendor qualification barriers.
- Legacy Mainframe Dependency:Decades-old actuarial systems in tier-one carriers resist cloud migration due to embedded business logic and regulatory audit trail requirements.
- Input Cost Concentration:Hyperscaler compute pricing is dominated by three vendors, limiting carrier negotiating leverage for long-term infrastructure contracts.
Strategic Opportunities
- Sustainability-Linked Procurement:The EU Green Deal and CSRD disclosure mandates are embedding carbon-intensity criteria into vendor selection, favoring providers with dedicated renewable-energy data centers.
- Wearable-Derived Risk Data:FDA guidelines on software-as-medical-device are intersecting with health insurance platforms, opening new premium-pricing models based on real-time biometric streams.
- Hybrid Cloud Bursting:Carriers are retaining sensitive policyholder data in private nodes while shifting actuarial analytics to public environments, creating dual-architecture service contracts.
Industry Challenges
- Actuarial Talent Scarcity:Cloud-native skill gaps in legacy carrier IT departments are delaying mainframe-to-modern-platform transitions.
- Fragmented Supervisory Frameworks:Federal and state jurisdictions impose non-aligned cybersecurity protocols that complicate multi-tenant architecture design for vendors serving admitted carriers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Cloud Computing in Insurance Market |
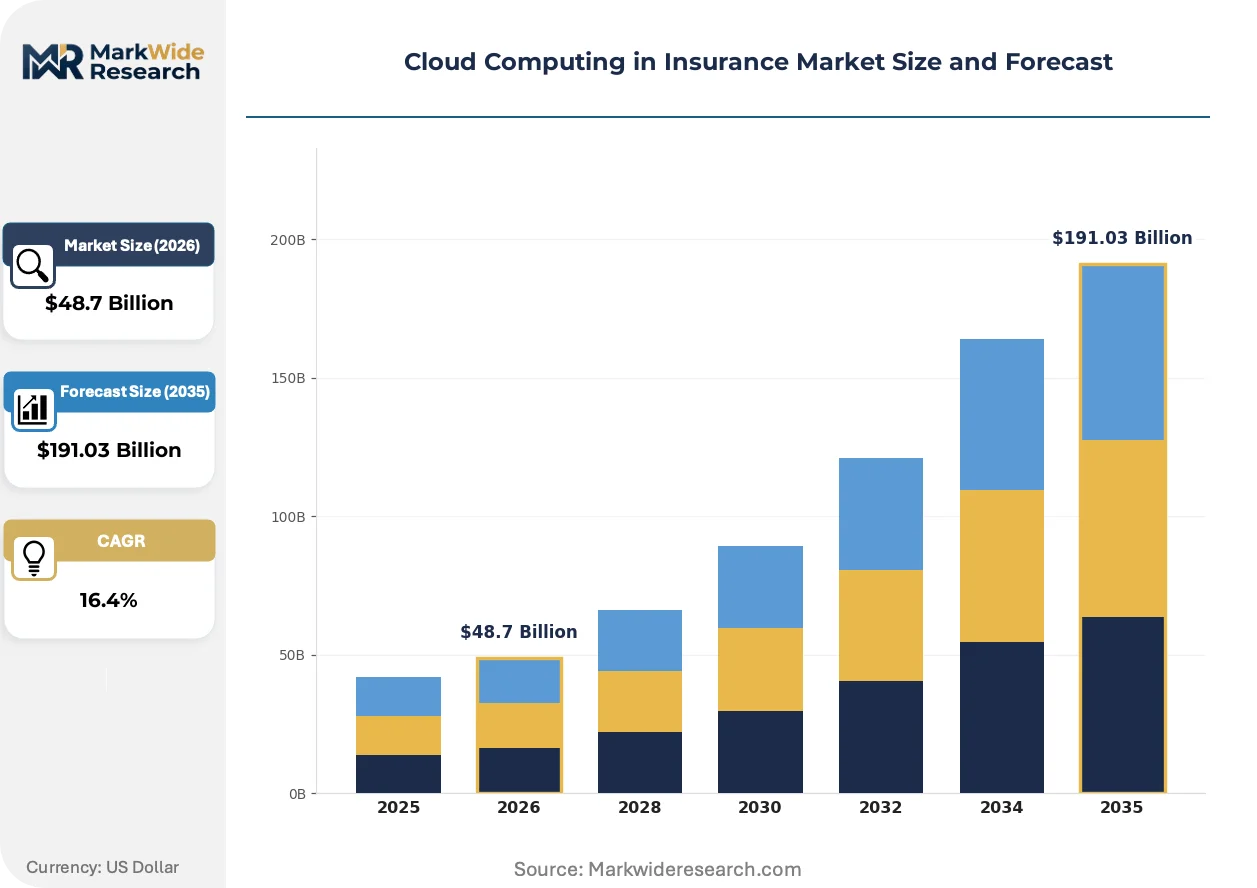
| Market Size in 2026 | $48.7 Billion |
| Market Size in 2035 | $191.03 Billion |
| CAGR (2026 – 2036) | 16.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Deployment Model: Public Cloud, Private Cloud, Hybrid Cloud, Multi-Cloud Service Type: IaaS, PaaS, SaaS, DRaaS End User: Life Insurance, Health Insurance, Property Insurance, Liability Insurance Functionality: Claims Management, Policy Administration, Underwriting, Risk Assessment |
| Companies Covered | IBM Cloud, Oracle Cloud, Amazon Web Services, Guidewire Software, Salesforce, Microsoft Azure, Duck Creek Technologies, Redian Software, Google Cloud, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Cloud Computing in Insurance Market Emerging Trajectories
Serverless processing architectures are absorbing traditional batch-compute workloads as insurers seek to eliminate idle infrastructure costs during non-peak premium processing periods.
Containerized microservices are absorbing monolithic policy administration systems, enabling carriers to deploy incremental updates without system-wide downtime. Mid-tier property insurers in Florida and Texas are adopting this architecture fastest to meet hurricane-season scaling demands. The structural consequence is compressing vendor implementation cycles from multi-year transformations to quarterly capability releases.
The EU AI Act's risk-classification framework for automated decision-making is forcing carriers to document algorithmic transparency in underwriting and claims systems. This is mandating explainable-AI tooling investments across continental European operations. German and French carriers are responding by embedding audit-log capabilities directly into cloud-native policy engines.
Usage-based procurement models are displacing fixed-term enterprise licenses as carriers demand consumption-metered contracts aligned to premium volume fluctuations. Managing general agents and broker platforms are driving this shift, pressuring vendors to offer granular billing tied to policy transactions rather than seat-based pricing. This pattern is most visible in North American commercial lines where seasonal insured exposure varies significantly.
Cloud Computing in Insurance Market Segmentation
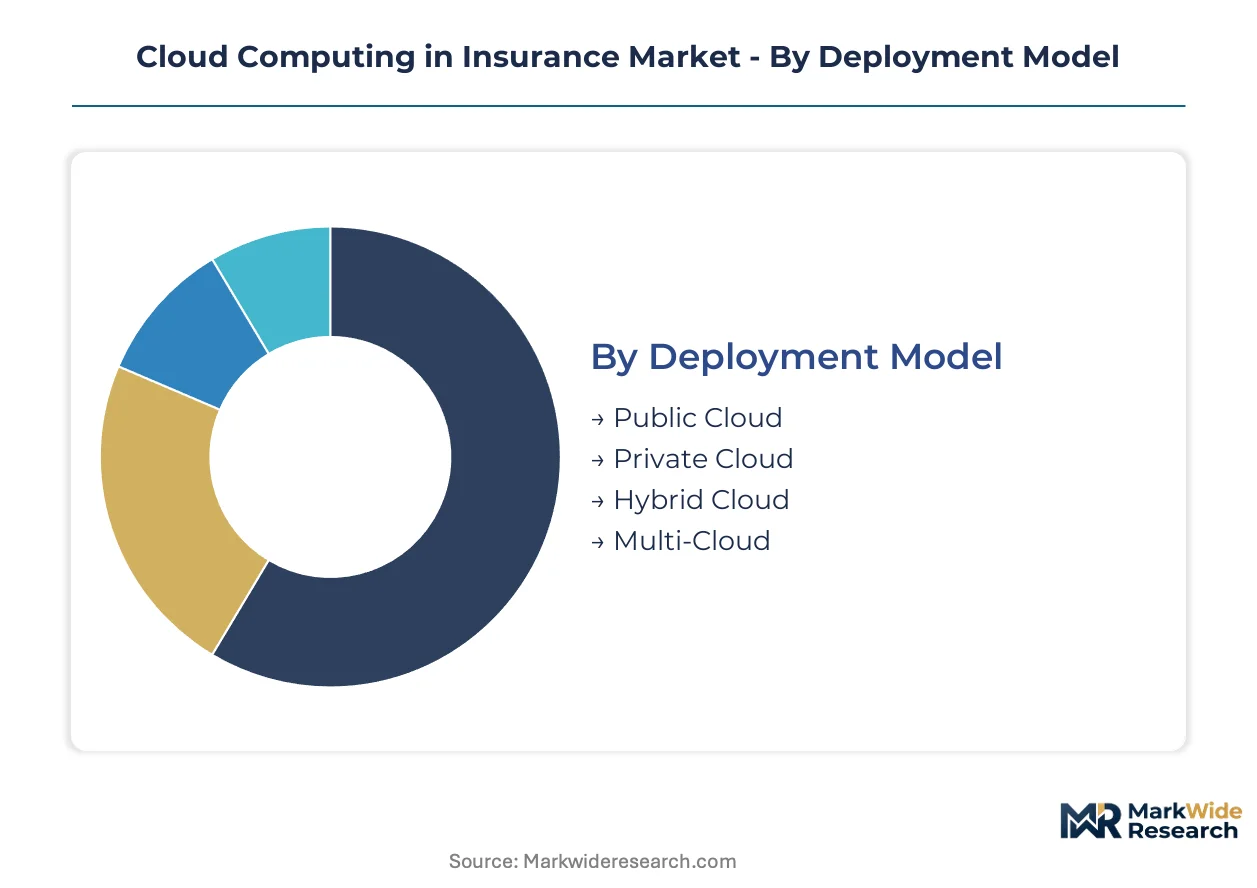
Cloud infrastructure procurement in insurance diverges sharply by integration depth, with carriers balancing data sovereignty against elastic scaling needs. Deployment architecture determines regulatory compliance pathways and cost structures across policy lifecycle management.
Deployment Model:
Standalone cloud environments serve discrete workloads while embedded multi-cloud fabrics orchestrate unified control planes across heterogeneous infrastructure.
- Public Cloud:Shared-tenant infrastructure delivers metered compute and storage without capital expenditure. North American property insurers burst catastrophe modeling workloads here during hurricane seasons, constrained by HIPAA encryption mandates for health data traversing multi-tenant architectures.
- Private Cloud:Single-tenant dedicated infrastructure isolates sensitive policyholder records and actuarial systems. German carriers deploy these to satisfy BaFin data-localization requirements for core systems, accepting higher fixed costs for regulatory certainty.
- Hybrid Cloud:Orchestrated public-private bridges enable sensitive data retention in private nodes while shifting analytics bursts to public environments. Mid-tier carriers favor this for phased modernization without full mainframe displacement.
- Multi-Cloud:Distributed workloads across competing hyperscalers reduce vendor lock-in and negotiate pricing leverage. Large carriers architect failover resilience across Azure, AWS, and IBM Cloud zones.
Volume placements concentrate in Hybrid Cloud; the faster expansion belongs to Multi-Cloud.
Service Type:
Cost tiering separates raw infrastructure rentals from fully abstracted application layers, with margin pools deepening toward the application stack.
- IaaS:Bare-metal compute, storage, and networking resources provisioned on-demand. Tier-one carriers with captive IT expertise prefer IaaS for legacy system containerization, managing their own middleware and security layers.
- PaaS:Development and deployment environments abstracting infrastructure management. InsurTech startups and managing general agents adopt PaaS for rapid policy-administration prototyping without DevOps overhead.
- SaaS:Complete application delivery through subscription models, concentrating vendor margin in vertical solutions. Guidewire and Duck Creek policy-administration suites dominate this tier atop hyperscaler foundations.
- DRaaS:Disaster-recovery-as-a-service replicates critical systems to geographically separated cloud zones. Florida and Texas property insurers mandate DRaaS for business-continuity compliance against climate-driven operational disruption.
Revenue concentration sits with SaaS; steepest expansion trajectory marks DRaaS as climate resilience budgets inflate.
End User:
Customer-type segmentation maps cloud sophistication to product-line complexity and regulatory density.
- Life Insurance:Long-duration liability modeling and mortality-table analytics drive demand for high-memory compute instances. Actuarial system modernization lags here due to embedded business logic in decades-old mainframes.
- Health Insurance:Real-time claims adjudication and wearable-data integration require low-latency processing architectures. FDA software-as-medical-device guidelines intersect with HIPAA mandates, complicating multi-tenant design.
- Property Insurance:Catastrophe risk modeling and seasonal claims spikes create elastic compute demand. Florida carriers lead adoption of serverless batch processing for post-hurricane damage assessment.
- Liability Insurance:Litigation analytics and long-tail reserving need document-intensive cloud storage with e-discovery tooling. Commercial lines brokers drive usage-based procurement models here.
Technology spending concentrates in Property Insurance; Health Insurance climbs fastest on biometric-data platform investments.
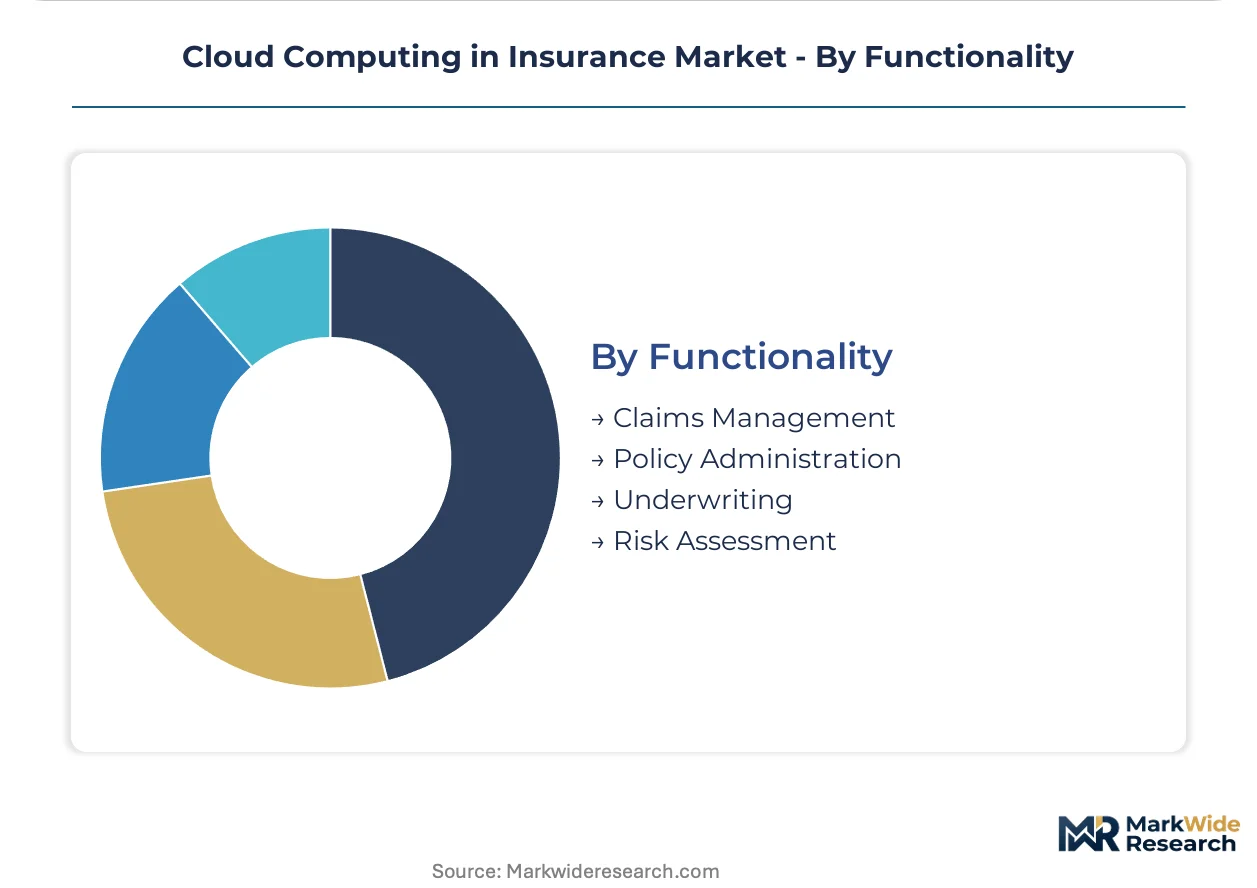
Functionality:
Maturity gradients separate legacy batch systems from real-time API-orchestrated workflows across the policy lifecycle.
- Claims Management:Image recognition, geospatial mapping, and automated adjudication accelerate settlement cycles. Containerized microservices enable Florida insurers to deploy incremental updates without hurricane-season downtime.
- Policy Administration:Core system-of-record functions including quoting, issuance, and endorsements. Monolithic legacy suites resist migration due to regulatory audit trail requirements embedded in decades of policy history.
- Underwriting:Risk selection algorithms and pricing engines increasingly deploy machine learning models. EU AI Act risk-classification frameworks mandate explainable-AI tooling investments for automated decision documentation.
- Risk Assessment:Catastrophe modeling, stress testing, and capital adequacy calculations. Elastic compute bursts here during regulatory filing windows and post-event portfolio revaluation.
Implementation volume centers on Claims Management; Underwriting gains share fastest on AI governance mandates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Frankfurt's Mainhattan financial district anchors continental Europe's sovereign cloud infrastructure buildout, with carrier data centers clustering along the Rhine-Main corridor to satisfy strict regulatory mandates.
United States
Florida and Texas property insurers drive elastic compute demand for hurricane-season catastrophe modeling. HIPAA encryption standards govern health data traversing multi-tenant architectures. Miami-Dade carriers deploy serverless batch processing for post-storm damage assessment workflows.
Germany
BaFin's data-localization mandates for actuarial systems create captive demand for single-tenant private cloud deployments. EU AI Act risk-classification frameworks force algorithmic transparency investments in underwriting platforms. Munich's insurance technology corridor hosts sovereign cloud zones dedicated to legacy core system modernization.
United Kingdom
Lloyd's syndicates and London market carriers concentrate cloud procurement in policy administration and claims management functions. FCA operational resilience requirements mandate disaster-recovery-as-a-service for business continuity. The City of London's fintech cluster drives API-orchestrated microservices adoption among commercial lines brokers.
Japan
Life insurers with decades-old mainframe actuarial systems pursue phased hybrid cloud migration. METI digital transformation incentives accelerate legacy modernization timelines. Tokyo's Marunouchi financial district hosts concentrated vendor implementation teams serving tier-one carriers.
India
InsurTech startups and managing general agents adopt platform-as-a-service for rapid policy-administration prototyping. RBI data localization norms for insurance intermediaries shape vendor selection criteria. Bengaluru's technology corridor anchors development centers building cloud-native claims adjudication tools for domestic and export markets.
Cloud Computing in Insurance Market Vendor Landscape
The competitive structure tilts toward hyperscale infrastructure providers with dedicated financial services verticals. Three vendors dominate compute pricing, limiting carrier negotiating leverage for long-term contracts. Strategic archetypes separate sovereign cloud specialists, vertical SaaS application layers, and legacy mainframe modernization consultants. Competitive moves concentrate on geographic data residency certifications and sustainability-linked procurement credentials.
Within the vertical SaaS tier, Guidewire Software and Duck Creek Technologies exemplify policy-administration specialists that have built integrated application layers atop hyperscaler foundations. Microsoft Azure anchors sovereign cloud deployments across continental European carriers, leveraging dedicated EU data residency zones that satisfy GDPR and EU AI Act mandates. IBM Cloud occupies a position serving legacy actuarial system modernization, competing on regulatory audit trail capabilities that satisfy state-level insurance commissioners.
| Leading Market Players |
|---|
| IBM Cloud |
| Oracle Cloud |
| Amazon Web Services |
| Guidewire Software |
| Salesforce |
| Microsoft Azure |
| Duck Creek Technologies |
| Redian Software |
| Google Cloud |
| Others |
Supply Flow & Price Mechanics
Hyperscaler compute capacity serves as the foundational cost driver, flowing from concentrated data center infrastructure in Northern Virginia, Frankfurt, and Dublin through tiered service contracts to insurance carriers negotiating usage-metered agreements. This input concentration grants Amazon Web Services, Microsoft Azure, and Google Cloud substantial pricing power over long-term infrastructure commitments.
Pricing Analysis
Outcome-based pricing tied to claims-processing throughput anchors carrier procurement decisions, with vendors metering charges against policy transaction volumes rather than fixed seat licenses. Price differentiation separates sovereign cloud deployments with EU data residency certifications from standard multi-tenant offerings, while sustainability-linked procurement criteria from the EU Green Deal add carbon-intensity premiums. Pricing pressure stems from hyperscaler oligopoly concentration limiting carrier negotiating leverage for elastic compute contracts. Managing general agents and mid-tier property insurers exhibit highest price sensitivity due to seasonal exposure volatility, whereas tier-one carriers with captive IT expertise accept premium IaaS rates for customization control.
Supply Chain Analysis
Cloud engineering talent scarcity in Bangalore, Hyderabad, and Warsaw constrains implementation velocity for legacy system modernization programs. Infrastructure hardware supply draws from semiconductor fabrication in Taiwan, memory module production in South Korea, and server assembly in China, creating tariff exposure through cross-border component flows. Supply chain risk centers on single-source vulnerability for specialized GPU clusters essential to catastrophe risk modeling workloads. Distribution runs through direct enterprise sales teams and systems integrator partnerships serving carrier IT procurement functions.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market is a vertical-integration race, with hyperscalers pursuing downstream control over policy-administration application layers and incumbent software vendors seeking upstream infrastructure ownership.
For Market Incumbents: Extend sovereign cloud certification investments to preempt EU AI Act compliance mandates, while embedding audit-log capabilities directly into policy engines to defend against emerging explainable-AI specialists. Consolidation through acquisition of containerized microservices startups addresses cloud-native talent scarcity delaying mainframe transitions. For New Entrants and Emerging Players: API marketplace routes offer lowest friction entry for claims adjudication automation targeting Florida and Texas property carriers with hurricane-season scaling pain points. White-space concentration sits in usage-based procurement models for commercial lines brokers, with serverless batch processing for post-event damage assessment as the most penetrable initial wedge. For Investors and Strategic Acquirers: BaFin enforcement actions against non-compliant data localization are the leading indicator that sovereign cloud infrastructure valuations will detach from standard multi-tenant multiples. Long-term viability favors acquisition targets with dedicated EU zone deployments and renewable-energy data center credentials, with carrier RFP language shifting toward carbon-intensity disclosure as the critical inflection signal.| Strategic Initiative | Industry Significance |
|---|---|
| Sovereign Cloud Certification | BaFin and EU AI Act mandates create captive demand for EU data residency zones. |
| Microservices Platform Launch | Containerized architecture compresses implementation cycles from years to quarterly releases. |
| Backward Integration into GPU Supply | Catastrophe modeling workloads require dedicated AI training clusters with scarce availability. |
| Strategic Partnership with InsurTech | Managing general agents drive usage-based procurement requiring granular billing integration. |
| Sustainability Repositioning | CSRD disclosure mandates embed carbon-intensity criteria into vendor selection scorecards. |
Methodological Framework
Document review covered hyperscaler financial disclosures, carrier IT procurement RFPs, and regulatory filings with BaFin and state insurance departments, complemented by interviews with cloud infrastructure architects, carrier CIOs, and compliance officers at tier-one insurers. Secondary validation drew from SEC 10-K infrastructure segments, EU AI Act implementation guidance, and industry association cloud adoption surveys. Bottom-up carrier spending estimates triangulated against top-down hyperscaler financial services revenue allocations.
Segment-level projections across deployment models, service types, and end-user categories produced volume and value trajectories across the analysis window. The analytical framework modeled hybrid cloud adoption curves, SaaS penetration rates in policy administration, and elastic compute demand spikes correlated to catastrophe event frequency. CAGRs derived from carrier IT budget growth rates, hyperscaler contract value disclosures, and regulatory compliance investment timelines.
The model holds under sustained regulatory fragmentation across federal and state jurisdictions; deviation in harmonized EU AI Act enforcement or HIPAA encryption standard relaxation would shift infrastructure procurement patterns. Forecasts reflect assumptions of continued hyperscaler oligopoly concentration and escalating climate-driven claims volatility. Material deviation in named triggers warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Insurance
Europe Entertainment Insurance Market
Insurance
Fire Insurance Market
Insurance
Microinsurance Market
Insurance
Middle East Business Income Insurance Market
Insurance
Aircraft Insurance Market
Insurance
Japan Property and Casualty Insurance Market
Insurance
Asia-Pacific Usage-Based Insurance Market
Insurance
Europe Extended Warranty Market
Insurance
Employee Benefit Broker Market
Insurance
Indonesia Private Health Insurance Market
Insurance
Aviation Insurance Market
Insurance
Asia-Pacific Travel Insurance Market
Insurance
United States Bancassurance Market
Insurance
Art Insurance Market
Insurance
Germany Car Insurance Market
Insurance
Road Assistance Insurance Market