
 US Extended Warranty Market | 2026-2036
US Extended Warranty Market Size, Share, and Industry Trends Forecast 2026-2036
US Extended Warranty Market Insights
Texas is reconfiguring its extended warranty distribution footprint through new service center investments and regional underwriting capacity. Endurance leverages direct-to-consumer digital channels to capture market share outside traditional dealership networks. CarShield sustains brand visibility through national advertising while competing on monthly payment flexibility. Olive specializes in embedded warranty APIs for e-commerce platforms, differentiating from legacy call-center models.
An extended warranty constitutes a service contract that transfers repair or replacement liability from the consumer to the issuer for a defined term, typically covering mechanical, electronic, or structural failures beyond manufacturer guarantees. These contracts specify coverage limits, deductible structures, claims adjudication protocols, and exclusion clauses to mitigate buyer risk exposure. Automotive coverage dominates service type revenue given rising repair costs for advanced driver-assistance systems and electric powertrains. Individual consumers represent the fastest-growing customer type as inflation-sensitive households seek predictable maintenance budgeting. Comprehensive coverage offerings command premium pricing but face margin pressure from specialty coverage products tailored to niche electronics categories.
The FTC enforces disclosure standards under the Magnuson-Moss Warranty Act, requiring clear separation of manufacturer warranties from optional service contracts. State insurance regulators in California, New York, and Illinois classify certain extended warranties as regulated insurance products, creating compliance complexity for multi-state issuers. The CFPB monitors add-on product sales practices at auto dealerships, with recent enforcement actions targeting deceptive warranty packaging in vehicle financing. Stakeholders must monitor state-level regulatory divergence and embedded finance integration trends to align product architecture with evolving compliance and distribution expectations.
Market Dynamics
Vehicle electrification and ADAS proliferation are compressing traditional warranty coverage gaps while forcing issuers to recalibrate actuarial models for battery degradation and sensor replacement costs.
Growth Catalysts
- FTC Magnuson-Moss enforcement:The FTC's disclosure mandates under the Magnuson-Moss Warranty Act are compelling clearer contract separation, reducing consumer confusion and elevating service contract attachment rates at point of sale.
- Electric powertrain complexity:Battery thermal management systems and inverter assemblies generate repair cost exposures that manufacturer warranties rarely cover fully, driving supplemental coverage demand.
- Texas service infrastructure:Regional underwriting capacity expansion and dedicated EV service center investments in Texas are creating localized distribution advantages for warranty issuers targeting fleet conversions.
Market Restraints
- Lithium-ion battery cost volatility:Raw material price swings for cobalt and nickel directly impact loss reserve requirements, compressing margins on EV-specific coverage products.
- California regulatory fragmentation:State insurance regulators classify certain vehicle service contracts as regulated insurance products, creating multi-state compliance friction for national issuers.
- Telematics data asymmetry:OEM-controlled vehicle health data streams limit third-party warranty providers' ability to price risk accurately against manufacturer captive programs.
Strategic Opportunities
- Embedded finance APIs:E-commerce platform integration enables point-of-transaction warranty attachment for consumer electronics and appliances, bypassing traditional call-center acquisition costs.
- Florida RV and marine segments:High-value recreational vehicle ownership density in Florida supports specialty mechanical coverage products with premium pricing tolerance.
- CFPB compliance automation:Automated disclosure and pricing transparency tools align with CFPB monitoring of dealership add-on sales practices, creating competitive differentiation for compliant issuers.
Industry Challenges
- ADAS calibration technician scarcity:Advanced driver-assistance system repair requires specialized equipment and certification that dealer networks control, limiting independent warranty administrator claim fulfillment options.
- Legacy claims system integration:Mainframe-based adjudication platforms at established insurers resist real-time data ingestion from connected vehicle telematics, slowing claims automation.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | US Extended Warranty Market |
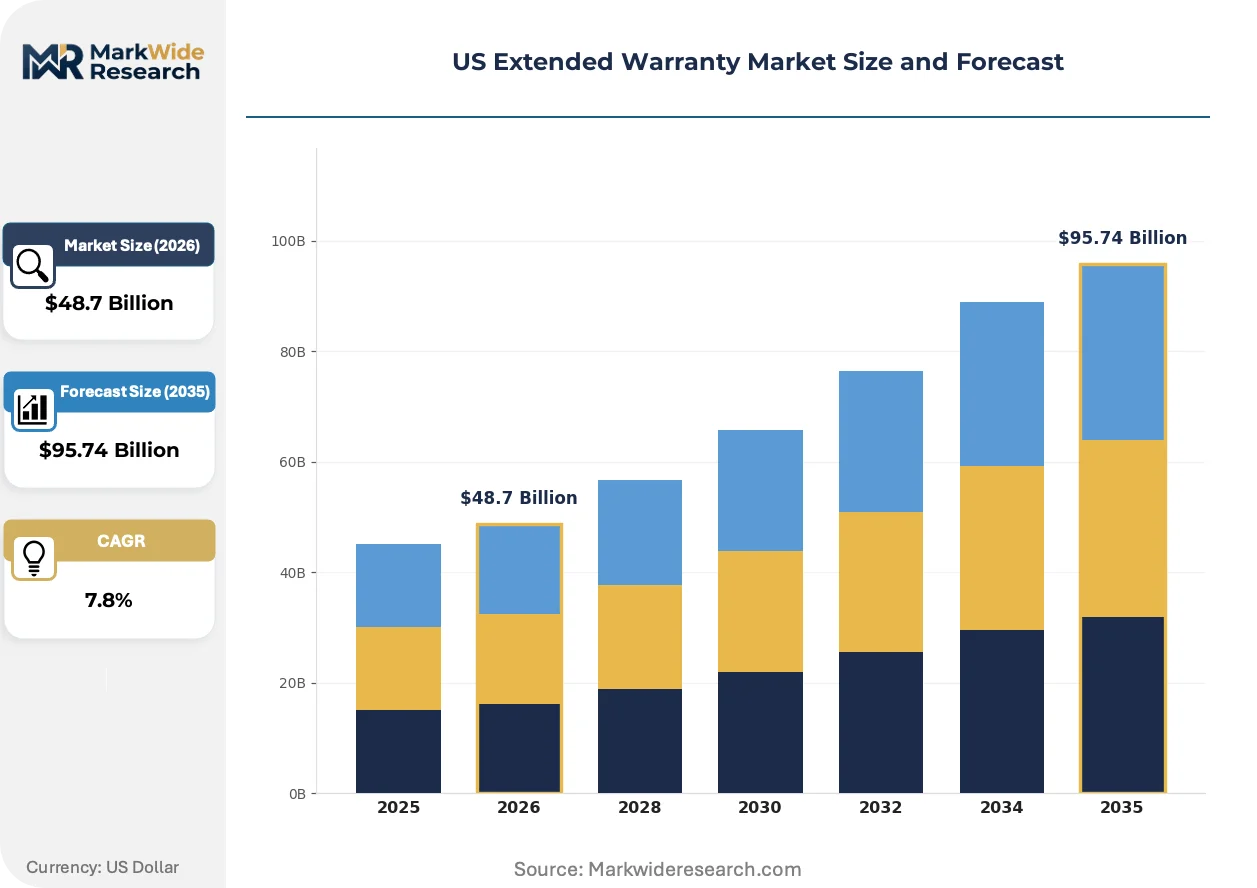
| Market Size in 2026 | $48.7 Billion |
| Market Size in 2035 | $95.74 Billion |
| CAGR (2026 – 2036) | 7.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Electronics, Appliances, Automotive, Home Systems Customer Type: Individual Consumers, Businesses, Retailers, Wholesalers Offering: Comprehensive Coverage, Powertrain Coverage, Bumper-to-Bumper, Specialty Coverage End User: Households, Corporations, Small Businesses, Resellers |
| Companies Covered | Olive, American Dream Auto Protect, Endurance, Omega Auto Care, Toco Warranty, CarShield, Premier Auto Protect, Empire Auto Protect, Carchex, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
US Extended Warranty Market Trends and Innovations
Warranty distribution architecture is fragmenting across embedded digital channels, regulatory technology investments, and predictive service integration models that compress the traditional claims cycle.
Artificial intelligence-driven claims adjudication is migrating from pilot deployments to operational scale. Automotive warranty administrators deploy machine learning models to flag anomalous repair patterns and route claims to appropriate approval tiers. Large regional insurers in California and Texas are adopting these platforms to reduce loss adjustment expenses and accelerate contractor payments.
The CFPB's intensified scrutiny of dealership add-on product sales is reshaping disclosure workflows. Enforcement actions targeting deceptive warranty packaging in vehicle financing have compelled issuers to implement point-of-sale documentation systems with audio recording and e-signature verification. Subprime auto lending channels face the steepest compliance cost increases as they retrofit legacy sales processes.
Subscription-based warranty pricing is displacing lump-sum prepaid contracts among inflation-sensitive households. Monthly payment flexibility reduces upfront cash requirements for used vehicle buyers in Texas and Florida, where high ownership turnover sustains demand for transferable coverage. Digital-native competitors capture this segment through mobile-first enrollment with immediate policy activation, bypassing traditional mail-based documentation delays.
US Extended Warranty Market Segmentation
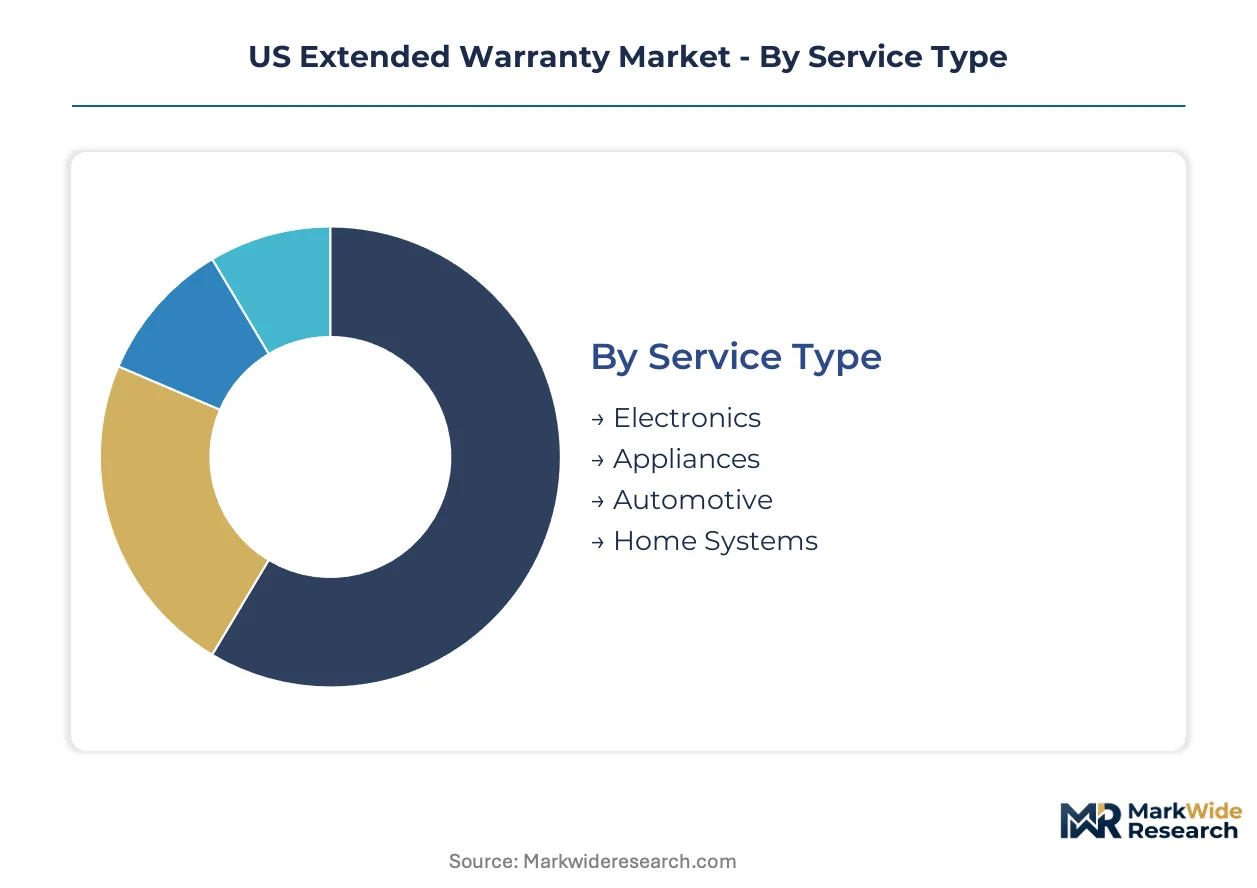
Warranty issuers calibrate product architecture across four structural dimensions to match risk profiles with distribution economics. Each segmentation axis reveals distinct pricing power, compliance exposure, and channel attachment dynamics that determine competitive positioning.
Service Type:
Cost tier stratification across service types reflects divergent repair cost trajectories and actuarial complexity.
- Automotive:Coverage spans powertrain, electrical, and ADAS component failures as vehicle complexity elevates repair costs beyond manufacturer warranty periods. Demand concentrates in Texas and Florida where high vehicle ownership density and fleet conversion activity sustain premium pricing for supplemental protection.
- Electronics:Smartphones, laptops, and connected devices carry coverage for accidental damage, battery degradation, and motherboard failures. California households drive attachment rates through e-commerce platform integration and embedded checkout offers.
- Appliances:Refrigeration, laundry, and HVAC systems carry mechanical and electrical failure protection. Coverage demand tracks homeownership patterns and replacement cost sensitivity in inflationary cycles.
- Home Systems:Roofing, plumbing, and electrical infrastructure coverage addresses structural component failures. This segment serves aging housing stock in suburban markets with deferred maintenance accumulation.
Automotive holds installed capacity. Electronics is rotating up the share rankings.
Customer Type:
Volume concentration varies sharply across customer categories, with individual acquisition costs and lifetime value profiles dictating channel investment priorities.
- Individual Consumers:Direct-to-consumer digital enrollment and dealership point-of-sale attachment dominate acquisition. Monthly payment flexibility and immediate policy activation are displacing lump-sum prepaid contracts among inflation-sensitive households.
- Businesses:Fleet operators and corporate procurement departments negotiate multi-vehicle or multi-site coverage with customized deductible structures and claims adjudication protocols.
- Retailers:Big-box electronics and appliance merchants embed warranty offers at checkout through API integration, capturing attachment without call-center friction.
- Wholesalers:Distributors of refurbished equipment and secondary market inventory bundle coverage to enhance resale value and reduce buyer risk perception.
Individual Consumers command premium pricing tolerance. Retailers are climbing the fastest as embedded finance architectures mature.
Offering:
Maturity gradients across coverage tiers separate legacy comprehensive products from targeted specialty designs calibrated to component-specific risk exposure.
- Comprehensive Coverage:Broad protection against mechanical, electrical, and structural failures with minimal exclusion lists. Premium pricing faces margin compression from more targeted specialty alternatives.
- Powertrain Coverage:Engine, transmission, and drivetrain-specific protection addresses the highest-cost repair categories. Electric vehicle battery thermal management and inverter assemblies are forcing actuarial model recalibration.
- Bumper-to-Bumper:Near-manufacturer warranty replication for used vehicle buyers seeking predictable maintenance budgeting. Transferability provisions support resale value in high-turnover markets.
- Specialty Coverage:Niche products targeting RV marine segments, ADAS sensor arrays, or specific electronics categories command premium pricing with concentrated underwriting expertise.
Comprehensive Coverage holds legacy share. Specialty Coverage is gaining share fastest through margin-focused product design.
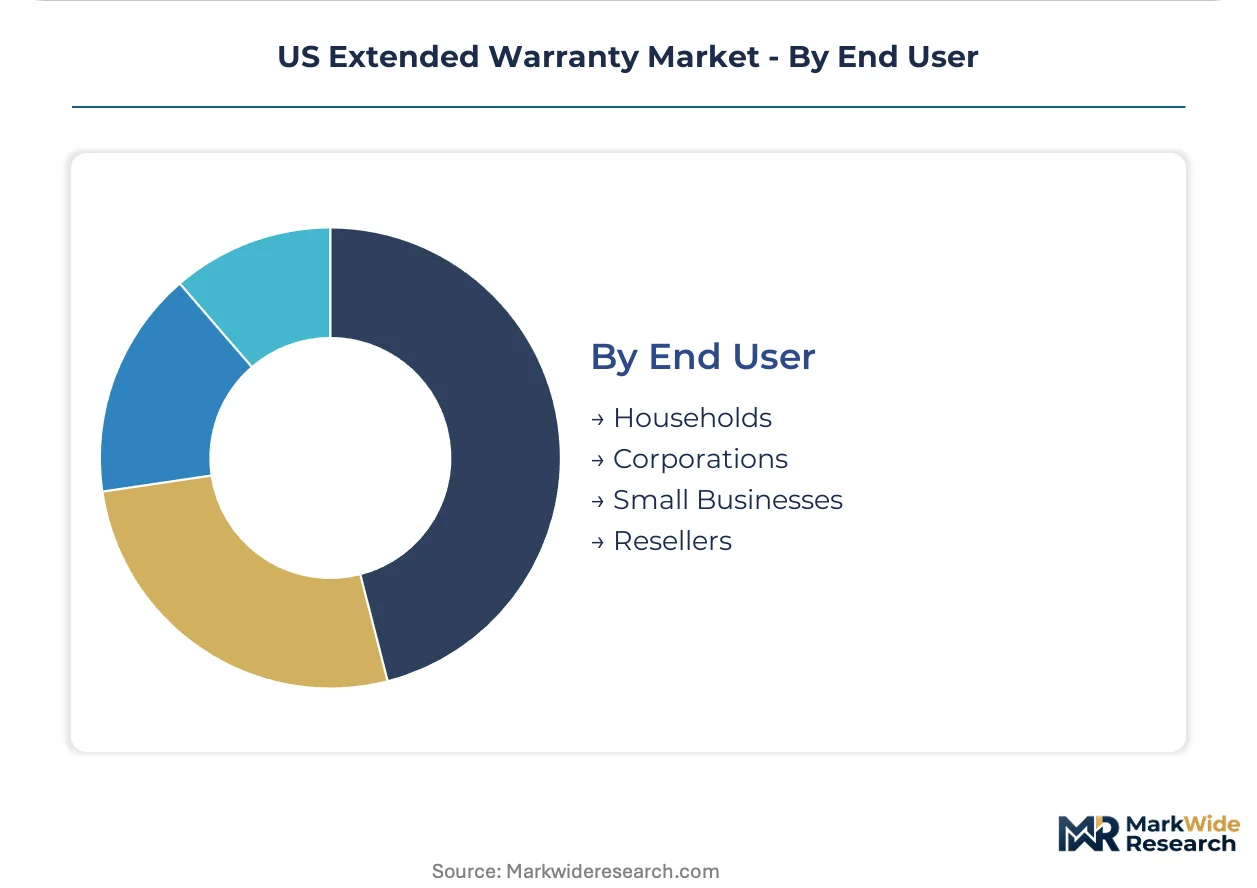
End User:
Application context determines coverage duration, claims frequency, and regulatory compliance intensity across end-user categories.
- Households:Residential consumers purchase coverage for vehicles, appliances, and home systems through direct digital channels or retail point-of-sale. CFPB disclosure requirements and state insurance classification rules shape contract architecture.
- Corporations:Enterprise procurement of fleet vehicle and facility equipment coverage emphasizes service level agreements and nationwide contractor networks.
- Small Businesses:Commercial vehicle and essential equipment protection addresses cash flow vulnerability to unexpected repair costs. Regional underwriting capacity in Texas and Florida targets this segment with localized service infrastructure.
- Resellers:Used vehicle dealers and refurbished electronics merchants leverage transferable coverage as a differentiation tool. Magnuson-Moss Warranty Act compliance mandates clear separation from manufacturer guarantees.
Households anchor volume throughput. Small Businesses are rotating up the share rankings as fleet electrification accelerates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Warranty underwriting capacity clusters in states with high vehicle density and favorable regulatory classification. California, Texas, and Florida generate disproportionate premium volume through concentrated dealership networks and direct-to-consumer digital penetration.
California
Electronics warranty attachment rates surge through e-commerce platform integration and embedded checkout offers. State insurance regulators classify certain vehicle service contracts as regulated insurance products, creating compliance friction for multi-state issuers. Silicon Valley technology clusters drive demand for smartphone and laptop coverage through API-enabled point-of-sale distribution.
Texas
Fleet conversion activity and high vehicle ownership density sustain premium pricing for automotive supplemental protection. Regional underwriting capacity expansion and dedicated EV service center investments create localized distribution advantages for warranty issuers. Houston and Dallas-Fort Worth metropolitan areas anchor dealership network concentration and independent administrator operations.
Florida
Recreational vehicle and marine ownership density supports specialty mechanical coverage products with premium pricing tolerance. High used vehicle turnover sustains demand for transferable bumper-to-bumper contracts among inflation-sensitive households. Miami and Tampa service infrastructure investments target snowbird seasonal vehicle protection segments.
New York
State insurance classification rules for vehicle service contracts parallel California regulatory complexity, limiting national issuer operational standardization. Upstate manufacturing heritage sustains commercial equipment warranty demand among small business procurement departments. New York City metropolitan area concentrates electronics retail warranty attachment through big-box merchant checkout integration.
Illinois
Chicago-centered automotive aftermarket distribution supports warranty administrator claims fulfillment networks across the Midwest. State regulatory alignment with Magnuson-Moss disclosure mandates reduces multi-state compliance burden relative to coastal jurisdictions. Fleet operator concentration in the I-55 corridor drives negotiated multi-vehicle coverage with customized deductible structures.
US Extended Warranty Market Competitive Landscape
Direct-to-consumer digital platforms and traditional dealership-centric administrators split the market across divergent acquisition cost structures. The competitive terrain separates into three strategic archetypes: digital-native subscription issuers, captive dealership administrators, and embedded finance API specialists. Consolidation pressure concentrates among mid-scale call-center operators facing customer acquisition cost inflation. Dominant competitive moves include embedded checkout technology licensing and regional service infrastructure expansion.
Within the digital-native tier, Endurance and CarShield exemplify direct-to-consumer platform strategies, while Olive occupies a position representing embedded finance API specialization for e-commerce integration. These three anchors illustrate the market's bifurcation between legacy call-center models and mobile-first enrollment architectures that bypass traditional mail-based documentation delays.
| Leading Market Players |
|---|
| Olive |
| American Dream Auto Protect |
| Endurance |
| Omega Auto Care |
| Toco Warranty |
| CarShield |
| Premier Auto Protect |
| Empire Auto Protect |
| Carchex |
| Others |
Pricing and Supply Chain Analysis
Commodity volatility in lithium-ion battery raw materials compresses margin spreads across EV-specific coverage tiers while simultaneously forcing issuers to reconfigure supplier relationships toward long-term offtake arrangements with cobalt and nickel processors.
Pricing Analysis
The Magnuson-Moss Warranty Act dictates the pricing tier structure by mandating clear separation between manufacturer warranties and optional service contracts, elevating compliance costs that issuers recover through premium positioning. Three-tier pricing structure across premium, standard, and economy levels reflects deductible gradients and claims adjudication speed. Cost compression in the economy tier is intensifying because telematics-enabled OEM captives undercut third-party providers on acquisition efficiency. Fleet operators demonstrate the least price sensitivity due to negotiated multi-vehicle structures, while individual used-vehicle buyers in inflationary cycles exhibit acute payment flexibility demands.
Supply Chain Analysis
Raw material feedstock for EV battery coverage reserves draws from Chilean lithium brine operations, Indonesian nickel laterite processing, and Congolese cobalt mining. Semiconductor content for ADAS calibration equipment rests on Taiwanese foundry output and South Korean memory fabrication. Single-source vulnerability concentrates in OEM-controlled vehicle health data streams that limit third-party actuarial precision. Distribution runs through regional underwriting facilities in Texas and Florida, with claims fulfillment anchored in dealership service bay networks and independent certified repair shops.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The scarcity of ADAS calibration technicians and certified EV powertrain specialists constrains claim fulfillment capacity, creating defensive moats for issuers with captive technical training pipelines and OEM data access agreements.
For Market Incumbents: Build regulatory compliance moats through automated point-of-sale disclosure systems with audio recording and e-signature verification that satisfy CFPB monitoring requirements. Expand regional underwriting capacity in Texas through dedicated EV service center investments that shorten claim cycle times. Vertical integration into telematics data partnerships with fleet operators reduces pricing asymmetry against manufacturer captive programs. For New Entrants and Emerging Players: Build out embedded finance API architectures for e-commerce platform integration in California electronics retail, bypassing call-center acquisition cost inflation. Target the Florida RV and marine specialty coverage segment where premium pricing tolerance and concentrated ownership density support niche underwriting economics. Lead with mobile-first monthly subscription enrollment to capture inflation-sensitive household demand outside legacy mail-based documentation systems. For Investors and Strategic Acquirers: The market sits at a consolidation phase that favors digital-native platforms with embedded distribution technology and compliance automation capabilities. Long-term viability hinges on underwriting expertise in battery degradation modeling and ADAS component risk calibration. Acquisition candidates with established OEM data sharing agreements and regional service infrastructure in Texas or Florida warrant priority evaluation. Monitor CFPB enforcement action frequency as an inflection indicator for compliance cost trajectories across subprime auto lending channels.| Strategic Initiative | Industry Significance |
|---|---|
| Embedded Finance API Development | Enables point-of-transaction warranty attachment through e-commerce platform integration, reducing call-center acquisition costs. |
| Regional Service Infrastructure Expansion | Dedicated EV service center investments in Texas create localized distribution advantages for fleet conversion coverage. |
| Compliance Automation Platform Deployment | Automated disclosure and pricing transparency tools align with CFPB monitoring of dealership add-on sales practices. |
| Telematics Data Partnership Formation | OEM-controlled vehicle health data access improves actuarial precision against manufacturer captive warranty programs. |
| Specialty Coverage Product Design | RV and marine mechanical protection in Florida commands premium pricing with concentrated underwriting expertise. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with warranty issuer underwriting executives, dealership F&I managers, fleet procurement directors, and automotive service center operators. Secondary validation drew from FTC enforcement action records, state insurance regulator filings in California and New York, CFPB consumer complaint databases, and vehicle registration data from IHS Markit. Bottom-up policy volume estimates and top-down premium value assessments were triangulated to reconcile segmentation outputs.
Calibration across the analysis window applied discrete choice modeling for customer type penetration rates and actuarial loss ratio projections for coverage tier profitability. Segmentation dimensions included service type, customer type, offering maturity, and end-user application context, with propulsion architecture and ADAS content level as automotive-specific modifiers. CAGRs were derived from trend extrapolation of historical attachment rates adjusted for electrification-driven repair cost trajectories and regulatory compliance cost burdens.
The forecast holds incumbent behavior within observed patterns; aggressive moves by OEM captive warranty programs or embedded finance technology specialists would shift outcomes beyond modeled ranges. Cross-checking against NAIC state insurance filing data and S&P Global vehicle production forecasts is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Insurance
Germany Travel Insurance Market
Insurance
Europe Entertainment Insurance Market
Insurance
GCC Health Insurance Market
Insurance
Compulsory Third Party (CTP) Insurance Market
Insurance
China Property and Casualty Insurance Market
Insurance
US Long-Term Care Private Insurance Market
Insurance
Japan Liability Insurance Market
Insurance
Income Protection Insurance Market
Insurance
EV Insurance Market
Insurance
China Business Income Insurance Market
Insurance
Agriculture Reinsurance Market
Insurance
Global Vehicle Insurance Market
Insurance
China Online Insurance Market
Insurance
North America Car Insurance Aggregators Market
Insurance
Medical Professional Liability Insurance Market
Insurance
Sri Lanka Cyber (Liability) Insurance Market