
 Motorcycle Insurance Market | 2026-2036
Motorcycle Insurance Market Size, Share, and Industry Trends Forecast 2026-2036
Motorcycle Insurance Market Intelligence
A widening capital-intensity gap between legacy underwriters and digital-native entrants is bifurcating competitive dynamics in motorcycle insurance. Progressive leverages proprietary telematics infrastructure to price risk at the individual ride level, while Allstate sustains brand recognition through captive agency networks and bundled auto-motorcycle cross-sell programs. Dairyland anchors its position in the non-standard segment, specializing in high-risk rider pools that larger carriers often decline.
Motorcycle insurance constitutes a specialized property-casualty contract indemnifying riders against bodily injury, physical damage, and third-party liability, with premiums calibrated through actuarial models that weight engine displacement, rider age, and annual mileage. Comprehensive coverage commands the thickest margin pools as it extends protection against theft, vandalism, and weather damage beyond collision events. Sport bike policies generate elevated loss ratios relative to cruiser segments, reflecting higher accident frequency and severity in performance-oriented vehicle classes.
State departments of insurance in the US enforce minimum liability mandates, while the EU Insurance Distribution Directive imposes conduct standards on cross-border policy sales. The National Association of Insurance Commissioners coordinates model laws that shape solvency requirements and rate filing transparency across American jurisdictions. Stakeholders must monitor how embedded IoT devices and real-time data streams redefine underwriting precision, claims adjudication speed, and customer retention economics.
Market Dynamics
Telematics infrastructure is compressing actuarial cycles from annual renewals to ride-level pricing granularity, forcing legacy underwriters to rebuild core systems or cede share to data-native competitors.
Growth Catalysts
- State compulsory coverage mandates:US state departments of insurance enforce minimum liability laws that sustain baseline premium volumes across all rider segments.
- Urban congestion patterns:Metropolitan commuters in congested corridors are adopting motorcycles for last-mile efficiency, expanding the addressable policyholder pool.
- Embedded IoT sensors:Real-time data streams from connected vehicles enable dynamic risk scoring and usage-based policy structures.
Market Restraints
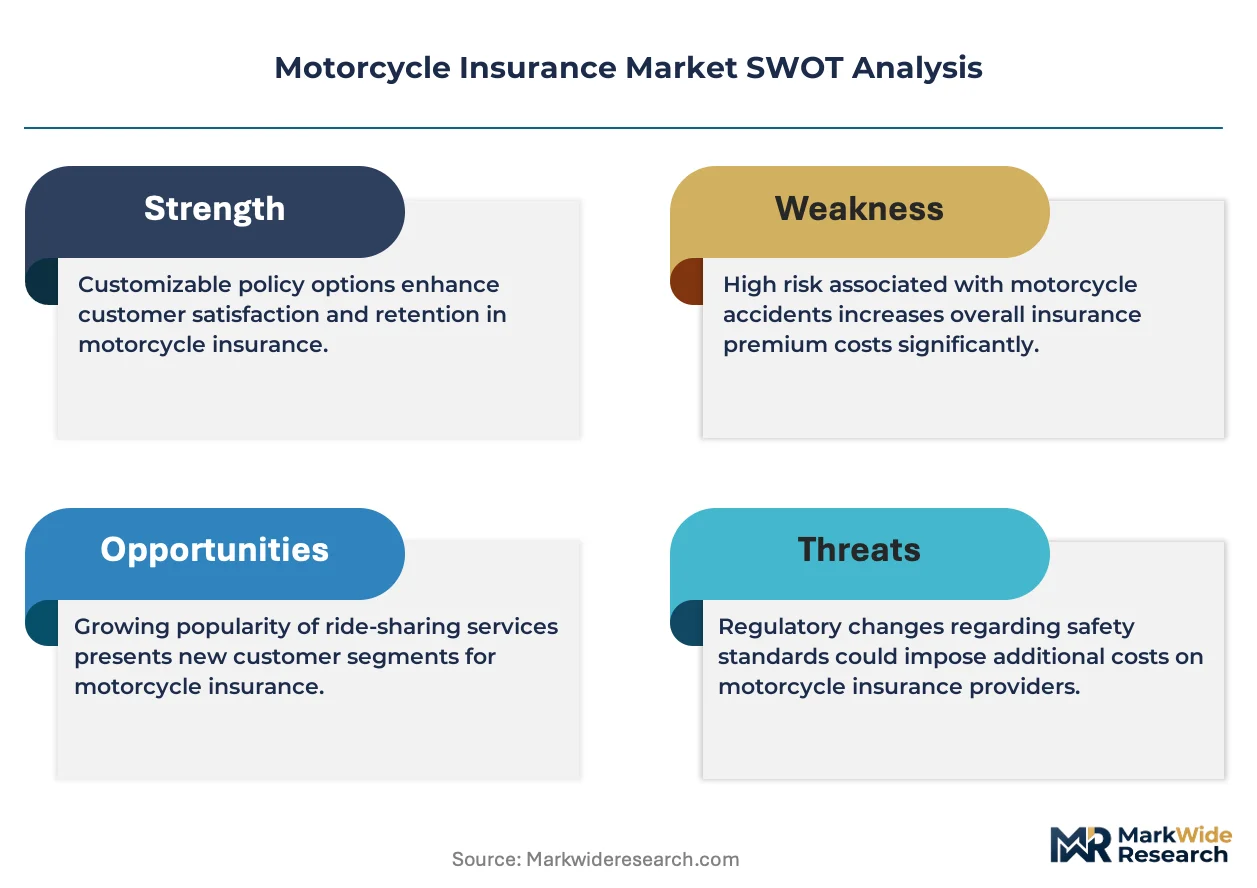
- Loss ratio volatility in sport bike segments:Higher accident frequency and severity in performance-oriented vehicle classes compress underwriting margins.
- Capital intensity of telematics platforms:Proprietary data infrastructure requires sustained technology investment that smaller carriers cannot match.
- Regulatory fragmentation across US jurisdictions:The National Association of Insurance Commissioners coordinates model laws, but state-by-state rate filing requirements create compliance friction.
Strategic Opportunities
- Non-standard rider pools:High-risk segments declined by mainstream carriers present white-space expansion potential for specialized underwriters.
- EU Insurance Distribution Directive:Cross-border conduct standards create pathways for standardized product distribution across European markets.
- Comprehensive coverage penetration:Theft, vandalism, and weather protection remain underpenetrated relative to mandatory liability, offering margin expansion.
Industry Challenges
- Actuarial talent scarcity:Demand for data scientists capable of interpreting real-time telematics streams exceeds supply in traditional insurance labor markets.
- Legacy system integration:Core policy administration platforms require costly reconfiguration to ingest continuous data feeds from connected vehicles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Motorcycle Insurance Market |
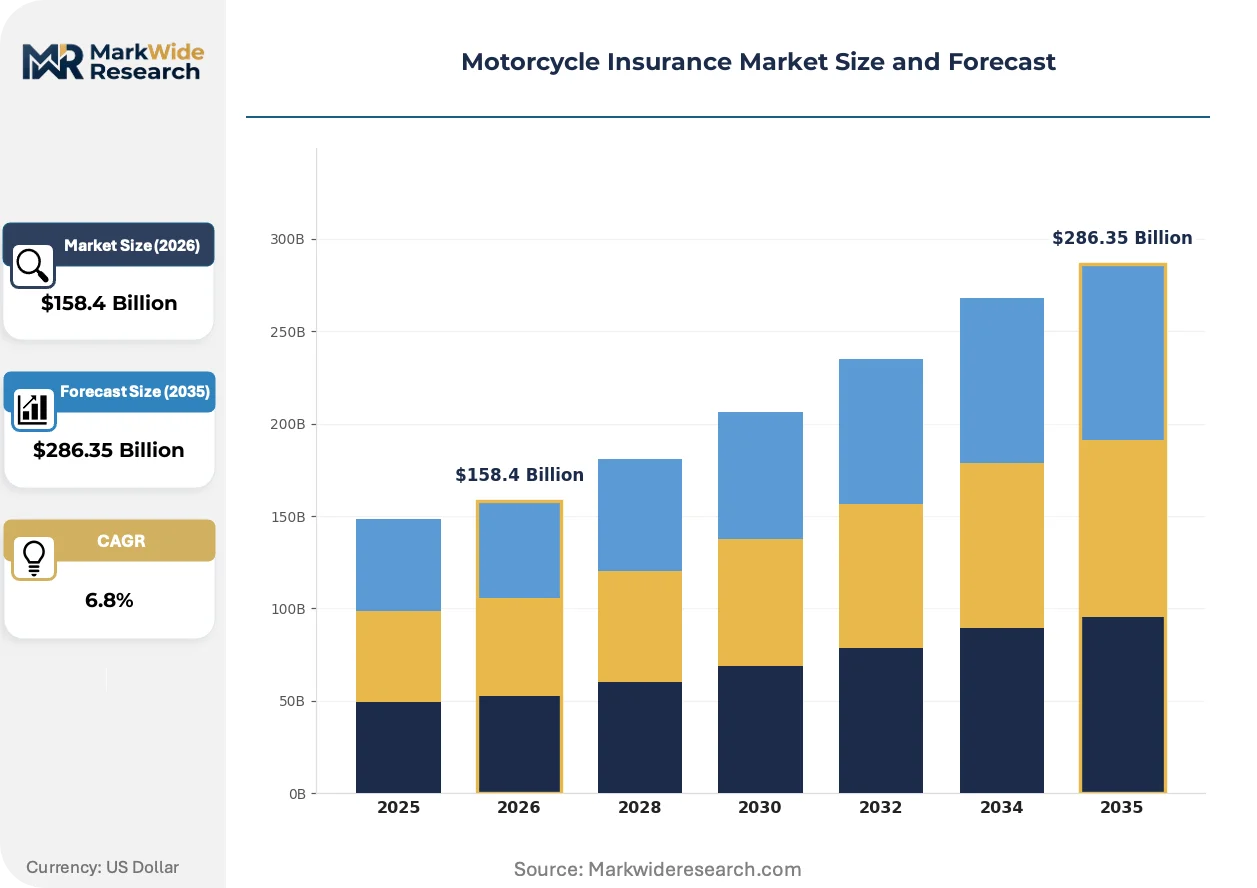
| Market Size in 2026 | $158.4 Billion |
| Market Size in 2035 | $286.35 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Policy Type: Liability, Comprehensive, Collision, Uninsured Motorist Coverage Level: Basic, Standard, Enhanced, Premium Customer Type: Individual Riders, Fleets, Dealerships, Renters Vehicle Type: Sport Bikes, Cruisers, Touring Bikes, Off-Road Bikes |
| Companies Covered | Harley-Davidson Insurance, Allstate, Progressive, Nationwide, Foremost, Dairyland, Safeco, Markel, GEICO, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Motorcycle Insurance Market Strategic Shifts & Innovations
Usage-based insurance models are rewriting the contract structure of motorcycle coverage, shifting from pooled annual premiums to individualized risk pricing calibrated through continuous data capture.
Telematics-enabled dynamic pricing is supplanting static annual rating factors in North American markets. Individual riders now transmit location, speed, and braking telemetry to carriers who adjust premiums monthly. This compression of the rating cycle is enabling behavioral risk selection that static actuarial tables cannot replicate.
The EU Insurance Distribution Directive imposes conduct standards on cross-border policy sales, forcing carriers to harmonize disclosure protocols across member states. This regulatory convergence is accelerating product standardization while raising compliance costs for multi-territory operators. Digital distribution platforms are absorbing these requirements through automated disclosure engines.
After-sales service unbundling is fragmenting the traditional agency relationship. Riders in congested US metropolitan corridors are purchasing coverage through direct digital channels rather than captive agent networks. This channel rotation is compressing acquisition costs for data-native carriers while stranding legacy distribution infrastructure dependent on commission-based intermediaries.
Motorcycle Insurance Market Segmentation
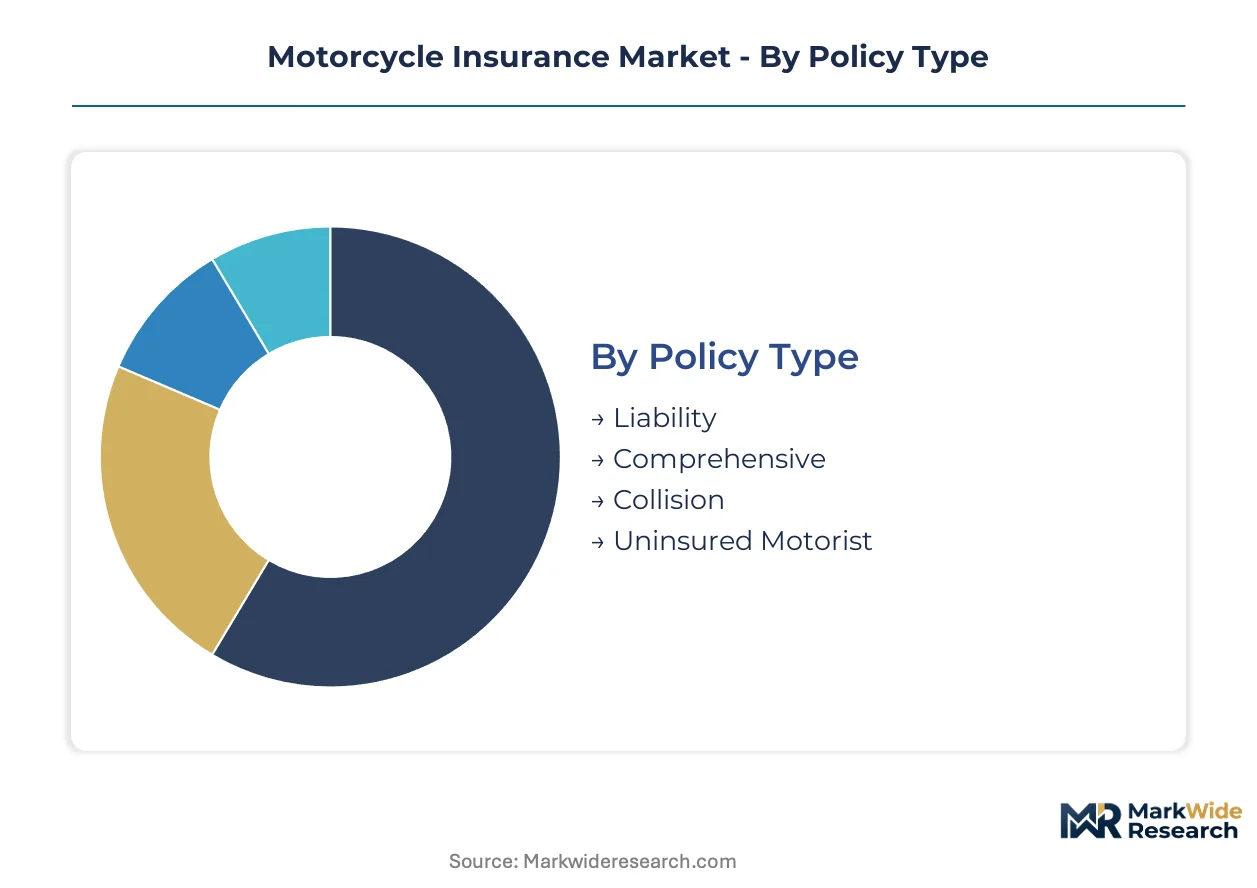
Motorcycle insurance segmentation determines risk pooling precision and pricing granularity. Distinct policy structures, coverage tiers, customer profiles, and vehicle classes each demand specialized underwriting approaches and distribution strategies.
Policy Type:
Geographic concentration varies sharply across policy types, with compulsory liability anchored in domestic US state mandates while comprehensive and collision products expand through discretionary purchase patterns in higher-income metropolitan corridors.
- Liability:State-mandated minimum coverage indemnifying third-party bodily injury and property damage. Demand concentrates in California, Texas, and Florida where compulsory coverage laws sustain baseline premium volumes across all rider income tiers.
- Comprehensive:Full-spectrum protection extending to theft, vandalism, fire, and weather damage beyond collision events. Metropolitan riders in congested urban parking environments drive adoption, with theft-prone coastal cities generating the thickest margin pools.
- Collision:Physical damage coverage for at-fault accidents. Sport bike owners in performance-oriented recreational corridors purchase at elevated rates despite higher deductibles.
- Uninsured Motorist:Protection against bodily injury from non-compliant drivers. Penetration spikes in states with elevated uninsured driver rates and limited enforcement infrastructure.
Liability holds the largest share; momentum sits with comprehensive as theft and weather risks intensify in urban parking ecosystems.
Coverage Level:
Cost tier stratification aligns with rider asset exposure and financing requirements, with premium tiers commanding superior margins through bundled add-ons and deductible reductions.
- Basic:State-minimum liability limits with no physical damage protection. Price-sensitive commuters in congested corridors select this tier despite exposure gaps.
- Standard:Moderate liability limits plus collision coverage for financed vehicles. Lenders in Texas and Ohio mandate this tier for loan compliance.
- Enhanced:Elevated liability ceilings, comprehensive protection, and roadside assistance. Touring bike owners on extended interstate routes drive adoption.
- Premium:Maximum limits, agreed-value coverage, and OEM parts guarantees. High-displacement cruiser collectors in affluent suburban markets sustain this segment.
Standard coverage holds the largest share; premium tiers are climbing the fastest as asset values rise and collector motorcycle markets deepen.
Customer Type:
Volume concentration tilts heavily toward individual purchasers, though fleet and dealership segments present superior unit economics through policy aggregation and captive distribution.
- Individual Riders:Personal policyholders purchasing single-vehicle coverage. Metropolitan commuters in Los Angeles, Chicago, and New York City represent the expanding core as congestion drives modal shift.
- Fleets:Commercial operators with multi-vehicle exposure including delivery services and rental platforms. Food delivery aggregators in dense urban markets sustain this segment's growth trajectory.
- Dealerships:Inventory coverage and floorplan protection for retail operations. Motorcycle retailers in Sun Belt states with extended riding seasons carry elevated inventory exposure.
- Renters:Short-term coverage for peer-to-peer motorcycle sharing platforms. Tourist corridors in Florida and coastal California generate episodic demand spikes.
Individual riders hold the largest share; fleet segments are gaining share fastest as gig-economy delivery penetration accelerates.
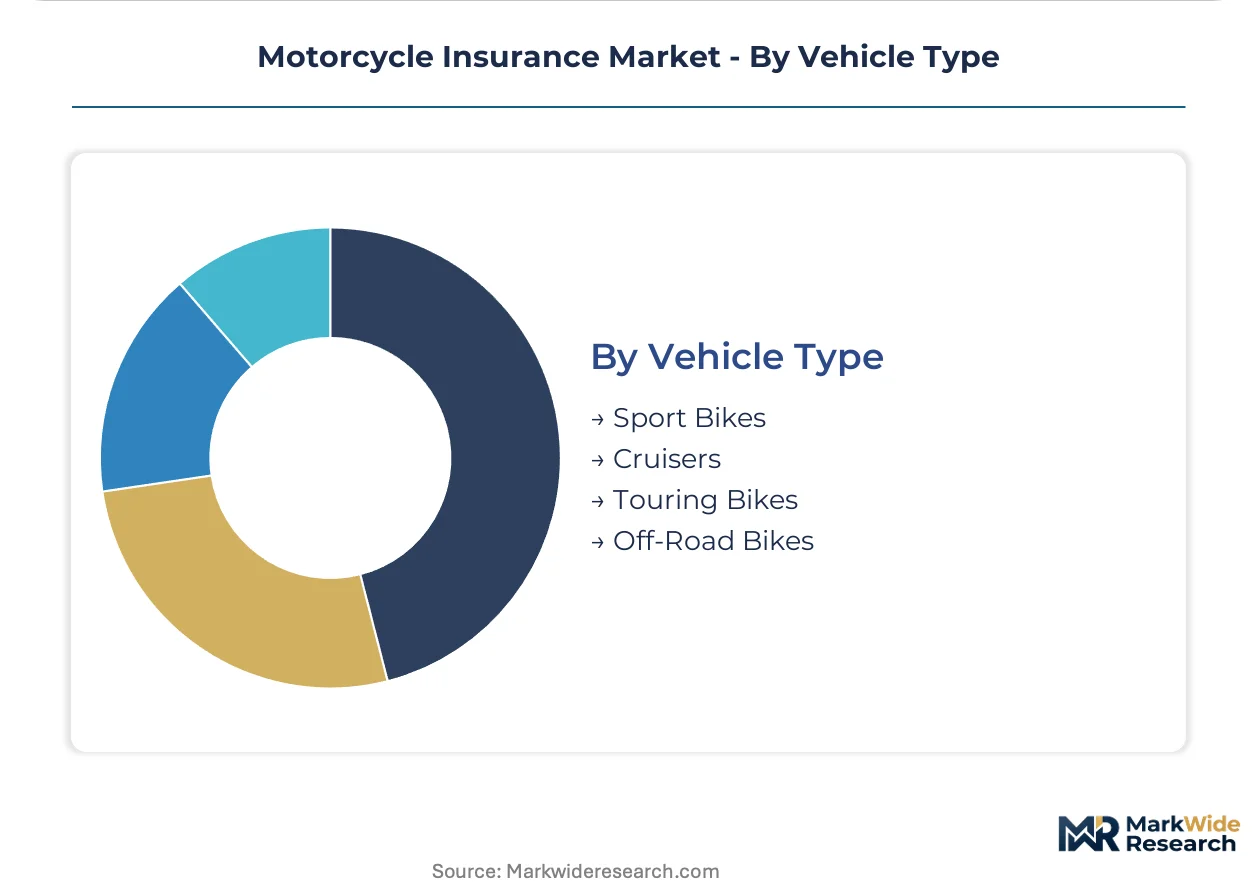
Vehicle Type:
Loss ratio dispersion across vehicle classes creates underwriting specialization, with sport bikes generating elevated claims frequency that mainstream carriers often decline.
- Sport Bikes:High-performance machines with elevated power-to-weight ratios. Young male riders in recreational corridors generate loss ratios that compress margins for undifferentiated carriers.
- Cruisers:Low-slung, torque-heavy machines favored by mature riders. The American Midwest and Southern states sustain this segment through established riding culture and extended touring routes.
- Touring Bikes:Full-dress machines with integrated luggage and passenger accommodations. Affluent retirees on interstate corridor routes purchase comprehensive coverage at superior retention rates.
- Off-Road Bikes:Dirt bikes and dual-sport machines with limited street legality. Rural and exurban recreational areas in the Mountain West and Pacific Northwest sustain this niche.
Cruisers hold the largest share; sport bikes present the steepest expansion trajectory for specialized underwriters willing to price risk precisely.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Metropolitan commuters in congested US corridors exhibit the highest price elasticity, while affluent touring bike owners in affluent suburban markets absorb premium tiers without volume attrition. This demand-elasticity contrast shapes regional expansion priorities for carriers calibrating portfolio mix.
United States
State compulsory coverage mandates in California, Texas, and Florida sustain baseline premium volumes across all rider income tiers. The National Association of Insurance Commissioners coordinates model laws that shape solvency requirements and rate filing transparency across American jurisdictions. Los Angeles, Chicago, and New York City metropolitan corridors concentrate individual rider growth as congestion drives modal shift toward two-wheeled commuting.
Germany
KBA vehicle registration data and the EU Insurance Distribution Directive impose conduct standards on cross-border policy sales, forcing harmonized disclosure protocols. The KBA enforces type-approval standards that influence risk classification for high-performance machines. Bavaria and Baden-Württemberg anchor cruiser and touring bike populations, with extended autobahn touring routes sustaining comprehensive coverage penetration among affluent retirees.
United Kingdom
FCA conduct rules and continuous insurance enforcement sustain baseline policyholder retention despite premium pressure. The FCA's Consumer Duty requirements reshape product disclosure and claims handling standards across distribution channels. London and Southeast England concentrate fleet segments as food delivery aggregators expand gig-economy rider pools.
France
ANSM and CNIL oversight intersect where health data from connected vehicles meets insurance pricing algorithms, creating compliance complexity for telematics rollouts. The EU Green Deal's mobility transition incentives indirectly support two-wheeled commuting adoption in dense urban cores. Île-de-France and Auvergne-Rhône-Alpes concentrate sport bike registrations among younger riders, generating elevated loss ratios that specialized underwriters target.
Japan
METI industrial policy and JIS standards shape connected vehicle data protocols that telematics platforms must integrate. The PMDA's limited direct relevance to property-casualty lines nonetheless signals broader regulatory attention to algorithmic decision-making in financial services. Kanto and Kansai metropolitan areas concentrate individual commuter policies as aging demographics shift toward practical urban mobility solutions.
Motorcycle Insurance Market Key Industry Players
Technology leadership and cost leadership are held by different player archetypes, with data-native carriers compressing actuarial cycles while legacy networks sustain brand recognition through captive agency infrastructure. The market exhibits tiered concentration: national multi-line carriers with proprietary telematics platforms, specialized non-standard underwriters serving declined risk pools, and captive finance affiliates of major manufacturers. Dominant competitive moves include embedded IoT partnership structures and direct digital channel expansion that bypasses commission-based intermediaries.
Among the telematics-enabled tier, Progressive and GEICO exemplify data-native pricing architectures, while Dairyland occupies a specialized position in non-standard rider segments that mainstream carriers decline. These three anchors span the competitive spectrum from mass-market digital distribution to niche risk specialization.
| Leading Market Players |
|---|
| Harley-Davidson Insurance |
| Allstate |
| Progressive |
| Nationwide |
| Foremost |
| Dairyland |
| Safeco |
| Markel |
| GEICO |
| Others |
Cost & Logistics Intelligence
State-level compulsory coverage mandates in the United States gate both carrier qualification and premium differentiation simultaneously, forcing underwriters to navigate minimum liability floors while competing on comprehensive coverage tiers above regulatory baselines.
Pricing Analysis
Extended service contracts and roadside assistance bundles drive lifetime value in motorcycle insurance. Three-tier pricing structure across premium, standard, and economy levels segments riders by asset exposure and financing requirements. Price differentiation rests on telematics data quality and geographic risk density. Cost compression in the non-standard segment intensifies as specialized underwriters compete for high-risk pools. Metropolitan commuters in congested corridors exhibit the highest price sensitivity, while affluent touring bike owners absorb premium tiers without volume attrition.
Supply Chain Analysis
Port congestion on trans-Pacific lanes elevates inbound logistics costs for telematics hardware components sourced from Taiwan, South Korea, and China. Semiconductor chips, GPS modules, and cellular modems constitute critical input dependencies for connected vehicle platforms. Single-source vulnerability concentrates in Taiwanese foundry capacity for precision sensors. Distribution runs through captive agency networks, direct digital platforms, and embedded OEM partnerships at point of sale.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Telematics-enabled usage pricing constitutes a high-growth disruption, with real-time data streams compressing actuarial cycles and displacing static annual rating methodologies.
For Market Incumbents: Secure proprietary data infrastructure investments to defend against data-native entrants. Rebuild core policy administration systems to ingest continuous telemetry feeds from connected vehicles. Legacy system integration costs represent the critical margin pressure point. Channel control through captive agency networks remains a viable defensive lever against direct digital disintermediation. For New Entrants and Emerging Players: Lead with non-standard rider segments that mainstream carriers decline, particularly sport bike policies with elevated loss ratios. Metropolitan gig-economy delivery fleets present the most penetrable white-space target. Direct digital distribution with embedded IoT partnerships at point of sale offers the strongest go-to-market angle against commission-based intermediaries. For Investors and Strategic Acquirers: The EU Insurance Distribution Directive reshapes the acquisition landscape by standardizing cross-border conduct requirements and elevating compliance infrastructure value. Long-term viability favors carriers with data-native pricing architectures over legacy distribution-dependent underwriters. The signal to monitor is state-level telematics mandate adoption as an inflection indicator for platform consolidation.| Strategic Initiative | Industry Significance |
|---|---|
| Telematics Platform Integration | Progressive and GEICO leverage proprietary data infrastructure to price risk at individual ride level. |
| Non-Standard Segment Specialization | Dairyland anchors market position in high-risk rider pools that larger carriers decline. |
| Direct Digital Channel Expansion | Direct-to-consumer platforms bypass captive agency networks and compress customer acquisition costs. |
| Embedded OEM Partnership | Harley-Davidson Insurance captures riders at point of sale through manufacturer-affiliated distribution. |
| Cross-Border Product Harmonization | EU Insurance Distribution Directive creates standardized distribution pathways across European member states. |
Research Approach
Two parallel data streams informed the analysis: structured interviews with insurance underwriting executives, telematics platform engineers, and state regulatory affairs officers; and secondary validation through NAIC rate filing databases, state insurance department solvency reports, and connected vehicle patent filings. Primary fieldwork captured carrier pricing methodologies and IoT integration roadmaps. Secondary sources included SEC 10-K insurance disclosures, EU Insurance Distribution Directive implementation guidance, and vehicle registration data from state DMVs. Bottom-up policy volume estimates triangulated against top-down premium pool calculations.
Across the analysis window, forecasts model policy type segmentation by liability, comprehensive, collision, and uninsured motorist tiers; coverage level stratification across basic, standard, enhanced, and premium tiers; customer type disaggregation among individual riders, fleets, dealerships, and renters; and vehicle class differentiation across sport bikes, cruisers, touring bikes, and off-road machines. CAGRs derive from actuarial cycle compression rates and telematics penetration curves. Forecast inputs include urban congestion indices and state-level compulsory coverage mandate adoption.
Forecasts assume regulatory continuity in US state insurance departments and EU member state implementations; material policy shifts would require re-modeling. Specific risks include NAIC model law revisions altering solvency requirements and state-level telematics privacy regulations constraining data collection scope. Practitioners should keep alternative scenarios live as embedded IoT device penetration rates and cross-border conduct standard harmonization evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Motor Insurance
India Motor Insurance Market
Motor Insurance
Brazil Car Insurance Market
Motor Insurance
Philippines Motor Insurance Market
Motor Insurance
India Car Insurance Market
Motor Insurance
United Arab Emirates Motor Insurance Market
Motor Insurance
China Motor Insurance Market
Motor Insurance
Taiwan Car Insurance Market
Motor Insurance
Europe Mandatory Motor Third-Party Liability Insurance Market
Motor Insurance
Asia-Pacific Car Insurance Market
Motor Insurance
Crop Agricultural Insurance Market
Motor Insurance
Singapore Motor Insurance Market
Motor Insurance
Guaranteed Auto Protection (GAP) Insurance Market
Motor Insurance
New Energy Vehicle Accident Insurance Market
Motor Insurance
Saudi Arabia Motor Insurance Market
Motor Insurance
China Car Insurance Market
Motor Insurance
Motor Insurance Market