
 Crop Insurance Market | 2026-2036
Crop Insurance Market Size, Share, and Industry Trends Forecast 2026-2036
Crop Insurance Market Intelligence
The gap between premium revenue-protection policies and commodity-grade hail-only coverage is repositioning how insurers structure portfolios. Chubb Ltd. leverages its commercial agribusiness strength to serve large-scale operators with customized revenue products. Zurich Insurance Group anchors its presence through direct relationships with agricultural cooperatives across multiple continents. Farmers Mutual Hail competes on speed of claims settlement in hail-dense regions.
Crop insurance is a risk-transfer mechanism that indemnifies agricultural producers against yield shortfalls or revenue losses triggered by weather events, pests, or price declines; policies incorporate actuarial pricing models using satellite imagery, soil data, and historical yield benchmarks to set premiums and trigger payouts. Multi-Peril coverage dominates premium volumes due to its comprehensive protection against drought, flood, and disease, while Index-Based products are gaining traction among commercial operators seeking lower administrative costs and faster settlements. Distribution through captive agents still controls the majority of policy placements, though online platforms are capturing share among younger farm operators managing smaller acreage.
The USDA Risk Management Agency sets coverage terms and premium subsidies for participating insurers, while EIOPA in Europe mandates solvency capital requirements for agricultural underwriters operating across EU member states. India's Ministry of Agriculture administers the Pradhan Mantri Fasal Bima Yojana through state-level coordination with insurers like ICICI Lombard. Stakeholders must monitor how satellite-based index triggers reshape traditional loss-adjustment economics and agent commission structures.
Market Dynamics
Climate volatility is compressing underwriting cycles and forcing insurers to rebuild actuarial models around satellite-derived yield data rather than historical farm-level records. The USDA Risk Management Agency's subsidy structure continues to dictate product design across North American distribution channels.
Growth Catalysts
- EIOPA solvency requirements:European agricultural underwriters are capitalizing on standardized capital buffers to expand multi-peril coverage into Eastern European grain belts previously served by informal risk pools.
- Revenue protection policies:Large-scale corn and soybean operators in Illinois, Iowa, and Indiana are converting from yield-only to revenue-linked products as price volatility intensifies.
- Satellite imagery integration:Remote sensing platforms enable index-based triggers that slash loss-adjustment costs and accelerate claims settlement timelines for commercial grain handlers.
Market Restraints
- Reinsurance capacity concentration:Bermuda and London market carriers control catastrophic agricultural risk transfer, creating pricing spikes after consecutive drought years in Australian wheat belts.
- Soil moisture sensor deployment costs:Precision agriculture hardware requirements for parametric index products price smallholder participation out of technology-enabled coverage tiers.
- USDA premium subsidy caps:Congressional appropriations limits on farmer premium support compress insurer margins on federally reinsured policies in high-risk counties.
Strategic Opportunities
- Pradhan Mantri Fasal Bima Yojana expansion:India's federally subsidized crop insurance scheme offers volume growth as state governments integrate tenant farmers and sharecroppers into enrollment databases.
- Blockchain-enabled smart contracts:Automated index triggers and instant settlement execution reduce administrative overhead for mutual insurers serving hail-dense Great Plains territories.
- Carbon credit linkage:Cover crops and no-till practices eligible for climate-smart agriculture incentives create bundled products combining risk transfer with sustainability revenue streams.
Industry Challenges
- Actuarial talent scarcity:Specialized underwriters capable of pricing correlated weather risks across multi-year drought cycles command compensation premiums that strain regional mutual carrier cost structures.
- Legacy policy administration system migration:Decades-old mainframe infrastructure at established agricultural insurers impedes real-time satellite data integration and mobile agent platform deployment.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Crop Insurance Market |
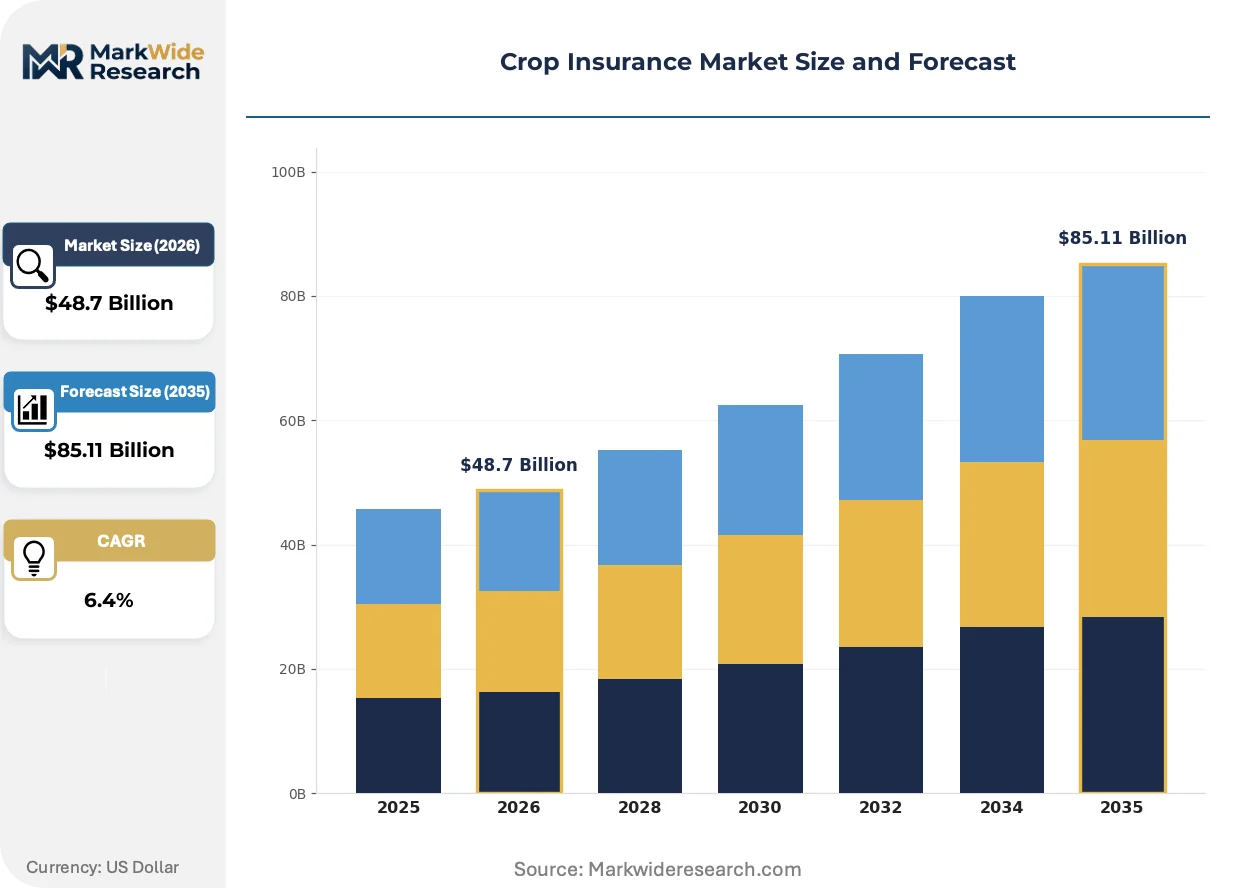
| Market Size in 2026 | $48.7 Billion |
| Market Size in 2035 | $85.11 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Insurance Type: Multi-Peril, Crop-Hail, Revenue Insurance, Index-Based Crop Type: Cereal, Oilseed, Fruits, Vegetables Distribution Channel: Direct Sales, Agents, Brokers, Online Platforms Customer Segment: Farmers, Agricultural Cooperatives, Agribusinesses, Government Programs |
| Companies Covered | QBE Insurance Group, Chubb Ltd., Sompo Holdings, Great American Insurance Group, Farmers Mutual Hail, Zurich Insurance Group, Tokio Marine HCC, ICICI Lombard General Insurance Company, American International Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Crop Insurance Market Strategic Shifts & Innovations
Satellite remote sensing is displacing manual crop scouting as the primary loss-verification mechanism, compressing settlement timelines from months to weeks. Insurers are rebuilding core systems around geospatial data pipelines.
Hyperspectral imaging is integrating drought stress detection and pest infestation mapping into parametric trigger designs. Commercial operators managing ten-thousand-acre spreads in Nebraska and Kansas are adopting these tools fastest. The technology is integrating yield forecasting directly into policy pricing engines, collapsing the traditional separation between underwriting and claims functions.
The USDA Risk Management Agency's expansion of enterprise units allows aggregated coverage across multiple counties, altering how large operators structure deductible layers. This policy shift rewards geographic diversification and penalizes concentrated single-county exposure. Corn Belt cooperatives are responding by reorganizing member enrollment to optimize subsidy capture and minimize basis risk.
Younger farm operators are bypassing captive agent networks for direct online policy binding and mobile claims submission. Digital platforms now capture placement share among operators under forty managing mid-sized acreage in Wisconsin and Minnesota. This channel rotation is most visible where USDA-subsidized premium calculators enable instant price comparison across revenue protection levels.
Crop Insurance Market Segmentation
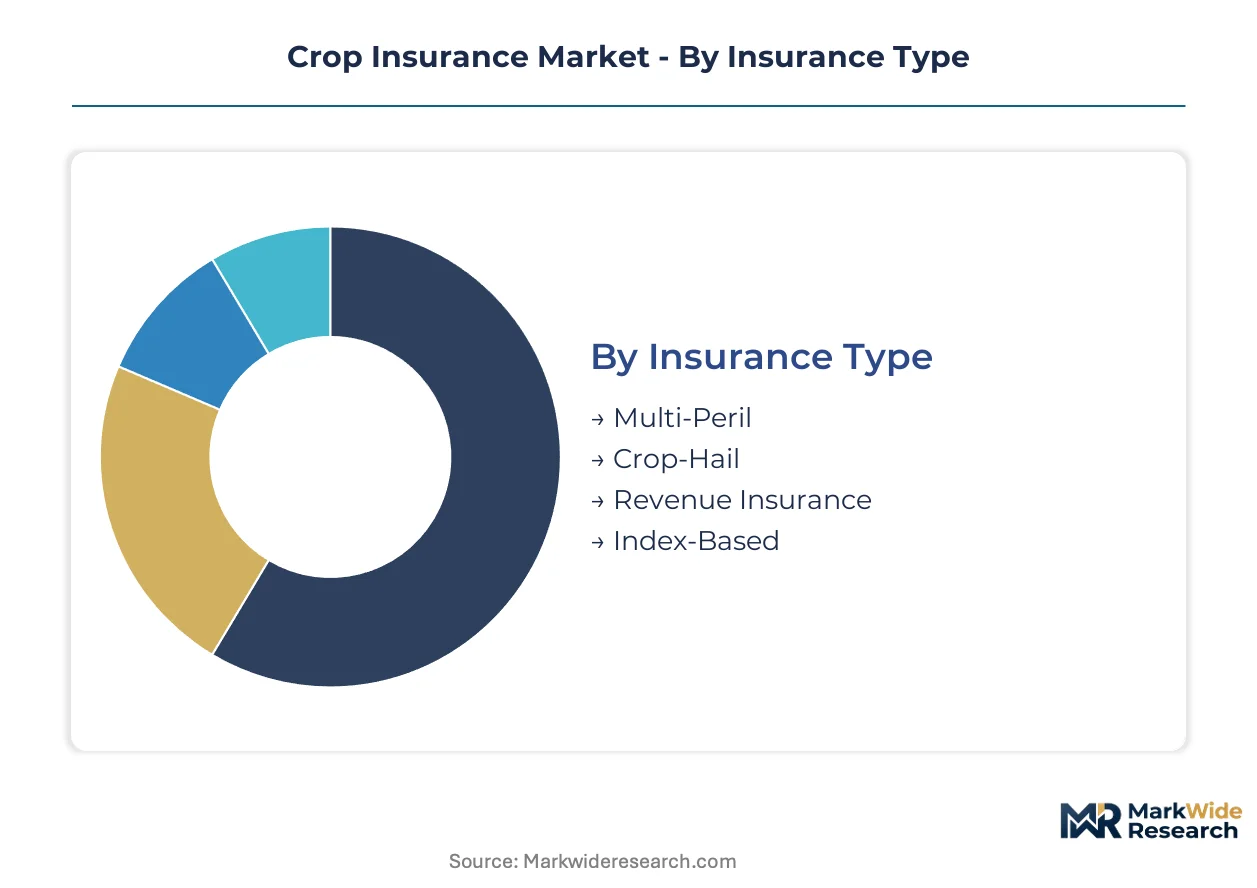
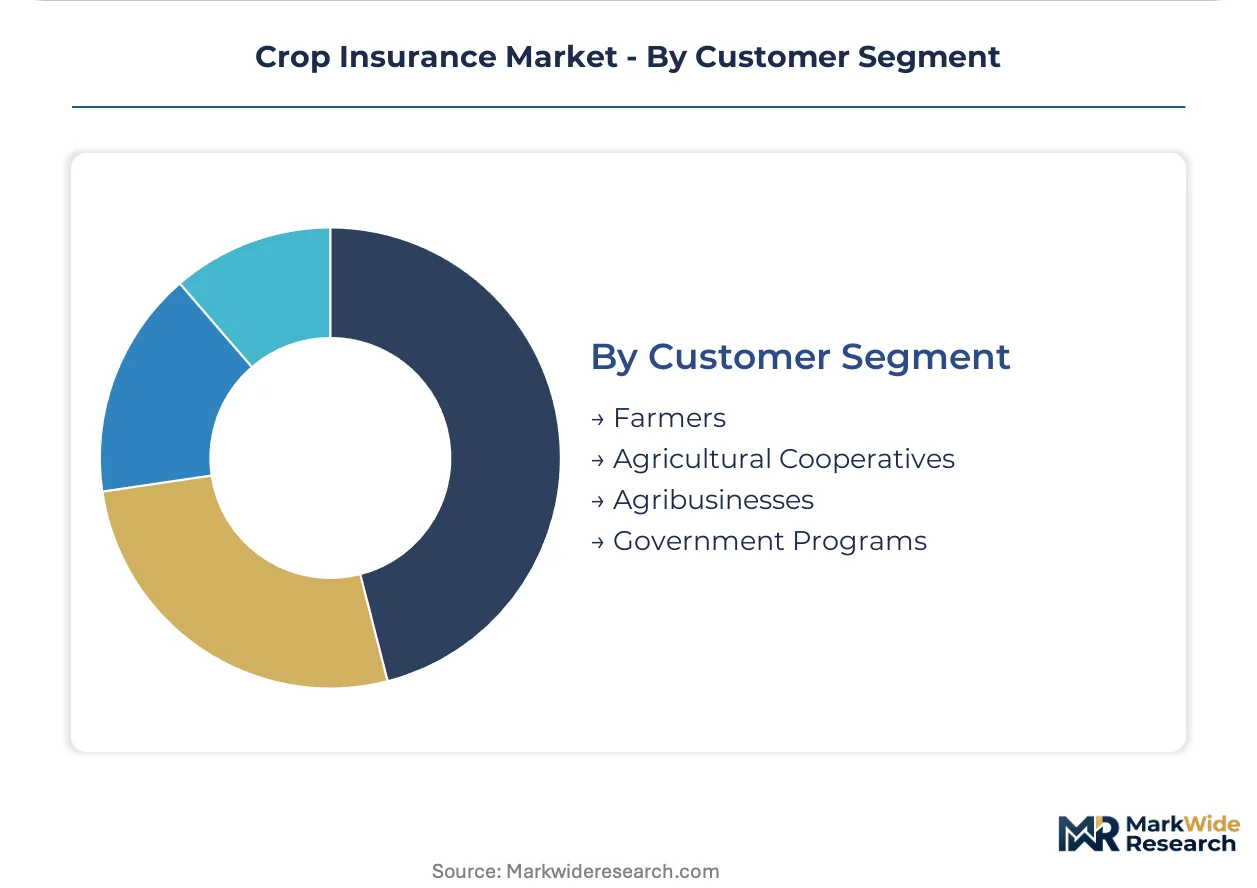
Segmentation in crop insurance reflects divergent risk profiles across farming operations and distribution economics. Underwriters structure product tiers around peril complexity, crop value density, and customer scale rather than uniform coverage templates.
Insurance Type:
Supply concentration among federally reinsured carriers shapes how product tiers reach different farmer risk appetites and subsidy eligibility thresholds.
- Multi-Peril:Comprehensive coverage bundling drought, flood, disease, and yield shortfall into single policies with USDA premium subsidies. Demand concentrates in the US Corn Belt where Illinois and Iowa corn-soybean operators prioritize revenue stability over peril-specific savings. Federal reinsurance backing limits carrier selection but guarantees claim payment capacity across catastrophic weather years.
- Revenue Insurance:Hybrid products protecting against both yield declines and commodity price drops using futures-market benchmarks. Large-scale operators in Nebraska and Kansas are converting acreage to revenue-linked structures as price volatility outpaces yield variance in profit-risk calculations. USDA subsidy formulas favor these products in high-value crop counties.
- Crop-Hail:Named-peril coverage for localized storm damage with faster claims settlement and lower premiums. Hail-dense Great Plains territories drive placement volume through mutual carriers specializing in rapid loss adjustment.
- Index-Based:Parametric triggers using satellite rainfall or vegetation indices eliminate individual farm loss verification. Commercial grain handlers in drought-prone Australian wheat belts adopt these for administrative cost reduction and immediate payout execution.
Multi-Peril absorbs the bulk of installed capacity; Index-Based is expanding most quickly.
Crop Type:
Margin structures vary sharply by crop value density and peril correlation across growing regions.
- Cereal:Corn, wheat, and rice coverage dominates premium volumes due to planted acreage scale and price volatility exposure. US Midwest corn operations generate the highest policy counts among federally subsidized products.
- Oilseed:Soybean and canola insurance carries elevated premium rates reflecting price sensitivity and disease vulnerability. Argentine and Brazilian soybean belts are expanding coverage penetration as export dependency intensifies.
- Fruits:Perennial crop policies require multi-year actuarial models accounting for freeze damage and establishment costs. California Central Valley almond and grape operators drive specialty coverage innovation.
- Vegetables:High-value row crops with concentrated harvest windows demand customized revenue protection. Florida tomato and lettuce growers prioritize revenue-linked structures given price collapse risks.
Cereal captures the steepest expansion trajectory; Fruits command premium rate multiples above field crops.
Distribution Channel:
Customer acquisition costs and policy servicing economics determine channel viability across farmer age and scale segments.
- Agents:Captive agent networks control the majority of policy placements through relationships built over decades of farm-level consultation. USDA-subsidized premium calculators embedded in agent workflows sustain this channel's dominance among operators over fifty.
- Brokers:Independent intermediaries access multiple carrier panels for large agribusiness accounts requiring customized coverage structures. Commercial grain cooperatives in Minnesota and Wisconsin leverage broker relationships for enterprise-unit optimization.
- Direct Sales:Carrier-employed representatives target national agribusiness accounts with standardized product suites. Simplified revenue protection policies for ten-thousand-acre spreads bypass agent commissions.
- Online Platforms:Digital binding and mobile claims submission capture share among operators under forty managing mid-sized acreage. Wisconsin and Minnesota placement data shows fastest adoption where instant premium comparison tools are available.
Agents retain the majority of policy volume; Online Platforms are climbing the fastest among emerging channels.
Customer Segment:
Risk pooling mechanisms and subsidy access create distinct service requirements across farmer scale and organizational structure.
- Farmers:Individual owner-operators represent the foundational customer base with policies sized to single-family acreage and equipment collateral requirements. Subsidy-dependent participation concentrates in US federal crop counties.
- Agricultural Cooperatives:Member-owned organizations aggregate coverage across hundreds of farms to optimize enterprise-unit subsidies and minimize basis risk. Iowa and Illinois corn cooperatives reorganize enrollment annually to capture geographic diversification benefits.
- Agribusinesses:Vertically integrated operators from seed production through grain handling require bundled property and crop coverage with international reinsurance backing. Argentine soybean processors and US ethanol plants drive commercial policy complexity.
- Government Programs:Federally administered schemes like India's Pradhan Mantri Fasal Bima Yojana mandate insurer participation through state-level tender processes. Volume allocation depends on rural branch network density and claims settlement speed metrics.
Farmers represent the deepest penetration base; Agricultural Cooperatives are gaining share fastest through pooled enrollment strategies.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Des Moines anchors the world's densest crop insurance underwriting cluster, with actuarial talent and federal program administration concentrated across the US Corn Belt. Premium volumes concentrate in four countries where agricultural policy and climate exposure create distinct market architectures.
United States
Illinois and Iowa corn-soybean operators drive revenue protection policy volumes through the USDA Risk Management Agency's subsidy framework. The federal crop insurance program mandates minimum coverage standards that shape product design across all participating carriers. Chicago serves as the reinsurance placement hub where Bermuda and London market carriers absorb catastrophic agricultural risk.
Brazil
Soybean processors in Mato Grosso and Paraná are expanding coverage penetration as export dependency intensifies price volatility exposure. The country's national agricultural insurance program provides premium subsidies through federal rural credit mandates. São Paulo-based cooperatives aggregate member coverage to optimize enterprise-unit structures and minimize basis risk.
India
Tenant farmers in Maharashtra and Madhya Pradesh are entering enrollment databases under the Pradhan Mantri Fasal Bima Yojana expansion. The Ministry of Agriculture administers this federally subsidized scheme through state-level tender processes with insurers. ICICI Lombard maintains rural branch network density to capture volume allocation in drought-prone Deccan Plateau districts.
Canada
Prairie Province wheat and canola operators utilize provincial crown corporations alongside private carriers for multi-peril coverage. Agriculture and Agri-Food Canada coordinates with provincial risk management agencies to set coverage terms and premium pools. Winnipeg serves as the administrative center where Manitoba and Saskatchewan farm organizations negotiate enterprise-unit aggregation rules.
Australia
Commercial grain handlers in New South Wales and Queensland are adopting index-based parametric triggers for drought-prone wheat belts. The Australian Prudential Regulation Authority oversees solvency requirements for agricultural underwriters operating across multiple states. Sydney-based brokers place catastrophic risk into London and Bermuda reinsurance markets after consecutive drought years compress capacity.
Crop Insurance Market Key Industry Players
Premium-margin players sit above commodity-margin players across product complexity and customer scale dimensions. The market structures around federally reinsured carriers with USDA backing, mutual insurers specializing in hail-dense territories, and international carriers with agricultural reinsurance capacity. Three archetypes dominate: commercial agribusiness specialists, cooperative-aligned mutuals, and diversified global underwriters. Competitive moves concentrate on satellite data integration partnerships and geographic expansion into subsidized government schemes.
Among diversified global underwriters, Chubb Ltd. and Zurich Insurance Group occupy positions serving large-scale operators with customized revenue products. Farmers Mutual Hail exemplifies the mutual archetype competing on claims settlement speed in hail-dense Great Plains territories. ICICI Lombard represents the government-program specialist tier, anchoring volume through India's federally subsidized crop insurance scheme.
| Leading Market Players |
|---|
| QBE Insurance Group |
| Chubb Ltd. |
| Sompo Holdings |
| Great American Insurance Group |
| Farmers Mutual Hail |
| Zurich Insurance Group |
| Tokio Marine HCC |
| ICICI Lombard General Insurance Company |
| American International Group |
| Others |
Cost & Logistics Intelligence
Captive reinsurance arrangements in Bermuda and London anchor catastrophic risk transfer capacity, concentrating pricing power among carriers with multi-year treaty relationships while compressing margins for regional mutuals without direct market access. USDA premium subsidy formulas create tiered pricing floors that differentiate federally reinsured products from private hail-only coverage across the Corn Belt.
Pricing Analysis
Yield-outcome pricing anchors actuarial models where satellite-derived vegetation indices replace historical farm records as the primary valuation input. Premium stratification separates revenue protection with futures-market benchmarks from commodity-grade hail coverage, with price differentiation resting on peril bundling and claims settlement speed. Pricing pressure stems from congressional appropriation caps on farmer premium support in high-risk counties. Smallholder operators in tenant farming arrangements exhibit highest price sensitivity, while ten-thousand-acre commercial grain handlers absorb premium multiples for customized enterprise-unit structures.
Supply Chain Analysis
Domestic-content mandates in India's Pradhan Mantri Fasal Bima Yojana require participating insurers to maintain rural branch networks above threshold density, reshaping capital deployment toward district-level presence. Catastrophic risk capacity concentrates in Bermuda, London, and Zurich where global reinsurers aggregate agricultural exposure across multiple continents. The supply chain draws from satellite imagery providers, soil moisture sensor manufacturers, and legacy policy administration system vendors. Single-source vulnerability runs through concentrated reinsurance capacity after consecutive drought cycles in Australian wheat belts. Distribution runs through captive agent networks controlling majority policy placements, with digital platforms capturing mid-sized acreage segments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Actuarial talent scarcity constrains underwriting capacity expansion, propping pricing power for carriers with specialized drought-cycle modeling capabilities. Reinsurance treaty renewals face tightened terms as climate volatility compresses loss ratios.
For Market Incumbents: Anticipate satellite-data integration partnerships as the primary defensive move against insurtech entrants with native geospatial capabilities. Consolidate around legacy policy administration system modernization to preserve agent channel control. Vertical integration into remote sensing platforms offers margin protection against third-party data vendor price escalation. USDA subsidy formula revisions represent the critical regulatory threat requiring Washington-based government relations investment. For New Entrants and Emerging Players: Enter via India's state-level tender processes for Pradhan Mantri Fasal Bima Yojana expansion, where volume allocation depends on claims settlement speed metrics rather than decades-long agent relationships. Target index-based parametric products for commercial grain handlers in drought-prone Australian wheat belts, where administrative cost reduction drives purchasing decisions. Blockchain-enabled smart contracts provide the specific go-to-market angle for mutual insurers seeking hail-dense Great Plains penetration without legacy mainframe infrastructure. For Investors and Strategic Acquirers: Exit pathways concentrate in strategic acquisition by diversified global underwriters seeking agricultural reinsurance capacity and Corn Belt distribution density. Long-term viability favors carriers with demonstrated satellite data integration and enterprise-unit optimization capabilities for large-scale cooperatives. Acquisition target archetype: mutual insurers with hail-dense territory specialization and sub-48-hour claims settlement benchmarks. Watch reinsurance treaty renewal terms as the inflection signal for capacity-constrained pricing power shifts.| Strategic Initiative | Industry Significance |
|---|---|
| Satellite Data Integration Partnership | Remote sensing platforms from Planet Labs and Maxar enable index-based trigger deployment across Nebraska and Kansas acreage. |
| Enterprise Unit Optimization | USDA Risk Management Agency aggregation rules reward geographic diversification across Iowa and Illinois cooperative memberships. |
| Blockchain Smart Contract Deployment | Automated settlement execution reduces administrative overhead for mutual insurers in hail-dense Great Plains territories. |
| Rural Branch Network Expansion | India's state-level tender processes allocate Pradhan Mantri Fasal Bima Yojana volume based on district-level presence density. |
| Legacy System Modernization | Real-time satellite data integration requires core system replacement at decades-old agricultural mutual carriers. |
Research Approach
USDA Risk Management Agency actuarial documents, satellite imagery provider technical specifications, and reinsurance market treaty filings formed the secondary backbone of data collection. Primary interviews with crop insurance underwriters, agricultural cooperative risk managers, and reinsurance placement brokers validated demand-side assumptions. The analysis combined bottom-up policy count aggregation with top-down premium pool estimation across federally reinsured and private market segments.
Bottom-up modeling built county-level exposure from USDA subsidy participation records, while top-down approaches cross-referenced national agricultural statistics with carrier financial disclosures. Segmentation dimensions included insurance type, crop value density, distribution channel economics, and customer scale archetypes. CAGRs were derived from trend extrapolation adjusted for climate volatility assumptions and subsidy policy continuity. Forecast inputs incorporated satellite-derived yield forecast accuracy improvements and enterprise-unit adoption curves among Corn Belt cooperatives.
Forecast precision tightens around the base case; tail outcomes carry wider variance under consecutive catastrophic drought years or congressional subsidy appropriation reductions. The analytical envelope assumes regulatory continuity for federal crop insurance program participation and reinsurance market capacity availability. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Insurance
China Online Insurance Market
Insurance
Entertainment Insurance Market
Insurance
Property Insurance Market
Insurance
Cargo Insurance Market
Insurance
Insurance BPO Services Market
Insurance
Bancassurance Market
Insurance
Australia Parametric Insurance Market
Insurance
India Health Insurance Market
Insurance
Global Healthcare Claims Management Market
Insurance
United States Insurance Brokerage Market
Insurance
Business Income Insurance Market
Insurance
Insurance Big Data Analytics Market
Insurance
Vietnam Private Health Insurance Market
Insurance
Europe Embedded Insurance Market
Insurance
Microinsurance Market
Insurance
Digital Monetary Insurance Market