
 North America Car Insurance Aggregators Market | 2026-2036
North America Car Insurance Aggregators Market Size, Share, and Industry Trends Forecast 2026-2036
North America Car Insurance Aggregators Market Insights
NAIC producer licensing reciprocity standards are redrawing competitive boundaries across state lines. EverQuote leverages its proprietary data-matching engine to sustain quote volume leadership in high-premium states. The Zebra anchors its position through brand strength and direct-to-consumer channel control. Insurify competes via AI-powered conversational interfaces that compress quote-to-bind timelines.
North America car insurance aggregators function as digital intermediaries that normalize carrier rate filings, coverage terms, and underwriting criteria into comparable quote formats, typically processing real-time API calls to multiple insurers within sub-60-second response windows. Their primary commercial purpose is reducing consumer search friction while generating qualified leads for carrier direct writers and captive agents. The comparison service segment dominates transaction volume, though policy management tools capture disproportionate recurring revenue per user. Mobile app platforms represent the fastest-growing engagement channel, displacing legacy website-first architectures among under-45 demographics.
FCC digital advertising transparency rules, state-level NAIC data privacy model laws, and NHTSA telematics data ownership guidance collectively shape aggregator compliance costs and product design constraints. The patchwork of state insurance department rate-filing requirements creates operational complexity that favors platforms with dedicated regulatory technology infrastructure. Stakeholders must monitor evolving state-by-state restrictions on lead-sale practices and algorithmic pricing disclosures to preserve monetization flexibility.
Market Dynamics
Telematics-enabled usage-based insurance mandates across multiple US states are forcing aggregators to rebuild quote-matching engines around real-time driving data feeds rather than static risk tables.
Growth Catalysts
- NAIC Data Privacy Model Laws:Standardized consumer data protection frameworks reduce compliance fragmentation across state lines, lowering platform operational overhead for multi-state quote aggregation.
- Small Business Fleet Digitization:Commercial auto coverage procurement is migrating from broker-mediated channels to self-service comparison platforms as fleet management software integrates insurance APIs.
- Mobile-First Architecture:Sub-60-second quote generation on smartphone interfaces is compressing consumer decision cycles and expanding addressable demographics below age 45.
Market Restraints
- Carrier API Rate Limiting:Major insurers throttle real-time quote requests during peak demand windows, creating response latency that degrades user experience and conversion rates.
- State Rate-Filing Patchwork:Insurance departments in Texas, Florida, and California maintain incompatible prior-approval requirements that force aggregators to maintain redundant regulatory technology stacks.
- Lead Quality Erosion:Price-sensitive shoppers generating multiple quotes without purchase intent dilute lead value for carrier direct writers, pressuring aggregator revenue per transaction.
Strategic Opportunities
- Embedded Insurance Partnerships:Auto dealership management systems and vehicle telematics OEMs present white-label distribution channels that capture consumers at point-of-purchase.
- Policy Lifecycle Management Tools:Comparison platforms expanding into renewal optimization, coverage gap analysis, and claims advocacy capture recurring revenue streams beyond initial quote generation.
- FCC Digital Advertising Transparency Rules:Disclosed ad pricing mechanisms favor established aggregators with proprietary first-party data over ad-dependent challengers, consolidating market access.
Industry Challenges
- Actuarial-Data Science Talent Gap:Platforms struggle to hire professionals capable of translating telematics streams into carrier-acceptable risk scoring models.
- Legacy Carrier System Integration:Mainframe-based insurer policy administration systems require expensive middleware development to enable real-time API connectivity.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Car Insurance Aggregators Market |
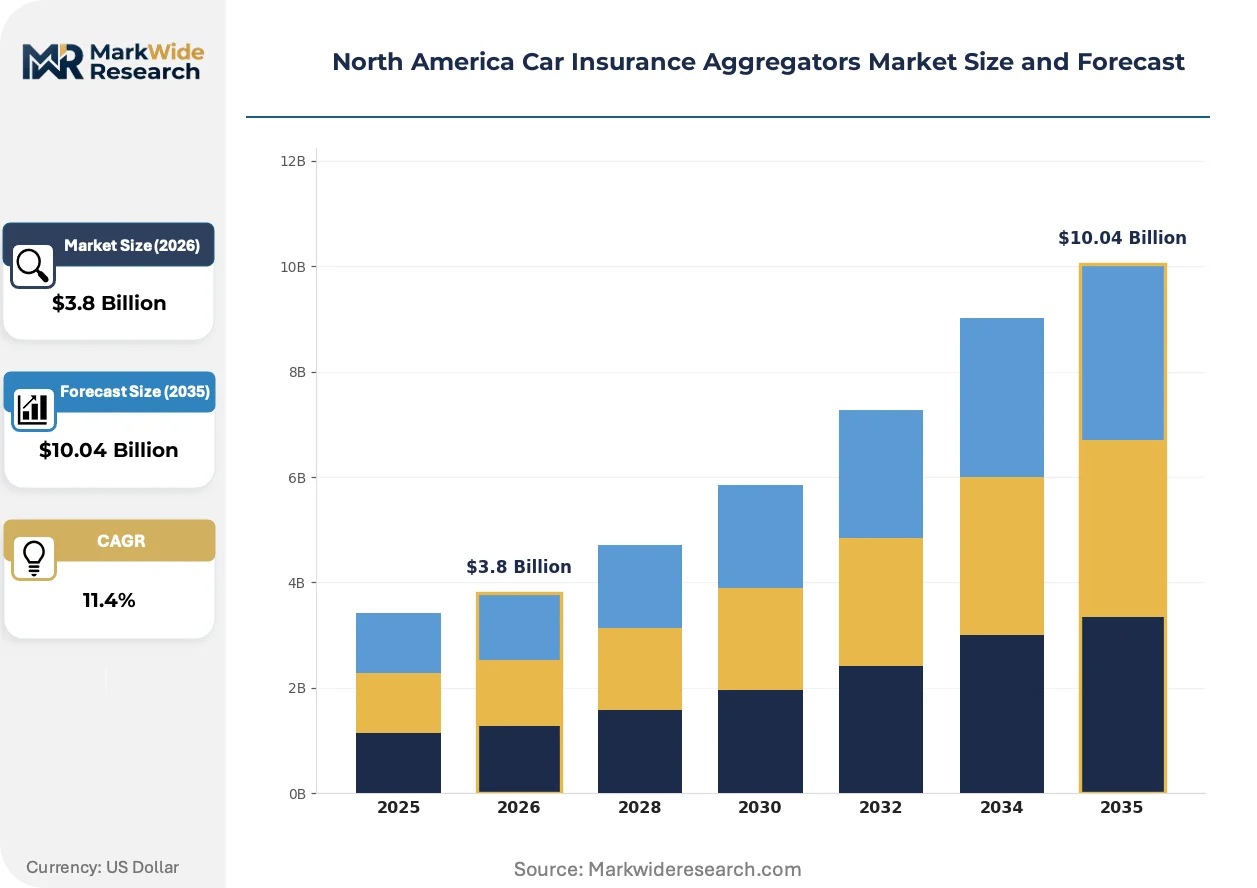
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $10.04 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Comparison, Quotes, Policy Management, Claims Handling Customer Type: Individuals, Small Businesses, Fleet Owners, Corporations Insurance Type: Liability, Comprehensive, Collision, Uninsured Motorist Platform Type: Website, Mobile App, Hybrid Platform, API Integration |
| Companies Covered | Compare.com, EverQuote, The Zebra, CoverHound, QuoteWizard, Insurify, Policygenius, NerdWallet, Gabi, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Car Insurance Aggregators Market Trends and Innovations
Artificial intelligence and embedded distribution channels are compressing the traditional insurance shopping journey from days to minutes while fragmenting control over customer relationships.
Conversational AI interfaces powered by large language models are bifurcating the quote acquisition process. Younger demographics engage through natural-language chat rather than form-based data entry, accelerating quote completion rates. This interface shift is compressing the competitive advantage of incumbent platforms with legacy web architectures.
NHTSA telematics data ownership guidance is clarifying consumer control over vehicle-generated information. Aggregators must now negotiate data-sharing agreements directly with drivers rather than accessing streams through carrier partnerships. Platforms with explicit opt-in consent frameworks gain preferential access to usage-based pricing models in California and Texas.
Channel control is rotating from aggregators toward embedded distribution partners. Auto lenders, vehicle subscription services, and connected-car platforms are capturing insurance shopping intent before consumers reach standalone comparison sites. Texas-based digital auto retailers now originate coverage binding at point of vehicle delivery, bypassing traditional aggregator funnels.
North America Car Insurance Aggregators Market Segmentation
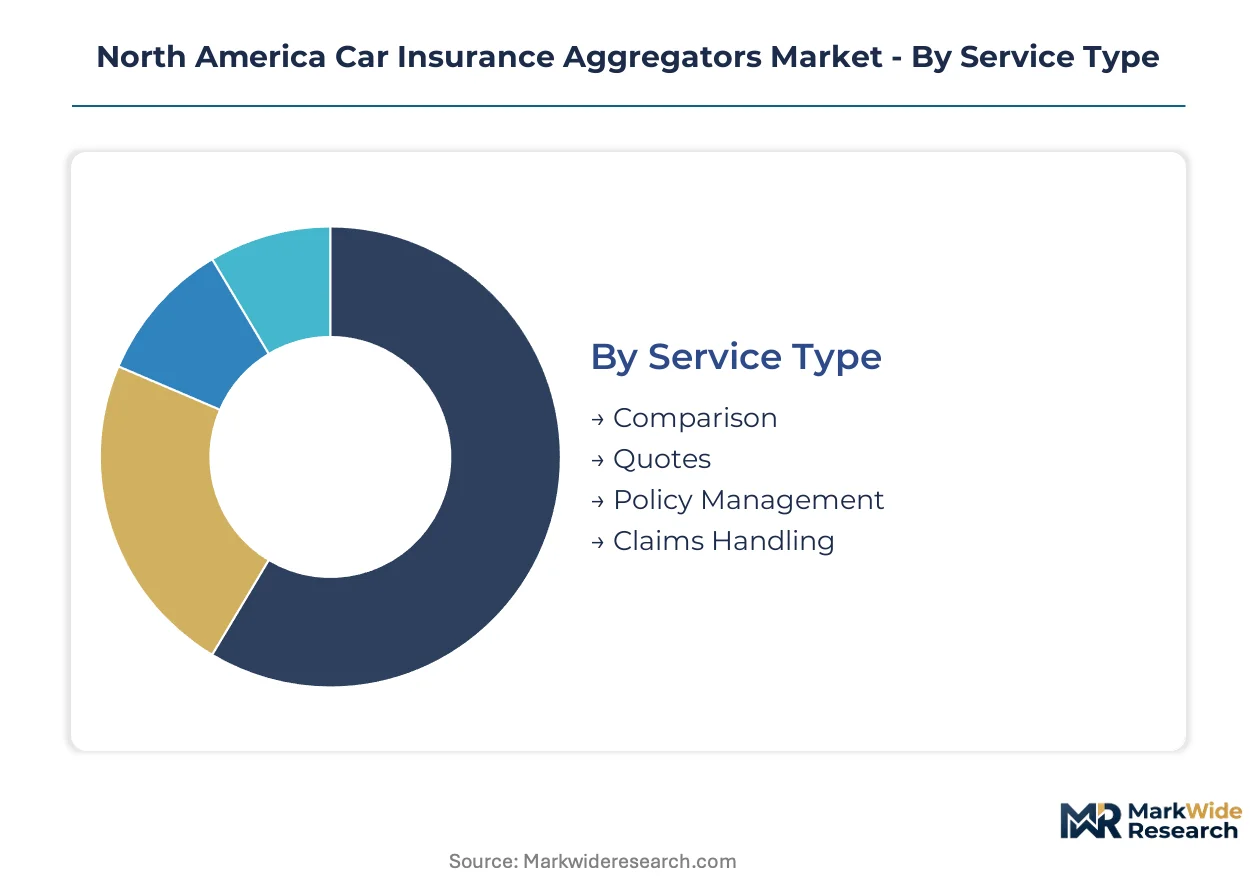
Car insurance aggregators serve heterogeneous demand pools with divergent quote complexity, renewal frequency, and carrier integration requirements. Channel economics vary sharply across segments, dictating platform architecture investments and monetization strategies.
Service Type:
Comparison services flow through high-velocity web funnels optimized for lead generation volume, while policy management tools monetize through recurring SaaS subscriptions and carrier referral fees.
- Comparison:Real-time rate normalization across multiple carrier APIs constitutes the core technical capability. Texas, Florida, and California generate disproportionate transaction volume due to prior-approval rate regimes that amplify price dispersion. FCC digital advertising transparency rules favor established platforms with proprietary first-party data assets in this segment.
- Quotes:Instant bind-ready proposals require deep carrier system integration and dynamic underwriting rule interpretation. Small business fleet owners in Texas are expanding adoption as fleet management software embeds quote APIs directly into procurement workflows.
- Policy Management:Renewal optimization and coverage gap analysis tools capture recurring revenue per user.
- Claims Handling:Post-loss advocacy services represent emerging attach revenue beyond quote origination.
Comparison dominates installed base. Policy Management is where expansion concentrates.
Customer Type:
Cost tiers diverge sharply: individual consumers generate low-margin lead volume while fleet owners command premium placement fees and dedicated account management layers.
- Individuals:Price-sensitive shoppers with high quote-to-bind latency and elevated churn. Mobile app platforms displace website-first architectures among under-45 demographics in this segment.
- Small Businesses:Commercial auto coverage procurement is migrating from broker-mediated channels to self-service platforms. NAIC producer licensing reciprocity standards enable cross-state quote aggregation for multi-location operators.
- Fleet Owners:Telematics-enabled usage-based mandates across multiple states are forcing quote-matching engine rebuilds around real-time driving data feeds. California and Texas lead adoption due to state-level UBI regulatory clarity.
- Corporations:Enterprise risk managers demand API-first integration with internal procurement systems and consolidated billing across dispersed vehicle pools.
Individuals anchor transaction volume. Fleet Owners deliver the steepest expansion trajectory.
Insurance Type:
Application urgency varies by coverage trigger: liability mandates create continuous demand while collision purchases concentrate around vehicle acquisition events.
- Liability:State-mandated minimum coverage generates baseline quote volume with compressed margin due to regulatory rate compression.
- Comprehensive:Full coverage policies command higher carrier commissions and longer policy tenures. Florida and California drive disproportionate demand due to weather-related loss severity and vehicle theft rates.
- Collision:Physical damage coverage correlates with new vehicle sales cycles and lender requirements.
- Uninsured Motorist:Coverage uptake concentrates in states with elevated non-compliance rates and limited enforcement infrastructure.
Liability saturates addressable households. Comprehensive is gaining share fastest.
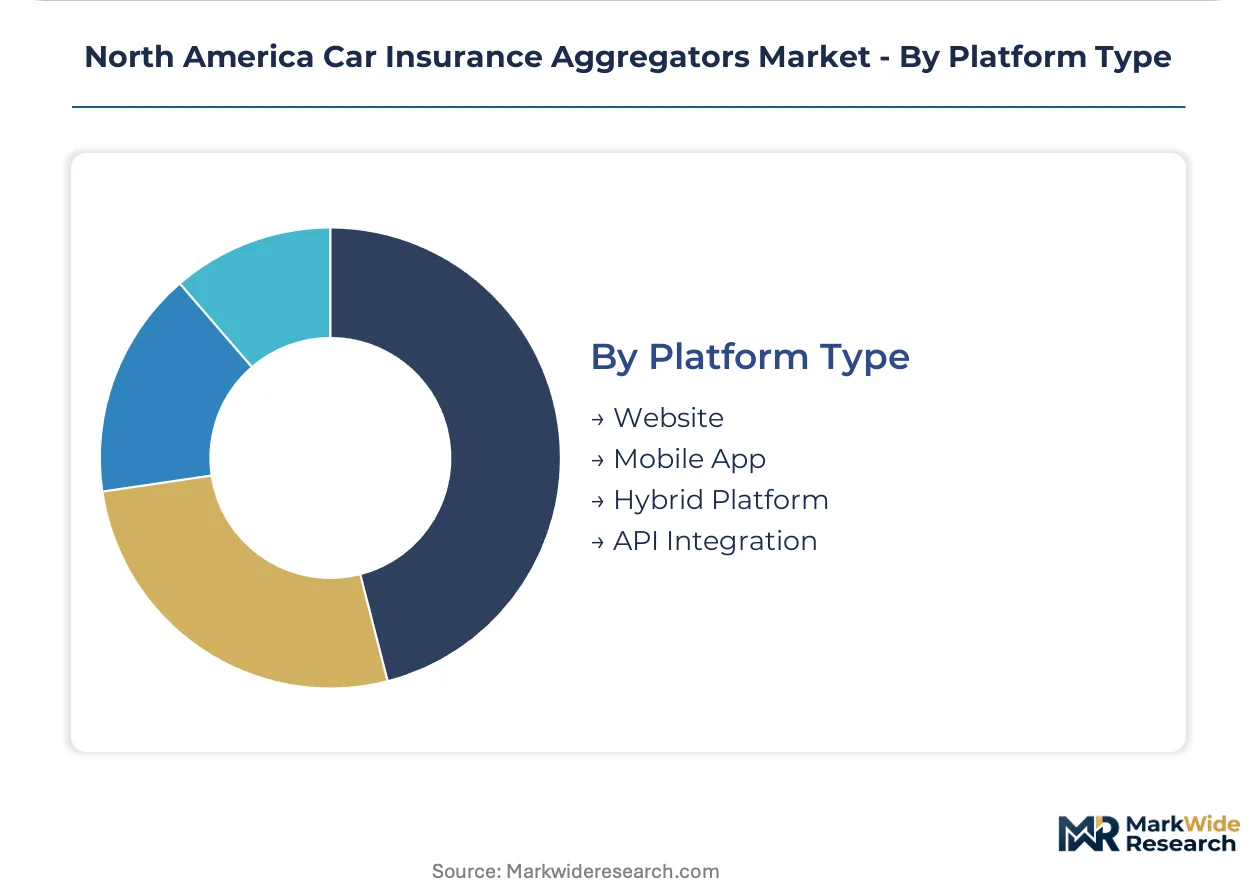
Platform Type:
Supply concentration favors hybrid architectures that unify mobile engagement velocity with website depth for complex commercial submissions.
- Website:Legacy desktop-first platforms retain dominance in commercial auto segments requiring extensive documentation upload and multi-driver scheduling.
- Mobile App:Sub-60-second quote generation on smartphone interfaces compresses consumer decision cycles. Younger demographics engage through natural-language chat rather than form-based data entry.
- Hybrid Platform:Unified codebases serving responsive web and native app experiences capture cross-device shopping journeys. Texas-based digital auto retailers embed hybrid quote modules at point of vehicle delivery.
- API Integration:White-label distribution through auto dealership management systems and vehicle telematics OEMs captures insurance shopping intent before consumers reach standalone comparison sites.
Website retains commercial auto dominance. API Integration is where carrier partnership investment concentrates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The I-35 corridor freight rail network and cross-border data trunk lines underpin North America's role as the primary aggregation hub for US-Mexico-Canada automotive insurance flows.
United States
Texas, Florida, and California generate disproportionate transaction volume due to prior-approval rate regimes that amplify price dispersion. FCC digital advertising transparency rules favor established platforms with proprietary first-party data assets. Dallas-Fort Worth anchors commercial auto aggregation growth as fleet management software vendors cluster along the Telecom Corridor.
Canada
Ontario and British Columbia drive platform adoption through provincial auto insurance reforms that expand consumer choice. The country's national insurance regulator maintains harmonized data privacy standards that reduce compliance fragmentation for cross-border operators. Toronto's fintech corridor hosts white-label aggregation infrastructure serving US-bound commercial fleets.
Mexico
Nuevo León and Mexico City concentrate demand as mandatory auto insurance laws expand coverage penetration. The central bank's open finance framework enables real-time carrier API connectivity previously limited to cash-based broker networks. Monterrey's automotive manufacturing cluster generates embedded insurance partnerships at vehicle point-of-sale.
North America Car Insurance Aggregators Market Competitive Landscape
Listed leaders compete with private specialists across data-matching engine sophistication and carrier API depth. The vendor base concentrates around three functional tiers: quote-volume platforms, brand-centric direct-to-consumer operators, and AI-native conversational interfaces. Strategic archetypes include proprietary data aggregators, white-label infrastructure providers, and embedded distribution enablers. Dominant competitive moves center on regulatory technology infrastructure investment and telematics data partnership formation.
Among US-based digital intermediaries, EverQuote, The Zebra, and Insurify exemplify distinct positioning vectors. EverQuote occupies the data-matching scale tier. The Zebra represents brand-strength consumer channel control. Insurify anchors the AI-powered interface compression archetype.
| Leading Market Players |
|---|
| Compare.com |
| EverQuote |
| The Zebra |
| CoverHound |
| QuoteWizard |
| Insurify |
| Policygenius |
| NerdWallet |
| Gabi |
| Others |
Pricing and Supply Chain Analysis
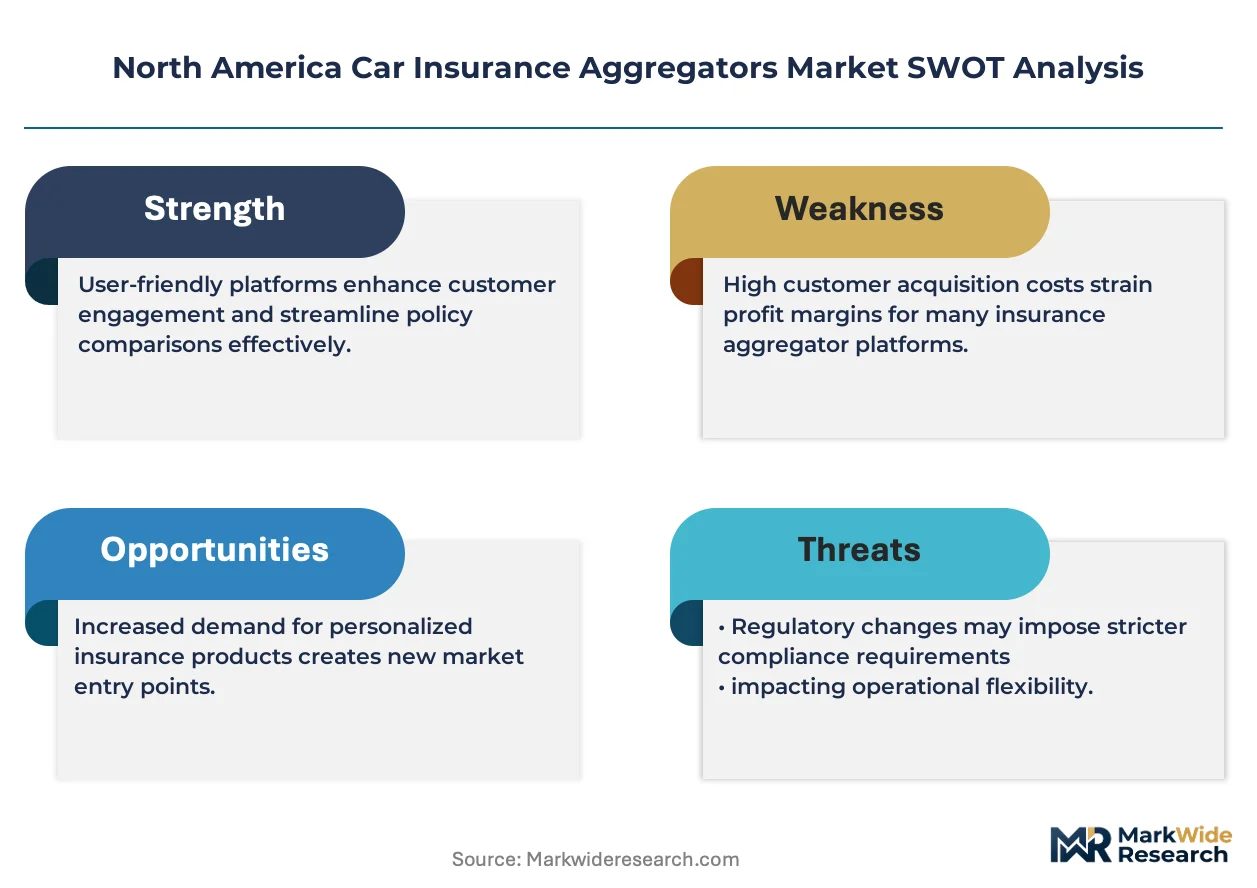
Cost-per-acquisition contracts with carrier direct writers lock in both quote volume commitments and lead pricing visibility across Texas, Florida, and California. These arrangements tether aggregator revenue stability to carrier marketing budget cycles while insulating platforms from spot-market lead price volatility during seasonal demand swings.
Pricing Analysis
Lead quality tiering creates the primary spread between premium placement fees and standard auction-rate pricing. Aggregators charge carriers premium rates for telematics-verified, bind-ready leads while standard quote requests flow through programmatic auction markets. Pricing pressure stems from carrier API rate limiting during peak demand windows, which degrades conversion rates and compresses effective revenue per transaction. Individual consumers exhibit highest price sensitivity, shopping multiple platforms simultaneously, while fleet owners accept premium pricing for dedicated account management and multi-state coverage consolidation.
Supply Chain Analysis
Carrier API gateway chokepoints in Texas and California constrain real-time quote throughput during high-volume periods. Aggregator technology stacks draw from three core inputs: proprietary data-matching engines, telematics data feeds, and carrier underwriting rule libraries. Single-source vulnerability concentrates around dominant carrier API providers whose system outages cascade across comparison platforms. Distribution runs through hybrid architectures unifying mobile app engagement with embedded white-label partnerships at auto dealerships and fleet management software vendors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation opportunity concentrates around telematics-enabled usage-based insurance mandates that create specialized quote-engine requirements distinct from legacy rate-table platforms. Small business fleet digitization opens niche positioning for API-first specialists against incumbent consumer-focused aggregators.
For Market Incumbents: Consolidate carrier API depth in Texas and California to defend quote volume leadership against embedded distribution challengers. Deepen vertical integration into proprietary telematics data partnerships with NHTSA-compliant consent frameworks. Regulatory technology infrastructure investment in state rate-filing compliance preserves multi-state operational flexibility against patchwork enforcement expansion. For New Entrants and Emerging Players: Lead with AI-powered conversational interfaces targeting under-45 demographics in Florida and Texas where mobile-first quote completion rates lag incumbent platform optimization. White-label embedded partnerships with auto dealership management systems in Dallas-Fort Worth and Monterrey automotive clusters offer lower customer acquisition costs than direct-to-consumer channel buildouts. Fleet management software API integration presents the most penetrable commercial auto entry point. For Investors and Strategic Acquirers: The market sits at a consolidation phase that favors regulatory technology infrastructure and telematics data partnership assets over pure lead-volume platforms. Long-term viability across the analysis window hinges on first-party data moats and embedded distribution channel control. Watch NAIC data privacy model law adoption velocity as the signal indicating whether multi-state compliance overhead favors scaled incumbents or creates acquisition opportunities for regional specialists.| Strategic Initiative | Industry Significance |
|---|---|
| Telematics Data Partnership Formation | NHTSA guidance compliance unlocks usage-based pricing models in California and Texas. |
| Regulatory Technology Infrastructure Investment | State rate-filing automation reduces operational overhead across prior-approval jurisdictions. |
| Embedded Insurance White-Label Expansion | Auto dealership management system integration captures pre-aggregator shopping intent. |
| AI-Powered Conversational Interface Deployment | Natural-language quote completion accelerates mobile app conversion among younger demographics. |
| Small Business Fleet Platform Specialization | Commercial auto API integration with fleet management software displaces broker-mediated procurement. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted across the North American car insurance aggregation value chain. Primary interviews engaged platform engineering executives, carrier direct writer marketing officers, state insurance department regulatory leads, and fleet management software procurement directors. Secondary validation drew from NAIC rate-filing databases, FCC digital advertising transparency disclosures, NHTSA telematics guidance documents, and state insurance department enforcement actions. Bottom-up quote volume modeling and top-down carrier commission flow analysis were triangulated to ground market sizing.
Across the analysis window, forecasts employed a segmented growth framework disaggregating by service type, customer archetype, insurance coverage category, and platform architecture. CAGRs were derived from carrier API call volume trajectories, embedded partnership penetration curves, and telematics-enabled policy growth patterns. Quote-to-bind conversion rate assumptions and lead quality tier migration informed revenue per transaction progression.
The analysis sits within stated boundaries; outcomes outside sustained state-level UBI mandate expansion and stable carrier marketing budget allocation would require recalibration. Forecasts reflect assumptions about NAIC data privacy model law harmonization velocity and embedded distribution channel capture rates. Practitioners should keep alternative scenarios live as FCC digital advertising transparency enforcement and NHTSA telematics data ownership guidance evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Insurance
Japan Liability Insurance Market
Insurance
Cloud Computing in Insurance Market
Insurance
Directors and Officers (Dando) Insurance Market
Insurance
Aerospace Insurance Market
Insurance
Drone Insurance Market
Insurance
Self Funded Insurance Market
Insurance
Single Trip Travel Insurance Market
Insurance
Agriculture Reinsurance Market
Insurance
Global Sports Insurance Market
Insurance
Cybersecurity Insurance Market
Insurance
Dental Insurance Market
Insurance
Asia-Pacific Usage-Based Insurance Market
Insurance
Asia-Pacific Surety Market
Insurance
Africa Microinsurance Market
Insurance
US Travel Insurance Market
Insurance
Slovenia Property and Casualty Insurance Market