
 Peru Life and Non-Life Insurance Market | 2026-2036
Peru Life and Non-Life Insurance Market Size, Share, and Industry Trends Forecast 2026-2036
Peru Life and Non-Life Insurance Market Analytics
Actuarial talent scarcity in provincial markets is reorganizing how insurers deploy underwriting capacity outside Lima. Rimac leverages its captive agency network to sustain dominance in individual life products across Peru's northern corridor. Pacifico Seguros anchors its position through bancassurance partnerships with Credicorp's banking subsidiaries. Mapfre Peru competes on commercial property lines by controlling relationships with multinational mining contractors operating in Ancash and Cajamarca.
Peru life and non-life insurance constitutes risk-pooling contracts underwritten against mortality, morbidity, property damage, and liability exposures, with premium reserves held in solvency-mandated instruments governed by SBS technical provisions. The primary purpose spans individual financial protection, enterprise risk transfer, and pension accumulation aligned with Peru's AFP-integrated retirement system. Term life and whole life products within the product type segment generate the thickest margin pools due to persistency-linked commission structures and long-duration float. Health coverage under the coverage type segment shows the fastest structural expansion as Peru's EsSalud parallel demand drives supplemental policy uptake among formal-sector employees.
SBS, Peru's insurance and private pension regulator, enforces risk-based capital requirements and consumer protection standards that dictate product filing timelines and reserve adequacy tests for all authorized insurers. The SBS digital reporting framework and anti-money laundering protocols from Peru's UIF-integrated financial intelligence unit shape distribution channel economics and agent licensing burdens. Stakeholders must monitor how SBS implements IFRS 17-aligned disclosure standards and whether Peru's pension reform debate alters AFP-integrated life product structures.
Market Dynamics
SBS digital onboarding mandates are compressing distribution economics while forcing insurers to rebuild agent networks around mobile-first policy issuance. The informal-to-formal workforce transition is creating a dual-speed market where traditional AFP-integrated products compete against flexible microinsurance alternatives.
Growth Catalysts
- EsSalud Parallel Demand:Peru's public health system gaps are driving supplemental private health coverage uptake among formal-sector employees seeking faster access to specialists and elective procedures.
- SBS Regulatory Modernization:Risk-based capital requirements and streamlined product filing timelines are reducing time-to-market for innovative term life and microenterprise property products.
- Provincial Microenterprise Expansion:Property coverage adoption is accelerating in Arequipa, Trujillo, and Cusco as informal businesses formalize and require bank-mandated insurance for credit access.
Market Restraints
- Actuarial Talent Scarcity:Peru's provincial markets lack sufficient credentialed underwriters, forcing Lima-based insurers to absorb higher travel and remote assessment costs for risk evaluation outside the capital corridor.
- Solvency Reserve Requirements:SBS-mandated technical provisions tie significant capital in low-yield instruments, compressing investment income that subsidizes pricing in competitive segments.
- Informal Economy Persistence:Approximately two-thirds of Peruvian workers remain outside formal employment structures, limiting addressable market for AFP-integrated pension and life products.
Strategic Opportunities
- Amazonas and Loreto Penetration:Northern jungle regions show minimal insurance density despite extractive industry presence, creating first-mover advantage for insurers building rural agency networks.
- Parametric Agriculture Coverage:Satellite-indexed crop and livestock products can bypass traditional loss-adjustment infrastructure in regions with sparse claims assessor coverage.
- UIF-Integrated Distribution:Anti-money laundering protocol alignment enables insurers to leverage banking correspondent networks for policy sales without building standalone agent infrastructure.
Industry Challenges
- Legacy Core System Migration:Mid-tier insurers face multi-year transformation timelines to achieve SBS digital reporting compliance while maintaining policy servicing continuity.
- Agent Licensing Burden:SBS continuing education mandates and UIF certification requirements are increasing attrition among part-time provincial agents.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Peru Life and Non-Life Insurance Market |
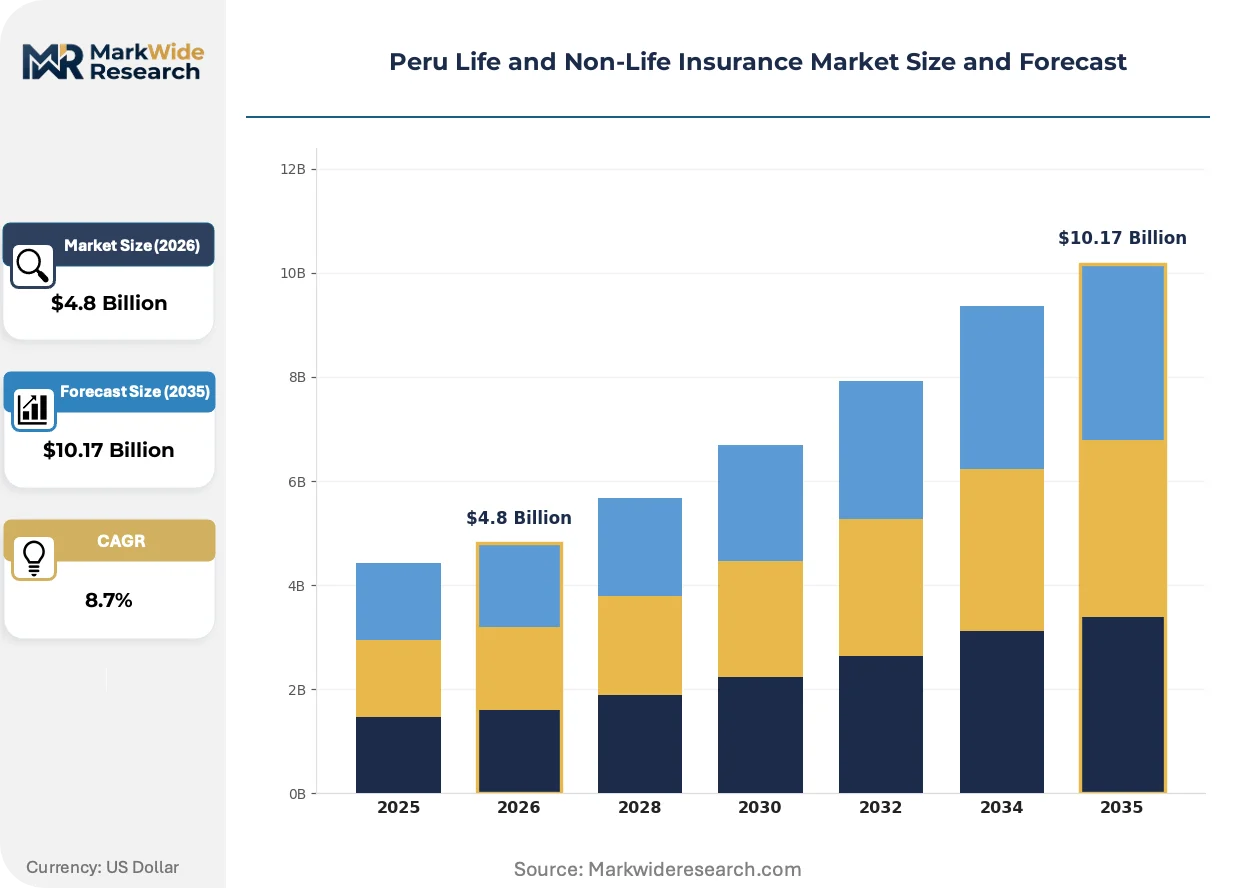
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $10.17 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
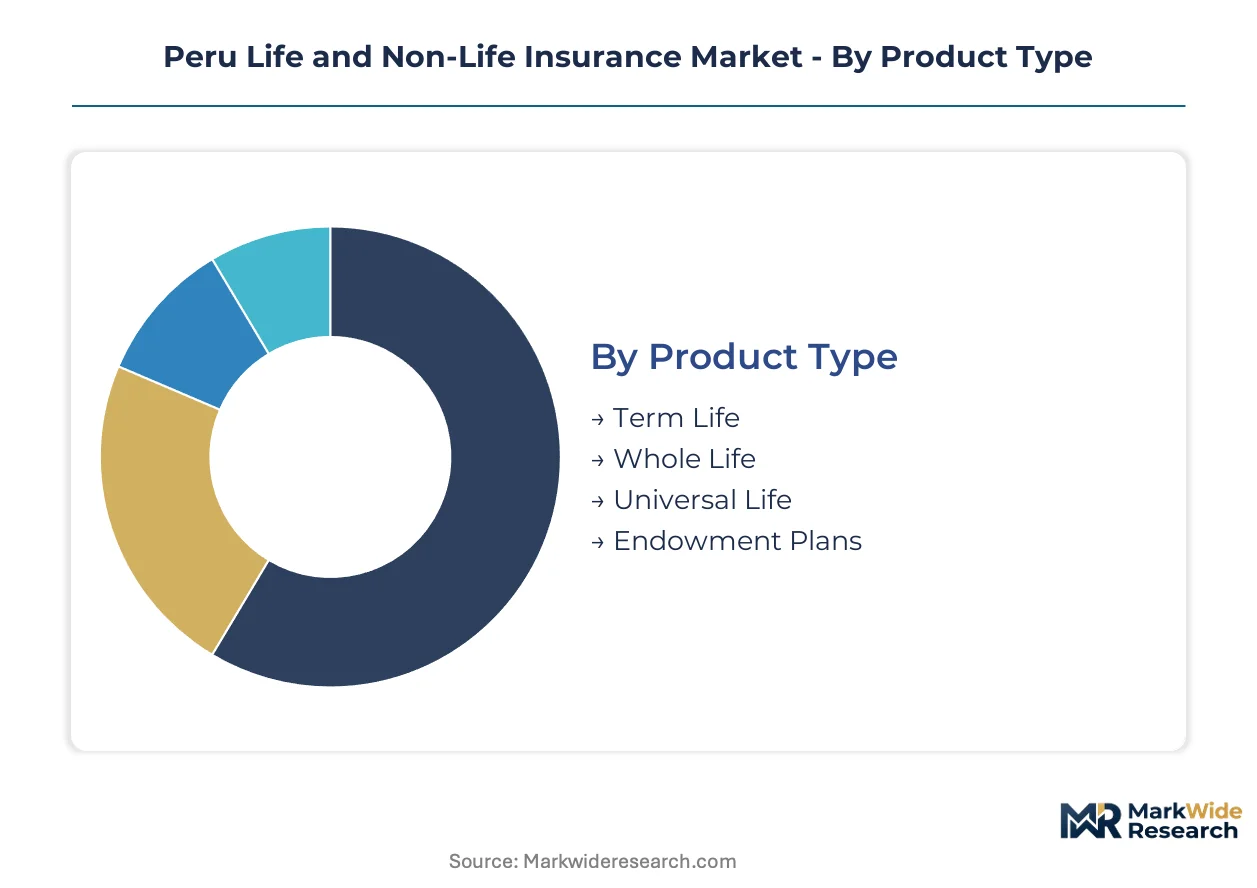
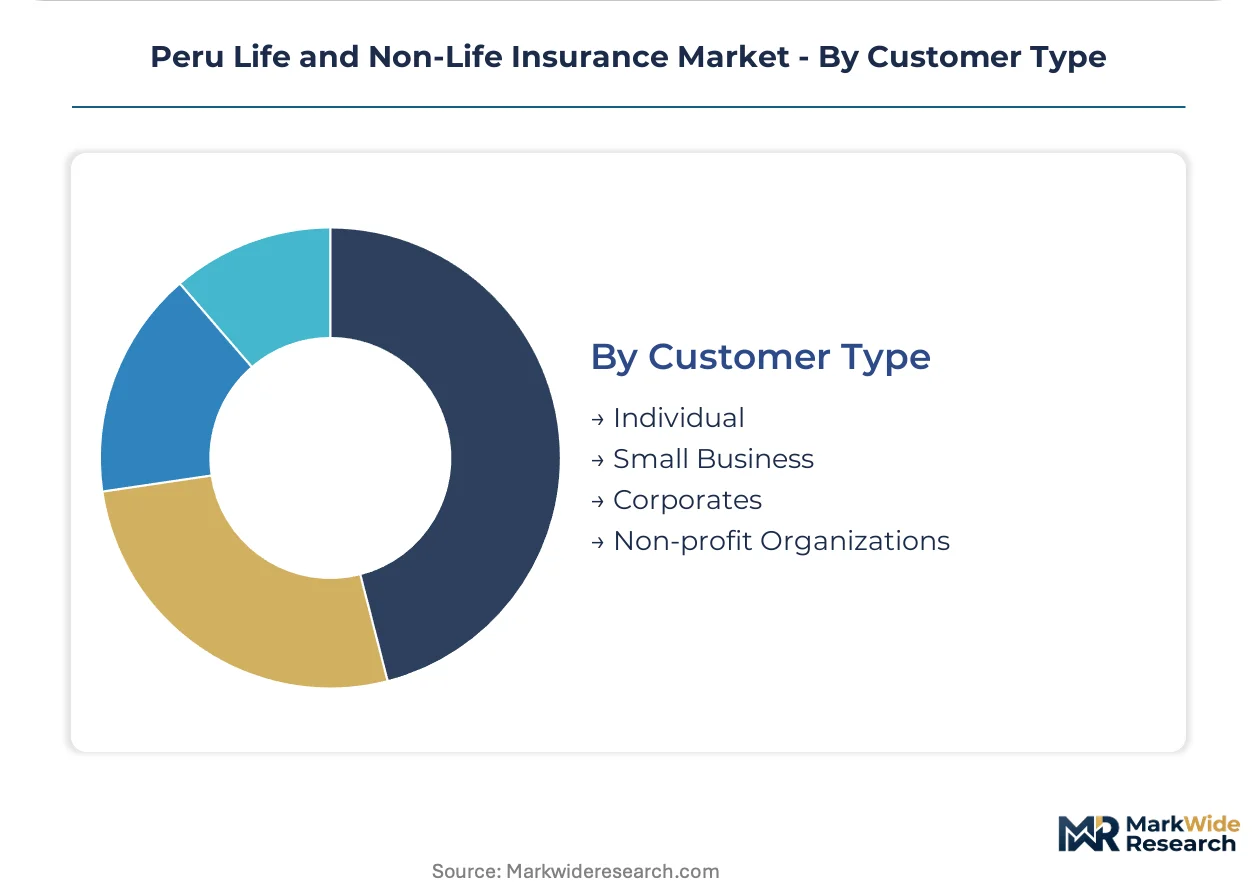
| Segmentation | Product Type: Term Life, Whole Life, Universal Life, Endowment Plans Coverage Type: Health, Property, Casualty, Liability Distribution Channel: Direct Sales, Brokers, Agents, Online Platforms Customer Type: Individual, Small Business, Corporates, Non-profit Organizations |
| Companies Covered | Mapfre Peru, Protecta, Rimac, Chubb Seguros, Seguros SURA, Pacifico Seguros, Interseguro, HDI Seguros, La Positiva, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Peru Life and Non-Life Insurance Market Evolving Landscape
Digital distribution infrastructure is bifurcating Peru's insurance landscape between technology-enabled direct channels and relationship-dependent traditional networks. Three convergent forces are redefining product design, regulatory compliance, and customer acquisition economics.
Telematics-enabled auto and commercial fleet coverage is bifurcating the motor insurance segment. Large mining and logistics operators in La Libertad and Ica are adopting usage-based pricing models that reward defensive driving metrics. This technology is compressing traditional risk-pooling margins while creating data advantages for early adopters with integrated IoT platforms.
SBS IFRS 17-aligned disclosure standards are reshaping reserve calculation methodologies and investor reporting timelines. Insurers must rebuild actuarial models to capture contract boundary assessments and discount rate sensitivity analyses. The life and pension segment faces the steepest compliance burden as long-duration liability measurement requirements intensify.
Informal workers are fragmenting distribution channel preferences across generational and geographic lines. Younger policyholders in Lima metropolitan areas favor app-based quote comparison and digital claims submission. Older customers and provincial buyers maintain loyalty to captive agency relationships, forcing insurers to maintain dual infrastructure without full cost recovery on either channel.
Peru Life and Non-Life Insurance Market Segmentation
Segmentation reveals how SBS regulatory frameworks and Peru's geographic fragmentation create divergent growth trajectories across product lines and distribution channels. Understanding these divides clarifies where capital deployment generates sustainable returns versus structural drag.
Product Type:
Term life and whole life products dominate Lima's formal employment corridor, while universal life and endowment plans find traction among provincial wealth accumulation needs.
- Term Life:Pure mortality coverage with fixed premiums over defined periods generates the thickest margin pools through persistency-linked commission structures. Demand concentrates among formal-sector employees in Lima and Callao seeking income replacement protection during peak earning years, with SBS-mandated reserve requirements compressing pricing flexibility.
- Whole Life:Permanent coverage combining mortality protection with cash value accumulation appeals to affluent households in San Isidro and Miraflores districts. Provincial adoption lags due to premium affordability constraints outside the capital corridor.
- Universal Life:Flexible premium and adjustable death benefit structures accommodate income volatility among self-employed professionals in Arequipa and Trujillo.
- Endowment Plans:Savings-linked products with maturity payouts target education funding and dowry traditions in Cusco and Puno highland communities.
Term life commands the established base. The steepest expansion runs through universal life as informal workers seek flexible premium schedules.
Coverage Type:
Cost tier stratification separates essential mandated coverage from discretionary supplemental protection across Peru's income distribution.
- Health:Medical expense reimbursement and critical illness riders address EsSalud system gaps. Demand concentrates among formal-sector employees in Lima metropolitan area seeking specialist access and elective procedure coverage, with SBS consumer protection standards dictating minimum benefit floors.
- Property:Fire, theft, and natural peril coverage for residential and commercial assets. Bank-mandated policies for credit access drive adoption among formalizing microenterprises in Arequipa, Trujillo, and Chiclayo provincial hubs.
- Casualty:Accident and disability income protection covers occupational risks in mining and construction sectors across Ancash and La Libertad.
- Liability:Professional and product liability coverage remains underpenetrated outside multinational contractor relationships in extractive industry zones.
Property coverage anchors the revenue base. Health coverage is gaining share fastest as EsSalud parallel demand intensifies among formal employees.
Distribution Channel:
Volume concentration varies dramatically between high-touch relationship channels and emerging digital infrastructure across generational divides.
- Direct Sales:Insurer-employed representatives targeting corporate group policies and affinity relationships. Large mining contractors in Cajamarca and Pasco generate concentrated premium volumes through direct negotiation.
- Brokers:Independent intermediaries placing commercial property and liability coverage for mid-market enterprises. Regulatory licensing burdens under SBS and UIF protocols are compressing broker profitability.
- Agents:Captive and independent agents dominate individual life product distribution in northern corridor provinces where Rimac maintains network density.
- Online Platforms:Digital quote comparison and policy issuance emerging among younger demographics in Lima metropolitan area, constrained by SBS digital onboarding compliance requirements.
Agent networks retain the dominant share. Online platforms are climbing the fastest as mobile penetration deepens among under-35 policyholders.
Customer Type:
Maturity differentiation separates established corporate risk transfer markets from emerging microenterprise and informal worker segments.
- Individual:Personal life, health, and property coverage purchased through AFP-integrated channels or direct retail. Formal employment transition in Lima drives pension-linked product uptake.
- Small Business:Microenterprise property and liability coverage formalizing alongside credit access in provincial hubs. Arequipa and Trujillo show accelerating adoption as informal businesses register for tax purposes.
- Corporates:Group life, health, and commercial property programs for medium and large enterprises. Mining and logistics operators in Ica and La Libertad generate concentrated premium pools.
- Non-profit Organizations:Specialized coverage for NGOs and civil society organizations operating in rural development and environmental conservation across Amazonas and Loreto.
Corporate accounts command the premium base. Small business coverage is expanding most quickly as provincial formalization accelerates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Insurance consumption patterns diverge sharply between Lima's formal employment corridor and provincial markets where informal workers favor flexible microinsurance over AFP-integrated pension products.
Lima Metropolitan Area
Corporate group policies and individual life products dominate premium volumes in Lima and Callao, driven by formal-sector employees seeking EsSalud supplemental coverage. SBS digital onboarding mandates accelerate mobile-first policy issuance among younger demographics. San Isidro and Miraflores districts concentrate demand for whole life and universal life products with cash value accumulation features.
Ancash and La Libertad
Mining contractors and logistics operators generate concentrated commercial property and casualty premium pools in these northern regions. Chubb Seguros and multinational insurers anchor relationships with extractive industry players through direct negotiation channels. SBS risk-based capital requirements shape how underwriters price occupational risk coverage for construction and mining workforces.
Arequipa and Trujillo
Provincial formalization drives microenterprise property coverage adoption as informal businesses register for tax purposes and seek bank-mandated insurance for credit access. Rimac's captive agency network maintains density advantages in these hubs. SBS streamlined product filing timelines reduce time-to-market for standardized property and liability products targeting small business segments.
Cusco and Puno
Highland communities show distinctive demand for endowment plans tied to education funding and dowry traditions, with lower penetration of term life due to premium affordability constraints. La Positiva and regional insurers compete through simplified underwriting for rural property coverage. SBS consumer protection standards mandate minimum benefit floors that reshape product economics in lower-income segments.
Amazonas and Loreto
Northern jungle regions exhibit minimal insurance density despite extractive industry presence, creating whitespace for first-mover rural agency networks. Parametric agriculture coverage using satellite indexing bypasses sparse claims assessor infrastructure. SBS anti-money laundering protocols from Peru's UIF-integrated financial intelligence unit complicate distribution expansion in remote areas with limited banking correspondent penetration.
Peru Life and Non-Life Insurance Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier, with the top tier controlling dominant positions in both AFP-integrated pension products and commercial property lines while mid-tier players compete on niche segments and geographic specialization. The market structure rewards captive distribution networks in provincial corridors and bancassurance partnerships in urban centers. Two strategic archetypes define competitive positioning: integrated conglomerates with banking and pension affiliates, and specialist underwriters targeting mining and commercial property segments. Dominant competitive moves include geographic expansion into underpenetrated northern jungle regions and portfolio diversification into parametric microinsurance products.
Within the integrated conglomerate tier, Rimac and Pacifico Seguros exemplify divergent distribution strategies—Rimac anchors its position through captive agency density in Peru's northern corridor while Pacifico Seguros leverages bancassurance partnerships with banking subsidiaries. Among specialist underwriters, Mapfre Peru occupies a position serving multinational mining contractors in commercial property lines. These three players represent how scale advantages and distribution control separate market leaders from regional competitors.
| Leading Market Players |
|---|
| Mapfre Peru |
| Protecta |
| Rimac |
| Chubb Seguros |
| Seguros SURA |
| Pacifico Seguros |
| Interseguro |
| HDI Seguros |
| La Positiva |
| Others |
Value Network & Pricing Analysis
Mobile-first policy issuance platforms are displacing paper-based agent contracts across Peru's provincial corridors, simultaneously compressing distribution costs in Lima while inflating technology infrastructure investments needed for SBS digital onboarding compliance. This substitution dynamic concentrates pricing power among insurers with captive agency networks in northern provinces while eroding margins for mid-tier players absorbing legacy system migration burdens.
Pricing Analysis
Long-term AFP-integrated pension contracts anchor pricing structures for formal-sector employees, while spot-market microinsurance products serve informal workers with project-based premium schedules. Price differentiation rests on SBS risk-based capital tiers and geographic delivery costs, with provincial policies commanding higher loadings due to actuarial talent scarcity. Cost compression in the microenterprise segment is intensifying because bank-mandated coverage requirements standardize product features. Small business buyers in Arequipa and Trujillo show highest price sensitivity, while mining contractors in Ancash demonstrate lowest sensitivity due to captive risk transfer needs.
Supply Chain Analysis
Inbound logistics costs through Callao port congestion and container availability constraints on Asia-Pacific trade lanes shape reinsurance treaty placement economics for Peruvian underwriters. Capacity concentrates in Bermuda, London, and Miami as primary retrocession markets, with local insurers drawing from global reinsurer panels for catastrophe exposure coverage. Treaty renewals hinge on sovereign credit rating volatility and solvency reserve requirement changes. Distribution runs through captive agency networks in provincial corridors and bancassurance partnerships in Lima metropolitan area.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Peru's insurance market is recovering from regulatory compression cyclicality, with SBS digital modernization mandates and IFRS 17 alignment costs now peaking and creating entry windows for capitalized players.
For Market Incumbents: Secure captive agency network density in Peru's northern corridor against Rimac's entrenched position through exclusive product distribution agreements and SBS continuing education subsidies for provincial agents. Threat substitution comes from UIF-integrated banking correspondent networks that bypass standalone agent infrastructure. Channel control remains the priority lever for sustaining individual life product margins. For New Entrants and Emerging Players: Differentiate on parametric agriculture coverage using satellite-indexed triggers for Amazonas and Loreto regions where traditional claims assessor infrastructure is sparse. The most penetrable geography sits in northern jungle provinces with extractive industry presence but minimal insurance density. A go-to-market angle through anti-money laundering protocol alignment with banking correspondent networks enables policy sales without standalone agent buildout. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed mid-tier insurers facing multi-year legacy core system migration timelines to achieve SBS digital reporting compliance. Long-term viability over a 5-10 year window favors targets with completed IFRS 17 actuarial model rebuilds and established bancassurance distribution partnerships. The signal to watch is SBS implementation of pension reform debate outcomes that could alter AFP-integrated product structures.| Strategic Initiative | Industry Significance |
|---|---|
| Parametric Product Development | Satellite-indexed triggers bypass sparse claims assessor coverage in Amazonas and Loreto regions. |
| Legacy Core System Migration | SBS digital reporting compliance requires multi-year transformation timelines for mid-tier insurers. |
| Bancassurance Partnership Expansion | Credicorp banking subsidiaries anchor Pacifico Seguros position in Lima formal employment corridor. |
| Provincial Agency Network Buildout | Rimac sustains dominance in individual life products through captive density in northern provinces. |
| UIF-Integrated Distribution Alignment | Anti-money laundering protocol compliance enables banking correspondent network policy sales. |
Research Methodology
The analysis maps term life, whole life, health coverage, and property segments, each validated through actuarial directors, SBS regulatory affairs leads, AFP pension product managers, and provincial agency network heads. Primary interviews with underwriting executives and distribution channel strategists combined with secondary validation against SBS technical provision filings, EsSalud system utilization data, and AFP association membership statistics. Bottom-up policy volume estimates and top-down premium pool assessments triangulate market sizing across the analysis window.
Consistency checks against external benchmarks validated volume and value outputs, with segmentation dimensions spanning product type, coverage tier, distribution channel, and customer archetype across the projection horizon. CAGRs were derived from historical premium growth trajectories and workforce formalization rate assumptions. Forecast inputs incorporated SBS risk-based capital requirement evolution and IFRS 17 disclosure standard implementation timelines.
Material uncertainties — SBS pension reform debate outcomes, sovereign credit rating volatility affecting reinsurance treaty terms, and EsSalud system capacity expansion — sit outside the modeled envelope. Forecasts reflect assumptions about informal-to-formal workforce transition velocity and provincial microenterprise formalization rates. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Life and Non Life Insurance
Finland Life and Non-Life Insurance Market
Life and Non Life Insurance
Sweden Life and Non-Life Insurance Market
Life and Non Life Insurance
Indonesia Life and Non-Life Insurance Market
Life and Non Life Insurance
Asia-Pacific Life and Annuity Insurance Market
Life and Non Life Insurance
China Life and Non-Life Insurance Market
Life and Non Life Insurance
Germany Life and Non-Life Insurance Market
Life and Non Life Insurance
Global Life and Non-Life Insurance Market
Life and Non Life Insurance
Russia Life and Non-Life Insurance Market
Life and Non Life Insurance
Austria Life and Non-Life Insurance Market
Life and Non Life Insurance
Canada Life and Non-Life Insurance Market
Life and Non Life Insurance
Spain Life & Non-Life Insurance Market
Life and Non Life Insurance
Poland Life and Non-Life Insurance Market
Life and Non Life Insurance
Denmark Life and Non-Life Insurance Market
Life and Non Life Insurance
Greece Life and Non-Life Insurance Market
Life and Non Life Insurance
Japan Life and Non-Life Insurance Market
Life and Non Life Insurance
Ireland Life and Non-Life Insurance Market