
 Internet of Things Insurance Market | 2026-2036
Internet of Things Insurance Market Size, Share, and Industry Trends Forecast 2026-2036
Internet of Things Insurance Market Analysis
Agent and broker distribution is reconfiguring around embedded IoT policy offerings at the point of device sale. Munich Re leverages its reinsurance balance sheet to backstop parametric IoT products across multiple carrier front-ends. Progressive Corporation competes through direct-to-consumer telematics integration that captures real-time driving behavior. Octo Telematics S.p.A. dominates the connected vehicle data layer, supplying telemetry infrastructure to insurers lacking in-house IoT capabilities.
Internet of Things Insurance denotes coverage products whose pricing, underwriting, and claims settlement depend on continuous data streams from connected sensors, typically transmitted via cellular or low-power wide-area networks and processed through cloud-based actuarial engines. Its primary commercial purpose is to replace retrospective risk assessment with dynamic, usage-calibrated premium structures that align insurer liability with actual exposure. Usage-Based Insurance leads policy type revenue pools due to mature telematics adoption in auto lines, while Parametric Insurance represents the fastest-growing category as climate-linked IoT sensors enable automatic triggers for weather and flood coverage. Connected Vehicles anchors device type volume, though Industrial IoT Devices is displacing it in margin contribution as manufacturing and logistics clients demand asset-level risk visibility.
FDA oversight of connected health devices, GDPR data portability mandates from European regulators, and state-level telematics disclosure rules enforced by US insurance commissioners collectively shape product design and market access conditions. The EU AI Act introduces additional algorithmic transparency requirements for automated underwriting decisions that rely on IoT-derived behavioral scores. Stakeholders must monitor whether emerging cybersecurity certification frameworks for IoT hardware become de facto prerequisites for policy eligibility across major jurisdictions.
Market Dynamics
Parametric trigger mechanisms are compressing claims settlement cycles from weeks to hours, forcing traditional indemnity underwriters to rebuild core systems around real-time sensor validation rather than retrospective loss adjustment.
Growth Catalysts
- EU AI Act compliance mandates:European carriers must deploy algorithmic transparency frameworks for automated underwriting, creating procurement urgency for explainable telematics scoring platforms.
- Cellular LPWAN infrastructure densification:Narrowband-IoT and LTE-M network rollouts by telecom operators are slashing connectivity costs for remote asset monitoring in agriculture and construction fleets.
- Climate-linked parametric expansion:Flood and wildfire sensor networks are enabling index-based payouts that bypass traditional loss verification, attracting capital from catastrophe bond investors.
Market Restraints
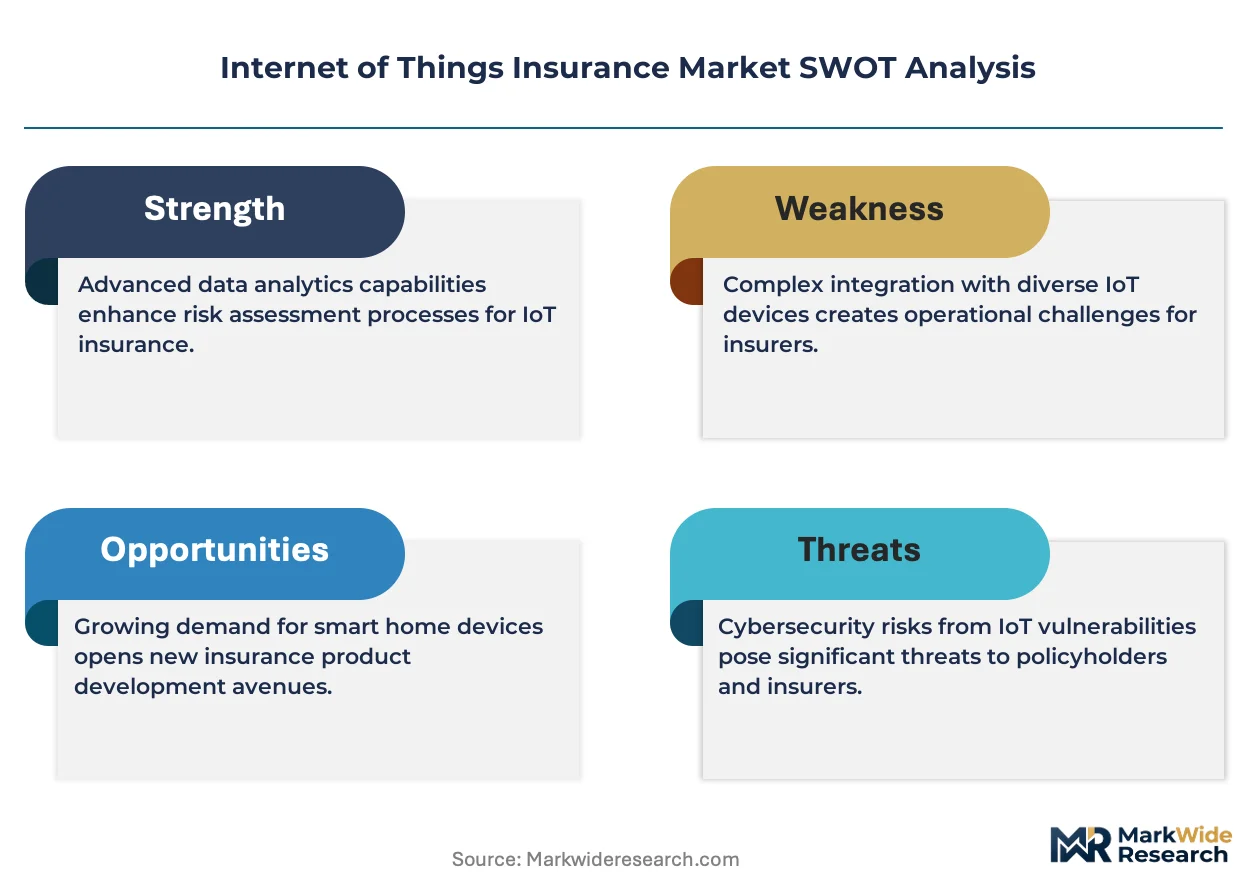
- GDPR data portability friction:European policyholders' right to transfer behavioral driving data between carriers creates technical interoperability costs that deter smaller underwriters from telematics entry.
- Silicon supply concentration:Semiconductor fabrication for vehicle telematics control units remains concentrated in East Asian foundries, exposing premium pricing volatility to geopolitical disruption.
- Actuarial model opacity:Black-box machine learning scores derived from IoT sensor fusion resist traditional regulatory scrutiny, slowing product approval timelines in state-level US insurance filings.
Strategic Opportunities
- Industrial IoT in German manufacturing:Mittelstand firms lack captive risk engineering capabilities, creating white space for sensor-enabled machinery breakdown coverage with predictive maintenance bundling.
- Embedded distribution at point-of-sale:Smart home device retailers in the United States represent untapped policy origination channels where premium collection can be automated through subscription billing integration.
- 5G network slicing convergence:Ultra-reliable low-latency communication channels enable mission-critical industrial sensor streams that support higher-limit coverage for autonomous logistics fleets.
Industry Challenges
- Cross-functional talent scarcity:Underwriting teams lack embedded systems engineers capable of validating sensor data integrity against tampering or calibration drift.
- Legacy core system integration:Policy administration platforms built for annual renewal cycles cannot ingest continuous telemetry streams without expensive middleware development.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Internet of Things Insurance Market |
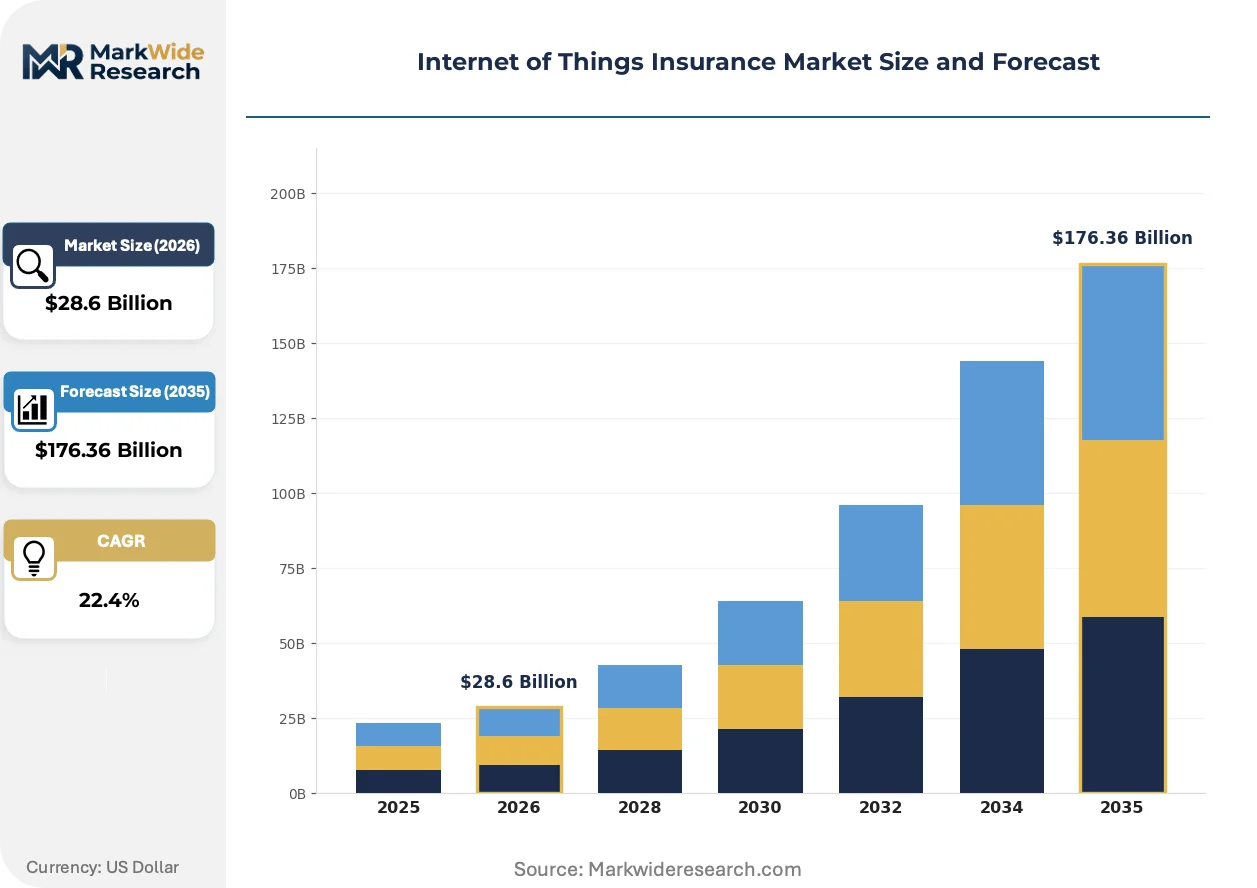
| Market Size in 2026 | $28.6 Billion |
| Market Size in 2035 | $176.36 Billion |
| CAGR (2026 – 2036) | 22.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Policy Type: Usage-Based Insurance, Parametric Insurance, Coverage Extensions, Liability Insurance Device Type: Smart Home Devices, Wearables, Connected Vehicles, Industrial IoT Devices Application Area: Health Monitoring, Property Protection, Vehicle Tracking, Asset Management Client Segment: Private Individuals, Small Businesses, Corporates, Government Agencies |
| Companies Covered | Allianz SE, AXA SA, Munich Re, Ping An Insurance, Zurich Insurance Group, Octo Telematics S.p.A., Cambridge Mobile Telematics, Inc., Samsara Inc., Progressive Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Internet of Things Insurance Market Emerging Trajectories
Digital twin architectures are virtualizing risk exposure assessment, compressing the gap between physical asset behavior and actuarial liability calculation. Three developments are restructuring competitive advantage.
Edge computing deployments in vehicle telematics units are virtualizing real-time crash reconstruction and fraud detection. Commercial auto fleets in the United States are adopting these systems fastest, with large trucking operators mandating onboard inference chips to reduce cellular data transmission costs. This virtualization of claims investigation is collapsing the traditional adjuster field visit model into automated severity scoring.
The EU AI Act's risk classification framework for automated decision-making is forcing European underwriters to maintain human-in-the-loop protocols for premium adjustments derived from behavioral scores. This industrial consequence elevates operational costs but creates defensible moats against pure algorithmic competitors. Personal auto lines in Germany and France face the steepest compliance burdens, with carriers hiring algorithmic accountability officers to satisfy national regulator interpretations.
Fleet managers are consolidating procurement authority over telematics-enabled insurance, displacing fragmented driver-level policy selection with enterprise-wide risk transfer contracts. This buyer concentration is compressing commission structures for traditional agent distribution channels. The shift is most visible in United States long-haul logistics, where procurement departments now specify insurance telemetry requirements in RFPs for vehicle leasing agreements.
Internet of Things Insurance Market Segmentation
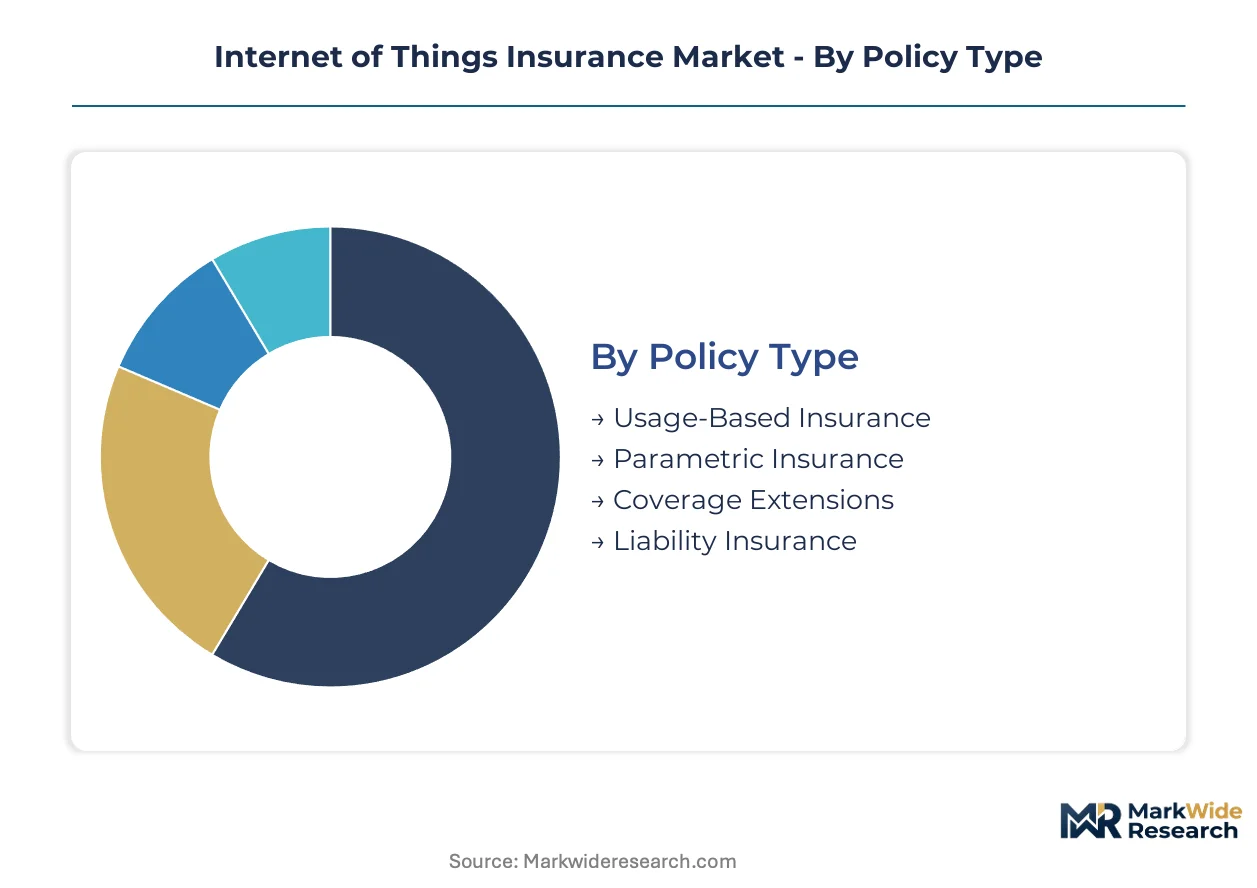
IoT insurance segmentation reflects the tension between mature telematics deployments and emerging sensor categories. Underwriters calibrate product architectures around data stream velocity, regulatory exposure, and integration complexity.
Policy Type:
The use-case spectrum spans retrospective indemnity to real-time risk transfer, with pricing models diverging sharply across data dependency levels.
- Usage-Based Insurance:Continuous telemetry from vehicle telematics units or wearable sensors calibrates premiums to actual behavioral exposure. Personal auto lines in the United States concentrate demand, where Progressive and State Farm have normalized driver score transparency.
- Parametric Insurance:Index-triggered payouts bypass loss verification through IoT-validated thresholds for flood depth, wind speed, or seismic intensity. Climate-linked sensor networks in coastal Florida and Gulf Coast Texas are expanding fastest, attracting catastrophe bond capital.
- Coverage Extensions:Endorsements attach IoT-derived protections to traditional property and casualty policies, bundling smart home leak detection or equipment breakdown monitoring.
- Liability Insurance:Connected product liability covers manufacturers against failure of IoT-enabled safety systems, with German automotive suppliers driving procurement.
The dominant share belongs to Usage-Based Insurance, while Parametric Insurance is closing the gap fastest.
Device Type:
Hardware categories stratify by data granularity, with industrial-grade sensors commanding premium pricing against consumer electronics.
- Connected Vehicles:OEM-embedded telematics control units transmit location, acceleration, and diagnostic data through cellular networks. Commercial fleet operators in the United States mandate these systems for driver behavior monitoring and fuel optimization.
- Industrial IoT Devices:Vibration, temperature, and pressure sensors on manufacturing equipment enable predictive maintenance bundling with machinery breakdown coverage. German Mittelstand firms lacking captive risk engineering drive fastest adoption.
- Smart Home Devices:Water leak detectors, smoke alarms, and security systems reduce property loss frequency for homeowners insurers.
- Wearables:Health-monitoring bands and smartwatches feed biometric data to life and health underwriters, though FDA oversight of connected devices constrains product velocity.
Connected Vehicles retain volume leadership, yet Industrial IoT Devices generate superior margin contribution per policy.
Application Area:
Functional deployment maps to underlying asset categories, with mobility and fixed property representing mature channels.
- Vehicle Tracking:Real-time location and geofencing support stolen asset recovery and usage-based premium adjustment. Long-haul logistics fleets in the United States consolidate procurement authority here.
- Asset Management:Sensor-enabled inventory and equipment monitoring extends coverage to construction, agriculture, and renewable energy infrastructure. Cellular LPWAN densification is slashing connectivity costs for remote deployment.
- Health Monitoring:Biometric streaming supports life insurance underwriting and wellness program incentives.
- Property Protection:Environmental and intrusion sensors reduce loss severity for residential and commercial buildings.
Vehicle Tracking anchors revenue pools, though Asset Management is climbing the fastest as industrial digitization accelerates.
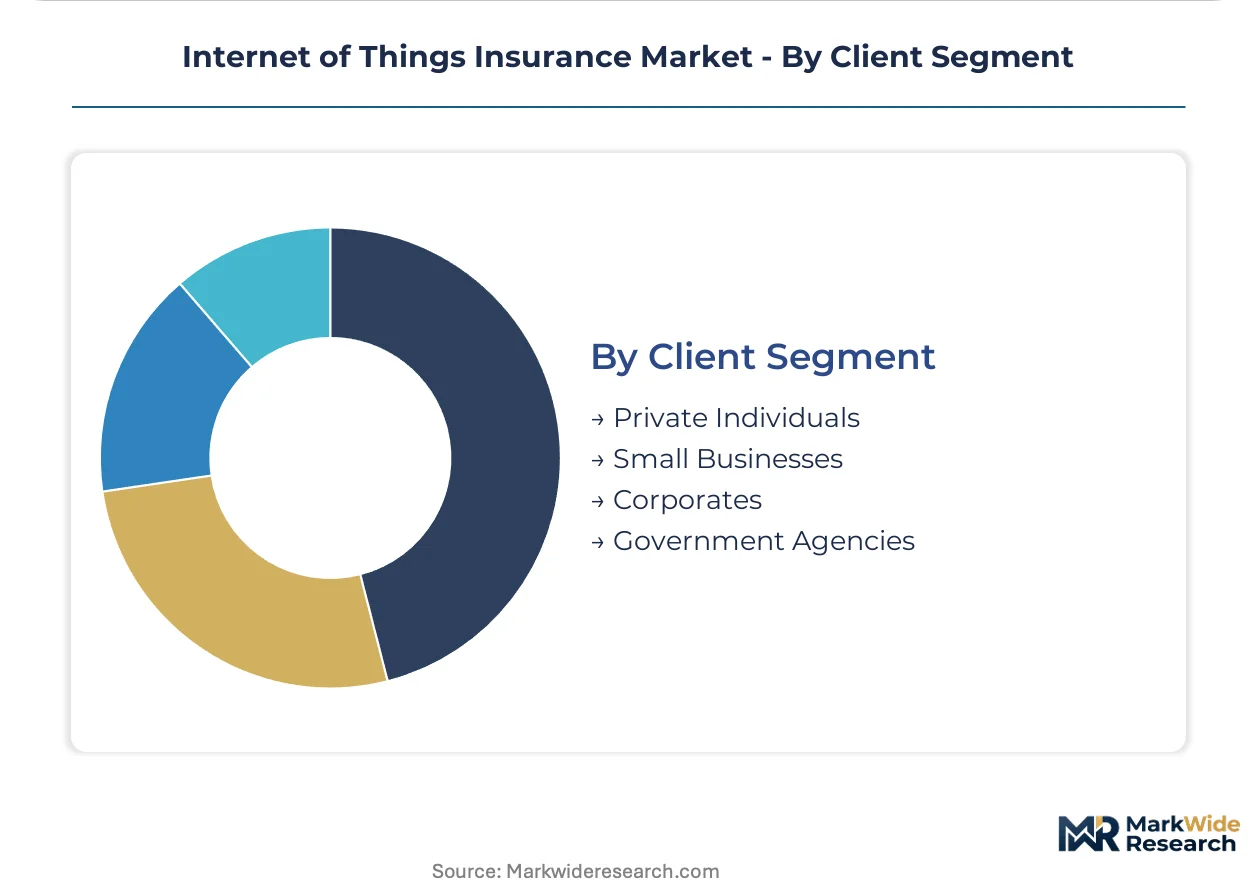
Client Segment:
Buyer sophistication determines data integration depth, with enterprise procurement teams specifying telemetry requirements contractually.
- Corporates:Fleet managers and risk engineering departments demand enterprise-wide risk transfer with predictive maintenance bundling. United States logistics operators now embed insurance telemetry specifications in vehicle leasing RFPs.
- Small Businesses:Commercial auto and property owners adopt plug-and-play telematics without dedicated risk management staff.
- Private Individuals:Personal auto and homeowners lines drive volume through direct-to-consumer telematics apps.
- Government Agencies:Municipal fleet and infrastructure coverage represents procurement-heavy, price-sensitive demand with extended sales cycles.
Corporates command the largest policy limits, while Small Businesses show steepest expansion trajectory as embedded distribution simplifies purchase friction.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The United States interstate highway network and Germany's autobahn freight corridors anchor transcontinental telematics infrastructure, underwriting national concentration in commercial fleet insurance. Cellular LPWAN tower densification along these transport arteries enables continuous sensor streaming at reduced connectivity cost. Regulatory divergence across jurisdictions is fragmenting product standardization.
United States
Telematics penetration in personal auto lines deepens as Progressive and State Farm normalize driver score transparency. State-level insurance commissioners enforce telematics disclosure rules that mandate algorithmic explainability. Long-haul logistics operators in the Midwest and Southeast now embed insurance telemetry specifications in vehicle leasing RFPs.
Germany
Mittelstand manufacturing firms lacking captive risk engineering drive industrial IoT adoption for machinery breakdown coverage. The KBA enforces stringent vehicle data access regulations that shape telematics control unit specifications. Bavaria and Baden-Württemberg cluster automotive suppliers procuring connected product liability coverage.
China
Ping An Insurance scales usage-based products through integration with domestic telematics platforms. The MIIT mandates connected vehicle data localization standards that restrict cross-border sensor streaming. Yangtze River Delta manufacturing hubs deploy predictive maintenance bundling with industrial sensor networks.
United Kingdom
Commercial fleet operators adopt parametric flood coverage linked to IoT-validated water level sensors. The FCA scrutinizes algorithmic pricing transparency for telematics-derived premiums. London-based insurtech intermediaries broker sensor data aggregation contracts between carriers and device manufacturers.
France
Climate-linked parametric expansion accelerates along coastal zones with sensor-validated wind speed triggers. The CNIL enforces GDPR data portability mandates that create technical interoperability costs for telematics entry. Île-de-France hosts algorithmic accountability officer hiring by carriers facing EU AI Act compliance deadlines.
Internet of Things Insurance Market Vendor Landscape
On the supply side, the industry is bifurcated between capital-intensive reinsurance balance sheets and specialized telematics infrastructure providers. Tier-one carriers underwrite parametric products through front-end partnerships, while data layer specialists supply telemetry platforms to underwriters lacking in-house IoT capabilities. Two strategic archetypes dominate: reinsurance-backed product sponsors and sensor data aggregators. Competitive moves concentrate on embedded distribution partnerships and algorithmic transparency platform procurement.
Within the reinsurance-backed tier, Munich Re exemplifies balance sheet deployment across multiple carrier front-ends, while Octo Telematics S.p.A. anchors the connected vehicle data layer. Progressive Corporation occupies a position at the direct-to-consumer integration vector. These three entities represent distinct competitive positioning: capital intermediation, infrastructure supply, and channel control.
| Leading Market Players |
|---|
| Allianz SE |
| AXA SA |
| Munich Re |
| Ping An Insurance |
| Zurich Insurance Group |
| Octo Telematics S.p.A. |
| Cambridge Mobile Telematics, Inc. |
| Samsara Inc. |
| Progressive Corporation |
| Others |
Supply Flow & Price Mechanics
Undercapacity in cellular LPWAN module fabrication across East Asian foundries is compressing supplier margins while amplifying pricing power for semiconductor vendors serving telematics control unit manufacturers. This utilization asymmetry forces insurers to absorb connectivity hardware costs upfront or pass them through as policy surcharges.
Pricing Analysis
Volume-discount tiering separates enterprise fleet contracts from individual policyholder subscriptions, with commercial auto operators commanding per-device rates below consumer telematics by an order of magnitude. Price differentiation hinges on data granularity—real-time biometric streaming commands premium positioning against batch-upload vehicle diagnostics—and on certification grade, with GDPR-compliant EU data handling adding operational overhead. Pricing pressure stems from embedded distribution models where device retailers bundle coverage at point-of-sale, compressing standalone policy margins. Small businesses show highest price sensitivity due to limited risk management staff, while corporate fleet managers prioritize predictive maintenance bundling over premium minimization.
Supply Chain Analysis
Tariff exposure between United States and China dominates semiconductor procurement risk for vehicle telematics control units, with fabrication concentrated in Taiwan, South Korea, and mainland China. Raw material dependencies include silicon wafers, rare earth magnets for sensor calibration, and lithium-ion cells for remote device power. Supply chain risk centers on single-source vulnerability for narrowband-IoT chipsets following industry consolidation among three dominant vendors. Distribution runs through tier-one telematics platform providers who aggregate sensor data for insurers lacking in-house IoT engineering.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation opportunity concentrates in industrial IoT insurance for mid-market manufacturing, where enterprise risk engineering capabilities remain scarce and sensor-enabled predictive maintenance bundling creates service differentiation.
For Market Incumbents: Entrench algorithmic transparency infrastructure ahead of EU AI Act enforcement deadlines, deploying explainable scoring platforms that satisfy national regulator interpretations in Germany and France. Acquire specialized telematics data layer capabilities to reduce dependency on Octo Telematics and Cambridge Mobile Telematics for connected vehicle telemetry. Channel control through embedded distribution partnerships with smart home device retailers defends against direct-to-consumer disintermediation. For New Entrants and Emerging Players: Pursue parametric flood coverage expansion along United States Gulf Coast and Florida coastal zones, where climate-linked sensor networks attract catastrophe bond capital and bypass established indemnity incumbents. Target German Mittelstand manufacturing firms lacking captive risk engineering for machinery breakdown coverage with predictive maintenance bundling. Go-to-market leverage rests on cellular LPWAN infrastructure partnerships that slash connectivity costs for remote asset deployment. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among telematics infrastructure providers with multi-year data supply contracts across carrier front-ends, positioning these archetypes for durable cash flow generation across a five-to-ten year viability window. Acquisition priority targets sensor data aggregators with established GDPR compliance frameworks and cross-carrier interoperability. The signal to watch is regulatory certification of IoT hardware cybersecurity standards becoming de facto policy eligibility prerequisites across major jurisdictions.| Strategic Initiative | Industry Significance |
|---|---|
| Algorithmic Transparency Platform Deployment | EU AI Act compliance mandates explainable underwriting scores in Germany and France. |
| Embedded Distribution Partnership | Smart home device retailers in the United States automate premium collection through subscription billing. |
| Parametric Product Expansion | Climate-linked sensor networks enable index-based payouts bypassing traditional loss adjustment. |
| Industrial IoT Capability Acquisition | German Mittelstand manufacturing demand for predictive maintenance bundling outstrips captive supply. |
| Cellular LPWAN Infrastructure Convergence | 5G network slicing supports mission-critical industrial sensor streams for autonomous logistics coverage. |
Methodological Framework
Two parallel data streams informed the analysis: structured primary interviews with insurance carrier product executives, telematics platform engineers, and fleet risk managers, alongside secondary validation through regulatory filings with the EU AI Act implementation bodies, FDA connected device oversight records, and state insurance commissioner telematics disclosure rules. Primary fieldwork encompassed underwriting leads at Munich Re and Zurich Insurance Group, algorithmic accountability officers at French and German carriers, and procurement directors at United States long-haul logistics operators. Secondary sources included SEC 10-K disclosures from Progressive Corporation and Samsara Inc., EU GDPR enforcement actions by CNIL and national data protection authorities, and cellular carrier narrowband-IoT deployment announcements. Bottom-up policy volume estimates triangulated against top-down reinsurance premium allocations.
Forecast inputs encompassed connected vehicle penetration trajectories, industrial IoT sensor deployment rates in German manufacturing, and parametric insurance adoption curves across coastal climate zones. Segmentation dimensions modeled include policy type, device category, application area, and client sophistication tier. CAGRs derived from logistic diffusion curves fitted to telematics adoption benchmarks, adjusted for regulatory acceleration effects from EU AI Act compliance deadlines and GDPR data portability implementation. Industry-specific forecast inputs included cellular LPWAN tower densification schedules and semiconductor fabrication capacity utilization signals from East Asian foundries.
The forecast holds incumbent behavior within observed patterns; aggressive vertical integration moves by reinsurance-backed carriers into telematics hardware would shift outcomes substantially. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Insurance
Family Floater Health Insurance Market
Insurance
US Travel Insurance Market
Insurance
Peer to Peer Insurance Market
Insurance
Europe Online Insurance Market
Insurance
Canada Cyber (Liability) Insurance Market
Insurance
South Africa Property and Casualty Insurance Market
Insurance
North America Car Insurance Aggregators Market
Insurance
Digital Insurance Market
Insurance
Medical Professional Liability Insurance Market
Insurance
Spain Parametric Insurance Market
Insurance
Workers Compensation Insurance Market
Insurance
Insurance Brokerage Market
Insurance
Critical Illness Insurance Market
Insurance
UK Dental Insurance Market
Insurance
Global Long Term Care Insurance Market
Insurance
MENA Health and Medical Insurance Market