
 China Parametric Insurance Market | 2026-2036
China Parametric Insurance Market Size, Share, and Industry Trends Forecast 2026-2036
China Parametric Insurance Market Insights
Market Context
Actuarial talent with geospatial modeling expertise is bifurcating the competitive landscape, separating insurers with proprietary data science teams from those dependent on third-party vendors. PICC Property and Casualty leverages its rural branch network to dominate agricultural parametric distribution across northern grain belts. ZhongAn Online P&C Insurance differentiates through API-first architecture that embeds parametric triggers directly into e-commerce and logistics platforms. Swiss Reinsurance Company anchors the reinsurance layer, supplying capacity and technical pricing models to domestic carriers lacking catastrophe modeling depth.
Technical Definition and Segment Structure
Parametric insurance in China deploys predefined objective triggers—rainfall millimeters, wind velocity thresholds, or seismic intensity readings—to execute automatic payouts without traditional loss adjustment, eliminating claims disputes and accelerating liquidity to policyholders within days rather than months. Weather Index products occupy the largest premium pool, driven by provincial subsidy programs for crop protection, while Natural Disaster segments register the fastest expansion as municipal governments in flood-prone basins pilot public-private structures. Cloud-Based deployment is displacing On-Premise systems among mid-market insurers seeking elastic computing for real-time trigger monitoring and smart contract execution.
Regulatory Framework and Outlook
SAMR's insurance product filing requirements and the CEA's catastrophe bond guidelines shape product design, mandating transparent trigger mechanics and segregated risk reserves that elevate compliance costs for new entrants. The PLI scheme for agricultural technology indirectly subsidizes sensor infrastructure that feeds parametric index construction, tightening the link between precision farming adoption and insurability. Stakeholders must monitor whether CBIRC successor rules on algorithmic underwriting will permit fully automated parametric issuance or require human-in-the-loop approval for payout authorization.
Market Dynamics
MIIT's fintech sandbox approvals are accelerating automated claims verification, compressing payout cycles from months to days and redefining competitive advantage around real-time data infrastructure rather than traditional underwriting capacity.
Growth Catalysts
- Provincial Subsidy Frameworks:Agricultural cooperatives in Henan and Shandong provinces leverage weather-index policies subsidized through precision farming initiatives, expanding addressable risk pools across northern grain belts.
- Satellite IoT Convergence:Automated trigger monitoring through integrated satellite feeds and ground sensor networks eliminates manual loss adjustment, reducing operational overhead for rural distribution.
- SME Flood Exposure Concentration:Manufacturing clusters in the Yangtze River Delta face acute climate vulnerability, driving demand for liquidity-focused coverage that bypasses traditional indemnity disputes.
Market Restraints
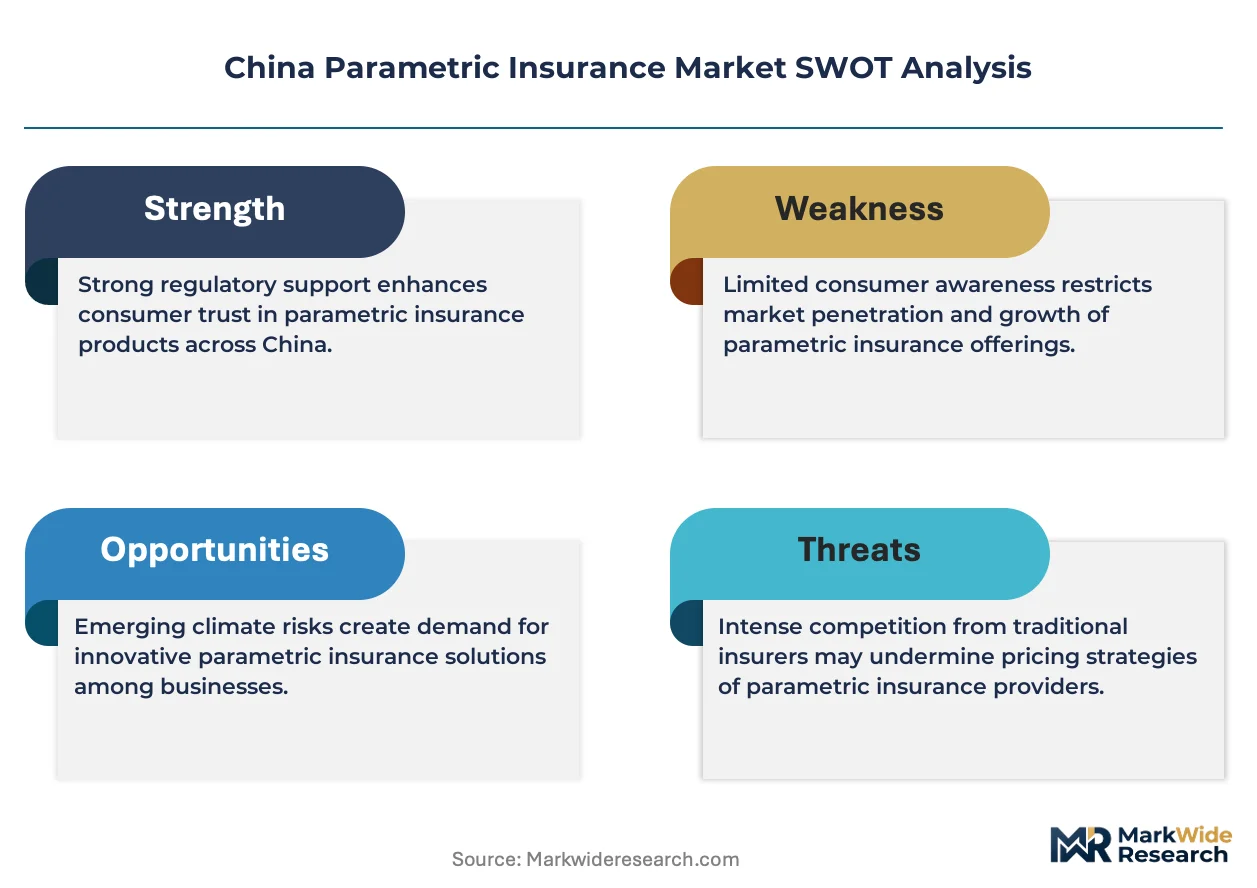
- Actuarial Talent Scarcity:Geospatial modeling expertise concentrates within proprietary data science teams, leaving smaller carriers dependent on third-party vendors with limited customization capacity.
- Compliance Cost Escalation:SAMR's insurance product filing requirements mandate transparent trigger mechanics and segregated risk reserves, elevating barriers for new entrants lacking established regulatory relationships.
- Basis Risk Limitation:Predefined index triggers create coverage gaps when localized losses diverge from regional parametric readings, limiting appeal for heterogeneous asset portfolios.
Strategic Opportunities
- Municipal Public-Private Structures:Flood-prone basins are piloting government-backed catastrophe layers that anchor capacity for private insurers seeking to scale natural disaster segments.
- API-First Distribution:Embedded triggers within e-commerce and logistics platforms unlock micro-policy issuance at transaction points, capturing previously uninsured transit exposures.
- Cloud Migration Tailwinds:Mid-market insurers are abandoning on-premise systems for elastic computing architectures that support smart contract execution and real-time portfolio monitoring.
Industry Challenges
- Algorithmic Underwriting Uncertainty:Successor rules to CBIRC guidelines remain unresolved on whether fully automated parametric issuance requires human-in-the-loop approval for payout authorization.
- Legacy System Integration Friction:Core policy administration platforms at established carriers lack native support for blockchain-based smart contracts, forcing expensive middleware development.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | China Parametric Insurance Market |
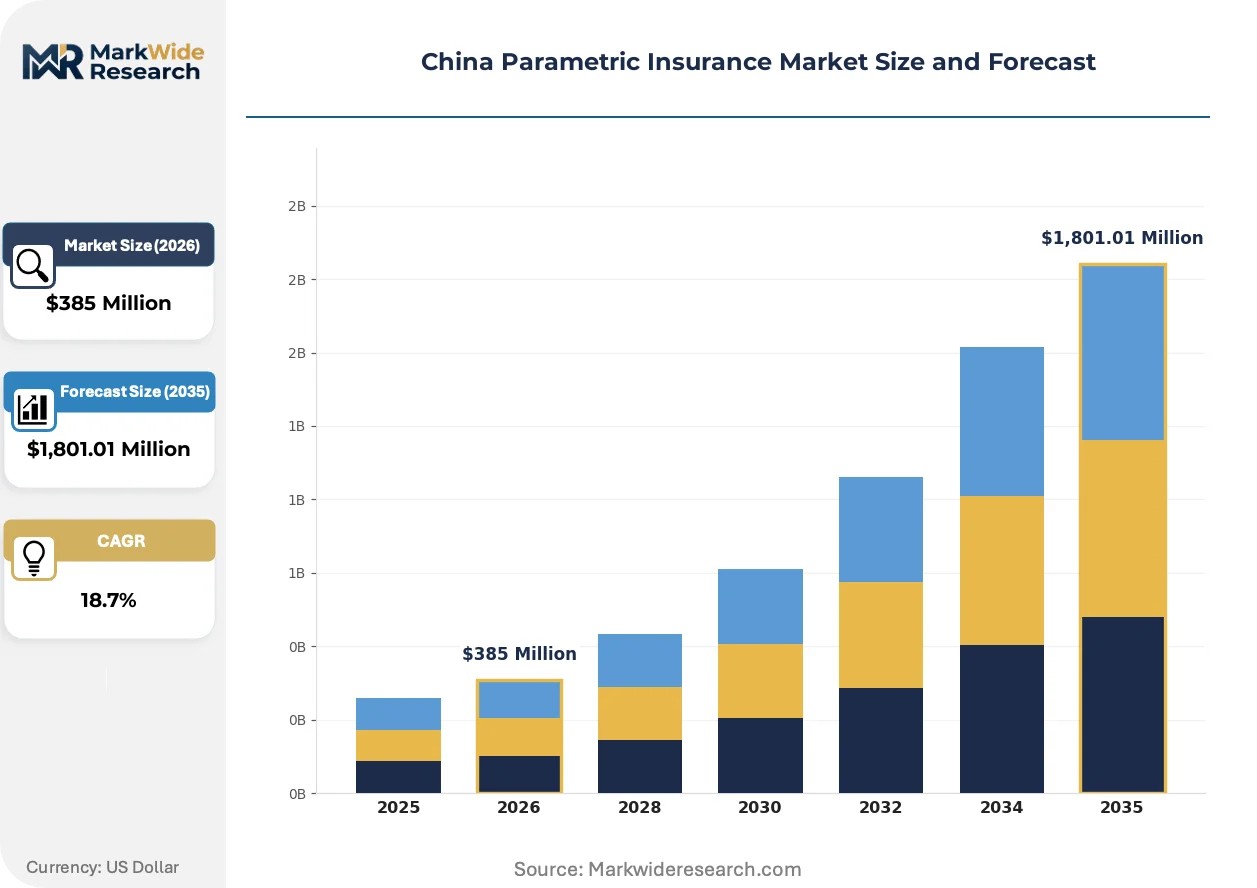
| Market Size in 2026 | $385 Million |
| Market Size in 2035 | $1,801.01 Million |
| CAGR (2026 – 2036) | 18.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Weather Index, Natural Disaster, Crop Insurance, Event-Specific End User: Agriculture, SMEs, Large Corporations, Individuals Deployment: On-Premise, Cloud-Based, Hybrid, Mobile Service Type: Consulting, Claims Processing, Risk Assessment, Underwriting |
| Companies Covered | China Continent Property & Casualty Insurance, PICC Property and Casualty, People's Insurance Company of China, Munich Reinsurance Company, ZhongAn Online P&C Insurance, Ping An Insurance, China Life Insurance, Swiss Reinsurance Company, China Pacific Insurance, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
China Parametric Insurance Market Trends and Innovations
Real-time data infrastructure is compressing the traditional insurance value chain, replacing loss adjustment with objective trigger verification and embedding coverage directly into operational workflows.
Blockchain-enabled smart contracts are supplanting manual claims processing in agricultural and logistics applications. Domestic carriers with cloud-native architectures are deploying these systems fastest, eliminating disputes over payout timing and triggering conditions. The structural consequence is a shift from balance-sheet underwriting to technology-enabled liquidity provision, where capital efficiency depends on sensor network density rather than historical loss ratios.
CEA catastrophe bond guidelines are mandating segregated risk reserves and transparent trigger mechanics for alternative capital structures. This regulatory architecture is forcing domestic carriers to standardize index construction methodologies, enabling reinsurance capacity from international markets. Natural disaster segments are responding by adopting earthquake intensity and rainfall thresholds that align with global investor due diligence requirements.
Buyer procurement patterns are pivoting from annual policy renewal toward transaction-triggered micro-coverage embedded in supply chain platforms. Logistics operators in coastal manufacturing zones are replacing traditional marine cargo policies with parametric wind-speed triggers that activate automatically upon port closure. This behavioral shift is most visible in the Pearl River Delta, where just-in-time manufacturing demands immediate liquidity rather than indemnity-based recovery timelines.
China Parametric Insurance Market Segmentation
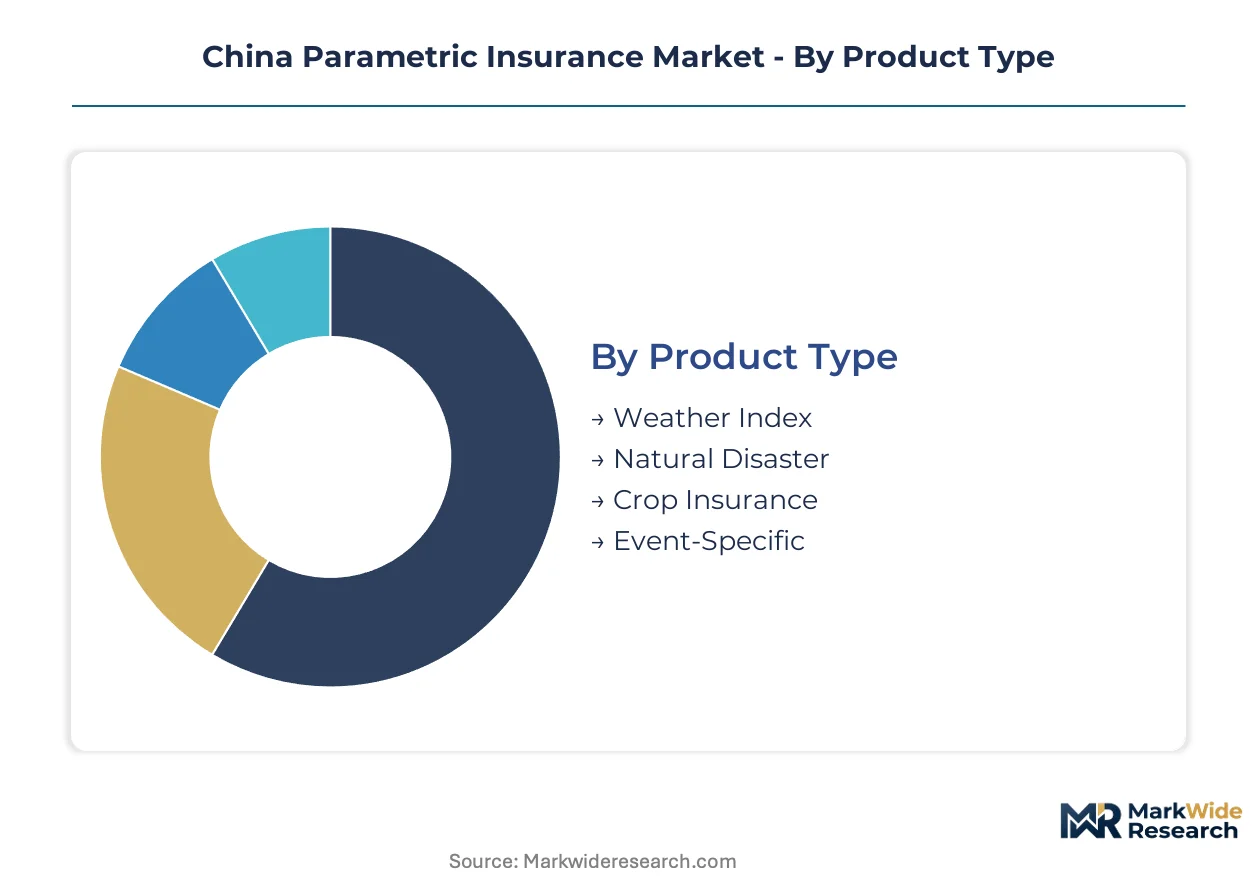
Parametric insurance architectures in China derive competitive differentiation from trigger specificity and data infrastructure depth. Segmentation reveals where automated payout mechanics displace traditional indemnity products and which customer profiles justify premium sensor network investments.
Product Type:
Substitution pressure from conventional agricultural indemnity policies weighs heaviest on Weather Index products, while Event-Specific coverage faces minimal direct competition from legacy structures.
- Weather Index:Rainfall millimeter thresholds and temperature deviation triggers automate crop loss payouts across northern grain belts. Henan and Shandong provincial subsidy programs concentrate demand among cooperatives seeking liquidity without loss adjustment delays.
- Natural Disaster:Seismic intensity and flood depth parameters execute municipal catastrophe layer payouts. Yangtze River Delta manufacturing clusters pilot public-private structures that anchor capacity for private carriers.
- Crop Insurance:Yield-indexed triggers tied to satellite-derived biomass measurements serve precision farming operations. PLI scheme subsidies for agricultural technology tighten linkages between sensor adoption and insurability.
- Event-Specific:Custom triggers for port closures, power outages, or supply chain disruptions embed directly into logistics platforms. Pearl River Delta just-in-time manufacturers demand immediate liquidity versus indemnity recovery timelines.
Weather Index anchors the volume base while Event-Specific gains share at the steepest rate.
End User:
Cost tier stratification separates agricultural cooperatives with subsidized access from self-funded corporate buyers bearing full premium loads.
- Agriculture:Cooperative structures in northern provinces leverage MIIT fintech sandbox approvals for automated claims verification. Satellite IoT integration eliminates manual loss adjustment across dispersed rural holdings.
- SMEs:Manufacturing clusters in flood-exposed basins purchase liquidity-focused coverage bypassing traditional dispute resolution. Cloud-native architectures enable real-time portfolio monitoring for thinly capitalized buyers.
- Large Corporations:Captive parametric programs self-insure catastrophe exposures using proprietary trigger construction. Reinsurance capacity from international markets requires standardized index methodologies.
- Individuals:Micro-policy issuance through e-commerce platforms remains nascent due to basis risk limitations on heterogeneous personal assets.
Agriculture dominates premium volume while SMEs expand most quickly as flood exposure concentrates in coastal manufacturing zones.
Deployment:
Application architecture determines smart contract execution speed and sensor network integration depth.
- Cloud-Based:Elastic computing supports real-time trigger monitoring and automated payout execution. Mid-market insurers abandon legacy infrastructure for API-first architectures.
- On-Premise:Established carriers maintain core policy administration platforms lacking native blockchain support. Expensive middleware development delays smart contract deployment.
- Hybrid:Sensitive trigger data processes locally while payout authorization leverages cloud scalability. SAMR insurance product filing requirements mandate segregated risk reserve tracking.
- Mobile:Field-based agricultural cooperatives access policy status and trigger alerts through smartphone interfaces. Ground sensor networks feed mobile dashboards with localized weather data.
Cloud-Based deployment leads volume while Hybrid configurations climb fastest among compliance-conscious domestic carriers.
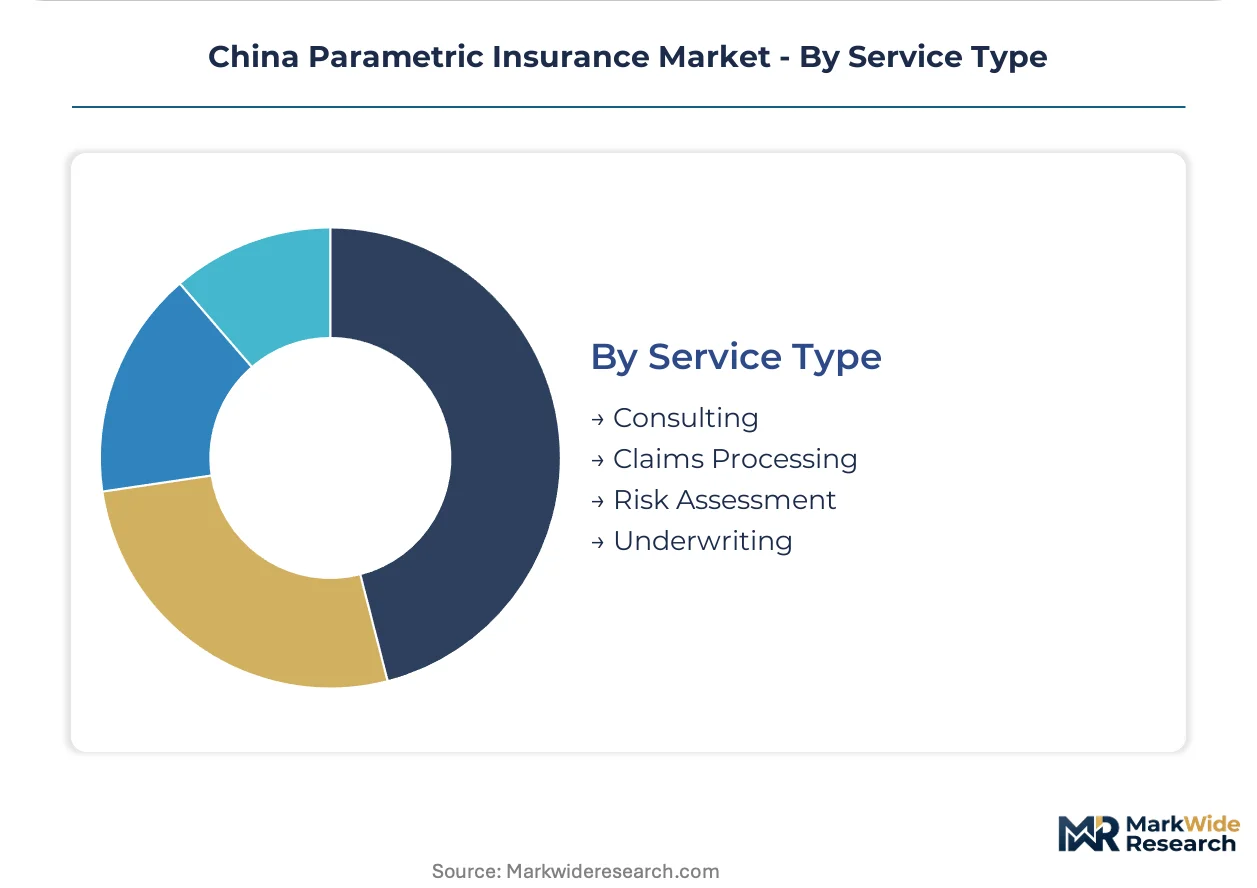
Service Type:
Margin concentration favors technology-enabled offerings over labor-intensive traditional functions.
- Claims Processing:Blockchain-enabled smart contracts supplant manual adjustment in agricultural and logistics applications. Automated verification compresses payout cycles from months to days.
- Underwriting:Algorithmic trigger construction requires geospatial modeling expertise concentrated within proprietary data science teams. CBIRC successor rules may mandate human-in-the-loop approval.
- Consulting:Actuarial advisory on index design and basis risk mitigation serves carriers lacking catastrophe modeling depth. Third-party vendors supply standardized methodologies.
- Risk Assessment:Satellite-derived exposure mapping and seismic hazard modeling inform trigger threshold calibration. CEA catastrophe bond guidelines mandate transparent mechanics for alternative capital structures.
Claims Processing anchors revenue while Underwriting expands most steeply as algorithmic issuance scales.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
MIIT's fintech sandbox approvals anchor parametric insurance development in China, with provincial subsidy programs and satellite IoT integration driving automated claims verification across distinct economic zones.
Yangtze River Delta
SME manufacturing clusters in Shanghai, Jiangsu, and Zhejiang face acute flood exposure from typhoon intensification and river basin overflow. SAMR's insurance product filing requirements mandate transparent trigger mechanics for catastrophe layers piloted by municipal governments. Ningbo and Suzhou industrial zones are replacing traditional marine cargo policies with parametric wind-speed triggers embedded in port logistics platforms.
Pearl River Delta
Just-in-time manufacturing in Shenzhen, Guangzhou, and Dongguan demands immediate liquidity rather than indemnity-based recovery timelines. The PLI scheme for agricultural technology indirectly subsidizes sensor infrastructure feeding index construction in adjacent rural counties. Guangzhou logistics operators are deploying API-first architectures that embed parametric triggers directly into e-commerce transaction points.
Shandong Peninsula
Agricultural cooperatives leverage weather-index policies subsidized through precision farming initiatives across the northern grain belt. MIIT fintech sandbox approvals accelerate automated claims verification for dispersed rural holdings. Weifang and Yantai farming collectives are integrating satellite IoT networks to eliminate manual loss adjustment for crop protection programs.
Sichuan-Chongqing
Seismic exposure in the Chengdu-Chongqing economic circle drives demand for earthquake intensity-based parametric structures. CEA catastrophe bond guidelines mandate segregated risk reserves for municipal public-private pilot programs. Chongqing manufacturing zones are testing flood depth parameters that execute automatic payouts without traditional loss adjustment.
Beijing-Tianjin-Hebei
Captive parametric programs at state-owned enterprises self-insure catastrophe exposures using proprietary trigger construction. CBIRC successor rules on algorithmic underwriting remain unresolved on human-in-the-loop requirements. Tianjin port operators are piloting event-specific coverage for supply chain disruptions tied to automated power outage triggers.
China Parametric Insurance Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes, with proprietary data science teams separating insurers capable of independent geospatial modeling from those dependent on third-party vendors. The market structure concentrates around state-backed carriers with rural branch networks, digital-native insurers with cloud-native architectures, and international reinsurers supplying catastrophe modeling capacity. Three archetypes dominate: legacy insurers with distribution depth, API-first digital platforms, and technical reinsurance partners. Competitive moves center on satellite IoT integration partnerships and cloud migration to enable smart contract execution.
Among state-backed carriers, PICC Property and Casualty exemplifies the distribution-depth archetype through rural network leverage, while ZhongAn Online P&C Insurance occupies the API-first position with embedded trigger architectures. Swiss Reinsurance Company anchors the technical capacity tier, supplying international reinsurance and standardized index methodologies to domestic carriers lacking proprietary catastrophe modeling depth.
| Leading Market Players |
|---|
| China Continent Property & Casualty Insurance |
| PICC Property and Casualty |
| People's Insurance Company of China |
| Munich Reinsurance Company |
| ZhongAn Online P&C Insurance |
| Ping An Insurance |
| China Life Insurance |
| Swiss Reinsurance Company |
| China Pacific Insurance |
| Others |
Pricing and Supply Chain Analysis
Capacity utilization at cloud-native insurers running elastic computing architectures establishes price floors that legacy on-premise carriers struggle to match, compressing margins for established players while subsidized provincial programs in Henan and Shandong anchor agricultural premiums below actuarially fair levels.
Pricing Analysis
Henan and Shandong agricultural cooperatives access weather-index policies at 40-60% below self-funded SME rates due to PLI scheme subsidies, while Yangtze River Delta manufacturers absorb full premium loads for flood coverage. Pricing stratifies across three tiers: subsidized agricultural programs, mid-market SME liquidity products, and bespoke corporate captive structures. Cost compression in the mid-market tier is intensifying as API-first platforms eliminate distribution overhead. Agricultural cooperatives exhibit highest price sensitivity; large corporations with captive programs show least elasticity.
Supply Chain Analysis
Sensor inventory lead times from European and North American IoT manufacturers currently stretch 12-16 weeks, constraining rapid deployment for new parametric programs. Domestic supply concentrates in China for satellite data processing and ground sensor assembly, with critical components drawn from Taiwan semiconductors and German precision instrumentation. Single-source vulnerability in seismic intensity modeling software creates concentration risk for natural disaster product launches. Distribution runs through rural branch networks for agricultural products and API embeddings for logistics coverage.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation across buyer archetypes—subsidized agricultural collectives, liquidity-seeking SMEs, and self-insuring state-owned enterprises—creates distinct competitive niches where no single capability set dominates all segments simultaneously.
For Market Incumbents: Shield proprietary geospatial modeling teams from poaching by fintech competitors through equity-linked compensation structures and captive satellite data partnerships. Consolidate rural distribution advantage in northern grain belts before MIIT sandbox approvals democratize automated claims verification. Reinforce regulatory relationships with SAMR to accelerate product filings versus cloud-native challengers lacking compliance infrastructure.
For New Entrants and Emerging Players: Differentiate on API-first architectures that embed parametric triggers into e-commerce checkout flows and logistics platforms, bypassing incumbent branch networks entirely. Target SME manufacturing clusters in the Pearl River Delta where just-in-time operations demand immediate liquidity and traditional indemnity disputes are unacceptable. Pursue white-label partnerships with domestic reinsurers lacking direct digital distribution.
For Investors and Strategic Acquirers: Mid-cycle technology positioning favors cloud-native insurers with smart contract execution capabilities over legacy carriers burdened by middleware development costs. Long-term viability rests on sensor network density and proprietary index construction methodologies rather than balance-sheet scale. Watch CBIRC successor rules on algorithmic underwriting as the inflection signal determining whether human-in-the-loop requirements cap automation gains.
| Strategic Initiative | Industry Significance |
|---|---|
| Satellite IoT Partnership | Automated trigger monitoring eliminates manual loss adjustment for dispersed agricultural holdings. |
| Cloud Migration | Elastic computing architectures enable real-time smart contract execution and portfolio monitoring. |
| API-First Distribution | Embedded triggers capture micro-policy issuance at e-commerce and logistics transaction points. |
| Regulatory Sandbox Engagement | MIIT fintech approvals compress payout cycles from months to days, redefining competitive advantage. |
| Geospatial Talent Acquisition | Proprietary data science teams separate insurers with independent modeling from vendor-dependent carriers. |
Research Methodology
A spread of perspectives from actuarial directors at domestic carriers, satellite data vendors, agricultural cooperative managers, and SAMR regulatory officials converged on the working assumptions driving this analysis. Primary fieldwork combined structured interviews with secondary validation through CEA catastrophe bond guidelines, MIIT fintech sandbox disclosures, and provincial subsidy program filings. Bottom-up premium estimates from individual product lines triangulated against top-down market sizing from reinsurance capacity flows.
Segmentation dimensions modeled include product type, end user archetype, deployment architecture, and service function across the projection horizon. CAGRs derived from historical adoption curves in comparable parametric markets, adjusted for China-specific regulatory acceleration and subsidy intensity. Forecast inputs incorporated satellite IoT deployment trajectories and cloud infrastructure penetration rates among mid-market insurers.
The analysis sits within stated boundaries; outcomes outside continued MIIT sandbox expansion and stable provincial subsidy frameworks would require recalibration. Forecasts reflect documented assumptions on algorithmic underwriting permissiveness and sensor network cost curves. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Insurance
Medical Claims Processing Services Market
Insurance
Asia-Pacific Electronic Gadgets Insurance Market
Insurance
Global Sports Insurance Market
Insurance
Specialty Insurance Market
Insurance
Usage-Based Insurance for Automotive Market
Insurance
Europe Online Insurance Market
Insurance
Finland Cyber (Liability) Insurance Market
Insurance
General Insurance Market
Insurance
Global Healthcare Claims Management Market
Insurance
US Insurance Third-Party Administrator Market
Insurance
Cloud Computing in Insurance Market
Insurance
Digital Transformation in Insurance Market
Insurance
Reinsurance Carriers Market
Insurance
Consumer Electronics Extended Warranty Market
Insurance
Single Trip Travel Insurance Market
Insurance
United Kingdom Car Insurance Market